
 Middle East and Africa Whey Protein Market | 2026-2036
Middle East and Africa Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Whey Protein Market Foresight
Sports nutrition distribution in the Middle East and Africa is narrowing as multinational ingredient suppliers consolidate shelf access through direct-to-manufacturer partnerships. Glanbia Nutritionals leverages its isolate production scale to supply premium contract brands across the GCC. Arla Foods Ingredients sustains competitive positioning through backward integration into European whey streams that feed African blenders. Fonterra Co-operative Group anchors supply reliability with ocean-freight logistics covering MEA port infrastructure gaps.
Whey protein encompasses the complete, soluble protein fraction isolated from milk during cheese manufacturing, typically yielding concentrates with protein content ranging from 34% to 80% and isolates exceeding 90% protein by dry weight. Its primary commercial purpose centers on delivering high-biological-value amino acid profiles for muscle protein synthesis in nutritional applications. Whey Protein Isolate commands premium positioning in athlete-focused formulations where lactose minimization drives purchase decisions. The Nutritional Supplements application segment generates the fastest volume expansion as gym penetration rises across urban Nigeria and Kenya. Online Retail distribution captures disproportionate growth in markets where traditional health food store networks remain underdeveloped.
South Africa's Department of Health enforces strict food fortification standards that constrain whey protein additive claims in mass-market beverages. The UAE's Ministry of Industry and Advanced Technology aligns import protocols with GCC standardization requirements, creating uniform but demanding technical barriers for new entrants. Saudi Arabia's SFDA mandates detailed allergen labeling that shapes product reformulation priorities for regional manufacturers. Stakeholders must monitor evolving halal certification protocols and port-of-entry testing regimes as the primary variables determining market access speed and compliance cost structures.
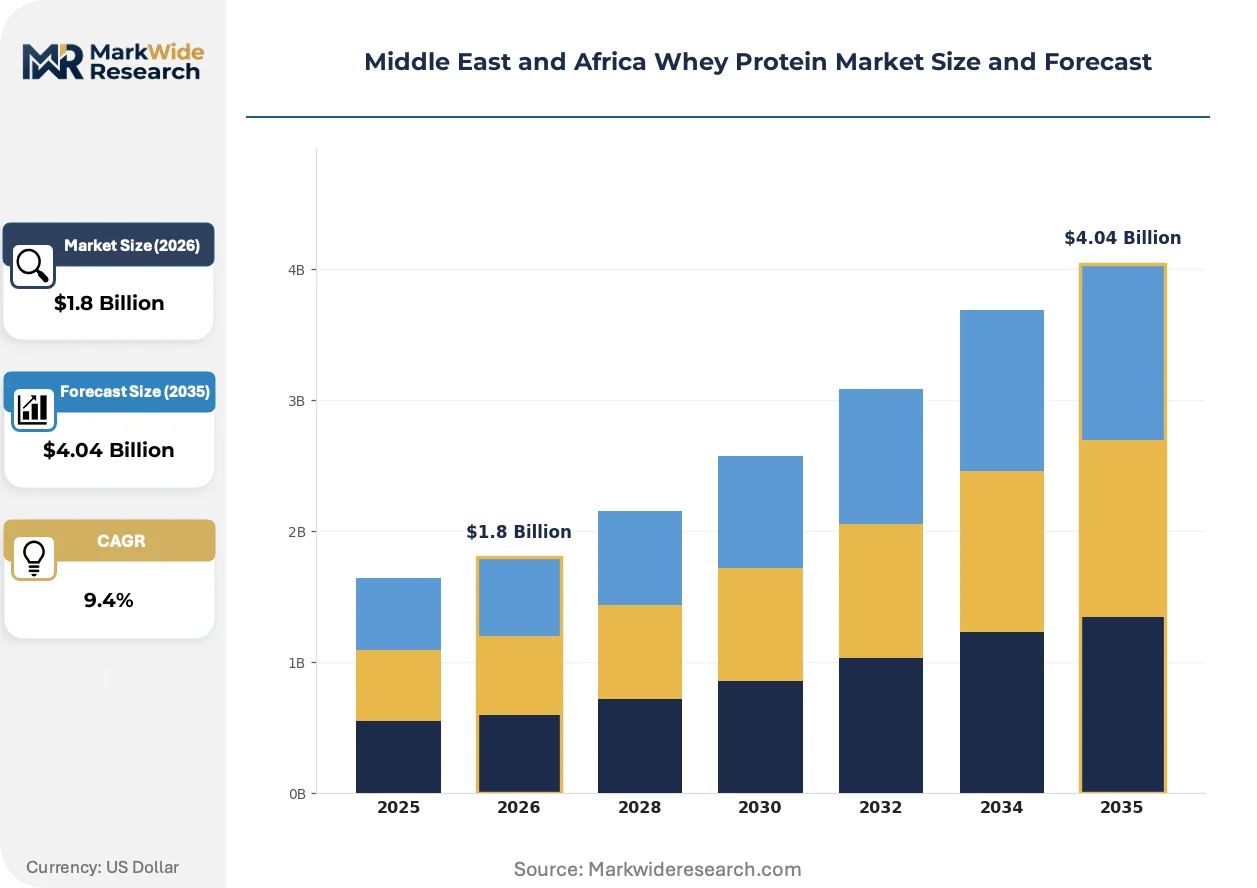
Market Dynamics
Halal certification protocols are restructuring supplier qualification timelines across the Middle East and Africa whey protein market, forcing reformulation cycles and segregated production lines that reshape competitive entry costs.
Growth Catalysts
- SFDA Allergen Labeling Mandates:Saudi Arabia's detailed disclosure requirements are elevating transparency standards that premium brands leverage for differentiation in athlete-focused retail channels.
- Urban Gym Network Expansion:Fitness club penetration in Lagos and Nairobi is creating concentrated demand nodes that justify localized blending investments and shorten last-mile distribution.
- Cross-Flow Microfiltration:This membrane separation technology is enabling regional processors to achieve isolate-grade protein content without capital-intensive ion exchange infrastructure.
Market Restraints
- European Whey Stream Concentration:Backward integration by Nordic dairy cooperatives limits independent African blenders to spot-market whey concentrate purchases with volatile pricing.
- Lactose Intolerance Prevalence:Undiagnosed sensitivity rates across North African populations constrain mass-market beverage applications despite protein fortification interest.
- GCC Import Protocol Uniformity:The UAE's Ministry of Industry and Advanced Technology alignment with Gulf standardization creates technical barriers that duplicate testing costs for multi-market entrants.
Strategic Opportunities
- Kenyan E-Commerce Infrastructure:Mobile payment penetration and logistics platform maturation enable direct-to-consumer isolate sales bypassing underdeveloped health food retail networks.
- Medical Nutrition Applications:Hospital-grade whey protein for sarcopenia management in aging South African populations represents an adjacent clinical channel with reimbursement potential.
- Egyptian Bodybuilding Retail Corridors:Cairo's concentrated supplement districts offer brand-building density for premium isolate positioning before national distribution scale.
Industry Challenges
- Halal Certification Timeline Variability:Divergent approval speeds between Saudi SFDA, UAE MOHAP, and Egyptian regulatory bodies complicate synchronized multi-market launches.
- Cold Chain Infrastructure Gaps:Port-to-warehouse temperature control deficiencies in Nigerian and Kenyan logistics networks accelerate protein denaturation and shelf-life compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Whey Protein Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Isolate, Whey Protein Concentrate, Hydrolyzed Whey Protein, Others Application: Food & Beverage, Nutritional Supplements, Bakery Products, Dairy Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Athletes, Fitness Enthusiasts, Vegan Consumers, General Population |
| Companies Covered | The Agropur Dairy Cooperative, Glanbia Nutritionals, Arla Foods Ingredients, Clover Industries, Fonterra Co-operative Group, Carbery Group, FrieslandCampina, Danone, Lactalis Ingredients, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Whey Protein Market Shifts & Advancements
Membrane filtration advances and certification digitization are compressing production economics while e-commerce penetration reshapes how isolate products reach end-users across underretailed African markets.
Cross-flow microfiltration combined with ceramic membrane cascades is collapsing the capital barrier between concentrate and isolate production for mid-scale African processors. Regional blenders in South Africa and Egypt are adopting these systems to bypass European toll-manufacturing dependencies. The technology is collapsing the historical isolate premium by enabling in-house 90% protein production at sub-million-dollar facility investments.
Saudi Arabia's SFDA has mandated blockchain-traceable halal certification documentation for all imported whey protein isolates entering the Kingdom. This policy is forcing suppliers to implement farm-to-facility digital audit trails that previously served only pharmaceutical-grade dairy. Egyptian and UAE manufacturers are responding by pre-certifying production runs to Saudi standards, effectively harmonizing compliance costs across GCC markets.
Fitness influencers on Instagram and TikTok are displacing traditional retail discovery for first-time whey protein buyers in urban Nigeria and Kenya. Supplement brands are redirecting trade marketing spend from health store shelf fees to creator partnership programs with measurable conversion attribution. This channel shift is most visible in Lagos, where direct-to-consumer isolate sales through social commerce now outpace pharmacy distribution for premium SKUs.
Middle East and Africa Whey Protein Market Segmentation
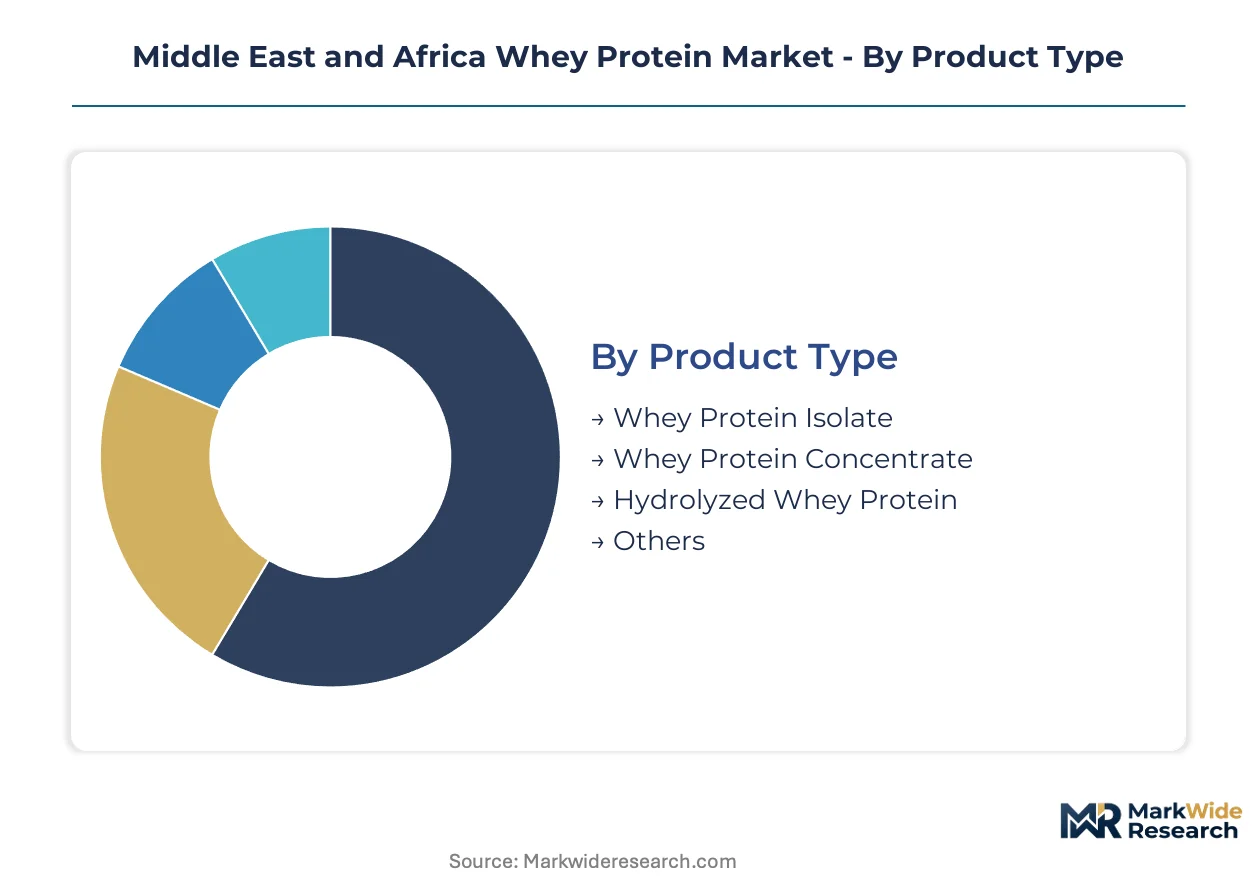
Whey protein segmentation across the Middle East and Africa reveals distinct demand corridors shaped by halal certification requirements, urban fitness infrastructure maturity, and e-commerce penetration gaps. Each dimension exposes where formulation investments concentrate versus where distribution shortcuts unlock volume.
Product Type:
Cost tier differentiation determines margin architecture and production capital requirements across whey protein formats.
- Whey Protein Isolate:Protein content exceeds 90% by dry weight with minimal lactose and fat residues. Premium athlete formulations in Saudi Arabia and the UAE leverage isolate positioning to command shelf space in pharmacy and specialty retail channels where SFDA allergen disclosure mandates elevate transparency premiums.
- Whey Protein Concentrate:Protein content ranges from 34% to 80% depending on filtration grade, delivering cost-accessible nutrition for mass-market applications. Egyptian bodybuilding retail corridors and Nigerian fitness club networks concentrate concentrate demand where price sensitivity dominates purchase decisions.
- Hydrolyzed Whey Protein:Enzymatic pre-digestion creates smaller peptide fractions for rapid absorption in clinical and elite athletic protocols.
- Others:Includes native whey and whey protein hydrolysate variants serving niche medical nutrition and infant formula specifications.
Whey Protein Concentrate commands the established base. The steepest expansion runs through Whey Protein Isolate as Gulf premiumization accelerates.
Application:
End-use functionality dictates formulation complexity, certification burden, and channel placement strategy.
- Nutritional Supplements:Powder and ready-to-drink formats dominate gym-adjacent retail with protein-per-serving claims driving purchase comparison. Urban Nigeria and Kenya generate concentrated demand nodes as fitness club penetration rises and localized blending investments shorten last-mile distribution economics.
- Food & Beverage:Mass-market fortification applications span dairy beverages, breakfast cereals, and functional drinks where South Africa's Department of Health enforces strict additive claim constraints.
- Bakery Products:Protein-enriched bread and snack applications face formulation challenges from Maillard reaction browning and texture modification requirements.
- Dairy Products:Yogurt and cheese fortification leverages existing cold chain infrastructure but competes with native milk protein cost structures.
Food & Beverage captures volume scale through retail distribution density. Nutritional Supplements climbs fastest as gym network expansion outpaces traditional grocery channel growth.
Distribution Channel:
Channel selection reflects infrastructure maturity, consumer discovery behavior, and margin capture potential across urban and peri-urban markets.
- Online Retail:Mobile payment penetration and logistics platform maturation in Kenya and Nigeria enable direct-to-consumer isolate sales bypassing underdeveloped health food retail networks. Social commerce through Instagram and TikTok creator partnerships now outpace pharmacy distribution for premium SKUs in Lagos.
- Supermarkets:Mass-market concentrate placement depends on cold chain reliability and shelf-space negotiation with pan-African retail chains.
- Health Food Stores:Specialty retail concentrates in South Africa's urban centers and the UAE's mall-based wellness corridors.
- Specialty Stores:Cairo's concentrated supplement districts and Johannesburg's bodybuilding retail clusters offer brand-building density before national distribution scale.
Supermarkets anchor mass-market volume throughput. Online Retail gains share fastest as digital payment infrastructure and last-mile logistics mature across East and West Africa.
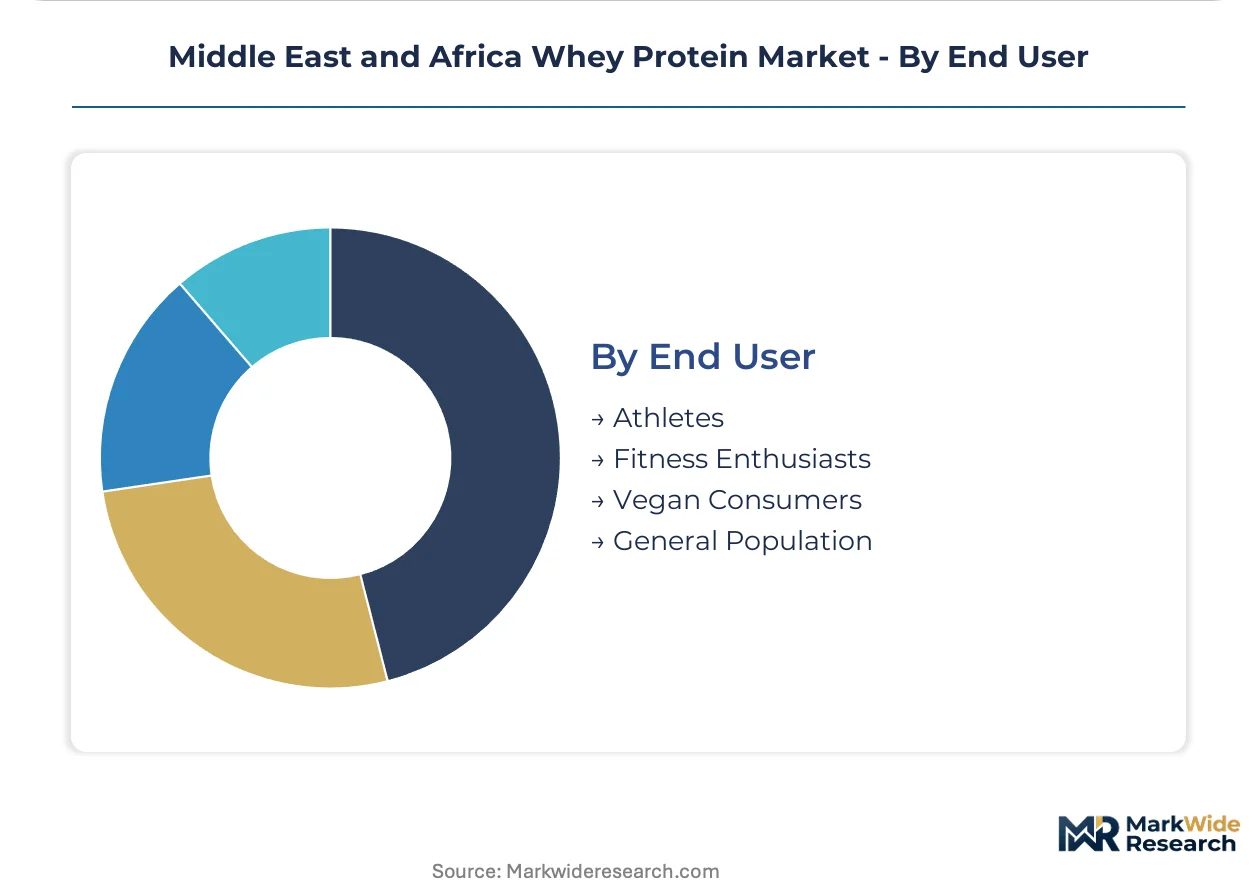
End User:
Customer type segmentation exposes where education investment converts trial to repeat purchase versus where latent demand awaits activation.
- Athletes:Competitive and recreational athletes in the UAE, Saudi Arabia, and South Africa drive isolate-grade demand with performance-linked purchase justification and subscription replenishment patterns.
- Fitness Enthusiasts:Urban gym members across Lagos, Nairobi, and Cairo represent the expansion frontier where first-time whey adoption concentrates.
- Vegan Consumers:Plant-forward dietary preference creates addressable demand for hybrid formulations and clear allergen labeling transparency.
- General Population:Sarcopenia-conscious aging demographics in South Africa and clinical nutrition applications represent adjacent channel potential with reimbursement infrastructure development.
Fitness Enthusiasts represent the fastest-expanding trajectory as gym penetration rises across secondary African cities. Athletes defend the premium revenue base with highest per-capita spend and brand loyalty conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput capacity anchors the UAE's position as the primary whey protein import gateway for Gulf markets, with direct feeder connections to Red Sea and East African terminals.
Saudi Arabia
Fitness club membership in Riyadh and Jeddah has doubled since 2020, driving isolate-grade demand in pharmacy retail channels. SFDA mandates blockchain-traceable halal certification documentation for all imported whey protein isolates, forcing farm-to-facility digital audit trail implementation. Dammam's King Abdulaziz Port now handles specialized cold-chain whey concentrate shipments serving regional blending facilities.
United Arab Emirates
Dubai's mall-based wellness corridors concentrate premium supplement retail density unmatched elsewhere in the region. The Ministry of Industry and Advanced Technology aligns import protocols with GCC standardization requirements, creating uniform technical barriers for new market entrants. Abu Dhabi's Khalifa Port free zone hosts contract manufacturing operations supplying isolate formulations across the Gulf.
South Africa
Johannesburg's bodybuilding retail clusters and Cape Town's specialty fitness networks generate concentrated demand for performance nutrition. The Department of Health enforces strict food fortification standards that constrain whey protein additive claims in mass-market beverages. Durban's container terminal serves as the primary landing point for ocean-freight whey shipments feeding Southern African distribution networks.
Egypt
Cairo's concentrated supplement districts in Nasr City and Mohandessin offer brand-building density for premium isolate positioning before national scale. The country's national food safety regulator maintains evolving halal certification protocols that complicate synchronized multi-market launches with Gulf neighbors. Alexandria Port's expanded cold storage capacity now supports direct whey concentrate imports previously routed through European intermediaries.
Nigeria
Lagos fitness club networks and emerging gym penetration in Abuja create demand nodes justifying localized blending investments. The country's central pharmaceutical regulator maintains port-of-entry testing regimes that determine market access speed and compliance cost structures. Apapa Port's ongoing infrastructure upgrades aim to reduce temperature control deficiencies that accelerate protein denaturation in transit.
Middle East and Africa Whey Protein Market Competitive Landscape
On the supply side, the industry is consolidating around dairy cooperative structures with captive whey stream access and ocean-freight logistics capabilities spanning MEA port infrastructure gaps. Three strategic archetypes dominate: European dairy cooperatives with backward integration into whey processing, Australasian suppliers leveraging long-haul shipping networks, and regional African blenders adopting membrane filtration to reduce toll-manufacturing dependencies. Competitive moves center on halal certification pre-qualification to Saudi SFDA standards and cross-flow microfiltration technology licensing to mid-scale African processors.
Among European dairy cooperative specialists, Glanbia Nutritionals, Arla Foods Ingredients, and Fonterra Co-operative Group occupy positions exemplifying the integrated supply archetype. Glanbia Nutritionals represents isolate production scale deployed across GCC contract manufacturing relationships. Arla Foods Ingredients anchors competitive positioning through upstream control over European whey streams feeding African blenders. Fonterra Co-operative Group exemplifies supply reliability architecture built on ocean-freight logistics covering port infrastructure gaps from Mombasa to Durban.
| Leading Market Players |
|---|
| The Agropur Dairy Cooperative |
| Glanbia Nutritionals |
| Arla Foods Ingredients |
| Clover Industries |
| Fonterra Co-operative Group |
| Carbery Group |
| FrieslandCampina |
| Danone |
| Lactalis Ingredients |
| Others |
Supply & Pricing Matrix
European whey stream concentration risk determines both pricing tier spreads and supply chain shape across Middle East and Africa markets. Nordic dairy cooperative backward integration into processing infrastructure limits independent African blenders to volatile spot-market concentrate purchases, compressing margin architecture at the standard tier while elevating isolate premiums.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade isolate positioning from mass-market concentrate economics. Three-tier pricing stratifies across premium isolate, standard concentrate, and economy-grade blends with halal certification grade and ocean-freight delivery cost as primary differentiation drivers. Pricing pressure stems from European spot-market whey volatility feeding African blending operations. Mass-market Nigerian fitness clubs exhibit highest price sensitivity; Gulf pharmacy channels show lowest sensitivity due to performance-linked purchase justification.
Supply Chain Analysis
Export-control regime angles around membrane filtration technology licensing limit regional processing capability diffusion. Supply concentrates in Ireland, Denmark, and New Zealand as primary whey stream sources. Raw material dependencies center on cheese production byproduct streams, ceramic membrane components, and halal certification audit infrastructure. Single-source vulnerability runs through Jebel Ali Port's container throughput capacity as the Gulf's dominant import gateway. Distribution runs through ocean-freight bulk shipments to MEA port infrastructure with last-mile cold chain fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as gym penetration across urban Nigeria and Kenya creates concentrated demand nodes that justify localized blending investments before national distribution scale.
For Market Incumbents: Entrench Gulf pharmacy channel control through SFDA pre-certification to blockchain-traceable halal standards, blocking emerging European entrants from synchronized multi-market launches. Deepen upstream integration into ocean-freight logistics covering MEA port infrastructure gaps to defend against Australasian suppliers leveraging long-haul shipping network advantages. Priority investment centers on cross-flow microfiltration technology licensing to mid-scale African processors, converting toll-manufacturing dependencies into captive supply relationships.
For New Entrants and Emerging Players: Kenyan e-commerce infrastructure underpenetration offers direct-to-consumer isolate sales bypassing underdeveloped health food retail networks. Target Lagos social commerce channels where fitness influencer partnerships now outpace pharmacy distribution for premium SKUs. White-space opportunity concentrates in medical nutrition applications for sarcopenia management in aging South African populations with reimbursement infrastructure development. Go-to-market angle should leverage mobile payment penetration and logistics platform maturation for creator partnership programs with measurable conversion attribution.
For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors regional African blenders adopting membrane filtration to reduce European toll-manufacturing dependencies. Long-term viability over the next decade hinges on halal certification digitization and cold chain infrastructure investment. Acquisition target archetype: mid-scale processors with ceramic membrane cascade installations achieving isolate-grade production at sub-million-dollar facility investments. Signal to watch: Saudi SFDA blockchain-traceable certification mandate adoption speed across Egyptian and UAE manufacturers as harmonization indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Qualification | SFDA blockchain-traceable standards create uniform Gulf market entry barriers that favor early compliant suppliers. |
| Cross-Flow Microfiltration Licensing | Ceramic membrane technology transfer collapses isolate production capital barriers for mid-scale African processors. |
| Direct-to-Consumer E-Commerce Launch | Mobile payment penetration in Kenya and Nigeria enables isolate sales bypassing underdeveloped health food retail. |
| Medical Nutrition Channel Development | Hospital-grade whey for sarcopenia management in South Africa opens adjacent clinical reimbursement potential. |
| Ocean-Freight Logistics Expansion | Port infrastructure gap coverage from Mombasa to Durban anchors supply reliability against European cooperative dominance. |
Research Methodology
Operator-level perspectives from dairy cooperative procurement directors, African blending facility managers, Gulf pharmacy retail buyers, and fitness club supplement purchasers anchored the qualitative base. Primary interview insights combined with secondary validation from customs trade records, GCC standardization body filings, SFDA regulatory databases, and dairy industry cooperative disclosures. Bottom-up demand modeling across gym penetration metrics and top-down supply analysis through European whey stream production data enabled triangulation.
Scenario-bracketing framed analytical approach across the projection horizon with segmentation dimensions spanning product type tier, application end-use, distribution channel maturity, and urban fitness infrastructure development stage. CAGRs derived from gym network expansion trajectories, e-commerce penetration curves, and halal certification timeline variability. Industry-specific forecast inputs incorporated membrane filtration technology adoption rates and blockchain-traceable documentation implementation speeds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European dairy cooperatives expanding direct African blending investments would shift outcomes. Material shifts in Saudi SFDA certification protocol harmonization across GCC markets or cold chain infrastructure investment acceleration in Nigerian and Kenyan logistics networks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Camel Dairy Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Plain Yogurt Market
Dairy Products
Milk Mineral Market
Dairy Products
Flavoured Milk Market
Dairy Products
Butter Powder Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
GCC Dairy Market
Dairy Products
Low-Fat Cheese Nutrition Market
Dairy Products
White Cheese Market
Dairy Products
Halal Cheese Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Flavored Yogurt Market