
 GCC Camel Dairy Market | 2026-2036
GCC Camel Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Camel Dairy Market Intelligence
Saudi Arabia's central Najd region is repositioning its camel herd management toward commercial dairy output. Al Ain Farms for Livestock Production anchors production scale across the UAE's interior emirates. Camelicious LLC leverages its integrated farm-to-bottle infrastructure to sustain supply continuity during peak summer months. Desert Farms Inc. competes through direct-to-consumer channels that bypass traditional retail markups.
Camel dairy encompasses milk, fermented products, and derivatives extracted from Camelus dromedarius herds, typically processed under low-temperature pasteurization to preserve immunoglobulin and lactoferrin content; the category serves nutritional, functional food, and premium gastronomy applications. Milk commands the dominant volume position within product type segmentation due to its use across infant nutrition and sports recovery formulations. Online retail represents the fastest-expanding distribution channel, though supermarkets still capture the largest margin pool through private-label placement and chilled logistics investment.
GCC national food safety authorities enforce halal certification alongside CODEX-aligned dairy standards, while Saudi Food and Drug Authority and UAE Ministry of Industry and Advanced Technology regulate labeling claims for camel milk's purported therapeutic properties. Stakeholders must track evolving shelf-life extension protocols and cold chain compliance costs as product formats diversify beyond fresh liquid milk.
Market Dynamics
UAE Ministry of Climate Change and Environment livestock welfare mandates are compressing farm certification timelines and redrawing competitive boundaries across the Gulf dairy landscape.
Growth Catalysts
- SFDA therapeutic labeling pathways:Saudi Food and Drug Authority protocols for immunoglobulin content claims unlock premium positioning in infant nutrition formulations.
- Dubai chilled logistics infrastructure:Jebel Ali port cold chain investments slash spoilage rates for fresh liquid milk exports to Southeast Asian diaspora markets.
- Lactoferrin extraction scale-up:Bioseparation membrane technology cuts protein recovery costs by half, enabling sports nutrition contract manufacturing.
Market Restraints
- Alfalfa import dependency:GCC camel herds rely on Jordanian and Sudanese fodder supplies exposed to Red Sea shipping disruptions.
- Dromedary lactation biology:Shorter milking windows and lower daily yields versus bovine systems cap unit economics at commercial scale.
- CODEX alignment costs:Dual compliance with Gulf Standards Organization and international dairy codes strains mid-tier processor margins.
Strategic Opportunities
- Kuwait retail underpenetration:Specialty grocer shelf space for camel dairy remains below two percent of fresh milk facings, creating first-mover vacancy.
- Fermented product line extensions:Labneh and kefir formats attract lactose-intolerant consumer segments underserved by conventional dairy.
- Direct-to-subscription channels:Cold-chain-enabled home delivery bypasses supermarket margin stacking and captures recurring revenue.
Industry Challenges
- Veterinary specialist scarcity:Dromedary reproductive health expertise concentrates in Al Ain and Riyadh, constraining herd expansion in secondary Emirates.
- Halal certification latency:Multi-stage slaughter-byproduct clearance for whey derivatives extends new product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Camel Dairy Market |
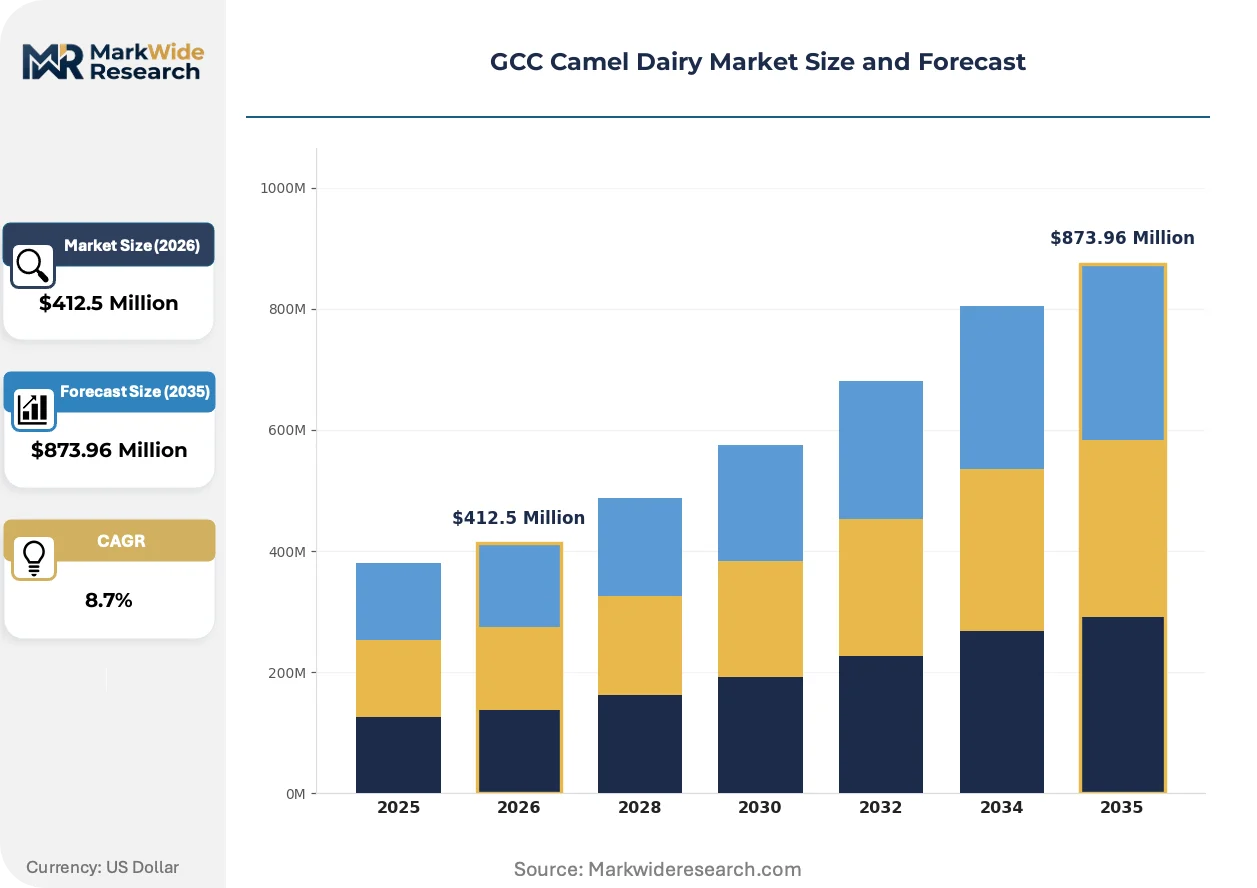
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Ice Cream, Yogurt Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales End User: Households, Restaurants, Cafes, Health Clubs Pricing Model: Premium, Mid-Range, Budget, Subscription |
| Companies Covered | Al Safi Dairy Company, Qcamel, Al Ain Farms for Livestock Production, Camilk Dairy, Desert Farms Inc., Camelicious LLC, Al Ain Dairy, Camel Dairy Farm Smits, Al Nassma Chocolate LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Camel Dairy Market Strategic Shifts & Innovations
Processing technology and distribution infrastructure are converging to compress product development cycles and unlock shelf-stable formats previously unavailable to camel dairy processors.
Ultrafiltration ceramic membrane systems is electrifying protein fractionation capabilities at Al Ain Farms and Camelicious facilities. Sports nutrition brands in the UAE now specify immunoglobulin-enriched isolates for post-workout formulations. The technology is compressing raw material waste ratios from forty percent to under fifteen percent, reshaping cost structures for premium ingredient suppliers.
UAE Ministry of Industry and Advanced Technology has tightened nutritional claim substantiation requirements for camel milk therapeutic properties. Processors must now submit clinical trial summaries to SFDA-equivalent review panels before packaging health assertions. Infant formula segments face the steepest compliance burden, with several Riyadh-based brands reformulating labels to remove unverified immunity claims.
Specialty retailers in Dubai and Riyadh are unbundling camel dairy from commodity milk aisles into standalone functional food sections. Pharmacists at BinSina and Life Health stores now stock chilled camel milk alongside probiotic supplements, displacing traditional supermarket placement. This channel rotation concentrates margin capture in health-and-wellness retail formats where price elasticity runs lower than mass grocery.
GCC Camel Dairy Market Segmentation
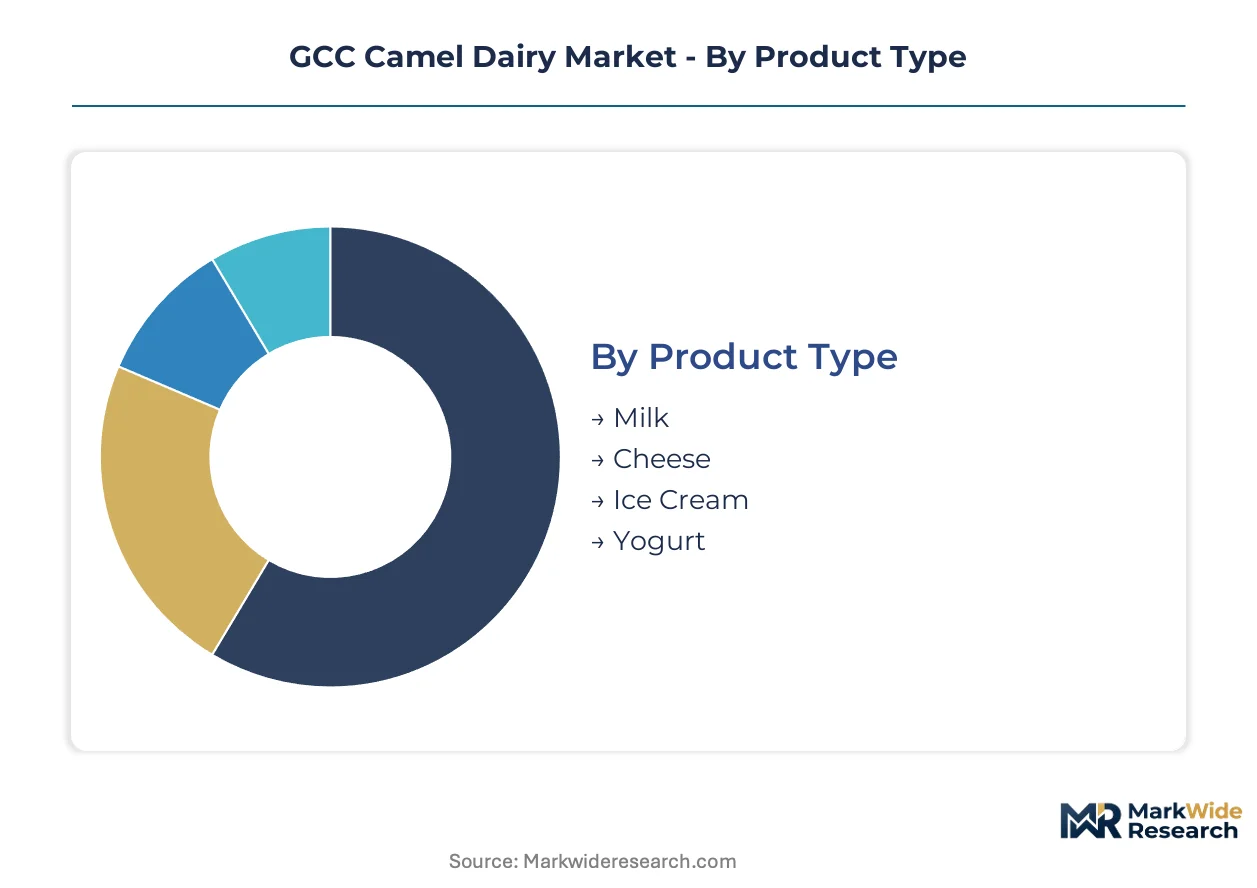
Camel dairy processors in the Gulf must align product formats with distinct consumption occasions and channel economics. Segmentation reveals where margin pools concentrate versus where volume scales fastest across the GCC's fragmented retail landscape.
Product Type:
Supply concentration in fresh liquid processing dominates capital deployment across Saudi Arabia and the UAE.
- Milk:Low-temperature pasteurization preserves immunoglobulin and lactoferrin bioactivity. Demand concentrates in Dubai and Riyadh infant nutrition formulations where SFDA therapeutic labeling unlocks premium positioning.
- Cheese:Soft white varieties and aged styles require controlled ripening infrastructure that few Gulf processors have mastered. Production gravity centers on Al Ain Farms' integrated facilities serving UAE hospitality procurement.
- Ice Cream:Churned formulations with elevated fat content target summer consumption peaks in Jeddah and Doha.
- Yogurt:Drinking and set varieties attract lactose-intolerant segments across Kuwait and Bahrain.
Today's leader: Milk. Tomorrow's challenger: Cheese.
Distribution Channel:
Channel cost structures determine which formats reach profitability at commercial scale.
- Supermarkets:Chilled logistics investment and private-label placement capture the largest margin pool. Carrefour and Lulu Hypermarket dominate shelf space allocation in Dubai and Riyadh.
- Online Retail:Cold-chain-enabled home delivery bypasses traditional retail markups. This channel is expanding most quickly through subscription models targeting recurring revenue.
- Specialty Stores:Pharmacist-staffed health formats at BinSina and Life Health displace commodity placement with functional food positioning.
- Direct Sales:Farm-to-door subscription bypasses margin stacking entirely. Desert Farms Inc. anchors this channel across UAE expatriate segments.
Supermarkets still command volume leadership. Online retail shows the steepest expansion trajectory.
End User:
User type dictates formulation specifications and packaging formats across the GCC.
- Households:One-liter and two-liter chilled formats dominate weekly purchase cycles in Saudi urban centers.
- Restaurants:Foodservice specifications require extended shelf-life UHT variants for kitchen inventory management.
- Cafes:Barista-grade frothing properties drive procurement decisions in Dubai's specialty coffee segment.
- Health Clubs:Sports recovery formulations with elevated protein content attract post-workout consumption in Abu Dhabi and Doha.
Households anchor current demand. Health clubs represent the emerging volume frontier.
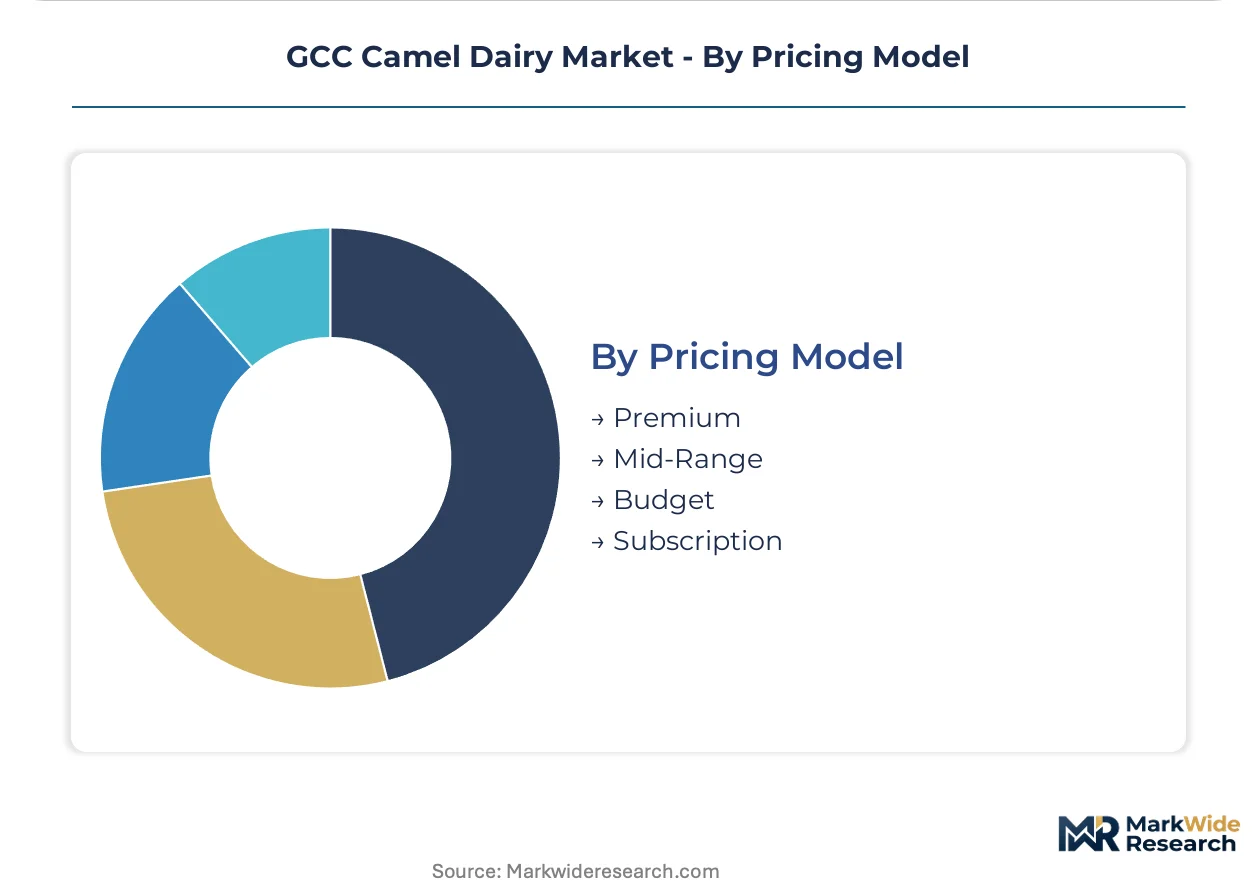
Pricing Model:
Price tier alignment with certification grade and channel type determines margin capture.
- Premium:Organic and therapeutic-grade certifications command shelf space in Dubai Mall and Riyadh Park retail formats.
- Mid-Range:Standard halal-certified products balance accessibility with quality signaling across Lulu and Carrefour.
- Budget:Private-label placement targets price-sensitive segments in Saudi mass grocery.
- Subscription:Recurring delivery models lock in customer lifetime value through cold-chain reliability guarantees.
Premium tiers capture margin leadership. Subscription models are gaining share fastest among urban professionals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE and Saudi Arabia have widened their regulatory-arbitrage advantage as Bahrain and Oman lag in livestock welfare certification timelines, drawing capital toward the two dominant production hubs.
Saudi Arabia
Riyadh and Jeddah households drive chilled camel milk consumption through weekly purchase cycles. The SFDA enforces therapeutic labeling protocols for immunoglobulin content claims, forcing reformulation of infant nutrition products. The central Najd region is repositioning camel herd management toward commercial dairy output with expanded pasteurization capacity.
United Arab Emirates
Dubai's premium retail infrastructure and health-conscious consumer segments overlap to concentrate demand. The UAE Ministry of Climate Change and Environment has tightened livestock welfare standards, pushing farms toward certified production protocols. Al Ain Farms anchors production scale across the interior emirates with integrated farm-to-bottle infrastructure.
Kuwait
Specialty grocer shelf space for camel dairy remains below two percent of fresh milk facings, creating first-mover vacancy for entrants. The country's national food safety authority enforces halal certification alongside CODEX-aligned dairy standards. Kuwait City retail clusters show emerging demand for fermented formats targeting lactose-intolerant segments.
Qatar
Doha's hospitality procurement channels absorb extended shelf-life UHT variants for kitchen inventory management. The central veterinary authority maintains strict import protocols for Jordanian and Sudanese fodder supplies. Health clubs in the capital represent an emerging volume frontier for sports recovery formulations.
Bahrain
Manama's supermarket chains capture private-label placement opportunities with chilled logistics investment. The national standards body aligns with Gulf Standards Organization dairy codes but lacks specialized camel dairy inspection capacity. Secondary retail penetration trails the Saudi and UAE benchmarks by three to five years.
GCC Camel Dairy Market Key Industry Players
UAE producers anchor one tier; Saudi specialists hold integrated processing advantages. The vendor base clusters around three to four dominant entities with farm-to-bottle infrastructure, while mid-tier processors struggle with CODEX alignment costs. Strategic archetypes include integrated farm-processor hybrids, direct-to-consumer subscription operators, and hospitality-focused ingredient suppliers. Capacity expansion and cold chain partnerships represent the dominant competitive moves across the analysis window.
Within the integrated farm-processor tier, Al Ain Farms for Livestock Production and Camelicious LLC exemplify captive supply and processing control. Desert Farms Inc. occupies a position among direct-to-consumer specialists, bypassing traditional retail markups through subscription channels. Al Safi Dairy Company represents the scale-driven archetype with broad retail distribution across Saudi urban centers.
| Leading Market Players |
|---|
| Al Safi Dairy Company |
| Qcamel |
| Al Ain Farms for Livestock Production |
| Camilk Dairy |
| Desert Farms Inc. |
| Camelicious LLC |
| Al Ain Dairy |
| Camel Dairy Farm Smits |
| Al Nassma Chocolate LLC |
| Others |
Cost & Logistics Intelligence
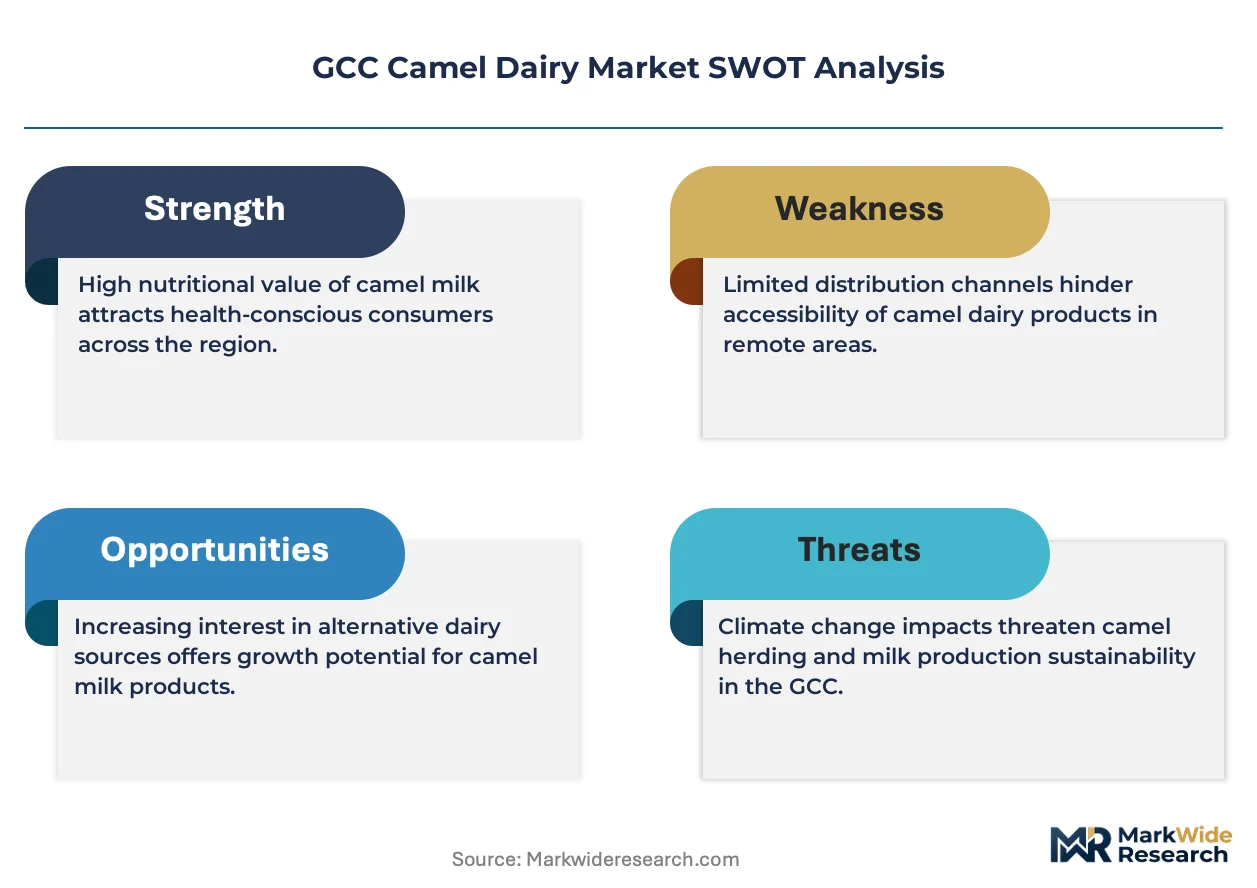
Captive supply integration across Al Ain and Riyadh production clusters anchors both procurement stability and premium pricing power for GCC camel dairy processors. This structural choice concentrates cost control in the hands of integrated farm-processor hybrids while insulating them from spot-market fodder volatility that strains mid-tier competitors.
Pricing Analysis
Retailer markup layers at Carrefour and Lulu Hypermarket compress processor margins by fifteen to twenty percent versus direct-to-consumer channels. Pricing stratifies across therapeutic-grade certifications, volume scale, and cold-chain reliability guarantees. Cost compression in mid-tier halal-certified segments is intensifying because CODEX alignment expenses compound with alfalfa import tariffs. Household buyers in Saudi urban centers exhibit highest price sensitivity, while Dubai Mall premium formats serve least elastic demand.
Supply Chain Analysis
Dual-sourcing requirements for Jordanian and Sudanese alfalfa shipments are mandating multi-supplier qualification across GCC camel herds. Geographic supply concentration centers on the UAE and Saudi Arabia, with secondary inputs drawn from Egyptian veterinary equipment suppliers. Raw material dependencies encompass imported fodder, ceramic membrane filtration systems, and halal-certified packaging substrates. Single-source vulnerability runs through Red Sea shipping corridors. Distribution feeds from farm-gate through chilled logistics networks to supermarket private-label placement and subscription direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC camel dairy functions as a stable compounder anchored by irreversible dietary shifts toward functional foods and infant nutrition formulations. Regulatory tailwinds from SFDA therapeutic labeling protocols reinforce premium tier expansion across the analysis window.
For Market Incumbents: Deploy certification investment as the primary defensive lever. SFDA immunoglobulin claim substantiation requirements threaten unverified infant nutrition brands with forced reformulation. Incumbents should deepen upstream control over dromedary herd genetics in the Najd region while locking in multi-year fodder supply contracts with Sudanese exporters. Channel control through pharmacist-staffed health formats at BinSina displaces vulnerable supermarket placement. For New Entrants and Emerging Players: SFDA therapeutic labeling pathways in Saudi Arabia open a window for first-mover positioning in immunoglobulin-enriched sports recovery formulations. Kuwait retail underpenetration offers immediate shelf space vacancy below two percent fresh milk facings. Fermented product line extensions targeting lactose-intolerant Bahraini and Kuwaiti households provide the most penetrable entry vector. A direct-to-subscription go-to-market angle bypasses incumbent-dominated retail margin stacking entirely. For Investors and Strategic Acquirers: Roll-up economics work for integrated farm-processor hybrids because veterinary specialist scarcity in secondary Emirates constrains organic expansion for fragmented mid-tier operators. Long-term viability centers on five-to-ten year compounder returns from recurring subscription revenue and therapeutic-grade certification premiums. Acquisition targets should display captive dromedary herds plus existing SFDA or MOHAP regulatory clearances. The signal to watch is veterinary specialist licensing velocity in Oman and Bahrain as herd expansion constraint indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dromedary Genetics | Najd region herd expansion secures captive supply against Sudanese fodder disruption. |
| Therapeutic Certification Investment | SFDA immunoglobulin claim clearance unlocks infant nutrition premium positioning. |
| Direct-to-Subscription Channel Launch | Cold-chain home delivery captures recurring revenue from UAE expatriate segments. |
| Fermented Product Line Extension | Labneh and kefir formats penetrate lactose-intolerant Kuwait and Bahrain households. |
| Pharmacist-Staffed Retail Partnership | BinSina and Life Health placement displaces commodity supermarket positioning. |
Research Approach
Direct dialogue with dairy processing executives, veterinary herd managers, SFDA regulatory affairs leads, supermarket category buyers, and cold-chain logistics operators grounded qualitative insights. Secondary validation drew from SFDA therapeutic labeling guidelines, UAE Ministry of Climate Change and Environment livestock welfare mandates, CODEX dairy standards documentation, and GCC customs trade records. Bottom-up volume modeling and top-down value reconciliation triangulated market sizing across product type, distribution channel, and end-user segments.
Bottom-up demand modeling tracked consumption occasions through household purchase cycles, foodservice procurement patterns, and health club sports nutrition uptake. Segmentation dimensions encompassed product format, channel economics, user type, and pricing tier alignment with certification grade. CAGRs were derived from trend extrapolation anchored in documented regulatory shifts and infrastructure investment trajectories. Forecast inputs included dromedary lactation yield curves, ceramic membrane protein recovery cost trajectories, and chilled logistics capacity expansion timelines.
Revisions become necessary when Red Sea shipping disruptions extend beyond current contingency horizons, SFDA accelerates therapeutic claim substantiation timelines, or veterinary specialist training programs expand capacity in secondary Emirates. Deviation in fodder import dependency ratios would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Low Fat Cheese Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Sour Cream Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Milk Mineral Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Latin America Cheese Market
Dairy Products
India Milk Protein Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Argentina Whey Protein Market