
 Yogurt and Probiotic Drink Market | 2026-2036
Yogurt and Probiotic Drink Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt and Probiotic Drink Market Intelligence
The fragmentation of demand across new consumer segments like fitness enthusiasts and seniors is rebalancing competitive focus. Danone S.A. leverages its extensive global distribution network to reach these diverse consumer groups. Chobani LLC differentiates through high-protein Greek yogurt formulations. Meanwhile, Yakult Honsha Co., Ltd. specializes in concentrated probiotic shots, maintaining a strong brand legacy in key Asian markets.
Yogurt and probiotic drinks are fermented dairy or non-dairy products containing live microorganisms, such as Lactobacillus and Bifidobacterium species. Their primary commercial purpose is to deliver beneficial bacteria to the digestive system to support gut health and immune function. While drinkable yogurt formats command significant volume, the dairy-free probiotics segment represents the fastest-growing category. Supermarkets remain the dominant distribution channel, but online retail gains share through subscription models and targeted marketing.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) scrutinize health claims associated with specific probiotic strains. These regulations directly influence product labeling, marketing language, and the scientific evidence required to substantiate functional benefits. Navigating the evolving scientific standards for proving specific health outcomes remains a central challenge for manufacturers and innovators.
Market Dynamics
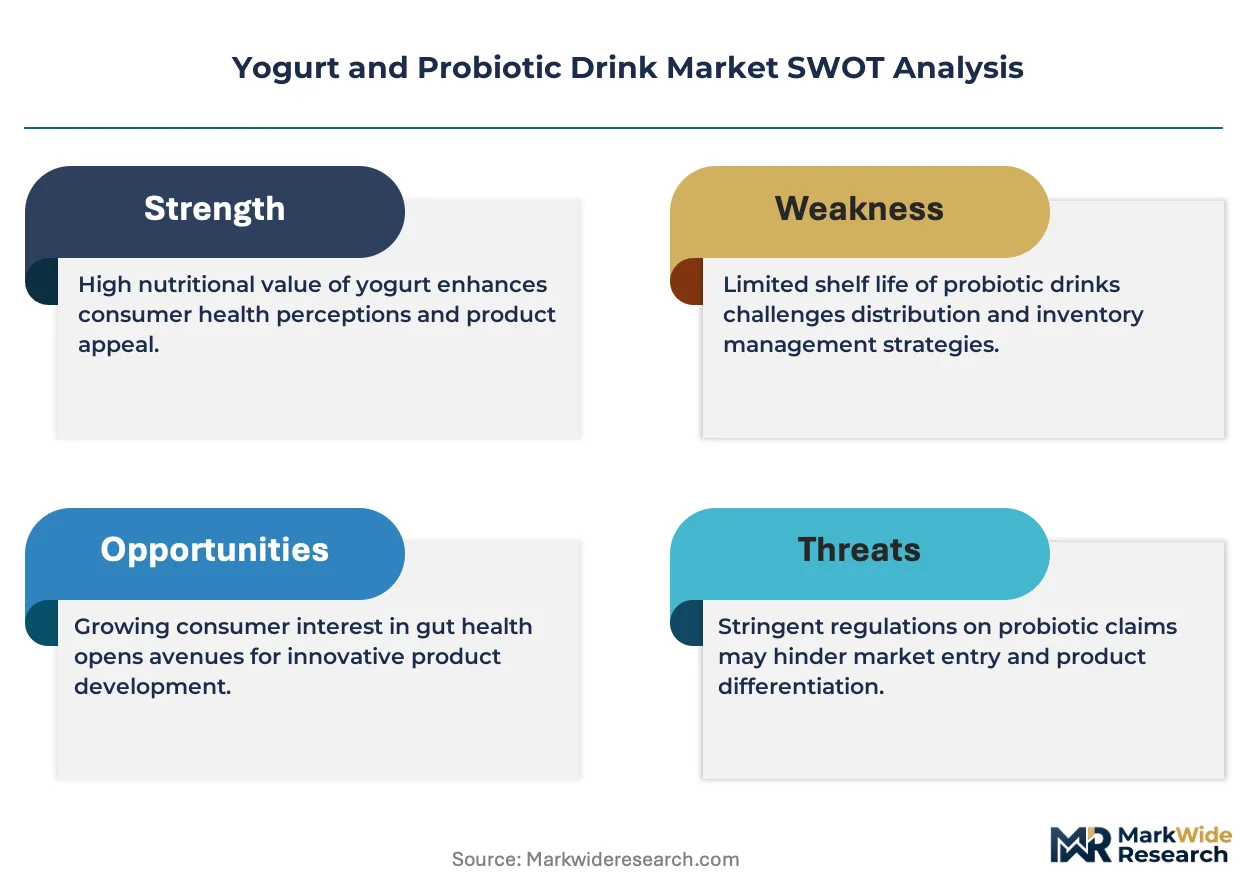
The market's central dynamic is the tension between consumer demand for functional health benefits and the rigorous scientific and regulatory burden of proof. This conflict shapes R&D investment, marketing claims, and the competitive landscape for all manufacturers.
Growth Catalysts
- Dairy-Free Innovation:Advances in fermentation technology for non-dairy bases like oat, almond, and soy expand the consumer base to include those with lactose intolerance or plant-based dietary preferences.
- Segmented Health Demand:Targeted demand from distinct consumer groups, such as fitness enthusiasts seeking protein-rich options in the United States or seniors focused on digestive health, creates new product development pathways.
- Scientific Validation:A growing body of clinical research linking specific probiotic strains to tangible health outcomes, supported by dietary guidelines from bodies like the WHO, strengthens consumer trust and validates product claims.
Market Restraints
- Input Cost Volatility:Fluctuation in the price of raw milk, a primary input for traditional yogurt, directly impacts production costs and puts pressure on manufacturer margins, especially in commodity segments.
- Regulatory Scrutiny:Stringent health claim regulations, particularly from the European Food Safety Authority (EFSA), require extensive and costly clinical trials, limiting the scope of marketing language for many products in Europe.
- Shelf-Life Stability:Maintaining the viability and potency of live probiotic cultures throughout the product's entire shelf life poses a significant technical and logistical challenge, impacting product efficacy and consistency.
Strategic Opportunities
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America, including countries like Indonesia and Brazil, offer significant growth potential as disposable incomes rise and awareness of gut health increases.
- Personalized Nutrition:The emergence of at-home microbiome testing creates an opportunity for personalized probiotic drink formulations tailored to an individual's specific gut health needs and deficiencies.
- Channel Diversification:Direct-to-consumer subscription models provide a pathway to build direct customer relationships, gather data, and bypass the competitive shelf space of traditional supermarket retailers.
Industry Challenges
- Cold Chain Complexity:Ensuring an unbroken cold chain from production to final consumption is a critical operational challenge, particularly for products distributed through online channels or exported over long distances.
- Fragmented Labeling Rules:Manufacturers face the complex and costly task of adapting product labels and health claim language to comply with disparate regulations set by authorities like the FDA and EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt and Probiotic Drink Market |
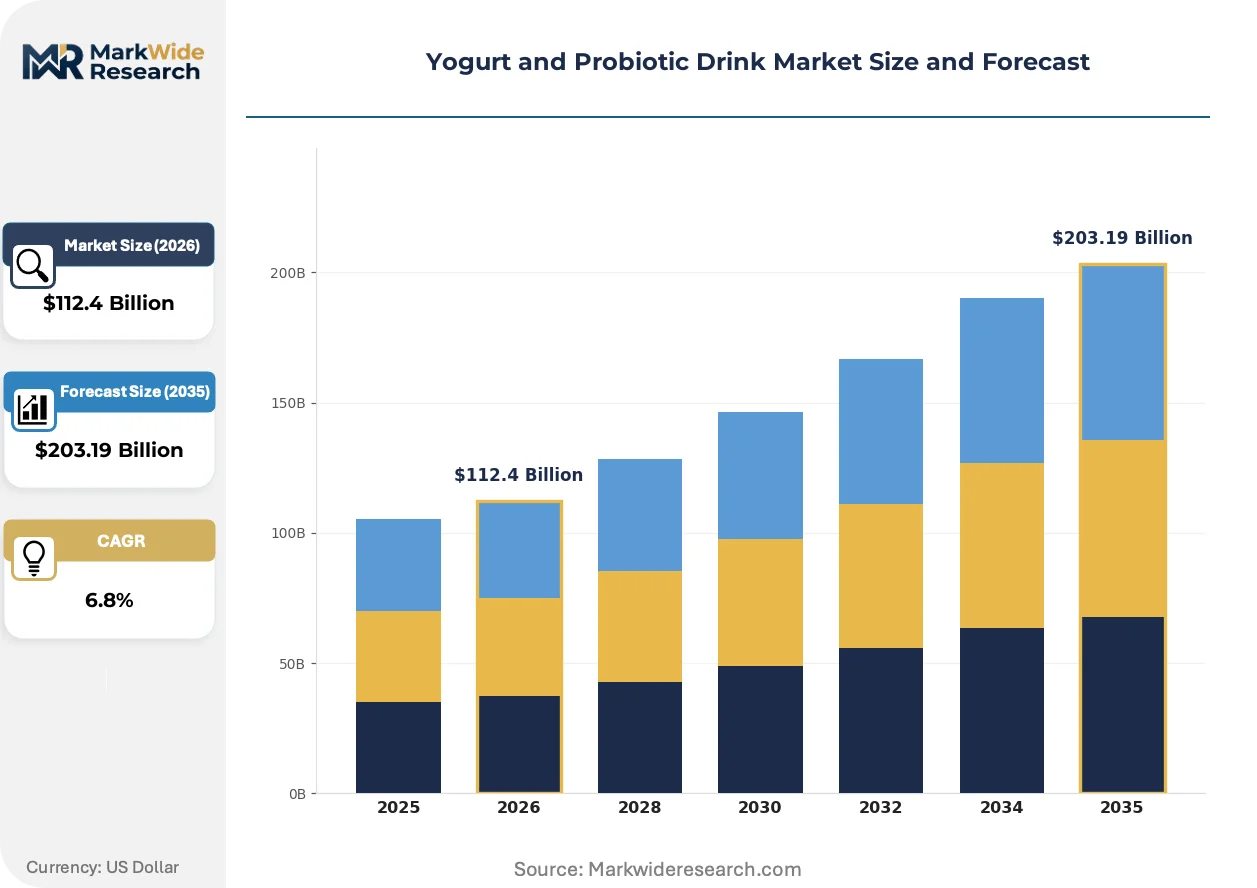
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
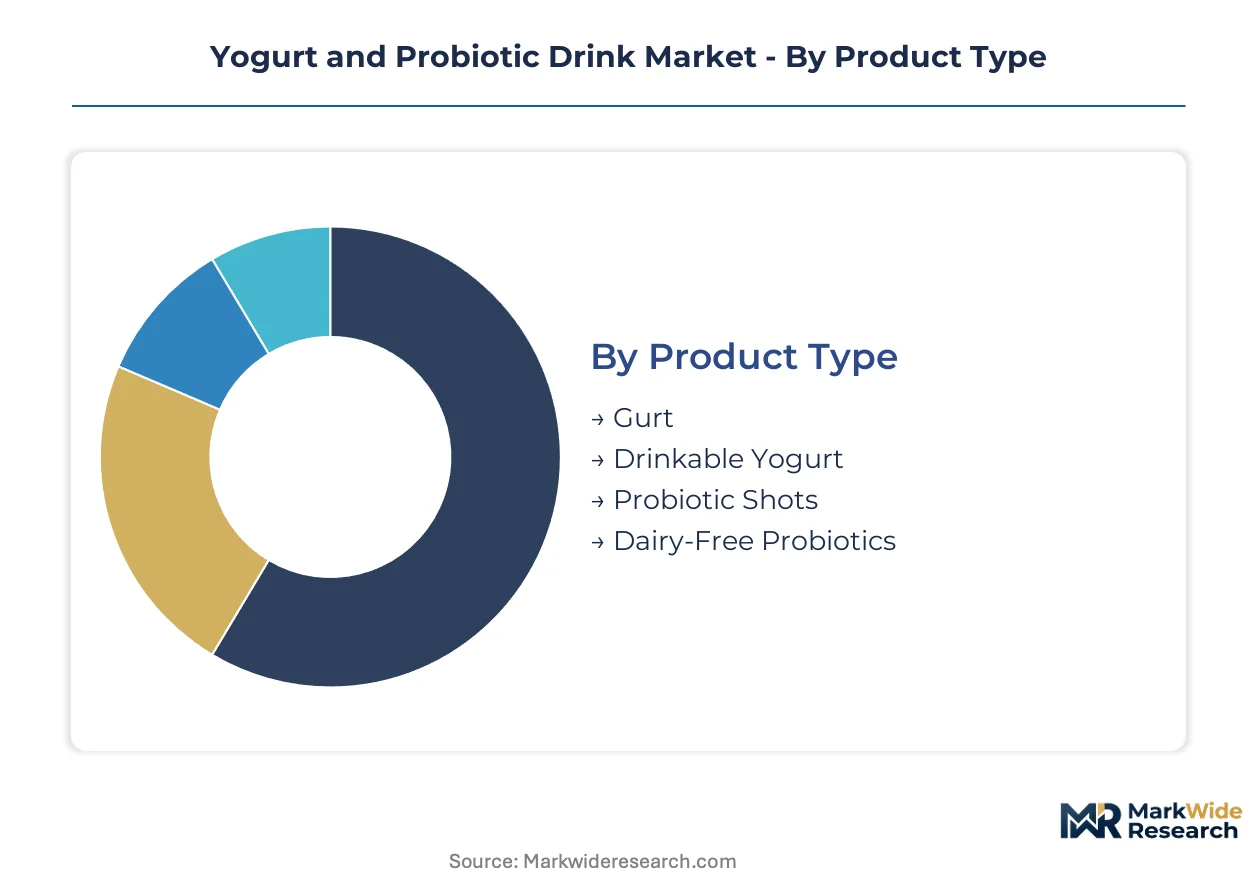
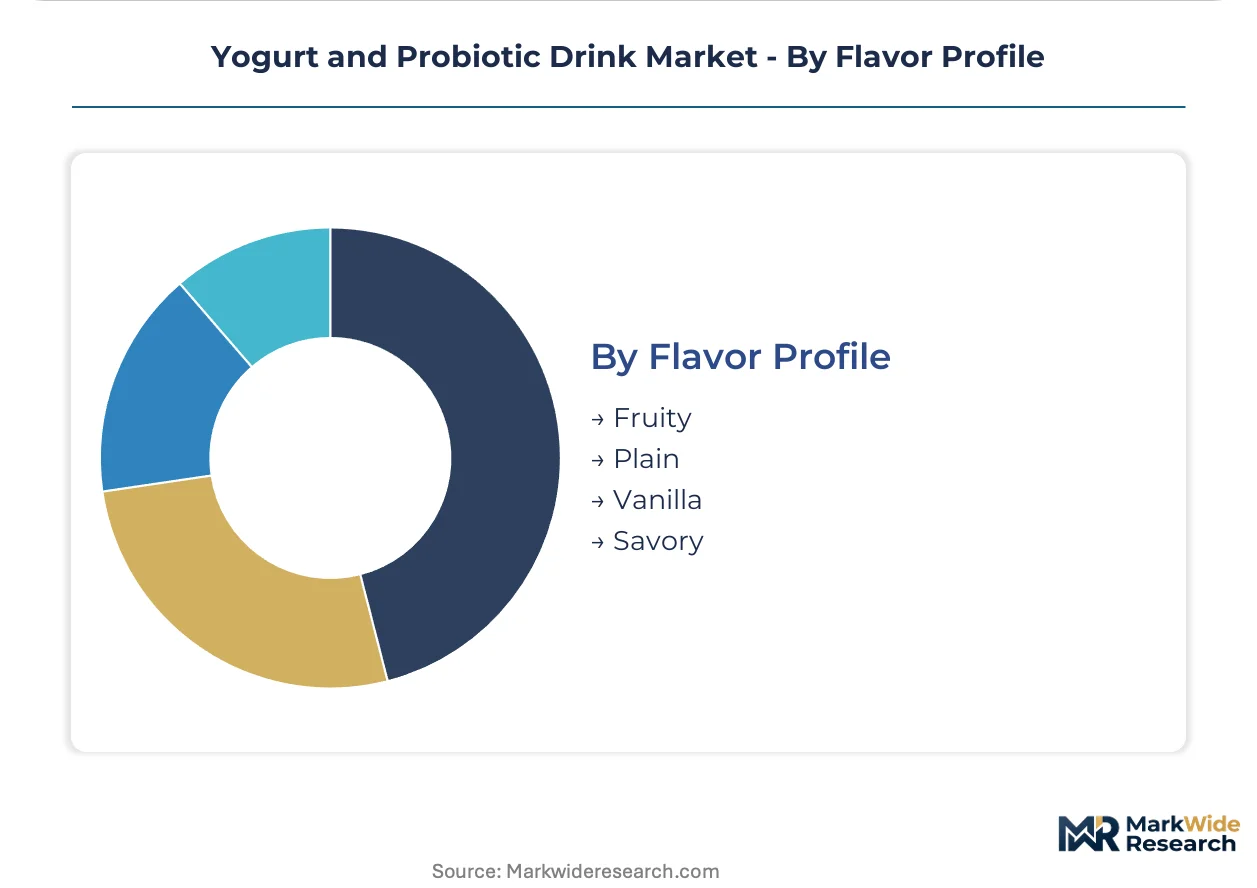
| Segmentation | Product Type: Gurt, Drinkable Yogurt, Probiotic Shots, Dairy-Free Probiotics Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores End User: Health-Conscious Consumers, Fitness Enthusiasts, Children, Seniors Flavor Profile: Fruity, Plain, Vanilla, Savory |
| Companies Covered | Danone S.A., Chobani LLC, Nestlé S.A., Yakult Honsha Co., Ltd., General Mills Inc., Fage International S.A., Lactalis Group, Arla Foods amba, Grupo Lala, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt and Probiotic Drink Market Strategic Shifts & Innovations
The market is pivoting from generic wellness positioning toward scientifically-backed, strain-specific functionalities. This shift is driven by advancements in microbiology and a more discerning consumer base demanding tangible, verifiable health outcomes from the products they consume.
Precision Fermentation
Precision fermentation technology enables the cultivation of specific, non-GMO probiotic strains with well-documented health benefits. Functional food formulators and health-focused consumers are rapidly adopting products containing these targeted strains. This technology is absorbing R&D investment that was previously allocated to generic, multi-strain probiotic blends, pushing the industry toward evidence-based product development.
Regulatory Gateways
Japan's Foods for Specified Health Uses (FOSHU) system provides a clear regulatory pathway for products to gain official approval for scientifically substantiated health claims. This framework incentivizes manufacturers to conduct rigorous clinical trials on specific probiotic strains to validate benefits. The probiotic shot and drinkable yogurt segments are most impacted, with FOSHU certification serving as a powerful marketing tool in the Japanese market.
Subscription-Based Consumption
A significant behavioral change is underway as consumers increasingly purchase probiotic drinks via online subscription services and specialized e-commerce platforms. This model disrupts the dominance of traditional supermarket channels, especially for premium and niche dairy-free product lines. This trend is most advanced in North America and parts of Western Europe, where digital retail is mature and consumers value convenience.
Yogurt and Probiotic Drink Market Segmentation
Market segmentation provides a granular view of consumer preferences and product innovation within the yogurt and probiotic drink sector. Understanding these distinct categories helps manufacturers tailor offerings and optimize distribution strategies. Each segment reflects unique demand drivers and competitive dynamics across various geographies.
Product Type:
Segmentation by product type highlights the diverse formats available to consumers, driven by specific functional benefits and consumption occasions.
- Dairy-Free Probiotics:These products utilize plant-based alternatives like oat, almond, or soy milk as their base, fermented with live probiotic cultures. Demand concentrates in the United States and Western Europe, propelled by lactose intolerance and plant-based dietary trends.
- Drinkable Yogurt:Characterized by its liquid consistency, this format offers convenience and portability, making it suitable for on-the-go consumption. Significant volume is observed in markets like Brazil and Indonesia, where consumers seek accessible digestive health solutions.
- Gurt:Traditional spoonable yogurt, often thicker in texture, serves as a versatile food item for breakfast or snacks. This segment remains a staple in household consumption across countries like France and Germany, valued for its culinary applications.
- Probiotic Shots:Concentrated, small-volume beverages designed to deliver a potent dose of probiotics in a single serving. Japan and South Korea show strong demand for these functional shots, leveraging a legacy of probiotic consumption.
Drinkable Yogurt leads on scale; Dairy-Free Probiotics leads on momentum.
Distribution Channel:
The distribution landscape for yogurt and probiotic drinks is evolving, with traditional retail channels maintaining dominance while digital platforms gain traction.
The channel structure reflects consumer purchasing habits and product accessibility, influencing market reach and competitive strategy.
- Supermarkets:Large retail chains offering a wide selection of brands and product types, serving as the primary point of purchase for most consumers. These stores drive significant volume in the United States and the United Kingdom, benefiting from high foot traffic.
- Online Retail:E-commerce platforms and brand-specific websites facilitate direct-to-consumer sales, often featuring subscription models for recurring purchases. This channel is gaining share in Germany and Canada, appealing to consumers seeking convenience and specialized products.
- Health Food Stores:Specialized retailers focusing on organic, natural, and functional food products, often catering to niche consumer segments. These stores attract health-conscious buyers in Australia and Sweden, emphasizing premium and specialty probiotic options.
- Convenience Stores:Smaller retail outlets offering quick access to everyday essentials and grab-and-go items, including single-serve probiotic drinks. Japan and Thailand utilize this channel extensively for immediate consumption needs.
Supermarkets hold the largest volume, while Online Retail exhibits the steepest expansion trajectory.
End User:
Segmentation by end user reveals distinct consumer needs and preferences that drive product development and marketing efforts.
Customer type defines product formulation and marketing messages, targeting specific demographic or lifestyle segments.
- Health-Conscious Consumers:Individuals actively seeking products that support overall well-being, often prioritizing gut health and immune function. This broad segment underpins demand across countries like the United States and Canada, influencing product innovation.
- Fitness Enthusiasts:Consumers engaged in regular physical activity who seek products that support muscle recovery, energy, and digestive balance. High-protein Greek yogurt formulations in markets like the United Kingdom cater directly to this group.
- Seniors:Older adults who prioritize digestive regularity and immune support, often seeking products with targeted probiotic strains. This demographic drives demand for specialized formulations in Japan and Germany, focusing on age-related health concerns.
- Children:Young consumers whose parents seek nutritious and palatable options to support digestive health and immunity. Flavored drinkable yogurts are popular among children in Mexico and India, offering a convenient health benefit.
Health-Conscious Consumers represent the largest addressable market; Fitness Enthusiasts show strong purchasing power for specialized products.
Flavor Profile:
Flavor profile segmentation reflects consumer taste preferences and cultural influences, impacting product appeal and regional market success.
The flavor dimension categorizes products based on their dominant taste characteristics, influencing consumer acceptance and repeat purchases.
- Fruity:Products infused with various fruit flavors like strawberry, blueberry, or peach, appealing to a broad consumer base, especially children. These flavors dominate sales in the United States and China, offering palatable options.
- Plain:Unsweetened or lightly sweetened products, often preferred by consumers who value the natural taste of yogurt or use it as a culinary ingredient. This classic profile maintains strong demand in Greece and Turkey, reflecting traditional consumption.
- Vanilla:A popular and versatile flavor, often serving as a bridge between plain and more adventurous fruity options. Vanilla-flavored products are widely consumed in the United Kingdom and Australia, offering a familiar taste.
- Savory:Less common but emerging flavors, incorporating ingredients like vegetables, herbs, or spices, appealing to adventurous palates. This niche segment is gaining interest in specific European markets like Germany for culinary experimentation.
Fruity flavors command the largest market share; Savory options are gaining share fastest among niche consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' health-conscious consumer base anchors demand for functional foods, driving significant innovation in the yogurt and probiotic drink market. Regulatory frameworks from the U.S. Food and Drug Administration (FDA) influence product labeling and health claims. Silicon Valley and Boston-area biotech clusters foster R&D in new probiotic strains and fermentation technologies.
United States
A strong wellness culture and high disposable income drive demand for premium probiotic products. The U.S. Food and Drug Administration (FDA) sets labeling standards for probiotic strains and health benefits. California's food innovation hubs are developing new dairy-free formulations and personalized nutrition solutions.
Japan
A legacy of probiotic consumption and an aging population seeking digestive health solutions fuel demand for concentrated shots. Japan's Foods for Specified Health Uses (FOSHU) system provides a clear regulatory pathway for substantiated health claims. Tokyo's research institutions collaborate with manufacturers on advanced strain isolation and efficacy studies.
Brazil
Increasing awareness of gut health and a preference for convenient formats bolster the drinkable yogurt segment. Brazil's National Health Surveillance Agency (ANVISA) regulates probiotic product claims and ingredient safety. São Paulo's food processing centers are expanding capacity for accessible and affordable probiotic options.
France
Traditional culinary applications and a discerning consumer base sustain demand for high-quality, spoonable yogurts. The European Food Safety Authority (EFSA) provides stringent guidelines for probiotic health claims across the European Union. Paris-based dairy companies invest in heritage brands and artisanal fermentation techniques.
Indonesia
Rising disposable incomes and a youthful population adopting Western health trends create growth opportunities for drinkable formats. Indonesia's National Agency of Drug and Food Control (BPOM) oversees food safety and product registration for probiotic beverages. Jakarta's expanding retail networks are crucial for distributing new probiotic drink lines.
Yogurt and Probiotic Drink Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered market structure. Large food and beverage companies leverage extensive distribution networks, while agile startups innovate with niche product offerings. Strategic partnerships for technology licensing and geographic expansion are common competitive moves.
On the scale-driven end, Danone S.A. represents a global leader with broad product portfolios and significant market reach. Chobani LLC exemplifies a specialist in high-protein Greek yogurt formulations, catering to fitness enthusiasts and health-conscious consumers. Yakult Honsha Co., Ltd. occupies a distinct position with its long-standing brand legacy in concentrated probiotic shots, particularly strong in Asian markets.
| Leading Market Players |
|---|
| Danone S.A. |
| Chobani LLC |
| Nestlé S.A. |
| Yakult Honsha Co., Ltd. |
| General Mills Inc. |
| Fage International S.A. |
| Lactalis Group |
| Arla Foods amba |
| Grupo Lala |
| Others |
Cost & Logistics Intelligence
The clear bifurcation between premium, strain-specific probiotic drinks and commodity drinkable yogurts drives distinct pricing and supply chain strategies across this market.
Pricing Analysis
Capacity additions in Southeast Asia for drinkable yogurt are reshaping price floors for entry-level products. The dominant pricing structure is per-unit transactional, with subscription models gaining share for premium offerings. Price differentiation stems from specific probiotic strain efficacy, FOSHU certification in Japan, and brand premium. Regulatory scrutiny from the European Food Safety Authority creates pricing pressure by increasing clinical trial costs, while health-conscious consumers show lower price sensitivity for validated products.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like the United States and France influences production capacity for dairy-based products. Geographic supply concentration for raw milk centers on regions with extensive dairy farming; plant-based alternatives are sourced globally. Raw material dependencies include milk, oat, almond, and specific probiotic cultures. Maintaining cold chain integrity throughout the distribution process poses a significant logistical risk, as distribution primarily runs through supermarkets, with online retail gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yogurt and probiotic drink market presents a geographic-arbitrage play, leveraging lower production costs in Southeast Asia against premium pricing potential in the United States and Europe.
For Market Incumbents: To counter the margin pressure from rising input costs, incumbents should deepen vertical integration into dairy or non-dairy base production. Capacity additions for precision fermentation in the United States can also secure specialized probiotic strain supply. Investing in FOSHU certification for existing product lines in Japan strengthens market position. Channel control through exclusive supermarket partnerships maintains distribution dominance.
For New Entrants and Emerging Players: The price-point gap between premium, personalized probiotic formulations and mass-market options offers significant entry opportunities. Target fitness enthusiasts in the United Kingdom with high-protein, dairy-free Greek yogurt alternatives. Penetrate under-served markets like Indonesia with affordable, convenient drinkable formats. Direct-to-consumer subscription models provide an effective go-to-market angle for building customer loyalty and data insights.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized biotech firms developing novel, clinically validated probiotic strains. Long-term viability for the market hinges on scientific advancements linking specific strains to tangible health outcomes over the next decade. Acquisition targets should include precision fermentation startups with strong intellectual property in dairy-free technologies. Monitor the increasing adoption of at-home microbiome testing for early signals of personalized nutrition market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Investment | Accelerates development of non-GMO probiotic strains with documented health benefits, enhancing product efficacy. |
| Dairy-Free Product Line Expansion | Captures new consumer segments with lactose intolerance or plant-based dietary preferences in Western markets. |
| Geographic Expansion into Southeast Asia | Taps into rising disposable incomes and increasing gut health awareness in Indonesia and Brazil. |
| Direct-to-Consumer Subscription Launch | Builds customer relationships and gathers valuable data, bypassing competitive supermarket shelf space. |
| FOSHU Certification Pursuit in Japan | Validates health claims for specific probiotic shots, providing a powerful marketing tool. |
Research Approach
Direct dialogue with R&D directors, marketing managers, category buyers, and regulatory affairs specialists provided primary insights. This qualitative data was validated through extensive secondary research, including FDA and EFSA regulatory filings, company annual reports, and academic journals. The analysis integrated bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
A bottom-up approach estimated market size by product type, distribution channel, and end-user across the analysis window. This was cross-referenced with top-down industry reports for validation. Compound annual growth rates were derived from historical trends and projected consumer adoption patterns. Key inputs included advancements in dairy-free fermentation technologies and evolving regulatory standards for health claims.
Caveats apply where shifts in consumer health perceptions or new regulatory frameworks could materially shift the outlook. Forecasts reflect current market assumptions regarding scientific validation and input cost stability. Practitioners should monitor new clinical research on probiotic efficacy and evolving food safety regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Crumbles Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Japan Casein Market
Dairy Products
North America Sour Cream Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Gruyere Market
Dairy Products
Global Yogurt Market
Dairy Products
Condensed Whey Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Filled Cheese Market