
 Buttermilk Powder Market | 2026-2036
Buttermilk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Buttermilk Powder Market Outlook
Consolidation among North American bakery chains and quick-service restaurant networks is realigning procurement volumes toward long-term supply contracts with dairy processors. Fonterra Co-operative Group Limited leverages its New Zealand-origin milk pool to sustain cost advantages in export markets. Glanbia plc anchors its position through specialized nutrition-grade buttermilk fractions, while Arla Foods amba competes on European quality certifications and cooperative sourcing scale.
Buttermilk powder comprises spray-dried fermented dairy solids retaining lactic acid, phospholipids, and milk proteins at moisture levels typically below 5 percent, functioning primarily as an acidulant, emulsifier, and browning agent in formulated foods. Dried buttermilk and instant buttermilk variants dominate industrial procurement due to superior reconstitution stability and extended shelf life, with low-fat buttermilk gaining formulation share as fat-reduction mandates intensify across processed food categories. Baking and confectionery applications absorb the majority of volume, though dairy product manufacturers increasingly specify buttermilk powder for cultured product extensions and texture standardization.
The FDA governs identity standards for buttermilk powder under Title 21 CFR, while the USDA administers grading and inspection protocols that influence export eligibility and premium pricing tiers. EFSA and national regulators across the European Union enforce microbiological thresholds and labeling requirements that constrain non-EU supplier access. Stakeholders must monitor evolving clean-label definitions and carbon-footprint disclosure rules, as these frameworks increasingly determine contract eligibility with multinational food manufacturers.
Market Dynamics
Bakery chains and QSR networks are consolidating procurement around long-term supply contracts, compressing spot-market liquidity and elevating processor scale requirements for contract eligibility.
Growth Catalysts
- Clean-label mandates:FDA dairy identity standard updates under Title 21 CFR are forcing reformulation toward recognizable ingredient panels. Buttermilk powder replaces chemical emulsifiers in mass-market baked goods.
- Phospholipid functionality:Industrial food manufacturers value the natural lecithin-like properties in buttermilk powder for egg reduction and texture stabilization in cake mixes and pancake batters.
- Export-grade milk pools:New Zealand-origin supply chains deliver consistent protein specifications that meet USDA grading protocols for premium export tiers.
Market Restraints
- Fluid milk price volatility:Input cost swings in feed grains and energy directly transmit to buttermilk powder base pricing, squeezing processor margins during commodity spikes.
- Single-origin concentration:New Zealand and select EU cooperative processors dominate export-grade supply, creating geographic vulnerability to regional climate or regulatory shocks.
- Whey protein displacement:Whey isolates and modified starches compete for emulsification slots in cost-sensitive formulations, particularly in emerging-market biscuit production.
Strategic Opportunities
- Specialized nutrition fractions:High-protein buttermilk concentrates targeting sports nutrition and clinical applications command pricing premiums above commodity grades.
- Carbon-footprint disclosure rules:EU Green Deal supply-chain transparency requirements favor processors with verified low-emission milk sourcing and renewable energy drying operations.
- Direct-to-bakery distribution:Bypassing traditional ingredient distributors through dedicated logistics contracts reduces handling costs and improves lot traceability for allergen-sensitive customers.
Industry Challenges
- Clean-label formulation expertise:Food technologists skilled in balancing acidulant functionality with shelf-stability requirements remain scarce relative to demand from expanding bakery chains.
- Dual certification timelines:Simultaneous pursuit of USDA grading and EFSA microbiological compliance extends product launch cycles by 8-14 months for multinational manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Buttermilk Powder Market |
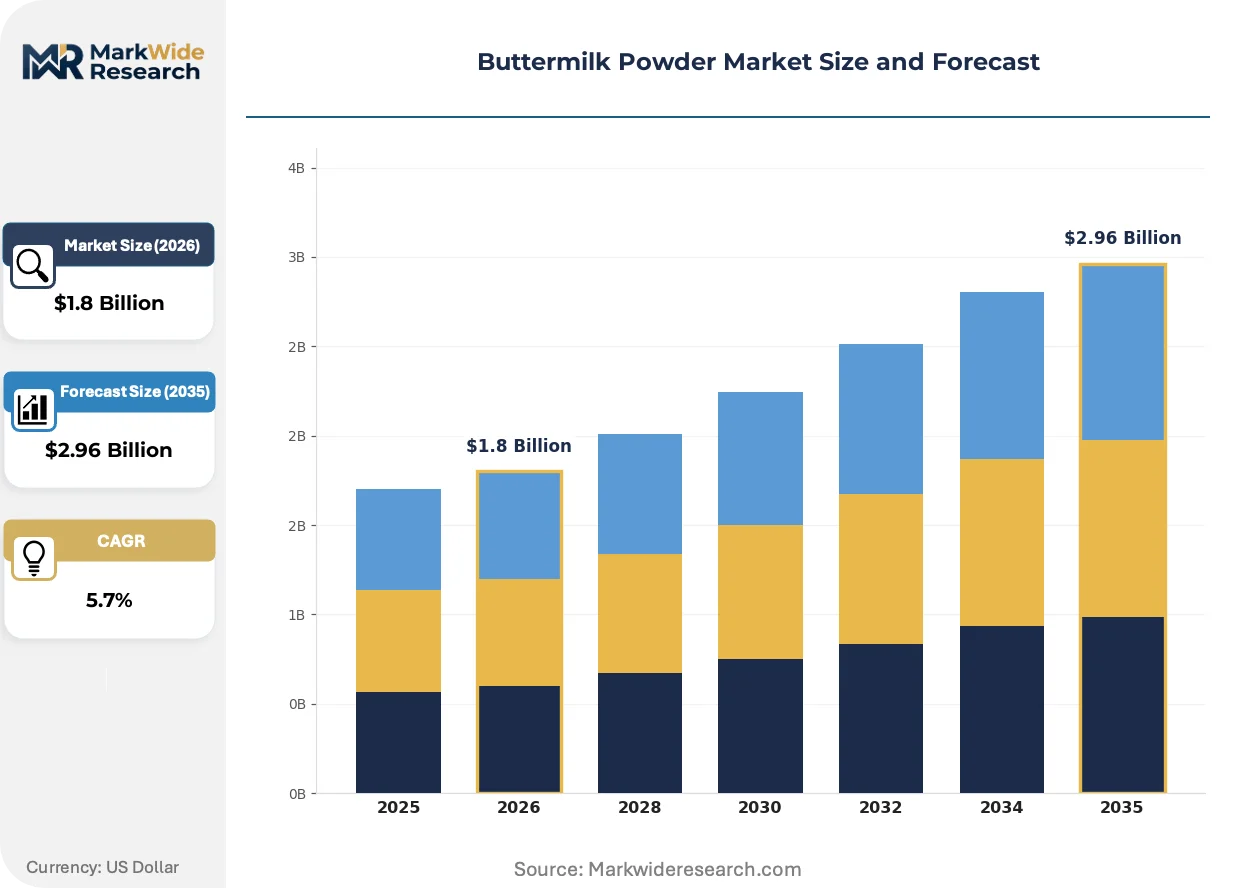
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Buttermilk, Dried Buttermilk, Whole Buttermilk, Low-Fat Buttermilk Application: Baking, Dairy Products, Sauces, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Restaurants, Bakeries, Home Cooks |
| Companies Covered | Dairy Farmers of America Inc., Land O’ Lakes Inc., Fonterra Co-operative Group Limited, Glanbia plc, Interfood AG, Arla Foods amba, Groupe Lactalis S.A., Saputo Inc., Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Buttermilk Powder Market Strategic Shifts
Spray-drying technology advances and regulatory transparency mandates are compressing the gap between commodity and specialty-grade production, enabling mid-scale processors to enter premium contract pools previously reserved for cooperative giants.
Membrane filtration is consolidating buttermilk solids recovery efficiency. This technology selectively concentrates phospholipid and protein fractions before spray-drying, improving reconstitution stability. Mid-cap dairy processors in Denmark and Ireland are adopting these systems to meet bakery chain specifications for consistent batter viscosity. The capital barrier to specialty-grade output is consolidating toward equipment financing rather than raw milk access.
EFSA updated microbiological thresholds for dried dairy ingredients entering EU food manufacturing, tightening Salmonella and Enterobacteriaceae limits. This regulatory compression is disqualifying non-EU suppliers lacking HACCP-equivalent certification infrastructure. North American exporters are responding with dedicated EU-compliant production lines and third-party audit investments to maintain contract eligibility with pan-European bakery groups.
Bakery procurement teams are consolidating supplier rosters from twelve-plus vendors to three-to-four strategic partners. This concentration demands processors offer integrated technical service, including formulation support and joint product development. The shift is most visible in United States QSR networks, where single-source buttermilk powder contracts now bundle annual volume commitments with exclusive flavor profile development.
Buttermilk Powder Market Segmentation
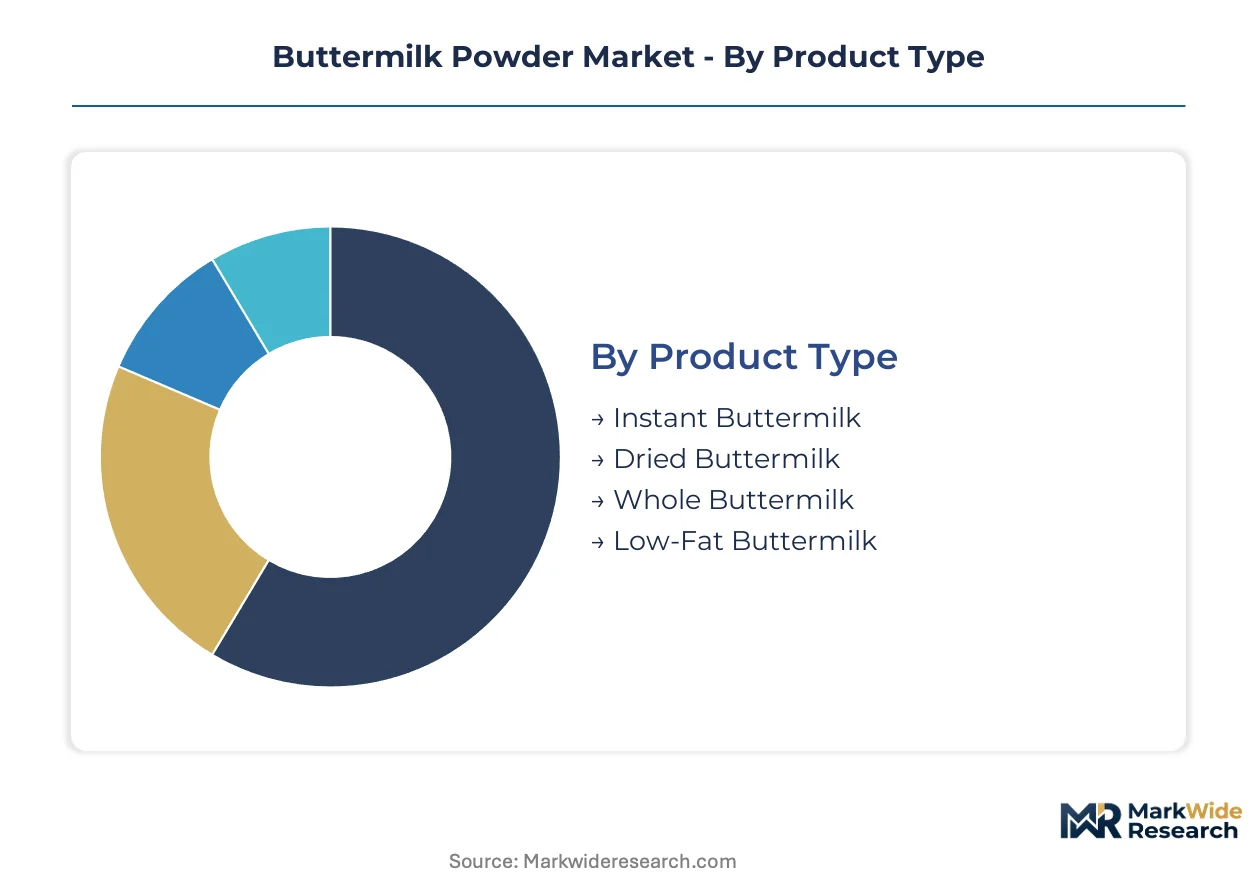
Buttermilk powder procurement splits sharply between industrial-scale bulk contracts and fragmented retail channels. Formulators select grades based on reconstitution speed, fat content, and phospholipid concentration for specific functional outcomes.
Product Type:
Instant variants integrate into continuous-process bakery lines requiring rapid hydration, while dried and whole grades serve batch operations with controlled reconstitution windows.
- Instant Buttermilk:Agglomerated particles engineered for dispersion in ambient-temperature water without mechanical shear. Large United States bakery chains specify instant grades for automated batter systems where hydration speed determines line throughput.
- Dried Buttermilk:Standard spray-dried powder with moderate particle size requiring mechanical mixing for full solubilization. Industrial food manufacturers in the Midwest and Southeast absorb the majority of commodity-grade dried volumes for cake and pancake mix production.
- Whole Buttermilk:Retains full butterfat content from fermented cream churning, delivering enhanced mouthfeel in premium confectionery applications.
- Low-Fat Buttermilk:Reduced-fat specification responding to FDA nutrition labeling pressures and restaurant chain menu reformulation mandates.
Volume placements concentrate in Dried Buttermilk; the faster expansion belongs to Instant Buttermilk.
Application:
End-use specifications diverge between acidulant-requiring systems and emulsification-critical formulations, with regulatory thresholds varying by finished product category.
- Baking:Dominant absorption channel spanning commercial bread, cake, and biscuit manufacturing. Phospholipid functionality enables egg reduction in mass-market pancake batters while maintaining Maillard browning.
- Dairy Products:Cultured product extensions and recombined dairy beverages leverage buttermilk powder for consistent acidity and protein standardization.
- Sauces:Acidulated cream and ranch-style dressings depend on buttermilk powder for flavor profile replication without refrigeration logistics.
- Confectionery:Premium chocolate and caramel applications exploit whole buttermilk fractions for dairy note enhancement and fat crystallization control.
Revenue concentration sits with Baking applications; Confectionery claims the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks customer scale and technical service requirements, with direct procurement displacing traditional distributor relationships among large-volume buyers.
- Wholesale:Bulk tote and tanker deliveries to food manufacturers and bakery chains under annual volume contracts with fixed pricing tiers.
- Online Retail:E-commerce platforms serving small-scale bakeries and ingredient brokers seeking spot purchases with rapid fulfillment.
- Supermarkets:Consumer-packaged goods in retail formats for home cooks and small restaurant operators.
- Specialty Stores:Gourmet and professional-grade packaging targeting artisan bakeries with specific origin or certification requirements.
Contract volumes flow through Wholesale; Online Retail is climbing the fastest.
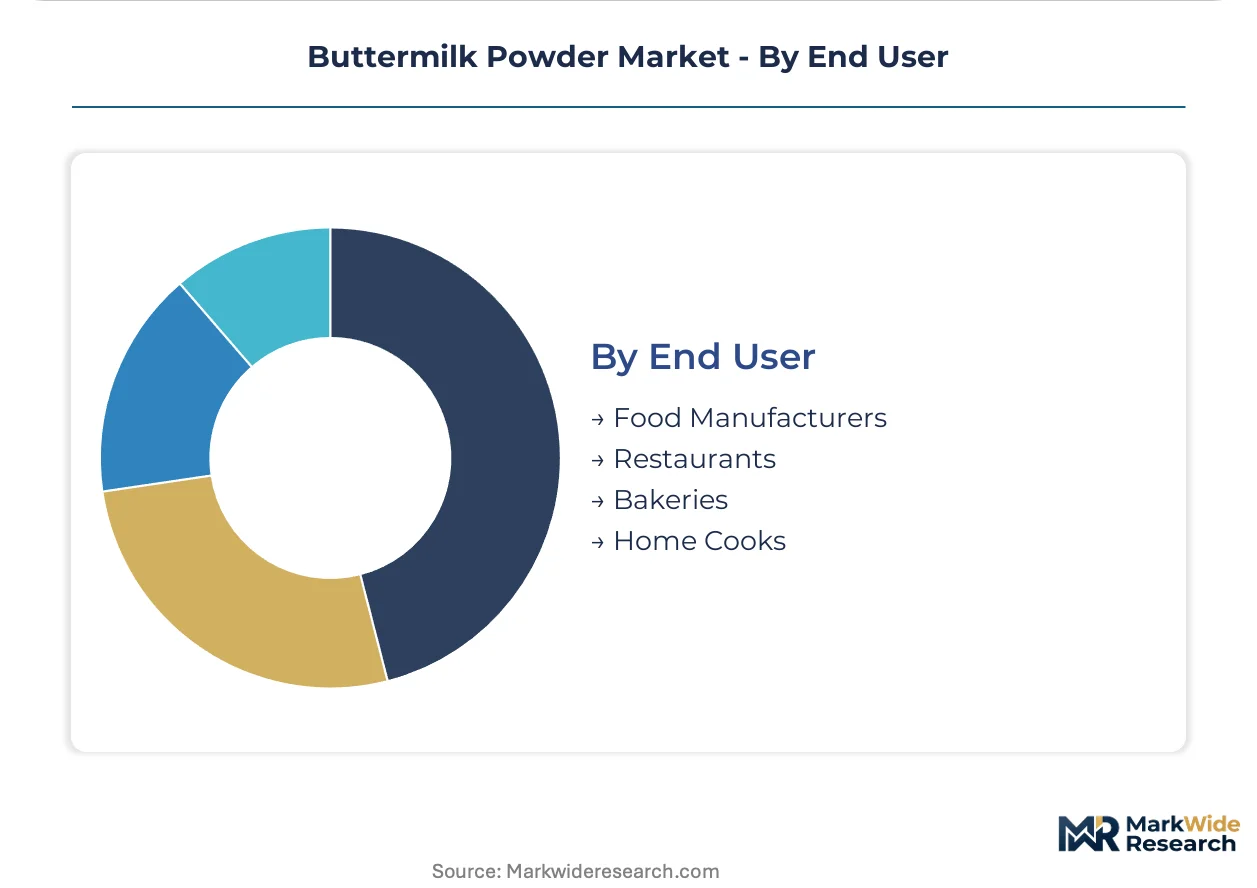
End User:
User categories separate by formulation expertise requirements and procurement scale, with technical support demands escalating alongside product complexity.
- Food Manufacturers:Industrial-scale buyers specifying custom protein and phospholipid profiles for standardized output across multiple production facilities.
- Bakeries:Mid-scale operations requiring consistent acidulant functionality for chemically leavened products with batch-to-batch uniformity.
- Restaurants:QSR networks and casual dining chains sourcing buttermilk powder for sauce bases and breading systems.
- Home Cooks:Retail-format purchasers representing minimal volume but driving brand recognition and recipe penetration.
Procurement scale peaks with Food Manufacturers; Bakeries are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale baking operations and QSR networks in the United States absorb the heaviest procurement volumes for buttermilk powder. Bakery chains across multiple continents are consolidating supplier rosters toward strategic partners with verified low-emission sourcing. Clean-label mandates and carbon-footprint disclosure rules are reshaping contract eligibility with multinational food manufacturers.
United States
Midwest and Southeast industrial food manufacturers drive bulk purchasing of dried buttermilk for cake and pancake mix production. FDA dairy identity standards under Title 21 CFR are forcing reformulation toward recognizable ingredient panels. Chicago and Minneapolis-St. Paul anchor concentrated clusters of automated batter systems requiring instant buttermilk grades.
Germany
Mid-cap dairy processors in Bavaria and North Rhine-Westphalia are adopting membrane filtration systems to meet bakery chain specifications. EFSA microbiological thresholds for dried dairy ingredients are tightening Salmonella and Enterobacteriaceae limits. The Eindhoven-Randstad corridor hosts technical service teams supporting pan-European bakery groups.
New Zealand
Fonterra Co-operative Group Limited leverages its milk pool to sustain cost advantages in export markets. The country's national dairy regulator enforces grading protocols that influence premium export pricing tiers. Canterbury and Waikato concentrate spray-drying operations delivering consistent protein specifications for USDA-compliant tiers.
France
Groupe Lactalis S.A. anchors cooperative sourcing scale for European quality certifications. EU Green Deal supply-chain transparency requirements favor processors with verified renewable energy drying operations. The Brittany dairy basin supplies phospholipid-rich fractions for premium confectionery applications.
Canada
Saputo Inc. processes buttermilk powder for North American bakery chain contracts under USDA-aligned inspection protocols. Health Canada administers dairy ingredient safety standards that parallel FDA frameworks. Quebec and Ontario host integrated technical service operations supporting joint product development with QSR networks.
Buttermilk Powder Market Competitive Environment
New Zealand cooperative producers anchor one tier; European and North American specialists hold differentiated positions on certification and technical service. The vendor base splits between scale-driven commodity processors and mid-cap membrane filtration adopters. Three archetypes dominate: cooperative giants with captive milk pools, nutrition-grade fraction specialists, and regional processors with EU-compliant production lines. M&A activity concentrates among bakery-facing ingredient platforms, while capacity expansion targets EU Green Deal-aligned renewable energy drying.
Within the cooperative tier, Fonterra Co-operative Group Limited and Arla Foods amba exemplify scale advantages derived from member-owned milk sourcing. Glanbia plc occupies a position among nutrition-grade specialists targeting sports nutrition and clinical applications. These three entities represent divergent geographic and functional strategies: Oceania-origin export scale, European quality certification, and specialized high-protein fraction development.
| Leading Market Players |
|---|
| Dairy Farmers of America Inc. |
| Land O' Lakes Inc. |
| Fonterra Co-operative Group Limited |
| Glanbia plc |
| Interfood AG |
| Arla Foods amba |
| Groupe Lactalis S.A. |
| Saputo Inc. |
| Lactalis Ingredients |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal carbon-footprint disclosure requirements now gate premium-tier contract eligibility with multinational bakery chains, compressing qualified supply pools to processors with verified renewable energy drying operations and low-emission milk sourcing. This sustainability mandate simultaneously elevates pricing power for compliant suppliers while forcing non-certified processors toward commodity spot markets or costly facility upgrades.
Pricing Analysis
Volume placements in dried buttermilk concentrate at thin margins, while instant and specialized nutrition-grade fractions capture expanded spreads. Three-tier pricing structure across premium, standard, and economy levels separates USDA/EFSA dual-certified supply from single-jurisdiction grades and uncertified commodity powder. Pricing pressure stems from whey protein isolates and modified starches competing for emulsification slots in cost-sensitive formulations. Food manufacturers in the Midwest and Southeast exhibit highest price sensitivity due to bulk procurement scale, whereas European confectionery buyers prioritize phospholipid concentration over unit cost.
Supply Chain Analysis
Fluid milk supply rests on New Zealand cooperative processors, select EU dairy basins in Denmark and Ireland, and North American concentrated feedlot operations near Chicago and Minneapolis-St. Paul. Spray-drying energy costs, membrane filtration equipment, and export-grade packaging materials constitute critical input dependencies. Single-origin concentration across Oceania and Northern Europe creates geographic vulnerability to regional climate shocks and regulatory fragmentation. Distribution runs through long-term annual volume contracts with fixed pricing tiers, displacing traditional ingredient distributors among large bakery chains and QSR networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buttermilk powder procurement is consolidating into a vertical-integration race where captive milk sourcing and in-house membrane filtration capacity determine contract eligibility with multinational food manufacturers. Players lacking upstream control over low-emission milk pools face exclusion from premium pricing tiers.
For Market Incumbents: Deploy membrane filtration technology adoption to defend formulation support relationships with consolidating bakery chains. Fonterra and Arla anchor positions through cooperative milk pool scale; mid-cap processors must acquire EU-compliant production lines or risk disqualification from pan-European contracts. Whey protein displacement in emerging-market biscuit production threatens commodity-grade volume placements.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in specialized nutrition-grade buttermilk fractions offers accessible white-space for sports nutrition and clinical application targeting. Direct-to-bakery distribution bypassing traditional ingredient distributors reduces handling costs and improves lot traceability for allergen-sensitive customers. Mid-scale Danish and Irish processors demonstrate viable entry through equipment financing rather than raw milk access.
For Investors and Strategic Acquirers: Bakery chain supplier roster consolidation from twelve-plus vendors to three-to-four strategic partners is the leading indicator that membrane filtration-equipped mid-caps will command acquisition premiums. Target processors with verified renewable energy drying and EU Green Deal-aligned carbon disclosure infrastructure. Watch EFSA microbiological threshold enforcement as the trigger for disqualification waves among non-EU suppliers lacking HACCP-equivalent certification.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Adoption | Mid-cap processors in Denmark and Ireland deploy selective phospholipid concentration to meet bakery chain viscosity specifications. |
| EU-Compliant Production Line Investment | North American exporters establish dedicated Salmonella and Enterobacteriaceae-compliant facilities to maintain pan-European contract eligibility. |
| Direct-to-Bakery Distribution Contracts | Bypassing traditional ingredient distributors reduces handling costs and improves allergen lot traceability for QSR networks. |
| Renewable Energy Drying Transition | EU Green Deal supply-chain transparency requirements favor processors with verified low-emission operations and carbon disclosure. |
| Specialized Nutrition Fraction Development | High-protein buttermilk concentrates targeting sports nutrition command pricing premiums above commodity grades. |
Study Parameters
Document review covered FDA Title 21 CFR filings, USDA grading protocols, EFSA microbiological threshold updates, and EU Green Deal supply-chain transparency requirements, complemented by interviews with dairy processing plant managers, bakery chain procurement leads, QSR network supply planners, and membrane filtration equipment specialists. Secondary validation drew from Fonterra and Arla cooperative sourcing disclosures, Glanbia nutrition-grade fraction specifications, and customs data on dried dairy ingredient trade flows. Bottom-up volume modeling across product types and applications triangulated with top-down market sizing from processor capacity assessments.
Cross-referencing historical procurement pattern analysis against expert panel input on clean-label reformulation timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, application category, distribution channel, and end-user scale tier. CAGRs were derived from volume placement trajectories in baking versus confectionery applications and the relative expansion rates of instant versus dried buttermilk grades. Forecast inputs incorporated membrane filtration adoption curves, EFSA compliance investment cycles, and bakery chain supplier consolidation velocity.
Inputs from dairy processor technical service teams and bakery chain R&D directors were available through the study window; gaps in real-time spot-market transaction data and confidential contract pricing introduce uncertainty bands around volume projections. Forecasts reflect assumptions on EFSA enforcement consistency, renewable energy drying cost curves, and whey protein displacement rates in emerging-market formulations. Regulatory threshold adjustments, climate impacts on Oceania milk pools, and QSR menu reformulation mandates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Fresh Milk Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Recombined Milk Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Evaporated Milk Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Gruyere Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
Europe Cheese Market