
 United States Dairy Desserts Market | 2026-2036
United States Dairy Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dairy Desserts Market Insights
Foodservice buyers are unwinding share from traditional retail consumers as on-premise dessert occasions recover and operators expand limited-time dairy offerings. General Mills leverages its frozen novelty infrastructure to supply chain-scale dessert programs for national restaurant accounts. Blue Bell Creameries anchors regional loyalty through its Gulf Coast production network and direct-store-delivery cold chain. Nestlé competes across both retail and foodservice with modular ingredient systems that let operators customize parfait builds.
United States dairy desserts comprise chilled or frozen formulations based on milk solids, cream, sweeteners, and stabilizers, typically processed through HTST pasteurization and set via controlled-temperature culturing or starch gelatinization to achieve spoonable or pourable textures; these products serve commercial foodservice and retail channels as finished ready-to-eat items or as dessert components in multi-layer preparations. Custard and pudding formats dominate volume through their extended shelf stability and institutional foodservice penetration, while yogurt parfait applications capture expanding margin pools as operators position them as breakfast-crossover items with functional positioning. Cup packaging leads at retail for single-serve convenience, though tub formats sustain growth in club and wholesale channels where household stocking behavior persists.
FDA dairy standards of identity and USDA grade labeling requirements shape permissible ingredient declarations and fat-content claims across interstate commerce, while state-level dairy-pricing orders under federal milk marketing regulations influence raw milk cost structures that cascade into dessert manufacturing economics. The Food Safety Modernization Act preventive controls mandate hazard analysis for refrigerated dairy dessert facilities, elevating capital requirements for smaller processors. Stakeholders must monitor evolving FDA guidance on added-sugar labeling and potential front-of-pack warnings, as these frameworks will determine which formulation investments secure retail placement and foodservice contract renewals.
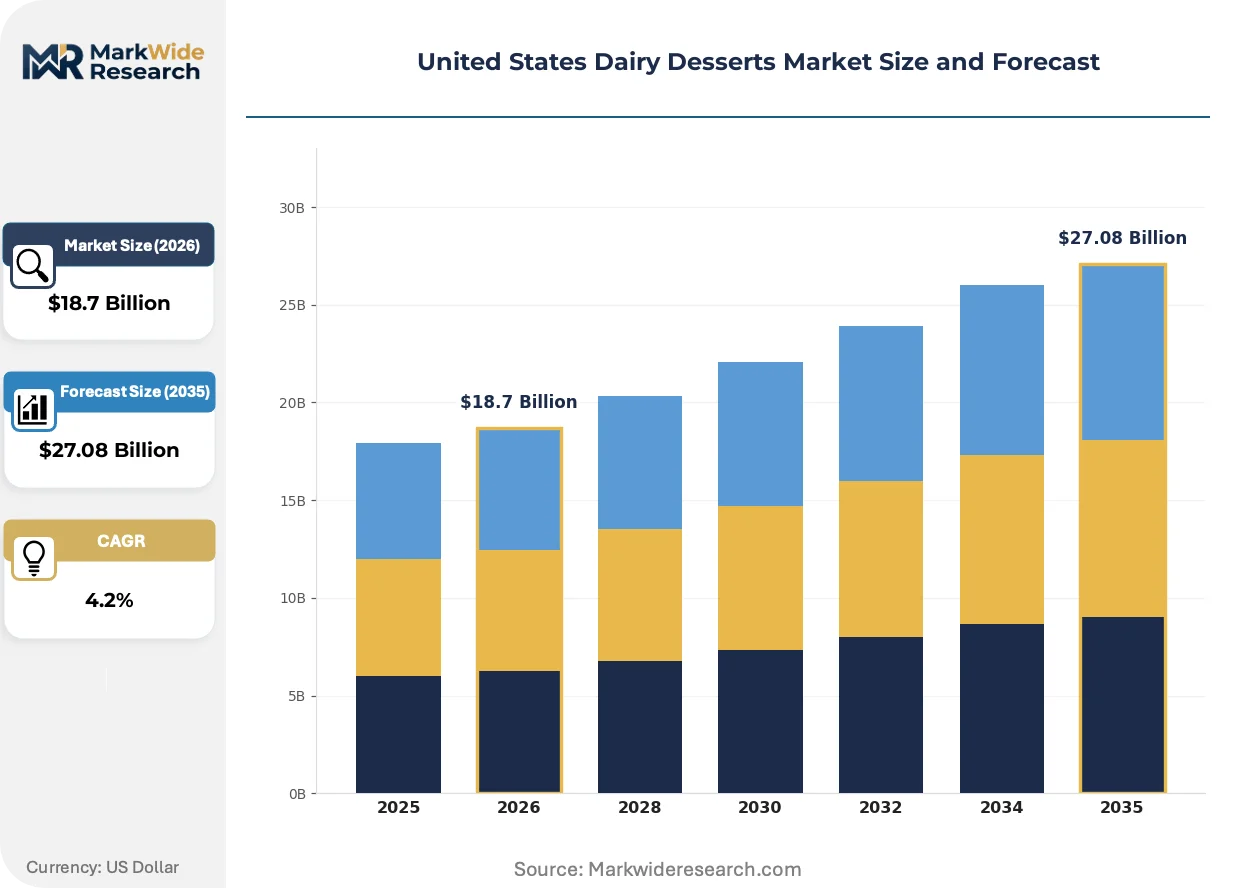
Market Dynamics
Foodservice operators are capturing consumption occasions from retail channels as on-premise dessert traffic rebounds and chains expand limited-time dairy offerings. This channel rotation is compressing traditional grocery volume while elevating contract manufacturing demand for customized dessert formats.
Growth Catalysts
- Clean-Label Reformulation:FDA labeling modernization pressures are redirecting R&D investment toward reduced-sugar and probiotic-enriched recipes that command shelf placement.
- Hot-Climate Migration:Population inflows to Texas and the Southeast sustain above-average per-household purchase rates through extended consumption seasons.
- Permissible Indulgence Positioning:Quick-service chains are expanding dairy dessert menus as consumers seek treat formats with functional or portion-controlled attributes.
Market Restraints
- Federal Milk Marketing Orders:State-level dairy-pricing regulations cascade into raw milk cost volatility that constrains margin predictability for dessert processors.
- Cold-Chain Infrastructure Gaps:Direct-store-delivery network concentration along the Gulf Coast limits expansion economics for temperature-sensitive parfait formats.
- Added-Sugar Disclosure Requirements:Evolving FDA guidance on front-of-pack warnings creates formulation recertification burdens ahead of contract renewal cycles.
Strategic Opportunities
- Breakfast-Crossover Positioning:Yogurt parfait applications capture expanding margin pools as operators merchandise them alongside morning dayparts with functional ingredient claims.
- Club Channel Tub Formats:Wholesale packaging configurations sustain growth in household stocking behavior that persists beyond pandemic-era purchasing patterns.
- Probiotic Strain Differentiation:Cultured dairy desserts with documented digestive health benefits command price premiums in retail and institutional accounts.
Industry Challenges
- Preventive Controls Compliance:FSMA-mandated hazard analysis elevates capital requirements for refrigerated facility upgrades among smaller processors.
- HTST Pasteurization Talent Scarcity:Specialized operator certification for high-temperature short-time systems constrains production scaling at regional plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dairy Desserts Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custard, Pudding, Flan, Yogurt Parfait End User: Restaurants, Cafes, Supermarkets, Retail Consumers Packaging Type: Cups, Tubs, Sachets, Jars Distribution Channel: Online Retail, Direct Sales, Specialty Stores, Wholesale |
| Companies Covered | General Mills, Dairy Farmers of America, Unilever, Kraft Heinz, Danone, Nestlé, Blue Bell Creameries, Conagra Brands, Wells Enterprises, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dairy Desserts Market Trends and Innovations
Formulation science and channel strategy are converging to reshape how dairy desserts reach consumers. Technology investments focus on texture engineering and shelf-life extension while regulatory pressures accelerate clean-label transitions.
Precision fermentation-derived dairy proteins are supplanting traditional milk solids in reduced-fat dessert formulations. National restaurant accounts are piloting these ingredients for custom parfait builds that maintain mouthfeel without full butterfat content. The structural consequence is compression in conventional cream sourcing contracts as operators seek supply security through biotechnology partnerships.
FDA standards of identity modernization is reshaping permissible ingredient declarations for frozen and spoonable dairy products. Interstate commerce requirements now permit modified starch gelatinization methods previously restricted to specific product categories. Frozen novelty manufacturers are responding by reformulating custard bases to qualify for broader labeling claims.
Foodservice procurement is consolidating dessert sourcing through chain-scale supply agreements that displace fragmented distributor relationships. Multi-unit operators now specify modular ingredient systems allowing in-store customization rather than finished-product delivery. This pattern concentrates most visibly in quick-service chains across the Southeast corridor where menu localization demands flexible component supply.
United States Dairy Desserts Market Segmentation
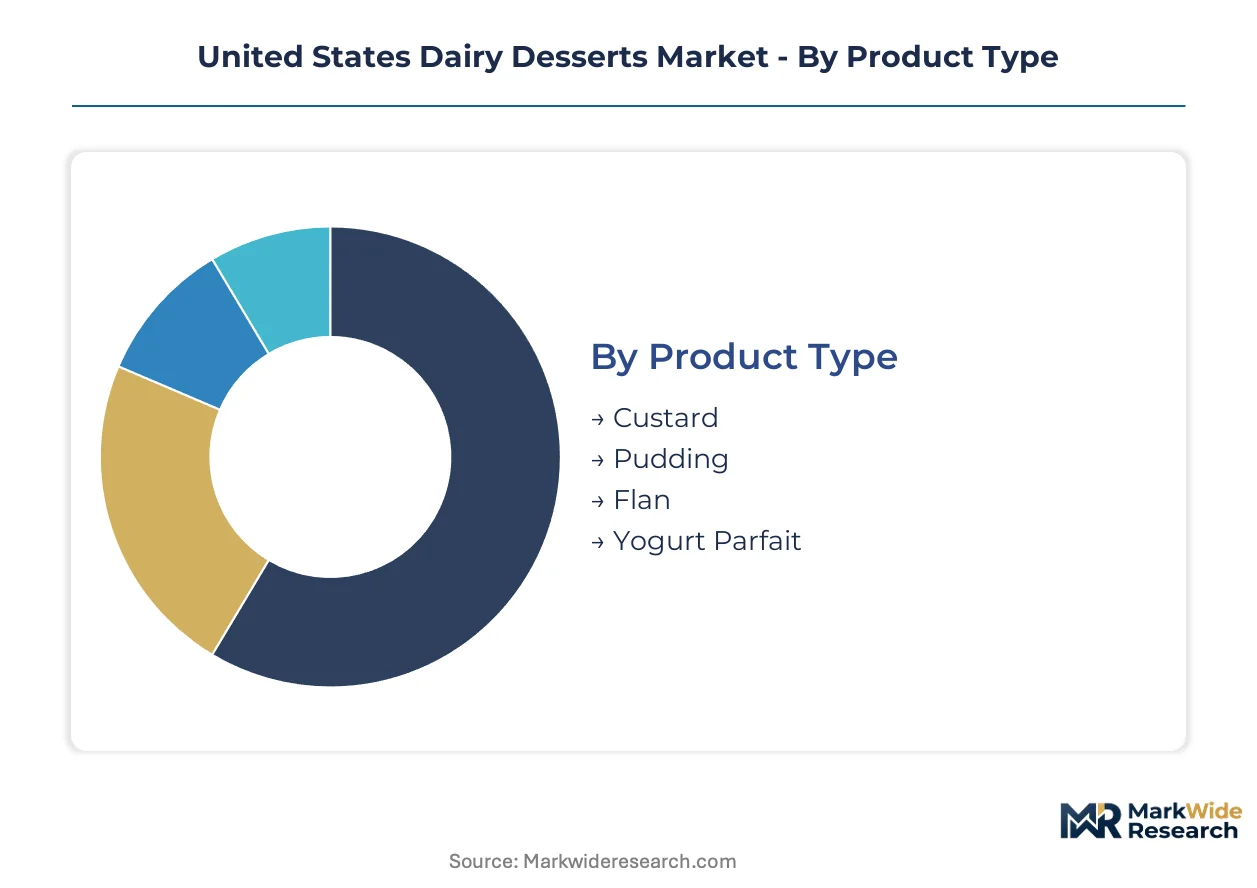
Dairy dessert manufacturers configure production lines and cold-chain investments around segment-specific shelf-life demands and channel economics. Substitution pressures from plant-based alternatives and frozen novelties reshape which segments warrant formulation R&D priority.
Product Type:
Plant-based dessert alternatives exert substitution pressure most acutely on custard and pudding formats, while yogurt parfaits leverage functional positioning to defend against non-dairy encroachment.
- Custard:Egg-thickened formulations with HTST pasteurization and controlled gelation achieve spoonable textures. Institutional cafeterias in Texas and Florida sustain volume through extended serving windows and hot-climate consumption patterns. Federal milk marketing orders compress margin predictability for processors dependent on conventional cream sourcing.
- Pudding:Starch-stabilized preparations with modified food starch gelatinization permit ambient distribution in shelf-stable formats. Quick-service chains across the Southeast corridor deploy pudding cups as limited-time dessert offerings, though clean-label reformulation pressures elevate R&D costs for starch replacement.
- Flan:Caramel-custard preparations with inverted sugar syrups and water-bath set methods serve Hispanic consumer concentrations in South Texas and Southern California.
- Yogurt Parfait:Layered cultured dairy with fruit compotes and granola components command breakfast-crossover placement in cafes.
Custard anchors the volume base while yogurt parfait gains share at the steepest rate.
End User:
Foodservice procurement consolidation elevates contract manufacturing scale requirements, fragmenting economics for smaller processors serving dispersed retail accounts.
- Restaurants:Full-service operators specify modular dessert components for in-house parfait assembly. National chain accounts in the Southeast negotiate chain-scale supply agreements that displace fragmented distributor relationships.
- Cafes:Beverage-forward operators merchandise yogurt parfaits as morning daypart extensions with probiotic functional claims.
- Supermarkets:Retail grocery buyers prioritize cup-format single-serve convenience with front-of-pack labeling compliance.
- Retail Consumers:Club channel household stocking behavior sustains tub format demand beyond pandemic-era purchasing patterns.
Restaurants concentrate procurement scale while cafes expand placement most quickly.
Packaging Type:
Temperature sensitivity and portion-control trends redistribute investment across material formats with divergent cold-chain requirements.
- Cups:Single-serve polypropylene containers with lidding film dominate retail convenience channels. Southeast supermarket chains specify cup formats for grab-and-go dairy dessert placement.
- Tubs:Multi-serve polypropylene or paperboard configurations serve club channel household stocking behavior.
- Sachets:Powdered dessert mix packaging permits ambient distribution with consumer reconstitution.
- Jars:Glass packaging for premium-positioned custard and flan formats serves specialty retail channels.
Cups capture the broadest channel penetration while tubs sustain the highest per-unit revenue.
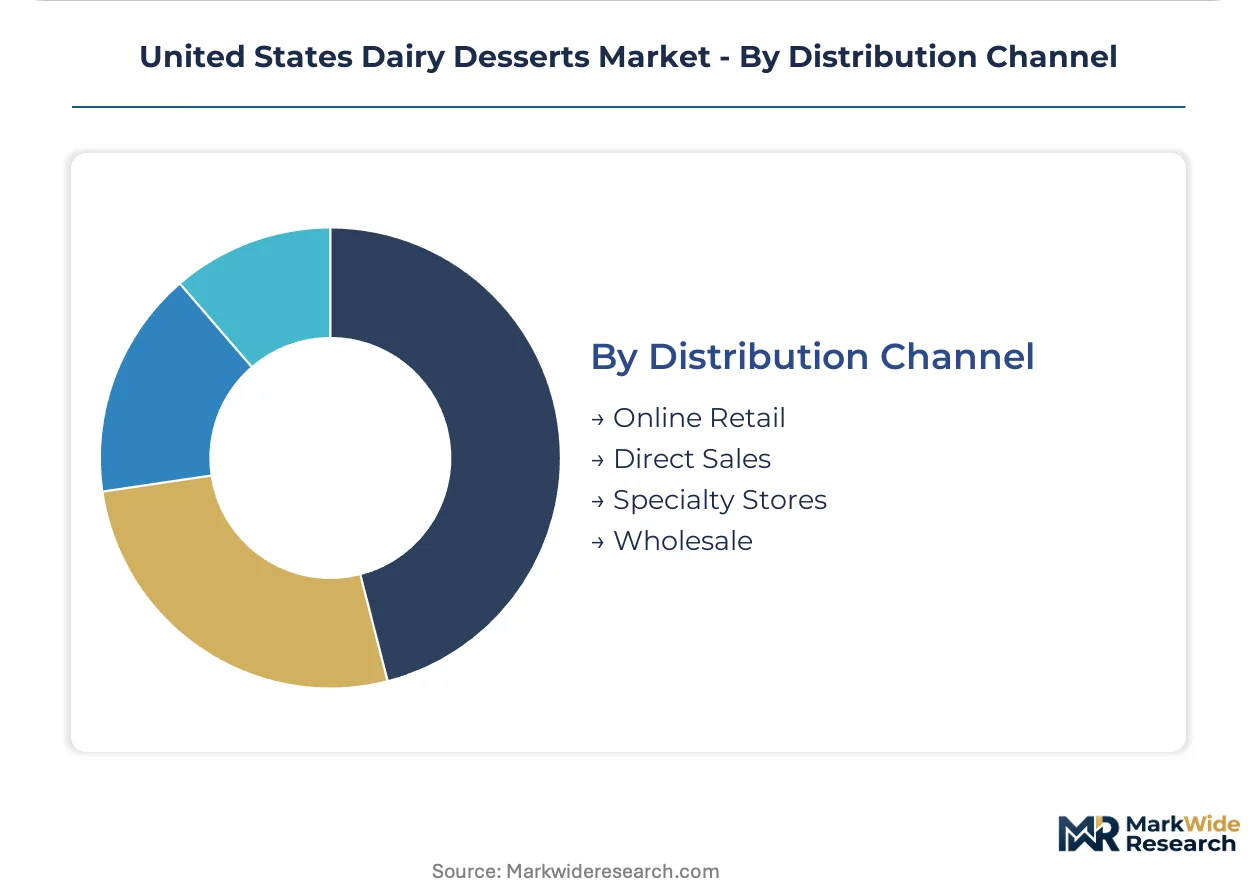
Distribution Channel:
Direct-store-delivery network economics constrain which formats achieve geographic expansion beyond Gulf Coast production clusters.
- Online Retail:Temperature-controlled last-mile fulfillment enables subscription dessert programs. Cold-chain infrastructure gaps limit parfait format viability outside major metropolitan zones.
- Direct Sales:Foodservice operators source through chain-scale agreements specifying modular ingredient systems.
- Specialty Stores:Independent retailers stock premium jar-format custards and flans for Hispanic consumer concentrations.
- Wholesale:Broadline distributors serve institutional accounts with extended-shelf-life pudding formats.
Direct sales concentrate contract value while online retail climbs the fastest despite fulfillment constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy dessert demand concentrates along population migration corridors where hot-climate consumption patterns intersect with expanding foodservice infrastructure. Interstate commerce flows from Gulf Coast production clusters toward Southeast and Southwest population centers.
Southeast
Florida and Georgia sustain above-average per-household purchase rates through extended consumption seasons and quick-service chain expansion. FDA standards of identity modernization permits modified starch gelatinization methods that regional processors leverage for custard reformulation. Atlanta anchors distribution networks supplying limited-time dessert programs to national restaurant accounts across the Carolinas and Tennessee.
Texas
Hispanic consumer concentrations in Houston and Dallas-Fort Worth drive flan and premium custard demand alongside traditional pudding formats. Federal milk marketing orders under USDA jurisdiction create raw milk cost volatility that compresses margin predictability for Dallas-based processors. The Gulf Coast production corridor leverages direct-store-delivery cold chains to serve institutional cafeteria accounts throughout the state.
California
Los Angeles and the Central Valley support specialty retail channels for jar-format premium desserts targeting diverse demographic segments. State-level clean-label regulations exceed federal baselines, elevating R&D costs for starch replacement and reduced-sugar formulations. San Francisco Bay Area cafes pioneer breakfast-crossover yogurt parfait placement with probiotic functional claims.
Midwest
Illinois and Ohio maintain institutional foodservice volume through extended-shelf-life pudding formats serving school and healthcare cafeterias. FSMA preventive controls mandates elevate capital requirements for refrigerated facility upgrades among smaller regional processors. Chicago functions as a wholesale distribution hub connecting broadline distributors to institutional accounts across the Great Lakes region.
Northeast Corridor
New York Metro and Boston concentrate specialty store demand for premium-positioned custard and flan formats. FDA labeling modernization pressures redirect formulation investment toward front-of-pack compliance ahead of contract renewal cycles. Philadelphia anchors club channel distribution for multi-serve tub formats sustaining household stocking behavior.
United States Dairy Desserts Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational flexibility dimensions. Publicly traded conglomerates leverage frozen novelty infrastructure and modular ingredient systems to secure chain-scale foodservice contracts, while private regional operators defend share through direct-store-delivery cold chain control. Three archetypes dominate: diversified packaged food conglomerates with dessert as portfolio component, dairy cooperative processors with captive milk supply, and specialized frozen dessert independents with geographic concentration. Competitive moves center on foodservice procurement consolidation and precision fermentation partnerships for reduced-fat formulation.
Within the diversified conglomerate tier, General Mills and Nestlé exemplify players leveraging cross-category infrastructure for dessert program scale. Kraft Heinz occupies a position bridging retail shelf-stable and refrigerated formats. Blue Bell Creameries represents the regional specialist archetype, anchoring Gulf Coast loyalty through production network proximity to core demand clusters. These three patterns illustrate how capital structure and geographic concentration shape competitive positioning across contract manufacturing and branded retail vectors.
| Leading Market Players |
|---|
| General Mills |
| Dairy Farmers of America |
| Unilever |
| Kraft Heinz |
| Danone |
| Nestlé |
| Blue Bell Creameries |
| Conagra Brands |
| Wells Enterprises |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation-derived dairy proteins displacing conventional milk solids simultaneously redraws supply geography toward biotechnology hubs and compresses legacy cream-sourcing contract values. This substitution dynamic redirects procurement investment from Gulf Coast dairy cooperatives toward synthetic biology partnerships, fragmenting historical pricing benchmarks anchored to federal milk marketing order baselines.
Pricing Analysis
Current-generation HTST pasteurization systems command premium pricing against legacy batch-processing infrastructure, while next-generation precision fermentation ingredients sit at cost parity with conventional cream in reduced-fat formulations. Three-tier pricing structure across premium probiotic-positioned, standard clean-label, and economy extended-shelf-life tiers reflects brand equity and certification burden differentials. Pricing pressure stems from clean-label reformulation mandates elevating R&D amortization across all tiers. Institutional foodservice buyers exhibit highest price sensitivity due to contract renewal cycles, while specialty retail channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inventory lead times for precision fermentation inputs stretch substantially beyond conventional dairy commodity procurement cycles, compressing formulation flexibility for limited-time product launches. Supply concentrates in Texas and Wisconsin dairy processing corridors alongside emerging biotechnology manufacturing clusters in California and Massachusetts. Raw material dependencies center on milk solids, specialized probiotic cultures, and modified food starches. Single-source vulnerability pervades the direct-store-delivery cold chain concentrated along the Gulf Coast. Distribution runs through foodservice chain-scale agreements displacing fragmented broadline distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as foodservice procurement consolidation creates tiered supplier gaps between national contract scale and regional flexibility demands. Channel rotation toward on-premise consumption generates white-space niches for specialized operators.
For Market Incumbents: Fortify Gulf Coast direct-store-delivery infrastructure against biotechnology supply disruption by securing captive precision fermentation partnerships. Expand modular ingredient system capacity in Southeast distribution hubs to defend contract renewal positioning against emerging contract manufacturers. Prioritize FSMA preventive controls certification investment as a barrier to smaller processor encroachment.
For New Entrants and Emerging Players: Differentiate on breakfast-crossover yogurt parfait formats with documented probiotic strain differentiation targeting cafe channel expansion. Penetrate the Hispanic consumer flan segment in South Texas and Southern California through specialty retail jar-format positioning. Deploy direct-to-foodservice sales models bypassing consolidated broadline distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional processors with existing HTST pasteurization certification and underutilized cold-chain assets. Long-term viability hinges on biotechnology ingredient transition readiness rather than conventional dairy supply security. Monitor FDA standards of identity modernization timeline as inflection indicator for formulation investment recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures supply security for reduced-fat formulations ahead of biotechnology cost curves. |
| Direct-Store-Delivery Expansion | Extends Gulf Coast cold-chain coverage into Southeast corridor parfait distribution. |
| Clean-Label Reformulation Investment | Positions for FDA front-of-pack labeling compliance ahead of contract renewals. |
| Breakfast-Crossover Product Development | Captures margin expansion from cafe channel yogurt parfait placement growth. |
| Probiotic Strain Differentiation | Commands price premiums through documented digestive health benefit claims. |
Research Methodology
The analysis maps custard, pudding, flan, and yogurt parfait sub-sectors, each validated through foodservice procurement directors, dairy processing plant managers, retail category buyers, and cold-chain logistics operators. Primary interview insights triangulate against FDA standards of identity documentation, USDA federal milk marketing order filings, FSMA compliance databases, and Nielsen retail audit data. Bottom-up production capacity modeling reconciles with top-down channel consumption estimates.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions span product type, end-user channel, packaging format, and distribution methodology alongside regional production cluster economics. CAGRs derive from trend extrapolation calibrated to historical channel shift patterns and population migration flows. Forecast inputs incorporate clean-label reformulation adoption curves and precision fermentation ingredient penetration assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hot-climate migration patterns or accelerated FDA labeling modernization would require recalibration. Forecasts reflect documented assumptions regarding foodservice recovery trajectories and biotechnology supply scale-up timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Canada Milk Protein Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Latin America Cheese Market
Dairy Products
Global Butter Market
Dairy Products
Spicy Dairy Products Market
Dairy Products
Camel Dairy Market
Dairy Products
United States Dairy Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Parmesan Cheese Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Buttermilk Powder Market
Dairy Products
India Dairy Market
Dairy Products
Probiotic Dairy Products Market