
 Mexico Lactose-Free Dairy Market | 2026-2036
Mexico Lactose-Free Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Lactose-Free Dairy Market Insights
Single-serve pouch formats is broadening buyer choice across convenience channels and on-the-go consumption occasions. Lala Group leverages its national refrigerated distribution network to secure shelf presence in traditional and modern trade. Grupo Alpura anchors its position through backward integration into domestic milk sourcing, reducing input cost volatility. Sigma Alimentos differentiates via specialized cold-chain logistics that protect enzymatic integrity during last-mile delivery.
Lactose-free dairy comprises fluid milk, fermented products, and fresh cheeses treated with beta-galactosidase enzyme to hydrolyze lactose into glucose and galactose, yielding sweetness profiles above 90% lactose reduction for lactose-intolerant consumers. The product category serves both clinical dietary management and mainstream digestive wellness positioning. Milk dominates volume throughput given its centrality in Mexican household consumption patterns and breakfast rituals. Yogurt captures accelerating demand from health-conscious millennials seeking probiotic-functional positioning alongside lactose reduction. Supermarkets and hypermarkets control the principal margin pool through negotiated slotting fees and private-label development, while online retail posts the fastest route-to-consumer expansion among digital-native urban shoppers.
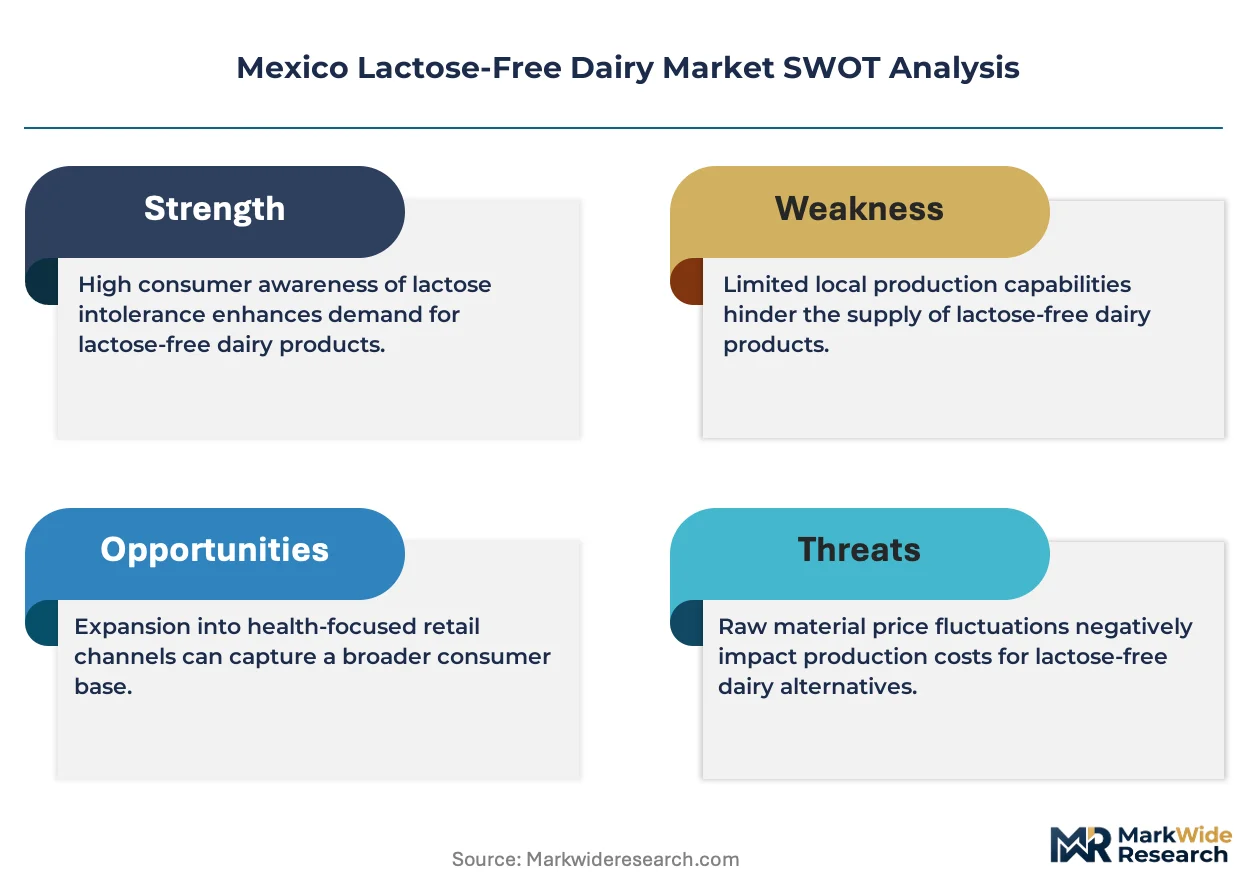
COFEPRIS enforces compositional standards and enzyme residual limits for hydrolyzed dairy products, while NOM-243-SCFI/SSA1-2010 specifies labeling requirements for nutritional claims. These frameworks elevate compliance costs for new entrants but simultaneously validate product authenticity for skeptical consumers. Stakeholders must monitor pending amendments to front-of-pack labeling regulations that could restrict health-related marketing claims. Producers and distributors should assess formulation flexibility against evolving standards before committing capital to capacity expansion.
Market Dynamics
COFEPRIS enforcement of NOM-243-SCFI/SSA1-2010 labeling mandates is compressing formulation timelines and elevating compliance spend across Mexican dairy processors, forcing enzymatic hydrolysis investments ahead of front-of-pack rule amendments.
Growth Catalysts
- Urban digestive wellness positioning:Young adult consumers in Mexico City and Monterrey treat lactose-free fluid milk as a daily functional food, expanding household penetration beyond clinical lactose intolerance into preventive health routines.
- Beta-galactosidase enzyme advancement:Improved thermal stability of commercial lactase preparations allows processors to achieve 90% lactose reduction without sweetness profile distortion, unlocking clean-label reformulation.
- NOM-243-SCFI/SSA1-2010 nutritional claim clarity:Mexico's standardized lactose content declarations reduce consumer skepticism and validate premium shelf positioning for hydrolyzed dairy products.
Market Restraints
- Domestic milk input cost volatility:Grupo Alpura's backward integration into captive milk sourcing highlights structural exposure for non-integrated processors facing spot market fluctuations in raw dairy procurement.
- Cold-chain infrastructure concentration:Last-mile refrigerated distribution remains concentrated among three national logistics networks, creating bottleneck risk for enzymatic integrity during summer temperature spikes.
- Plant-based dairy substitution:Oat and almond milk alternatives capture trial among flexitarian consumers in premium Mexico City retail formats, compressing addressable market expansion for animal-derived lactose-free options.
Strategic Opportunities
- Monterrey foodservice penetration:Industrial cafeteria and QSR chains in Nuevo León under-index on lactose-free menu offerings, presenting white space for bulk fluid milk and fresh cheese supply contracts.
- Single-serve pouch format expansion:Convenience channel shelf space in OXXO and 7-Eleven networks rewards portable packaging innovation for on-the-go breakfast consumption occasions.
- Pending front-of-pack warning label exclusions:COFEPRIS deliberations on nutrient profile models may exempt low-lactose dairy from octagon warnings, creating regulatory tailwind for reformulated product lines.
Industry Challenges
- Enzymatic process technician scarcity:Industrial biochemistry expertise for beta-galactosidase dosing optimization remains concentrated among a handful of Monterrey and Querétaro technical specialists, inflating recruitment timelines.
- Legacy ERP integration with batch traceability:Small and mid-size processors struggle to retrofit manufacturing execution systems for COFEPRIS-mandated enzyme residual documentation and lot-level recall protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Lactose-Free Dairy Market |
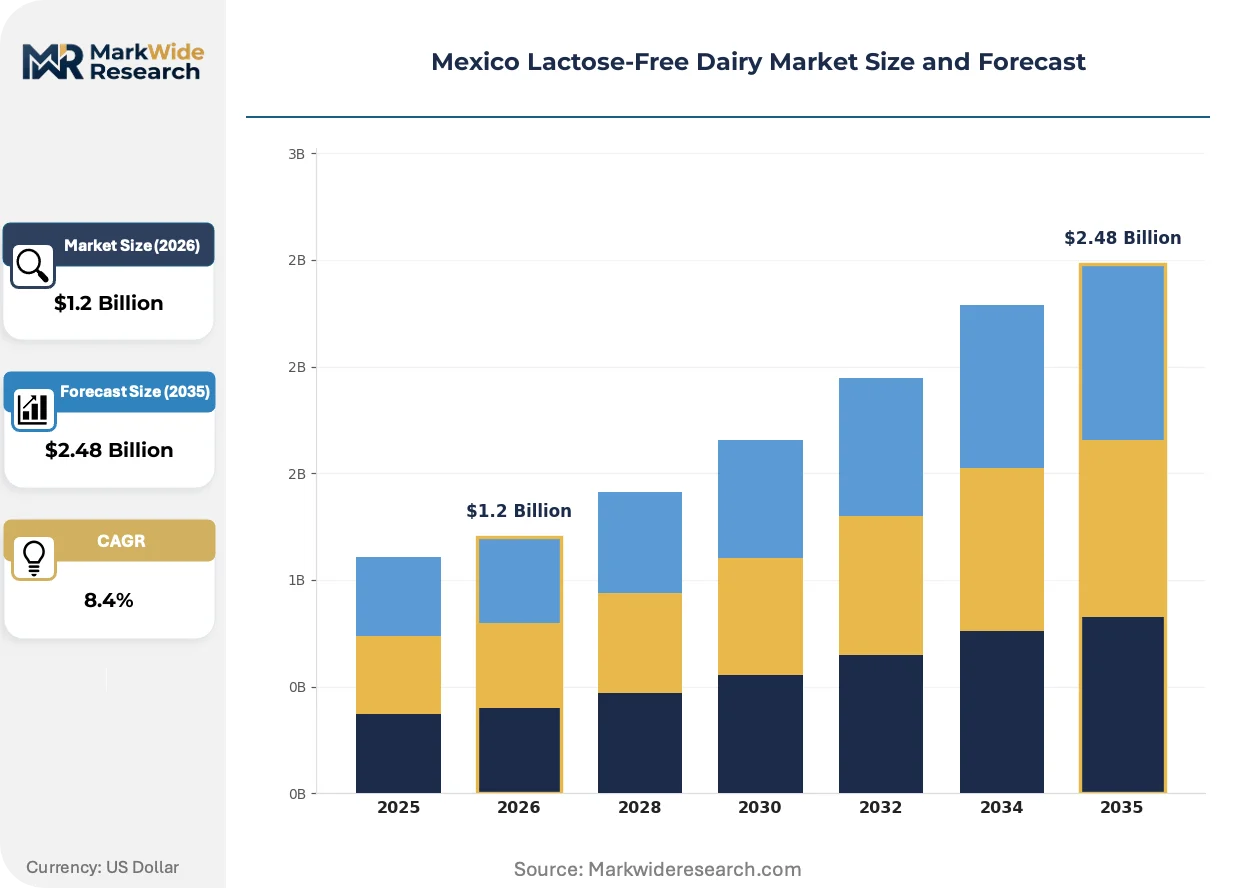
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Cream Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Customer Type: Individual Consumers, Restaurants, Cafés, Food Manufacturers Packaging Type: Cartons, Bottles, Tubs, Pouches |
| Companies Covered | Lala Group, Grupo Alpura, Sigma Alimentos, Nestlé S.A., Groupe Lactalis SA, Arla Foods amba, Fonterra Co-operative Group Ltd, Danone SA, FrieslandCampina NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Lactose-Free Dairy Market Trends and Innovations
Enzymatic hydrolysis protocols, regulatory labeling evolution, and channel format innovation are collectively repositioning lactose-free dairy from niche dietary management to mainstream functional food status across Mexican consumption occasions.
Advanced beta-galactosidase immobilization systems enable continuous-flow lactose reduction without batch interruption, cutting processing time by half for fluid milk lines. Medium-scale cooperatives in Jalisco and Guanajuato are piloting these systems to meet supermarket private-label specifications. This enzymatic efficiency gain is rewriting unit economics for regional processors competing against national refrigerated distribution networks.
NOM-243-SCFI/SSA1-2010 amendments under COFEPRIS review will tighten nutritional claim substantiation requirements for hydrolyzed dairy products. Reformulation investments are accelerating among processors seeking preemptive compliance ahead of enforcement windows. Fresh cheese and yogurt segments face the steepest documentation burdens given variable lactose reduction thresholds across SKU portfolios.
Digital-native urban shoppers in Mexico City are consolidating grocery purchases through supermarket app interfaces and quick-commerce platforms, collapsing traditional brand discovery at physical shelf. Rappi and Uber Eats partnerships now determine SKU visibility for lactose-free fluid milk in Polanco and Condesa neighborhoods. This route-to-consumer rotation privileges pack sizes and price points optimized for delivery economics over conventional multi-liter family formats.
Mexico Lactose-Free Dairy Market Segmentation
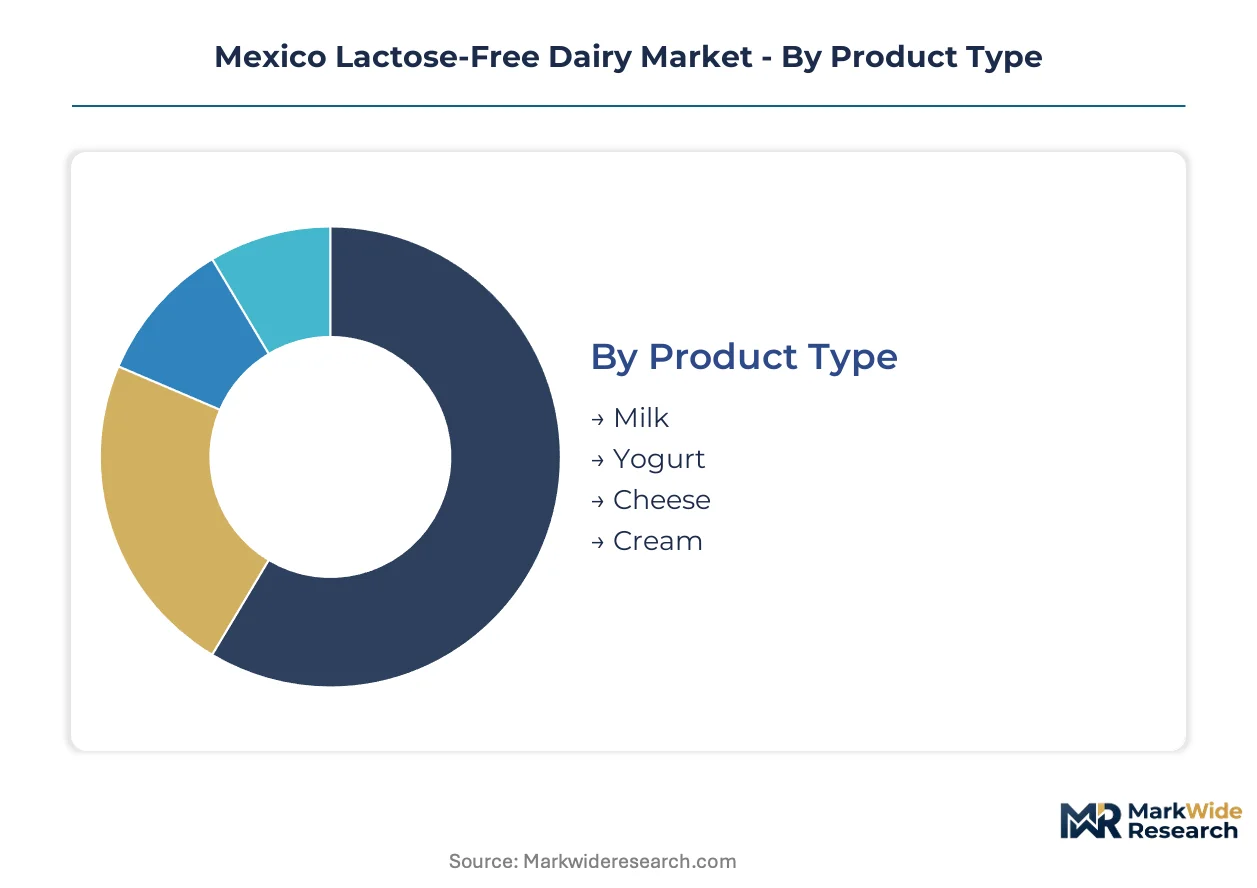
Segmentation reveals how enzymatic hydrolysis investments, cold-chain logistics constraints, and regulatory compliance burdens distribute differently across product formats and procurement channels. Understanding these fault lines helps processors prioritize capacity allocation and route-to-market strategies.
Product Type:
Supply concentration in fluid milk processing creates margin pressure for yogurt and cheese specialists lacking captive beta-galactosidase dosing capabilities.
- Milk:Fluid milk undergoes batch or continuous-flow enzymatic hydrolysis using beta-galactosidase to achieve 90% lactose reduction, yielding a sweetness profile that requires no added sugars. Household penetration concentrates in Mexico City and Monterrey breakfast consumption rituals, where urban consumers treat lactose-free positioning as a daily digestive wellness routine rather than clinical dietary management.
- Yogurt:Fermented lactose-free yogurt combines probiotic cultures with enzymatic pretreatment, creating dual-functional positioning that commands shelf space in premium supermarket formats. Demand from health-conscious millennials in Polanco and Condesa neighborhoods is climbing the fastest as probiotic-functional claims gain traction alongside lactose reduction.
- Cheese:Fresh cheese varieties dominate enzymatic hydrolysis applications given higher residual lactose tolerance in aged products; queso fresco and panela variants lead SKU development.
- Cream:Coffee creamer and cooking cream segments face formulation complexity from fat-water emulsion stability requirements during lactase treatment.
Today's leader: Milk. Tomorrow's challenger: Yogurt.
Distribution Channel:
Route-to-market economics split sharply between high-volume supermarket negotiations and emerging quick-commerce fulfillment models.
- Supermarkets:National chains control principal margin pools through slotting fees and private-label development, with Walmart, Soriana, and Chedraui dictating enzymatic specification standards for house brands. Their refrigerated distribution networks enforce batch traceability requirements that filter out smaller processors lacking ERP integration.
- Online Retail:Rappi and Uber Eats partnerships determine SKU visibility for single-serve formats in Mexico City neighborhoods, collapsing traditional brand discovery at physical shelf. Digital-native urban shoppers are consolidating grocery purchases through app interfaces, privileging pack sizes optimized for delivery economics.
- Convenience Stores:OXXO and 7-Eleven networks reward portable pouch packaging for on-the-go breakfast occasions, with limited refrigerated facings constraining SKU breadth.
- Health Food Stores:Specialized retailers in affluent districts carry premium-priced organic and grass-fed lactose-free variants targeting clinical dietary management segments.
Supermarkets anchor current volume. Online retail captures the steepest expansion trajectory.
Customer Type:
Procurement sophistication varies dramatically between household purchasers and institutional foodservice buyers.
- Individual Consumers:Household purchasers respond to front-of-pack labeling clarity and NOM-243-SCFI/SSA1-2010 nutritional claim validation, with price sensitivity moderating in urban centers where digestive wellness positioning commands premiums.
- Restaurants:QSR chains and casual dining operators in Monterrey under-index on lactose-free menu offerings, presenting white space for bulk fluid milk supply contracts with guaranteed enzymatic integrity through specialized cold-chain logistics.
- Cafés:Specialty coffee shops require barista-grade foaming performance from lactose-free milk, creating technical specification barriers for standard hydrolyzed products.
- Food Manufacturers:Industrial buyers of lactose-free dairy ingredients for baked goods and confectionery applications prioritize batch consistency and enzyme residual documentation for COFEPRIS compliance.
Individual consumers dominate transaction volume. Food manufacturers offer the most stable contract structures.
Packaging Type:
Format selection directly shapes channel access and consumption occasion targeting.
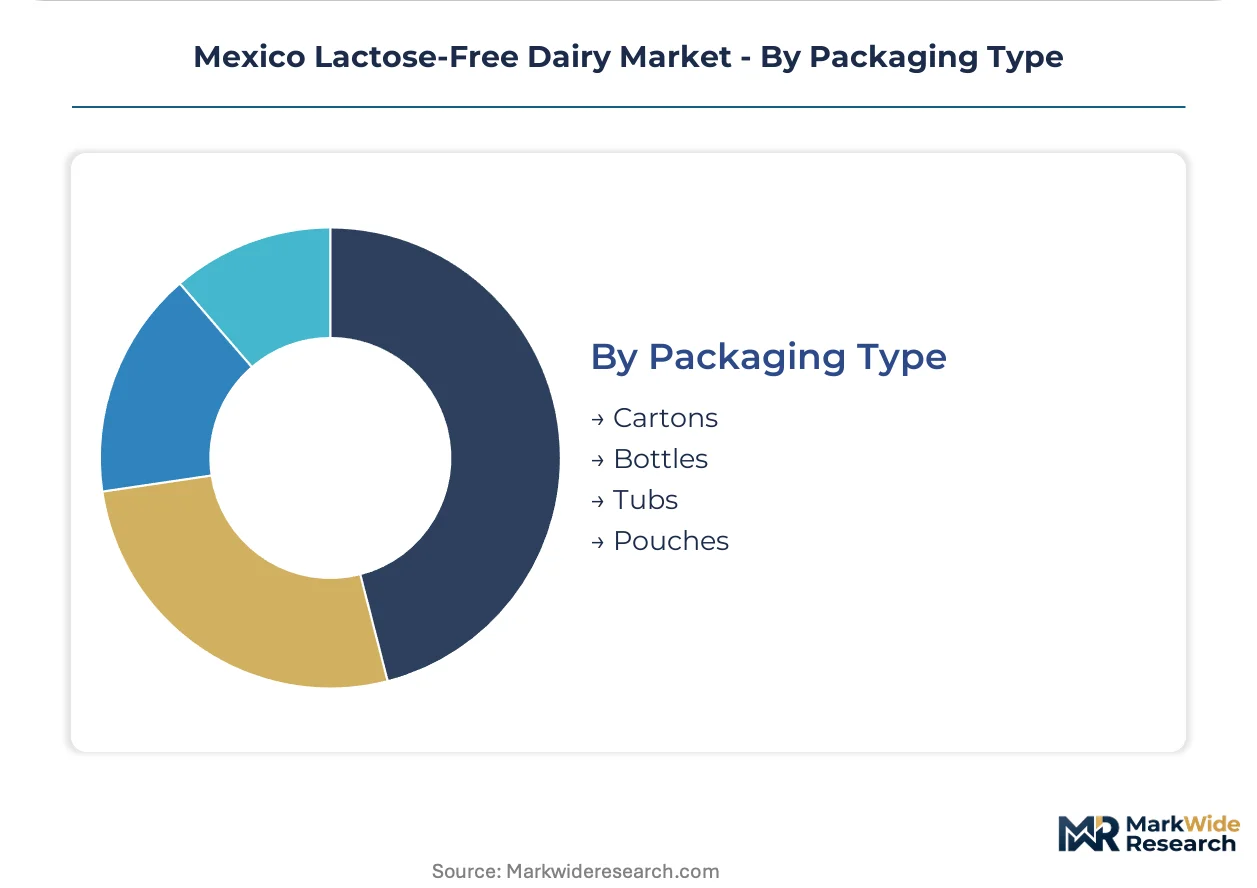
- Cartons:Aseptic cartons dominate multi-liter family formats for supermarket dairy aisles, with SIG Combibloc and Tetra Pak equipment investments required for shelf-stable lactose-free lines.
- Bottles:HDPE and PET bottles command refrigerated dairy case positioning, with clear packaging enabling visual quality cues for hydrolyzed milk's characteristic slight color shift.
- Tubs:Polypropylene tubs anchor yogurt and fresh cheese segments, with tamper-evident lidding requirements adding unit cost.
- Pouches:Single-serve flexible pouches are expanding most quickly in convenience channel distribution, with portion control and portability aligning with on-the-go urban consumption patterns.
Cartons hold current shelf dominance. Pouches represent the format innovation frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mexico lactose-free dairy industry traces its commercial roots to Mexico City's 1990s urbanization wave, when digestive wellness positioning first migrated from clinical dietary management into mainstream breakfast rituals. National processors subsequently scaled enzymatic hydrolysis capacity to serve concentrated metropolitan demand clusters.
Mexico City Metro
Polanco and Condesa neighborhoods drive premium yogurt adoption among millennial consumers seeking probiotic-functional positioning alongside lactose reduction. COFEPRIS headquarters proximity accelerates regulatory compliance timelines for processors testing NOM-243-SCFI/SSA1-2010 label amendments. Rappi and Uber Eats partnerships now dominate route-to-consumer economics, privileging single-serve formats optimized for quick-commerce delivery.
Nuevo León
Monterrey's industrial cafeteria and QSR chains under-index on lactose-free menu penetration, creating white space for bulk fluid milk supply contracts. The state's technical universities supply scarce enzymatic process technicians to regional dairy cooperatives. Sigma Alimentos anchors specialized cold-chain logistics infrastructure protecting beta-galactosidase integrity during summer temperature spikes.
Jalisco
Guadalajara's medium-scale cooperatives pilot continuous-flow lactase immobilization systems to meet supermarket private-label specifications. Agricultural extension programs promote backward integration into captive milk sourcing among family-owned processors. The Bajío dairy belt's feed grain concentration moderates input cost volatility for enzymatic hydrolysis operations.
Bajío Region
Querétaro's industrial biochemistry specialists command recruitment premiums for beta-galactosidase dosing optimization across central Mexico. Legacy ERP retrofitting for COFEPRIS-mandated batch traceability concentrates among Guanajuato-based software integrators. Regional processors leverage proximity to Mexico City distribution hubs without capital-city real estate costs.
Northern Border States
Chihuahua and Tamaulipas processors face cross-border competition from US lactose-free imports via NAFTA-era supply chains. Temperature-controlled warehousing investments accelerate to protect enzymatic integrity during extended summer transport. Maquiladora cafeteria procurement presents institutional volume opportunities for fluid milk suppliers meeting dual US-Mexico labeling standards.
Mexico Lactose-Free Dairy Market Competitive Landscape
The competitive structure tilts toward national refrigerated distribution networks with backward integration into milk sourcing. Three archetypes dominate: legacy dairy conglomerates leveraging captive supply chains, multinational CPG divisions importing enzymatic expertise, and regional cooperatives specializing in continuous-flow processing innovation. Dominant competitive moves include strategic partnerships with quick-commerce platforms and portfolio diversification into probiotic-functional yogurt lines.
Among Mexico-based processors, Lala Group exemplifies the national distribution archetype through refrigerated network scale, while Grupo Alpura anchors upstream control over domestic milk sourcing. Sigma Alimentos occupies the specialized logistics tier with cold-chain capabilities protecting enzymatic integrity. Multinational divisions including Nestlé S.A. and Danone SA represent imported formulation expertise and global R&D access.
| Leading Market Players |
|---|
| Lala Group |
| Grupo Alpura |
| Sigma Alimentos |
| Nestlé S.A. |
| Groupe Lactalis SA |
| Arla Foods amba |
| Fonterra Co-operative Group Ltd |
| Danone SA |
| FrieslandCampina NV |
| Others |
Pricing and Supply Chain Analysis
COFEPRIS-mandated front-of-pack labeling clarity is forcing processors to accelerate enzymatic hydrolysis investments ahead of enforcement windows, compressing margin structures and privileging national distributors with captive beta-galactosidase sourcing over spot-market dependent regional players.
Pricing Analysis
Premium-mid-economy pricing differentiation dominates Mexico's lactose-free dairy landscape. Brand heritage and enzymatic certification grade separate Lala Group and Grupo Alpura positioning from private-label supermarket tiers and unbranded cooperative supply. Cost compression in economy fluid milk is intensifying because OXXO and 7-Eleven networks negotiate volume rebates that erode per-unit economics for non-integrated processors. Quick-commerce shoppers in Polanco and Condesa demonstrate lowest price sensitivity, while household purchasers in Guadalajara's peripheral districts respond sharply to multi-liter promotional bundling.
Supply Chain Analysis
NOM-243-SCFI/SSA1-2010 nutritional claim substantiation requirements are reshaping domestic sourcing priorities toward captive milk supply and documented enzyme residual protocols. Raw dairy procurement draws from Jalisco, Guanajuato, and Nuevo León production belts, while beta-galactosidase enzyme concentrates rest on Danish and Dutch specialty chemical imports. Single-source vulnerability in refrigerated last-mile logistics concentrates risk among Sigma Alimentos and two national cold-chain networks during summer temperature spikes. Distribution runs through supermarket-controlled slotting fee negotiations and emerging Rappi quick-commerce partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's lactose-free dairy market functions as a geographic-arbitrage play where enzymatic process technician scarcity in Monterrey and Querétaro creates cost differentials against US border states competing for the same technical talent pool.
For Market Incumbents: To counter plant-based dairy substitution in premium Mexico City retail formats, Lala Group and Grupo Alpura should deepen backward integration into Guanajuato captive milk sourcing while accelerating single-serve pouch format development for OXXO channel exclusivity. Cold-chain infrastructure control remains the priority lever for protecting enzymatic integrity claims. For New Entrants and Emerging Players: Capture white space in Monterrey industrial cafeteria procurement and Nuevo León QSR bulk supply contracts where lactose-free menu penetration under-indexes national averages. Jalisco cooperatives piloting continuous-flow immobilization systems offer the most penetrable technical entry point through equipment partnership rather than greenfield capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with regional processors possessing documented COFEPRIS compliance infrastructure and established supermarket private-label relationships. The five-to-ten year viability window favors acquisition targets combining enzymatic hydrolysis expertise with ERP-integrated batch traceability. Pending front-of-pack warning label exclusions signal the critical inflection indicator for premium positioning validation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Enzyme Immobilization | Halves processing time for Jalisco cooperatives competing against national refrigerated networks. |
| Quick-Commerce Platform Partnership | Rappi and Uber Eats integration determines SKU visibility in Polanco and Condesa neighborhoods. |
| Backward Integration into Captive Milk | Grupo Alpura's upstream control moderates input cost volatility against spot market exposure. |
| COFEPRIS Preemptive Compliance Investment | Documentation readiness ahead of NOM-243-SCFI/SSA1-2010 amendments validates premium shelf positioning. |
| Single-Serve Pouch Format Expansion | OXXO and 7-Eleven channel access rewards portable packaging innovation for on-the-go breakfast occasions. |
Research Methodology
Bottom-up enzymatic hydrolysis capacity modeling reconciled against top-down refrigerated distribution network tracking forms the analytical core of this study. Primary interviews with dairy processing plant managers, COFEPRIS regulatory affairs leads, supermarket category buyers, and cold-chain logistics operators combined with secondary validation against SEC filings, customs import records for beta-galactosidase enzymes, and Nielsen retail audit data. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Historical trendline analysis of fluid milk, yogurt, and fresh cheese volume trajectories informed projection modeling across product type, distribution channel, and regional demand cluster dimensions. CAGRs were derived from curve-fitting observed adoption rates against urbanization and digestive wellness trend proxies. Forecast inputs incorporated enzymatic process efficiency gains, pending front-of-pack regulatory scenarios, and quick-commerce penetration curves.
Regulatory amendment timing, raw dairy input cost volatility, and plant-based substitution acceleration are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose and Derivative Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Dairy Foods Market
Dairy Products
China Dairy Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Low Fat Butter Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Flavored Yogurt Market
Dairy Products
India Milk Protein Market
Dairy Products
Kefir Market
Dairy Products
Organic Milk Powder Market