
 Middle East and Africa Dairy Ingredients Market | 2026-2036
Middle East and Africa Dairy Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dairy Ingredients Market Foresight
Saudi Arabia's dairy processing base is decoupling from historical dependence on European powder imports as domestic spray-drying capacity expands across the Kingdom. Fonterra Co-operative Group leverages its long-term Gulf supply contracts to sustain volume leadership in whey derivatives. Almarai Company anchors regional milk powder supply through its integrated dairy farming and processing operations in the Al Kharj cluster. Arla Foods Ingredients competes on specialized protein fractions for infant nutrition applications.
Middle East and Africa dairy ingredients encompass dehydrated milk solids, protein isolates, fat derivatives, and fermented fractions standardized for industrial food production, typically requiring heat stability above 80°C and defined protein dispersibility indices for reconstitution performance. Milk powder occupies the largest value share due to its ubiquity in beverage recombination and bakery applications across North African import markets. Whey protein represents the fastest-expanding product category as Gulf-based sports nutrition and clinical nutrition manufacturers expand captive formulation capacity. Infant formula application commands premium positioning through stringent mineral balance and microbiological specifications that filter supplier eligibility.
Saudi Arabia's SFDA enforces progressive dairy import standards aligned with Codex Alimentarius frameworks, while the UAE's Ministry of Climate Change and Environment administers halal certification protocols that govern cross-border ingredient acceptance. Egypt's National Food Safety Authority applies local microbiological thresholds that often exceed baseline Codex requirements for powdered dairy entering Alexandria and Damietta ports. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and Maghreb national standards when configuring multi-country distribution strategies.
Market Dynamics
Saudi Arabia's SFDA dairy fortification mandates and the UAE's halal certification protocols are compressing supplier qualification timelines while concentrating procurement authority among integrated dairy processors with captive testing laboratories.
Growth Catalysts
- Gulf infant formula localization:Saudi Arabia and the UAE are mandating domestic production quotas for pediatric nutrition, forcing multinational brands to establish regional blending facilities that source whey protein concentrates locally.
- Spray-drying capacity expansion:New processing clusters in Al Kharj and Al Ain are reducing lead times for milk powder reconstitution, enabling just-in-time beverage manufacturing across North African import markets.
- SFDA Codex alignment:The Saudi Food and Drug Authority's progressive adoption of international food safety frameworks is streamlining import documentation for qualified European and Oceania suppliers.
Market Restraints
- European whey concentrate dependency:Gulf-based formulators remain tethered to Danish and Dutch whey fractionation capacity, exposing margins to Atlantic freight volatility and currency swings.
- Halal certification fragmentation:Divergent protocols between the UAE's Ministry of Climate Change and Environment and Egypt's religious authority create duplicate audit burdens for cross-border ingredient shipments.
- Substitution by plant proteins:Pea and fava protein isolates are capturing share in sports nutrition applications where Muslim consumers accept non-dairy alternatives that bypass halal slaughter verification entirely.
Strategic Opportunities
- East African dairy belt development:Ethiopia's Awash Valley and Kenya's Rift Valley hold underexploited fluid milk collection networks that could anchor regional spray-drying infrastructure for export to Gulf markets.
- Clinical nutrition specialization:Arla Foods Ingredients and FrieslandCampina are developing medical-grade protein hydrolysates for dysphagia and renal care applications, commanding price multiples above standard whey concentrates.
- Blockchain traceability mandates:The UAE's emerging requirements for farm-to-fork documentation create first-mover advantage for suppliers with integrated ERP systems that can automate halal chain-of-custody records.
Industry Challenges
- Microbiological testing bottlenecks:Egypt's National Food Safety Authority applies Enterobacteriaceae thresholds below Codex baselines, forcing extended quarantine periods at Alexandria port that disrupt just-in-time manufacturing schedules.
- Integrated supply chain reconfiguration:Almarai and Nadec are backward-integrating into alfalfa farming and genetics, requiring ingredient suppliers to adapt procurement interfaces to vertically coordinated ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dairy Ingredients Market |
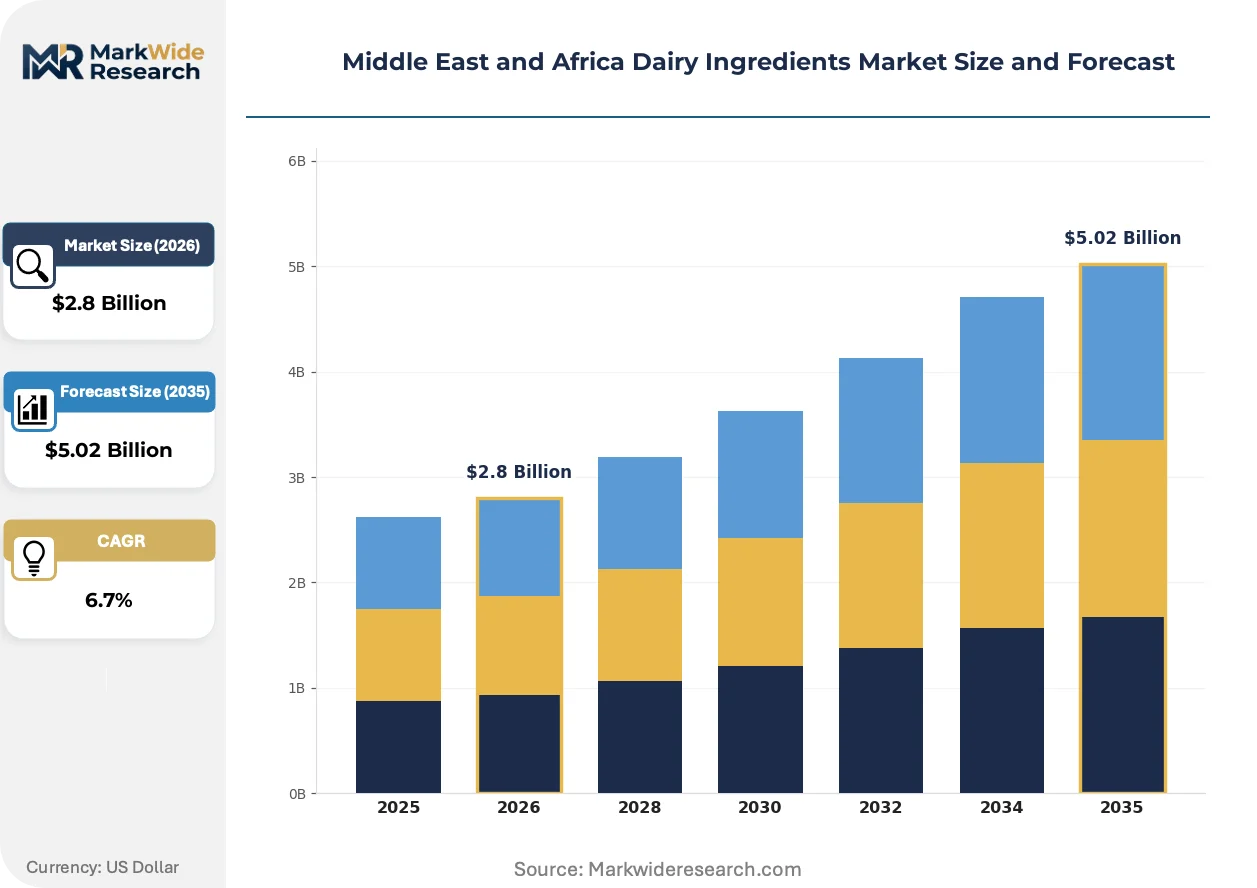
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Powder, Cheese Powder, Butter Oil, Whey Protein Application: Dairy Products, Bakery, Confectionery, Infant Formula End User: Food Manufacturers, Retailers, Food Service, Nutraceuticals Distribution Channel: Online, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Fonterra Co-operative Group, Almarai Company, Clover Industries Limited, LACTALIS Ingredients, Glanbia PLC, Royal FrieslandCampina, Saudi Dairy & Foodstuff Company (SADAFCO), Arla Foods Ingredients, Epi-ingrédients, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dairy Ingredients Market Shifts & Advancements
Membrane filtration advances and precision fermentation are compressing traditional extraction economics while Gulf regulators accelerate digitization of halal certification workflows.
Electrodialysis whey demineralization is electrifying the production of infant-grade protein fractions by enabling selective mineral removal without heat degradation. Saudi formulation houses are adopting this technology at pilot scale ahead of SFDA pediatric nutrition audits. The shift is compressing the cost gap between standard whey concentrates and pharmaceutical-grade isolates.
The UAE's Ministry of Climate Change and Environment is digitizing halal certificate verification through blockchain-linked platforms that cross-reference slaughterhouse records with ingredient batch codes. Industrial food manufacturers must now integrate API connections to these registries or face automatic customs holds at Jebel Ali. Dairy ingredient traders with legacy paper-based documentation are losing tender eligibility to technology-enabled competitors.
Direct procurement from processing cooperatives is displacing traditional trading house intermediaries in North African bulk milk powder purchasing. Egyptian and Moroccan recombination plants are establishing annual volume contracts with New Zealand's Fonterra and Ireland's Kerry Group, bypassing Dubai-based distributors. This channel compression is most visible in Cairo's beverage manufacturing corridor, where cost transparency pressures are eliminating historical markup layers.
Middle East and Africa Dairy Ingredients Market Segmentation
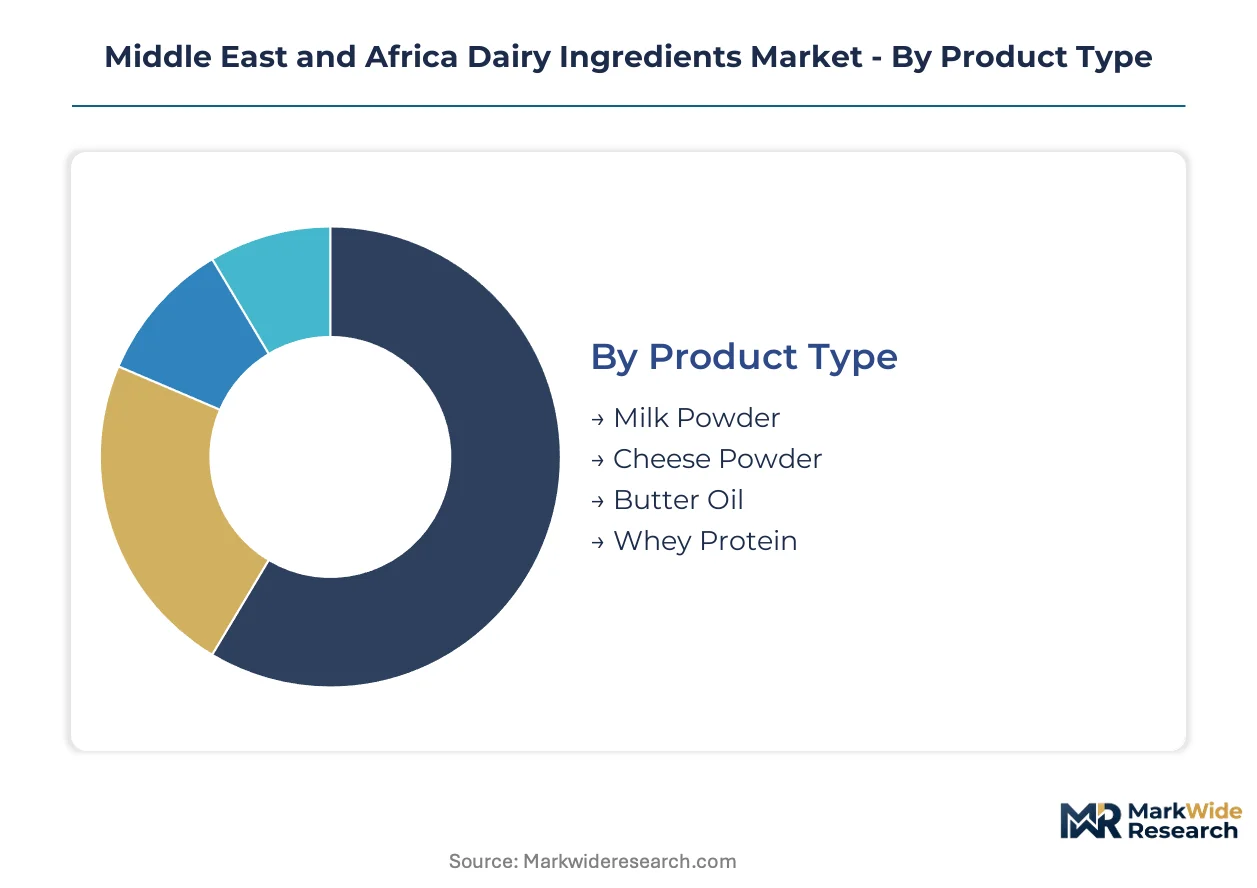
Dairy ingredient procurement in the Middle East and Africa splits sharply between commodity bulk purchasing and premium fractionation contracts. Gulf formulators prioritize functional specifications over origin, while North African buyers optimize for reconstitution economics at port.
Product Type:
Milk powder dominates tonnage flows through Alexandria and Jebel Ali, while whey protein commands the steepest price escalation curves.
- Milk Powder:Dehydrated whole and skim milk solids standardized for beverage recombination and bakery hydration. Egyptian recombination plants in the Cairo corridor source this grade for UHT milk production, though SFDA fortification mandates in Saudi Arabia are pushing specifications toward vitamin-enriched variants.
- Whey Protein:Protein concentrates and isolates fractionated through membrane separation, prized for dispersibility indices above 95% in infant formula applications. Gulf-based pediatric nutrition manufacturers in Riyadh and Dubai are expanding captive blending capacity, tightening regional supply.
- Cheese Powder:Spray-dried cheese solids with defined fat and salt content for savory snack seasoning.
- Butter Oil:Anhydrous milk fat fractions used in confectionery and ice cream manufacturing across North Africa.
Today's leader: Milk Powder. Tomorrow's challenger: Whey Protein.
Application:
Segment value correlates directly with specification stringency — infant formula tolerates no microbiological deviation, while bakery permits broader compositional ranges.
- Infant Formula:Pediatric nutrition requiring mineral-balanced protein fractions with Enterobacteriaceae thresholds below Codex baselines. SFDA audits of Saudi blending facilities are disqualifying suppliers lacking electrodialysis demineralization capability.
- Dairy Products:Recombined milk, yogurt, and cheese manufacturing across Egyptian and Moroccan processing corridors. Alexandria port quarantine delays for microbiological testing disrupt just-in-time production schedules for Cairo beverage manufacturers.
- Bakery:Milk powder for dough conditioning and browning reactions in industrial bread production.
- Confectionery:Butter oil and milk solids for chocolate and caramel applications.
Infant formula specifications filter supplier eligibility most aggressively. Bakery volume offers the deepest replacement market for plant protein substitutes.
End User:
Procurement authority concentrates among integrated manufacturers with captive laboratories, fragmenting among smaller traders.
- Food Manufacturers:Industrial dairy processors and recombination plants purchasing bulk powders and protein fractions. Almarai's Al Kharj cluster and Nadec's integrated operations in Saudi Arabia negotiate direct annual contracts, bypassing Dubai trading houses.
- Nutraceuticals:Sports nutrition and clinical nutrition formulators sourcing whey isolates and hydrolysates. UAE-based manufacturers are expanding medical-grade protein capacity for dysphagia and renal care applications.
- Retailers:Private-label dairy product chains importing packaged ingredients for repackaging.
- Food Service:Hospitality and catering distributors purchasing recombined milk and cream alternatives.
Integrated food manufacturers capture volume discounts through backward coordination. Nutraceuticals expand fastest on protein specialization.
Distribution Channel:
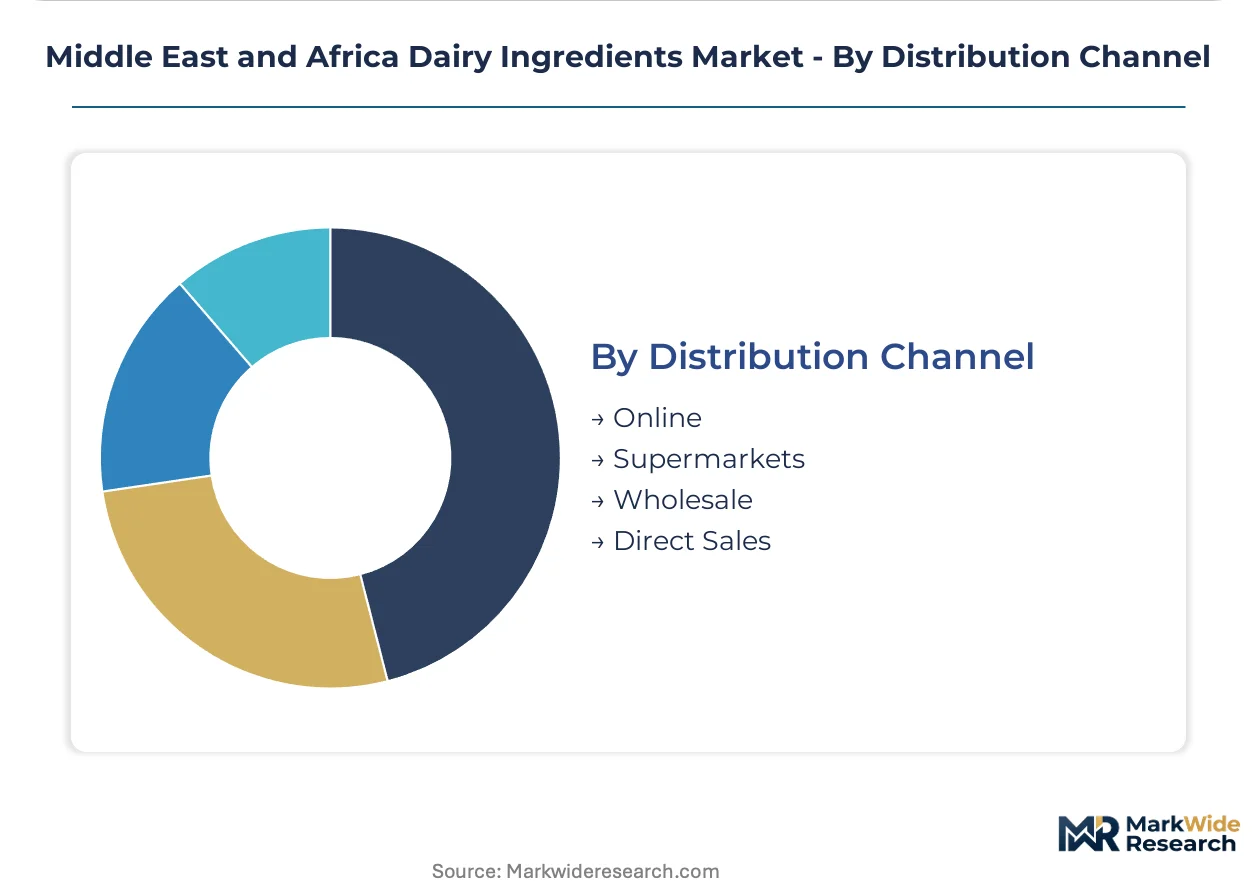
Channel selection tracks buyer scale and documentation sophistication — blockchain-enabled suppliers gain customs clearance advantages.
- Direct Sales:Annual volume contracts between processing cooperatives and industrial formulators. Fonterra and Kerry Group are displacing Dubai-based intermediaries in Egyptian bulk purchasing through direct procurement relationships with Cairo beverage manufacturers.
- Wholesale:Regional distributors serving mid-size recombination plants without import licensing capacity. Halal certification fragmentation between UAE and Egyptian protocols creates duplicate audit burdens for cross-border shipments.
- Online:Digital platforms for specialty protein samples and small-batch procurement.
- Supermarkets:Consumer-facing retail channels for packaged dairy ingredients.
Direct sales compress margin layers fastest. Wholesale retains relevance where halal documentation complexity demands intermediary expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography across the Middle East and Africa as Gulf fortification mandates and North African import testing protocols create divergent cost-of-compliance landscapes for dairy ingredient suppliers.
Saudi Arabia
SFDA dairy fortification guidelines and infant formula localization quotas are accelerating captive whey protein concentrate demand. The Al Kharj dairy cluster anchors domestic spray-drying capacity expansion as Almarai and Nadec backward-integrate into alfalfa farming and genetics programs. Riyadh-based formulation houses now source demineralized whey fractions from regional electrodialysis pilot facilities ahead of pediatric nutrition audits.
United Arab Emirates
MOCCAE blockchain-linked halal certification platforms are digitizing cross-border ingredient acceptance protocols. Dubai's Jebel Ali port customs now enforce automatic holds on dairy shipments lacking API-integrated chain-of-custody documentation. Abu Dhabi and Al Ain processing clusters are expanding medical-grade protein hydrolysate capacity for clinical nutrition applications targeting dysphagia and renal care segments.
Egypt
Cairo's beverage manufacturing corridor is displacing Dubai-based trading intermediaries through direct annual contracts with Oceania processing cooperatives. The National Food Safety Authority applies Enterobacteriaceae thresholds below Codex baselines, forcing extended quarantine periods at Alexandria and Damietta ports that disrupt just-in-time recombination schedules. Egyptian recombination plants prioritize cost transparency over intermediary markups in bulk milk powder procurement.
South Africa
Clover Industries and regional dairy cooperatives are developing spray-dried milk solids capacity for export to Gulf markets as East African fluid milk collection networks mature. The country's national food safety regulator maintains microbiological standards aligned with Codex frameworks, reducing documentation friction for European ingredient suppliers. Durban and Cape Town port infrastructure supports bulk powder re-export to North African markets.
Ethiopia
The Awash Valley holds underexploited fluid milk collection networks that could anchor regional spray-drying infrastructure for Gulf-bound export. Government-led agricultural modernization programs are targeting dairy belt development, though cold chain gaps currently limit industrial-scale ingredient processing. Addis Ababa's emerging food manufacturing base represents latent demand for standardized milk powders and protein fractions.
Middle East and Africa Dairy Ingredients Market Competitive Landscape
Oceania and European producers anchor the premium whey fractionation tier; Gulf-based integrated processors hold commodity powder supply through captive farming operations. The vendor base splits between membrane filtration specialists commanding infant-grade protein premiums and scale-driven recombination plants optimizing reconstitution economics. Three archetypes dominate: vertically coordinated dairy conglomerates with genetics-to-powder control, European fractionation houses competing on pharmaceutical-grade isolates, and trading intermediaries losing share to direct procurement relationships. Capacity expansion and blockchain traceability integration constitute the dominant competitive moves as customs digitization accelerates.
Within the integrated conglomerate tier, Fonterra Co-operative Group and Almarai Company exemplify divergent geographic anchoring strategies—Oceania cooperative structures versus Gulf captive supply chains. Arla Foods Ingredients occupies a position among European fractionation specialists targeting medical-grade protein applications. These three entities represent the competitive spectrum from commodity-scale powder supply through specialized clinical nutrition fractions, with each archetype responding differently to SFDA fortification mandates and MOCCAE halal digitization requirements.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Almarai Company |
| Clover Industries Limited |
| LACTALIS Ingredients |
| Glanbia PLC |
| Royal FrieslandCampina |
| Saudi Dairy & Foodstuff Company (SADAFCO) |
| Arla Foods Ingredients |
| Epi-ingrédients |
| Others |
Supply & Pricing Matrix
Global Dairy Trade price indices for whole milk powder and skim milk powder cascade through Middle East and Africa procurement contracts, compressing margins for Dubai-based trading intermediaries while rewarding direct relationships with Oceania processing cooperatives that bypass historical markup layers.
Pricing Analysis
Distributor margins of 8-12% in Egyptian wholesale channels are collapsing as Cairo beverage manufacturers negotiate direct annual contracts with Fonterra and Kerry Group, eliminating intermediary markups. Three-tier pricing structure across pharmaceutical-grade isolates, infant-grade demineralized fractions, and commodity recombination powders reflects certification stringency and electrodialysis capability. Cost compression in standard whey concentrates is intensifying because Gulf formulators remain tethered to European fractionation capacity. Price-sensitive North African recombination plants prioritize reconstitution economics over functional specifications, while premium infant formula manufacturers absorb minimal elasticity on mineral-balanced protein fractions.
Supply Chain Analysis
Atlantic and Red Sea freight volatility disrupts just-in-time schedules for whey protein concentrates moving from Danish and Dutch fractionation plants to Gulf blending facilities. Supply concentrates in New Zealand, Ireland, and Saudi Arabia's Al Kharj cluster, with backward integration into alfalfa farming and genetics programs reducing feedstock cost exposure. Raw material dependencies include fluid milk collection networks, membrane filtration equipment, and halal-certified slaughterhouse byproducts. Single-source vulnerability to European whey fractionation capacity exposes margins to currency swings. Distribution runs through Jebel Ali and Alexandria ports, with blockchain-enabled customs clearance creating tiered access advantages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
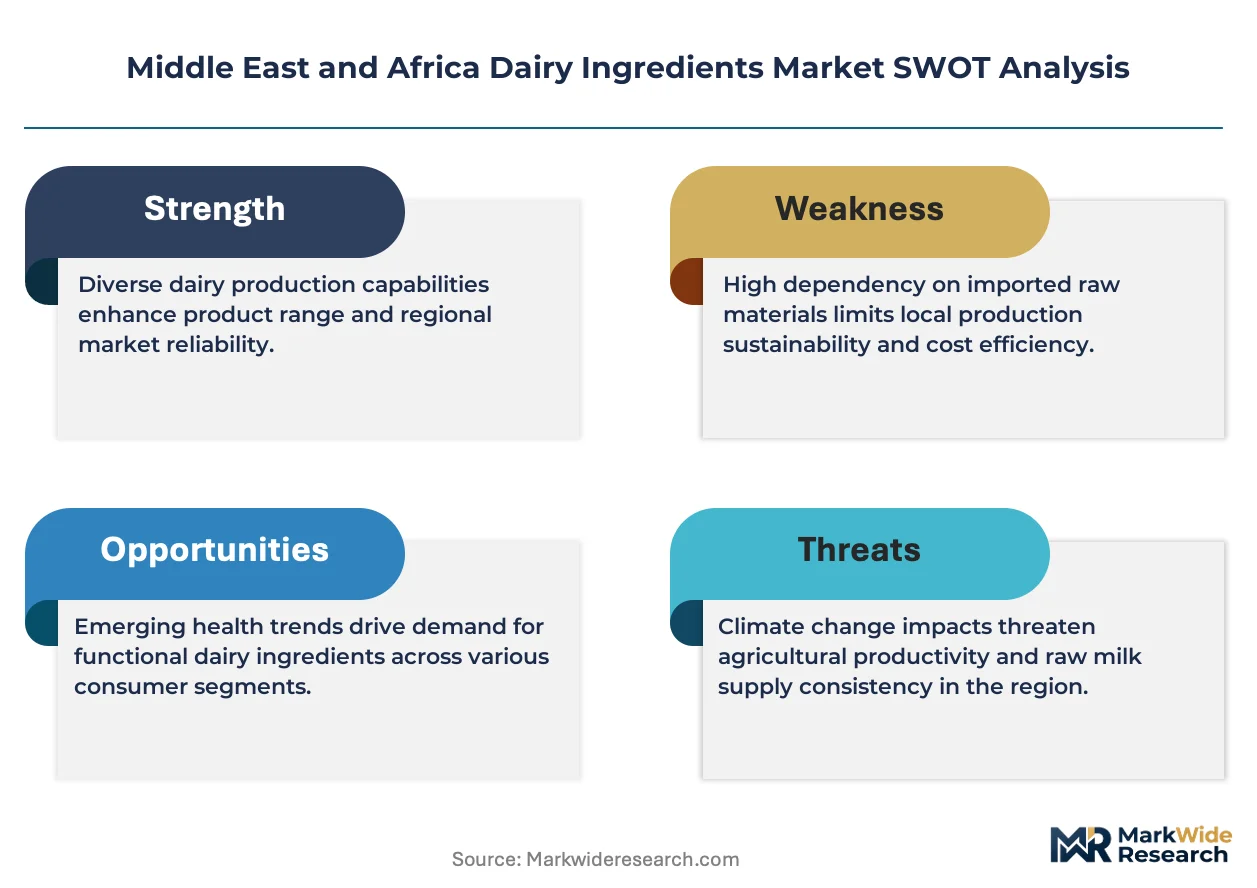
This market represents a late-cycle quality story as SFDA pediatric nutrition audits and MOCCAE blockchain traceability mandates filter supplier eligibility toward electrodialysis-capable fractionators with integrated ERP systems.
For Market Incumbents: Acquire membrane filtration pilot facilities in Riyadh ahead of SFDA pediatric nutrition audits to secure infant-grade protein fraction supply. Backward integration into alfalfa farming and genetics programs defends feedstock cost positions against Nadec and Almarai's captive supply chains. Certification investment in MOCCAE API-integrated documentation systems counters blockchain-enabled competitors gaining automatic customs clearance at Jebel Ali. For New Entrants and Emerging Players: Begin with clinical nutrition specialization targeting dysphagia and renal care applications in Abu Dhabi and Al Ain processing clusters, where medical-grade protein hydrolysates command price multiples above standard concentrates. Ethiopia's Awash Valley fluid milk collection networks offer the most penetrable white-space for regional spray-drying infrastructure serving Gulf export markets. A go-to-market angle anchored in halal chain-of-custody digitization bypasses legacy documentation burdens burdening established trading houses. For Investors and Strategic Acquirers: Asymmetric upside sits with European fractionation specialists possessing electrodialysis capability and existing Gulf supply contracts, as SFDA fortification mandates concentrate procurement authority among qualified suppliers. Long-term viability hinges on regulatory alignment capacity across divergent Egyptian and Gulf microbiological thresholds. The signal to watch is MOCCAE blockchain mandate expansion beyond Dubai to additional Emirates, which would accelerate technology-enabled supplier capture.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodialysis Capacity Installation | SFDA infant formula audits are disqualifying suppliers lacking demineralization capability, concentrating procurement authority. |
| Blockchain Traceability Integration | MOCCAE API-linked halal certificate verification creates automatic customs clearance advantages at Jebel Ali port. |
| East African Dairy Belt Development | Ethiopia's Awash Valley fluid milk networks could anchor regional spray-drying infrastructure for Gulf-bound export. |
| Direct Procurement Relationship Establishment | Cairo beverage manufacturers are bypassing Dubai intermediaries through annual volume contracts with Oceania cooperatives. |
| Clinical Nutrition Specialization | Medical-grade protein hydrolysates for dysphagia and renal care command price multiples above standard whey concentrates. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow databases, and stakeholder interviews — were reconciled to construct market estimates. Primary conversations with infant formula procurement directors, dairy processing plant managers, halal certification auditors, and port logistics coordinators were validated against secondary sources including SFDA guidance documents, MOCCAE blockchain platform specifications, Egyptian National Food Safety Authority import protocols, and Oceania dairy export statistics. Bottom-up volume modeling across product categories and top-down macroeconomic reconciliation ensured cross-verification.
Data-stream reconciliation anchored projections across the analysis window, with segmentation modeling spanning product type, application, end user, and distribution channel dimensions alongside regulatory compliance tier as an industry-specific stratifier. CAGRs were derived from trend extrapolation of import volume trajectories, capacity expansion announcements, and localization policy implementation timelines. Forecast inputs included Gulf infant formula production quotas, spray-drying capacity buildout schedules, and halal certification digitization rollout phases.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts, currency devaluation episodes, and animal disease outbreaks affecting fluid milk supply. Forecasts reflect assumptions about regulatory harmonization progress and technology adoption curves that may accelerate or stall. Stakeholders should weight assumptions against their own operating context and monitor SFDA audit enforcement intensity and MOCCAE blockchain mandate expansion as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Algae Omega-3 Ingredients Market
Ingredients
South America Soy Protein Ingredients Market
Ingredients
Distiller's Dried Grains with Solubles (DDGS) Feed Market
Ingredients
Glucuronolactone Market
Ingredients
Protein Hydrolysate Market
Ingredients
Green Gram Powder Market
Ingredients
Kilned Malt Market
Ingredients
Specialty Fats and Oils Market
Ingredients
South America Spirulina Extract Market
Ingredients
Bouillon Cubes Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Bran Market
Ingredients
Oyster Peptide Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Sunflower Meal Market
Ingredients
Instant Dry Yeast Market