
 Fermented Beverages Market | 2026-2036
Fermented Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Beverages Market Intelligence
The ascent of Health Enthusiasts and Gen Z Shoppers as primary consumer segments is recalibrating the competitive landscape for fermented drinks. Yakult Honsha sustains its market position through a singular focus on probiotic dairy beverages. The Coca-Cola Company leverages its extensive global distribution to introduce kombucha lines to mainstream consumers. Lifeway Foods competes by specializing in the kefir category, particularly within North American markets.
Fermented beverages are liquids produced via controlled microbial action, where microorganisms like yeast and bacteria convert carbohydrates into alcohol, carbon dioxide, or organic acids. This process defines the beverage's flavor, preservation, and nutritional profile. The kombucha product type shows significant expansion, driven by consumer interest in functional drinks. While Controlled Yeast Fermentation remains standard for hard cider, Symbiotic Culture technology is essential for the burgeoning kombucha and water kefir categories.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) create strict guidelines for alcohol content labeling and health benefit claims. National bodies like India's FSSAI also impose standards on production and sale. These rules force producers to manage fermentation processes with high precision to avoid classification as alcoholic beverages. Navigating the disparate legal definitions of these products remains a central strategic challenge for manufacturers aiming for cross-border expansion.
Market Dynamics
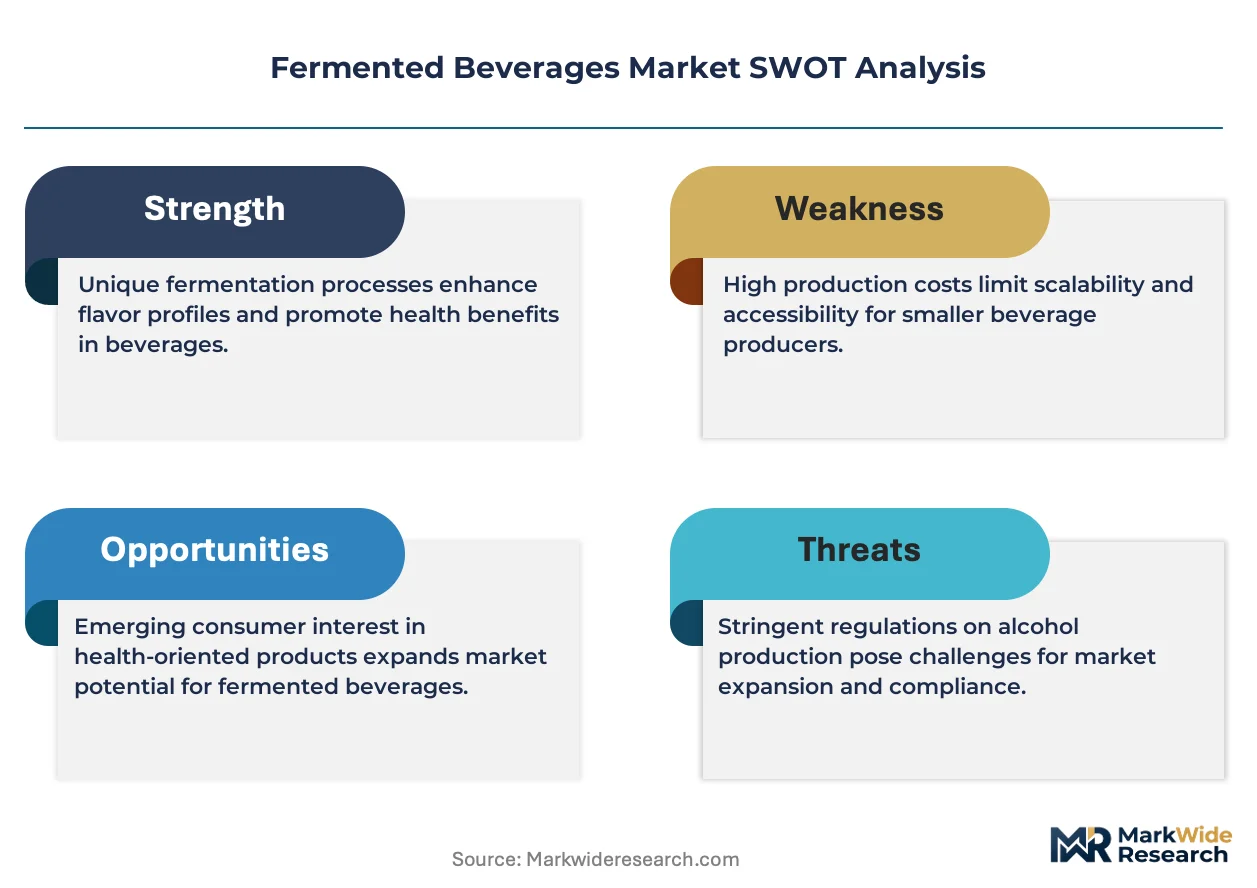
The central tension shaping the fermented beverages market is the conflict between consumer demand for functional health benefits and the stringent regulatory frameworks governing alcohol content and health claims, a dynamic that forces producers into precise process control.
Growth Catalysts
- SCOBY Innovation:Advances in the cultivation of Symbiotic Cultures of Bacteria and Yeast (SCOBY) are improving fermentation consistency, extending shelf life, and enabling the development of novel flavor profiles for products like kombucha.
- Functional Beverage Demand:Health-conscious consumer segments, particularly in the United States, are driving consumption of fermented drinks perceived as beneficial for gut health, creating a strong pull for probiotic-rich options like kefir and kombucha.
- Cold-Chain Logistics Expansion:The build-out of refrigerated supply chains allows for the stable distribution of live-culture beverages to a wider array of retail channels, including convenience stores and mainstream supermarkets, beyond specialty health food stores.
Market Restraints
- Alcohol Content Regulation:Strict limits on alcohol by volume, enforced by bodies like the US Food and Drug Administration (FDA), create a significant compliance burden, with slight process deviations risking reclassification as an alcoholic beverage.
- Input Cost Volatility:The price and quality of live starter cultures and organic raw materials are subject to fluctuation, impacting production costs and margin stability for manufacturers of premium fermented drinks.
- Substitution from Functional Drinks:Fermented beverages face competition from a wide array of other functional products, including fortified juices, plant-based milks, and enhanced waters that also target health-oriented consumers.
Strategic Opportunities
- Geographic Expansion:Commercialization of fermented beverages in Latin American and Southeast Asian markets presents a significant opportunity, leveraging local traditions of fermented foods to introduce new commercial product formats.
- Non-Dairy Product Development:Innovation in non-dairy fermented products, such as water kefir, fermented vegetable juices, and beet kvass, opens new avenues to attract vegan consumers and those with lactose intolerance.
- Process Optimization with AI:The application of artificial intelligence and machine learning to monitor and control fermentation parameters in real-time offers a path to maximizing batch consistency, optimizing flavor, and reducing waste.
Industry Challenges
- Production Inconsistency:Achieving consistent flavor, acidity, and carbonation levels from batch to batch remains a primary operational hurdle, especially for smaller producers relying on less-controlled fermentation environments.
- Cross-Border Compliance:Navigating disparate national food safety and labeling standards, such as the distinct requirements of the European Food Safety Authority (EFSA) and India's FSSAI, complicates international expansion strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Beverages Market |
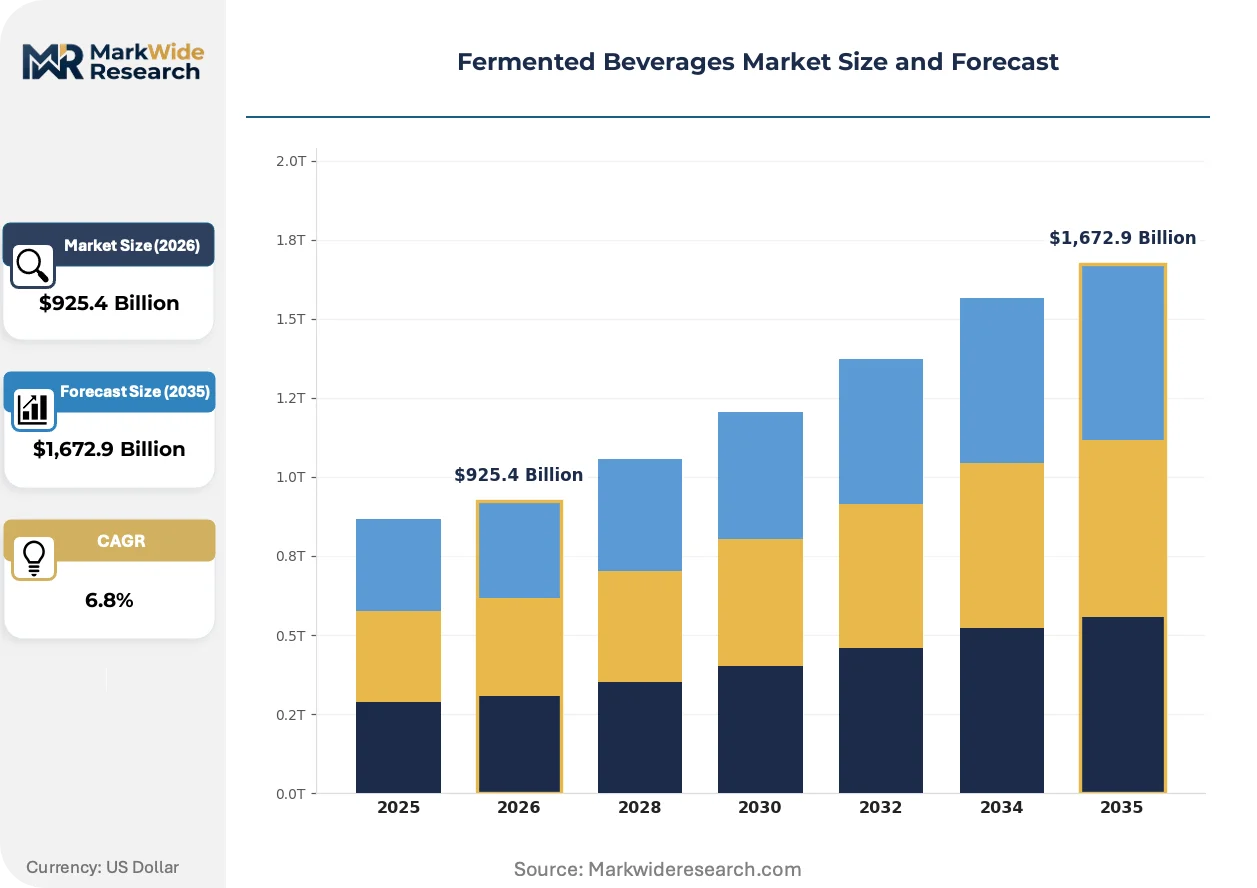
| Market Size in 2026 | $925.4 Billion |
| Market Size in 2035 | $1,672.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kombucha, Kefir, Hard Cider, Sake, Mead Fermentation Technology: Wild Fermentation, Controlled Yeast Fermentation, Symbiotic Culture, Lactobacillus Fermentation, Solid-State Fermentation Distribution Channel: Specialty Stores, Online Retailers, Restaurants, Liquor Stores, Farmers Markets Consumer Segment: Health Enthusiasts, Gen Z Shoppers, Premium Buyers, Eco-Conscious Consumers, Lifestyle Seekers |
| Companies Covered | PepsiCo, The Coca-Cola Company, Heineken, Chr. Hansen, Nestlé, Diageo, Yakult Honsha, Lifeway Foods, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Beverages Market Strategic Shifts & Innovations
The industrialization of artisanal fermentation methods defines the market's current trajectory. Precision control technologies and sophisticated culture management are transforming production from a craft-based art into a scalable science, enabling greater consistency and functional specialization across product lines.
Automated bioreactors integrated with real-time sensors provide granular control over fermentation variables like pH and temperature. Large-scale kombucha and kefir producers are rapidly adopting this equipment to ensure product safety and consistency. This technology is modularizing the fermentation process, allowing manufacturers to precisely engineer specific functional outcomes and flavor profiles by adjusting inputs and culture compositions.
European Food Safety Authority (EFSA) guidelines impose a high evidence threshold for health and nutrition claims on food labels. This regulatory stance compels manufacturers to fund expensive clinical trials to validate any specific probiotic or gut-health benefits. The functional kombucha and kefir categories are most affected, leading many brands to pivot their marketing from explicit health claims to more general messaging around wellness and natural ingredients.
Consumer preference is shifting toward products with transparent sourcing and local production origins. This behavior challenges the economies of scale enjoyed by national brands in mass-market retail channels, creating openings for smaller, regional producers. This trend is most visible in metropolitan areas across North America and Europe, where farmers' markets and specialty food retailers become key sales channels for artisanal fermented beverages.
Fermented Beverages Market Segmentation
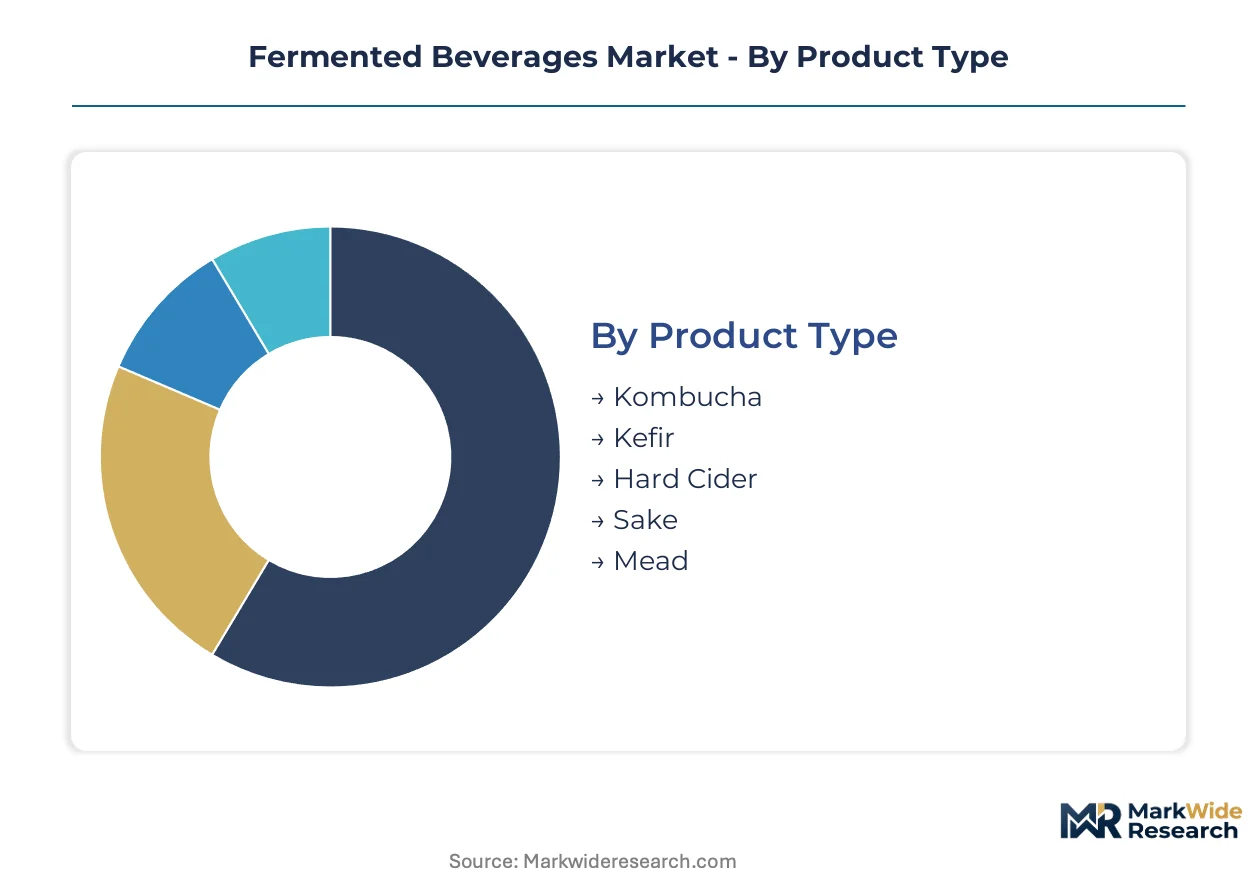
The segmentation of the fermented beverages market provides a granular view of consumer preferences and technological advancements driving product innovation. Understanding these distinct market slices enables manufacturers to tailor product development and marketing strategies effectively, addressing specific demand pockets across diverse consumer groups and geographical regions.
Product Type:
Supply concentration in the fermented beverages market heavily influences product type availability and market dominance, with specific categories benefiting from established production methods and consumer familiarity.
- Kombucha:This effervescent beverage, made from tea fermented with a Symbiotic Culture of Bacteria and Yeast (SCOBY), offers a tangy flavor profile. Consumer interest in functional drinks, particularly in the United States, drives significant demand for probiotic-rich kombucha.
- Kefir:A fermented milk drink, kefir contains a diverse array of probiotics and is produced by inoculating milk with kefir grains. Health-conscious consumers, especially in North American markets, seek kefir for its gut health benefits and nutritional value.
- Hard Cider:An alcoholic beverage produced from the fermentation of apple juice, hard cider maintains a traditional consumer base.
- Sake:This Japanese alcoholic beverage is made by fermenting rice, water, yeast, and koji mold, offering a unique cultural and flavor experience.
- Mead:An ancient alcoholic beverage created by fermenting honey with water, mead appeals to niche markets seeking artisanal and historical drink options.
Today's leader: Kombucha. Tomorrow's challenger: Kefir.
Fermentation Technology:
The maturity of fermentation technologies dictates consistency and scalability within the fermented beverages sector, influencing product quality and market reach.
- Symbiotic Culture:This technology utilizes a live culture of bacteria and yeast, such as SCOBY for kombucha or kefir grains, to ferment a substrate. Advances in SCOBY cultivation are improving product consistency and extending shelf life for categories like kombucha and water kefir.
- Controlled Yeast Fermentation:This method employs specific strains of yeast under controlled conditions to convert sugars into alcohol and carbon dioxide. Hard cider production widely utilizes controlled yeast fermentation to achieve desired alcohol content and flavor profiles.
- Wild Fermentation:This traditional process relies on naturally occurring microorganisms from the environment or raw ingredients to initiate fermentation.
- Lactobacillus Fermentation:This technology uses lactic acid bacteria to ferment sugars, primarily found in dairy products like yogurt and some vegetable ferments.
- Solid-State Fermentation:This technique involves microbial growth on solid substrates in the absence or near absence of free water, often used for producing enzymes or specific metabolites.
The Symbiotic Culture segment is gaining share fastest, driven by health-conscious consumer demand.
Distribution Channel:
Customer type significantly shapes the distribution channels for fermented beverages, with different retail environments catering to distinct purchasing behaviors and product access needs.
- Specialty Stores:These outlets often focus on niche, artisanal, or organic products, providing a curated selection of fermented beverages. Consumers seeking premium or unique fermented drinks frequently visit specialty stores for their diverse offerings.
- Online Retailers:E-commerce platforms offer convenience and a broader product range, enabling consumers to access a wide variety of fermented beverages from different brands. The expansion of cold-chain logistics supports the stable distribution of live-culture products through online channels.
- Restaurants:Foodservice establishments integrate fermented beverages into their menus, offering options like kombucha or craft ciders as complementary drinks.
- Liquor Stores:These retail locations primarily stock alcoholic fermented beverages such as hard cider, sake, and mead, catering to adult consumers.
- Farmers Markets:Local producers frequently sell artisanal and small-batch fermented beverages directly to consumers at farmers markets, emphasizing transparent sourcing and regional appeal.
Online Retailers exhibit the steepest expansion trajectory, reflecting evolving consumer purchasing habits.
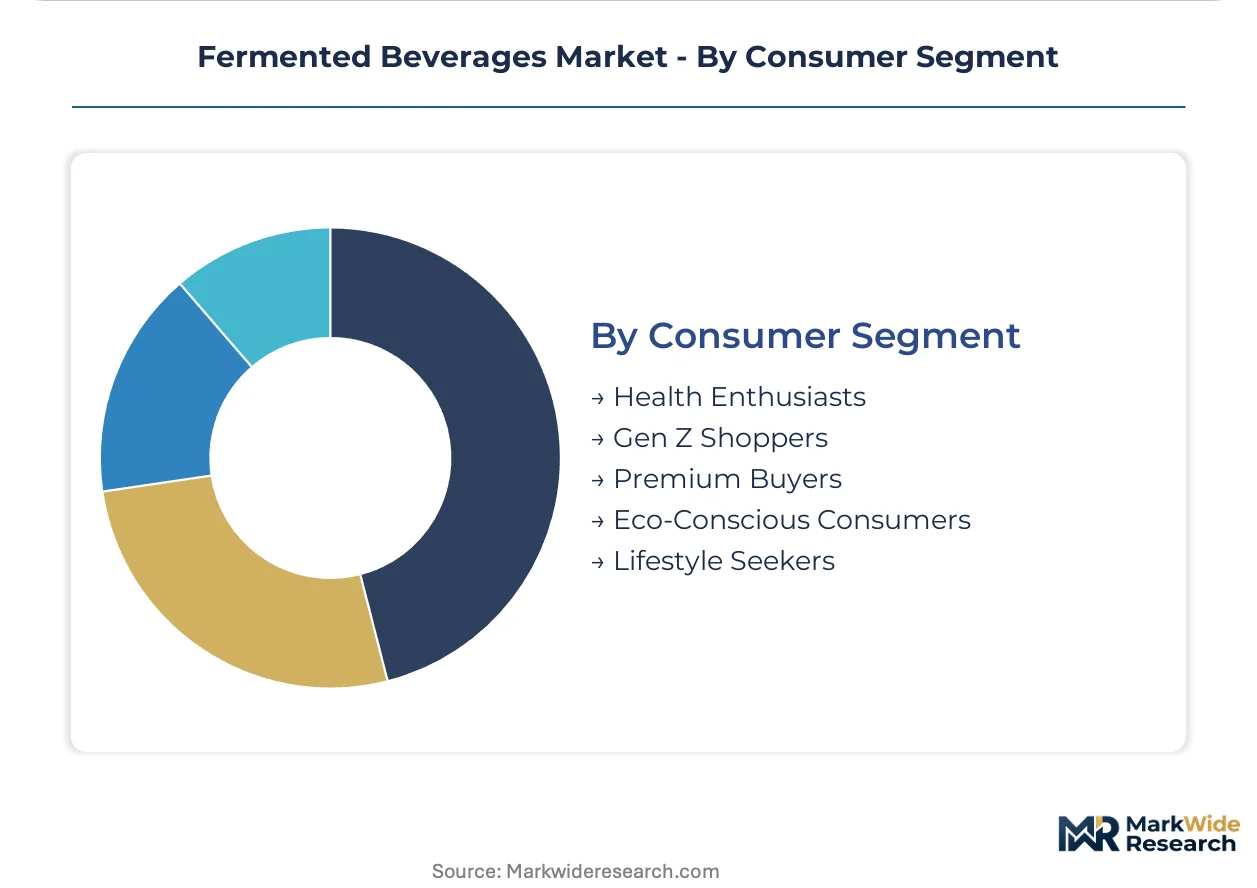
Consumer Segment:
The cost tier of fermented beverages often aligns with specific consumer segments, reflecting varying priorities from health benefits to lifestyle choices.
- Health Enthusiasts:This segment prioritizes functional benefits, seeking fermented beverages for gut health, probiotics, and natural ingredients. Demand from health enthusiasts, particularly in the United States, serves as a primary growth engine for the market.
- Gen Z Shoppers:This younger demographic often seeks innovative, transparently sourced, and socially conscious products. Gen Z shoppers are recalibrating the competitive landscape for fermented drinks, favoring brands that align with their values.
- Premium Buyers:Consumers in this segment are willing to pay more for high-quality, artisanal, or specialty fermented beverages with unique flavor profiles.
- Eco-Conscious Consumers:This group prefers products with sustainable sourcing, eco-friendly packaging, and minimal environmental impact.
- Lifestyle Seekers:These consumers integrate fermented beverages into their daily routines as part of a broader wellness or experiential lifestyle.
Health Enthusiasts represent the fastest-growing segment, driving significant market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Producers navigate varying regulatory landscapes, influencing where production concentrates due to compliance costs and market access. Differing alcohol content limits for fermented beverages create opportunities for regulatory arbitrage, especially for products like kombucha. This dynamic fosters localized production hubs that cater to specific national standards.
United States
Health enthusiasts drive significant demand for functional fermented beverages, particularly kombucha and kefir. The US Food and Drug Administration (FDA) enforces strict alcohol content limits, influencing production processes. California's vibrant food scene, especially around cities like Los Angeles, acts as a hub for innovative fermented beverage startups and artisanal producers.
Germany
European consumers prioritize health and wellness, fueling demand for probiotic-rich drinks. The European Food Safety Authority (EFSA) sets stringent guidelines for health claims, compelling manufacturers to focus on general wellness messaging. Berlin's burgeoning craft beverage industry fosters innovation in non-alcoholic fermented drinks and alternative flavor profiles.
India
Consumer interest in traditional health remedies and functional foods supports the growth of fermented beverages. India's FSSAI establishes comprehensive standards for food production and labeling, ensuring product safety and quality. Urban centers like Bengaluru and Mumbai are seeing a rise in specialized fermented beverage producers catering to health-conscious populations.
Japan
A deep cultural appreciation for fermented foods, such as miso and sake, translates into sustained interest in new fermented beverage formats. The Ministry of Economy, Trade and Industry (METI) supports traditional food industries, including sake production. Kyoto, with its rich culinary heritage, remains a center for artisanal fermentation techniques and premium beverage craftsmanship.
Brazil
Emerging market demand for functional and natural food products is expanding the fermented beverages sector. Brazil's ANVISA regulates food and beverage safety, impacting production and distribution for both local and imported products. São Paulo, as a major economic hub, sees significant investment in modern production facilities for kefir and kombucha to serve a growing consumer base.
Fermented Beverages Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. Large consumer packaged goods (CPG) companies often leverage their existing distribution networks to introduce fermented lines, while smaller, specialized brands focus on niche health-conscious consumers. Strategic archetypes include global beverage giants, dedicated probiotic specialists, and regional artisanal producers. Competitive moves frequently involve portfolio diversification into functional categories and strategic partnerships to expand market reach.
Global CPG leaders like PepsiCo and The Coca-Cola Company occupy a significant position by integrating fermented beverage lines into their extensive product portfolios, leveraging their global distribution capabilities. These companies represent the scale-driven end of the market, focusing on mainstream appeal. Conversely, Yakult Honsha exemplifies a specialist, anchoring its market presence through a singular focus on probiotic dairy beverages and maintaining a distinct niche within the health and wellness segment.
| Leading Market Players |
|---|
| PepsiCo |
| The Coca-Cola Company |
| Heineken |
| Chr. Hansen |
| Nestlé |
| Diageo |
| Yakult Honsha |
| Lifeway Foods |
| Danone |
| Others |
Cost & Logistics Intelligence
Skilled fermentation specialists in regions with established artisanal traditions, such as Kyoto, influence pricing tiers. These labor-cost differentials contribute to the premiumization of specialty fermented beverages over mass-produced lines.
Pricing Analysis
Retailer markup significantly impacts the final consumer price for fermented beverages. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade and brand premium, alongside geographic delivery costs. Pricing softness reflects competition from substitute functional drinks, especially in mainstream channels. Health Enthusiasts exhibit lower price sensitivity for probiotic-rich options, while Gen Z Shoppers often seek value and transparently sourced alternatives.
Supply Chain Analysis
Regional distribution centers facilitate the movement of temperature-sensitive fermented beverages to retail outlets. Supply concentration for key ingredients such as live starter cultures and organic raw materials centers on the United States and Japan. The supply chain relies on robust cold-chain logistics, creating potential chokepoints and increasing operational costs for wider market penetration. Distribution runs through both specialty stores and online retailers, with direct-to-consumer models gaining traction for artisanal brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermented beverages represent a stable compounder, with consistent growth driven by sustained consumer demand for functional health benefits. This market offers resilient opportunities for strategic positioning.
For Market Incumbents:Anticipate continued pressure from functional drink substitutes by diversifying product portfolios into non-dairy fermented options. Invest in process optimization, leveraging AI to enhance product consistency and reduce waste, countering margin pressure. Reinforce channel control through strategic partnerships with major supermarket chains. Expand capacity in key regional hubs like São Paulo to meet emerging market demand.
For New Entrants and Emerging Players:Launch via direct-to-consumer online retail channels to penetrate the market with innovative non-dairy fermented products like water kefir. Target vegan consumers and those with lactose intolerance in North American metropolitan areas. Focus on unique flavor profiles and transparent sourcing to differentiate from established brands. Leverage social media campaigns to build brand awareness among Gen Z shoppers.
For Investors and Strategic Acquirers:Global CPG leaders are the most active acquirers in this space, seeking to integrate functional beverage lines. This market offers long-term viability over the next decade due to sustained wellness trends. Target niche brands with proprietary SCOBY innovations or strong regional presence, particularly in Europe. The signal to watch is regulatory clarity on health claims from bodies like the European Food Safety Authority (EFSA).
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach to vegan consumers with non-dairy fermented options. |
| AI-driven Process Optimization | Enhances product consistency and reduces waste in large-scale kombucha production. |
| Direct-to-Consumer Channel Development | Captures health-conscious consumers seeking transparently sourced artisanal products. |
| Geographic Expansion into Emerging Markets | Leverages local fermented food traditions to introduce new commercial formats. |
| Investment in Clinical Validation | Provides evidence for health claims, strengthening market position against competitors. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and market sizing models — were reconciled for this analysis. Primary research included conversations with fermentation scientists, brand managers, retail buyers, and regulatory compliance officers. Secondary data sources comprised FDA filings, EFSA reports, and industry association publications. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
Historical market performance was cross-referenced against expert panel input to project future trajectories across the analysis window. The analytical framework modeled product type, fermentation technology, distribution channel, and consumer segment. Compound Annual Growth Rates were derived through regression analysis and expert consensus, factoring in SCOBY innovation rates and cold-chain logistics expansion.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or unexpected input cost volatility. Forecasts reflect underlying market assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Draught Beer Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
Europe Kegs Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Champagne Market