
 Port Wine Market | 2026-2036
Port Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Port Wine Market Outlook
REACH compliance is repositioning export economics for Port houses selling into European markets. Symington Family Estates Vinhos S.A. leverages its vertical vineyard ownership across the Douro Superior to secure grape supply. Niepoort Vinhos S.A. differentiates through its concentration on traditional foot-treading methods and niche colheita releases. The Fladgate Partnership dominates the luxury hospitality channel with its aged Tawny portfolio and lodge tourism infrastructure in Vila Nova de Gaia.
Port Wine denotes a fortified wine produced exclusively from grapes grown in the Douro Valley of Portugal, with neutral grape spirit added during fermentation to arrest sugar conversion and achieve alcohol levels between nineteen and twenty-two percent by volume; the resulting beverage serves as a premium dessert wine and after-dinner digestif across hospitality and retail channels. Tawny Port commands the largest volume share due to its approachable price positioning and consistent quality in non-vintage releases, while Vintage Port captures disproportionate margin pools through scarcity-driven auction and cellar-door channels. Online Retail is gaining traction among younger demographics seeking direct access to limited quinta bottlings, though Specialty Stores still anchor discovery and education for higher-alcohol-strength expressions.
EU Geographical Indication rules enforced by EFSA and national regulators in Portugal mandate strict provenance labeling, while the US TTB governs import standards for alcohol content and origin declarations. These frameworks elevate compliance costs for new entrants but reinforce price premiums for established Douro producers with certified vineyard traceability. Stakeholders must monitor evolving GI enforcement intensity and digital-channel regulatory adaptations to calibrate inventory and pricing strategies.
Market Dynamics
EU Geographical Indication enforcement under the EU Green Deal is tightening provenance verification requirements, forcing Port houses to restructure vineyard documentation and export certification workflows. This regulatory pressure compounds with premium hospitality channel consolidation in Portugal and the United States, where aged Tawny and Vintage releases command disproportionate margin concentration.
Growth Catalysts
- EU Green Deal GI Enforcement:Mandatory traceability systems elevate entry barriers for non-Douro producers, reinforcing price premiums for certified quintas with documented vineyard lineage.
- Premium Hospitality Channel Absorption:Luxury hotel and restaurant groups in Portugal and the United States are expanding aged Tawny by-the-glass programs, creating pull-through for higher-margin colheita and vintage releases.
- Online Retail Infrastructure:Direct-to-consumer platforms enable younger demographics to access limited quinta bottlings without intermediary markup, bypassing traditional wholesale tiers.
Market Restraints
- Grape Supply Concentration:Established quintas in the Douro Superior control the majority of mature vineyard holdings, constraining expansion capacity for newer entrants without backward integration into upstream acreage.
- REACH Compliance Cost Burden:Export economics for Port houses selling into European markets face elevated testing and documentation expenses for bottle materials and labeling substrates.
- Fortified Wine Substitution:Sherry from Jerez and Madeira compete for after-dinner digestif occasions, particularly in price-sensitive retail segments where Tawny Port premium positioning creates vulnerability.
Strategic Opportunities
- Lodge Tourism Integration:Vila Nova de Gaia cellar-door experiences convert visitors to high-margin direct purchasers, reducing channel dependency for aged stock releases.
- Foot-Treading Method Differentiation:Traditional lagar fermentation techniques command narrative premiums in experiential retail, creating white space against mechanized extraction competitors.
- United States TTB Label Clarity:Simplified origin declarations for Douro-certified imports reduce consumer education friction, accelerating discovery among wine-curious millennials.
Industry Challenges
- Viticultural Talent Scarcity:Schist-terroir vineyard management and manual harvesting expertise concentrate among aging Douro Valley workforces, constraining quality-consistency at scaling quintas.
- Aged Inventory Carrying Costs:Decades-long maturation requirements for Vintage and Tawny with age indications tie up working capital, compressing liquidity for smaller houses without diversified revenue streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Wine Market |
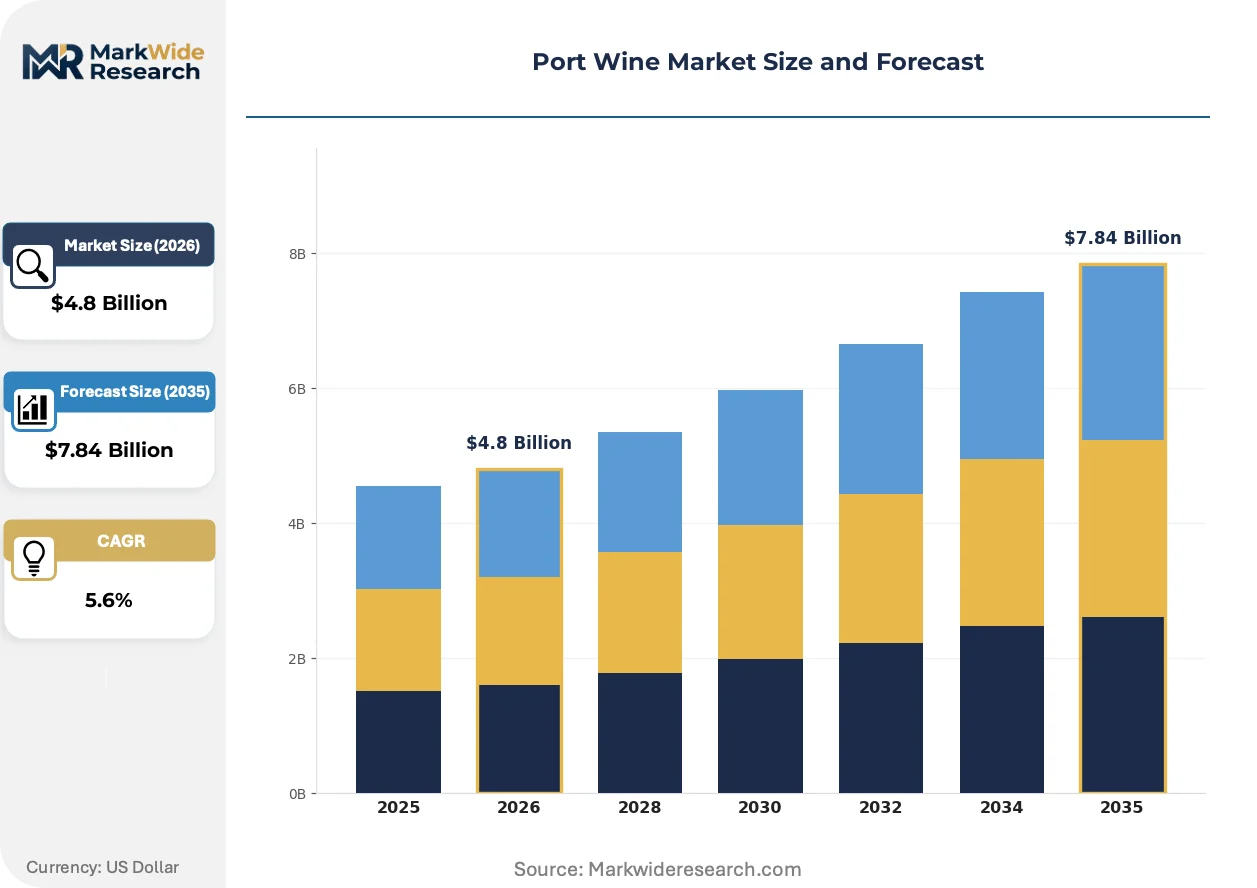
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Tawny, Ruby, White, Vintage Alcoholic Strength: Standard, Reserve, Late Bottled Vintage, Crusted Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bottle, Tetra Pak, Can, Keg |
| Companies Covered | Kopke Group, Niepoort Vinhos S.A., Symington Family Estates Vinhos S.A., Ramos Pinto, Quinta do Crasto SA, Sogrape SGPS SA, Quinta do Noval, Fonseca Port Wine, The Fladgate Partnership, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Wine Market Strategic Shifts
Digital traceability systems and fermentation technology refinements are compressing quality variance while regulatory transparency mandates reshape competitive positioning. These forces converge with channel fragmentation that privileges direct relationships over wholesale intermediation.
Precision viticulture sensors deployed across Douro Valley quintas monitor schist-terroir moisture and temperature gradients in real time. Established producers are absorbing this telemetry to optimize harvest timing and reduce vintage variation. The technology is absorbing quality-control functions previously dependent on experiential judgment, enabling more consistent extraction profiles across lagar lots.
EFSA-mandated Geographical Indication verification protocols now require blockchain-anchored vineyard documentation for EU market access. Port houses must retrofit supply chain audit trails from grape to bottle, elevating compliance overhead but reinforcing scarcity value for certified Douro origin. Smaller quintas without dedicated regulatory staff face disproportionate adaptation timelines.
Specialty Stores anchor discovery and education for higher-alcohol-strength expressions, yet Online Retail gains traction among demographics seeking direct access to limited releases. Younger buyers bypass traditional wholesale tiers through winery-direct platforms, compressing distributor margins. This channel rotation is most visible in United States coastal metropolitan markets where regulatory clarity around TTB import standards reduces purchase friction.
Port Wine Market Segmentation
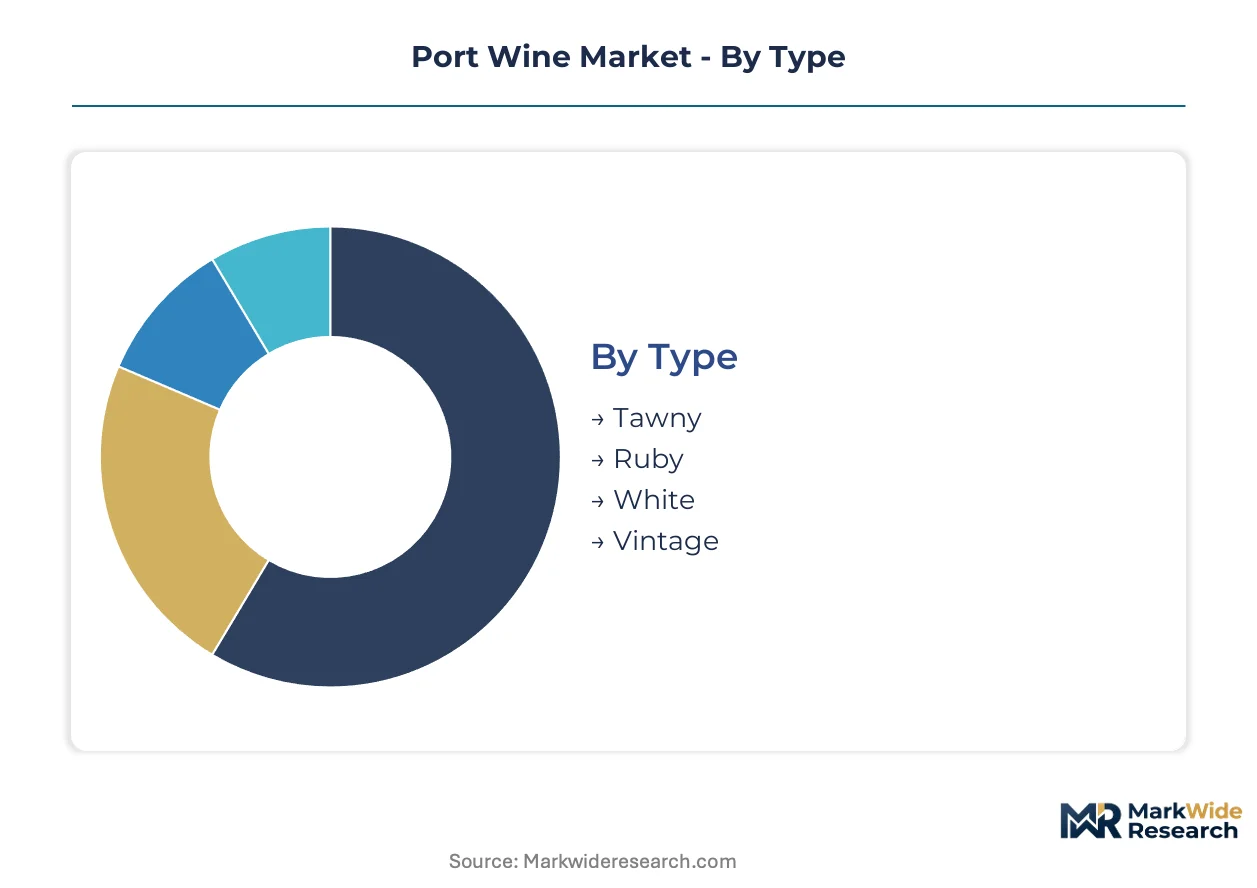
Port Wine segmentation reveals how certification burdens concentrate across product tiers, with aged categories demanding stricter Douro Valley documentation under EU Green Deal traceability mandates. Channel and packaging choices further stratify compliance exposure, shaping where producers allocate working capital.
Type:
Tawny and Vintage releases carry the heaviest certification overhead, requiring decades of barrel-age documentation for EU Geographical Indication verification, while Ruby and White face lighter provenance scrutiny for younger consumption windows.
- Tawny:Aged in wooden casks with gradual oxidation producing amber-brown coloration and nutty flavor development. Portugal's luxury hospitality channel in Lisbon and Porto absorbs the majority of 10-, 20-, and 40-year indications, though inventory carrying costs strain smaller houses without diversified revenue streams. Tawny sits at the top of the volume ranking, with Vintage climbing the fastest.
- Vintage:Single-year declaration wines from exceptional harvests, bottled after two years and matured for decades in cellars. Auction houses in London and New York command scarcity-driven premiums, while EFSA-mandated blockchain documentation elevates export compliance costs for certified Douro origin.
- Ruby:Young, fruit-forward fortified wines aged briefly in concrete or stainless steel before bottling. Price-sensitive retail segments in Brazil and Portugal favor this accessible entry point.
- White:Produced from white Douro grapes including Malvasia and Viosinho, serving aperitif occasions. Coastal metropolitan markets in the United States show rising curiosity for chilled White Port service.
Ruby commands the largest volume share among younger consumers, while Vintage captures the steepest expansion trajectory in collector channels.
Alcoholic Strength:
Cost tier stratification separates mass-market accessibility from connoisseur-grade scarcity, with Reserve and Late Bottled Vintage occupying the critical margin band between everyday Ruby and trophy Vintage declarations.
- Standard:Entry-level fortified wines at minimum 19.5% ABV, typically non-vintage Ruby blends. Supermarket chains in Portugal and Spain move this volume through promotional pricing.
- Reserve:Extended wood-ageing requirements elevate quality designation above basic Ruby. Specialty Stores in Germany and the United Kingdom anchor discovery for this mid-tier expression.
- Late Bottled Vintage:Single-year wines aged four to six years in cask before bottling, ready for immediate consumption. United States TTB label clarity reduces education friction for millennial buyers seeking Vintage character without cellaring commitment. Late Bottled Vintage sits at the top of the volume ranking, with Crusted gaining share fastest.
- Crusted:Unfiltered blend of multiple vintages, bottled with sediment for decanting ritual. Traditionalist consumers in British and Japanese markets prize this niche category.
Reserve dominates middle-market procurement, while Crusted expands most quickly among experiential retail curators.
Distribution Channel:
Customer-type fragmentation privileges direct relationships over wholesale intermediation, with younger demographics bypassing traditional tiers through winery-direct platforms.
- Online Retail:Direct-to-consumer platforms enabling access to limited quinta bottlings without intermediary markup. Coastal metropolitan United States markets show strongest traction among wine-curious millennials. Online Retail sits at the top of the volume ranking, with Specialty Stores climbing the fastest.
- Supermarkets:Mass-market Ruby and younger Tawny placements through centralized procurement. Price competition from Sherry and Madeira constrains premium positioning.
- Specialty Stores:Staff-guided discovery and education for higher-alcohol-strength expressions. Sommelier relationships in Paris, London, and New York drive aged Tawny by-the-glass conversion.
- Wholesale:Traditional three-tier distribution to restaurants and hotels, now compressing margins as direct channels expand. Portugal's Vila Nova de Gaia lodge tourism reduces dependency for established houses.
Wholesale retains institutional hospitality volume, while Online Retail shows the steepest expansion trajectory among demographic shifts.
Packaging Type:
Supply concentration in glass bottle production aligns with premium positioning, though alternative formats test price-sensitive penetration.
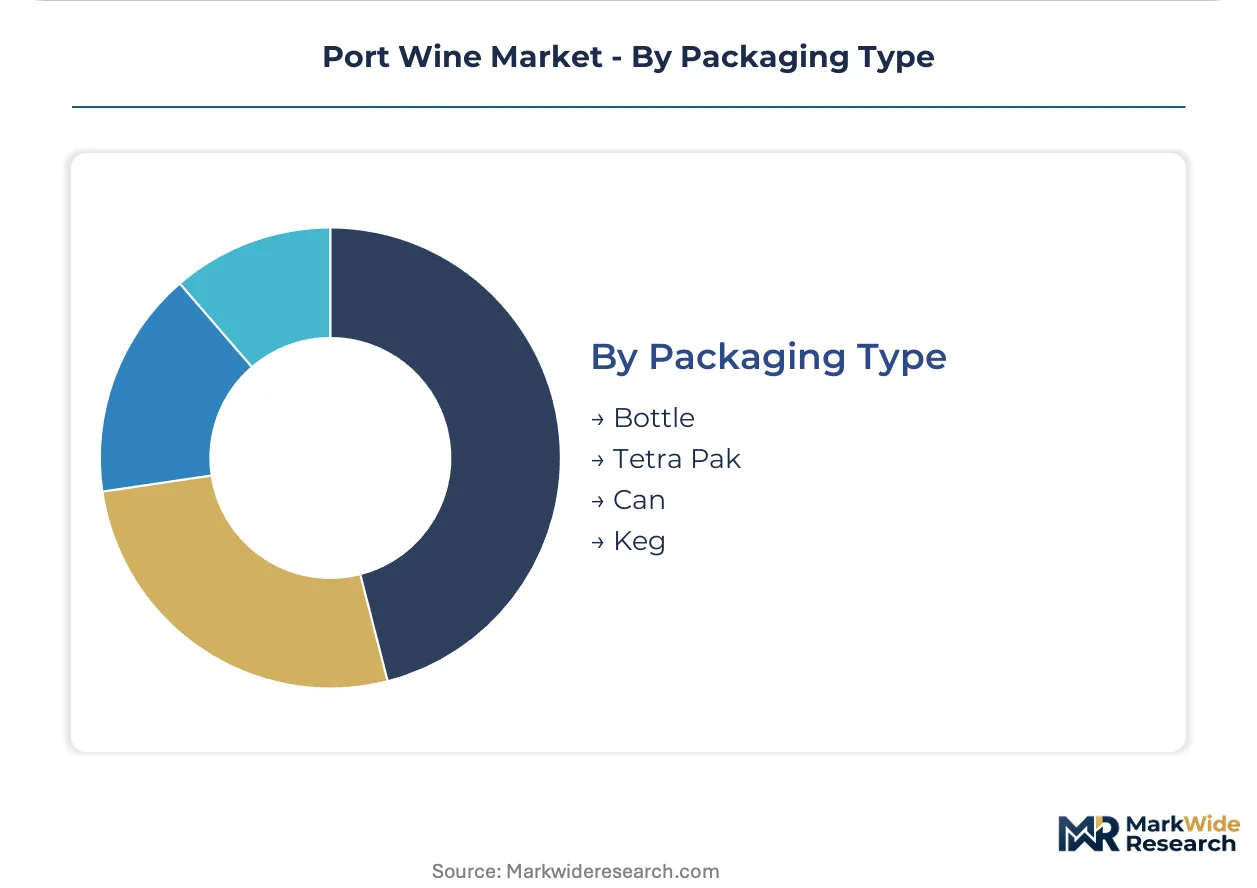
- Bottle:Standard 750ml glass with traditional cork closure, mandatory for Vintage and aged Tawny indications. REACH compliance elevates testing costs for European export economics. Bottle sits at the top of the volume ranking, with Keg climbing the fastest.
- Tetra Pak:Aseptic cartons for entry-level Ruby in Brazilian and Portuguese retail. Cost efficiency competes with perception barriers in mature markets.
- Can:Emerging single-serve format targeting outdoor consumption occasions. Regulatory clarity remains uneven across United States state-level distribution laws.
- Keg:On-premise dispensing for Tawny by-the-glass programs in high-volume hospitality. Lisbon and Porto wine bars drive adoption for reduced waste and portion consistency.
Tetra Pak captures value-tier volume, while Keg expands most quickly in premium hospitality channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portuguese viticultural talent concentrates in the Douro Superior, where generational expertise in schist-terroir management anchors production quality. This workforce distribution shapes competitive positioning across key export markets.
United States
Coastal metropolitan wine bars in New York and San Francisco drive aged Tawny by-the-glass absorption. TTB label clarity requirements reduce consumer education friction for Douro-certified imports. Millennial buyers in California bypass wholesale tiers through direct-to-consumer platforms.
Portugal
Lisbon and Porto luxury hospitality channels absorb the majority of 10-, 20-, and 40-year Tawny indications. EFSA-mandated blockchain documentation elevates compliance overhead for Vila Nova de Gaia lodge operations. Quintas in the Douro Superior control mature vineyard holdings.
United Kingdom
London auction houses command scarcity-driven premiums for Vintage Port declarations. REACH compliance elevates testing costs for bottle materials and labeling substrates. Specialty retailers in Mayfair anchor discovery for higher-alcohol-strength Reserve expressions.
Brazil
Price-sensitive retail segments in São Paulo favor accessible Ruby entry points. Tetra Pak formats compete with perception barriers in supermarket chains. Portuguese diaspora communities sustain traditional consumption patterns.
France
Paris sommelier relationships drive aged Tawny conversion in luxury restaurant groups. EU Green Deal Geographical Indication enforcement tightens provenance verification for Douro Valley documentation. Specialty stores in Île-de-France educate consumers on foot-treading differentiation.
Port Wine Market Competitive Environment
The competitive structure tilts toward vertically integrated quintas with captive vineyard holdings. Established Portuguese houses dominate aged stock inventory while smaller producers compete on niche colheita releases. Two strategic archetypes prevail: Douro Superior landowners controlling upstream supply and Vila Nova de Gaia lodge operators commanding hospitality tourism. Capacity expansion through vineyard acquisition and direct-channel infrastructure represent the dominant competitive moves.
Within the integrated-quinta tier, Symington Family Estates Vinhos S.A. and Niepoort Vinhos S.A. exemplify divergent positioning strategies. The Fladgate Partnership occupies a position emphasizing luxury hospitality infrastructure. These Portuguese S.A.-structured entities anchor the competitive landscape through documented Douro Valley lineage and certified provenance systems.
| Leading Market Players |
|---|
| Kopke Group |
| Niepoort Vinhos S.A. |
| Symington Family Estates Vinhos S.A. |
| Ramos Pinto |
| Quinta do Crasto SA |
| Sogrape SGPS SA |
| Quinta do Noval |
| Fonseca Port Wine |
| The Fladgate Partnership |
| Others |
Value Chain & Pricing Dynamics
Luxury hospitality procurement groups in Portugal and the United States anchor volume absorption for aged Tawny and Vintage releases, creating tiered pricing power for certified Douro quintas with documented vineyard lineage. This buyer concentration enables premium markups for blockchain-verified provenance while compressing margins for non-certified entrants.
Pricing Analysis
Age-statement bundling separates 10-, 20-, and 40-year Tawny tiers from non-vintage Ruby entry points. Price differentiation rests on EFSA-mandated Geographical Indication certification grade and barrel-age documentation depth. Cost compression in younger Ruby segments intensifies because Tetra Pak formats compete with fortified wine substitutes from Jerez. Brazilian supermarket buyers show highest price sensitivity, while London auction houses demonstrate least sensitivity for single-year Vintage declarations.
Supply Chain Analysis
Single-source vulnerability sits with Douro Superior schist-terroir vineyard holdings concentrated in Portugal. Raw material dependencies center on Touriga Nacional and Touriga Franca grape varieties, neutral grape spirit for fortification, and French oak cask cooperage. Supply chain risk stems from viticultural talent scarcity among aging Douro Valley workforces. Distribution runs through Vila Nova de Gaia lodge infrastructure for hospitality tourism conversion, supplemented by direct-to-consumer platforms bypassing wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Port Wine operates as a geographic-arbitrage play where EU Green Deal compliance costs in European markets contrast with TTB label clarity advantages in the United States, creating divergent margin structures across Atlantic export corridors.
For Market Incumbents: Cement backward integration into Douro Superior vineyard acreage to secure grape supply against quinta concentration. Fortify lodge tourism infrastructure in Vila Nova de Gaia to reduce wholesale channel dependency. EFSA blockchain documentation requirements threaten smaller competitors without dedicated regulatory staff. For New Entrants and Emerging Players: The mid-tier price-point gap between entry-level Ruby and trophy Vintage declarations offers white-space targeting. Late Bottled Vintage captures millennial buyers seeking Vintage character without cellaring commitment. United States coastal metropolitan markets present the most penetrable geography. Foot-treading method differentiation supplies narrative premium for experiential retail positioning. For Investors and Strategic Acquirers: Luxury hospitality groups are the most active acquirer in this space, seeking vertical control over aged stock inventory. Long-term viability centers on certified Douro provenance systems with documented vineyard traceability. Watch EFSA enforcement intensity as inflection indicator for compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Vineyard Acquisition | Captive supply of Touriga Nacional from Douro Superior schist terraces secures quality consistency. |
| Lodge Tourism Expansion | Vila Nova de Gaia cellar-door experiences convert visitors to high-margin direct purchasers. |
| Blockchain Documentation | EFSA-mandated traceability systems reinforce scarcity value for certified Douro origin. |
| Direct-to-Consumer Platform Launch | Winery-direct sales bypass wholesale tiers and compress distributor margins. |
| Foot-Treading Method Certification | Traditional lagar fermentation techniques command narrative premiums in experiential retail. |
Study Parameters
Bottom-up hospitality channel modeling reconciled against top-down vineyard holding tracking forms the analytical core. Primary interviews with quinta viticulturists, Vila Nova de Gaia lodge operators, Portuguese regulatory affairs specialists, and United States TTB import compliance officers combined with secondary validation from IVDP production statistics, EFSA Geographical Indication registries, and United States customs import records. Triangulation across supply-side acreage data and demand-side channel absorption patterns ensures coherence.
Historical trendline analysis of aged stock releases and vintage declaration frequency informs projection mechanics across the analysis window. Segmentation dimensions modeled include Port type, alcoholic strength tier, distribution channel, and packaging format. CAGRs derive from vintage-year production volumes correlated with channel-specific price realization data. Forecast inputs incorporate schist-terroir yield variability and EFSA enforcement intensity trajectories.
Caveats apply where EU Green Deal regulatory expansion or TTB label requirement modifications could materially shift the outlook. Forecasts reflect assumptions about viticultural talent pipeline sustainability and luxury hospitality channel consolidation continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Home Brew Boiler Market
Alcoholic Beverages
South America Fermented Drinks Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Pub Cellar Equipment Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Sake Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Smart Wine Cellar Market