
 Global Craft Vodka Market | 2026-2036
Global Craft Vodka Market Size, Share, and Industry Trends Forecast 2026-2036
Global Craft Vodka Market Foresight
Subscription-based tasting clubs and membership-driven allocation models are restructuring how craft vodka reaches consumers beyond traditional wholesale channels. Tito's Handmade Vodka leverages its Texas production base to anchor domestic supply chain efficiency. St. George Spirits differentiates through pot still specialization and botanical innovation. Diageo Plc competes by extending its premium portfolio into craft-adjacent positioning through controlled distribution.
Craft vodka denotes small-batch spirit distilled from fermented grains or potatoes, typically below defined annual production thresholds, with emphasis on terroir-specific ingredients and artisanal filtration methods. The product serves both mixology-forward hospitality venues and direct-to-consumer connoisseur channels seeking provenance transparency. Flavored vodka occupies the largest volume position, though organic vodka commands superior margin pools due to certified ingredient sourcing and limited supply. Ultra-premium vodka is concentrating fastest among high-income professionals, while plain vodka retains mature, price-sensitive demand through specialty liquor stores.
The FDA and TTB govern labeling, proof standards, and health claims for US craft vodka, while the EU's Spirits Regulation and EFSA guidelines shape export compliance for European entrants. REACH chemical safety protocols affect flavoring additive approvals across European distribution channels. Stakeholders must monitor evolving organic certification requirements and craft designation thresholds as regulatory bodies tighten authenticity definitions.
Market Dynamics
Subscription-based allocation models and membership-driven tasting clubs are restructuring distribution economics, pulling craft vodka away from wholesale dependency toward direct consumer relationships. This channel migration alters margin capture, inventory velocity, and brand control simultaneously.
Growth Catalysts
- TTB Labeling Modernization:Streamlined approval pathways for experimental flavor profiles accelerate product pipeline velocity for US craft distillers.
- Premium Cocktail Bar Expansion:Mixology-forward venues in Austin, Los Angeles, and Brooklyn anchor volume placement for small-batch producers seeking provenance credibility.
- Pot Still Specialization:Artisanal copper still configurations enable terroir-specific botanical extraction that column stills cannot replicate.
Market Restraints
- Organic Grain Input Volatility:Certified organic wheat and potato sourcing concentrates in the Great Plains, exposing margins to climate-driven yield fluctuations.
- REACH Flavoring Additive Friction:European chemical safety protocols delay approval timelines for novel botanical infusions targeting export markets.
- Neutral Spirit Substitution:Mass-market vodka brands with scale economies erode craft positioning through private-label sourcing at hospitality accounts.
Strategic Opportunities
- Direct-to-Consumer Channel Maturation:State-level shipping law liberalization in Texas and California enables allocation models bypassing three-tier distribution.
- EU Organic Certification Tailwind:EFSA-aligned craft designation thresholds create premium shelf positioning for certified US exporters in Berlin and Amsterdam.
- Botanical-Grain Convergence:Hybrid fermentation protocols combining heritage grains with foraged botanicals open gin-adjacent category positioning.
Industry Challenges
- Master Distiller Talent Scarcity:Artisanal fermentation expertise and sensory evaluation skills command premium compensation in Texas and California clusters.
- TTB Formula Approval Timelines:Experimental product development cycles face 90-120 day federal review windows for non-standard ingredient declarations.
- Legacy Equipment Integration:Automated bottling lines require retrofitting to accommodate small-batch viscosity variations without compromising throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Craft Vodka Market |
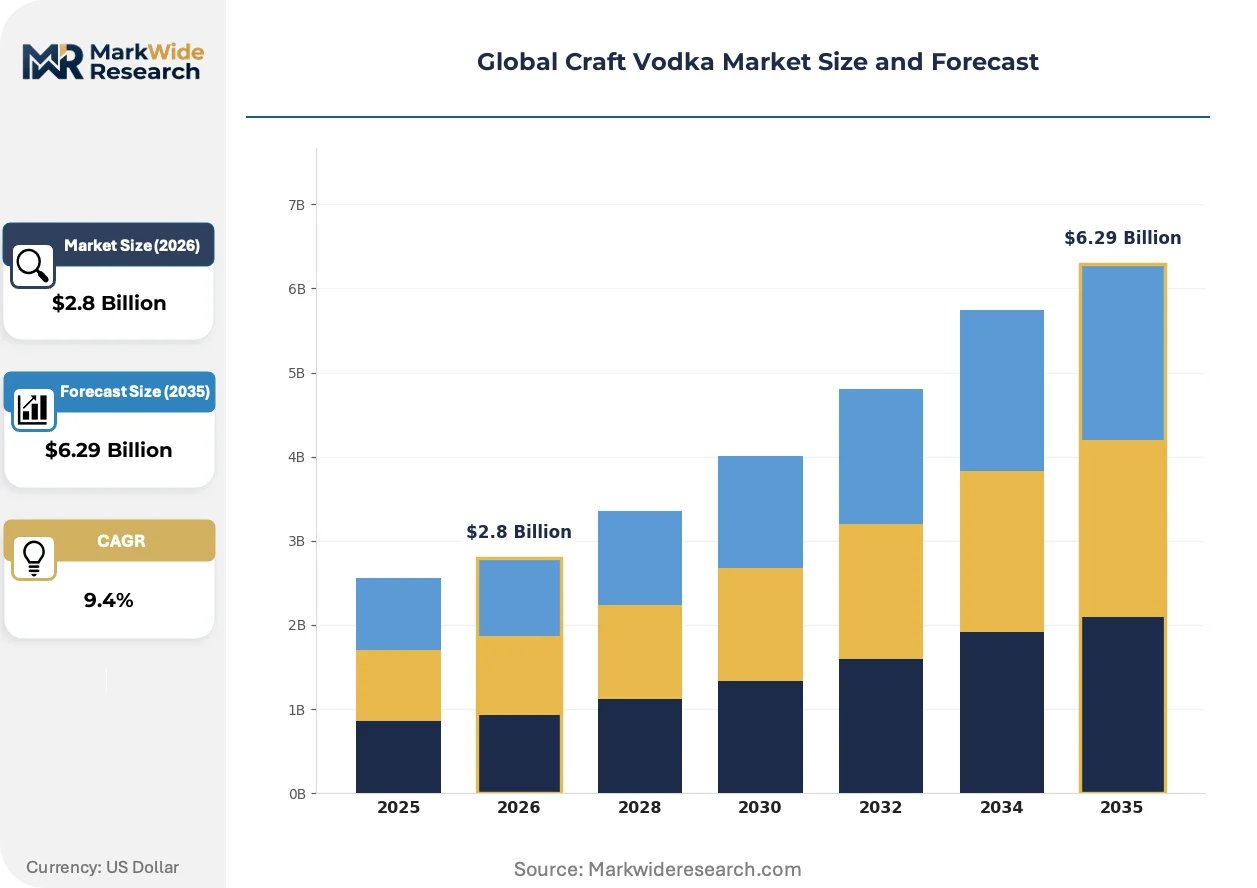
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored Vodka, Plain Vodka, Organic Vodka, Ultra-Premium Vodka, Limited Edition Production Method: Pot Still Distillation, Column Still Distillation, Continuous Distillation, Batch Brewing, Cold Filtration Distribution Channel: Specialty Liquor Stores, Bars & Nightclubs, Online Retailers, Premium Restaurants, Event Catering Consumer Segment: Millennials, High-Income Professionals, Cocktail Enthusiasts, Connoisseurs, Festival Attendees |
| Companies Covered | Diageo Plc, Pernod Ricard SA, William Grant and Sons Ltd, Beam Suntory Inc., Sazerac Co., Tito's Handmade Vodka, Heaven Hill Brands, Bacardi Limited, St. George Spirits, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Craft Vodka Market Shifts & Advancements
Carbon filtration methods and terroir-specific water sourcing are redefining quality differentiation, while regulatory bodies tighten authenticity thresholds. These forces compress traditional production timelines and reward transparent provenance documentation.
Activated carbon and bone char filtration systems are overtaking traditional sand and gravel methods in small-batch production. Premium hospitality venues in Manhattan and San Francisco specify filtration transparency on cocktail menus. This specification pressure is compressing market share for producers relying on undisclosed industrial filtration inputs.
REACH chemical safety protocols and EFSA flavoring guidelines are tightening additive approval pathways for European export-bound products. US craft distillers reformulate botanical blends to preempt compliance failures in German and Dutch distribution. The reformulation burden falls heaviest on flavored vodka portfolios targeting cross-border hospitality placement.
Allocation-based membership programs are displacing traditional wholesale dependency for established craft brands. High-income connoisseurs in Austin and Los Angeles subscribe to quarterly releases with guaranteed access. This channel rotation is most visible in Texas, where state law permits limited direct shipment from bonded distillery premises.
Global Craft Vodka Market Segmentation
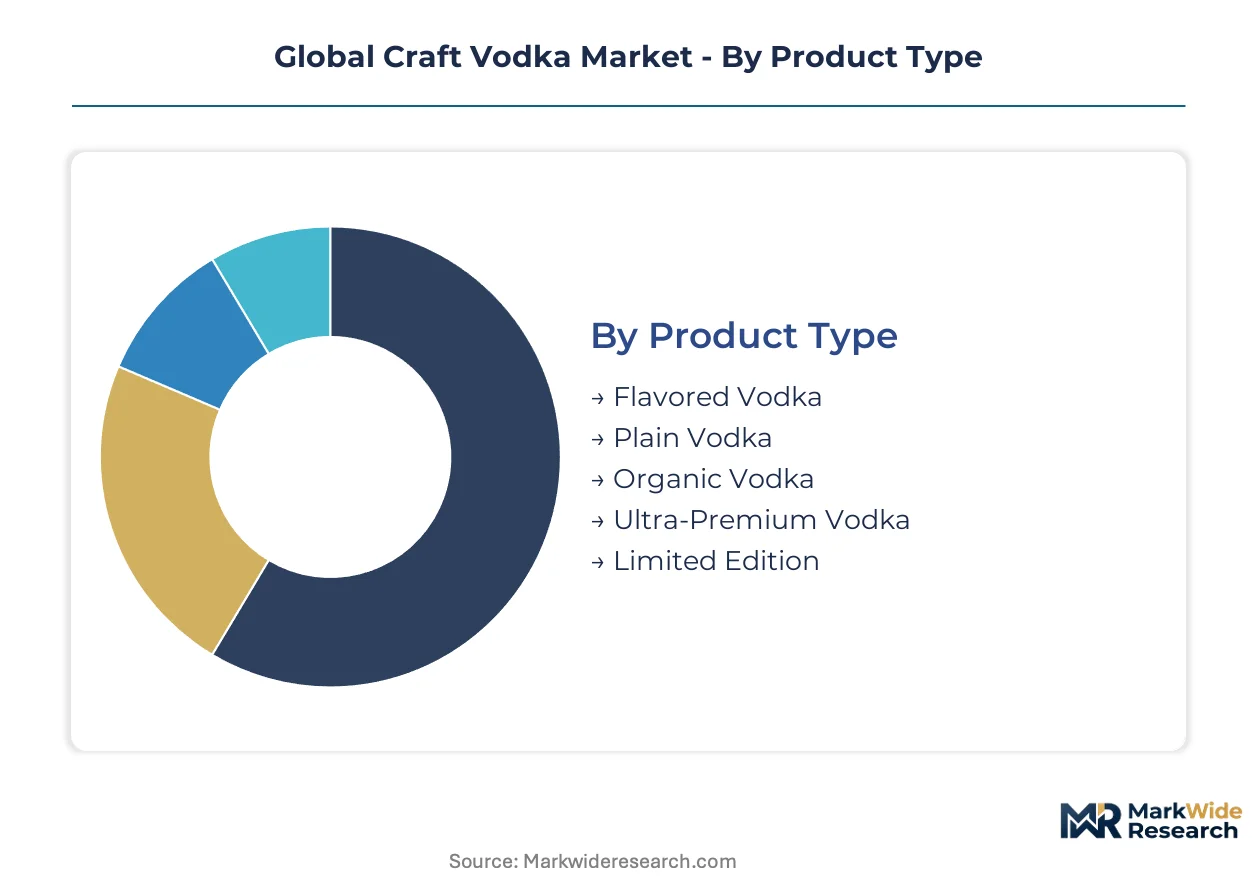
Craft vodka segmentation reveals how capital deployment, regulatory exposure, and channel economics fragment the competitive landscape. Distinct production thresholds and certification requirements create tiered investment profiles that shape producer strategy across each dimension.
Product Type:
Capital intensity varies sharply across product tiers, with certification and aging infrastructure demanding differential upfront commitment.
- Flavored Vodka:Botanical infusion and post-distillation compounding require dedicated blending vessels and TTB formula approval cycles. Demand concentrates in Brooklyn and Austin mixology venues where cocktail menu differentiation drives placement. Flavor innovation cycles compress margin recovery timelines.
- Organic Vodka:USDA certification and certified organic grain sourcing impose traceability infrastructure and multi-year field conversion costs. High-income professionals in California and Texas pay provenance premiums that sustain superior margin pools despite input volatility.
- Plain Vodka:Minimal processing overhead enables entry-level craft positioning with neutral spirit neutrality.
- Ultra-Premium Vodka:Extended filtration protocols and limited batch releases demand artisanal labor concentration.
- Limited Edition:Seasonal allocation models require flexible production scheduling and membership platform investment.
Most installed capacity flows through Flavored Vodka. Expansion is steepest in Organic Vodka.
Production Method:
Equipment selection locks producers into fixed cost structures and botanical extraction capabilities that define competitive positioning.
- Pot Still Distillation:Copper still configurations enable terroir-specific botanical concentration impossible in continuous systems. Artisanal producers in Scotland and the Czech Republic command hospitality premiums for provenance documentation. Batch throughput constraints limit scale economies.
- Column Still Distillation:Continuous rectification delivers neutral spirit efficiency at volume thresholds that disqualify craft designation. Mass-market producers leverage this method to erode craft positioning through price undercutting at Texas hospitality accounts.
- Continuous Distillation:Automated feedstock processing minimizes labor overhead for high-volume neutral spirit output.
- Batch Brewing:Fermentation tank scheduling flexibility accommodates heritage grain variability and seasonal ingredient windows.
- Cold Filtration:Sub-zero temperature processing removes congeners without activated carbon contact, preserving mouthfeel complexity.
Pot Still Distillation commands the highest per-liter capital investment. Cold Filtration is gaining share fastest among premium hospitality specifications.
Distribution Channel:
Channel selection determines margin capture, inventory velocity, and regulatory compliance burden simultaneously.
- Specialty Liquor Stores:Curated shelf placement and staff education investments build connoisseur loyalty in California and Texas markets. Three-tier distribution requirements compress net margins through wholesaler markups. Tasting event programming drives trial conversion.
- Bars & Nightclubs:Well-placement contracts and cocktail menu integration anchor volume throughput for emerging brands. Austin and Los Angeles venues specify filtration transparency that favors documented craft producers.
- Online Retailers:State shipping law fragmentation creates compliance complexity that favors established brands with legal infrastructure.
- Premium Restaurants:Sommelier-driven placement rewards provenance storytelling and food-pairing versatility.
- Event Catering:Festival and wedding volume spikes demand flexible logistics and temporary permitting expertise.
Specialty Liquor Stores currently move the highest absolute volume. Online Retailers are expanding most quickly following state-level shipping liberalization.
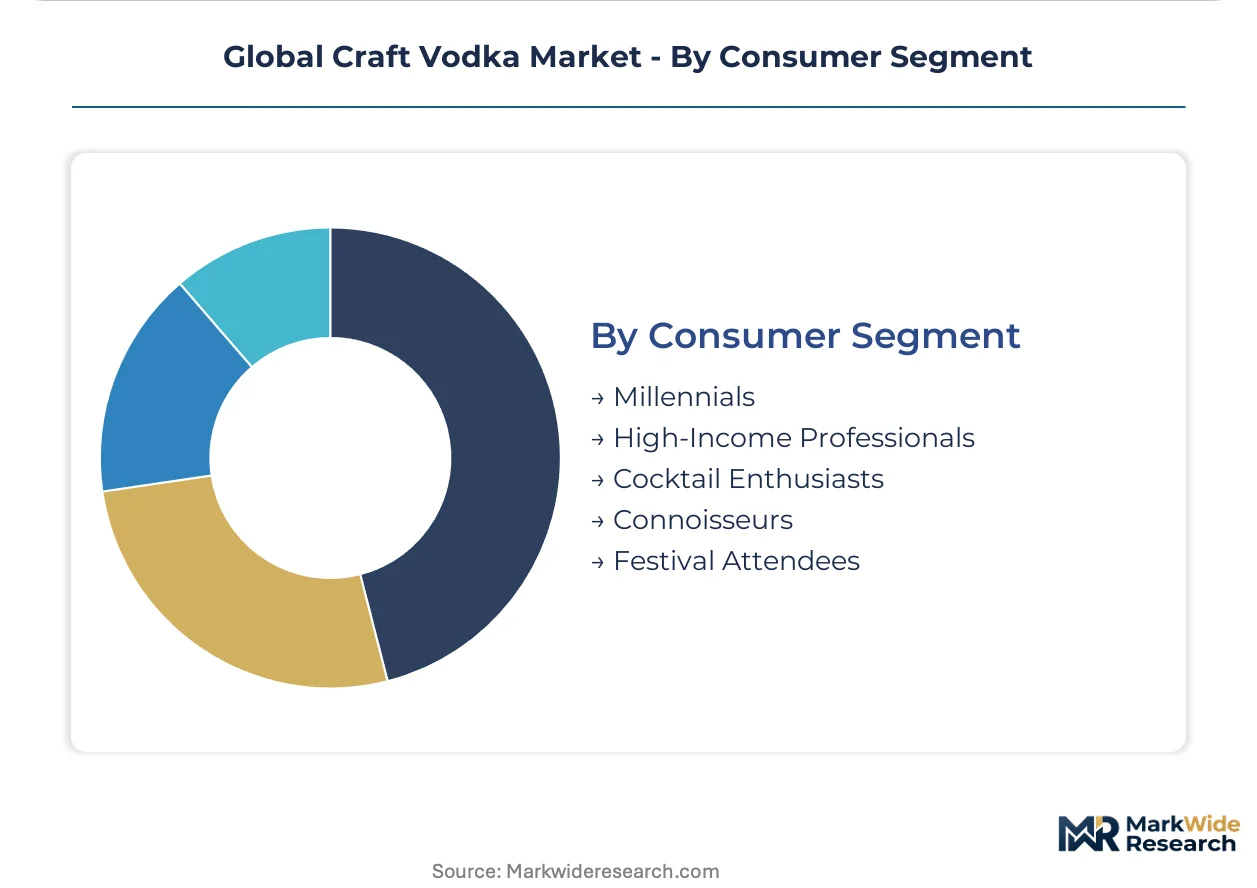
Consumer Segment:
Demographic targeting shapes product formulation, packaging investment, and communication channel allocation.
- Millennials:Digital-native discovery patterns and values-aligned purchasing reward transparent sourcing documentation and social media engagement. Subscription allocation models in Texas and California convert this cohort through exclusivity signaling.
- High-Income Professionals:Price-agnostic quality seeking supports ultra-premium positioning and limited release access programs. Manhattan and San Francisco concentrations anchor margin-rich volume.
- Cocktail Enthusiasts:Mixology skill investment drives ingredient specification awareness and brand advocacy in hospitality settings.
- Connoisseurs:Sensory evaluation expertise demands detailed production methodology disclosure and vertical tasting formats.
- Festival Attendees:Experiential consumption occasions favor portable formats and on-premise activation sampling.
High-Income Professionals generate the highest per-capita revenue. Millennials are gaining share fastest through direct-to-consumer channel migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and California dominate US craft vodka density, while Germany and the Netherlands anchor European export compliance infrastructure. Distinct regulatory environments and hospitality channel maturation create divergent growth trajectories across these markets.
United States
Texas and California concentrate craft distillery licensing, with Austin and Los Angeles anchoring mixology-forward demand. The TTB governs formula approvals and labeling standards, creating 90-120 day review windows for experimental products. State-level shipping law liberalization in Texas enables direct-to-consumer allocation models that bypass three-tier distribution markups.
Germany
Berlin and Amsterdam hospitality venues drive premium placement for certified organic US exporters. The EU Spirits Regulation and EFSA guidelines shape additive approval pathways, forcing reformulation of botanical blends before market entry. REACH chemical safety protocols delay novel flavor infusions targeting German distribution channels.
Netherlands
Amsterdam's cocktail bar density and re-export hub status attract craft vodka seeking EU market access. Dutch food safety authorities enforce EFSA-aligned craft designation thresholds that create premium shelf positioning. Rotterdam logistics clusters facilitate bonded warehousing for American producers awaiting German and French retail authorization.
United Kingdom
London's premium hospitality sector specifies filtration transparency on cocktail menus, compressing share for undisclosed industrial methods. The UK Food Standards Agency applies retained EU spirits regulations post-Brexit, maintaining alignment with EFSA flavoring guidelines. Scottish pot still expertise influences English craft distiller equipment procurement decisions.
France
Parisian mixology venues reward provenance storytelling and terroir-specific production documentation. ANSM and DGCCRF enforcement of EU additive regulations creates compliance friction for flavored vodka portfolios. The Île-de-France region concentrates sommelier-driven placement that favors heritage grain and botanical convergence products.
Global Craft Vodka Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with small-batch distillers commanding hospitality premiums while scale producers erode positioning through private-label sourcing. The vendor base organizes around three strategic archetypes: terroir-focused artisanal producers, premium portfolio extenders from multinational spirits groups, and regional contract distillers serving white-label demand. Consolidation pressure concentrates among mid-tier players lacking direct-to-consumer infrastructure or organic certification. Dominant competitive moves include state-level shipping law exploitation for channel bypass and botanical-grain hybrid formulation for gin-adjacent category expansion.
Within the terroir-specialist tier, Tito's Handmade Vodka and St. George Spirits exemplify geographic anchoring and production methodology differentiation respectively. Tito's represents the Texas-production-base archetype that optimizes domestic supply chain efficiency. St. George occupies a position emphasizing pot still specialization and botanical innovation. Among multinational portfolio extenders, Diageo Plc sits within the premium-adjacent positioning archetype, leveraging controlled distribution to compete without full craft authenticity claims. These three patterns illustrate how scale, geography, and equipment choice fragment competitive strategy.
| Leading Market Players |
|---|
| Diageo Plc |
| Pernod Ricard SA |
| William Grant and Sons Ltd |
| Beam Suntory Inc. |
| Sazerac Co. |
| Tito's Handmade Vodka |
| Heaven Hill Brands |
| Bacardi Limited |
| St. George Spirits |
| Others |
Supply & Pricing Matrix
Family-owned craft distilleries in Texas and California anchor supply-side discipline through multi-generational grain sourcing relationships and bonded warehouse ownership, insulating premium pricing from commodity volatility while constraining volume expansion capital.
Pricing Analysis
Capacity additions in Texas are reshaping price floors for organic vodka as heritage grain acreage expands. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and filtration transparency. Cost compression in flavored vodka stems from neutral spirit substitution at hospitality accounts. Cocktail enthusiasts show highest price sensitivity, while high-income professionals absorb ultra-premium markups without volume elasticity.
Supply Chain Analysis
Dual-sourcing requirements from TTB-licensed bonded warehouses mandate multi-supplier qualification for organic grain inputs. Sourcing concentrates in the United States, Canada, and France for certified wheat and heritage potato varieties. Supply chains hinge on climate-driven yield volatility in the Great Plains. Tariff exposure on European-bound flavored vodka creates margin compression. Distribution runs through three-tier wholesale networks with direct-to-consumer bypass emerging in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
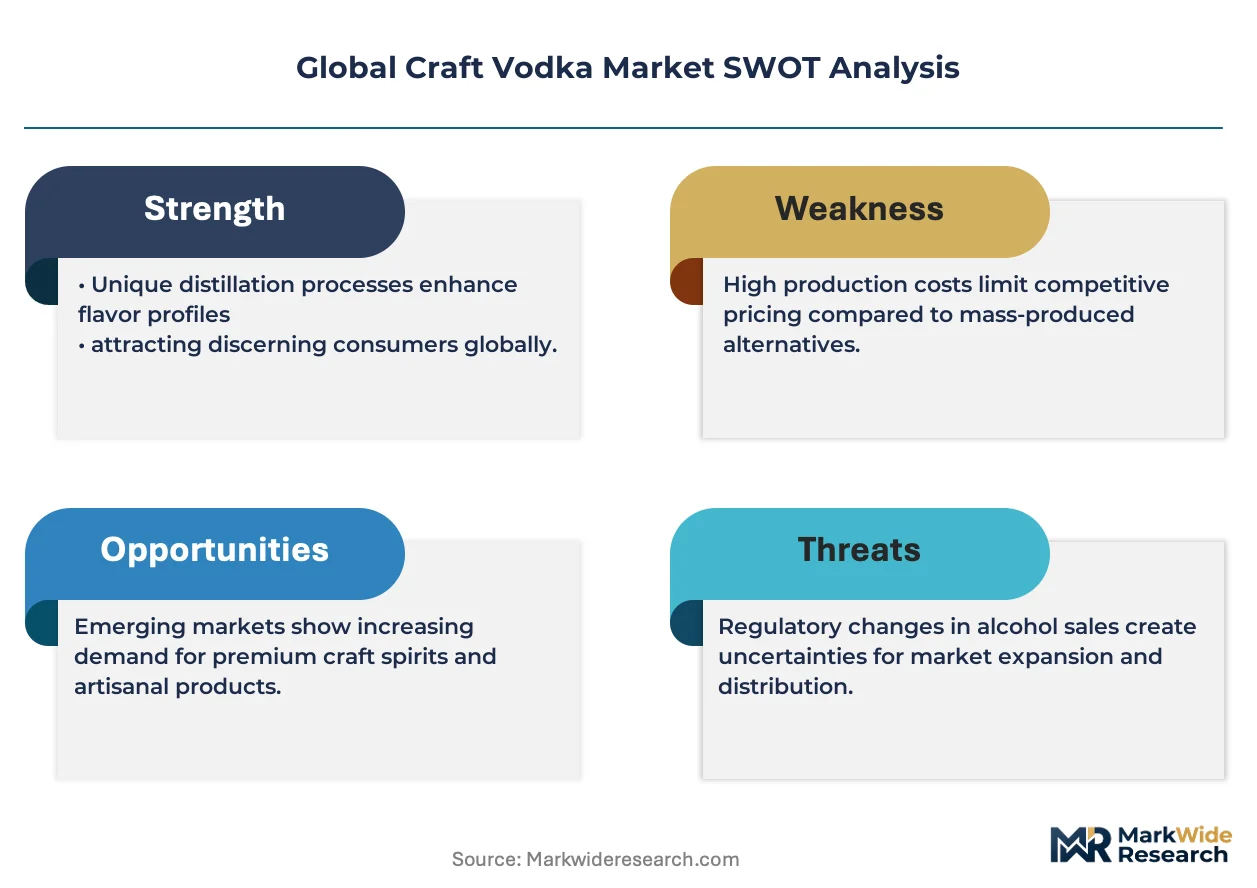
This market functions as a geographic-arbitrage play between Texas shipping-law liberalization and EU organic certification premiums, exploiting regulatory divergence for margin capture.
For Market Incumbents: Acquire direct-to-consumer membership platform infrastructure to defend against subscription-based allocation models eroding wholesale dependency. Secure backward integration into certified organic grain acreage in the Great Plains to neutralize input volatility. TTB formula approval delays threaten pipeline velocity; preemptive filing strategies accelerate experimental product launches. For New Entrants and Emerging Players: Mixology-forward venues in secondary US cities represent underserved buyer archetypes with lower placement competition than Austin or Brooklyn. Target Berlin and Amsterdam hospitality accounts seeking certified organic US exports with reformulated botanical blends. State-level shipping law exploitation enables channel bypass without wholesaler markup capture. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier craft distilleries lacking organic certification or direct-to-consumer infrastructure. Long-term viability centers on regulatory arbitrage sustainability and terroir documentation authenticity. Watch for EFSA craft designation threshold tightening as inflection indicator for certified exporter premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Texas shipping law liberalization enables margin recovery previously captured by three-tier wholesalers. |
| Organic Certification Investment | USDA and EFSA-aligned thresholds command shelf premiums in Berlin and Amsterdam hospitality venues. |
| Pot Still Capacity Expansion | Copper still configurations extract terroir-specific botanicals impossible in continuous column systems. |
| Botanical-Grain Hybrid Development | Gin-adjacent category positioning opens sommelier-driven placement in Parisian mixology venues. |
| REACH Compliance Pre-certification | Reformulation ahead of German distribution prevents additive approval timeline delays. |
Research Methodology
Bottom-up hospitality venue modeling reconciled against top-down distillery capacity tracking forms the analytical core of this study. Primary interviews with master distillers, TTB compliance officers, specialty liquor store buyers, and mixology program directors combined with secondary validation from FDA distilled spirits standards, TTB labeling filings, EFSA flavoring guidelines, and state-level shipping law databases. Trade flow analysis from customs records and bonded warehouse disclosures anchored supply-side triangulation.
Historical trendline analysis across installed craft distillery capacity and premium hospitality venue expansion established baseline growth parameters. Segmentation modeling covered product type, production method, distribution channel, and consumer demographic dimensions across the projection horizon. CAGRs derived from regression analysis against regulatory event timelines and organic grain acreage forecasts. Climate-driven yield volatility in the Great Plains and REACH approval cycle duration served as key forecast inputs.
Underlying measurement precision varies by segment; organic vodka and ultra-premium tiers carry tighter precision than flavored vodka due to certification documentation density. Forecasts reflect assumptions on state shipping law liberalization velocity and EFSA threshold stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Ice Cream Market
Alcoholic Beverages
Kegs Market
Alcoholic Beverages
Canned Cocktails Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Flavored Whiskey Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Low Alcohol Beverages Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Middle East and Africa Kegs Market
Alcoholic Beverages
Ouzo Market
Alcoholic Beverages
Bottled Craft Beer Market