
 Dark Spirits Market | 2026-2036
Dark Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Dark Spirits Market Intelligence
A clear divergence in aging statements and provenance claims is repositioning the market into distinct premium and mass-market segments. Diageo plc leverages its extensive portfolio of aged Scotch whiskies to capture high-margin opportunities. Pernod Ricard SA differentiates through its focus on craft-style American whiskeys and single-origin rums. Beam Suntory Inc. competes on scale and distribution reach in the high-volume standard whiskey category.
Dark spirits are alcoholic beverages that derive their characteristic color and flavor from aging in wooden casks, typically oak. The maturation process, which can last for many years, imparts complex flavor compounds and a darker hue compared to clear spirits. Whiskey continues to dominate the product type segment, driven by consumer interest in single malts and small-batch bourbons. In terms of packaging, glass bottles remain standard for premium offerings, while cans gain traction for ready-to-drink cocktails using dark spirit bases.
Regulations from bodies like the US FDA on labeling and the EU's EFSA concerning flavor additives define product composition and marketing claims. National standards, such as those set by India's FSSAI, govern import requirements and alcohol content verification, impacting market access. Future brand strategy will hinge on navigating these divergent international regulations for appellation and age statements.
Market Dynamics
The central structural force shaping the dark spirits market is the bifurcation of consumer demand, which simultaneously pulls toward ultra-premium, aged products with verifiable provenance and convenient, accessible ready-to-drink (RTD) formats. This dynamic influences everything from production cycles to channel strategy.
Growth Catalysts
- Premiumization in Emerging Economies:Rising disposable incomes in urban centers within China and India are fueling demand for super-premium aged whiskies and rums, viewed as status symbols and collectible assets.
- Digital Channel Enablement:The deployment of robust online age verification technologies is expanding e-commerce and direct-to-consumer (DTC) sales channels, allowing brands to bypass traditional retail gatekeepers.
- Craft and Small-Batch Appeal:A consumer preference for unique, artisanal products drives interest in small-batch bourbons and single-origin rums, creating growth opportunities for both new and established distillers in on-trade venues.
Market Restraints
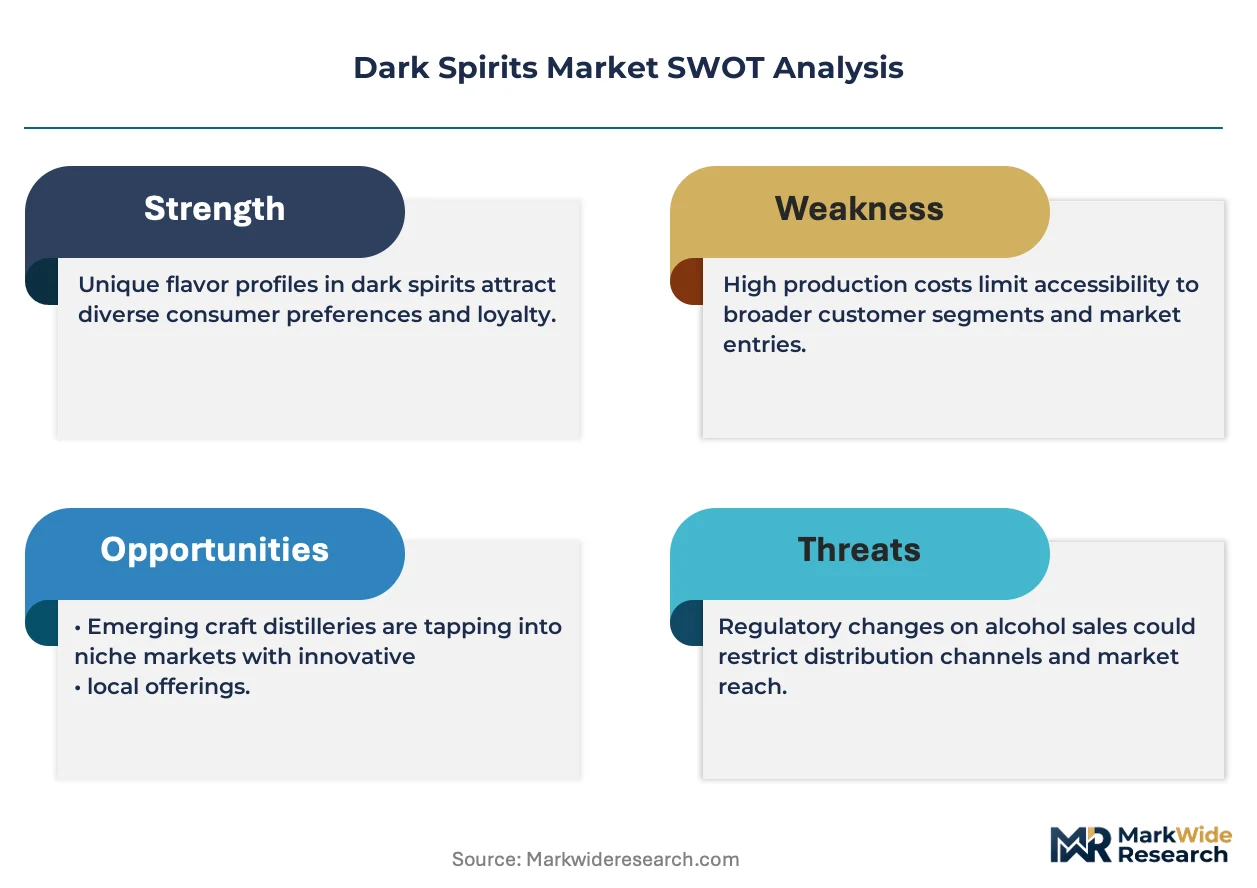
- Divergent International Regulations:Conflicting labeling standards for age statements and definitions of origin between bodies like the US FDA and the EU's EFSA create significant compliance costs and marketing complexity for global brands.
- Input Cost Volatility:The price and availability of critical raw materials, especially high-quality oak for casks and specific grains like malted barley, are subject to climate-related and supply chain pressures.
- Long Maturation Cycles:The multi-year aging process required for premium whiskies, rums, and brandies creates inherent supply inflexibility, making it difficult for producers to respond quickly to sudden shifts in consumer demand.
Strategic Opportunities
- Ready-to-Drink (RTD) Innovation:Developing premium canned cocktails using dark spirit bases like whiskey or rum offers a significant opportunity to enter a high-growth category and attract new consumer demographics.
- Provenance Technology:Implementing blockchain or NFC-enabled tracking on bottles allows brands to offer consumers verifiable proof of origin and age, justifying premium price points and building trust.
- Geographic Expansion:Targeting middle-class consumers in Southeast Asian and Latin American markets, where appreciation for premium dark spirits is growing but market penetration remains relatively low, presents a key growth vector.
Industry Challenges
- Complex Import and Tariff Navigation:Managing a global patchwork of import duties and country-specific compliance standards, such as those mandated by India's FSSAI, creates significant operational friction and cost.
- Capital-Intensive Aging Infrastructure:The substantial investment required to build and maintain temperature-controlled warehouses for cask maturation represents a major financial barrier for new entrants and constrains capacity expansion for incumbents.
- Skilled Labor Scarcity:A persistent shortage of experienced master distillers, master blenders, and coopers with the specialized knowledge to produce and age high-quality spirits poses an operational risk to quality and consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dark Spirits Market |
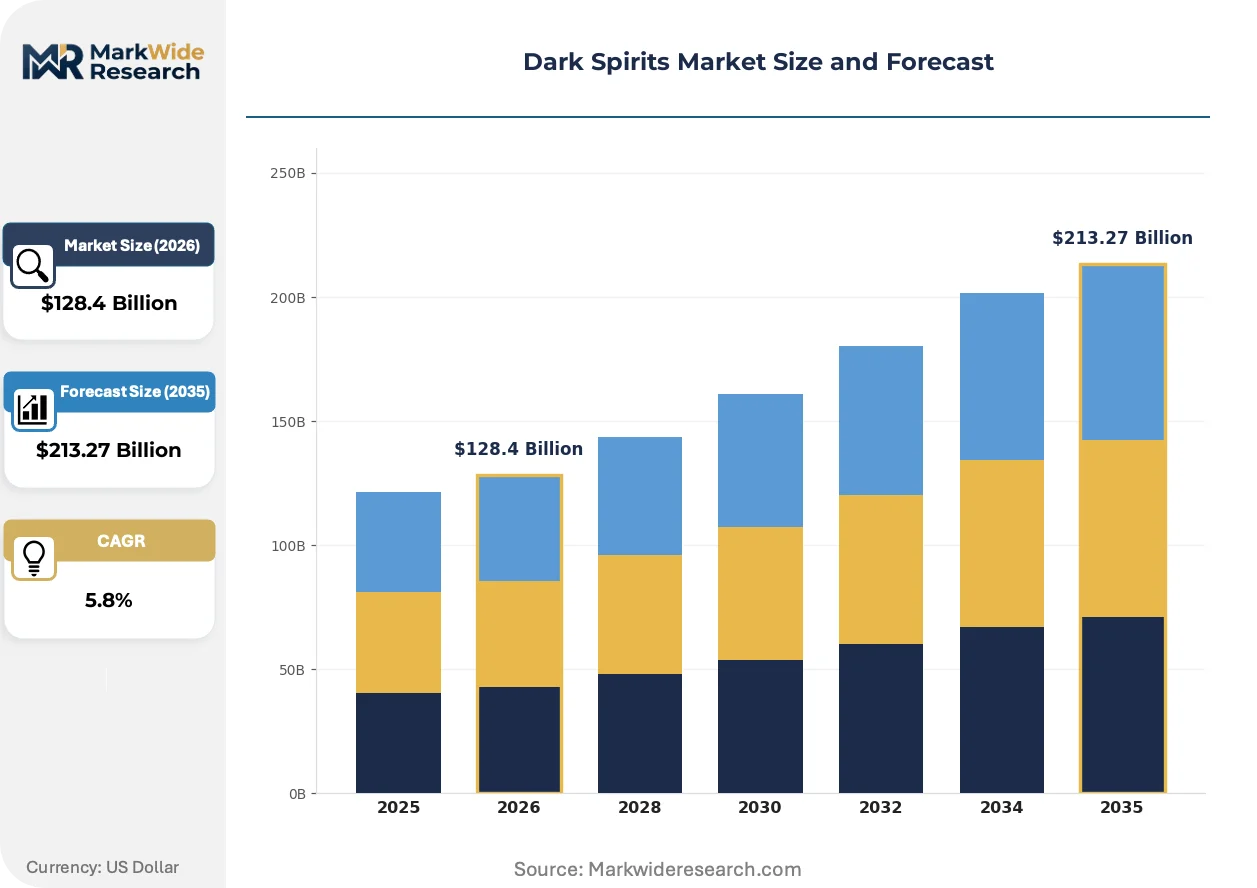
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $213.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whiskey, Rum, Brandy, Vodka Alcohol Content: Low, Medium, High, Super Premium Flavor Profile: Smooth, Spicy, Fruity, Herbal Packaging Type: Bottle, Can, Keg, Tetra Pak |
| Companies Covered | Bacardi Limited, LVMH Moët Hennessy Louis Vuitton SE, Diageo plc, Edrington Group, William Grant & Sons Ltd, Pernod Ricard SA, Beam Suntory Inc, Campari Group, Brown-Forman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dark Spirits Market Strategic Shifts & Innovations
Technological advancements in production and authentication are converging with evolving consumer expectations for transparency. This shift is compelling brands to innovate beyond flavor profiles, focusing on verifiable product history and new digital-first engagement models that redefine the consumer relationship.
Advanced sensory analysis technology, often powered by AI, monitors chemical compounds to predict flavor development during maturation. Major distillers are adopting these systems to maintain product consistency across vast inventories of aging casks. This technology is automating routine quality control, freeing master blenders from repetitive sampling to focus on the final artistry of blending and finishing.
European Union regulations governing Geographical Indications (GIs) for spirits like Scotch Whisky and Cognac continue to tighten, reinforcing their protected status. This creates a powerful brand moat for European producers but poses a challenge for distillers in other regions. American whiskey brands exporting to the EU are most affected, needing to invest in marketing that clearly communicates their unique value proposition, distinct from protected European categories.
A notable behavioral shift is the consumer migration toward direct-to-consumer (DTC) channels for purchasing super-premium spirits. This trend disrupts the traditional three-tier distribution model of producer, wholesaler, and retailer, particularly for limited-edition releases. This direct engagement is most prominent in the US and UK, where enthusiasts join distillery mailing lists and subscription clubs to gain access to exclusive bottlings.
Dark Spirits Market Segmentation
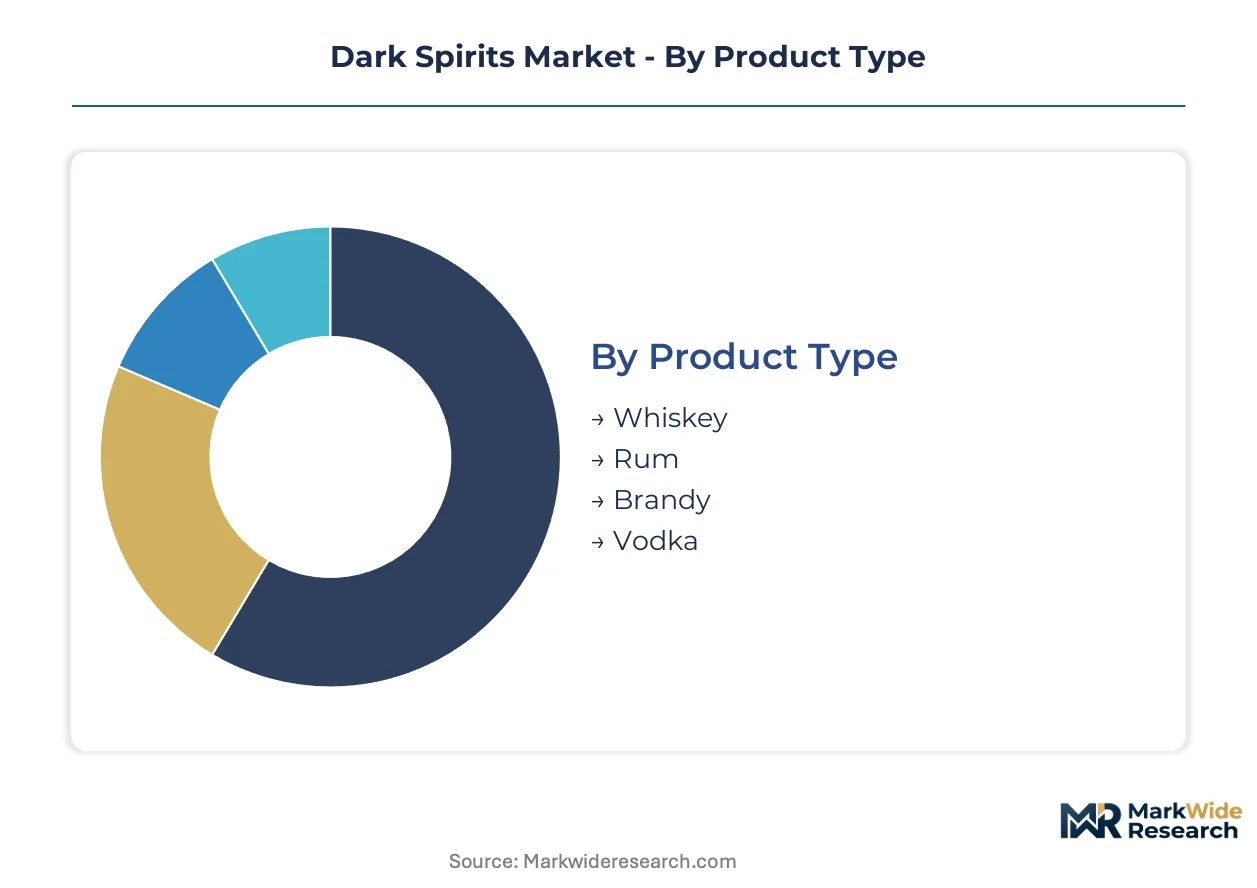
The dark spirits market's segmentation reflects diverse consumer preferences and production methodologies. This granular analysis provides a clear understanding of product variations and their commercial implications. It highlights how distillers tailor offerings to specific demographic and geographic demands.
Product Type:
The customization-vs-standardization spectrum deeply influences the product type segment, distinguishing between highly artisanal creations and mass-market staples.
- Whiskey:This category encompasses spirits distilled from fermented grain mash, aged in wooden barrels, primarily oak, imparting distinct color and flavor. Demand for single malts and small-batch bourbons concentrates in urban centers like Shanghai and Mumbai, driven by their status as collectible assets.
- Rum:Produced by fermenting and distilling sugarcane juice or molasses, rum typically ages in oak barrels, developing a range of flavor profiles. Single-origin rums are gaining traction in on-trade venues across London and New York, appealing to consumers seeking artisanal products.
- Brandy:Distilled from fermented fruit juice, most commonly grapes, brandy undergoes aging in wooden casks, developing complex aromatics.
- Vodka:Traditionally a clear spirit, certain vodka varieties are aged or flavored to mimic dark spirit characteristics, though this is less common.
Most installed capacity flows through Whiskey. Expansion is steepest in Rum.
Alcohol Content:
Cost tiering significantly shapes the alcohol content segment, with higher proof points often commanding premium prices due to production complexity and aging.
- Super Premium:These spirits feature exceptional purity, extended aging, and often limited production, resulting in higher alcohol by volume (ABV) and price points. Consumer demand for super premium dark spirits is robust in affluent markets such as Singapore and Dubai, where status and exclusivity are valued.
- High:Products in this category typically exhibit an ABV above 40%, offering a more intense flavor profile suitable for connoisseurs and cocktail enthusiasts. This segment sees strong sales in established European markets like Germany and France, where traditional consumption patterns prevail.
- Medium:Spirits with moderate alcohol content balance flavor intensity with broader drinkability, often serving as versatile bases for mixed beverages.
- Low:This segment includes spirits with reduced alcohol content, catering to health-conscious consumers seeking lighter options or those in regions with strict alcohol regulations.
The market prioritizes Super Premium for its exclusivity, while Low is gaining traction among health-conscious consumers.
Flavor Profile:
The application of dark spirits, whether neat, on the rocks, or in cocktails, directly influences the prominence of specific flavor profiles.
- Smooth:Characterized by a mellow, easy-drinking quality with minimal harshness, often achieved through extensive filtration or specific aging processes. This profile is widely preferred in emerging Asian markets, including Vietnam and Thailand, for its accessibility.
- Spicy:These spirits present notes of cinnamon, clove, pepper, or ginger, derived from barrel charring or specific botanical infusions. Spicy dark spirits find strong appeal in colder climates, such as Canada and Russia, where warming flavors are sought after.
- Fruity:Exhibiting flavors reminiscent of dried fruits, berries, or citrus, often a result of the base ingredients or cask finishing.
- Herbal:Defined by botanical notes like anise, mint, or licorice, typically from specific distillation techniques or added ingredients.
Consumer preferences are shifting towards Smooth in Southeast Asian markets, whereas Spicy maintains its appeal in traditional Western markets.
Packaging Type:
Volume requirements and customer types dictate the evolution of packaging types, from individual serving formats to bulk distribution.
- Bottle:The traditional and primary packaging for dark spirits, offering product integrity, aesthetic appeal, and suitability for long-term aging and premium presentation. Premium glass bottles remain standard for super-premium offerings sold in retail and on-trade channels globally.
- Can:This format is gaining significant traction for ready-to-drink (RTD) cocktails that utilize dark spirit bases, offering convenience and portability. Demand for canned dark spirit cocktails is accelerating in the US and Australia, driven by outdoor consumption trends.
- Keg:Larger format packaging primarily used in on-trade establishments for high-volume service of certain dark spirits or pre-mixed cocktails.
- Tetra Pak:A lightweight, often more economical packaging option, though less common for premium dark spirits, sometimes used for lower-tier or travel-friendly products.
The primary distribution channel for Bottle remains traditional retail, while Can facilitates new consumption occasions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global dark spirits market sees significant talent concentration in regions with long-standing distillation traditions. Master blenders and distillers, often with generations of expertise, anchor production capabilities across key geographies. This specialized workforce drives innovation and maintains product quality.
China
Rising disposable incomes in urban centers drive demand for super-premium aged whiskies. China's GB standards influence import requirements and product specifications for distillers. Major urban centers like Shanghai and Beijing concentrate high-net-worth individuals, fueling luxury dark spirits consumption.
India
Consumer interest in super-premium aged whiskies and rums is expanding across India's growing middle class. The FSSAI sets national standards for import requirements and alcohol content verification. Urban hubs such as Mumbai and Delhi represent significant markets for collectible dark spirits.
United States
A strong preference for unique, artisanal products fuels demand for small-batch bourbons and American whiskeys. US FDA regulations define labeling requirements and product composition for domestic and imported spirits. Kentucky remains the epicenter of bourbon production, with numerous distilleries attracting tourism and investment.
United Kingdom
The United Kingdom maintains a robust market for aged Scotch whiskies, driven by both domestic connoisseurs and global exports. European Union Geographical Indications protect the provenance of Scotch Whisky, reinforcing its premium status. Scotland's Speyside region concentrates distilleries, driving innovation in single malt production.
France
Demand for high-quality brandies, particularly Cognac, remains consistent across France and international markets. European Union Geographical Indications strictly govern the appellation and production methods for spirits like Cognac. The Cognac region in southwestern France is the global hub for brandy distillation and aging.
Dark Spirits Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the dark spirits market. The industry exhibits a tiered structure, from global conglomerates managing extensive portfolios to specialized craft distillers. Strategic archetypes include diversified beverage giants, premium-focused specialists, and regional volume leaders. Companies prioritize portfolio diversification and geographic expansion while also engaging in strategic partnerships to enhance distribution reach.
At the scale-driven end, Diageo plc, Pernod Ricard SA, and Beam Suntory Inc. represent established global players in the dark spirits sector. These entities manage extensive portfolios of dark spirits, spanning multiple categories and price points across international markets. Diageo plc occupies a position as a diversified beverage giant, leveraging its broad brand presence and extensive distribution networks. Pernod Ricard SA exemplifies a premium-focused specialist, strategically developing its craft-style offerings and single-origin rums. Beam Suntory Inc. anchors the high-volume standard whiskey category through its significant production capacity and global distribution reach.
| Leading Market Players |
|---|
| Bacardi Limited |
| LVMH Moët Hennessy Louis Vuitton SE |
| Diageo plc |
| Edrington Group |
| William Grant & Sons Ltd |
| Pernod Ricard SA |
| Beam Suntory Inc |
| Campari Group |
| Brown-Forman Corporation |
Cost & Logistics Intelligence
High-net-worth individuals in urban centers like Shanghai and Dubai concentrate demand for super-premium dark spirits, enabling value-based pricing driven by brand premium and exclusivity. This pricing strategy incentivizes distillers to invest in extended maturation cycles and high-quality inputs.
Pricing Analysis
The bundled-vs-unbundled service split is less prominent in dark spirits, where product quality and brand dictate pricing. Value-based pricing dominates for super-premium offerings, driven by extended aging, verifiable provenance, and brand prestige. Pricing stratifies across premium, standard, and economy tiers, with quality grade and appellation serving as key differentiators. Pricing pressure is upward for aged products due to supply inflexibility, while health-conscious consumers exhibit higher price sensitivity for low-ABV options.
Supply Chain Analysis
Reverse-logistics angles, such as bottle recycling initiatives, are emerging but do not yet define the dark spirits supply chain. Production gravity centers on Scotland for Scotch, Kentucky for bourbon, and Cognac for brandy. The industry draws from high-quality oak for casks and specific grains like malted barley and corn. A structural risk involves the long maturation cycles, which create significant supply inflexibility. Distribution primarily runs through traditional retail channels, though direct-to-consumer models are expanding for exclusive bottlings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dark spirits market presents a geographic-arbitrage play, as divergent international regulations for appellation and age statements create cost and market access differentials between regions like the EU and the US. Navigating these variances optimizes brand positioning and profitability.
For Market Incumbents: Deploy digital age verification technologies to strengthen direct-to-consumer channels, mitigating distribution gatekeeper influence. Reinforce brand authenticity through blockchain-enabled provenance tracking on bottles, countering the threat of counterfeit products and justifying premium price points. Invest in advanced sensory analysis technology to maintain product consistency across vast aging inventories, protecting brand reputation from quality fluctuations.
For New Entrants and Emerging Players: Enter via ready-to-drink (RTD) innovation, targeting the high-growth segment of premium canned cocktails using dark spirit bases to attract new consumer demographics. Focus on middle-class consumers in Southeast Asian markets, where appreciation for premium dark spirits is growing but market penetration remains low. Leverage craft-style American whiskeys or single-origin rums with unique flavor profiles to appeal to artisanal product preferences.
For Investors and Strategic Acquirers: Diversified beverage giants are the most active acquirers in this space, seeking to expand premium portfolios and distribution reach. The long-term viability of the dark spirits market, particularly for aged products, remains strong but depends on stable input costs and regulatory clarity. Target specialized craft distillers or technology firms offering provenance solutions to enhance portfolio differentiation. Monitor significant shifts in high-quality oak pricing as an inflection indicator for future profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| RTD Product Launch | Introduces dark spirits to new consumer demographics through convenient formats. |
| Blockchain Provenance | Enhances trust and justifies premium price points for aged whiskies and rums. |
| Geographic Expansion into SEA | Captures untapped demand from rising middle-class consumers in Southeast Asia. |
| Capacity Expansion in Scotland | Addresses growing global demand for protected Scotch Whisky appellations. |
| Digital Age Verification | Streamlines online sales channels and ensures regulatory compliance for e-commerce. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and market intelligence databases — were reconciled to construct a comprehensive market view. This involved conversations with master distillers, brand managers, procurement leads, and regulatory compliance officers across key regions. Secondary data from EU EFSA reports, US FDA guidelines, India's FSSAI standards, and customs trade data informed the analysis. Bottom-up and top-down triangulation ensured robust data accuracy.
Historical market performance was cross-referenced with expert panel input to project future growth across the analysis window. The quantitative model segmented the market by product type, alcohol content, flavor profile, and packaging type, alongside regional regulatory nuances. Compound Annual Growth Rates (CAGRs) were derived from a multi-factor regression analysis. Raw material price trends and consumer disposable income growth served as critical forecast inputs.
The model holds under current regulatory frameworks and stable geopolitical conditions; deviation in international trade policies or climate-related input supply disruptions would shift forecasts. Forecasts reflect assumptions regarding consumer preference evolution and technological adoption. Practitioners should monitor global trade agreements and extreme weather events for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Premixed Cocktail Shots Market
Alcoholic Beverages
Ethanol Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Citrus Alcohol Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Global Wine Coolers Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Asia-Pacific Spirits Market
Alcoholic Beverages
Germany Wine Coolers Market