
 F-Style Jugs Market | 2026-2036
F-Style Jugs Market Size, Share, and Industry Trends Forecast 2026-2036
F-Style Jugs Market Foresight
North American HDPE blow molding capacity expansion is reshaping supply availability for rigid industrial packaging. Berry Global Inc. leverages integrated resin-to-container manufacturing across multiple US facilities to secure feedstock cost advantages. Greif Inc. anchors its position through steel and plastic hybrid F-style offerings that serve dual-use chemical and food-grade applications. Mauser Packaging Solutions specializes in reconditioned and recycled-content jug programs that address circular economy mandates from large chemical buyers.
An F-style jug denotes a rectangular container with a molded handle integrated into one narrow side, typically manufactured through extrusion blow molding of high-density polyethylene or injection stretch blow molding of polyethylene terephthalate, with wall thickness calibrated to meet UN performance standards for hazardous liquid transport. Plastic variants dominate volume production due to chemical resistance and lightweight logistics economics, while metal and fiber alternatives retain niche positions in solvent packaging and dry goods applications where static dissipation or moisture buffering matters. The 5-gallon capacity segment leads industrial chemical procurement, whereas 1-gallon formats capture food-grade vinegar, cooking oil, and cleaning concentrate distribution where retail handling convenience drives selection.
The US EPA enforces RCRA container integrity requirements that mandate specific wall thickness and closure torque specifications for hazardous waste F-style containers, while FDA 21 CFR regulations govern food-contact resin approvals and migration limits for edible product packaging. OSHA hazard communication standards further dictate labeling compatibility and chemical resistance documentation that suppliers must maintain. Stakeholders should monitor evolving state-level extended producer responsibility legislation and recycled content minimums that will reshape material sourcing decisions and capital allocation for blow molding equipment.
Market Dynamics
HDPE resin supply concentration along the US Gulf Coast is tightening procurement leverage for F-style jug converters, as petrochemical feedstock volatility forces container manufacturers toward long-term tolling agreements with integrated resin producers.
Growth Catalysts
- RCRA Subtitle C container integrity mandates:EPA enforcement of hazardous waste packaging specifications is compelling chemical distributors to replace non-compliant legacy containers with UN-certified F-style alternatives.
- Food-grade vinegar and cooking oil bottling:Retail private-label brands are consolidating packaging formats toward 1-gallon rectangular jugs that optimize shelf density and e-commerce shipping cube efficiency.
- Reconditioned container circularity programs:Large chemical buyers are embedding closed-loop packaging requirements into procurement contracts, accelerating demand for industrial jug refurbishment services.
Market Restraints
- HDPE resin price volatility:Ethylene feedstock exposure to natural gas liquids markets creates margin compression for independent blow molders without captive resin supply.
- Single-source tooling dependency:Custom extrusion blow molds for F-style handle integration require 16-20 week lead times from specialized Ohio and Michigan tool shops, constraining capacity responsiveness.
- Steel drum substitution in solvent applications:Static-dissipative metal containers retain preference for flammable liquid transport where polyethylene triboelectric charging risks exceed acceptable thresholds.
Strategic Opportunities
- California and New York extended producer responsibility laws:State-mandated recycled content minimums for rigid plastic packaging are creating premium market tiers for post-consumer HDPE jug supply.
- IoT-enabled smart closure integration:RFID-tagged tamper-evident caps paired with blockchain provenance tracking are opening value-added service contracts in pharmaceutical and agrochemical distribution.
- Direct-to-contractor e-commerce channels:Maintenance, repair, and operations platforms are disintermediating traditional industrial distribution for 5-gallon cleaning concentrate and lubricant jug sales.
Industry Challenges
- UN performance certification testing bottlenecks:Third-party laboratory capacity constraints at Oregon and New Jersey facilities are extending new product qualification timelines from 8 to 14 weeks.
- Multi-layer coextrusion technician scarcity:Barrier-enhanced jug production requiring EVOH or nylon interlayers faces recruitment gaps for experienced blow molding process engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | F-Style Jugs Market |
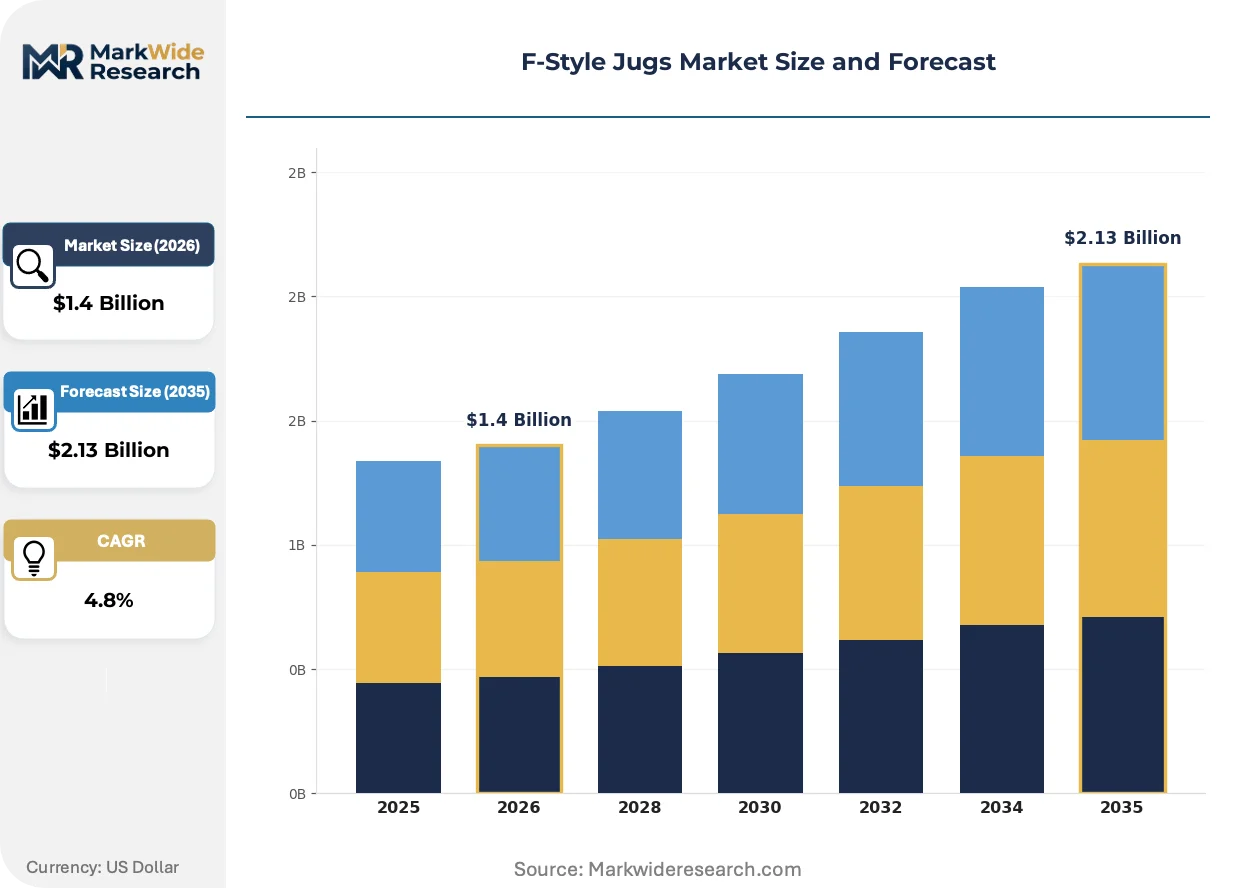
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Fiber Capacity: 1 Gallon, 2 Gallon, 5 Gallon, 7 Gallon Closure Type: Screw Cap, Snap Cap, Flip Top, Child Resistant Application: Food & Beverage, Chemical, Industrial, Household |
| Companies Covered | Berlin Packaging, Qorpak, U.S. Plastic Corp, Berry Global Inc., Mauser Packaging Solutions, Greif Inc., The Cary Company, TricorBraun, LPS Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
F-Style Jugs Market Shifts & Advancements
Digital manufacturing integration and regulatory compliance automation are compressing product development cycles while reshaping how container specifications travel from chemical shipper to converter.
Machine vision-based inline thickness gauging is digitizing quality assurance protocols for extrusion blow molded F-style containers. Tier-1 chemical distributors are mandating real-time wall thickness data logging to satisfy EPA audit trails. This digitizing of inspection workflows is reducing post-mold destructive testing by 60% and accelerating lot release velocity.
California's SB 54 rigid plastic packaging producer responsibility act is forcing jug manufacturers to document post-consumer recycled content percentages through mass balance certification. Compliance deadlines are accelerating capital allocation toward optical sorting and flake washing equipment. Food-contact and non-food container lines are diverging as FDA 21 CFR migration testing requirements constrain recycled HDPE sourcing pools.
Maintenance, repair, and operations procurement teams are consolidating supplier panels from 12-15 regional converters to 3-4 national accounts with integrated inventory management systems. Vendor-managed stock programs at Gulf Coast petrochemical facilities are displaced by consignment arrangements tied to consumption-based billing. This consolidation is most visible in Texas and Louisiana downstream chemical corridors where jug consumption density supports dedicated fleet deployment.
F-Style Jugs Market Segmentation
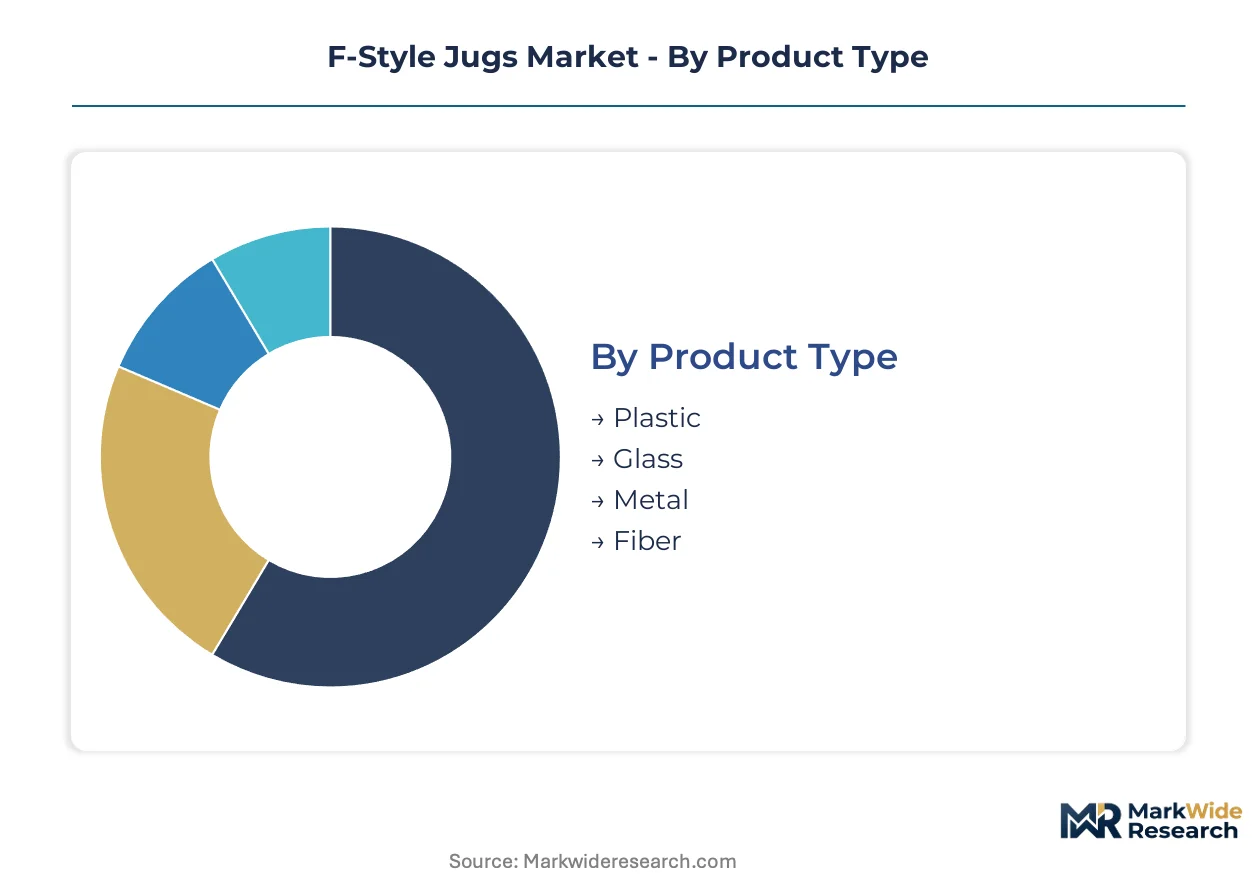
F-style jug procurement patterns diverge sharply across material grades, volume tiers, and regulatory exposure levels. Understanding these segment boundaries reveals where converter margins concentrate and where specification flexibility creates sourcing leverage.
Product Type:
Material selection pivots on chemical compatibility requirements and UN certification economics.
- Plastic:HDPE blow molding dominates industrial chemical packaging through superior corrosion resistance and lightweight logistics. Gulf Coast petrochemical corridors source 5-gallon formats for hazardous liquid transport under EPA RCRA Subtitle C mandates.
- Metal:Steel hybrid constructions retain solvent packaging applications where static dissipation exceeds polyethylene triboelectric charging thresholds. UN-certified steel F-styles command premium positioning in flammable liquid distribution.
- Glass:Borosilicate and soda-lime variants serve laboratory reagent and high-purity chemical niches requiring inert contact surfaces and visual inspection capability.
- Fiber:Multiwall paperboard drums with polyethylene liners address dry goods and moisture-sensitive powder applications where crush stacking matters more than liquid containment.
Plastic commands the established base. The steepest expansion runs through metal hybrid formats bridging chemical resistance with static control.
Capacity:
Volume tier selection reflects handling economics and end-use consumption patterns.
- 5 Gallon:The industrial workhorse format captures bulk chemical procurement from downstream petrochemical producers. UN performance certification requirements concentrate converter investment at this tier.
- 1 Gallon:Retail-facing formats dominate food-grade vinegar and cooking oil bottling where shelf density and e-commerce cube efficiency drive private-label consolidation.
- 2 Gallon:Mid-volume positioning serves cleaning concentrate and automotive fluid niches balancing portability with procurement frequency reduction.
- 7 Gallon:Specialty industrial applications include agricultural chemical bulk dispensing and commercial cleaning system refills where pump attachment compatibility matters.
5-gallon formats anchor revenue concentration. The sharpest volume gains are emerging in 1-gallon retail-optimized configurations.
Closure Type:
Sealing mechanism selection intertwines with regulatory compliance exposure and end-user safety requirements.
- Screw Cap:Standard threaded closures dominate industrial chemical applications where torque specification documentation satisfies EPA audit trails. HDPE and polypropylene resin grades optimize thread engagement durability.
- Child Resistant:Push-and-turn mechanisms are mandatory for household chemical and agrochemical distribution under EPA FIFRA and CPSC poisoning prevention standards. Certification testing extends product qualification timelines.
- Snap Cap:Friction-fit designs serve single-use food-grade applications where resealability matters less than production line throughput.
- Flip Top:Hinged dispensing closures capture cleaning concentrate and automotive additive segments where controlled pouring reduces spillage.
Screw cap configurations hold the volume base. Child-resistant mechanisms are climbing the fastest as regulatory mandates expand across chemical categories.
Application:
End-use segmentation determines resin specification, certification burden, and channel strategy.
- Chemical:Hazardous liquid transport under UN performance standards drives HDPE wall thickness calibration and closure torque documentation. RCRA container integrity mandates are accelerating replacement cycles for non-compliant legacy packaging.
- Food & Beverage:FDA 21 CFR migration limits constrain recycled HDPE sourcing pools. 1-gallon vinegar and cooking oil bottling concentrates demand in retail private-label consolidation.
- Industrial:Maintenance, repair, and operations procurement platforms are disintermediating traditional distribution for lubricant and cleaning concentrate jug sales.
- Household:Consumer-facing formats prioritize shelf aesthetics and e-commerce shipping durability over industrial certification economics.
Chemical applications anchor converter capacity allocation. Food-grade positioning is gaining share fastest as retail channel consolidation accelerates format standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HDPE resin supply concentrates along the US Gulf Coast, creating feedstock cost advantages for domestic blow molders while European and Asian converters face higher import dependency. Container demand patterns diverge sharply by regulatory environment and downstream chemical production density.
United States
Downstream petrochemical corridors in Texas and Louisiana drive 5-gallon hazardous liquid container consumption under EPA RCRA Subtitle C mandates. The EPA enforces tightening container integrity specifications for corrosive substance packaging. Houston-area chemical distributors are consolidating supplier panels toward national accounts with integrated inventory management systems.
Germany
Industrial chemical packaging demand centers on the Rhine-Ruhr and Ludwigshafen chemical clusters where BASF and downstream producers source UN-certified containers. ECHA REACH regulations govern chemical compatibility documentation and migration testing for resin formulations. Bavarian blow molders specialize in barrier-enhanced multi-layer constructions for solvent applications.
China
Coastal manufacturing provinces of Jiangsu and Zhejiang host extrusion blow molding capacity serving both domestic chemical distribution and export food-grade markets. NMPA and GB standards regulate pharmaceutical and food-contact packaging migration limits. The Yangtze River Delta exhibits fastest capacity expansion for recycled-content HDPE processing equipment.
India
Maharashtra and Gujarat chemical zones drive procurement of 1-gallon retail formats for edible oil and vinegar bottling under FSSAI food-contact regulations. BIS certification requirements for industrial chemical containers are accelerating replacement of non-standard legacy packaging. Mumbai-Pune corridor converters are investing in optical sorting equipment to meet emerging extended producer responsibility mandates.
Japan
Kanto and Kansai industrial belts maintain demand for high-purity laboratory reagent packaging in glass and fluoropolymer-lined F-style configurations. METI circular economy guidelines are pressuring converters to document mass balance recycled content. Osaka-area specialists dominate precision barrier coextrusion for agrochemical distribution.
F-Style Jugs Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin formulation and custom mold fabrication. The vendor base organizes around three archetypes: integrated resin-to-container manufacturers with captive HDPE supply, reconditioning and circularity service providers, and regional converters serving food-grade retail bottling. Dominant competitive moves include backward integration into resin tolling agreements and geographic consolidation through maintenance, repair, and operations platform partnerships.
Among North American packaging conglomerates, Berry Global Inc., Greif Inc., and Mauser Packaging Solutions exemplify divergent strategic positioning. Berry Global anchors the integrated manufacturing archetype through multi-facility resin-to-container operations. Greif occupies the hybrid-format tier bridging steel and plastic container technologies. Mauser Packaging Solutions represents the circularity-focused model through reconditioned jug programs and recycled-content certification capabilities.
| Leading Market Players |
|---|
| Berlin Packaging |
| Qorpak |
| U.S. Plastic Corp |
| Berry Global Inc. |
| Mauser Packaging Solutions |
| Greif Inc. |
| The Cary Company |
| TricorBraun |
| LPS Industries |
| Others |
Supply & Pricing Matrix
HDPE resin price volatility tethered to natural gas liquids markets determines both the premium-to-economy pricing spread across container grades and the geographic clustering of blow molding capacity. Feedstock exposure forces independent converters toward long-term tolling agreements that reshape procurement leverage and margin distribution.
Pricing Analysis
EPA RCRA Subtitle C container integrity mandates dictate the pricing tier structure across UN-certified and non-certified F-style jugs. Three-tier pricing stratifies across premium UN-performance-certified, standard industrial-grade, and economy non-hazardous formats. Price differentiation centers on wall thickness calibration and closure torque documentation quality. Cost compression in the economy tier is intensifying because recycled-content minimums in California and New York constrain virgin HDPE sourcing pools. Small regional converters exhibit highest price sensitivity, while national accounts with integrated inventory systems absorb premium positioning for audit-compliant documentation.
Supply Chain Analysis
Integrated resin producers along the US Gulf Coast, specialized Ohio and Michigan blow mold tool shops, and regional reconditioning facilities hold concentrated contract-manufacturing capacity. Raw material flows draw from Texas and Louisiana ethylene crackers, while custom extrusion molds feed from specialized Great Lakes tooling clusters. Single-source vulnerability runs through 16-20 week lead times for F-style handle-integrated molds. Distribution runs through maintenance, repair, and operations platforms disintermediating traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel drum substitution in solvent applications represents the most immediate substitution threat that HDPE jug incumbents must navigate through static-dissipative material innovation.
For Market Incumbents: Insulate core chemical segment positioning through backward integration into Gulf Coast resin tolling agreements that neutralize feedstock volatility. Secure UN performance certification capacity at Oregon and New Jersey testing facilities before qualification bottlenecks extend further. Child-resistant closure mandates across agrochemical and household chemical categories threaten margin compression without dedicated certification infrastructure. For New Entrants and Emerging Players: Reconditioned container circularity programs for large chemical buyers represent the most penetrable entry point, bypassing capital-intensive virgin blow molding equipment. California SB 54 mass balance certification services offer regulatory-driven service revenue with lower asset intensity. Direct-to-contractor e-commerce channels for 5-gallon lubricant and cleaning concentrate sales provide disintermediation leverage against established distribution relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors circularity-enabled mid-cap specialists with reconditioning infrastructure and recycled-content certification capabilities. Long-term viability hinges on extended producer responsibility mandate expansion across additional states. The signal to watch is BIS certification acceleration in India that could replicate replacement cycle dynamics seen under EPA enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gulf Coast tolling agreements neutralize ethylene feedstock volatility for blow molders. |
| UN Performance Certification Investment | Oregon and New Jersey laboratory partnerships compress 14-week qualification timelines. |
| Reconditioned Container Program Expansion | Closed-loop packaging contracts with Dow and BASF address circularity procurement mandates. |
| Child-Resistant Closure Capability Buildout | EPA FIFRA compliance positions converters for agrochemical distribution growth. |
| Optical Sorting Equipment Deployment | California SB 54 mass balance certification enables premium recycled-content tier access. |
Research Methodology
Cross-validation between primary interviews with blow molding plant managers, chemical distributor procurement leads, and EPA compliance officers and secondary validation through customs trade data, SEC 10-K packaging segment disclosures, and ACC industry reports anchors the qualitative findings. Bottom-up capacity modeling triangulates against top-down resin consumption estimates from Gulf Coast petrochemical corridor analysis.
Calibration against historical replacement cycle timing under RCRA enforcement phases and forward projection of state extended producer responsibility adoption curves shapes the analytical framework across the analysis window. Segmentation dimensions include material grade tier, capacity format, closure certification level, and end-use regulatory exposure. CAGR derivation incorporates HDPE resin price elasticity coefficients and UN certification penetration rates by chemical shipper tier.
Macroeconomic conditions sit as an overlay; deviation in natural gas liquids pricing and ethylene cracker operating rates would shift the trajectory of converter margin expansion. Forecasts reflect assumptions regarding California and New York recycled-content mandate enforcement timing. Quarterly review of EPA audit inspection frequency and BIS certification acceleration in India is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
RTD Cocktail Shots Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Beer Kegs Market
Alcoholic Beverages
US Wine Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Australia and New Zealand Tequila Market
Alcoholic Beverages
Pinot Meunier Market
Alcoholic Beverages
Mini Brew Fermenter Market
Alcoholic Beverages
India Gin Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
Beer Filter System Market