
 Home Brew Boiler Market | 2026-2036
Home Brew Boiler Market Size, Share, and Industry Trends Forecast 2026-2036
Home Brew Boiler Market Foresight
CE marking is hardening the cost-of-entry calculus for smaller manufacturers seeking access to European hobbyist brewers. SS Brewtech leverages stainless steel fabrication expertise to sustain premium positioning across digital-control product lines. Grainfather anchors its competitive stance through integrated smart-control ecosystems that simplify all-grain workflows for residential users. Bosch competes on heating-element reliability and brand recognition in consumer appliance channels, while Shandong Zunhuang Brewing Equipment dominates cost-engineered gas boiler exports to price-sensitive Asian markets.
A home brew boiler is a purpose-built thermal vessel designed to heat mash water and wort to precise temperatures, typically constructed from food-grade stainless steel with wattage ratings between 1,500 and 5,500 watts and incorporating temperature sensors accurate to within one degree Celsius. Its primary commercial purpose is to enable consistent enzymatic conversion and hop isomerization during small-batch beer production. Electric boilers lead the product type category due to plug-and-play convenience and apartment-friendly operation, while smart control systems represent the fastest-growing segment as WiFi-enabled programmable units command margin premiums over manual alternatives. The 5-gallon and 10-gallon capacity tiers capture the bulk of residential demand, though 15-gallon systems are gaining traction among semi-professional home brewers scaling toward nanobrewery output.
The US Consumer Product Safety Commission and the EU's CE marking framework govern electrical safety and pressure vessel integrity, while Germany's KBA-influenced product liability standards shape quality expectations for exported European equipment. These regulatory layers elevate compliance spending but simultaneously filter out low-reliability competitors, concentrating demand among certified manufacturers. Stakeholders must monitor evolving energy-efficiency labeling requirements and smart-device cybersecurity standards as connected brewing equipment proliferates in residential settings.
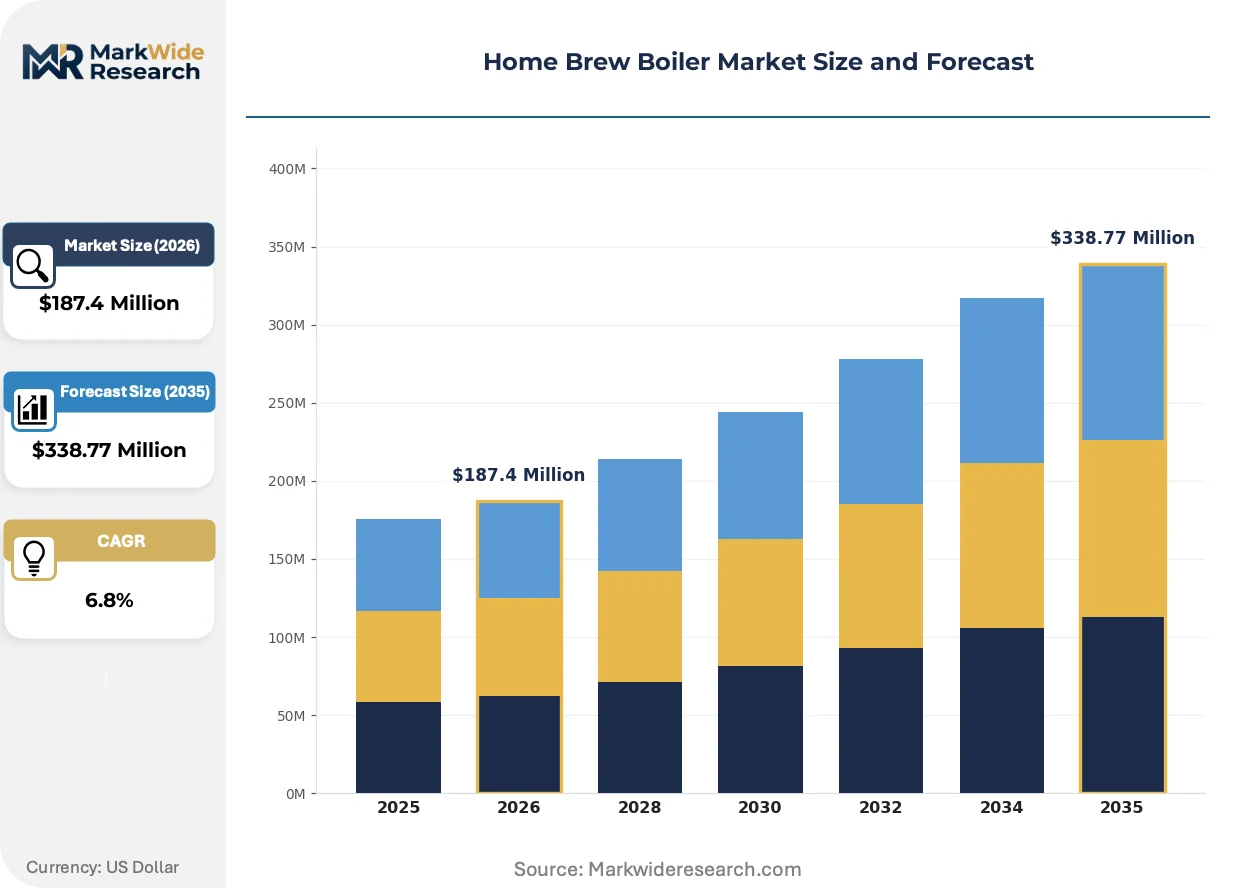
Market Dynamics
The EU F-Gas Regulation is tightening thermal equipment standards while WiFi-enabled control systems reshape buyer expectations across residential and craft brewing segments.
Growth Catalysts
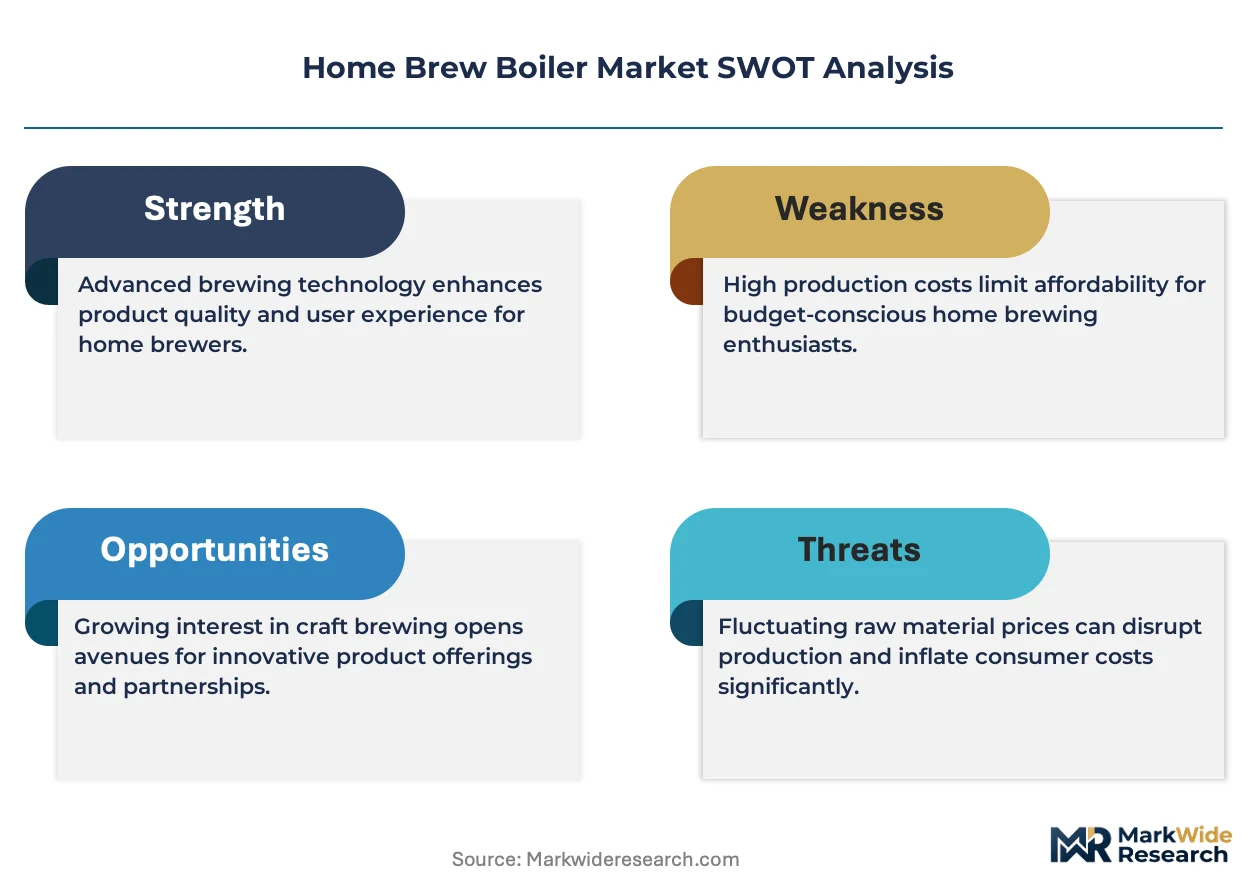
- CE marking compliance:European hobbyist brewers prioritize certified equipment, filtering demand toward tested manufacturers and elevating average selling prices for compliant systems.
- Smart home integration:WiFi-enabled boilers with app-based temperature scheduling attract tech-forward residential buyers seeking unattended mash monitoring.
- German brewing culture:Deep-rooted homebrewing traditions in Bavaria and Baden-Württemberg sustain replacement demand for precision-controlled all-grain systems.
Market Restraints
- Stainless steel price volatility:Food-grade 304 and 316 alloy costs fluctuate with nickel and chromium commodity markets, squeezing fabrication margins.
- Supply concentration in Shandong:Chinese gas boiler exports dominate price-sensitive Asian segments, limiting pricing power for electric-system manufacturers elsewhere.
- Apartment electrical limits:North American residential circuits cap at 2,400 watts in older buildings, constraining high-wattage electric boiler adoption.
Strategic Opportunities
- Semi-professional scaling:15-gallon systems serve home brewers transitioning toward nanobrewery output, commanding margin premiums over standard residential tiers.
- Energy-efficiency labeling:EU Ecodesign requirements create competitive differentiation for low-consumption electric models in German and French markets.
- Direct-to-consumer channels:Specialty retailers and manufacturer-owned web stores bypass traditional appliance distributors, capturing full margin on replacement sales.
Industry Challenges
- Cybersecurity certification:Connected brewing equipment faces emerging smart-device security standards, requiring firmware investment and third-party testing.
- Pressure vessel welding:Qualified TIG welders for food-grade stainless fabrication remain scarce, extending production lead times for certified manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Brew Boiler Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Boiler, Gas Boiler, Hybrid Boiler, Induction Boiler Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 15 Gallon Heating Method: Direct Heating, Indirect Heating, Steam Infusion, Pressurized Heating Control System: Manual Control, Digital Control, Programmable Control, Smart Control |
| Companies Covered | SPEIDEL TANK AND CONTAINER CONSTRUCTION, Spike Brewing, Blichmann Engineering, SS Brewtech, Grainfather, Northern Brewers, Shandong Zunhuang Brewing Equipment, Bosch, Craft a Brew, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Brew Boiler Market Shifts & Advancements
Digital control architectures and regulatory tightening are converging to reshape product development priorities and channel economics across the home brewing equipment sector.
PID temperature controllers with Bluetooth connectivity are integrating into mid-tier electric boilers, enabling mash step automation previously limited to professional systems. Residential brewers in Germany and the United States are adopting these units at accelerating rates. This convergence is integrating hardware margins with recurring software service revenue, compressing the traditional equipment-only business model.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants and tightening thermal equipment efficiency standards. Boiler manufacturers serving European hobbyists must redesign heat exchange elements and insulation packages to maintain market access. Electric systems with solid-state heating elements face lighter compliance burdens than gas alternatives, tilting R&D investment toward all-electric platforms.
Specialty homebrew retailers are ceding share to manufacturer-direct ecommerce and subscription-based equipment leasing. Enthusiasts in urban United States markets increasingly rent high-capacity systems for seasonal brewing rather than owning depreciating assets. This behavioral shift is most visible in California and Pacific Northwest metropolitan clusters where storage space constraints intersect with high equipment turnover.
Home Brew Boiler Market Segmentation
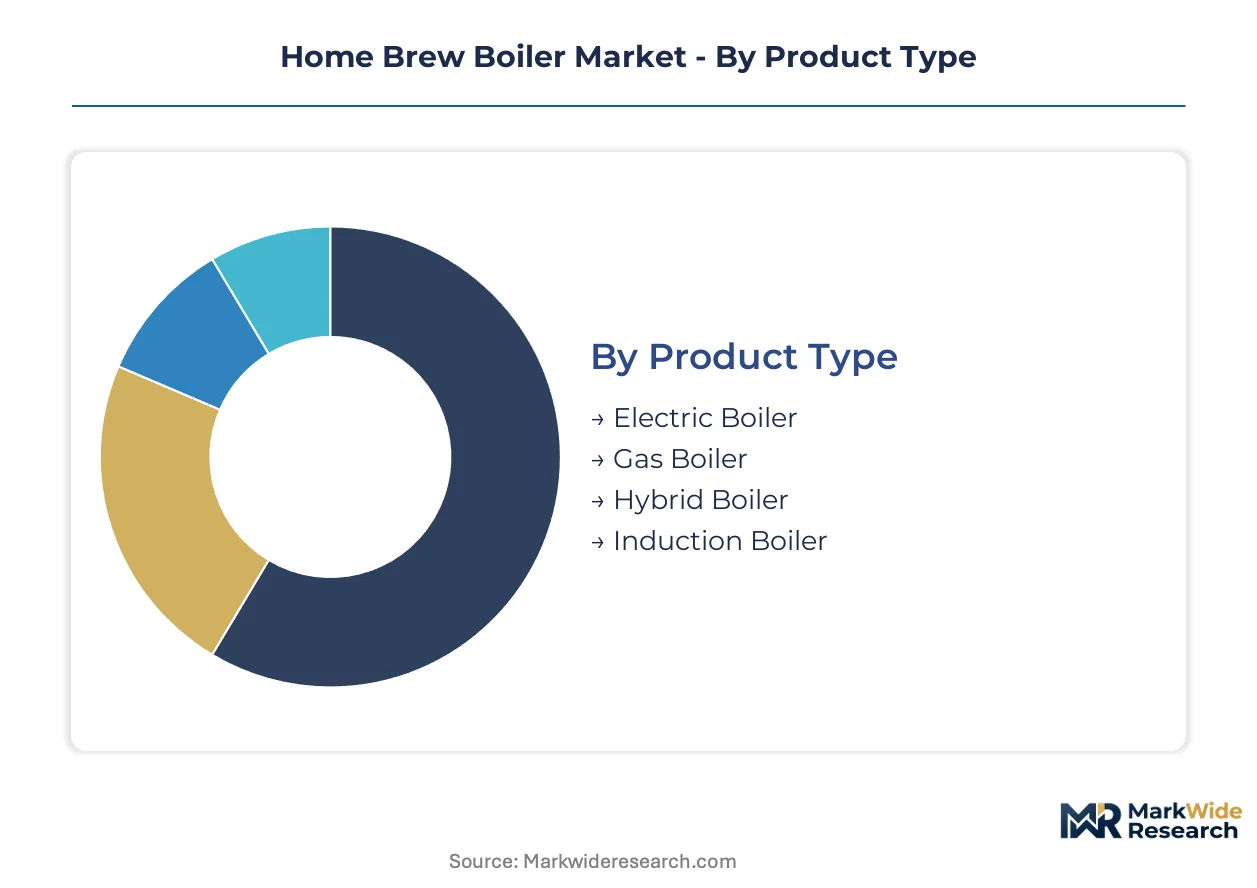
Home brew boiler purchasing decisions hinge on installation constraints, batch scaling ambitions, and automation preferences. Segmentation reveals how hobbyist brewers trade off upfront cost against operational precision and capacity headroom.
Product Type:
Replacement cycles accelerate where electrical infrastructure supports plug-and-play installation, while gas alternatives retain footholds in utility-cheap regions.
- Electric Boiler:Solid-state heating elements deliver wattage between 1,500 and 5,500 watts with temperature stability within one degree Celsius. Demand clusters in German and United States urban apartments where ventilation constraints eliminate combustion options. CE marking compliance elevates certified units toward premium positioning.
- Gas Boiler:Propane or natural gas burners achieve faster ramp rates for high-volume wort boiling. Rural United States brewers and Australian hobbyists favor these systems where utility costs favor fossil thermal energy over electrical resistance heating.
- Hybrid Boiler:Dual-fuel architectures pair electric mash control with gas-powered boil stages. Semi-professional users transitioning toward nanobrewery output value the operational flexibility.
- Induction Boiler:Electromagnetic coil systems heat ferrous vessels directly without immersion elements. Japanese and South Korean residential kitchens with existing induction cooktops drive adoption.
Volume placements concentrate in Electric Boiler configurations; the faster expansion belongs to Induction Boiler systems.
Capacity:
Cost tiering separates casual extract brewers from all-grain enthusiasts scaling toward commercial pilot batches.
- 1 Gallon:Compact countertop units serve experimental brewers testing recipe variants. Urban apartment dwellers in London and New York City favor these systems where storage space commands premium value.
- 5 Gallon:Standard corny keg compatibility defines this residential workhorse tier. Bavarian and Pacific Northwest hobbyists replace these units on three-to-five year cycles as heating element degradation accumulates.
- 10 Gallon:Dual-batch capability supports split fermentation experiments and higher-gravity brewing. Semi-professional users in Colorado and Oregon climbing toward nanobrewery licensing favor this capacity point.
- 15 Gallon:Full all-grain workflows with grain bills exceeding twenty-five pounds require this tier. German Braukurs participants and United States competition brewers value the headroom for high-volume seasonal production.
Revenue concentrates in 5 Gallon and 10 Gallon tiers; 15 Gallon systems climb the fastest as hobbyist commercialization accelerates.
Heating Method:
Application context determines whether brewers prioritize speed, temperature precision, or wort quality preservation.
- Direct Heating:Immersion elements or burner contact transfer thermal energy immediately to wort. Cost-sensitive Asian markets and entry-level United States brewers favor this straightforward approach despite scorching risks with high-gravity mashes.
- Indirect Heating:Jacketed vessels or external heat exchangers eliminate hot spots and enable precise step mashing. German and Belgian all-grain traditions sustain demand for these systems where enzymatic conversion precision determines recipe fidelity.
- Steam Infusion:Saturated steam injection achieves rapid temperature steps without dilution. Professional-grade home systems in Denmark and the Netherlands incorporate this method for delicate protein rests.
- Pressurized Heating:Elevated boiling temperatures accelerate hop isomerization and reduce boil times. Advanced hobbyists in Australia and New Zealand experiment with these systems for high-alpha hop utilization.
Unit economics favor Direct Heating at entry price points; Indirect Heating gains share fastest as all-grain sophistication deepens.
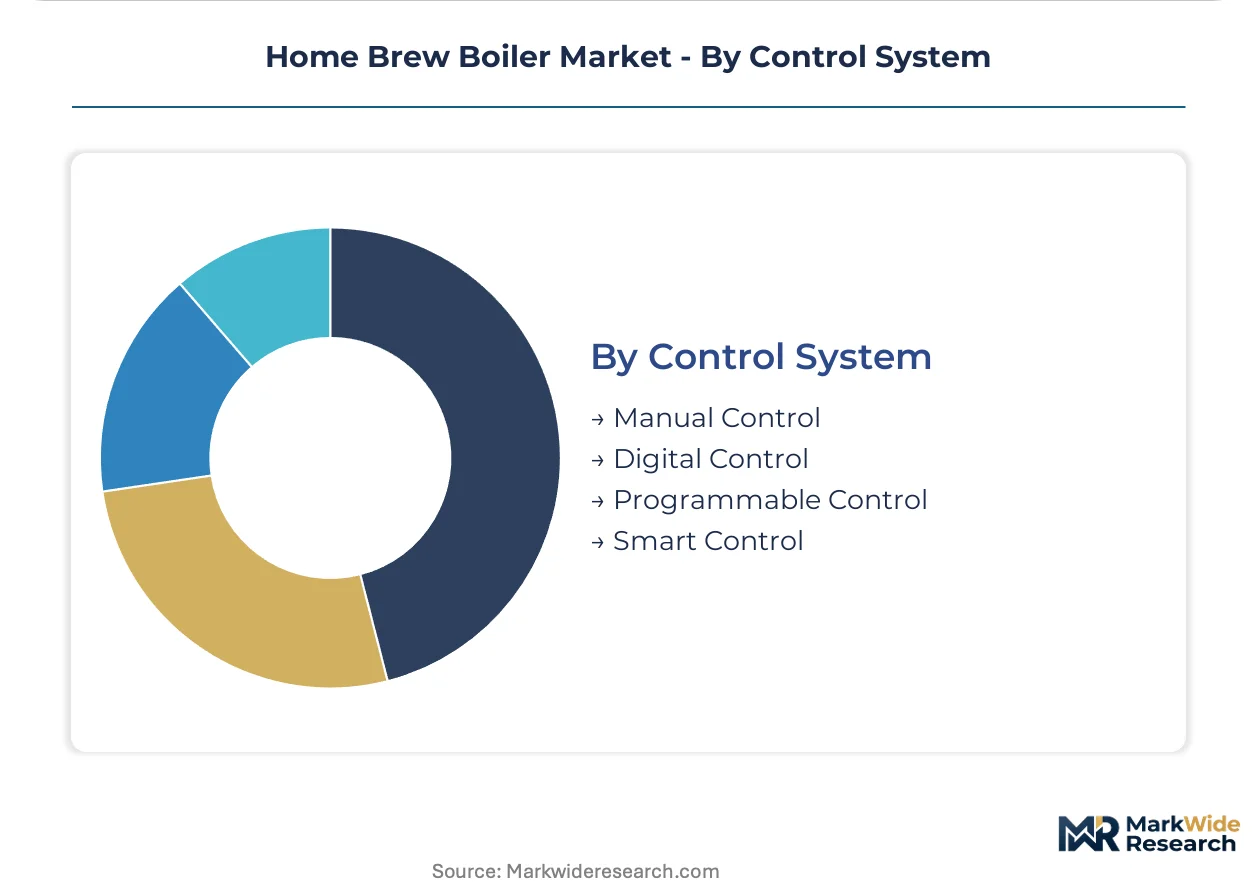
Control System:
Margin structures diverge sharply between mechanical simplicity and connected automation ecosystems.
- Manual Control:Dial thermostats and sight-glass observation demand continuous brewer attention. Price-sensitive Asian export markets and traditionalist European brewers sustain residual demand for these no-electronics systems.
- Digital Control:LED displays with single-setpoint temperature maintenance bridge mechanical and automated worlds. Mid-tier United States and United Kingdom retailers stock these units as volume drivers.
- Programmable Control:Multi-step mash schedules with automatic temperature transitions enable unattended brewing. German and Czech hobbyists value these systems for complex decoction and step-mash protocols.
- Smart Control:WiFi-enabled PID architectures with smartphone monitoring and cloud recipe integration command premium positioning. Tech-forward United States and Scandinavian markets drive adoption where smart home ecosystem compatibility matters.
Shipment volumes concentrate in Digital Control; Smart Control expands most quickly as firmware-update business models emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and United States hobbyists generate the densest demand clusters for precision-controlled brewing systems, with regulatory frameworks in both markets filtering supply toward certified manufacturers.
United States
Urban apartment dwellers in Brooklyn and Portland drive electric boiler adoption where ventilation constraints eliminate gas alternatives. The Consumer Product Safety Commission governs electrical safety standards for residential brewing equipment. Colorado Front Range brewers cluster around Boulder and Denver, scaling toward nanobrewery licensing with 10-gallon and 15-gallon systems.
Germany
Bavarian Braukurs participants and Baden-Württemberg all-grain enthusiasts sustain replacement cycles for precision step-mash systems. The KBA-influenced product liability standards shape quality expectations for exported European equipment. Munich and Stuttgart metropolitan areas concentrate demand for CE-marked programmable control units.
China
Shandong Province fabricators dominate cost-engineered gas boiler exports serving price-sensitive Asian hobbyists. The country's national standardization administration oversees GB standards for pressure vessel integrity. Qingdao and Jinan industrial clusters supply entry-level equipment to Southeast Asian and domestic residential markets.
Australia
Rural brewers in Victoria and New South Wales favor propane-fired systems where utility costs favor fossil thermal energy. The Therapeutic Goods Administration framework does not directly govern brewing equipment, leaving state-level electrical safety regulators to certify residential installations. Melbourne's craft beer culture sustains specialty retailer channels for premium electric alternatives.
United Kingdom
London apartment constraints push demand toward compact 1-gallon and 5-gallon electric units with storage-efficient footprints. CE marking compliance remains mandatory post-Brexit through retained EU law alignment. Manchester and Birmingham homebrew clubs drive word-of-mouth adoption of WiFi-enabled smart control systems.
Home Brew Boiler Market Competitive Landscape
United States fabricators anchor the premium-tier; Shandong-based specialists hold the cost-engineered export segment. The vendor base splits between stainless steel precision manufacturers and commodity gas boiler exporters. Three archetypes dominate: integrated smart-control ecosystem providers, heating-element reliability specialists, and volume-driven Asian fabricators. Capacity expansion and firmware development represent the dominant competitive vectors as connectivity features reshape buyer expectations.
Among German stainless fabricators, SPEIDEL TANK AND CONTAINER CONSTRUCTION exemplifies the precision-engineering archetype with pressure vessel expertise. SS Brewtech and Grainfather occupy positions within the North American premium tier, representing contrasting approaches to digital control integration and residential workflow simplification. These three anchors illustrate how geographic specialization and technical positioning stratify competitive access to hobbyist segments across regulatory environments.
| Leading Market Players |
|---|
| SPEIDEL TANK AND CONTAINER CONSTRUCTION |
| Spike Brewing |
| Blichmann Engineering |
| SS Brewtech |
| Grainfather |
| Northern Brewers |
| Shandong Zunhuang Brewing Equipment |
| Bosch |
| Craft a Brew |
| Others |
Supply & Pricing Matrix
WiFi-enabled PID controller integration is compressing margin structures for manual-system manufacturers while simultaneously concentrating procurement power among firmware-capable fabricators in Germany and the United States. This technology transition rewards CE-marked precision engineering with pricing premiums while forcing commodity gas boiler exporters toward volume-driven, low-margin positioning.
Pricing Analysis
Volume placements cluster in standard digital-control tiers where per-unit margins thin; premium positioning accrues to smart-control ecosystems with recurring firmware revenue. Price differentiation separates CE-certified stainless systems from uncertified Asian exports, with German and United States buyers absorbing certification premiums. Pricing pressure stems from Shandong gas boiler exports flooding Southeast Asian channels. Hobbyist brewers in price-sensitive segments exhibit highest elasticity, while semi-professional nanobrewery scalers prioritize precision over cost.
Supply Chain Analysis
Direct-to-consumer channels and specialty homebrew retailers handle United States and German demand, bypassing traditional appliance distributors. Food-grade 304 stainless steel draws from Chinese and Indian mills; TIG welding capacity concentrates in Bavarian and Shandong industrial clusters. Single-source vulnerability runs through nickel and chromium commodity markets. Distribution runs through manufacturer-owned web stores capturing full replacement margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU F-Gas Regulation and CE marking framework erect barrier-to-entry moats that certified stainless fabricators exploit for sustained premium positioning.
For Market Incumbents: To counter Shandong gas boiler price erosion in Asian export channels, deepen upstream control over food-grade stainless supply through captive mill relationships or long-term offtake agreements with Indian and Chinese alloy producers. Invest in cybersecurity certification capacity ahead of emerging smart-device standards for connected brewing equipment. For New Entrants and Emerging Players: The 15-gallon semi-professional tier offers white-space opportunity between Grainfather's smart-ecosystem premium and entry-level Asian commodity positioning. Target Colorado and Oregon nanobrewery licensing corridors with hybrid electric-gas architectures. Pursue direct-to-consumer launch through subscription-based equipment leasing models tested in California metropolitan clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by consumer appliance conglomerates seeking smart-home ecosystem integration. Long-term viability favors vertically integrated stainless fabricators with CE marking capacity and firmware development capabilities. Watch German KBA-influenced liability standard expansions as inflection signals for quality-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU F-Gas Regulation compliance secures access to German and French premium hobbyist channels. |
| Smart Control Firmware Development | WiFi-enabled PID architectures command margin premiums over manual alternatives in United States tech-forward segments. |
| Backward Integration into Stainless Supply | Captive food-grade 304 sourcing insulates fabrication margins from nickel commodity volatility. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned web stores bypass distributor margin capture on replacement sales cycles. |
| 15-Gallon Capacity Line Extension | Semi-professional tier serves nanobrewery transition demand in Colorado and Oregon licensing corridors. |
Research Methodology
Trade publications, customs export databases, and EU regulatory filing repositories formed the secondary backbone for demand quantification. Primary interviews with homebrew equipment distributors, stainless fabrication plant managers, and regulatory compliance officers at CE marking bodies were cross-referenced against secondary validation. Bottom-up shipment analysis and top-down consumer expenditure triangulation anchored volume estimates.
Historical trendline analysis of replacement cycles and technology adoption curves informed projection modeling across the analysis window. Segmentation dimensions included product type, capacity tier, control system sophistication, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating smart-home penetration rates and craft brewery licensing trends. Stainless steel price indices and electrical safety standard evolution served as industry-specific forecast inputs.
Inputs from distributor channel partners and regulatory filing databases were available through the study window; gaps in real-time smart-device cybersecurity certification timelines introduce uncertainty bands around connected equipment adoption trajectories. Forecasts reflect documented assumptions regarding CE marking enforcement continuity and F-Gas Regulation phase-down schedules. Periodic stress-testing of base assumptions against nickel commodity volatility and apartment electrical infrastructure upgrade rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
UAE Alcohol E-Commerce Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Australia Alcohol E-Commerce Market
Alcoholic Beverages
Canada Tequila Market
Alcoholic Beverages
Rice Wine Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Wine Cellar Market
Alcoholic Beverages
White Spirits Market
Alcoholic Beverages
Cigar and Cigarillos Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Oak Barrel Alternatives Market