
 Fruit and Vegetable Cleaners Market | 2026-2036
Fruit and Vegetable Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable Cleaners Market Foresight
India is reconfiguring regional supply chains through expanded contract manufacturing for Asia-Pacific distribution. Procter & Gamble Company leverages its household brand equity to dominate retail shelf space in North American grocery channels. Earth Friendly Products LLC anchors its competitive stance through concentrated plant-derived formulations that appeal to environmentally certified food service operations. The Clorox Company sustains volume leadership through institutional procurement contracts with hospital and school cafeteria networks.
Fruit and vegetable cleaners comprise aqueous or solvent-based formulations containing surfactants, organic acids, and antimicrobial agents designed to remove pesticide residues, wax coatings, and microbial contaminants from raw produce surfaces. These products typically operate at pH ranges between 3.5 and 6.0 to preserve produce integrity while achieving log reduction in pathogen loads. Spray cleaners lead household adoption due to convenience-driven purchasing patterns, while soaking solutions capture margin pools in food processing facilities where immersion protocols are mandated. Gel formulations represent the fastest-growing category among hospitality sector buyers seeking controlled-dispense compliance with HACCP documentation requirements.
The EPA regulates antimicrobial claims on produce wash products through FIFRA registration requirements, while the FDA's Food Safety Modernization Act drives traceability standards that cleaner manufacturers must document in facility audits. Ecolab Inc. navigates this compliance landscape through integrated sanitation programs that bundle chemical supply with validation services. Stakeholders must monitor evolving state-level restrictions on quaternary ammonium compounds in organic-handling facilities, as these prohibitions are reshaping formulation roadmaps and certification pathways across multiple regulatory jurisdictions.
Market Dynamics
The EU's F-Gas Regulation and REACH compliance requirements are compressing formulation timelines and forcing surfactant suppliers to validate biodegradable alternatives before 2027 certification deadlines.
Growth Catalysts
- REACH chemical restrictions:The EU's phased ban on persistent organic pollutants in cleaning formulations creates replacement demand for citric acid and peracetic acid-based cleaners in German commercial kitchens.
- Hospitality sector protocols:Post-pandemic HACCP documentation mandates in hotel chains and restaurant groups are converting manual washing stations to metered dispensing systems.
- Electrolyzed water systems:On-site generation technology is reducing chemical transport costs for large-scale food processors in California's Central Valley agricultural corridor.
Market Restraints
- Coconut-derived surfactant volatility:Lauryl glucoside prices fluctuate with Philippine and Indonesian raw material harvest cycles, compressing margins for natural-formulation specialists.
- Quaternary ammonium compound restrictions:USDA organic handling prohibitions in 23 US states block antimicrobial claims for conventional hospital-grade cleaners.
- Validation timeline bottlenecks:EPA FIFRA registration requires 18-24 month efficacy studies against Salmonella and E. coli, freezing product launch schedules.
Strategic Opportunities
- India contract manufacturing expansion:Maharashtra and Gujarat production zones are capturing Asia-Pacific distribution contracts previously routed through Chinese surfactant suppliers.
- Gel format hospitality penetration:Controlled-dispense gel cartridges align with automated compliance logging systems in Dubai and Riyadh hotel chains.
- ISO 22000 convergence:Food safety management certification integration with cleaner validation protocols opens bundled service contracts in Brazilian meat processing facilities.
Industry Challenges
- Microbiologist talent scarcity:Log-reduction validation studies require specialized food safety personnel concentrated in Netherlands and Denmark research clusters.
- Legacy dispensing infrastructure:Retrofitting soaking tanks with IoT-enabled dosing systems in Midwest US canneries demands capital allocation competing with automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable Cleaners Market |
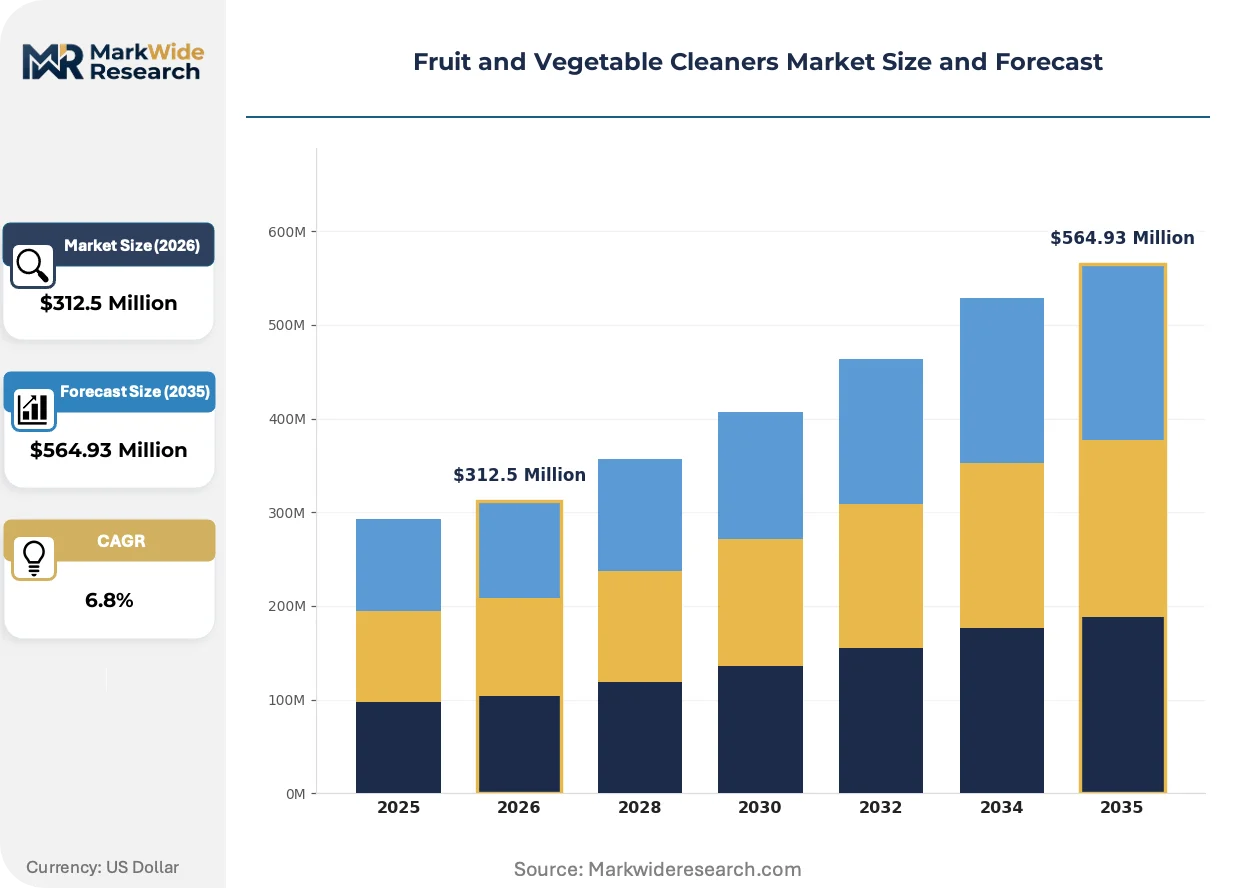
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Cleaners, Soaking Solutions, Wipes, Foam Cleaners, Gel Formulations Application: Home Use, Food Processing, Commercial Kitchens, Restaurants, Catering Services End User: Household Consumers, Food Manufacturers, Hospitality Sector, Institutional Buyers, Retail Chains Packaging Type: Bottles, Sachets, Pump Dispensers, Spray Cans, Refill Packs |
| Companies Covered | Procter & Gamble Company, Earth Friendly Products LLC, The Clorox Company, BioSafe Systems, LLC, Puracy, LLC, Ecolab Inc., ITC Limited, Seventh Generation Inc., Diversey Holdings, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable Cleaners Market Shifts & Advancements
Formulation chemistry and dispensing hardware are converging to create closed-loop systems where chemical efficacy and usage traceability become inseparable product attributes.
Peracetic acid and hydrogen peroxide blends are hybridizing with cold plasma surface treatment in premium produce processing lines. European salad packaging facilities in Spain and Italy are piloting these combinations to reduce water consumption while maintaining 5-log pathogen reduction standards. The technology is hybridizing equipment procurement decisions, forcing chemical suppliers to partner with plasma system manufacturers rather than selling standalone formulations.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon propellants is eliminating aerosol delivery formats for spray cleaners by 2030. German and French retailers are delisting conventional spray products ahead of schedule, redirecting shelf space toward trigger-bottle concentrates. Hospitality buyers in Munich and Paris are responding by installing bulk-fill dispensing stations that bypass single-use packaging entirely.
Food service distributors are unbundling chemical supply from equipment leasing agreements that previously locked buyers into multi-year surfactant contracts. Independent restaurant groups in Texas and Florida are sourcing cleaners through restaurant supply cooperatives, bypassing traditional broadline distributors. The shift is most visible in fast-casual chains where procurement authority has decentralized from corporate headquarters to regional franchise operators.
Fruit and Vegetable Cleaners Market Segmentation
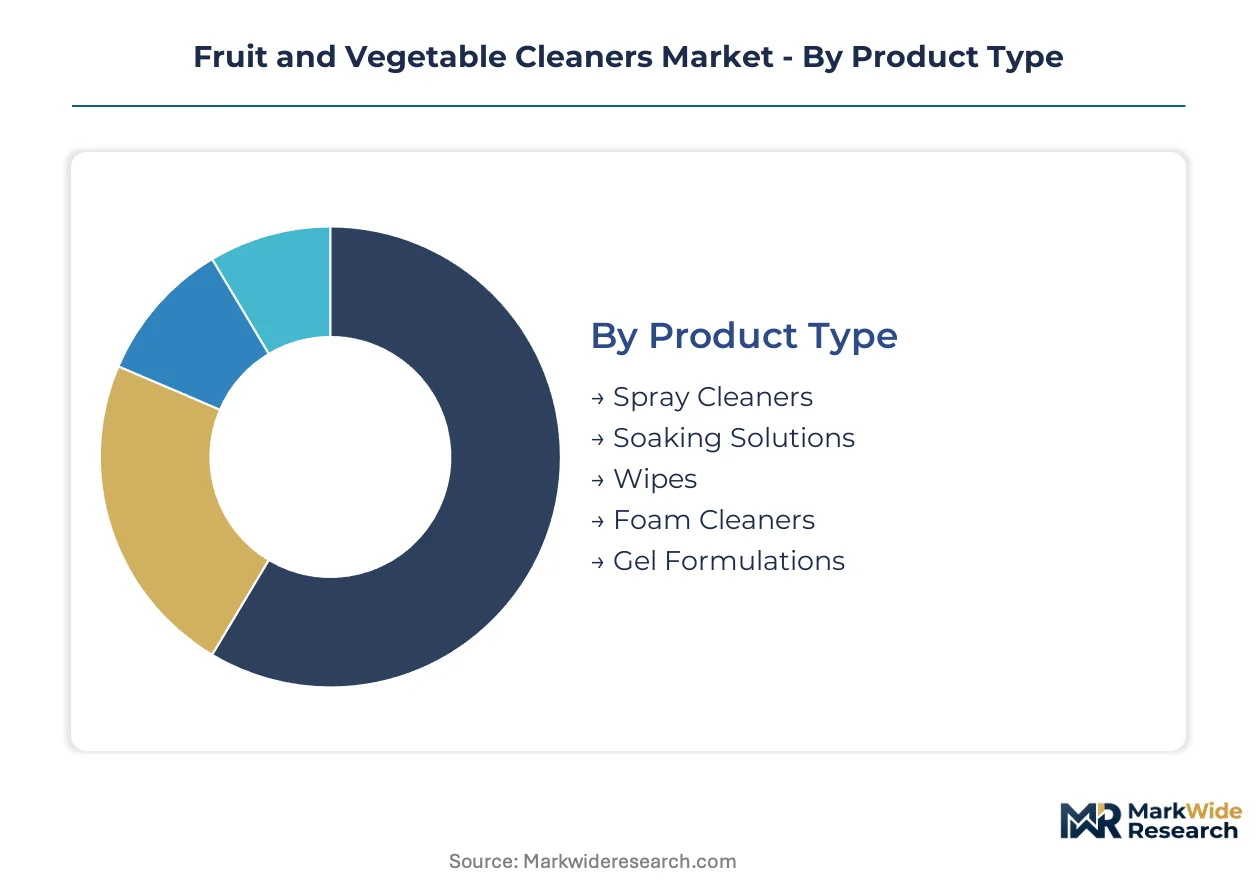
Segmentation in fruit and vegetable cleaners reflects divergent efficacy requirements across household convenience, commercial compliance, and industrial throughput. Formulation chemistry, dispensing format, and documentation capability vary sharply by end-use intensity.
Product Type:
Mature spray formats dominate retail shelf presence while emerging gel systems capture hospitality compliance budgets.
- Spray Cleaners:Aqueous formulations with surfactant-acid blends delivered through trigger mechanisms for direct surface application. German and French retailers are delisting aerosol variants ahead of F-Gas Regulation deadlines, redirecting volume toward trigger-bottle concentrates with refill compatibility.
- Soaking Solutions:Concentrated liquid formulations requiring dilution for immersion washing protocols in food processing facilities. California's Central Valley agricultural processors are adopting these for bulk produce washing where 5-log pathogen reduction is mandated.
- Gel Formulations:Viscous controlled-dispense systems enabling precise dosage logging for HACCP documentation. Dubai and Riyadh hotel chains are installing automated cartridge systems that integrate with compliance software.
- Wipes:Pre-moistened cellulose substrates impregnated with citric acid and peracetic acid for quick-turn produce prep in small commercial kitchens.
- Foam Cleaners:Expanding surfactant matrices for extended contact time on irregular produce surfaces in specialty food retail.
Spray cleaners handle the majority of throughput; gel formulations are expanding most quickly on share.
Application:
Cost tier separation runs from premium institutional protocols to economy household convenience.
- Home Use:Low-concentration formulations prioritizing sensory safety and packaging aesthetics for supermarket impulse purchase.
- Food Processing:High-throughput immersion systems requiring EPA FIFRA-registered antimicrobial claims and validated log-reduction documentation. Brazilian meat processing facilities are bundling ISO 22000 certification with cleaner supply contracts.
- Commercial Kitchens:Metered dispensing installations in hotel chains and restaurant groups subject to post-pandemic HACCP documentation mandates. Munich and Paris hospitality buyers are deploying bulk-fill stations to eliminate single-use packaging.
- Restaurants:Independent operators in Texas and Florida are sourcing through supply cooperatives, bypassing traditional broadline distributor lock-in.
- Catering Services:Mobile preparation units requiring portable wipe and spray formats with rapid reconstitution capability.
Food processing commands the highest formulation standards; commercial kitchens are gaining share fastest.
End User:
Customer type determines procurement authority concentration versus fragmentation.
- Household Consumers:Price-sensitive retail purchasers influenced by shelf placement and brand recognition in grocery channels.
- Food Manufacturers:Technical buyers conducting 18-24 month EPA validation studies before supplier qualification.
- Hospitality Sector:Procurement decentralization to regional franchise operators in fast-casual chains is unbundling chemical supply from equipment leases.
- Institutional Buyers:Hospital and school cafeteria networks sustaining volume through multi-year procurement contracts with documentation requirements.
- Retail Chains:Private-label development programs in European markets seeking REACH-compliant biodegradable surfactant formulations.
Food manufacturers absorb the longest validation timelines; hospitality sector procurement is climbing the fastest.
Packaging Type:
Volume scale separates industrial bulk from single-serve convenience formats.
- Bottles:Standard HDPE and PET containers for retail distribution, with concentrate ratios rising to reduce transport intensity.
- Refill Packs:Flexible pouches enabling closed-loop dispensing systems in institutional settings with sustainability mandates.
- Pump Dispensers:Controlled-volume mechanisms for commercial kitchen hand-wash stations and produce prep sinks.
- Sachets:Single-dose formats for food service travel kits and emergency sanitation protocols.
- Spray Cans:Aerosol delivery facing phaseout under EU F-Gas Regulation, with remaining demand concentrated in non-European markets.
Bottles retain the largest installed base; refill packs are ascending the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA FIFRA registration requirements in the United States anchor the regulatory framework that shapes formulation validation timelines across the industry. Germany's REACH compliance deadlines and commercial kitchen certification standards drive premium product development in European markets. India's contract manufacturing expansion is reconfiguring Asia-Pacific supply chains.
United States
California's Central Valley agricultural processors command immersion washing protocols for bulk produce handling. EPA FIFRA registration mandates 18-24 month efficacy studies against Salmonella and E. coli before antimicrobial claims approval. Midwest canneries face capital allocation decisions between IoT-enabled dosing retrofits and broader automation upgrades.
Germany
Munich and Paris hospitality buyers deploy bulk-fill dispensing stations to eliminate single-use packaging from produce prep operations. The EU F-Gas Regulation phases down hydrofluorocarbon propellants, forcing aerosol format delistings ahead of 2030 deadlines. REACH chemical restrictions on persistent organic pollutants create replacement demand for citric acid and peracetic acid formulations in commercial kitchens.
India
Maharashtra and Gujarat production zones capture Asia-Pacific distribution contracts previously routed through Chinese surfactant suppliers. FSSAI food safety standards align with international HACCP documentation requirements for export-oriented processors. Contract manufacturers in these states serve hospitality sector buyers across Southeast Asian markets.
Brazil
Meat processing facilities in São Paulo and Minas Gerais bundle ISO 22000 certification with cleaner supply contracts for validated sanitation programs. ANVISA regulates antimicrobial claims on produce wash products through registration requirements comparable to EPA frameworks. Food safety management certification integration opens bundled service contracts in the country's protein processing corridor.
United Arab Emirates
Dubai and Riyadh hotel chains install automated gel cartridge systems that integrate with HACCP compliance software for produce preparation documentation. MOHAP food safety protocols align with international hospitality standards for commercial kitchen operations. The Gulf Cooperation Council's procurement centralization in hospitality groups drives metered dispensing system adoption.
Fruit and Vegetable Cleaners Market Competitive Landscape
Capability concentration sits with formulation specialists holding EPA FIFRA registrations and validated log-reduction documentation; scale advantage sits with diversified household chemical manufacturers with retail shelf access. The market structures around three tiers: institutional sanitation integrators bundling chemical supply with validation services, retail brand owners leveraging grocery channel relationships, and natural-formulation specialists serving certified organic handling facilities. Dominant competitive moves include geographic expansion through contract manufacturing partnerships and portfolio diversification into concentrated refill formats.
Among institutional sanitation providers, Ecolab Inc. and Diversey Holdings, Ltd. occupy positions emphasizing integrated service bundling. Within the natural-formulation tier, Earth Friendly Products LLC exemplifies plant-derived positioning for environmentally certified food service operations. Procter & Gamble Company anchors the retail-centric archetype through household brand equity and grocery channel dominance.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Earth Friendly Products LLC |
| The Clorox Company |
| BioSafe Systems, LLC |
| Puracy, LLC |
| Ecolab Inc. |
| ITC Limited |
| Seventh Generation Inc. |
| Diversey Holdings, Ltd. |
| Others |
Supply & Pricing Matrix
Philippine and Indonesian lauryl glucoside harvest cycles tether margin stability to surfactant procurement timing, concentrating value capture with formulation specialists who hedge raw material exposure through long-term supply contracts. Buyers in Germany's commercial kitchen certification tier absorb premium pricing for REACH-compliant biodegradable alternatives, while price-sensitive household segments in North American grocery channels compress margins through private-label substitution.
Pricing Analysis
Geographic price spreads separate German REACH-compliant formulations from economy-grade alternatives in Indian contract manufacturing zones. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EPA FIFRA-registered antimicrobial claims commanding substantial premiums over generic surfactant blends. Price differentiation stems from validation documentation requirements and volume scale procurement. Cost compression in natural-formulation tiers is intensifying because coconut-derived surfactant harvest volatility feeds through to input costs. Household consumers exhibit highest price sensitivity; institutional buyers with multi-year procurement contracts demonstrate lowest.
Supply Chain Analysis
Extended payment terms from Maharashtra and Gujarat contract manufacturers to Southeast Asian hospitality distributors are restructuring working capital requirements across Asia-Pacific distribution networks. Supply concentrates in India, China, and Germany for surfactant intermediates and finished formulation blending. Raw material dependencies center on coconut-derived lauryl glucoside, citric acid feedstocks, and peracetic acid precursors. Single-source vulnerability in Philippine coconut harvests threatens natural-formulation specialists. Distribution runs through food service broadline distributors, restaurant supply cooperatives, and direct institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fruit and vegetable cleaners market reads as a service-attach opportunity where validation documentation and compliance software integration expand recurring revenue faster than standalone chemical formulations. Bundled sanitation programs with HACCP logging capabilities are displacing transactional chemical supply.
For Market Incumbents: Pre-empt electrolyzed water on-site generation technology by acquiring cold plasma equipment partnerships before chemical-formulation commoditization accelerates. Defend margin position through backward integration into citric acid and peracetic acid feedstock supply. Capacity addition in Maharashtra and Gujarat production zones secures Asia-Pacific distribution control against contract manufacturing competitors. For New Entrants and Emerging Players: Build out gel formulation controlled-dispense systems targeting Dubai and Riyadh hotel chains where automated compliance logging creates switching costs. Underpenetrated white-space sits with independent restaurant groups in Texas and Florida sourcing through supply cooperatives outside traditional broadline distributor networks. Fast-casual regional franchise operators represent the most penetrable buyer archetype. Go-to-market angle: restaurant supply cooperative partnerships bypassing corporate headquarters procurement centralization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed institutional sanitation providers bundling chemical supply with validation services. Five-to-ten year viability hinges on regulatory compliance documentation becoming embedded in food safety management certification. Acquisition target archetype: natural-formulation specialists with FSSAI-aligned export capabilities serving Southeast Asian hospitality markets. Signal to watch: state-level quaternary ammonium compound restrictions expanding beyond current 23-state USDA organic handling prohibitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstocks | Coconut-derived lauryl glucoside supply hedging insulates margins from Philippine harvest volatility. |
| Gel Format Controlled-Dispense Development | HACCP documentation integration with Dubai hotel chain compliance software creates recurring revenue attachment. |
| Contract Manufacturing Expansion in India | Maharashtra and Gujarat production zones capture Asia-Pacific distribution from Chinese surfactant suppliers. |
| Cold Plasma Equipment Partnership | European salad packaging facilities in Spain and Italy pilot hybrid chemical-surface treatment combinations. |
| ISO 22000 Certification Bundling | Brazilian meat processing facilities in São Paulo integrate food safety management with cleaner validation protocols. |
Research Methodology
Initial hypotheses were tested against primary input from food safety managers at hospitality chains, procurement leads at institutional cafeteria networks, plant managers at agricultural processing facilities, and technical directors at surfactant manufacturers and refined through secondary validation. FDA FIFRA registration databases, ECHA REACH compliance filings, customs trade data on surfactant imports, and FSSAI food safety standard documentation provided foundational benchmarks. Bottom-up demand modeling across end-use segments triangulated with top-down supply-side capacity assessments.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application intensity, end-user procurement authority concentration, and packaging sustainability tier. CAGRs derived from segment-level growth trajectory synthesis weighted by regulatory compliance timeline acceleration. Forecast inputs incorporated EPA validation study bottlenecks, EU F-Gas Regulation phase-down schedules, and coconut harvest cycle volatility patterns.
Sensitivities concentrate around REACH chemical restriction expansion, quaternary ammonium compound prohibition spread, and electrolyzed water technology adoption curves. Forecasts reflect documented assumptions on regulatory enforcement timing and hospitality sector HACCP mandate penetration. Macroeconomic contraction in food service spending, accelerated F-Gas Regulation enforcement, or breakthrough cold plasma cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Starchy Roots Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Passion Fruit Extract Market