
 Champagne Market | 2026-2036
Champagne Market Size, Share, and Industry Trends Forecast 2026-2036
Champagne Market Intelligence
The European Union's Appellation d'Origine Contrôlée (AOC) framework is consolidating market power among established houses with significant vineyard holdings. Louis Vuitton SE leverages its extensive portfolio of prestige brands to command premium pricing tiers. Pernod Ricard competes through its global distribution network, while Laurent-Perrier differentiates with its focus on specific cuvée styles. These large players navigate the strict production quotas and land costs that define the region's competitive landscape.
Champagne is a sparkling wine produced exclusively within the Champagne wine region of France, following specific viticultural and winemaking rules. The secondary fermentation process, known as 'méthode champenoise', creates its characteristic carbonation and fine bubbles. Brut styles dominate sales volume due to their versatility, while vintage expressions represent a high-margin, premium category. The on-premise service channel, including restaurants and events, is a critical arena for brand building, contrasting with volume-driven off-premise retail.
The Comité Champagne (CIVC) strictly governs production yields, grape sourcing, and marketing, preserving the appellation's integrity. In export markets, bodies like the US Alcohol and Tobacco Tax and Trade Bureau (TTB) enforce labeling laws that protect the term 'Champagne' from misuse. Producers must now navigate evolving consumer preferences for sustainability and lower-dosage styles while upholding centuries-old production standards.
Market Dynamics
The central dynamic is the tension between a geographically constrained supply, governed by the Comité Champagne (CIVC), and expanding global luxury demand. This scarcity, enforced by strict appellation rules, dictates market structure and pricing power across all channels.
Growth Catalysts
- Premiumization in Key Markets:Rising disposable incomes in countries such as the United States and Japan are driving demand for luxury goods, with Champagne serving as a key status symbol in on-premise and celebratory contexts.
- E-commerce and Direct-to-Consumer Channels:The expansion of specialized online wine retailers and producer-led DTC platforms is improving accessibility and brand engagement for consumers, bypassing traditional three-tier distribution bottlenecks in some regions.
- Diversification of Product Styles:Growing consumer interest in rosé and lower-dosage (Brut Nature) expressions creates new product categories, attracting a wider demographic beyond traditional Brut Champagne drinkers.
Market Restraints
- Finite Vineyard Land:The strictly demarcated Champagne AOC region has limited land available for vineyard expansion, creating intense competition for grapes and driving up raw material costs for all producers.
- Strict Production Quotas:The Comité Champagne (CIVC) imposes annual yield limits per hectare, constraining total production volume regardless of global demand and limiting producers' ability to scale output quickly.
- Competition from High-Quality Sparkling Wines:The rising quality of other traditional method sparkling wines, such as English Sparkling Wine and Italian Franciacorta, presents a credible substitution threat in key export markets.
Strategic Opportunities
- Luxury Hospitality in Southeast Asia:Expanding luxury hotel and resort development in countries like Vietnam and Thailand presents a significant opportunity for on-premise channel growth and brand-building among new affluent consumers.
- Sustainability Certification as a Differentiator:Highlighting organic, biodynamic, or HVE (Haute Valeur Environnementale) certifications can attract environmentally conscious consumers, particularly in markets across Scandinavia and North America.
- Experiential Wine Tourism:Developing curated, high-end tourism experiences within the Champagne region can build brand loyalty and create a direct, high-margin sales channel with affluent global consumers.
Industry Challenges
- Climate Change Adaptation:Producers face the operational challenge of adapting viticultural practices, such as harvest timing and grape varietal management, to mitigate the effects of rising temperatures and unpredictable weather in the Champagne region.
- Navigating Complex Export Logistics:Managing varied import duties, labeling laws enforced by bodies like the US TTB, and cold chain logistics for distant markets like Australia adds significant operational complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Champagne Market |
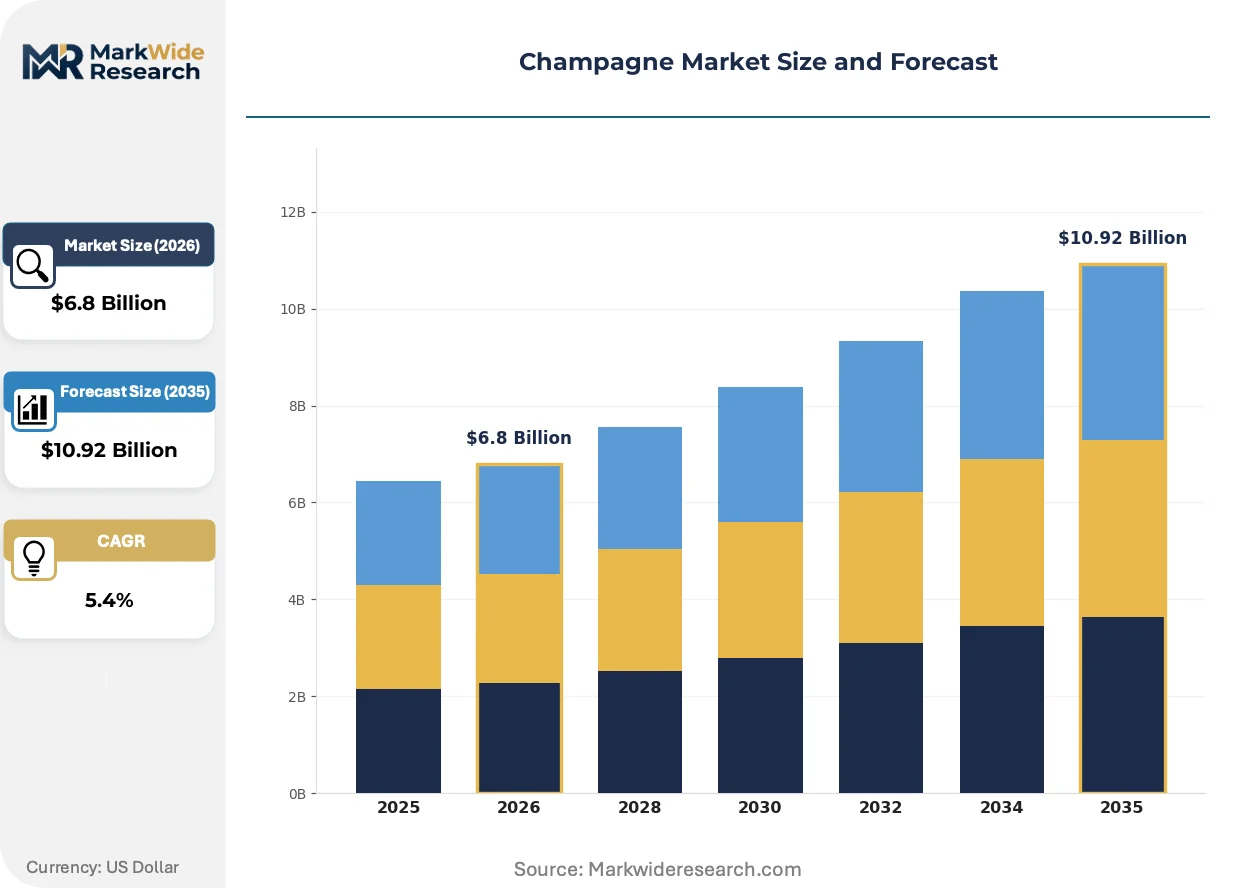
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brut, Demi-Sec, Extra Dry, Vintage Packaging Type: Bottle, Can, Tetra Pak, Bag-in-Box Service Type: On-Premise, Off-Premise, E-Commerce, Events End User: Restaurants, Retailers, Distributors, Online Consumers |
| Companies Covered | Moët & Chandon, Lanson-BCC, Louis Vuitton SE, Louis Roederer, Bollinger, Pernod Ricard, Laurent-Perrier, Krug, Henkell Freixenet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Champagne Market Strategic Shifts & Innovations
Producers are balancing centuries-old traditions with modern commercial and environmental pressures. This involves integrating new technologies for vineyard management and winemaking while responding to evolving global regulations and consumer expectations for transparency.
Digital viticulture technology, including soil sensors and drone imagery, provides granular data on vineyard parcels. Larger Champagne houses and forward-thinking growers adopt these tools to optimize resource use and grape quality. This data-driven approach is decentralizing decision-making from traditional cellar master intuition to a more empirical, plot-by-plot management system.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling large Champagne producers to provide extensive disclosures on environmental and social impacts. This regulation mandates detailed reporting on water usage, biodiversity, and labor practices throughout the supply chain. Large Champagne houses with significant global exports are most affected, investing in systems to track and verify their sustainability claims.
Consumption patterns are shifting from exclusive use in formal fine dining towards more accessible luxury experiences. This disrupts reliance on traditional high-end restaurant channels, giving rise to dedicated Champagne bars, premium airport lounges, and brand-led pop-up events. This trend is particularly pronounced in major urban centers like London, New York, and Tokyo, where consumers seek unique, shareable moments.
Champagne Market Segmentation
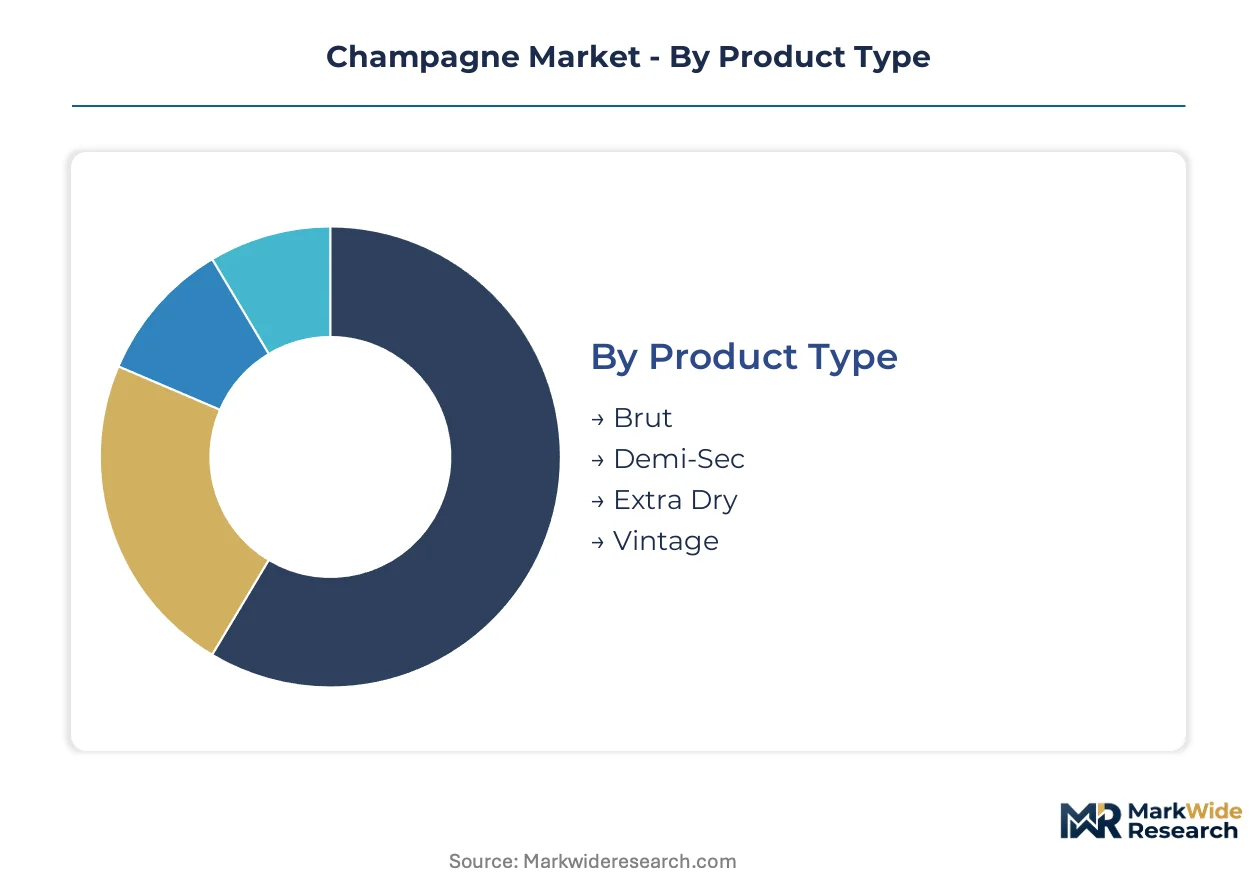
Segmentation analysis reveals the diverse avenues through which Champagne reaches consumers and the various product characteristics driving purchasing decisions. Understanding these distinct market components allows producers and distributors to tailor their strategies effectively. This market operates across multiple channels and product formats, catering to a wide range of consumer preferences and occasions.
Product Type:
The Champagne market exhibits a clear bifurcation between high-volume, accessible styles and premium, age-worthy expressions, influencing both pricing and consumer perception.
- Brut:This is the most common Champagne style, characterized by its dry profile with less than 12 grams of residual sugar per liter. Demand concentrates in global on-premise channels, particularly restaurants and events, due to its versatility and broad appeal.
- Vintage:Produced only in exceptional years from grapes harvested in a single year, reflecting the unique characteristics of that harvest. These command premium pricing in markets like the United States and Japan, driven by collector interest and perceived exclusivity.
- Demi-Sec:This style features a higher sugar content, typically between 32 and 50 grams per liter, offering a sweeter profile. It attracts consumers seeking dessert pairings or a less dry sparkling wine experience.
- Extra Dry:Despite its name, Extra Dry Champagne contains slightly more sugar than Brut, ranging from 12 to 17 grams per liter. This style appeals to a niche segment desiring a softer entry than traditional Brut.
Today's leader: Brut. Tomorrow's challenger: Vintage.
Packaging Type:
Packaging formats reflect both traditional presentation and evolving consumer convenience, with supply concentration heavily favoring established bottling methods.
- Bottle:Traditional glass bottles, primarily 750ml, remain the standard for Champagne, preserving its quality and prestige through controlled aging. Distribution heavily relies on established retail and on-premise channels, where its classic presentation reinforces brand value.
- Can:Smaller format aluminum cans represent an emerging trend, offering portability and single-serve convenience for casual consumption occasions. Demand for this innovative packaging is slowly gaining traction among younger consumers in urban centers like London and New York.
- Tetra Pak:Multi-layered cardboard packaging designed for shelf stability and reduced environmental impact, though rarely used for premium Champagne. This format is more common for other sparkling wines.
- Bag-in-Box:A flexible bag inside a cardboard box, offering volume and cost efficiency, but fundamentally incompatible with Champagne's secondary fermentation and pressure requirements. This packaging is not suitable for authentic Champagne.
Bottle formats maintain market dominance, while Can formats show the steepest expansion trajectory in niche convenience segments.
Service Type:
Service types differentiate significantly by margin potential and brand-building opportunity, influencing producer engagement strategies.
- On-Premise:This channel includes restaurants, bars, hotels, and clubs, where Champagne is consumed directly at the point of sale. It provides critical brand visibility and higher per-unit margins, particularly in luxury hospitality venues in Southeast Asia.
- Off-Premise:Comprising retail stores, supermarkets, and specialized wine shops, this channel focuses on volume sales for home consumption. It serves as the primary distribution route for accessible Champagne styles, driven by consumer convenience and competitive pricing.
- E-Commerce:Online platforms and direct-to-consumer sales provide increasing accessibility for consumers to purchase Champagne directly. This channel bypasses traditional distribution layers, offering brand engagement and convenience.
- Events:Catering services, private parties, and corporate functions represent dedicated occasions for Champagne consumption. This segment emphasizes celebratory contexts and often involves bulk purchasing for specific events.
On-Premise remains a crucial channel for brand building, with E-Commerce gaining share fastest due to improved accessibility.
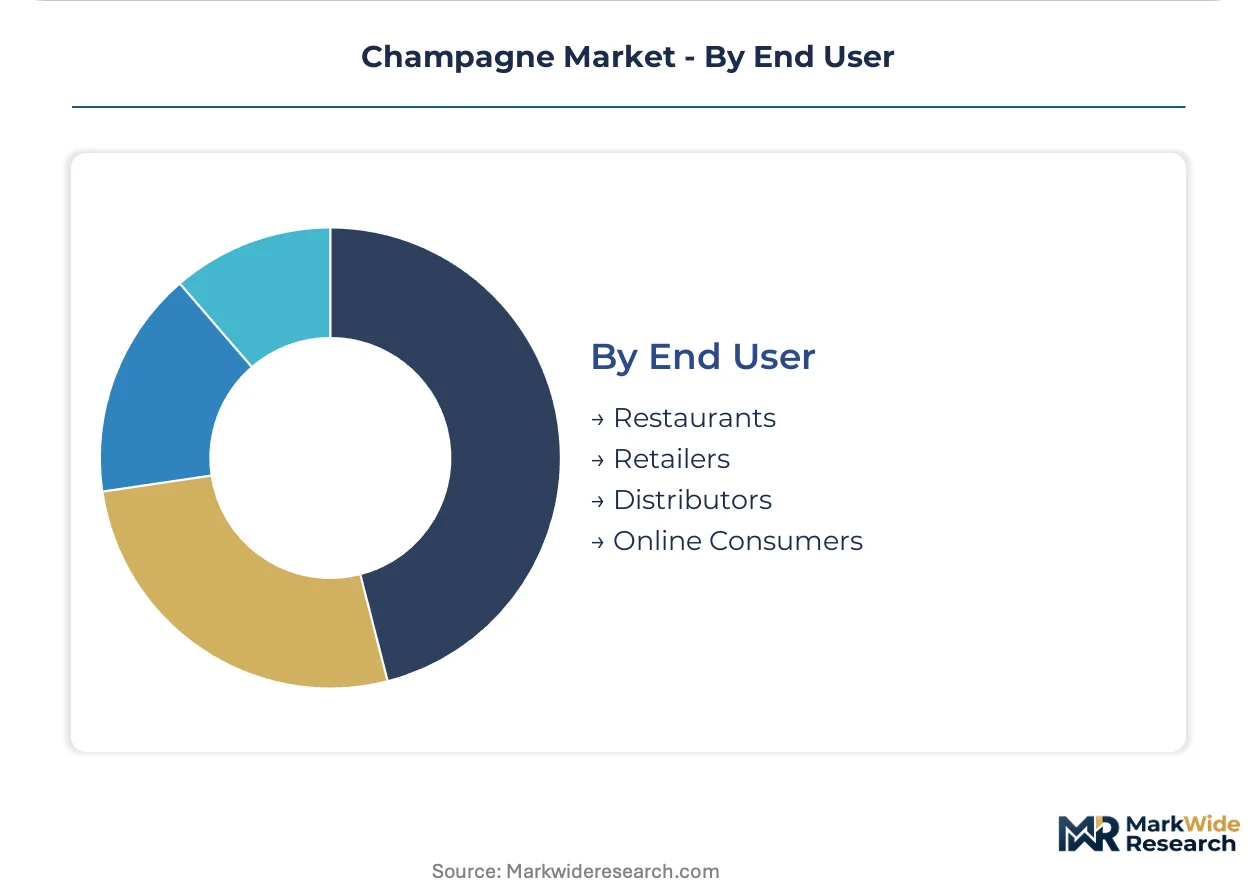
End User:
End user segmentation highlights the diverse customer base for Champagne, from commercial entities to individual consumers.
- Restaurants:Fine dining establishments and casual eateries serve Champagne to patrons for immediate consumption, often pairing it with specific cuisines. These establishments prioritize supplier reliability and brand prestige to enhance their guest experience.
- Retailers:Supermarkets, liquor stores, and specialty wine shops purchase Champagne in bulk for resale to individual consumers. Retailers focus on inventory management and competitive pricing to meet diverse consumer demand for various Champagne styles.
- Distributors:These intermediaries manage the logistics and sales of Champagne from producers to various retail and on-premise outlets. Distributors play a crucial role in market penetration and supply chain efficiency.
- Online Consumers:Individuals purchasing Champagne directly through e-commerce platforms for personal consumption or gifting. This segment values convenience, product variety, and direct delivery services.
Restaurants represent a premium end-user segment, while Online Consumers are climbing the fastest in purchasing volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled sommelier and hospitality workforce anchors demand for luxury beverages across key urban centers globally. This expertise drives consumer education and premiumization trends in the Champagne market. Such talent concentrations are critical for brand building within high-end on-premise channels.
United States
Rising disposable incomes in the United States drive significant demand for luxury goods, including Champagne, particularly for celebratory contexts. The US Alcohol and Tobacco Tax and Trade Bureau (TTB) rigorously enforces labeling laws to prevent misuse of the term 'Champagne'. Urban centers such as New York, Los Angeles, and Miami show strong demand for premium and vintage expressions.
United Kingdom
Strong consumer interest in premium sparkling wines supports robust Champagne consumption across the United Kingdom. The UK's Wine and Spirit Trade Association (WSTA) provides industry guidance for responsible alcohol sales and marketing practices. London remains a central hub for Champagne consumption, boasting a vibrant on-premise sector and specialized retailers.
Japan
Japan's sophisticated consumer base highly values Champagne's prestige and quality, driving demand for premium and vintage styles. The National Tax Agency in Japan regulates alcohol production and sales, ensuring adherence to strict quality and labeling standards. Tokyo's high-end restaurants, luxury hotels, and department stores form a significant consumption cluster.
Vietnam
Expanding luxury hospitality in Southeast Asia, particularly Vietnam, fuels new market growth for Champagne. Vietnam's Ministry of Industry and Trade oversees import regulations for alcoholic beverages, impacting distribution channels. Ho Chi Minh City and Hanoi increasingly witness Champagne consumption in upscale hotels, fine dining establishments, and private events.
Australia
Australia's strong wine culture and a preference for premium beverages characterize its Champagne market. The Department of Agriculture, Water and the Environment manages import requirements and labeling standards for wine products entering Australia. Sydney and Melbourne serve as key urban centers for Champagne sales, especially in high-end restaurants and bars.
Champagne Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists to capture market share in the Champagne industry. The market structure exhibits a tiered consolidation, with large luxury groups operating alongside numerous independent houses. Strategic archetypes include global beverage giants, prestige brand portfolio holders, and craft-oriented boutique producers. Companies engage in brand building, global distribution network expansion, and targeted marketing campaigns to strengthen their positions across various consumer segments.
Within the portfolio-driven segment, Louis Vuitton SE exemplifies a luxury conglomerate leveraging an extensive brand portfolio to command premium pricing tiers. Pernod Ricard, a global spirits and wine company, occupies a position anchored by its expansive international distribution network, enabling broad market penetration. Laurent-Perrier represents a specialist house, differentiating its offerings through a focused approach on specific cuvée styles and heritage, appealing to discerning consumers. These players collectively shape the market's competitive dynamics by influencing pricing, distribution, and product innovation.
| Leading Market Players |
|---|
| Moët & Chandon |
| Lanson-BCC |
| Louis Vuitton SE |
| Louis Roederer |
| Bollinger |
| Pernod Ricard |
| Laurent-Perrier |
| Krug |
| Henkell Freixenet |
| Others |
Cost & Logistics Intelligence
Digital viticulture technology adoption reshapes cost economics by optimizing resource use and grape quality, influencing supply concentration among producers. This technology enables more precise vineyard management, impacting raw material costs and production efficiency.
Pricing Analysis
Bundled service offerings from luxury hotels command higher per-unit prices for Champagne, contrasting with unbundled retail sales. The dominant pricing model is per-unit transactional, with premium-mid-economy pricing differentiation. Product authenticity, vintage exclusivity, and brand prestige drive price differentiation. Pricing softness stems from competition from high-quality sparkling wines in export markets. Online consumers are most price-sensitive, while luxury hospitality venues in Southeast Asia are least sensitive.
Supply Chain Analysis
Strict Protected Designation of Origin (PDO) certification gates entry into the Champagne supply chain, concentrating primary production in France. Raw material dependencies center on specific grape varietals like Chardonnay, Pinot Noir, and Pinot Meunier, alongside specialized glass bottles. Finite vineyard land and strict production quotas create a structural logistics chokepoint. Distribution runs through a three-tier system in many markets, involving distributors, retailers, and on-premise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
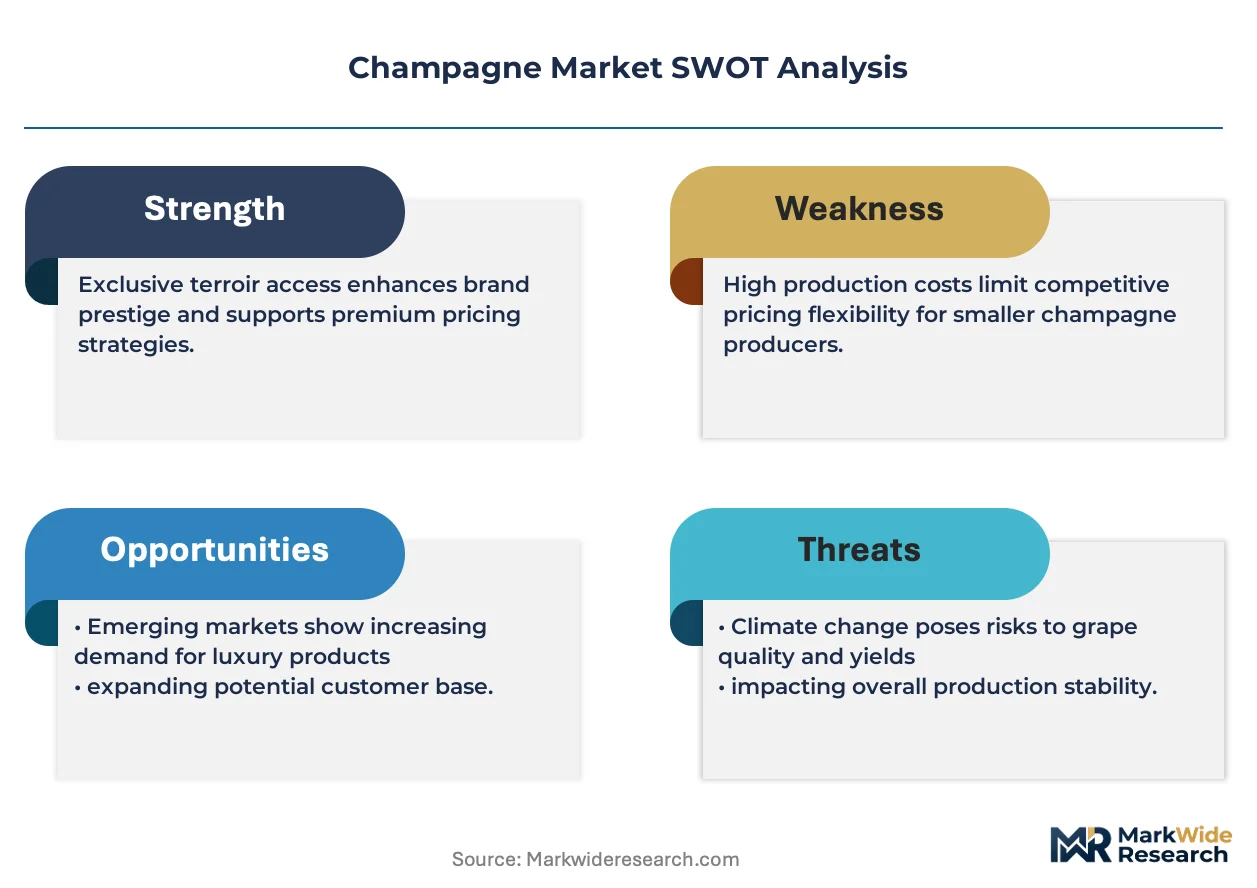
The Champagne market presents a late-cycle quality story, driven by a pronounced demand-shift towards premium and vintage expressions. Consumers increasingly seek authenticity and exclusivity, elevating the importance of heritage and terroir.
For Market Incumbents: Hedge against climate change impacts by investing in adaptive viticultural practices and drought-resistant varietals. Consolidate vineyard holdings within the Champagne AOC to secure grape supply amidst rising land costs. Diversify product portfolios with lower-dosage styles to appeal to evolving consumer preferences, countering competition from other premium sparkling wines. Emphasize HVE (Haute Valeur Environnementale) certifications to reinforce brand premium and address sustainability concerns.
For New Entrants and Emerging Players: Capture niche segments by focusing on organic or biodynamic production, targeting environmentally conscious consumers in Scandinavia and North America. Penetrate emerging markets in Southeast Asia through strategic partnerships with luxury hospitality groups. Differentiate with innovative packaging formats like single-serve cans for casual consumption occasions in urban centers. Leverage e-commerce platforms for direct-to-consumer sales, bypassing traditional distribution bottlenecks and building brand engagement.
For Investors and Strategic Acquirers: Valuations sit cheapest among smaller, independent Champagne houses with significant vineyard assets but limited global distribution. Long-term viability hinges on securing access to prime vineyard parcels within the appellation. Acquisition targets should focus on producers with strong sustainability credentials or unique cuvée styles. A signal to watch is the increasing institutional investment in Champagne land, indicating future supply constraint premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Vineyard Acquisition | Secures raw material supply and protects against rising land costs within the AOC. |
| Sustainability Certification | Attracts environmentally conscious consumers and enhances brand reputation in key markets. |
| E-commerce Channel Expansion | Improves direct consumer access and builds brand loyalty beyond traditional retail. |
| Luxury Hospitality Partnerships | Drives on-premise visibility and premium positioning in high-growth regions. |
| Digital Viticulture Adoption | Optimizes resource use and grape quality, enhancing production efficiency and yield stability. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. The study engaged industry stakeholders including cellar masters, export managers, luxury hotel F&B directors, and specialized wine retailers. Secondary data sources included the Comité Champagne annual reports, US TTB filings, and EU trade statistics, triangulated with market intelligence reports. This approach ensured robust bottom-up and top-down data validation.
Segment-weighting across product type, packaging format, service channel, and end-user categories formed the analytical framework over the projection horizon. The model incorporated historical consumption trends, macroeconomic indicators, and regulatory changes in key export markets. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included disposable income growth in luxury markets and global tourism recovery rates.
Climate change impacts, global economic downturns, and shifts in regulatory frameworks are the dominant revision risks for market forecasts. Forecasts reflect assumptions documented at the time of analysis. A model refresh is warranted upon material change in appellation rules or major consumer preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Craft Beer Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
North America Soju Market
Alcoholic Beverages
Brandy Market
Alcoholic Beverages
Alcohol-Free Pineapple Beer Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Europe Tequila Market
Alcoholic Beverages
Cannabis-Based Alcoholic Beverages Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Beer Stabilizers Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
United States Beer Market