
 Non-Alcoholic Spirits Market | 2026-2036
Non-Alcoholic Spirits Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Alcoholic Spirits Market Outlook
Subscription-based replenishment services is decoupling bottle sales from traditional retail velocity in the non-alcoholic spirits category. Lyre's Spirit Co leverages direct-to-consumer membership tiers to sustain recurring revenue outside conventional liquor stores. Diageo plc anchors its Seedlip and Tanqueray 0.0% lines through controlled distribution in premium hospitality channels. Ritual Zero Proof competes by occupying the whiskey-alternative niche with concentrated flavor formulations designed for bartender utility.
Non-alcoholic spirits are distilled or compounded beverages formulated to replicate the sensory profile of traditional spirits while containing negligible ethanol, typically below 0.5% ABV, achieved through vacuum distillation, maceration of botanicals, or reverse osmosis followed by reconstitution; their primary commercial purpose is to serve as mixology foundations for consumers and venues seeking sophisticated drinking experiences without alcohol consumption. Botanical and spiced product types lead current volume as established flavor architectures transfer directly from gin and amaro traditions, while citrus profiles represent the fastest-growing segment as bartenders seek bright, acidic components for complex zero-proof builds. Bottle packaging dominates premium positioning and gift occasions, though can formats are gaining traction in on-premise trial settings where speed-of-service matters.
The U.S. FDA governs alcohol-by-volume thresholds and labeling claims, while the U.K. Food Standards Agency enforces strict compositional standards that determine whether products qualify for reduced-tax treatment, and the EU's Food Information to Consumers regulation mandates precise allergen disclosure for botanical ingredients that shapes formulation choices across export markets. Stakeholders must monitor how divergent national definitions of "non-alcoholic" create compliance fragmentation that favors multi-market operators with dedicated regulatory affairs capacity over single-territory entrants.
Market Dynamics
Subscription-based replenishment services are decoupling bottle sales from traditional retail velocity in the non-alcoholic spirits category, forcing brands to build recurring revenue infrastructure outside conventional liquor stores.
Growth Catalysts
- Zero-proof cocktail programs:Premium hotel chains and upscale restaurants across North America are expanding dedicated alcohol-free menus, creating pull-through demand for bartender-ready formulations.
- EU Food Information to Consumers regulation:Mandatory allergen disclosure for botanical ingredients is standardizing formulation transparency across export markets, reducing cross-border compliance friction.
- Vacuum distillation adoption:This extraction technology preserves volatile aromatic compounds at low temperatures, enabling flavor fidelity that maceration methods cannot replicate.
Market Restraints
- Botanical supply concentration:Juniper, cardamom, and cassia sourcing clusters in specific growing regions create input cost volatility and harvest risk exposure.
- Reverse osmosis capex barriers:Small-scale entrants face prohibitive equipment costs for ethanol separation, concentrating production capacity among well-capitalized operators.
- U.S. FDA labeling friction:Evolving alcohol-by-volume thresholds and claim restrictions create formulation uncertainty that delays product launches.
Strategic Opportunities
- Can format trial channels:On-premise venues seeking speed-of-service are adopting single-serve packaging for zero-proof builds, opening distribution outside premium bottle retail.
- Citrus profile acceleration:Bartenders demand bright, acidic components for complex alcohol-free cocktails, creating whitespace beyond established botanical and spiced architectures.
- U.K. reduced-tax qualification:The Food Standards Agency's strict compositional standards reward compliant formulations with favorable excise treatment, incentivizing reformulation investment.
Industry Challenges
- Flavor chemist scarcity:Formulating convincing spirit analogs requires rare expertise in volatile compound interaction and sensory masking techniques.
- Multi-territory compliance fragmentation:Divergent national definitions of "non-alcoholic" force single-territory entrants to abandon cross-border expansion or absorb dedicated regulatory affairs costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Alcoholic Spirits Market |
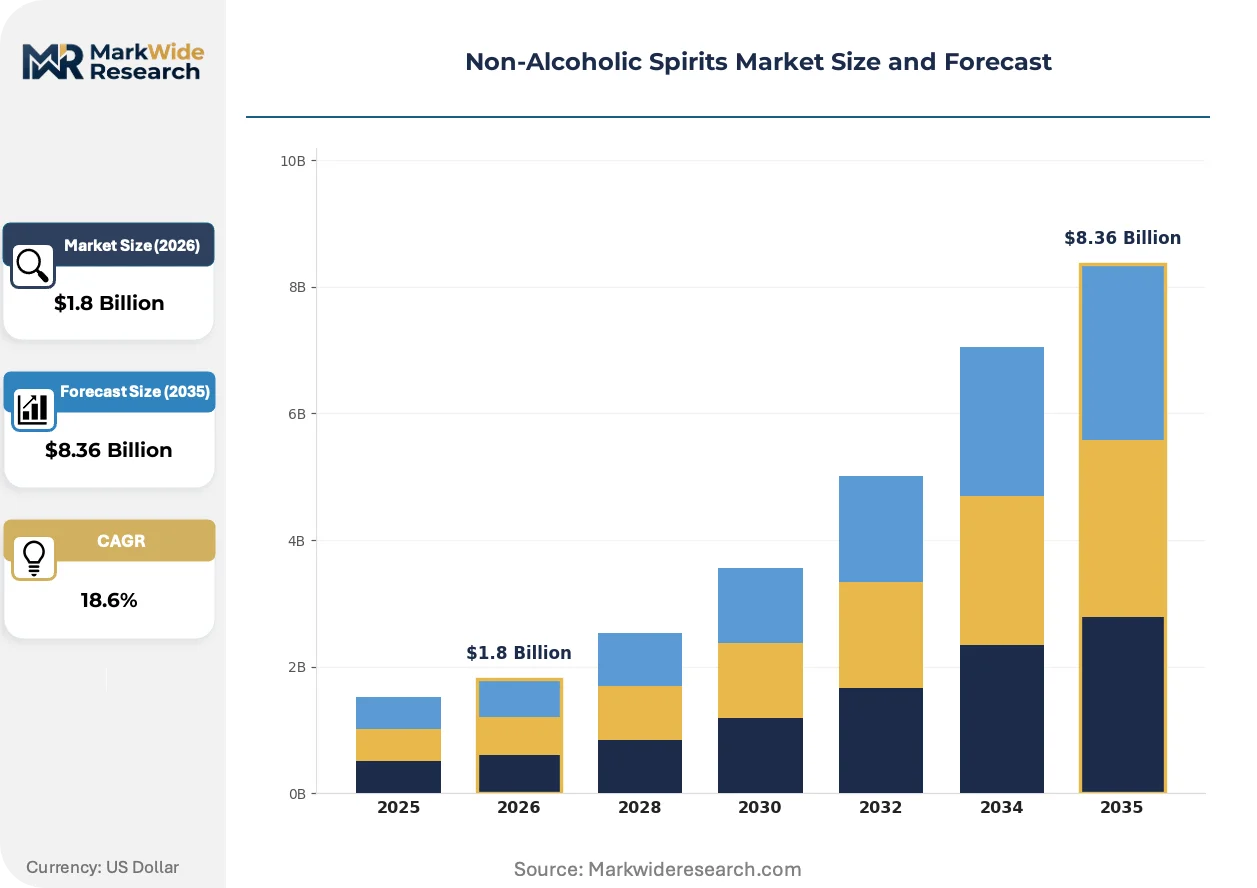
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiced, Botanical, Citrus, Herbal Flavor Profile: Sweet, Sour, Bitter, Smoky Packaging Type: Bottle, Can, Carton, Tetra Pak Distribution Channel: Online, Supermarkets, Specialty Stores, Bars |
| Companies Covered | Diageo plc, Pernod Ricard, Bacardi Limited, Lyre's Spirit Co, Ritual Zero Proof, Spiritless Inc, Caleño, Everleaf Drinks, ArKay Beverages LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Alcoholic Spirits Market Strategic Shifts
Flavor formulation technology is fragmenting the competitive landscape, as precision in volatile compound replication separates specialist producers from commodity botanical water blenders.
Rotary evaporator distillation systems are modularizing production scale for craft non-alcoholic distilleries. Mid-sized operators in London and New York are adopting benchtop units to prototype seasonal releases without committing to industrial-scale equipment. This technology is modularizing the traditional barrier between experimental R&D and commercial batch production.
REACH registration requirements for novel botanical extracts are tightening supply chain scrutiny across European manufacturing. Industrial consequence includes restricted access to exotic plant materials not previously assessed for human consumption safety. Citrus-derived terpene formulations are most affected, with suppliers accelerating GRAS self-determination documentation to maintain formulation continuity.
Direct-to-consumer membership tiers are displacing wholesale dependency for emerging brands. Established retailers in the United Kingdom and United States face disintermediation as producers capture lifetime value through recurring shipment models. Subscription retention metrics now determine valuation multiples more than traditional velocity per point of distribution.
Non-Alcoholic Spirits Market Segmentation
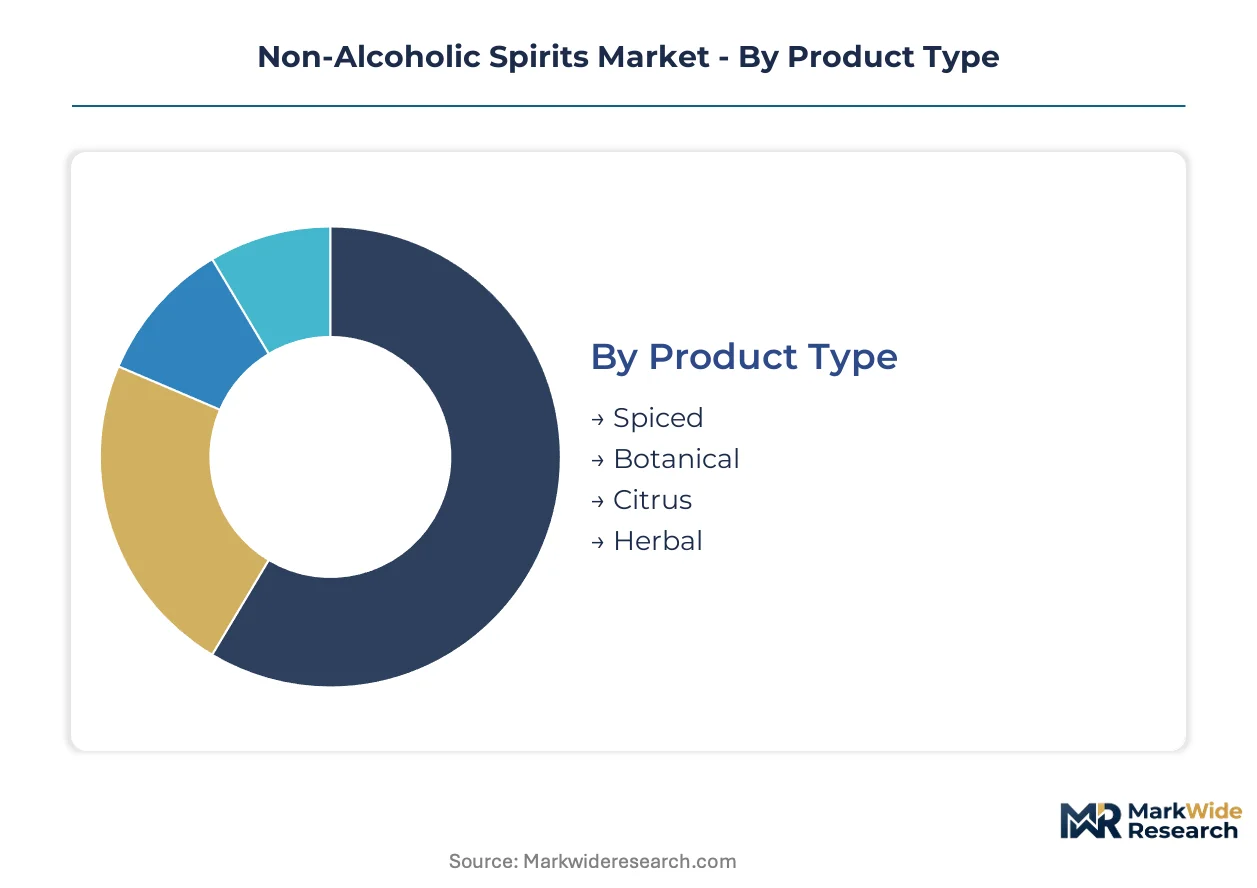
Segmentation in non-alcoholic spirits reveals how formulation choices, packaging formats, and channel strategies determine pricing power and customer lifetime value. Distinct product architectures command different production investments and regulatory compliance burdens across markets.
Product Type:
Upgrade cycles in non-alcoholic spirits follow flavor complexity and bartender utility rather than seasonal refresh patterns.
- Botanical:Vacuum-distilled juniper, coriander, and angelica root formulations replicate gin's aromatic signature. London's hotel bars and Manchester's mixology venues anchor volume for this segment, driven by established consumer familiarity with gin-based serves.
- Spiced:Macerated cassia, clove, and nutmeg compounds deliver whiskey and rum analogs. Demand concentrates in New York and Los Angeles hospitality clusters where bartenders require robust base spirits for zero-proof Old Fashioned and Manhattan variations.
- Citrus:Terpene-extracted grapefruit, yuzu, and bergamot profiles supply acidic brightness for complex builds.
- Herbal:Gentian, wormwood, and artemisia formulations mimic amaro and vermouth traditions for aperitif-style serves.
Volume placements concentrate in Botanical; the faster expansion belongs to Citrus.
Flavor Profile:
Cost tiering separates commodity mixers from premium craft formulations through ingredient sourcing depth and extraction method sophistication.
- Bitter:Gentian and quinine-forward formulations replicate Campari and Aperol profiles for Negroni-style builds. Upscale restaurant programs in Chicago and San Francisco drive adoption, constrained by FDA scrutiny of quinine concentration claims.
- Smoky:Lapsang souchong tea and mesquite smoke distillations emulate peated whiskey and mezcal. Premium hospitality venues in Edinburgh and Glasgow anchor demand, fueled by Scotland's existing smoke-forward spirits culture.
- Sweet:Vanilla, caramel, and fruit-derived glycoside formulations soften edges for entry-level consumers.
- Sour:Malic and citric acid adjustments provide cocktail-ready acidity without fresh citrus dependency.
Volume concentrates in Bitter for on-premise utility; Smoky gains share fastest as whiskey-alternative demand accelerates.
Packaging Type:
Application context dictates format selection between gift occasions, home consumption, and speed-of-service environments.
- Bottle:Premium glass formats with weighted bases and embossed labeling dominate retail shelf positioning and gifting. Specialty stores in London's Mayfair and New York's SoHo districts anchor volume, supported by unboxing experience requirements for direct-to-consumer subscription models.
- Can:Single-serve aluminum formats enable rapid pour-and-serve operations in high-volume bars. Miami and Austin hospitality clusters drive adoption, constrained by perception challenges around premium positioning for metal packaging.
- Carton:Paperboard formats reduce shipping weight for e-commerce fulfillment of multi-bottle orders.
- Tetra Pak:Aseptic cartons extend shelf stability for food-service bulk dispensing in hotel minibars.
Bottle placements dominate revenue; can formats expand most quickly through on-premise trial channels.
Distribution Channel:
Customer type fragmentation separates replenishment-driven subscribers from occasion-driven gift purchasers and impulse trialists.
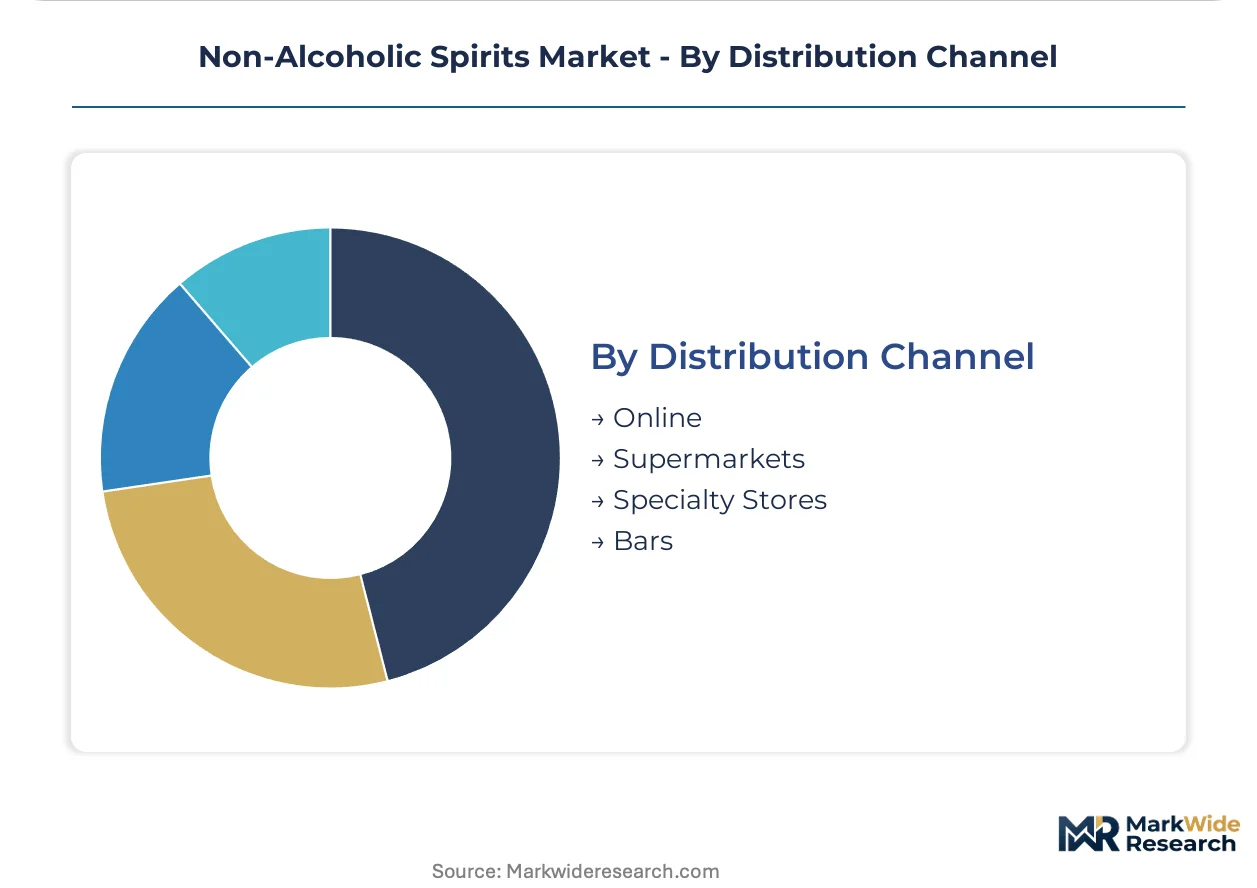
- Online:Direct-to-consumer platforms and subscription services capture lifetime value through recurring shipment models. United States and United Kingdom postal zones anchor volume, shaped by FDA and FSA labeling compliance requirements for cross-border fulfillment.
- Bars:On-premise venues provide discovery and education for new consumers through bartender recommendation. Melbourne and Sydney cocktail bars drive Asia-Pacific adoption, constrained by liquor licensing frameworks that vary across Australian states.
- Supermarkets:Mass retail placement requires slotting fee investments and velocity guarantees for shelf retention.
- Specialty Stores:Curated independent retailers provide discovery environment for emerging brands and limited releases.
Online volume leads for recurring revenue capture; bars deliver the steepest expansion trajectory through discovery-driven trial conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United Kingdom and United States, while consumption growth accelerates fastest in Australia and Germany. This geographic split shapes cross-border formulation standards and regulatory compliance investments.
United States
Premium hotel chains in New York and Los Angeles drive bartender-ready formulation demand. The FDA's evolving alcohol-by-volume thresholds and labeling claim restrictions force reformulation delays. Miami hospitality clusters adopt single-serve can formats for speed-of-service zero-proof programs.
United Kingdom
London's bar scene anchors global benchmarks for sophisticated alcohol-free serves. The Food Standards Agency enforces strict compositional standards determining reduced-tax qualification eligibility. Manchester mixology venues concentrate volume for vacuum-distilled botanical formulations.
Germany
REACH registration requirements for novel botanical extracts tighten supply chain scrutiny across manufacturing. The ECHA framework restricts access to exotic plant materials not previously assessed for human consumption safety. Berlin craft distilleries adopt rotary evaporator systems for seasonal release prototyping.
Australia
Melbourne and Sydney cocktail bars drive Asia-Pacific adoption through bartender recommendation and consumer education. State-level liquor licensing frameworks create compliance fragmentation across New South Wales and Victoria. Sydney hospitality clusters show steepest expansion trajectory for discovery-driven trial conversion.
Canada
Health Canada governs alcohol-free beverage labeling thresholds parallel to FDA frameworks. Toronto and Vancouver specialty retailers face disintermediation from direct-to-consumer subscription models capturing lifetime value. Pacific Northwest cross-border formulation standards influence Vancouver production investments.
Non-Alcoholic Spirits Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the non-alcoholic spirits category. Distillation equipment ownership separates multi-million dollar vacuum still operators from contract-manufactured brands. Three archetypes dominate: legacy spirits conglomerates with controlled hospitality distribution, direct-to-consumer specialists with subscription infrastructure, and craft distilleries with seasonal R&D agility. Competitive moves concentrate on strategic partnerships with premium hotel chains and portfolio diversification into adjacent zero-proof categories.
Within the legacy conglomerate tier, Diageo plc and Pernod Ricard occupy positions anchored by established hospitality channel relationships. Lyre's Spirit Co represents the direct-to-consumer archetype with membership tier infrastructure. Ritual Zero Proof exemplifies niche specialization within whiskey-alternative formulations. These three companies collectively illustrate how scale, subscription retention, and flavor chemist expertise separate viable operators from commodity botanical blenders.
| Leading Market Players |
|---|
| Diageo plc |
| Pernod Ricard |
| Bacardi Limited |
| Lyre's Spirit Co |
| Ritual Zero Proof |
| Spiritless Inc |
| Caleño |
| Everleaf Drinks |
| ArKay Beverages LTD |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up specialists in the non-alcoholic spirits category have consolidated production assets across the United Kingdom and United States, tightening supply discipline while enforcing premium pricing tiers through controlled hospitality distribution channels and direct-to-consumer subscription lock-in.
Pricing Analysis
Cost-down pressure on craft formulations accelerates because vacuum distillation equipment ownership concentrates among well-capitalized operators, forcing contract-manufactured brands into margin compression. Three-tier pricing structure across premium, standard, and economy levels separates estate-distilled botanical releases from compounded flavor houses and private-label commodity blenders. Price differentiation rests on extraction method sophistication and Food Standards Agency reduced-tax qualification status. Subscription-based buyers exhibit lowest price sensitivity; on-premise trialists through can formats show highest elasticity.
Supply Chain Analysis
Freight cost volatility from botanical sourcing clusters in India, Madagascar, and Guatemala shapes input cost structures for juniper, cardamom, and cassia dependent formulations. Raw material dependencies center on volatile aromatic compounds, glass bottle packaging from European manufacturers, and rotary evaporator components from German precision engineering suppliers. Single-source vulnerability concentrates in exotic citrus terpene suppliers facing REACH registration delays. Distribution runs through controlled hospitality channels in London and New York, direct-to-consumer postal zones, and specialty retail in premium urban districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream distillation equipment ownership and downstream subscription infrastructure determine sustainable margin capture against commodity botanical blenders.
For Market Incumbents: Cement hospitality channel exclusivity through controlled distribution partnerships with premium hotel chains in London and Los Angeles, locking out emerging entrants from bartender education touchpoints. Acquire rotary evaporator production capacity or secure long-term equipment leases to defend against contract-manufacturing margin erosion from flavor chemist scarcity. For New Entrants and Emerging Players: Capture citrus profile whitespace where terpene-extracted formulations for complex zero-proof builds face limited specialist competition. Target can format trial channels in Miami and Austin hospitality clusters where speed-of-service demands outstrip incumbent bottle-format supply. Lead with direct-to-consumer subscription models to bypass specialty retailer slotting fee barriers. For Investors and Strategic Acquirers: FDA labeling threshold clarification is the leading indicator that regulatory compliance capacity will separate viable multi-territory operators from stranded single-market assets. Frame long-term viability around flavor chemist expertise scarcity and subscription retention infrastructure rather than velocity per point of distribution. Monitor rotary evaporator adoption rates among craft distilleries as consolidation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Botanical Sourcing | Direct juniper and cassia procurement from Indian and Madagascan growing regions reduces harvest risk exposure. |
| Direct-to-Consumer Subscription Launch | Recurring shipment models in United States and United Kingdom postal zones capture lifetime value outside retail intermediation. |
| Vacuum Distillation Capacity Expansion | Equipment ownership in London and New York production clusters separates flavor-fidelity specialists from commodity compounders. |
| Can Format Portfolio Extension | Single-serve aluminum packaging penetrates Miami and Austin on-premise venues where speed-of-service dominates. |
| Regulatory Affairs Capability Buildout | Dedicated FDA and FSA compliance teams enable cross-border expansion without reformulation delays. |
Study Parameters
Trade publications, customs records, and Food Standards Agency compositional filings formed the secondary backbone, cross-referenced with primary interviews involving flavor chemists, hospitality procurement directors, and regulatory affairs specialists at multi-territory operators. Bottom-up volume estimates from production capacity installations and top-down validation against subscription shipment disclosures enabled triangulation across the analysis window.
Historical trendline analysis of vacuum distillation adoption rates and direct-to-consumer subscription growth patterns informed projection modeling across product type, packaging format, and distribution channel dimensions. CAGRs derived from segment-level growth trajectories weighted by bartender utility scores and regulatory compliance burden differentials. Forecast inputs incorporated rotary evaporator equipment shipment data and REACH registration timelines for novel botanical extracts.
The model holds under stable FDA and FSA labeling frameworks; deviation in alcohol-by-volume threshold revisions or novel botanical safety assessments would shift formulation investment timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Soy Beverage Market
Non-Alcoholic Beverages
Diet Soda Market
Non-Alcoholic Beverages
Zero Proof Spirit Market
Non-Alcoholic Beverages
Africa Non-Alcoholic Beverages Market
Non-Alcoholic Beverages
Zero Sugar Beverages Market
Non-Alcoholic Beverages
Lemonade Market
Non-Alcoholic Beverages
Non-Dairy Beverages Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Global Sugar Free Beverages Market
Non-Alcoholic Beverages
Europe Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Soft Drinks Market
Non-Alcoholic Beverages
North America Bottled Water Processing Market
Non-Alcoholic Beverages
India Energy Drinks Market
Non-Alcoholic Beverages
Non-Alcoholic Wine and Beer Market
Non-Alcoholic Beverages
Fruit-Infused Water Market