
 Draught Beer Market | 2026-2036
Draught Beer Market Size, Share, and Industry Trends Forecast 2026-2036
Draught Beer Market Analysis
Premium craft specifications are unwinding across the draught beer landscape as consumers trade up from mass-market lagers. Heineken leverages its global brewing network to sustain consistent quality in keg formats across multiple continents. Sierra Nevada Brewing Company anchors its position through in-house production of specialty hops and malt varieties. Anheuser-Busch InBev dominates mainstream draught volumes through extensive tap line placement contracts with major hospitality groups.
Draught beer denotes unpasteurized, cellar-temperature beer served under pressure from kegs or casks, typically maintaining carbonation at 10-14 psi through CO2 or mixed-gas systems for optimal foam stability and flavor expression. Its primary commercial purpose centers on delivering fresher, more aromatic consumption experiences in on-premise settings where per-glass margin economics outperform packaged alternatives. Lagers occupy the mature volume base in draught distribution, while nitrogen infusion systems command premium positioning in stout service at Irish-style pubs and craft establishments. Keg dispensing infrastructure represents the fastest-growing capital segment as microbreweries expand direct-to-consumer taproom footprints. Wheat beers compete for seasonal rotation slots in European beer gardens and North American outdoor dining venues.
FDA oversees sanitary standards for imported keg cleaning and filling protocols, while TTB enforces federal labeling and tax classification for beer distributed across state lines. The EU F-Gas Regulation constrains refrigerant choices in cellar cooling systems, elevating compliance costs for draft equipment operators in member countries. State-level alcohol beverage control boards in the United States impose varying keg registration and deposit requirements that fragment distribution logistics. Stakeholders must monitor evolving deposit-return schemes and carbon-accounting mandates that could reshape keg fleet economics and material choices in draft infrastructure procurement.
Market Dynamics
Cellar cooling infrastructure is consolidating around low-global-warming-potential refrigerants as the EU F-Gas Regulation phases down hydrofluorocarbon availability, forcing taproom operators and distributors to retool temperature control systems at substantial capital cost.
Growth Catalysts
- Nitrogen dispensing technology:Irish-style pubs and craft establishments are retrofitting gas systems to serve nitrogen-infused stouts, expanding premium per-glass margins beyond traditional CO2 service.
- Urban taproom clustering:Microbreweries in United States metropolitan cores are concentrating direct-to-consumer footprints within walkable districts, reducing distribution overhead while capturing on-premise margin premiums.
- Deposit-return schemes:Germany's packaging regulations and similar programs across Scandinavia are standardizing stainless steel keg circularity, lowering fleet replacement costs for regional distributors.
Market Restraints
- Aluminum and stainless steel input volatility:Keg manufacturing depends on commodity metal pricing subject to energy cost fluctuations and trade tariff uncertainty.
- Refrigerant supply concentration:EU F-Gas Regulation constraints have narrowed approved cooling agent options to a handful of specialized chemical suppliers, elevating maintenance contract pricing.
- Technical limitation in long-haul distribution:Unpasteurized draught beer maintains freshness windows of 30-45 days post-filling, constraining intercontinental keg logistics and import scale economics.
Strategic Opportunities
- Carbon accounting mandates:The EU Green Deal and emerging corporate sustainability reporting requirements are creating procurement preference for keg reuse programs over single-use packaging in European hospitality.
- Smart tap telemetry convergence:Integration of flow-monitoring sensors with inventory management software is enabling predictive maintenance and automated reordering for multi-location hospitality groups.
- Seasonal wheat beer rotation:North American outdoor dining venues and European beer gardens are expanding summer portfolio slots for unfiltered wheat styles, opening formulation partnerships between craft producers and seasonal operators.
Industry Challenges
- Certified cellarman skill scarcity:Proper line cleaning, gas balancing, and foam control require trained technicians, yet hospitality labor turnover outpaces specialized training program output.
- Legacy tap line integration complexity:Long-term exclusive pouring contracts between major hospitality groups and volume brewers create physical infrastructure lock-in that complicates craft brand access to prime dispensing locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Draught Beer Market |
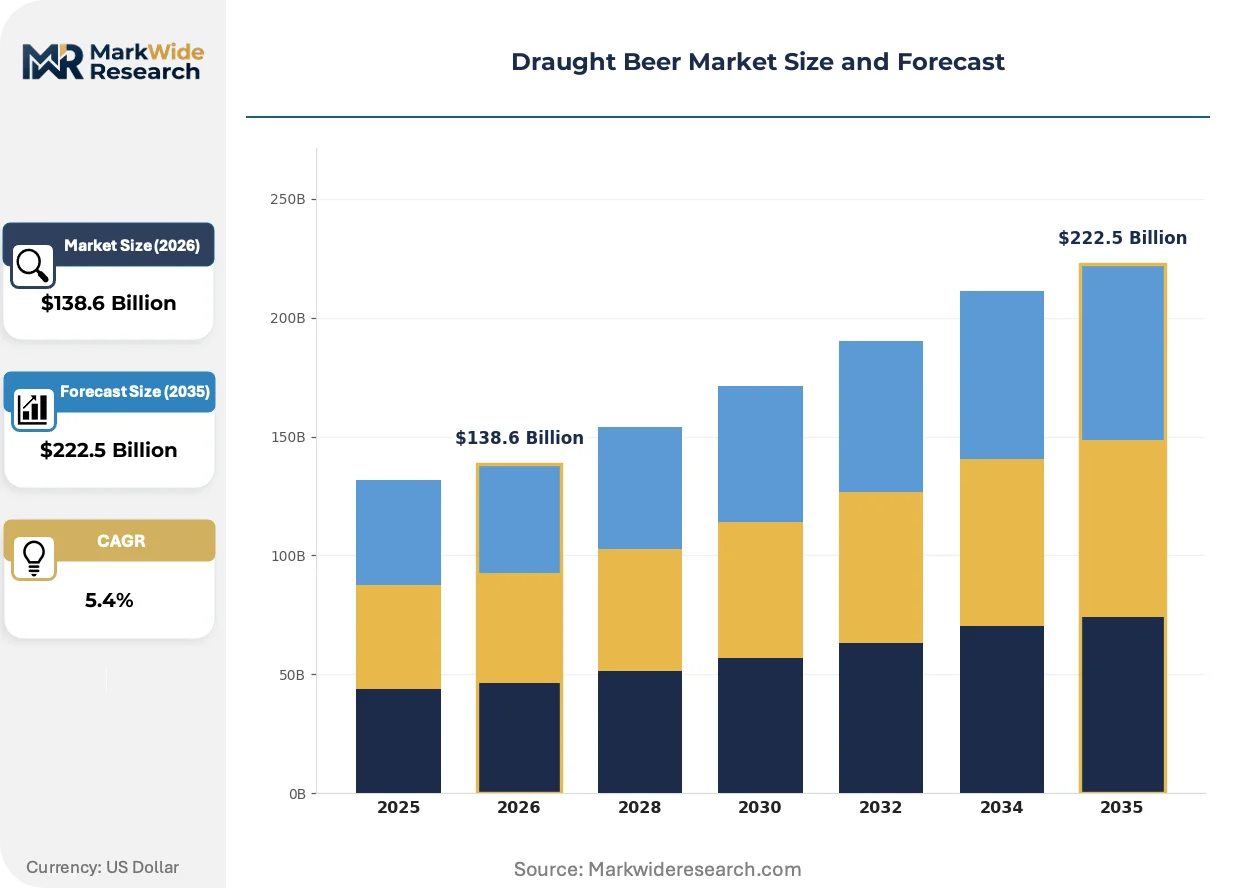
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $222.5 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ales, Lagers, Stouts, Wheat Beers Dispensing Method: Hand Pump, Keg, Nitrogen Infusion, CO2 System Consumer Demographics: Millennials, Gen Z, Gen X, Baby Boomers Distribution Channel: Bars, Restaurants, Breweries, Retail Outlets |
| Companies Covered | Anheuser-Busch InBev, Heineken, Molson Coors Beverage Company, Constellation Brands, Boston Beer Company, Carlsberg Group, Diageo, D.G. Yuengling & Son, Sierra Nevada Brewing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Draught Beer Market Emerging Trajectories
Draught service technology is converging around data-enabled dispensing systems that optimize pour economics while regulatory pressure on refrigerants and packaging circularity is reshaping capital deployment across the value chain.
Draft equipment is miniaturizing as countertop and under-counter dispensing systems shrink cooling footprints for smaller-format taprooms and restaurant bars with limited cellar space. Independent craft operators with 6-12 tap handles are adopting these compact units to avoid expensive basement excavation or remote cooling infrastructure. This compression is miniaturizing the minimum viable taproom footprint, enabling microbrewery expansion into secondary urban locations and suburban retail strips previously excluded by real estate constraints.
The EU F-Gas Regulation is mandating phased reductions in hydrofluorocarbon refrigerant quotas through 2030, compelling cellar cooling system manufacturers to accelerate natural refrigerant and hydrocarbon-based alternatives. Equipment operators face retrofit timelines and technician retraining requirements that compress replacement cycles for aging draft infrastructure. German and Belgian distributors with large tied-house estates are responding fastest, consolidating supplier relationships with refrigeration OEMs offering compliant next-generation platforms.
On-premise procurement is fragmenting as hospitality groups disaggregate beverage programs from exclusive multi-year tap line commitments toward rotating seasonal portfolios and local craft exclusives. Multi-unit restaurant operators are hiring dedicated beverage directors with authority to negotiate shorter-term, SKU-specific contracts rather than corporate-level master agreements. This pattern concentrates in United States coastal metropolitan markets where consumer experimentation rates and craft brewery density jointly sustain fragmented supplier relationships.
Draught Beer Market Segmentation
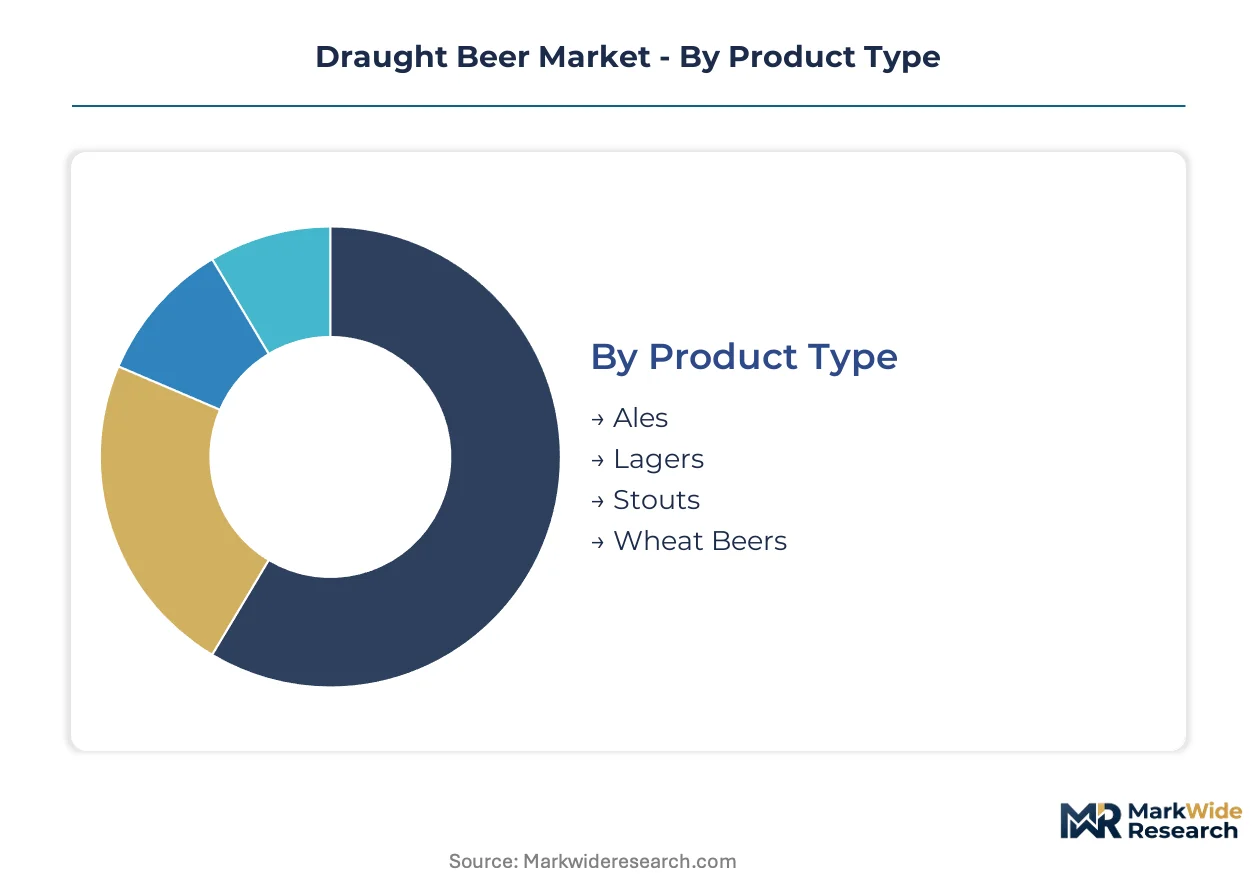
Margin pools in draught beer concentrate around dispensing technology and on-premise channel access, with product type and generational targeting determining portfolio composition for brewers and distributors.
Product Type:
Premium pricing power clusters around flavor intensity and production complexity rather than volume throughput.
- Lagers:Unpasteurized pilsners and helles styles dominate tap line placements through extended freshness windows and broad consumer acceptance. Demand concentrates in German beer gardens and American sports bars where per-glass velocity sustains distributor economics despite thinner margins.
- Ales:Pale ales and IPAs command elevated per-glass pricing through hop-forward profiles that signal craft authenticity. Urban taprooms in Portland, Oregon and Manchester, England rotate these styles aggressively to capture Millennial and Gen Z experimentation rates.
- Stouts:Nitrogen-dispensed dark beers anchor winter portfolios at Irish-style pubs.
- Wheat Beers:Unfiltered hefeweizens compete for seasonal outdoor dining slots.
The dominant share belongs to Lagers, while Ales is closing the gap fastest.
Dispensing Method:
Capital deployment intensity varies sharply across gas system architectures and manual versus automated pouring infrastructure.
- CO2 System:Standard carbon dioxide pressure dispensing at 10-14 psi maintains the installed base across mainstream hospitality venues. Cost-sensitive operators in Spain and Brazil prioritize this proven technology for its technician familiarity and parts availability.
- Nitrogen Infusion:Mixed-gas systems blending nitrogen with carbon dioxide create the cascading pour effect essential to stout service. Premium Irish pubs in Dublin and craft establishments in Denver retrofit lines specifically to justify elevated per-glass pricing on dark beer portfolios.
- Keg:Direct-draw systems from refrigerated cellars remain the volume default.
- Hand Pump:Cask-conditioned ale service persists at traditional English pubs.
CO2 System retains volume leadership, though Nitrogen Infusion is expanding most quickly in premium repositioning strategies.
Consumer Demographics:
On-premise frequency and per-session spend stratify sharply across age cohorts, driving divergent portfolio and marketing approaches.
- Millennials:This cohort sustains craft brewery taproom economics through elevated willingness to pay for local provenance and experimental small-batch releases. Concentrated demand in Brooklyn, New York and East London supports direct-to-consumer models that bypass traditional distribution.
- Gen Z:Emerging legal-age drinkers prioritize low-alcohol options and sustainability signaling in venue selection. Social media-native consumption patterns in Seoul and Amsterdam reward visually distinctive pour presentations and carbon-neutral keg programs.
- Gen X:Established preferences center on consistent quality and recognized brand names.
- Baby Boomers:Declining on-premise frequency limits segment growth despite higher per-occasion spend.
Millennials anchor current revenue, while Gen Z is gaining share fastest through values-aligned procurement.
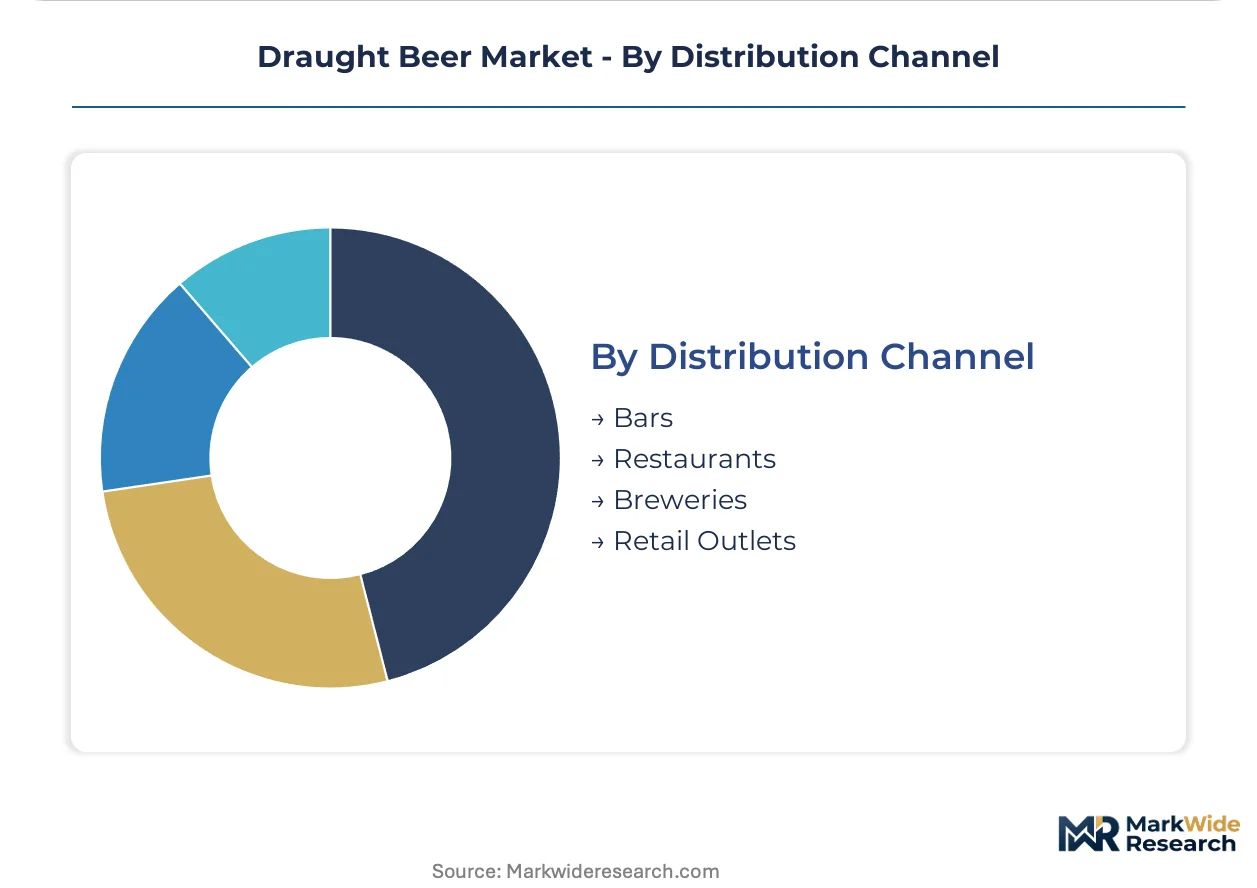
Distribution Channel:
Physical infrastructure control determines margin capture, with captive versus third-party dispensing creating divergent profitability profiles.
- Breweries:Direct-to-consumer taprooms capture the full retail margin by eliminating wholesale and hospitality intermediaries. Microbreweries in Denver, Colorado and Brussels, Belgium cluster production and service facilities to maximize per-keg economics.
- Bars:Independent and chain on-premise operators remain the volume gatekeepers, with exclusive pouring contracts constraining craft brand access. Major hospitality groups in Chicago and Sydney negotiate multi-tap commitments that lock out smaller suppliers.
- Restaurants:Beverage program fragmentation is accelerating as dedicated beverage directors gain contracting authority.
- Retail Outlets:Growler fills and crowler stations extend draught freshness into off-premise consumption.
Breweries command the steepest expansion trajectory in margin capture, while Bars retain absolute volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German keg exports supply taproom operators across the United States and United Kingdom, while Belgian distributors maintain secondary trade corridors into France and the Netherlands. This cross-border flow of unpasteurized draught beer shapes cellar infrastructure investment patterns in receiving markets.
United States
Urban taproom clusters in Denver, Colorado and Portland, Oregon concentrate microbrewery direct-to-consumer footprints. FDA sanitary standards for imported keg cleaning protocols elevate compliance costs for European suppliers. Brooklyn, New York anchors Millennial-driven demand for experimental small-batch releases.
Germany
Premium craft positioning gains traction among on-premise operators in Munich and Berlin beer gardens. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerant quotas through 2030, forcing cellar cooling retrofits. Bavarian distributors leverage standardized stainless steel keg circularity under national deposit-return schemes.
Belgium
Traditional lambic and farmhouse ale producers in Brussels and Flemish regions supply nitrogen-infusion systems to Irish-style pubs globally. REACH chemical compliance constrains cleaning agent formulations for keg sanitization. Antwerp-based distributors consolidate supplier relationships with refrigeration OEMs offering natural refrigerant platforms.
United Kingdom
Cask-conditioned ale service persists at traditional English pubs in Manchester and London. TTB labeling requirements reshape import compliance for American craft kegs entering British hospitality. East London supports direct-to-consumer models that bypass traditional distribution channels.
China
Expanding craft brewery density in Shanghai and Beijing drives demand for compact under-counter dispensing systems. SAMR market regulation standardizes food safety protocols for cellar-temperature beer service. Pearl River Delta manufacturing clusters produce CO2 pressure systems for domestic taproom expansion.
Draught Beer Market Vendor Landscape
Listed leaders compete with private specialists across tap line placement contracts and direct-to-consumer channel access. The vendor base concentrates around three tiers: multinational volume brewers with hospitality group exclusivity agreements, mid-scale craft operators with captive hop and malt supply, and regional specialists with urban taproom clustering strategies. Dominant competitive moves include exclusive multi-year pouring contracts with major hospitality groups and backward integration into specialty ingredient production.
Within the multinational volume tier, Anheuser-Busch InBev and Heineken exemplify scale-driven positioning through extensive tap line infrastructure control. Sierra Nevada Brewing Company occupies a specialist archetype with in-house production of proprietary hop varieties. These three anchors represent divergent strategic pathways: mass-market volume capture, global brewing network leverage, and vertical control over raw material quality.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken |
| Molson Coors Beverage Company |
| Constellation Brands |
| Boston Beer Company |
| Carlsberg Group |
| Diageo |
| D.G. Yuengling & Son |
| Sierra Nevada Brewing Company |
| Others |
Supply Flow & Price Mechanics
Natural refrigerant substitution for hydrofluorocarbon cooling agents is redrawing cellar equipment supply geography from Germany toward Chinese hydrocarbon compressor manufacturing while compressing maintenance contract pricing for European taproom operators facing EU F-Gas Regulation compliance deadlines.
Pricing Analysis
Next-generation nitrogen infusion systems command 40-60% per-glass premiums over standard CO2 dispensing infrastructure, while legacy direct-draw cellar systems face margin compression as aluminum keg input costs fluctuate with energy pricing. Three-tier pricing structure across premium nitrogen service, standard CO2 dispensing, and economy hand-pump cask conditioning reflects differentiation by gas system complexity and technician certification requirements. Cost compression in mainstream CO2 equipment is intensifying because Chinese manufacturers are scaling compact under-counter unit production for urban taprooms. Chain hospitality groups exhibit highest price sensitivity due to multi-location procurement volume, while independent craft breweries prioritize provenance signaling over unit economics.
Supply Chain Analysis
Strategic stockpiling of stainless steel keg inventories dominates distributor behavior in Germany and Belgium where deposit-return schemes ensure fleet circularity, while just-in-time refrigerant procurement prevails among United States taproom operators facing narrower approved cooling agent options. Manufacturing concentration centers on China for CO2 pressure systems, Germany for precision cellar cooling units, and Belgium for nitrogen gas blending equipment. Raw material dependencies include 304-grade stainless steel for keg bodies, food-grade CO2 and nitrogen gases, and hydrocarbon refrigerants. Single-source vulnerability in specialized compressor suppliers elevates risk for European retrofit timelines. Distribution runs through consolidated refrigeration OEM partnerships with major hospitality groups and direct-to-consumer equipment sales for microbrewery taprooms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Draught beer market expansion sits in early-cycle penetration as urban taproom clustering in United States metropolitan cores accelerates direct-to-consumer channel development beyond traditional bar and restaurant distribution.
For Market Incumbents: Secure exclusive multi-tap pouring contracts with major hospitality groups before beverage director authority fragments procurement toward rotating seasonal portfolios. Defend position by accelerating backward integration into specialty hop and malt production to differentiate from commodity volume competitors. Lock in certified cellarman training partnerships to address skill scarcity threatening service quality consistency.
For New Entrants and Emerging Players: Anchor in compact under-counter dispensing system segments where real estate constraints exclude traditional cellar infrastructure competitors. Target suburban retail strips and secondary urban locations previously inaccessible due to basement excavation costs. Pursue formulation partnerships with seasonal outdoor dining operators seeking distinctive wheat beer rotations.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown through 2030 reshapes the acquisition landscape toward refrigeration OEMs with natural refrigerant platforms and established technician training networks. Five-to-ten year viability favors targets with captive urban taproom footprints and direct-to-consumer margin capture. Watch carbon accounting mandate adoption rates in European hospitality procurement as inflection indicator for keg reuse program economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Tap Telemetry Integration | Flow-monitoring sensors from IoT vendors enable predictive maintenance for multi-location hospitality groups. |
| Natural Refrigerant Platform Transition | Hydrocarbon cooling systems from German OEMs satisfy EU F-Gas Regulation compliance for cellar retrofits. |
| Direct-to-Consumer Taproom Expansion | Microbreweries in Denver and Portland capture full retail margin by bypassing wholesale intermediaries. |
| Specialty Ingredient Backward Integration | In-house hop breeding programs from Sierra Nevada Brewing Company secure proprietary aroma profiles. |
| Deposit-Return Scheme Participation | German distributors leverage standardized stainless steel keg circularity to lower fleet replacement costs. |
Methodological Framework
Desk research of trade association filings, customs records for keg and refrigeration equipment, and regulatory databases from FDA and EU F-Gas authorities preceded structured interviews with taproom operations managers, beverage directors at hospitality groups, cellar equipment technicians, and distribution procurement leads. Primary fieldwork with microbrewery founders and refrigeration OEM account executives combined with secondary validation against TTB labeling guidance documents and state-level alcohol beverage control board regulations. Bottom-up taproom count estimates and top-down keg fleet economics were triangulated to anchor market sizing.
Variance decomposition across product type, dispensing method, consumer demographic, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups and value-per-keg economics rather than aggregate extrapolation. Forecast inputs included urban taproom density trajectories in United States metropolitan cores, EU refrigerant quota phase-down schedules, and generational consumption frequency shifts among Millennials and Gen Z cohorts.
Decision-makers should treat outputs as directional under assumptions of continued urban taproom clustering and stable aluminum pricing; material deviation in commodity metal volatility or hospitality real estate costs would warrant model refresh. Revision becomes warranted when carbon accounting mandate adoption crosses procurement preference thresholds in European on-premise channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bright Beer Tank Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Hookah Charcoal Market
Alcoholic Beverages
Commercial Wine Dispenser Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Beer Fermenter Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Wine Fermentation Equipment Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Tanzania Spirits Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
Beer Glass Chillers Market