
 Europe Kegs Market | 2026-2036
Europe Kegs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kegs Market Foresight
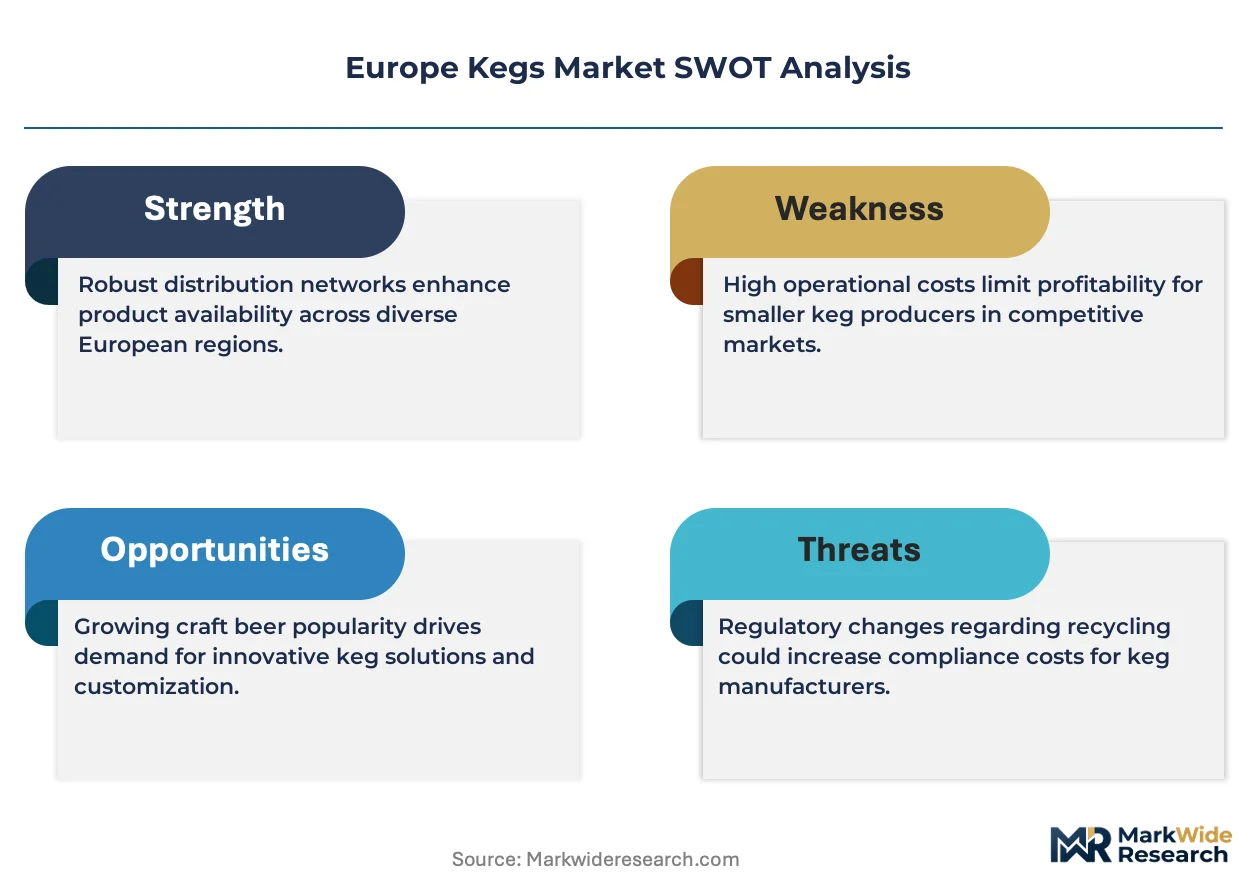
Stainless steel is broadening its share of European beverage logistics as brewers phase out disposable alternatives. THIELMANN The Container Company leverages its German manufacturing base to dominate reusable steel keg supply across Central Europe. BLEFA GmbH anchors its position through specialized production of high-grade stainless steel kegs for premium beer exports. Julius Kleemann GmbH & Co.KG differentiates via precision engineering of custom-capacity kegs for niche craft producers.
Europe kegs are cylindrical reusable vessels, typically manufactured from AISI 304 stainless steel with dual-valve spear systems and pressure ratings up to 3 bar, designed for carbonated beverage storage and draft dispensing in hospitality and retail channels. Steel kegs retain the largest installed base across European breweries due to decades of standardization around DIN and Euro norms, though plastic keg formats are gaining fastest adoption among mobile catering services and seasonal event operators seeking reduced tare weight. The 20L and 30L size categories capture the dominant share of volume throughput, while 5L formats serve expanding direct-to-consumer retail channels.
REACH compliance and the EU F-Gas Regulation shape material selection and valve sealing technologies across European keg manufacturing, while CE marking mandates govern pressure equipment safety standards. Germany's KBA and national weights and measures authorities enforce calibration protocols that determine market access for keg fleet operators. Stakeholders must monitor evolving Extended Producer Responsibility frameworks under the EU Green Deal, as these will recalibrate total cost of ownership calculations between reusable and single-trip packaging formats.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing breweries across Germany, the Czech Republic, and Belgium to accelerate fleet turnover from single-use packaging to reusable stainless steel formats, compressing replacement cycles and concentrating procurement among specialized keg manufacturers.
Growth Catalysts
- REACH compliance mandates:Chemical safety protocols under ECHA jurisdiction are disqualifying lower-grade steel alloys and plastic keg alternatives from food-contact applications across German and Czech brewing operations.
- Craft brewery clustering:Dense geographic concentration of small-batch producers in Bavaria and Bohemia generates pooled procurement volumes for 20L and 30L standardized formats.
- Carbon accounting integration:Lifecycle assessment tools embedded in brewery ERP systems are elevating reusable steel kegs over disposable alternatives in total cost of ownership calculations.
Market Restraints
- Nickel price volatility:AISI 304 stainless steel production depends on nickel input costs that fluctuate with Indonesian and Russian supply disruptions, compressing keg manufacturer margins.
- Fleet operator consolidation:Third-party keg pooling services in Germany and the Netherlands concentrate bargaining power against independent brewers and smaller keg suppliers.
- Plastic keg substitution:One-way PET keg formats from specialized packaging converters are capturing seasonal event and mobile catering demand through reduced tare weight and elimination of return logistics.
Strategic Opportunities
- Polish craft expansion:Underpenetrated brewery density in Lesser Poland and Silesian Voivodeships offers first-mover positioning for keg fleet operators establishing regional logistics hubs.
- Direct-to-consumer retail:5L mini-keg formats for home dispensing systems are opening incremental revenue channels beyond traditional hospitality supply.
- Extended Producer Responsibility frameworks:EU Green Deal implementation will impose packaging recovery obligations that favor reusable steel formats over single-trip alternatives in regulatory cost structures.
Industry Challenges
- Pressure equipment certification:CE marking and PED compliance timelines for new keg designs extend 8-14 months, delaying product launches and freezing R&D amortization schedules.
- Spear valve interoperability:Legacy DIN and Euro norm incompatibilities between German, Czech, and Belgian keg fleets create integration friction for multi-country brewery operations.
- Specialized welding talent:TIG welding certification for food-grade stainless steel pressure vessels faces acute scarcity across Central European manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kegs Market |
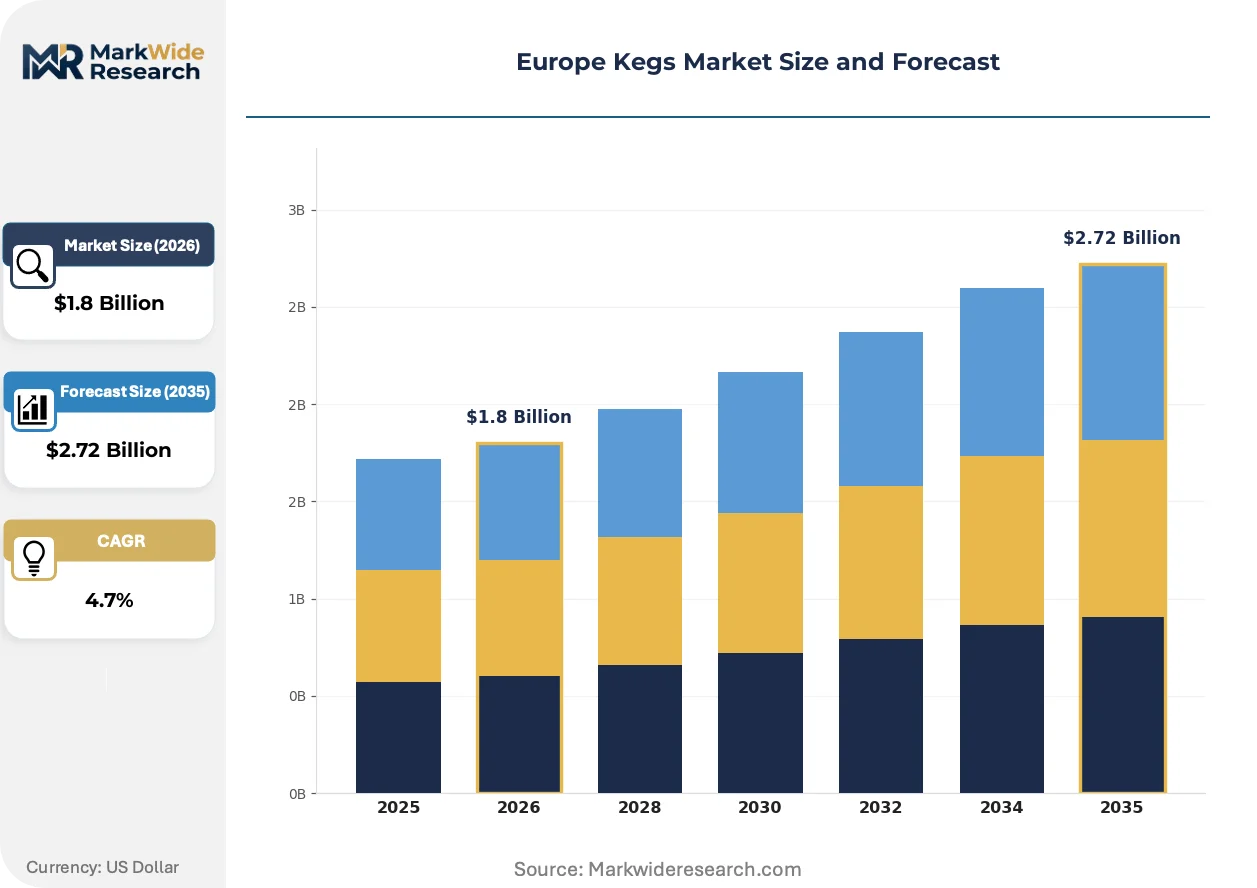
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Kegs, Steel Kegs, Aluminum Kegs, Glass Kegs End User: Restaurants, Breweries, Distributors, Catering Services Size: 5L, 10L, 20L, 30L Distribution Channel: Online Sales, Retail Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | NDL Keg Europe, BLEFA GmbH, Julius Kleemann GmbH & Co.KG, The Metal Drum Company, Petainer Ltd., Schaefer Container Systems, THIELMANN The Container Company, NEW MAISONNEUVE KEG, KeyKeg, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kegs Market Shifts & Advancements
Smart tracking technologies and regulatory compliance automation are converging to transform keg fleet management from passive logistics into data-integrated asset optimization. These developments compress operational visibility gaps and reshape competitive differentiation among European suppliers.
RFID and NFC-enabled keg tracking systems are modularizing fleet management by embedding unique identifiers at the valve spear and chime intersection. Mid-sized breweries in Belgium and the Netherlands are retrofitting existing stainless steel fleets with passive RFID tags to eliminate manual inventory counts. This technology is modularizing the relationship between keg manufacturers and logistics providers, enabling outcome-based fleet performance contracts rather than unit sales.
The EU F-Gas Regulation is tightening restrictions on hydrofluorocarbon seals and gaskets used in keg valve assemblies, forcing manufacturers to qualify fluoropolymer alternatives. Industrial consequence includes extended validation timelines for new material combinations and elevated component costs. Premium export breweries in Germany are responding by sourcing pre-certified valve systems from specialized suppliers to compress their own compliance timelines.
Brewery procurement departments are consolidating vendor relationships from fragmented regional suppliers to single-source keg fleet management contracts. This consolidation displaces spot purchasing and fragmented maintenance arrangements across hospitality-focused breweries in Bavaria. The shift is most visible in Germany's Mittelfranken region, where cooperative purchasing alliances aggregate demand across 40-plus craft producers for standardized 30L formats.
Europe Kegs Market Segmentation
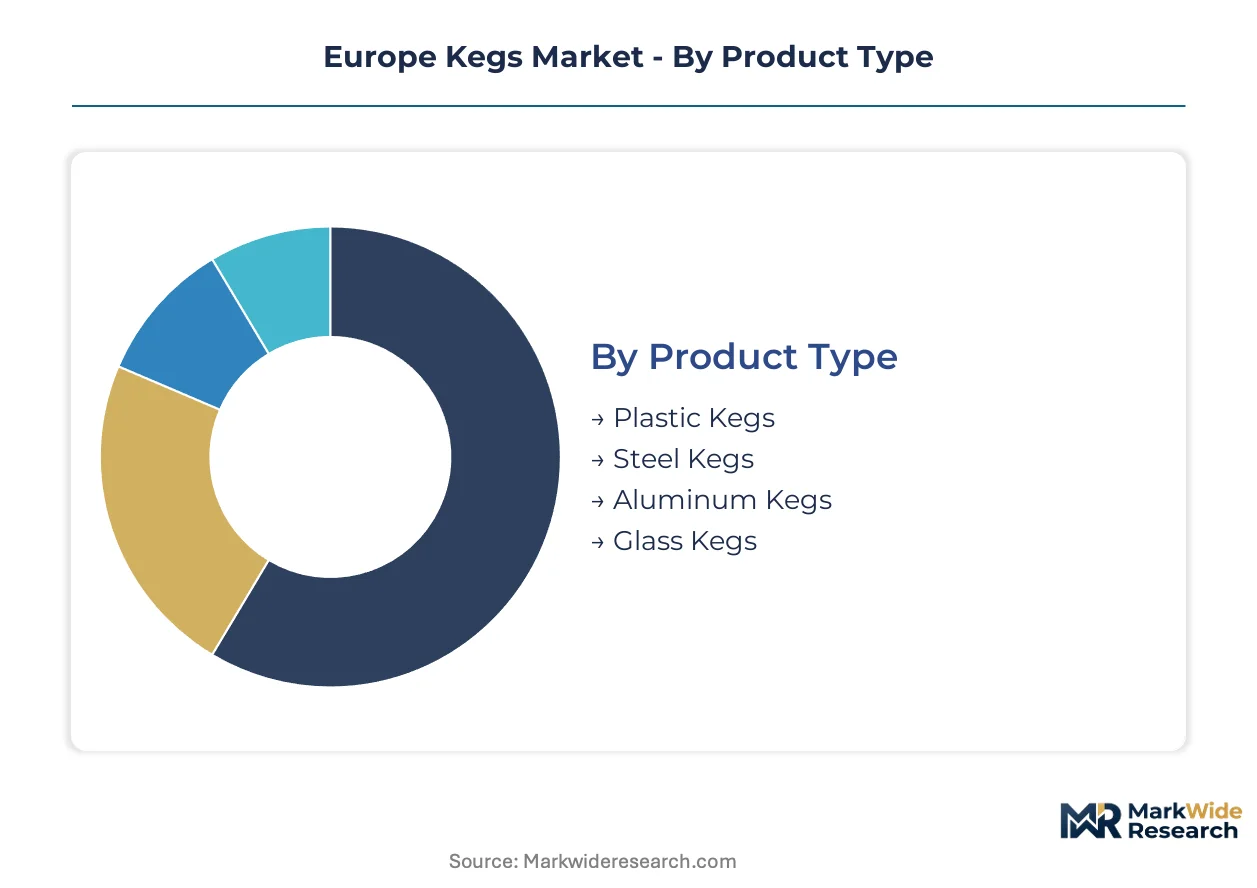
European keg procurement patterns diverge sharply between standardized fleet formats for volume breweries and custom-capacity solutions for niche producers. Segmentation reveals how material selection, channel configuration, and size specification map onto distinct operational economics across Germany, the Czech Republic, and Belgium.
Product Type:
The customization-to-standardization spectrum runs from commodity plastic disposables to precision-engineered steel vessels with decades of service life.
- Steel Kegs:Fabricated from AISI 304 stainless steel with dual-valve spear systems rated to 3 bar, these vessels dominate installed base across Bavarian and Bohemian brewing operations. DIN and Euro norm standardization enables interoperability across German, Czech, and Belgian fleet pools, though REACH compliance mandates now disqualify lower-grade alloys from food-contact applications.
- Plastic Kegs:One-way PET formats from specialized packaging converters capture seasonal event and mobile catering demand through reduced tare weight and elimination of return logistics. ECHA chemical safety protocols are compressing adoption timelines for non-compliant polymer grades.
- Aluminum Kegs:Lightweight alternatives serve export-focused breweries prioritizing freight cost reduction over multi-decade durability.
- Glass Kegs:Niche specialty formats for premium positioning in direct-to-consumer retail channels.
Most installed capacity flows through Steel Kegs. Expansion is steepest in Plastic Kegs.
End User:
Volume concentration versus fragmentation determines procurement sophistication and fleet management complexity across customer types.
- Breweries:Dense geographic clustering in Bavaria and Bohemia generates pooled procurement volumes for 20L and 30L standardized formats, with cooperative purchasing alliances aggregating demand across 40-plus craft producers in Germany's Mittelfranken region.
- Distributors:Third-party keg pooling services in Germany and the Netherlands concentrate bargaining power and drive vendor consolidation from fragmented regional suppliers toward single-source fleet management contracts.
- Restaurants:Draft-dispensing hospitality venues prioritize valve interoperability and pressure equipment certification compliance.
- Catering Services:Mobile operators favor reduced-tare alternatives for event logistics where return infrastructure is absent.
Procurement volume concentrates in Breweries. Technology adoption runs fastest through Distributors.
Size:
Operational scale and channel destination dictate capacity selection across the European installed base.
- 30L:The workhorse format for on-trade hospitality supply, capturing dominant throughput in German and Czech draft beer distribution. Standardization around this capacity enables maximum fleet utilization across pooling networks.
- 20L:Secondary standard for craft producers with limited production runs and regional distribution footprints, balancing batch flexibility with logistics efficiency.
- 5L:Mini-keg formats for home dispensing systems are opening incremental revenue channels beyond traditional hospitality supply, particularly in direct-to-consumer retail.
- 10L:Mid-capacity niche serving specialty importers and premium positioning strategies.
Volume throughput peaks at 30L. New application development concentrates in 5L.
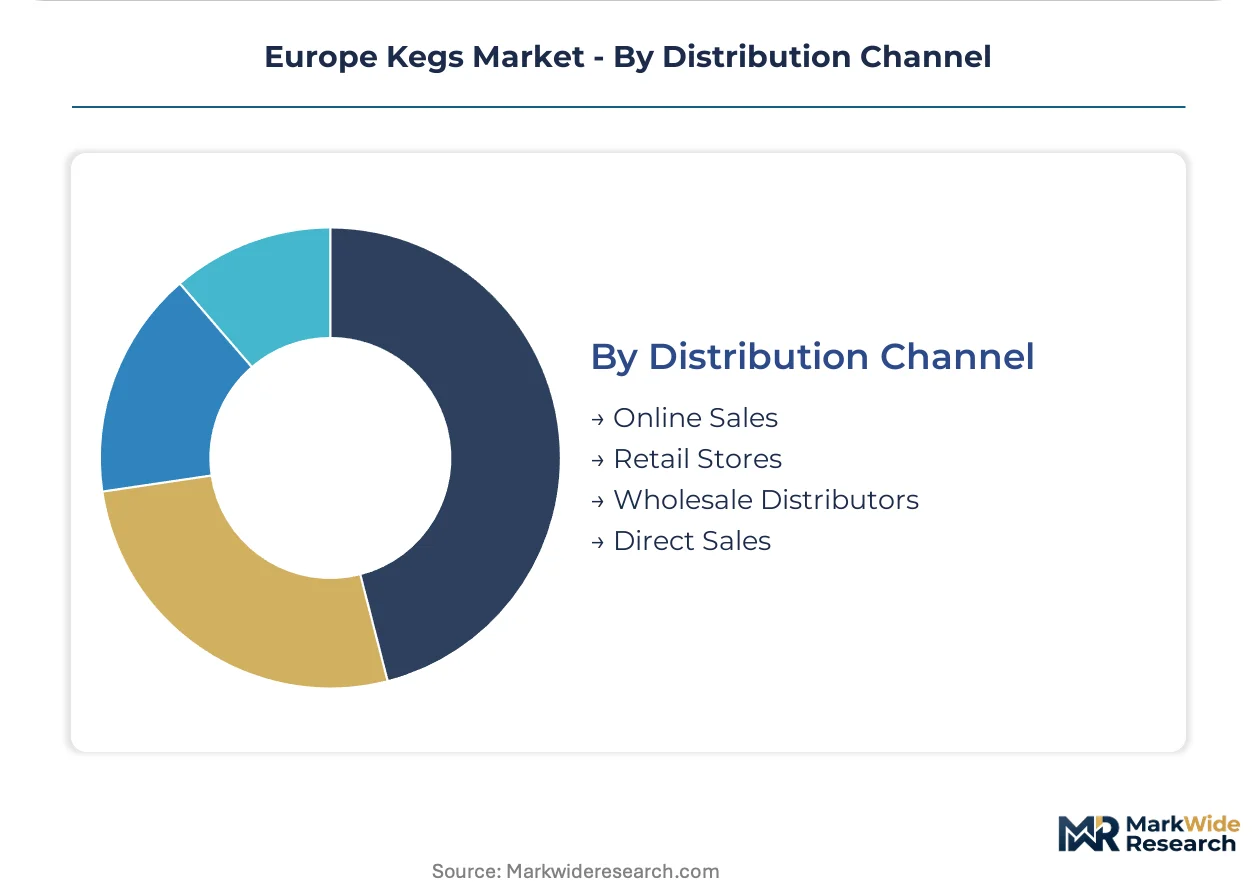
Distribution Channel:
Channel selection reflects customer scale, geographic reach, and service intensity requirements.
- Wholesale Distributors:Traditional keg logistics networks across Germany and Belgium maintain regional warehousing and cleaning infrastructure, though cooperative purchasing alliances are compressing spot purchasing arrangements.
- Direct Sales:Large fleet operators and major brewery groups bypass intermediaries for volume procurement, locking in multi-year supply agreements with THIELMANN and BLEFA for standardized formats.
- Online Sales:Emerging channel for 5L mini-keg retail and replacement component procurement.
- Retail Stores:Limited presence concentrated in homebrewing supply and specialty beverage equipment.
Logistics infrastructure anchors in Wholesale Distributors. Contract innovation is advancing through Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's dense brewery clustering generates concentrated procurement volumes for reusable steel keg formats across Central Europe. The EU's Packaging and Packaging Waste Regulation creates divergent compliance timelines across member states. REACH mandates and national weights and measures authorities shape material selection and fleet certification protocols.
Germany
REACH compliance mandates under ECHA jurisdiction disqualify lower-grade steel alloys from food-contact applications across Bavarian brewing operations. The KBA enforces calibration protocols that determine market access for keg fleet operators. Dense craft producer clustering in Mittelfranken generates pooled procurement volumes for standardized 30L formats through cooperative purchasing alliances.
Czech Republic
Bohemian brewery density creates concentrated demand for 20L and 30L DIN-norm standardized keg formats. National implementation of EU Green Deal Extended Producer Responsibility frameworks recalibrates total cost of ownership calculations between reusable and single-trip packaging. The Plzeň and Prague industrial corridors anchor stainless steel keg procurement for premium beer export operations.
Belgium
Specialty brewing operations in Flanders and Wallonia drive demand for precision-engineered custom-capacity kegs. CE marking and PED compliance timelines for new keg designs extend 8-14 months, delaying product launches. Brussels-based hospitality supply chains prioritize valve interoperability and pressure equipment certification compliance for draft-dispensing venues.
Netherlands
Third-party keg pooling services concentrate bargaining power and drive vendor consolidation toward single-source fleet management contracts. The EU F-Gas Regulation tightens restrictions on hydrofluorocarbon seals used in keg valve assemblies. Rotterdam and Amsterdam logistics hubs anchor RFID-enabled fleet tracking system deployment across Benelux distribution networks.
Poland
Underpenetrated brewery density in Lesser Poland and Silesian Voivodeships offers first-mover positioning for keg fleet operators establishing regional logistics hubs. National transposition of EU packaging waste directives accelerates replacement cycles from single-use formats. Kraków and Katowice emerging craft clusters generate nascent procurement volumes for 20L standardized steel formats.
Europe Kegs Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and customization depth. The vendor base stratifies between high-volume standardized producers and precision-engineering specialists serving niche craft segments. Three archetypes dominate: German-centered stainless steel fabricators with multi-decade fleet supply relationships, specialized valve system suppliers capturing premium export compliance demand, and plastic keg converters exploiting seasonal event logistics. Competitive moves concentrate on capacity expansion in Central European manufacturing corridors and strategic partnerships with third-party pooling services.
Among German fabricators, THIELMANN The Container Company, BLEFA GmbH, and Julius Kleemann GmbH & Co.KG occupy distinct positioning tiers. THIELMANN represents the scale-driven archetype with broad Central European supply coverage. BLEFA exemplifies the premium-tier specialist serving high-grade export requirements. Julius Kleemann sits within the custom-engineering niche addressing craft producer demand for non-standard capacities. These three entities collectively anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| NDL Keg Europe |
| BLEFA GmbH |
| Julius Kleemann GmbH & Co.KG |
| The Metal Drum Company |
| Petainer Ltd. |
| Schaefer Container Systems |
| THIELMANN The Container Company |
| NEW MAISONNEUVE KEG |
| KeyKeg |
| Others |
Supply & Pricing Matrix
EU Green Deal Extended Producer Responsibility frameworks gate qualified supply for reusable steel keg manufacturers while creating premium-tier pricing access for REACH-compliant producers serving Bavarian and Bohemian brewery clusters. Nickel price volatility in AISI 304 stainless steel production compresses margin structures, forcing tiered pricing differentiation between certified high-grade fabricators and lower-tier competitors facing ECHA disqualification.
Pricing Analysis
Input-cost pass-through from Indonesian and Russian nickel supply disruptions drives pricing stratification across premium, standard, and economy tiers in European keg procurement. Price differentiation hinges on REACH certification grade and volume scale, with cooperative purchasing alliances in Mittelfranken extracting favorable terms through aggregated 30L format demand. Cost compression in economy-tier plastic keg alternatives is intensifying because PET converters exploit seasonal event logistics without return infrastructure. Craft producers in Belgium and the Netherlands exhibit highest price sensitivity, while premium export breweries in Germany prioritize pre-certified valve systems to compress compliance timelines.
Supply Chain Analysis
Freight cost differentials between German manufacturing corridors and Polish emerging craft clusters anchor supply chain configuration for reusable steel keg distribution. Geographic supply concentration centers on Germany, the Czech Republic, and Belgium, with raw material dependencies drawing from Indonesian nickel, Ukrainian steel feedstock, and specialized fluoropolymer valve components. Single-source vulnerability in TIG welding certification for food-grade pressure vessels creates acute talent scarcity across Central European manufacturing regions. Distribution runs through third-party pooling services in Germany and the Netherlands that consolidate vendor relationships toward single-source fleet management contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's underpenetrated brewery density versus Germany's saturated craft cluster creates a geographic-arbitrage play, as Extended Producer Responsibility cost differentials between national transposition timelines shift total cost of ownership calculations toward reusable formats.
For Market Incumbents: Acquire specialized welding certification programs and TIG training infrastructure to lock in scarce manufacturing talent before competitors. Defend against plastic keg substitution by embedding RFID tracking systems that modularize fleet performance contracts, while expanding captive valve system production to compress CE marking and PED compliance timelines for premium export customers. For New Entrants and Emerging Players: Direct-to-consumer online channels for 5L mini-keg retail offer the lowest barrier to entry against entrenched hospitality supply relationships. Target Lesser Poland and Silesian Voivodeships for first-mover regional logistics hub establishment, leveraging cooperative purchasing alliance structures proven in Mittelfranken to aggregate nascent craft producer demand for standardized 20L formats. For Investors and Strategic Acquirers: Roll-up economics work for precision-engineering specialists serving niche craft segments because valve interoperability friction between DIN and Euro norm standards fragments multi-country brewery procurement. Mid-cap custom-capacity fabricators with established ECHA pre-certification represent the optimal acquisition target archetype. Watch for Polish national transposition of EU packaging waste directives as the signal indicating accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valve System Production | Captive supply of pre-certified fluoropolymer seals compresses PED compliance timelines for German export breweries. |
| Regional Logistics Hub Expansion | Polish hub placement in Kraków captures emerging craft cluster demand before incumbent pooling services consolidate. |
| RFID Fleet Tracking Deployment | Embedded tracking at valve spear and chime intersection enables outcome-based performance contracts with Dutch distributors. |
| Cooperative Purchasing Alliance Formation | Aggregated demand structures in Bavaria extract volume pricing leverage against THIELMANN and BLEFA supply dominance. |
| TIG Welding Certification Investment | Scarce talent pools in Central European manufacturing regions create defensive moat for qualified production capacity. |
Research Methodology
Coverage spans Germany, the Czech Republic, Belgium, the Netherlands, and Poland, with primary inputs from each market combining interviews with brewery procurement directors, keg fleet operations managers, ECHA regulatory compliance officers, and stainless steel fabrication plant engineers. Secondary validation draws from EU Packaging and Packaging Waste Regulation implementation trackers, ECHA REACH substance restriction databases, German KBA calibration protocol filings, and Benelux customs trade data. Bottom-up brewery fleet sizing triangulates against top-down steel consumption estimates for pressure vessel applications.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include material type, end-user archetype, size capacity, and distribution channel configuration, with additional granularity on REACH compliance tier and national EPR implementation status. CAGRs derive from historical fleet turnover patterns, replacement cycle compression under regulatory mandates, and craft brewery formation rates in underpenetrated regions. Nickel price volatility scenarios and F-Gas Regulation phase-out timelines feed sensitivity analysis.
Regulatory implementation delays, nickel supply disruption severity, and plastic keg substitution elasticity are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
Hip Flask Market
Alcoholic Beverages
Asia-Pacific Alcohol E-Commerce Market
Alcoholic Beverages
Roasted Malt Market
Alcoholic Beverages
Winetainer Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Asia Pacific Wine Coolers Market
Alcoholic Beverages
GCC Beer Market
Alcoholic Beverages
North America Spirits Market
Alcoholic Beverages
Cider Market
Alcoholic Beverages
Middle East and Africa Beer Market
Alcoholic Beverages
Cannabis Drinks Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
RTD Canned Cocktail Market
Alcoholic Beverages
Crystal Malt Market