
 Craft Wine Market | 2026-2036
Craft Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Wine Market Intelligence
Argentina's Mendoza province is rewriting supply dynamics through high-altitude vineyard expansion and export-oriented infrastructure. Jackson Family Wines leverages vertical integration from estate vineyards to direct-to-consumer channels, sustaining margin control across the value chain. Treasury Wine Estates anchors its competitive position through Penfolds-brand equity and calibrated allocation strategies in Asian markets. E&J Gallo Winery dominates volume-scale craft-adjacent production while navigating premiumization pressures through selective portfolio elevation.
Craft wine denotes small-production, terroir-expressive wine typically manufactured in lots under fifty thousand cases annually, employing native-yeast fermentation, minimal sulfur intervention, and hand-harvested fruit to preserve site-specific character. Its commercial purpose centers on authenticated provenance narratives that command price premiums over commoditized bulk wine. Red wine and sparkling wine segments lead value generation, with the former benefiting from aging-investment collectibility and the latter from celebratory occasion-based consumption. Direct-to-consumer distribution posts the fastest structural expansion, disintermediating traditional three-tier systems through winery subscription clubs and allocated release models that capture full retail margin.
USDA National Organic Program standards and TTB label-approval requirements govern domestic craft wine composition claims and interstate commerce eligibility, while EU Protected Designation of Origin frameworks shape export access for American producers seeking European shelf placement. FDA Food Safety Modernization Act provisions now extend to winery processing facilities, elevating hazard-control documentation burdens for small producers. Stakeholders must monitor evolving state direct-shipping legislation and carbon-footprint disclosure mandates as dual determinants of competitive access and consumer trust architecture.
Market Dynamics
Direct-to-consumer channel expansion is fragmenting the three-tier distribution system, compressing wholesale margins while elevating producer control over pricing and customer relationships.
Growth Catalysts
- USDA National Organic Program certification:Organic labeling commands shelf price premiums in retail channels and unlocks placement in natural-foods grocers. Compliance documentation requirements filter out bulk competitors.
- Boutique hospitality venues:Independent restaurants and wine bars in urban centers prioritize small-lot allocations for menu differentiation. Sommelier-driven purchasing elevates discovery-oriented producers.
- Native-yeast fermentation protocols:Low-intervention winemaking techniques differentiate terroir-expressive offerings from industrial alternatives. Consumer education through winery tasting rooms accelerates acceptance of bottle variation.
Market Restraints
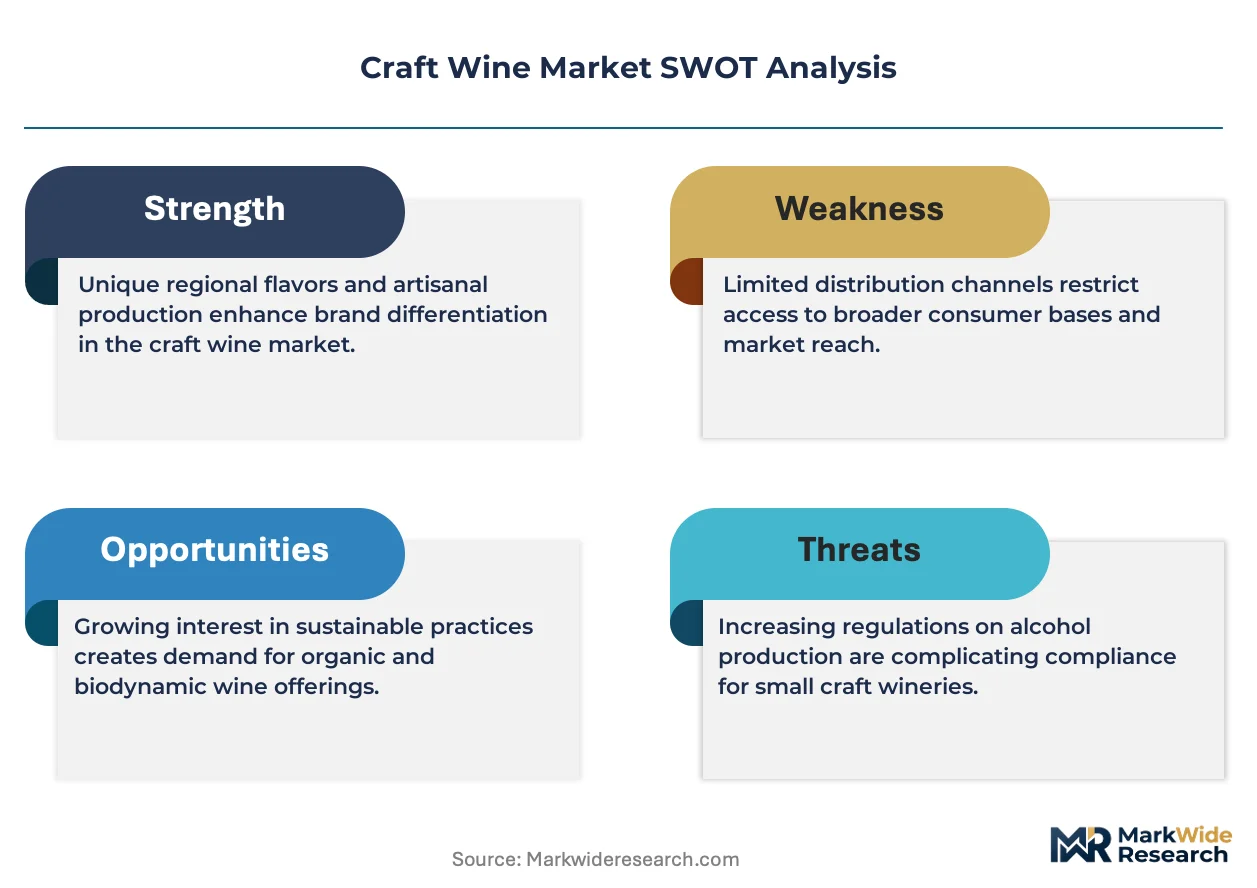
- TTB label-approval bottlenecks:Federal formula and label review timelines extend six to nine months for new SKUs, delaying seasonal releases and cash conversion.
- Oak barrel supply concentration:French cooperage dominates premium barrel sourcing, exposing small producers to euro-denominated cost volatility and allocation rationing during vintages.
- Climate-induced vintage variation:Heat spikes and drought pressure in California's Central Coast compress yield predictability and complicate multi-year financial planning.
Strategic Opportunities
- State direct-shipping liberalization:Remaining control-state jurisdictions in the southeastern United States are loosening interstate shipment restrictions, opening captive markets to out-of-state producers.
- Carbon-footprint disclosure mandates:Early adoption of lifecycle emissions accounting positions craft wineries for EU Green Deal-aligned import requirements and climate-conscious retail buyer scorecards.
- Subscription club models:Allocated release programs convert tasting-room visitors into recurring revenue streams with 40-60 percent lower customer acquisition costs than wholesale channel development.
Industry Challenges
- Winemaker talent scarcity:Experienced cellar masters with low-intervention expertise command premium compensation in competitive labor markets, constraining expansion timelines for emerging producers.
- FDA Food Safety Modernization Act compliance:Hazard-analysis documentation and preventive-controls requirements impose administrative burdens disproportionate to small-production scale, necessitating specialized consulting expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Wine Market |
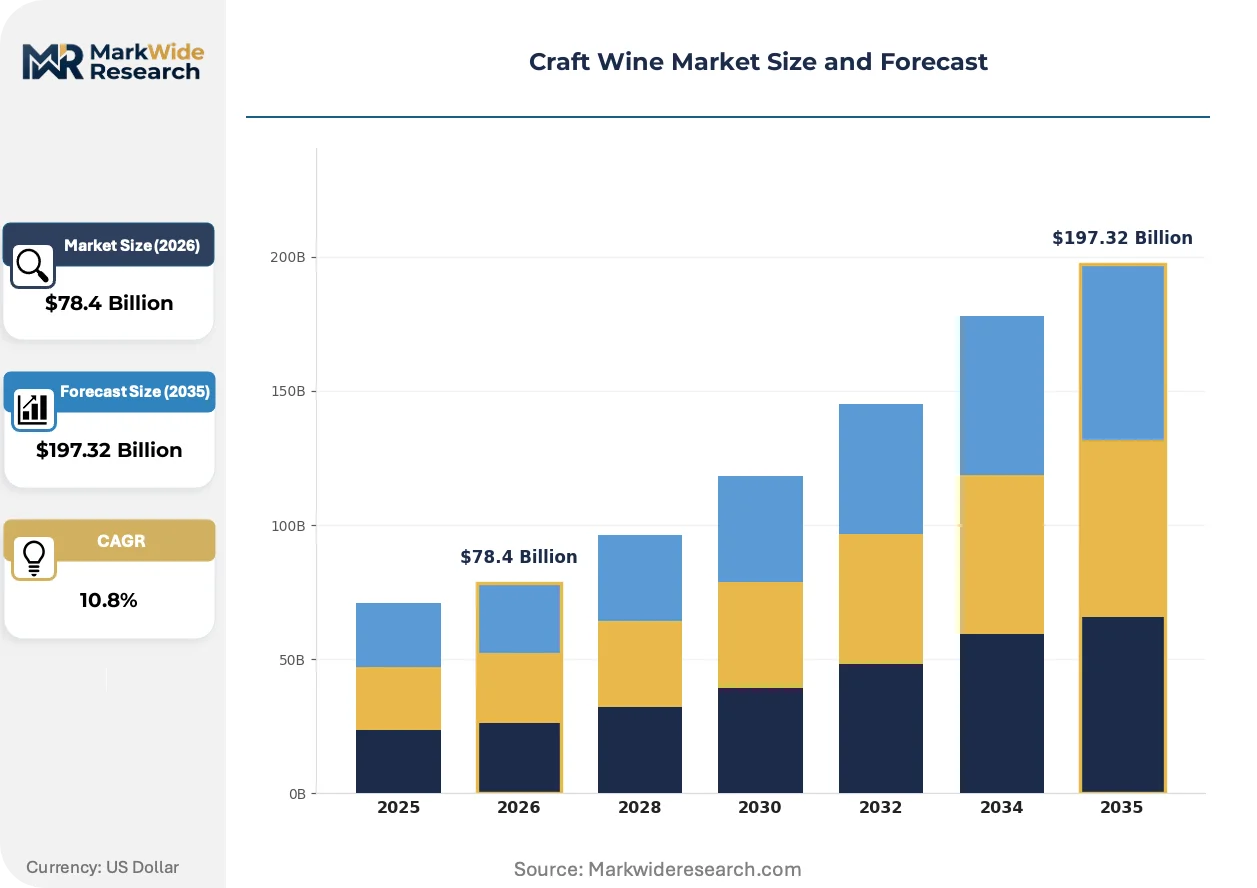
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $197.32 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé Wine, Sparkling Wine, Dessert Wine Grape Variety: Cabernet Sauvignon, Chardonnay, Merlot, Pinot Noir, Sauvignon Blanc, Syrah Distribution Channel: Specialty Stores, Online Retailers, Wine Bars, Restaurants, Direct to Consumer Consumer Type: Connoisseurs, Casual Drinkers, Collectors, Event Planners, Hospitality Professionals |
| Companies Covered | Jackson Family Wines, Treasury Wine Estates, E&J Gallo Winery, Sine Qua Non, Ste. Michelle Wine Estates, The Wine Group, Trinchero Family Estates, Ramey, Vintage Wine Estates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Wine Market Strategic Shifts & Innovations
Precision viticulture and alternative packaging formats are compressing traditional production timelines while expanding occasion-based consumption beyond conventional bottle formats.
Electrochemical sensors for real-time vineyard monitoring is migrating from research-station pilots to commercial estate deployment. High-altitude producers in Argentina's Uco Valley are adopting soil-moisture telemetry to optimize irrigation scheduling during drought vintages. This technology is compressing the gap between sensory vineyard assessment and data-driven canopy management decisions.
EU Protected Designation of Origin framework revisions are tightening geographic indication enforcement for imported wines. American producers seeking European shelf placement must intensify documentation of single-vineyard sourcing and vintage authenticity. Napa Valley estates with established export programs are accelerating TTB certificate-of-origin applications to preempt customs delays.
Consumer purchasing through winery mobile applications is displacing traditional allocation-list email campaigns. Younger collector segments in urban markets expect instant-release notifications and one-click reservation systems. This behavioral shift concentrates most visibly in California's direct-to-consumer channel, where digital-native wineries capture disproportionate share of new-customer acquisition.
Craft Wine Market Segmentation
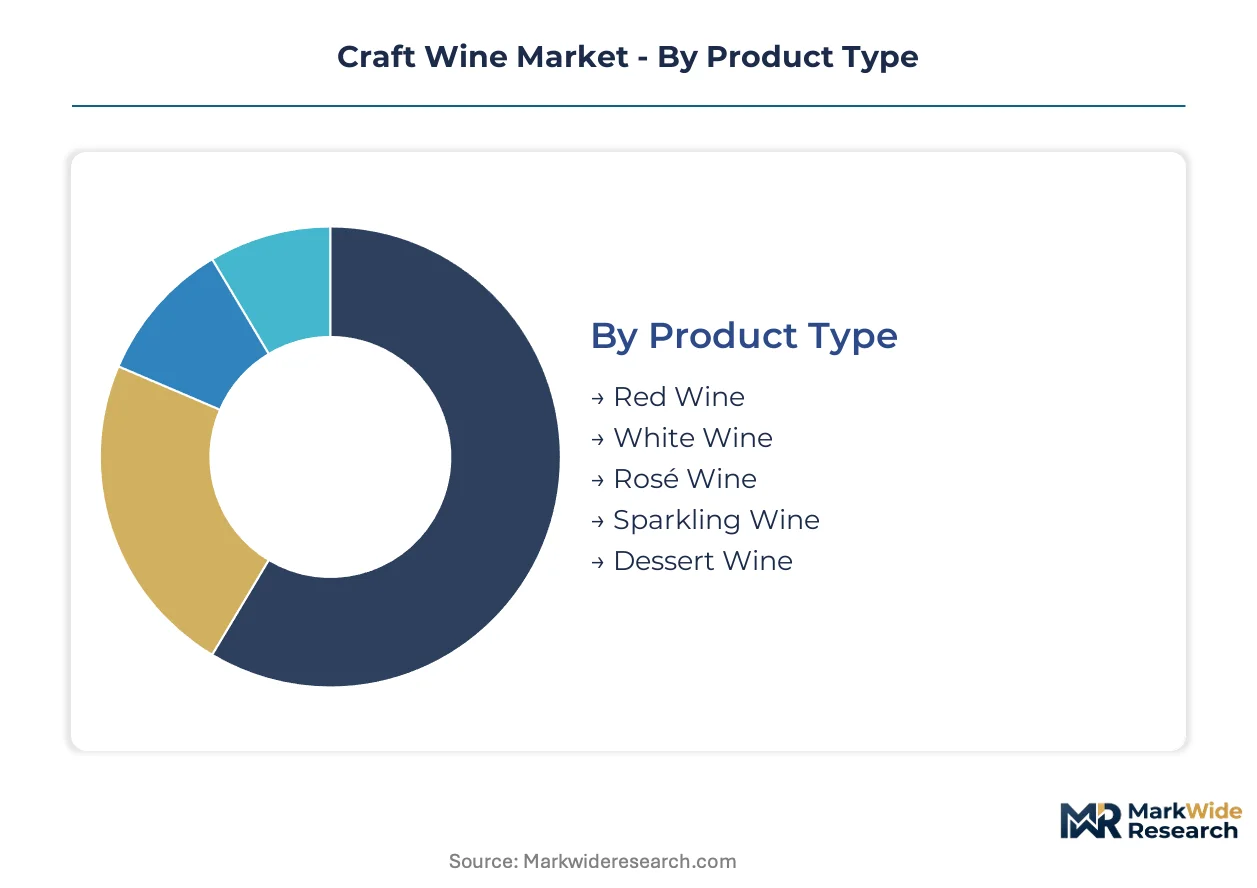
Craft wine segmentation reveals how production scale, distribution access, and consumer sophistication intersect to create distinct commercial territories. Understanding these boundaries helps producers allocate cellar capacity and marketing resources toward the highest-margin configurations.
Product Type:
Winemaking protocols diverge sharply across color and effervescence categories, determining barrel investment, aging timelines, and release cadence.
- Red Wine:Extended skin-contact fermentation extracts phenolic compounds that support decade-long cellar aging. Collector demand concentrates in Napa Valley and Bordeaux-style blends, where provenance documentation commands allocation-list premiums.
- Sparkling Wine:Traditional method secondary fermentation demands specialized equipment and extended tirage aging. Celebratory occasion-based consumption in urban hospitality venues drives recurring volume despite higher production complexity.
- White Wine:Stainless steel fermentation preserves aromatic freshness for early release. Sauvignon Blanc from cooler coastal sites attracts sommelier placement in seafood-focused restaurants.
- Rosé Wine:Provence-style pale extraction requires precise saignée timing. Seasonal purchasing patterns compress sales windows to spring and summer months.
- Dessert Wine:Late-harvest and botrytized production depends on specific climatic conditions. Limited vintage viability restricts commercial scale for most producers.
The dominant share belongs to Red Wine, while Sparkling Wine is closing the gap fastest.
Grape Variety:
Variety selection locks in vineyard site requirements, tariff exposure, and export market access for decades.
- Cabernet Sauvignon:Thick skins and loose clusters tolerate heat accumulation in hillside sites. Chinese import tariffs on Australian labels have redirected Asian demand toward California and Chilean expressions.
- Chardonnay:Neutral flavor profile responds dramatically to winemaker intervention choices. Burgundian-inspired producers in Sonoma Coast emphasize native-yeast fermentation for differentiation.
- Pinot Noir:Thin skins and tight clusters demand cool-climate precision. Willamette Valley and Central Otago sites command price premiums for color stability and aromatic complexity.
- Merlot:Early ripening avoids autumn rain risk in maritime climates. Right Bank Bordeaux styling influences blending proportions in Washington State.
- Sauvignon Blanc:Pyrazine expression divides consumer preference between grassy and tropical profiles. Marlborough supply gluts pressure pricing for New World alternatives.
- Syrah:Rhône-origin versatility spans Côte-Rôtie elegance to Barossa power. Hermitage pricing benchmarks support premium positioning for cooler-site expressions.
Cabernet Sauvignon holds the largest planted acreage, though Pinot Noir is expanding most quickly in premium-tier vineyard acquisitions.
Distribution Channel:
Channel choice determines margin capture, customer data ownership, and brand narrative control.
- Direct to Consumer:Subscription clubs and allocated releases capture full retail margin while building proprietary customer databases. TTB compliance costs filter out smaller competitors.
- Specialty Stores:Curated independent retailers provide discovery-oriented placement for limited-production labels. Staff education investments convert shelf position into velocity.
- Online Retailers:Third-party platforms expand geographic reach but compress margins and obscure customer relationships. State shipping restrictions fragment addressable markets.
- Restaurants:Sommelier-driven list placement builds prestige and trial among high-frequency drinkers. Coravin preservation technology extends by-the-glass program viability.
- Wine Bars:Dedicated tasting venues prioritize rotating small-lot selections. Urban density in Brooklyn and Portland supports dedicated craft-focused concepts.
Direct to Consumer commands the highest margin per case, while Online Retailers are scaling most rapidly in new-customer acquisition.
Consumer Type:
Purchasing behavior splits between expertise-driven discovery and occasion-driven convenience.
- Connoisseurs:Deep category knowledge supports premium pricing for single-vineyard designates. Vertical collection building drives allocation-list loyalty.
- Collectors:Investment-oriented purchasing treats wine as alternative asset class. Provenance documentation and critic scores dominate acquisition criteria.
- Casual Drinkers:Label recognition and price accessibility determine trial. Rosé and entry-level sparkling categories capture this volume.
- Hospitality Professionals:Sommeliers and beverage directors filter options for end-consumer exposure. List placement decisions concentrate discovery power.
- Event Planners:Volume purchasing for weddings and corporate functions prioritizes consistent supply. Sparkling wine dominates this segment.
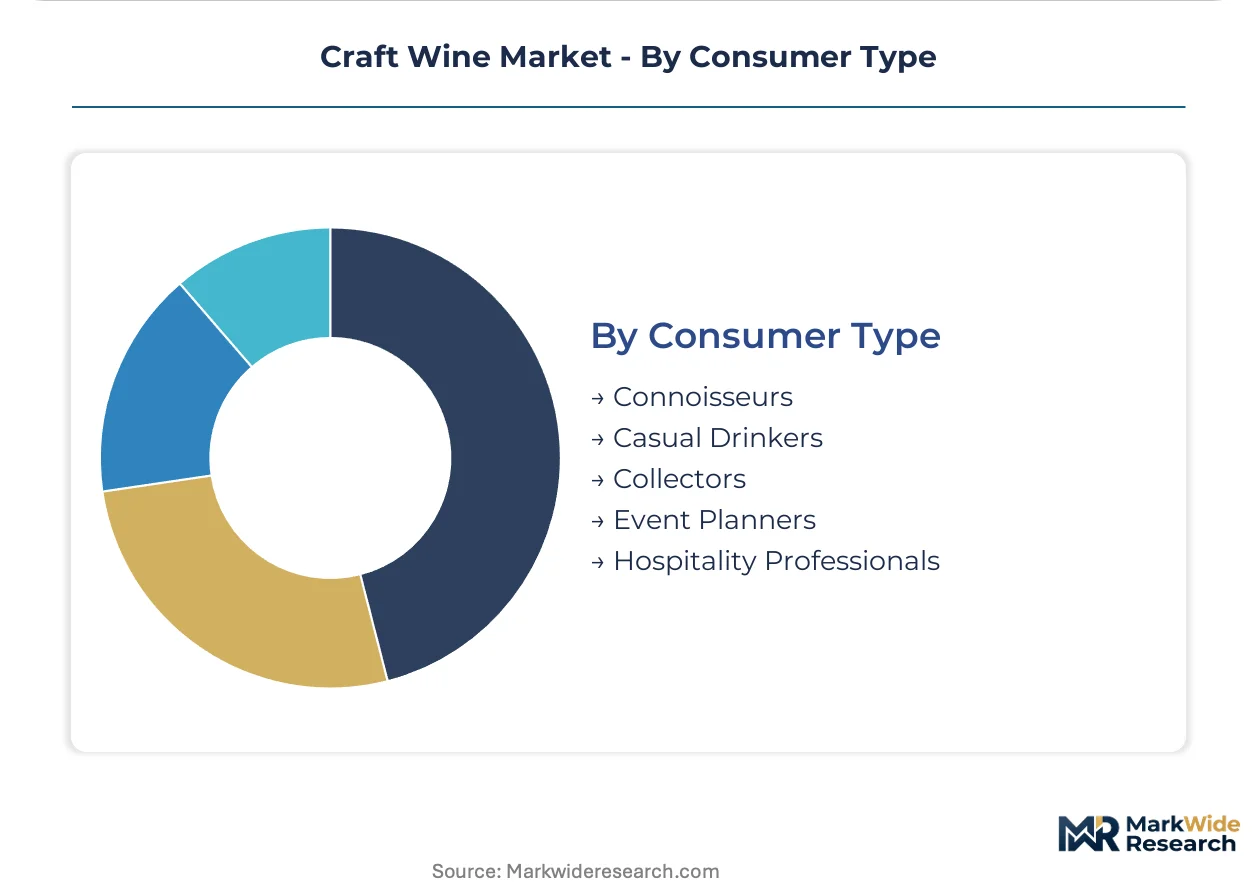
Connoisseurs generate the highest per-capita revenue, though Casual Drinkers represent the broadest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA National Organic Program certification anchors United States craft wine governance, while EU Protected Designation of Origin frameworks and state-level direct-shipping statutes reshape competitive access across producer geographies.
United States
Napa Valley and Sonoma County estate vineyards drive terroir-expressive production, with sommelier-driven restaurant placement elevating small-lot allocations. TTB label-approval requirements govern interstate commerce eligibility, creating six-to-nine-month bottlenecks for seasonal releases. California's Central Coast clusters concentrate precision viticulture investment, where Paso Robles producers expand high-density planting to capture premium positioning.
France
Burgundy and Bordeaux appellations command allocation-list premiums through enforced geographic indication protocols. EU Protected Designation of Origin framework revisions tighten enforcement for imported competitors, reinforcing domestic shelf placement advantages. Champagne houses in Épernay sustain traditional-method production dominance despite climate-induced harvest compression.
Italy
Tuscany and Piedmont estates leverage DOCG classification hierarchies to differentiate reserve-tier pricing from entry-level alternatives. ANSM enforces additive disclosure requirements that filter out bulk competitors from premium channel placement. Barolo producers in Cuneo province intensify single-vineyard bottling to satisfy collector demand for provenance documentation.
Argentina
Mendoza province high-altitude vineyards in the Uco Valley rewrite supply dynamics through export-oriented infrastructure expansion. The national agricultural regulator enforces geographic indication standards that elevate Malbec-origin claims in European markets. Luján de Cuyo sub-regional producers adopt soil-moisture telemetry to optimize irrigation during drought vintages.
Australia
Barossa Valley and Margaret River estates navigate Chinese tariff redirection toward Southeast Asian market development. TGA-aligned food safety documentation requirements now extend to winery processing facilities, elevating hazard-control burdens. Adelaide Hills producers accelerate carbon-footprint accounting adoption to preempt EU Green Deal-aligned import requirements.
Craft Wine Market Key Industry Players
Estate-anchored family operations and multinational portfolio aggregators split the market into divergent margin-capture models. Consolidation pressure concentrates among mid-scale producers seeking distribution leverage against wholesale margin compression. Three archetypes dominate: terroir-focused single-estate houses, multi-brand portfolio platforms, and volume-scale craft-adjacent producers. Competitive moves center on direct-to-consumer channel expansion and selective vineyard estate acquisition.
Within the estate-anchored tier, Jackson Family Wines exemplifies vertical control from vineyard through allocation-list distribution, while Treasury Wine Estates occupies a position as multi-brand platform aggregating Penfolds-equity across Asian market development. E&J Gallo Winery anchors the volume-craft interface, navigating premiumization pressures through portfolio stratification.
| Leading Market Players |
|---|
| Jackson Family Wines |
| Treasury Wine Estates |
| E&J Gallo Winery |
| Sine Qua Non |
| Ste. Michelle Wine Estates |
| The Wine Group |
| Trinchero Family Estates |
| Ramey |
| Vintage Wine Estates |
| Others |
Cost & Logistics Intelligence
French cooperage concentration in Limousin and Allier forests anchors barrel cost structures, translating euro-denominated volatility directly into margin compression for Napa and Sonoma producers lacking captive stave sourcing. This upstream bottleneck forces pricing discipline downstream, where allocation-list premiums must absorb currency-driven cost spikes or surrender cellar-door profitability.
Pricing Analysis
Napa Valley commands three-to-four-fold premiums over Central Valley alternatives, with price stratification tracking terroir designation density and critic-score visibility. Pricing stratifies across estate-bottled single-vineyard designates, regional appellation blends, and bulk-wine alternatives. Cost compression in entry tiers intensifies as Argentine and Chilean imports capture casual-drinker volume. Connoisseurs exhibit lowest price sensitivity, prioritizing provenance documentation over per-bottle expenditure.
Supply Chain Analysis
Grape supply draws from California, France, and Argentina as the three dominant sourcing geographies for premium-tier production. Oak barrel, cork, and glass bottle dependencies expose producers to Atlantic shipping lane congestion and energy-cost pass-through. Single-source vulnerability concentrates in French cooperage allocation systems. Distribution runs through a hybrid structure blending direct-to-consumer subscription clubs with fragmented wholesale three-tier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from ready-to-drink cocktails and non-alcoholic alternatives capturing occasion-based consumption. Defense requires deepening moats around experiential authenticity that commoditized substitutes cannot replicate.
For Market Incumbents: Build allocation-list exclusivity moats through vertical vineyard acquisition in Napa and Sonoma. Expand estate-controlled acreage to secure fruit supply against climate-induced vintage compression. Deepen sommelier-education investments to defend on-premise placement against canned-wine and RTD encroachment.
For New Entrants and Emerging Players: Southeastern United States control-state liberalization presents the most penetrable geographic whitespace. Target direct-shipping eligibility in Georgia and Alabama as regulatory barriers fall. Anchor market entry through subscription club models capturing full retail margin before wholesale channel development.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed portfolio platforms seeking exit liquidity. Five-to-ten-year viability favors estate-anchored operations with demonstrated direct-to-consumer conversion rates. Monitor state direct-shipping legislative calendars as inflection signals for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Subscription clubs capture full retail margin while building proprietary customer databases for allocated releases. |
| Estate Vineyard Acquisition | Vertical control from fruit sourcing through bottling insulates margin structures from barrel-cost volatility. |
| USDA Organic Certification Investment | Compliance documentation filters bulk competitors while unlocking natural-foods grocer placement premiums. |
| Carbon-Footprint Disclosure Program | Lifecycle emissions accounting preempts EU Green Deal import requirements and climate-conscious retail scorecards. |
| Sommelier Education Partnership | Staff training investments convert independent restaurant placement into sustained velocity for small-lot allocations. |
Research Approach
A standing panel of winemakers, sommeliers, distributor portfolio managers, and TTB compliance officers provided ongoing calibration throughout the study period. Primary interviews with estate vineyard directors and direct-to-consumer channel heads combined with secondary validation against USDA National Organic Program filings, TTB label-approval databases, and state alcohol beverage control statutes. Bottom-up volume modeling triangulated against top-down value projections across product type, grape variety, distribution channel, and consumer type segments.
Scenario-bracketing anchored the analytical framework, with outputs reflecting conservative, baseline, and expansion assumptions across the projection horizon. Segmentation dimensions modeled include wine color category, production scale tier, distribution channel mix, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for structural channel shifts and certification adoption curves. Forecast inputs incorporated climate-induced vintage variation patterns and state direct-shipping legislative momentum.
Practitioners should monitor TTB label-approval backlog durations and euro-dollar exchange rate volatility for early signals requiring forecast revision. Cross-checking against customs import volume data and allocation-list release velocity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Sparkling Red Wine Market
Alcoholic Beverages
Yorker Spouts Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
South America Alcoholic Beverages Market
Alcoholic Beverages
Wine Bags Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Specialty Beer Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Fortified Wine Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Moscato Wine Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Fruit Wine Market