
 Door and Window Alarm Market | 2026-2036
Door and Window Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Door and Window Alarm Market Analytics
CE marking under the EU Radio Equipment Directive is restructuring the cost-of-entry calculus for connected door and window alarms sold in European markets. Honeywell International leverages its broad regulatory compliance infrastructure to sustain market access across multiple jurisdictions. Bosch Security Systems anchors its position through in-house production of magnetic and acoustic sensor modules. Ring competes aggressively on channel control, dominating direct-to-consumer online distribution for DIY installation systems.
Door and window alarms are electromechanical or electronic perimeter security devices that detect unauthorized entry through magnetic contact interruption, infrared beam breakage, or vibration signature analysis, typically operating at detection thresholds between 5-15 millimeters of gap separation or frequency ranges of 20-2000 Hz for glass-break variants. Their primary commercial purpose is to trigger audible alerts and transmit signals to monitoring stations or user smartphones upon breach detection. Smart alarms incorporating cellular and Wi-Fi connectivity represent the fastest-expanding product type as consumers demand remote arming and real-time notification capabilities. Magnetic sensors retain the largest installed base due to decades of proven reliability in both residential and commercial end-user applications, though infrared sensors command premium pricing in hospitality settings where aesthetic concealment matters.
The Federal Communications Commission in the United States governs radio frequency emissions for wireless alarm transmitters, while the EU AI Act imposes algorithmic transparency requirements on smart alarm systems employing behavioral analytics. BIS certification in India mandates specific decibel levels and battery backup duration for imported alarm devices, shaping product design for manufacturers targeting that market. Stakeholders must monitor evolving cybersecurity labeling schemes as jurisdictions begin treating connected alarms as critical home infrastructure subject to network security audits.
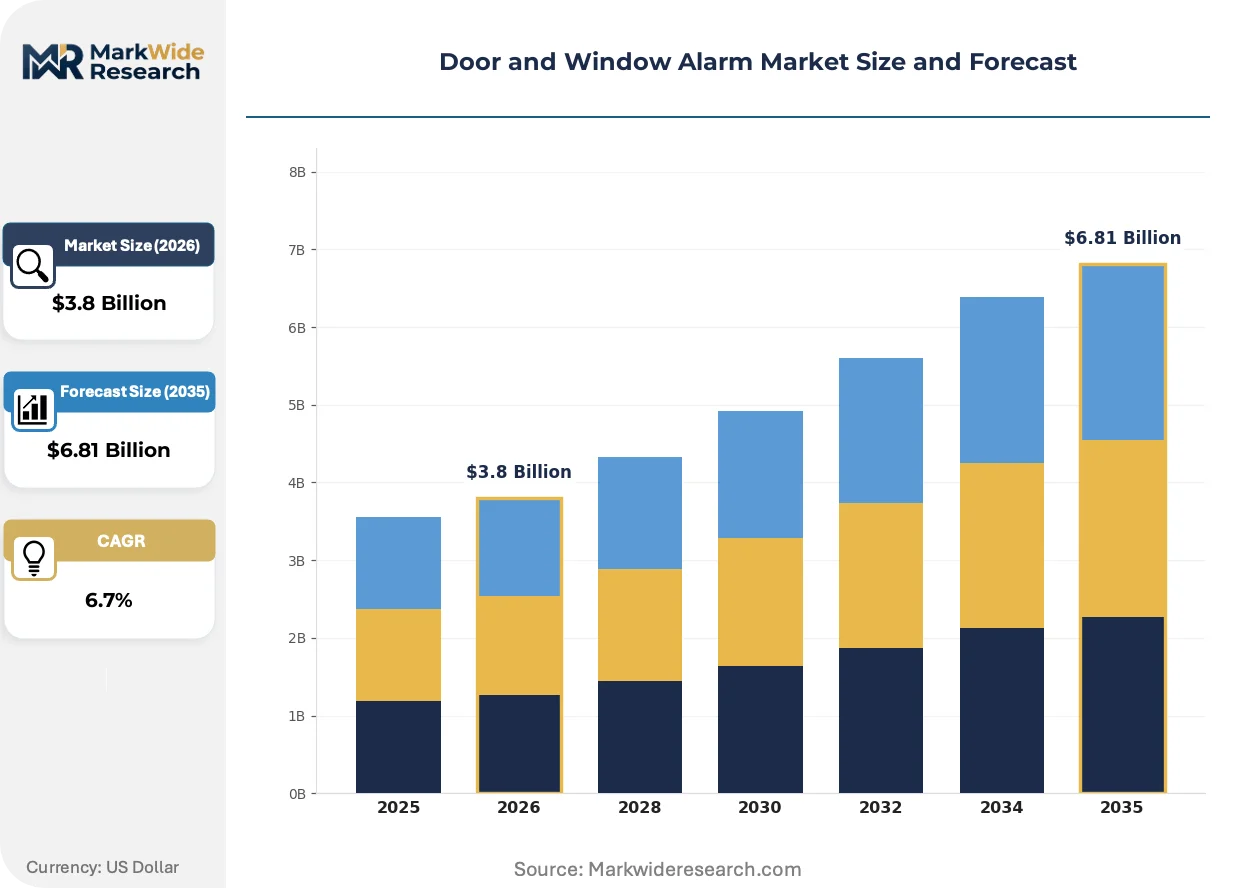
Market Dynamics
Smart home interoperability mandates are forcing manufacturers to rebuild firmware architectures around open protocols, fundamentally altering how door and window alarms connect to broader security ecosystems and home automation platforms.
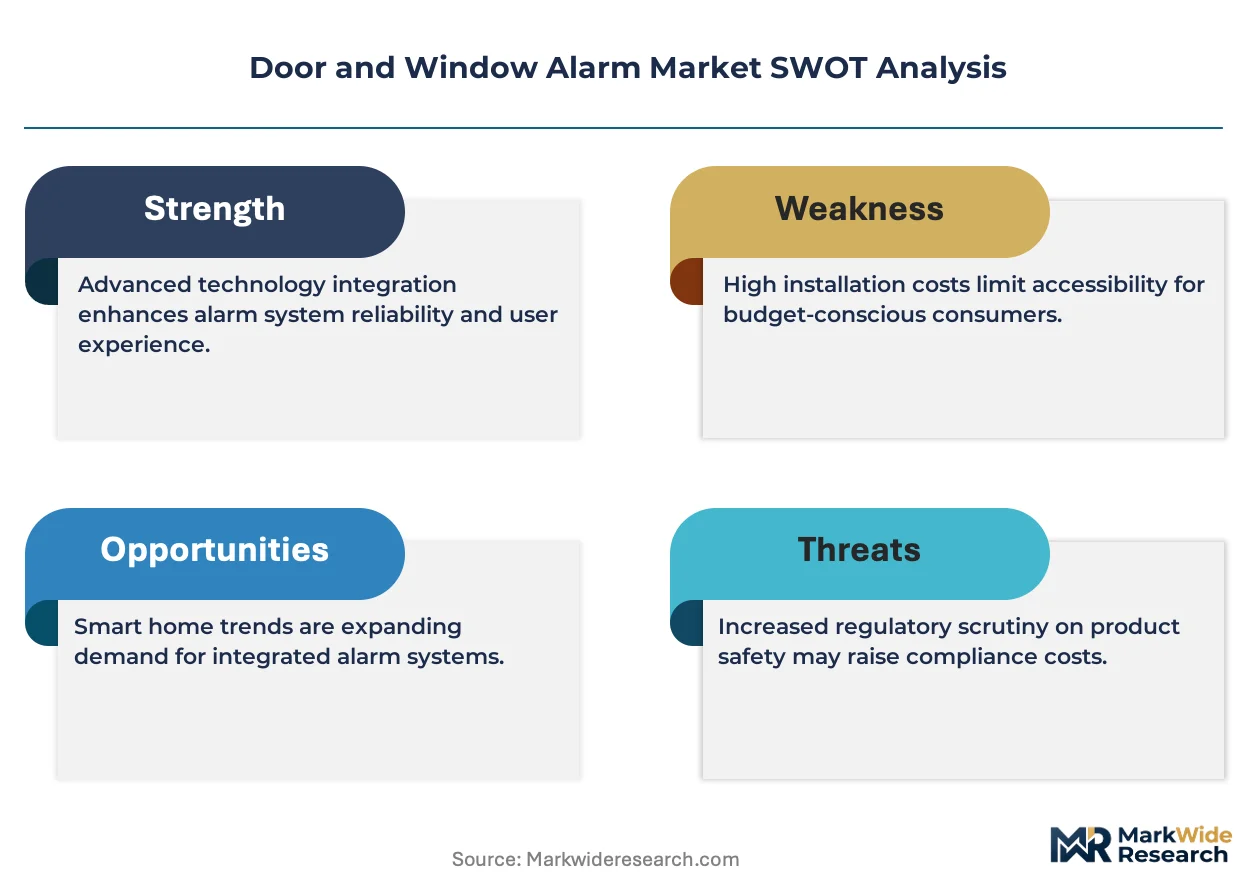
Growth Catalysts
- EU Radio Equipment Directive compliance:CE marking requirements for connected devices are accelerating certification investments among established suppliers, filtering out marginal competitors and consolidating shelf access for compliant brands.
- Insurance-linked demand in Germany:Premium reductions for certified alarm installations are driving replacement cycles among homeowners with legacy unmonitored systems.
- Cellular fallback modules:Broadband outage resilience is overtaking Wi-Fi-only designs as a mandatory specification in professionally monitored residential contracts.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on Chinese cell manufacturers creates input cost volatility and extended lead times for wireless sensor production.
- Magnetic sensor technical ceiling:Detection thresholds below 5 millimeters remain elusive without false alarm trade-offs, limiting penetration into high-precision industrial applications.
- FCC equipment authorization timelines:Radio frequency certification queues for novel transmission protocols are extending product launch windows by four to six months.
Strategic Opportunities
- Rural broadband gaps in the United States:Satellite-connected alarm systems address underserved markets where terrestrial infrastructure remains unreliable.
- Behavioral analytics convergence:Machine learning for occupancy pattern recognition is creating premium tier differentiation beyond simple breach detection.
- India BIS decibel mandates:Localized battery backup specifications are opening design partnerships with domestic electronics assemblers.
Industry Challenges
- Cybersecurity audit preparation:Connected alarm firmware must demonstrate resistance to man-in-the-middle attacks under emerging national labeling schemes.
- Legacy panel integration:Retrofit compatibility with 1990s-era hardwired zones requires specialized bridge hardware and skilled technician deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door and Window Alarm Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Alarms, Wired Alarms, Smart Alarms, Motion Detectors Technology: Infrared Sensors, Magnetic Sensors, Vibration Sensors, Acoustic Sensors End User: Residential, Commercial, Industrial, Hospitality Installation Type: DIY Installation, Professional Installation, Integrated Systems, Retrofit Systems |
| Companies Covered | ASSA ABLOY, Honeywell International, Allegion, Bosch Security Systems, Nabtesco Corporation, SimpliSafe, dormakaba, Ring, ADT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door and Window Alarm Market Evolving Landscape
Detection modalities are fragmenting as end-users reject one-size-fits-all perimeter solutions, creating parallel demand streams for invisible infrared arrays, vibration-sensing glass monitors, and concealed magnetic contacts.
Glass-break detection via acoustic signature analysis is overtaking shock sensors in hospitality and retail deployments where aesthetic constraints prohibit visible hardware. Hotel chains in Japan are specifying ceiling-mounted microphones over frame-mounted contacts to preserve interior design continuity. The shift is compressing demand for traditional magnetic pairs in premium commercial segments.
The EU AI Act's algorithmic transparency requirements are mandating documentation trails for smart alarms employing behavioral analytics. Manufacturers must now maintain audit logs of machine learning model updates and decision thresholds. Systems marketed in France, Germany, and the Netherlands face the strictest compliance timelines.
Direct-to-consumer channel expansion is fragmenting the installer-dependent model that dominated residential alarm sales for decades. Big-box retailers and online marketplaces are capturing specification authority previously held by security dealers. This pattern is most visible in the United States, where DIY system purchases now outnumber professionally installed new accounts in single-family housing.
Door and Window Alarm Market Segmentation
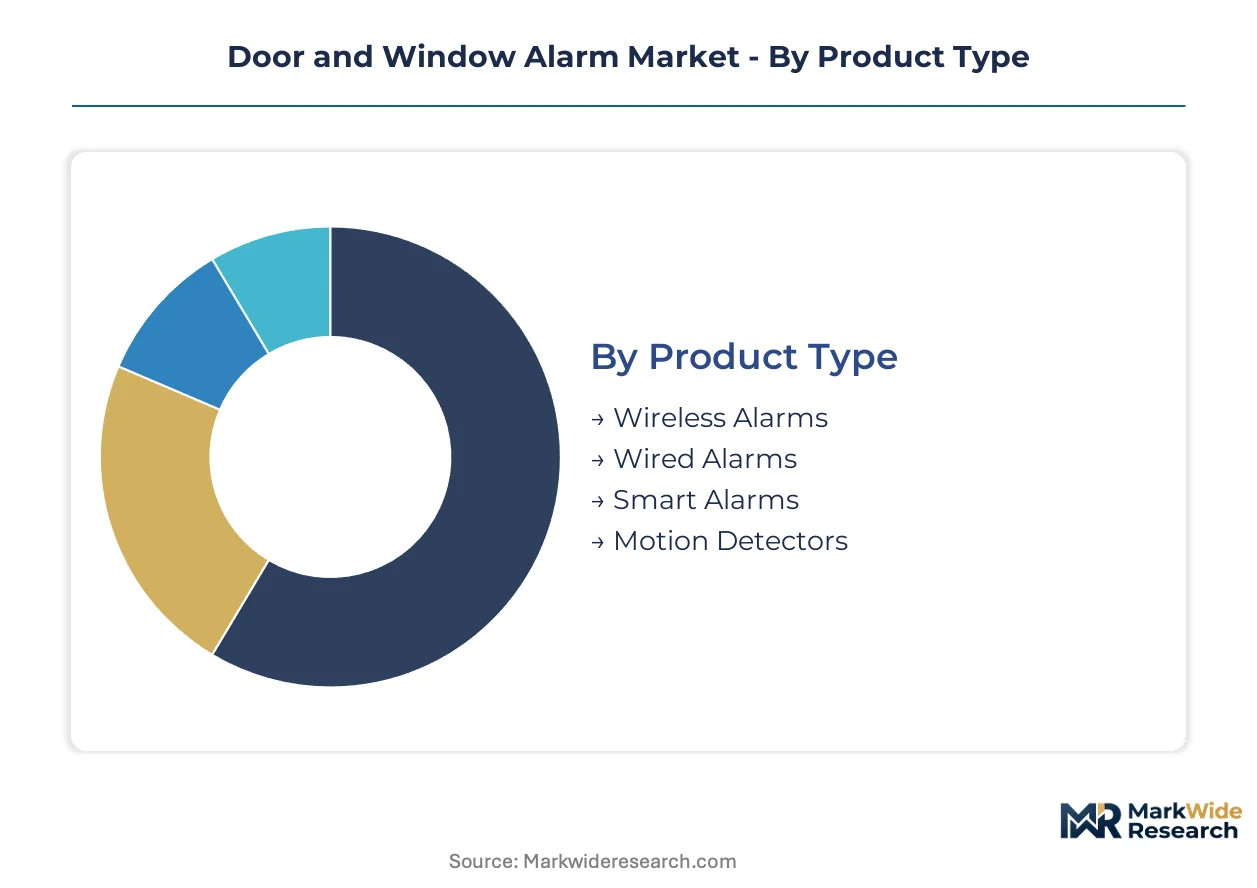
Door and window alarm segmentation reveals how certification burdens, connectivity requirements, and installation complexity create distinct competitive arenas. Manufacturers must align product architectures with the specific compliance and performance demands of each segment tier.
Product Type:
CE marking under the EU Radio Equipment Directive applies differentially across this category, with connected variants facing stricter electromagnetic compatibility testing than hardwired alternatives.
- Wireless Alarms:Battery-powered radio frequency transmitters operating at 433 MHz or 868 MHz bands, requiring FCC Part 15 authorization in the United States and RED compliance in Europe. Demand clusters in German residential retrofits where insurance premium reductions favor certified wireless systems over unmonitored legacy installations.
- Smart Alarms:Cellular and Wi-Fi enabled devices with cloud connectivity, smartphone arming, and real-time notification capabilities. These systems command premium positioning in Japan's urban condominium market where remote monitoring aligns with aging homeowner demographics and professional monitoring service bundling.
- Wired Alarms:Hardwired zone loops connected to central control panels via low-voltage cabling, prevalent in 1990s-era commercial installations. These systems face replacement pressure from wireless retrofit demand but retain installed base in industrial facilities where electromagnetic interference concerns persist.
- Motion Detectors:Passive infrared or microwave-based occupancy sensors often bundled with door and window perimeter protection. Hospitality specifications in France favor ceiling-mounted variants over contact sensors for aesthetic concealment in premium hotel renovations.
Smart alarms sit at the top of the volume ranking, with wireless alarms climbing the fastest.
Technology:
Cost tier differentiation separates premium concealed solutions from standard visible hardware, with acoustic and infrared variants commanding three-to-five-fold price multiples over magnetic contacts in commercial specifications.
- Magnetic Sensors:Reed switch or Hall effect devices detecting gap separation between 5-15 millimeters, the dominant installed base across residential and commercial applications. These sensors anchor Bosch Security Systems' in-house manufacturing strategy, supplying both OEM channels and proprietary alarm lines with captive component supply.
- Infrared Sensors:Active beam interruption or passive thermal detection arrays enabling invisible perimeter protection. Japanese hotel chains specify these for lobby and corridor monitoring where visible hardware conflicts with interior design continuity, driving premium pricing in hospitality procurement.
- Vibration Sensors:Piezoelectric or MEMS-based devices detecting glass fracture signatures through frame-mounted acceleration measurement. These sensors face displacement by acoustic alternatives in retail and hospitality settings where ceiling mounting permits cleaner aesthetic integration.
- Acoustic Sensors:Microphone arrays with frequency analysis algorithms detecting glass-break signatures across 20-2000 Hz ranges. The EU AI Act imposes algorithmic transparency documentation requirements on these systems when behavioral analytics extend beyond simple breach detection.
Magnetic sensors retain the largest installed base, though acoustic sensors are gaining share fastest in premium commercial segments.
End User:
Application context determines connectivity requirements, with monitored residential and commercial contracts demanding cellular fallback modules while industrial settings prioritize hardwired reliability over wireless convenience.
- Residential:Single-family homes and multi-unit dwellings driving DIY installation growth through direct-to-consumer channels. United States demand concentrates in suburban markets where broadband outage resilience has become a mandatory specification in professionally monitored contracts.
- Commercial:Office buildings, retail storefronts, and warehouses requiring centralized monitoring station integration. These installations favor hardwired zones with wireless expansion capabilities, creating hybrid architectures that complicate legacy panel compatibility.
- Industrial:Manufacturing facilities and logistics centers where electromagnetic interference and physical durability requirements exceed residential specifications. Detection thresholds below 5 millimeters remain elusive for magnetic variants without false alarm trade-offs, limiting precision applications.
- Hospitality:Hotels and resorts prioritizing aesthetic concealment and guest experience continuity. Ceiling-mounted acoustic sensors over frame-mounted contacts preserve interior design integrity in Japanese and French premium property renovations.
Residential applications dominate unit volume, with hospitality representing the steepest expansion trajectory among end-user categories.
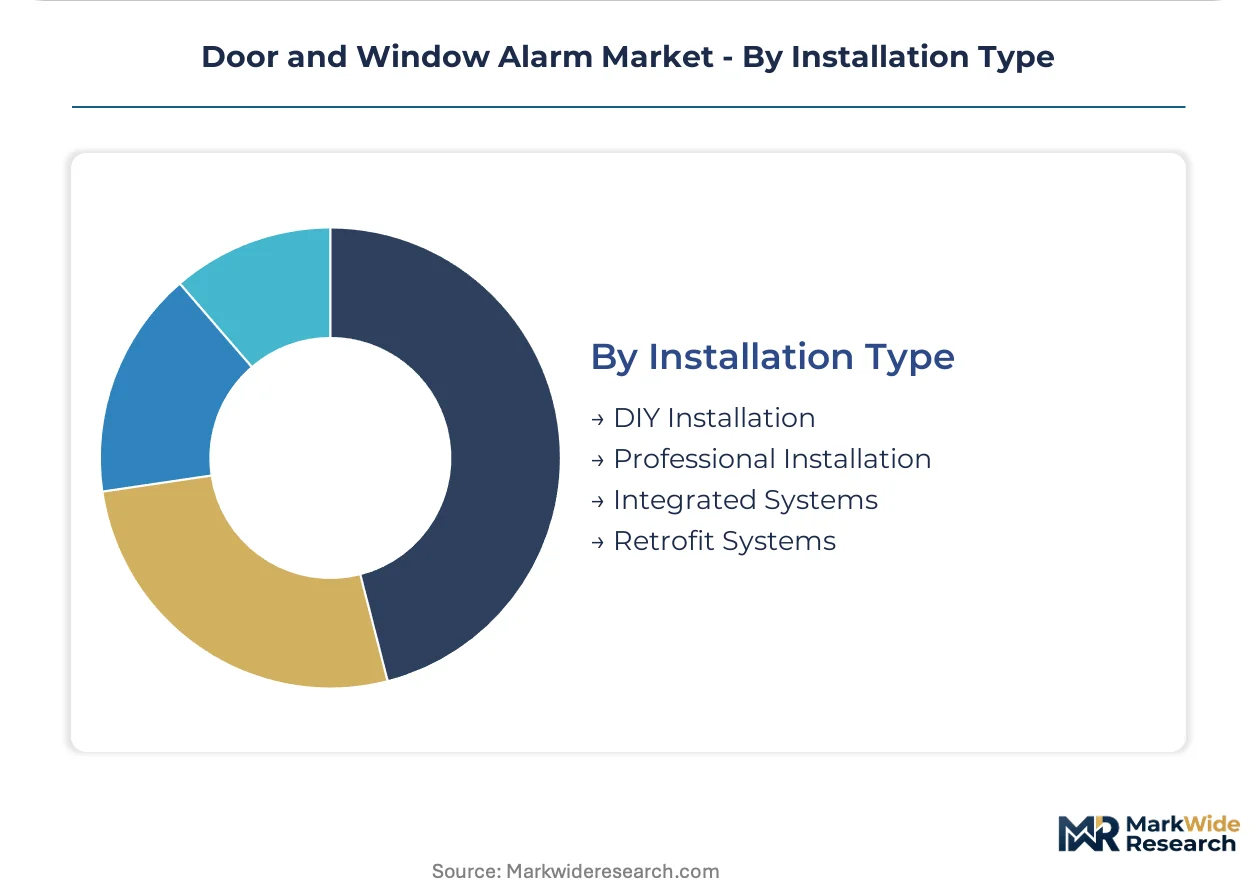
Installation Type:
Customer type fragmentation separates specification authority between security dealers, big-box retailers, and online marketplaces, with channel control determining margin capture and brand positioning.
- DIY Installation:Self-configured wireless systems sold through Amazon, Home Depot, and direct-to-consumer portals. Ring dominates this channel in the United States, capturing specification authority previously held by professional security dealers through aggressive online distribution investment.
- Professional Installation:Dealer-deployed systems with monitoring contracts and ongoing service relationships. Germany's insurance-linked premium reduction structure reinforces professional channel strength, as certified installation documentation qualifies homeowners for rate discounts unavailable with DIY alternatives.
- Integrated Systems:Whole-home automation platforms incorporating door and window alarms alongside lighting, climate, and access control. EU smart home interoperability mandates are forcing firmware rebuilds around open protocols, altering how alarms connect to broader security ecosystems.
- Retrofit Systems:Wireless bridge hardware enabling connected monitoring of 1990s-era hardwired zones. These solutions require specialized technician deployment for legacy panel integration, creating skilled labor bottlenecks in United States residential replacement cycles.
DIY installation leads in new account formation, with integrated systems climbing fastest as smart home platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Tokyo, and Boston anchor the geographic concentration of door and window alarm innovation, with regulatory compliance expertise clustering near capital cities where certification bodies maintain headquarters.
United States
DIY installation demand through Amazon and Home Depot channels is reshaping distribution economics, while broadband outage resilience has become mandatory in professionally monitored suburban contracts. FCC Part 15 authorization governs wireless transmitter frequencies, extending product launch timelines for novel protocols. Greater Boston hosts sensor firmware development clusters serving Northeast corridor security integrators.
Germany
Insurance premium reductions for certified alarm installations are accelerating replacement cycles among homeowners with legacy unmonitored systems. CE marking under the EU Radio Equipment Directive imposes electromagnetic compatibility testing that filters marginal competitors from retail shelf access. Stuttgart anchors Bosch Security Systems' in-house magnetic sensor manufacturing, supplying captive component flows to European OEM channels.
Japan
Aging homeowner demographics in urban condominiums are driving demand for remote monitoring capabilities bundled with professional service contracts. METI oversees technical standards for connected home devices, aligning with JIS certification requirements for electromagnetic resilience. Tokyo and Osaka hotel chains specify ceiling-mounted acoustic sensors over visible contacts to preserve interior design continuity in premium renovations.
India
Localized battery backup specifications under BIS certification are opening design partnerships with domestic electronics assemblers targeting price-sensitive residential retrofits. The Bureau of Indian Standards mandates specific decibel levels and power reserve duration for imported alarm devices. Maharashtra and Karnataka electronics manufacturing corridors are absorbing contract assembly volumes for wireless sensor modules.
France
Hospitality procurement in Paris and Lyon favors concealed detection arrays where aesthetic constraints prohibit visible hardware, compressing demand for traditional magnetic contacts in premium commercial segments. The EU AI Act imposes algorithmic transparency documentation on smart alarms employing behavioral analytics, with strictest compliance timelines in French, German, and Dutch markets. Île-de-France hosts compliance consulting clusters advising manufacturers on audit trail requirements.
Door and Window Alarm Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with scale advantages concentrating in regulatory compliance infrastructure and captive component supply. The vendor base separates into three strategic archetypes: diversified industrial conglomerates leveraging cross-divisional certification expertise, security-focused specialists optimizing sensor manufacturing economics, and direct-to-consumer platforms capturing specification authority through online channel control. Dominant competitive moves include backward integration into magnetic and acoustic sensor modules and firmware architecture rebuilds around open interoperability protocols mandated by EU smart home regulations.
Among diversified industrial conglomerates, Honeywell International and Bosch Security Systems occupy positions anchored by broad regulatory compliance infrastructure spanning multiple jurisdictions. ASSA ABLOY represents the access control integration archetype, while Ring exemplifies direct-to-consumer channel dominance in DIY installation markets. These three entities illustrate how scale, specialization, and platform economics fragment competitive positioning across distinct customer acquisition models.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Honeywell International |
| Allegion |
| Bosch Security Systems |
| Nabtesco Corporation |
| SimpliSafe |
| dormakaba |
| Ring |
| ADT |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot pricing volatility cascades through door and window alarm manufacturing, compressing margins on wireless sensor modules while pushing premium-tier suppliers toward fixed-price cell contracts with Korean and Japanese battery producers.
Pricing Analysis
The bundled-vs-unbundled service split separates professional monitoring contracts from standalone hardware sales, with subscription-anchored pricing commanding three-to-five-fold lifetime value over transactional unit sales. Price differentiation hinges on CE marking grade and insurance certification tier, with German VdS-certified systems capturing rate-linked premiums unavailable to uncertified alternatives. Cost compression in DIY channels is intensifying because Amazon and Home Depot procurement teams squeeze supplier margins through volume-scale purchasing commitments. Residential retrofit buyers exhibit highest price sensitivity, while Japanese hospitality procurement shows least sensitivity due to aesthetic concealment requirements.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion cell recovery and sensor module refurbishment are emerging as cost centers, with EU battery passport regulations mandating traceability documentation that extends liability upstream to original manufacturers. Component sourcing concentrates in China for MEMS microphones and piezoelectric elements, South Korea for battery cells, and Germany for precision magnetic reed switches. Raw material dependencies span neodymium for magnetic sensors, lithium carbonate for power cells, and rare-earth elements for acoustic transducer membranes. Single-source vulnerability in Chinese MEMS foundry capacity creates exposure to export license restrictions. Distribution runs through security dealer networks for professional installations, direct-to-consumer platforms for DIY systems, and OEM supply agreements for integrated smart home platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate between German certification premiums and Indian manufacturing cost bases, with BIS decibel mandates creating localized assembly partnerships that bypass import duty structures on finished goods.
For Market Incumbents: Acquire firmware architecture capabilities around Matter protocol stacks to defend against interoperability mandates fragmenting ecosystem control. Consolidate magnetic sensor manufacturing in Stuttgart to capture captive component flows for European OEM channels. Reinforce position against direct-to-consumer entrants by embedding cellular fallback modules as standard in professionally monitored contracts. For New Entrants and Emerging Players: Rural broadband gaps in the United States represent the most penetrable buyer archetype, with satellite-connected alarm systems addressing markets where terrestrial infrastructure remains unreliable. Target price-sensitive residential retrofits in Maharashtra and Karnataka through domestic electronics assembler partnerships. Pursue hospitality procurement in French premium hotel renovations where ceiling-mounted acoustic specifications displace visible magnetic contacts. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance infrastructure specialists possessing multi-jurisdiction certification expertise spanning FCC, CE marking, and BIS frameworks. Long-term viability favors entities with backward integration into sensor module production and firmware development clusters in Boston or Tokyo. Monitor EU AI Act algorithmic transparency enforcement timelines as inflection indicator for behavioral analytics premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Bosch Security Systems' captive magnetic sensor supply anchors European OEM channel access against price volatility. |
| Firmware Architecture Rebuild around Matter Protocol | EU smart home interoperability mandates force open-standard compliance for ecosystem connectivity certification. |
| Cellular Fallback Module Standardization | Broadband outage resilience specifications in US suburban contracts differentiate professionally monitored offerings. |
| Domestic Assembly Partnerships in India | BIS decibel and battery backup mandates favor localized production over finished goods import duty exposure. |
| Ceiling-Mounted Acoustic Sensor Development | Japanese and French hospitality procurement prioritizes aesthetic concealment over frame-mounted magnetic contacts. |
Research Methodology
Coverage spans Germany, the United States, Japan, India, and France, with primary inputs from each market's regulatory and commercial clusters. Primary interviews engaged security systems integrators, smart home platform engineers, insurance underwriting specialists, and hospitality procurement directors. Secondary validation drew from FCC equipment authorization databases, EU Radio Equipment Directive technical documentation, BIS certification registries, METI technical standards publications, and customs trade flow records for sensor module imports. Bottom-up unit demand modeling triangulated against top-down market sizing from installed base replacement cycles and new construction penetration rates.
Rate-of-change decomposition separated volume growth from value expansion across product type, technology modality, end-user application, and installation channel dimensions. Segmentation modeling captured wireless versus wired connectivity splits, magnetic versus acoustic detection technologies, residential versus commercial versus hospitality end-use patterns, and DIY versus professional versus integrated installation approaches. CAGRs were derived from regression analysis of historical replacement cycle data and regulatory mandate implementation timelines. Forecast inputs incorporated insurance premium reduction policy spreads, smart home interoperability compliance deadlines, and lithium-ion cell supply contract pricing trajectories.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in real-time customs data for component-level trade flows introduce uncertainty bands around supply chain cost assumptions. Forecasts reflect documented assumptions regarding certification timeline adherence and battery chemistry substitution elasticities. Practitioners should monitor EU AI Act audit trail enforcement actions, FCC Part 15 authorization queue lengths, and BIS decibel mandate implementation delays for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Private Military Security Services Market
Security and Surveillance
Residential Security Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Latin America Security Services Market
Security and Surveillance
Global Security Assurance Market
Security and Surveillance
Multi-Layer Security Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market