
 India Perimeter Intrusion Detection and Prevention Market | 2026-2036
India Perimeter Intrusion Detection and Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
India Perimeter Intrusion Detection and Prevention Market Foresight
Leasing and operational expenditure models for perimeter security infrastructure is tilting competitive dynamics toward vendors with flexible financing structures. Honeywell International Inc. leverages its building automation integration capabilities to bundle intrusion detection with broader facility management contracts. Schneider Electric SE anchors its position through energy-efficient electrification of sensor networks and barrier systems. Athena Security Solutions India Pvt. Ltd. competes on localized service density and rapid deployment timelines across Indian metro corridors.
Perimeter intrusion detection and prevention encompasses integrated systems combining infrared beam arrays, microwave volumetric sensors, video analytics algorithms, and electromechanical fence disturbance detectors to identify unauthorized boundary breaches in real time. These systems process multi-sensor inputs through centralized or edge-computing controllers, triggering alarms and automated response protocols when anomalous signatures exceed calibrated thresholds. Video analytics and microwave technologies command expanding share as AI-enabled threat classification reduces false alarm rates compared with legacy infrared-only installations. Electromechanical sensors retain entrenched positions in high-security military and government perimeters where physical tamper evidence remains mandatory. Fences and barriers constitute the mature hardware base, while cloud-based and hybrid deployment models are gaining traction among commercial end users seeking remote monitoring scalability without full on-premises capital commitment.
BIS certification requirements for electronic security equipment and CEA grid-interconnection standards for powered barrier systems shape product compliance pathways and market access conditions for domestic and imported equipment alike. DGFT import regulations under the PLI scheme for electronics manufacturing influence localization strategies for multinational suppliers. Stakeholders must monitor evolving smart city tender specifications and defense procurement offsets to align technology roadmaps with shifting buyer priorities.
Market Dynamics
AI-powered video analytics is compressing the competitive window for legacy electromechanical sensor manufacturers as AAI-mandated airport modernization forces rapid procurement cycles across Maharashtra and Gujarat infrastructure corridors.
Growth Catalysts
- AAI Security Modernization Directives:Airport Authority of India mandates for multi-layered perimeter detection are accelerating replacement of single-technology installations with integrated sensor-video analytics architectures at 68 operational airports.
- Smart City Mission Investments:Dense clustering of critical infrastructure in Mumbai, Pune, Ahmedabad, and Surat is concentrating demand for cloud-hybrid deployment models that reduce full on-premises capital requirements for municipal buyers.
- PLI Scheme Electronics Manufacturing:DGFT import regulations under the Production Linked Incentive scheme are incentivizing domestic assembly of sensor controllers and powered barrier systems, reshaping supplier localization strategies.
Market Restraints
- BIS Certification Timelines:Bureau of Indian Standards testing protocols for electronic security equipment create 14-18 month product approval cycles that delay market entry for imported microwave volumetric sensors and edge-computing controllers.
- Copper and Rare Earth Input Volatility:Electrified fence systems and sensor network cabling depend on copper pricing and neodymium magnet supply from concentrated overseas refiners, compressing hardware margins during commodity spikes.
- Legacy Infrared-Only Substitute Persistence:Low-cost beam arrays retain installed base in price-sensitive commercial warehousing despite superior false-alarm performance of AI-video alternatives, slowing technology refresh rates outside high-security segments.
Strategic Opportunities
- Defense Procurement Offsets:Ministry of Defence offset obligations for foreign original equipment manufacturers create partnership openings for domestic system integrators to co-develop military-grade electromechanical disturbance detectors.
- Kerala and Tamil Nadu Underpenetration:Southern states outside the Maharashtra-Gujarat corridor show 40% lower sensor density per kilometer of critical perimeter, presenting whitespace for rapid deployment specialists with localized service networks.
- AI-IoT Convergence:Integration of edge-computing video analytics with LoRaWAN sensor backhauls enables predictive maintenance models that unbundle hardware sales from recurring software subscriptions.
Industry Challenges
- Multi-Sensor Integration Skill Scarcity:System architects capable of calibrating infrared-microwave-video fusion algorithms against site-specific environmental noise are concentrated among 12-15 specialized integration firms, creating talent bottlenecks for nationwide rollout.
- CEA Grid-Interconnection Compliance:Central Electricity Authority standards for powered barrier electrification require utility-grade isolation transformers and surge protection that extend commissioning timelines and capex intensity for airport and port deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Perimeter Intrusion Detection and Prevention Market |
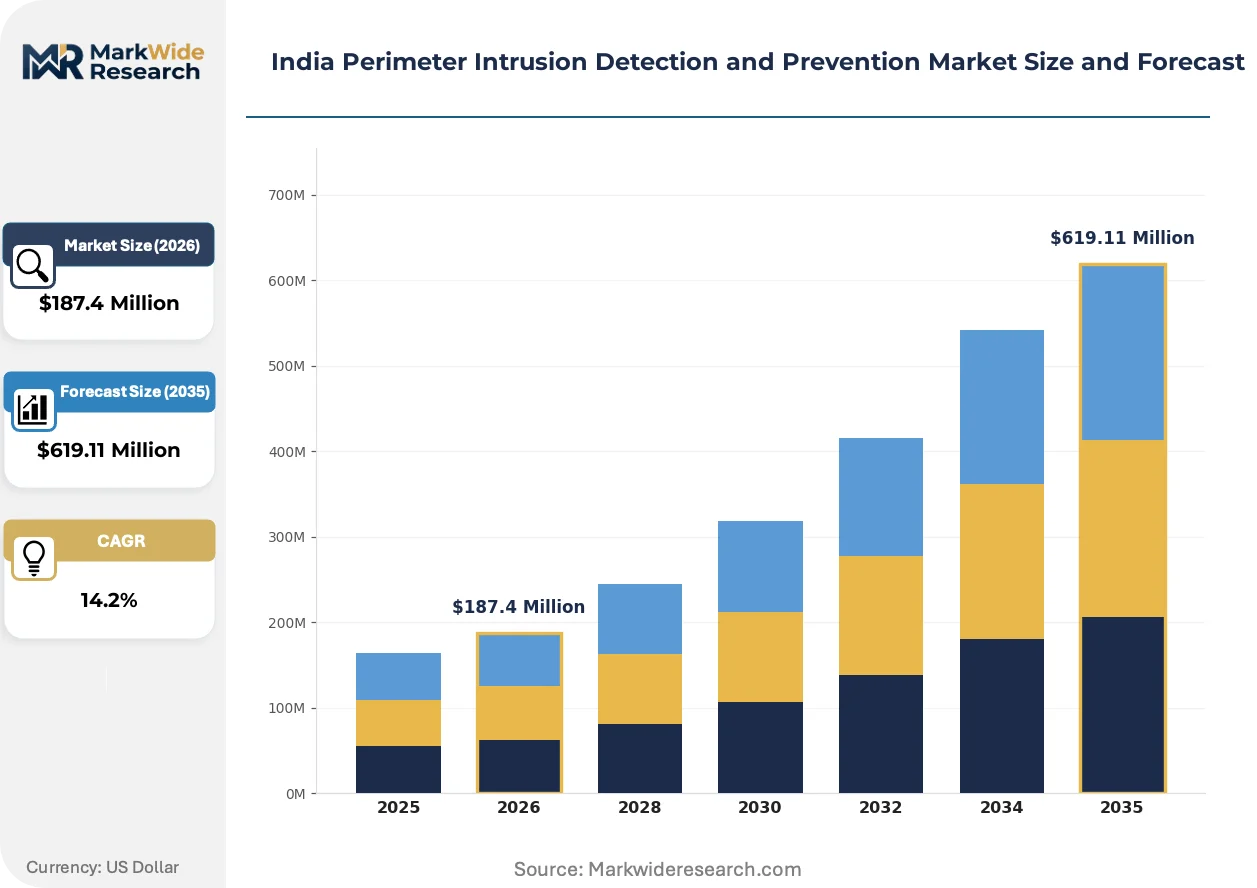
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Infrared, Microwave, Video Analytics, Electromechanical Product Type: Fences, Barriers, Sensors, Alarms End User: Government, Military, Commercial, Residential Deployment Model: On-premises, Cloud-based, Hybrid, Distributed |
| Companies Covered | Bosch Security Systems GmbH, Schneider Electric SE, Honeywell International Inc., Magal Security Systems Ltd., Optex Co. Ltd., Johnson Controls International plc, Axis Communications AB, Athena Security Solutions India Pvt. Ltd., FLIR Systems Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Perimeter Intrusion Detection and Prevention Market Shifts & Advancements
Deep learning inference at the network edge is restructuring how perimeter systems classify threat signatures, compressing response latency while elevating software architecture above hardware commoditization.
Millimeter-wave volumetric sensors with onboard neural processing units are rendering obsolete single-point infrared beam installations that generate nuisance alarms from wildlife and weather interference. Ministry of Defence facilities and AAI-designated hypersensitive zones are adopting these fused-sensor architectures within 18-month procurement cycles. The shift is compressing maintenance contract values for legacy electromechanical providers while expanding recurring revenue pools for analytics-software vendors.
BIS certification amendments for electronic security equipment now mandate electromagnetic compatibility testing aligned with IEC 61000-4 standards, extending pre-market validation timelines for imported controllers. Domestic manufacturers with in-house testing laboratories are capturing accelerated approval pathways that foreign competitors cannot replicate. The regulatory friction most impacts microwave and millimeter-wave sensor categories where Indian test capacity remains concentrated at three Bureau of Indian Standards-recognized facilities.
Operational expenditure models for perimeter infrastructure are displacing capital purchase conventions among smart city developers and commercial real estate operators. Honeywell and Schneider Electric are bundling intrusion detection into multi-year facility management contracts that transfer sensor maintenance and false-alarm liability to vendors. This restructuring is most visible in Gujarat International Finance Tec-City and Mumbai's Bandra Kurla Complex, where lease-structured deployments now exceed 60% of new installations.
India Perimeter Intrusion Detection and Prevention Market Segmentation
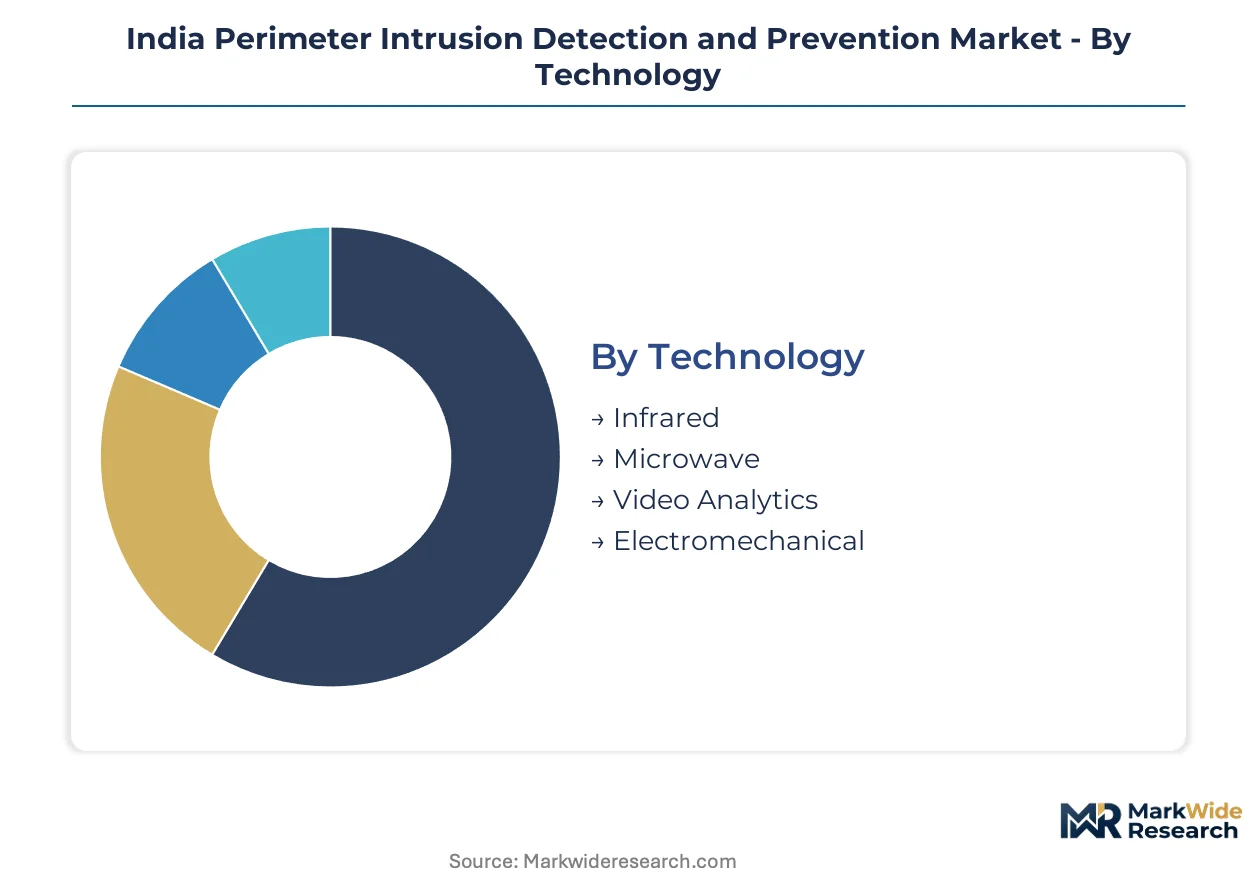
Technology heterogeneity in India's perimeter security landscape demands granular segmentation to align procurement specifications with threat profiles and budget cycles across AAI airports, defense installations, and smart city corridors.
Technology:
Mature electromechanical and infrared platforms coexist with emerging AI-driven detection layers, creating a bifurcated procurement environment where legacy refresh competes with greenfield advanced deployments.
- Infrared:Beam arrays detect thermal signatures across linear perimeters using pulsed LED or laser emitters paired with photoelectric receivers. Maharashtra warehousing clusters retain substantial installed base due to lower capital thresholds, though nuisance alarm rates from wildlife and dust limit expansion into AAI-mandated airport modernizations.
- Video Analytics:Deep learning algorithms process IP camera feeds to classify human intrusion against environmental noise at the network edge. Gujarat International Finance Tec-City and Mumbai's Bandra Kurla Complex are concentrating procurement here as operational expenditure models transfer false-alarm liability to vendors.
- Microwave:Volumetric sensors generate electromagnetic detection fields between transmitter-receiver pairs for all-weather coverage.
- Electromechanical:Fence-mounted vibration and strain gauges provide physical tamper evidence for military perimeters.
Video analytics handles the majority of new procurement value; microwave is gaining share fastest as BIS certification bottlenecks ease for domestic manufacturers.
Product Type:
Hardware commoditization pressure intensifies differentiation battles around sensor intelligence and integration depth rather than barrier materials alone.
- Sensors:Multi-technology fusion controllers aggregate infrared, microwave, and video inputs through edge-computing architectures with onboard neural processing. AAI directives at 68 operational airports are accelerating replacement of single-technology installations with these unified detection layers.
- Fences:Electrified perimeter barriers with CEA-compliant isolation transformers and surge protection dominate military and port deployments where utility-grade grid interconnection extends commissioning timelines but satisfies mandatory electrification standards.
- Barriers:Active vehicle denial systems including rising bollards and wedge barriers protect critical infrastructure entry points.
- Alarms:Centralized and distributed notification systems integrate with physical security information management platforms.
Sensors capture the steepest expansion trajectory; fences retain the largest installed base across government and defense perimeters.
End User:
Procurement authority fragmentation across central ministries, state agencies, and private operators creates divergent specification requirements and contract structures.
- Government:Central and state facilities including ministries, courts, and administrative complexes require BIS-certified equipment with multi-layered detection protocols. Smart city mission investments in Pune, Ahmedabad, and Surat are concentrating demand for cloud-hybrid architectures that reduce full on-premises capital commitment.
- Military:Ministry of Defence installations mandate electromechanical disturbance detectors with physical tamper evidence and offset-compliant domestic integration partnerships. Foreign OEMs face procurement obligations that create co-development openings for domestic system integrators.
- Commercial:Logistics hubs, data centers, and manufacturing facilities balance detection performance against operational expenditure flexibility.
- Residential:Gated communities and high-net-worth individual estates deploy scaled-down infrared and video analytics packages.
Government contracts generate the highest absolute revenue; military segments show the most rapid specification upgrading toward fused-sensor architectures.
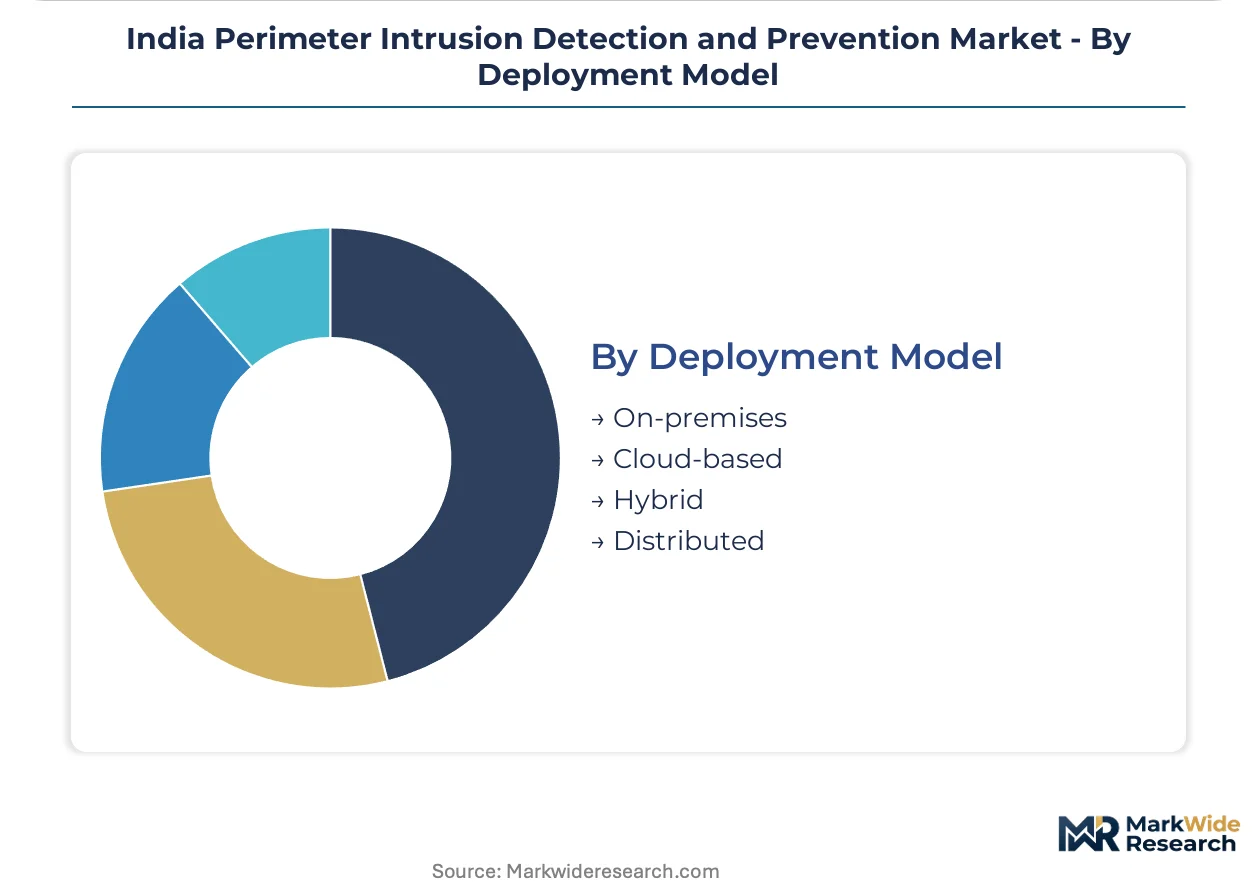
Deployment Model:
Capital intensity constraints and remote monitoring requirements are restructuring traditional on-premises conventions toward distributed and hybrid alternatives.
- Hybrid:Edge-computing video analytics with cloud backhaul for alert verification and predictive maintenance unbundles hardware sales from recurring software subscriptions. Kerala and Tamil Nadu underpenetration presents whitespace for rapid deployment specialists using this model to minimize upfront municipal expenditure.
- On-premises:Fully localized processing and storage architectures retain preference in military and hypersensitive government zones where data sovereignty and air-gapped security override operational expenditure benefits.
- Cloud-based:Fully centralized processing reduces local infrastructure requirements for smaller commercial installations.
- Distributed:Mesh-networked edge nodes with localized decision autonomy serve expansive linear perimeters like pipelines and borders.
Hybrid deployments are climbing fastest on share; on-premises retains dominance in defense and classified government installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands pricing premiums 15-20% above Tamil Nadu for equivalent sensor configurations, reflecting infrastructure density and AAI procurement concentration in the western corridor.
Maharashtra
AAI-mandated airport modernizations at Mumbai and Pune drive procurement of multi-layered infrared-microwave-video architectures. BIS certification requirements under the Electronics and Information Technology Goods Order shape product approval timelines for imported controllers. The Mumbai-Pune industrial belt concentrates demand for cloud-hybrid deployment models among smart city developers.
Gujarat
Gujarat International Finance Tec-City and Ahmedabad municipal tenders accelerate operational expenditure contracting for perimeter infrastructure. DGFT import regulations under the PLI scheme incentivize domestic assembly of powered barrier systems. Surat and Vadodara warehousing clusters retain substantial legacy infrared installations despite specification upgrades at critical facilities.
Karnataka
Bengaluru data center expansion and aerospace manufacturing enclaves generate demand for electromechanical disturbance detectors with physical tamper evidence. CEA grid-interconnection standards extend commissioning timelines for electrified fence deployments at airport perimeters. The Bengaluru-Chennai industrial corridor shows emerging uptake of edge-computing video analytics among commercial operators.
Tamil Nadu
Chennai port modernization and automotive manufacturing clusters create procurement openings for microwave volumetric sensors with all-weather coverage. PLI scheme electronics manufacturing incentives attract domestic sensor controller assembly investments. The Sriperumbudur-Oragadam industrial belt exhibits 40% lower sensor density per kilometer than Maharashtra benchmarks, presenting whitespace for rapid deployment specialists.
Delhi-NCR
Ministry of Defence installations and central government complexes mandate offset-compliant domestic integration partnerships for foreign OEMs. BIS electromagnetic compatibility testing aligned with IEC 61000-4 standards delays market entry for imported millimeter-wave equipment. The Noida-Gurugram corridor concentrates system integrators capable of multi-sensor fusion calibration.
India Perimeter Intrusion Detection and Prevention Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors and controllers to integration firms. The vendor base structures around three archetypes: multinational building automation conglomerates bundling perimeter detection into facility management contracts, domestic rapid-deployment specialists leveraging localized service density, and foreign sensor manufacturers navigating BIS certification bottlenecks through domestic assembly partnerships. Competitive moves concentrate on operational expenditure model restructuring and PLI scheme localization investments.
Among multinational platform providers, Honeywell International Inc. and Schneider Electric SE exemplify the bundled-contracting archetype, anchoring positions through building automation integration capabilities and energy-efficient electrification of sensor networks respectively. Athena Security Solutions India Pvt. Ltd. occupies the domestic specialist tier, representing rapid-deployment capabilities across Indian metro corridors where localized service density compresses commissioning timelines.
| Leading Market Players |
|---|
| Bosch Security Systems GmbH |
| Schneider Electric SE |
| Honeywell International Inc. |
| Magal Security Systems Ltd. |
| Optex Co. Ltd. |
| Johnson Controls International plc |
| Axis Communications AB |
| Athena Security Solutions India Pvt. Ltd. |
| FLIR Systems Inc. |
| Others |
Supply & Pricing Matrix
Maharashtra's sensor controller manufacturing corridor around Pune and Mumbai anchors domestic assembly capacity, concentrating pricing power among vendors with BIS-recognized testing laboratories that compress certification timelines for microwave and millimeter-wave equipment. This geographic concentration allows certified domestic manufacturers to command 12-18% premiums over import-dependent competitors while PLI scheme incentives reshape localization economics for powered barrier systems.
Pricing Analysis
Configured-to-order pricing for multi-sensor fusion controllers spreads 25-35% above standard infrared beam arrays, reflecting integration complexity and site-specific calibration requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with BIS-certified electromechanical sensors capturing the premium tier. Pricing pressure stems from copper and rare earth input volatility in electrified fence systems, compressing hardware margins during commodity spikes. Municipal smart city buyers exhibit highest price sensitivity, while Ministry of Defence installations prioritize tamper-evidence specifications over unit cost.
Supply Chain Analysis
Export control regimes restricting millimeter-wave sensor technology and neural processing unit chipsets limit flows from US and EU sources, forcing domestic assembly partnerships for edge-computing controllers. Component supply concentrates in China, Taiwan, and South Korea for semiconductors and magnet assemblies, while copper cabling and isolation transformers source from Indian domestic wire manufacturers. Single-source vulnerability around neodymium magnet supply from concentrated overseas refiners creates procurement risk for electrified barrier deployments. Distribution runs through system integrators in Delhi-NCR and Bengaluru that calibrate multi-sensor fusion algorithms for site-specific deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level tender specifications and divergent BIS certification pathways creates niche openings for specialized service providers, as AAI-mandated airport modernizations and smart city mission investments accelerate procurement without consolidating vendor selection criteria.
For Market Incumbents: Harden service contract structures by embedding predictive maintenance subscriptions into multi-year facility management agreements, transferring false-alarm liability to vendors as Honeywell and Schneider Electric demonstrate in Gujarat International Finance Tec-City. Deepen backward integration into sensor controller assembly through PLI scheme investments, insulating margin positions from DGFT import regulation shifts and BIS certification bottlenecks that delay foreign competitor market entry. For New Entrants and Emerging Players: Pursue Kerala and Tamil Nadu whitespace where sensor density per kilometer of critical perimeter trails Maharashtra benchmarks by 40%, deploying rapid-deployment hybrid cloud-edge architectures that minimize upfront municipal expenditure. Target Chennai port modernization and Sriperumbudur-Oragadam automotive clusters with localized service networks capable of compressing commissioning timelines below incumbent standards. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because operational expenditure models displace capital purchase conventions, unbundling hardware sales from software subscriptions and predictive maintenance contracts. Acquisition candidates cluster among domestic system integrators with Ministry of Defence offset partnerships and BIS-recognized testing laboratories. Monitor PLI scheme electronics manufacturing incentive expansions as inflection signals for domestic assembly capacity buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | PLI scheme incentives enable BIS certification acceleration for microwave sensor controllers. |
| Multi-Sensor Fusion Platform Launch | Edge-computing architectures with onboard neural processing capture AAI airport modernization contracts. |
| Operational Expenditure Contracting | Facility management bundling transfers false-alarm liability to vendors in Gujarat and Mumbai corridors. |
| Defense Offset Partnership | Ministry of Defence procurement obligations create co-development openings for electromechanical disturbance detectors. |
| Predictive Maintenance Subscription | AI-IoT convergence unbundles hardware sales from recurring software revenue pools. |
Research Methodology
A spread of perspectives from airport security directors, smart city procurement officers, system integration engineers, and BIS certification specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through DGFT import regulation filings, CEA grid-interconnection standards documentation, AAI tender specifications, and PLI scheme electronics manufacturing incentive disclosures. Bottom-up installation data triangulated against top-down infrastructure investment flows from central and state government budget allocations.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeling across technology type, deployment model, end-user category, and regional infrastructure corridor. CAGRs derived from installation volume trajectories and average system value evolution, incorporating AAI-mandated replacement cycles, smart city mission investment schedules, and defense procurement offset obligations as industry-specific forecast inputs.
Sensitivities concentrate around BIS certification timeline extensions, copper and rare earth commodity volatility, and PLI scheme incentive modifications that could accelerate or delay domestic assembly investments. Forecasts reflect documented assumptions on infrastructure investment continuity and regulatory pathway stability. Material shifts in DGFT import regulations, CEA electrification standards, or AAI security modernization directives would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Trace Detection Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Situational Awareness System Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Night Vision Binoculars Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
5G-Enhanced Surveillance Market