
 Panic Exit Devices Market | 2026-2036
Panic Exit Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Panic Exit Devices Market Analytics
Healthcare facility construction is recalibrating panic exit device specifications toward antimicrobial finishes and touchless actuation. ASSA ABLOY Group leverages its breadth across mechanical and electromechanical platforms to serve this shift. Allegion plc anchors North American distribution through specification relationships with major architectural firms. Dormakaba Group competes in European markets with modular systems that integrate access control and egress.
Panic exit devices are mechanical or electromechanical door hardware engineered to permit rapid, single-motion egress under emergency conditions, typically rated for cycles exceeding one million operations and tested to ANSI/BHMA A156.3 or EN 1125 standards. Their primary purpose is to balance free egress with controlled access in commercial, institutional, and high-occupancy buildings. Multiple point devices lead in high-security applications where perimeter doors require simultaneous latch retraction, while panic bar configurations dominate retrofit activity in older commercial buildings. Surface mounted installation types retain the largest volume share due to lower labor cost and minimal door preparation, though concealed systems command premium positioning in architecturally sensitive projects.
NFPA 101 Life Safety Code and the International Building Code shape product certification requirements in the United States, mandating listed hardware for assembly and educational occupancies. EMA building product directives and CE marking under the Construction Products Regulation govern market access across European member states. Stakeholders must monitor evolving electrified egress standards and cybersecurity provisions for networked exit devices as smart building integration deepens.
Market Dynamics
Electrification of building access systems is forcing hardware manufacturers to merge mechanical egress reliability with networked credential management and real-time occupancy sensing.
Growth Catalysts
- NFPA 101 Life Safety Code updates:Assembly occupancy egress mandates in the United States are accelerating replacement cycles in aging commercial stock.
- Touchless actuation technology:Healthcare facilities specify sensor-activated panic hardware to reduce pathogen transmission vectors.
- Retrofit volume concentration:Commercial building stock in the United States built before 2000 drives hardware upgrade demand.
Market Restraints
- Stainless steel input volatility:Raw material price swings compress margin buffers for surface-mounted device producers.
- Electrified component supply concentration:Solenoid and sensor module sourcing clusters in East Asian contract manufacturers create single-point vulnerability.
- Cybersecurity compliance friction:Networked exit devices face patching and certification burdens under evolving building automation security standards.
Strategic Opportunities
- India healthcare infrastructure buildout:Hospital construction under Ayushman Bharat creates specification openings for antimicrobial-finished hardware.
- Smart building convergence:Integration of panic devices with BACnet and IoT occupancy platforms opens recurring software revenue streams.
- Germany building energy retrofit mandates:The EU Green Deal renovation wave ties door hardware replacement to comprehensive facade upgrades.
Industry Challenges
- Electromechanical systems integration talent:Shortage of technicians credentialed in both mechanical door hardware and low-voltage networking slows deployment.
- Multi-jurisdiction certification timelines:UL 305 and EN 1125 parallel testing extends product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panic Exit Devices Market |
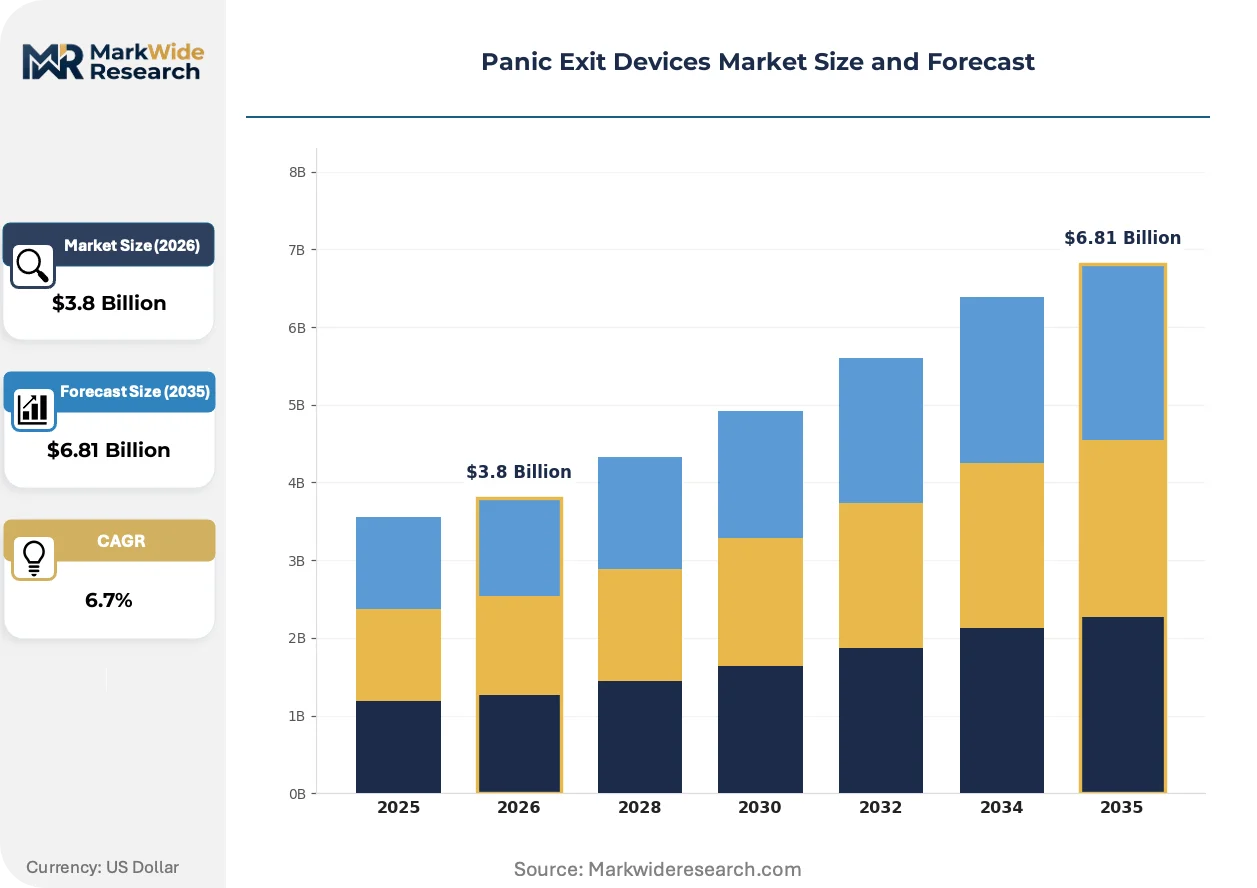
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Point, Multiple Point, Panic Bar, Exit Alarm Installation Type: Surface Mounted, Concealed, Vertical Rod, Horizontal Rod End User: Commercial Buildings, Educational Institutions, Hospitals, Government Facilities Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | ASSA ABLOY Group, Allegion plc, Dormakaba Group, Ingersoll Rand, Detex Corporation, GEZE GmbH, ISEO Serrature Spa., Von Duprin Inc., Fapim S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panic Exit Devices Market Evolving Landscape
Connected building infrastructure is rewriting how specifiers evaluate exit hardware, shifting selection criteria from mechanical durability alone to data interoperability and remote management capability.
Touchless infrared and capacitive sensing modules are rewriting the interface between occupants and egress hardware. Hospital and laboratory construction teams specify these systems to eliminate common touchpoints. The technology is compressing the traditional specification window by integrating antimicrobial surface treatments with sensor activation in single SKU offerings.
The EU Cyber Resilience Act and accompanying CE marking updates under the Construction Products Regulation are mandating vulnerability disclosure and secure update mechanisms for networked building products. Hardware manufacturers must embed over-the-air patching capability and document supply chain software bills of materials. Electrified panic devices with IP connectivity face the steepest compliance burden, with German and French certification bodies expanding testing protocols.
Specification authority is migrating from general contractors to specialized security integrators and building automation consultants. These intermediaries bundle door hardware selection within comprehensive access control packages, marginalizing traditional distributor relationships. The shift is most pronounced in United States commercial office and mixed-use developments where LEED and WELL certification requirements drive holistic building system procurement.
Panic Exit Devices Market Segmentation
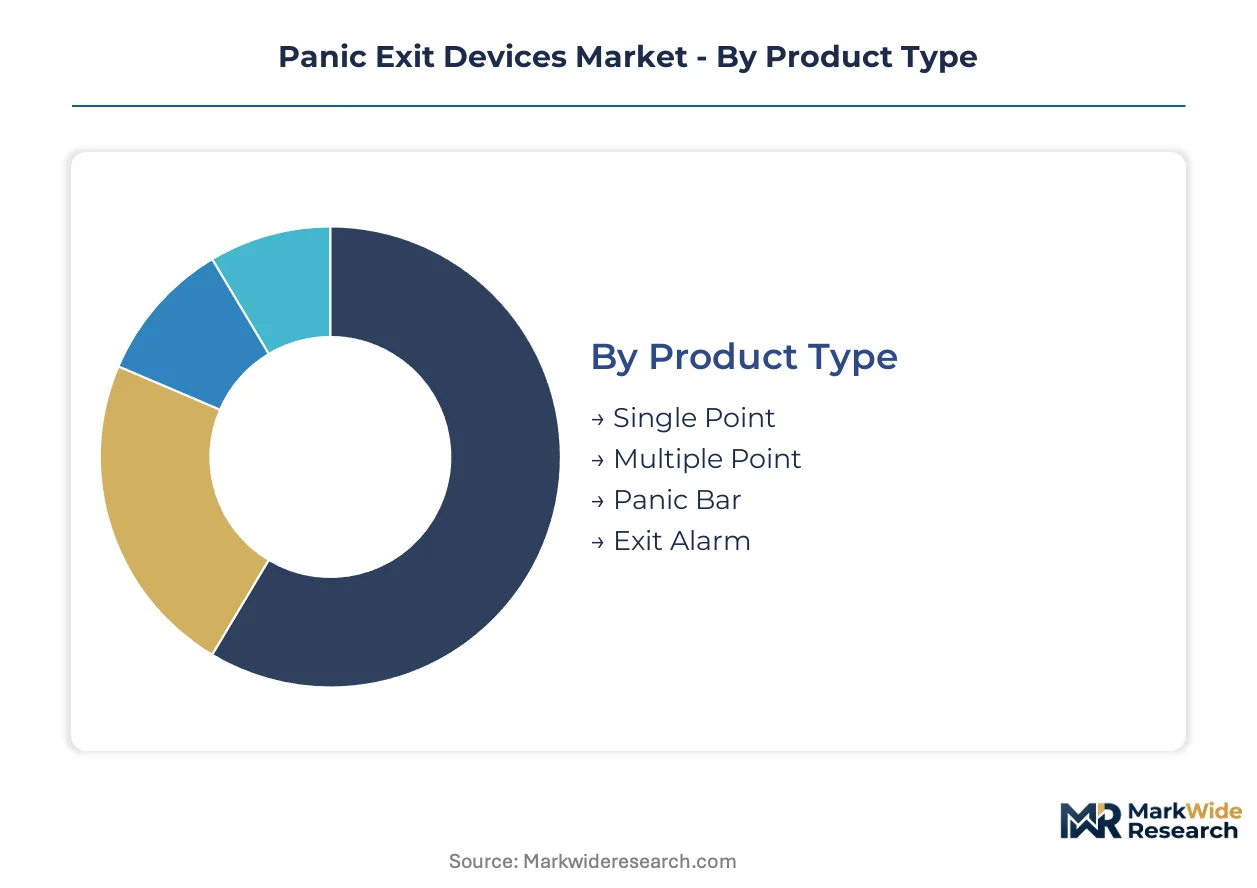
Panic exit device segmentation reflects the tension between standalone mechanical reliability and embedded electromechanical intelligence. Specification patterns diver sharply between retrofit projects prioritizing installation simplicity and new construction demanding integrated access control.
Product Type:
Integration depth varies dramatically across product architectures, with some segments functioning as isolated safety hardware and others serving as nodes in networked building systems.
- Single Point:Basic latch-retraction mechanisms mount at one door edge, suited for low-traffic secondary exits. Demand concentrates in United States retail strip renovations where cost minimization overrides access control integration.
- Multiple Point:Simultaneous top and bottom latch retraction secures tall or wide perimeter doors against forced entry. High-security government facilities in Germany specify these for embassy and consulate applications, driven by anti-ram and blast-resistance mandates.
- Panic Bar:Horizontal push-bar mechanisms dominate retrofit activity in aging United States commercial stock built before modern egress codes. Installation velocity and minimal door preparation sustain volume leadership.
- Exit Alarm:Integrated sounders and signaling circuits connect to central monitoring stations. Healthcare construction in India specifies these for psychiatric and pediatric wards where elopement prevention intersects with life safety.
Panic Bar leads volumes today; Multiple Point is gaining share fastest.
Installation Type:
Cost tier stratification separates premium architectural specifications from budget-driven replacement cycles, with labor intensity and aesthetic sensitivity driving the wedge.
- Surface Mounted:Rim-style devices bolt directly to door faces without mortising, minimizing field labor. United States facility managers favor these for rapid turnaround in multi-tenant office buildings where downtime costs exceed hardware premiums.
- Concealed:Mortised into door edges and frames, these preserve clean sightlines for high-design projects. Museum and performing arts construction in France specifies concealed systems to satisfy heritage board and architect aesthetic requirements.
- Vertical Rod:Top and bottom rods secure double doors or oversized single panels. Warehouse and distribution center construction in Mexico deploys these for loading dock egress compliance.
- Horizontal Rod:Cross-bar mechanisms span door pairs without center posts. Convention center and arena renovations in Japan specify these for wide corridor egress capacity.
Surface Mounted leads volumes today; Concealed is climbing the fastest.
End User:
Application-specific code requirements and duty-cycle demands reshape product selection, with occupancy type dictating antimicrobial, touchless, and security feature bundles.
- Commercial Buildings:Office, retail, and hospitality properties drive replacement volume through code-mandated upgrades. United States properties built before NFPA 101 adoption dominate retrofit scheduling.
- Educational Institutions:K-12 and university facilities face stringent assembly occupancy egress rules. Campus security departments in Canada specify electrified panic hardware with lockdown capability.
- Hospitals:Infection control protocols demand touchless actuation and antimicrobial finishes. Ayushman Bharat hospital construction in India creates specification pull for copper-alloy and silver-ion treated surfaces.
- Government Facilities:Federal, state, and municipal buildings integrate access control with life safety. United States GSA procurement standards mandate Buy America compliance and FICAM credential interoperability.
Commercial Buildings leads volumes today; Hospitals is expanding most quickly.
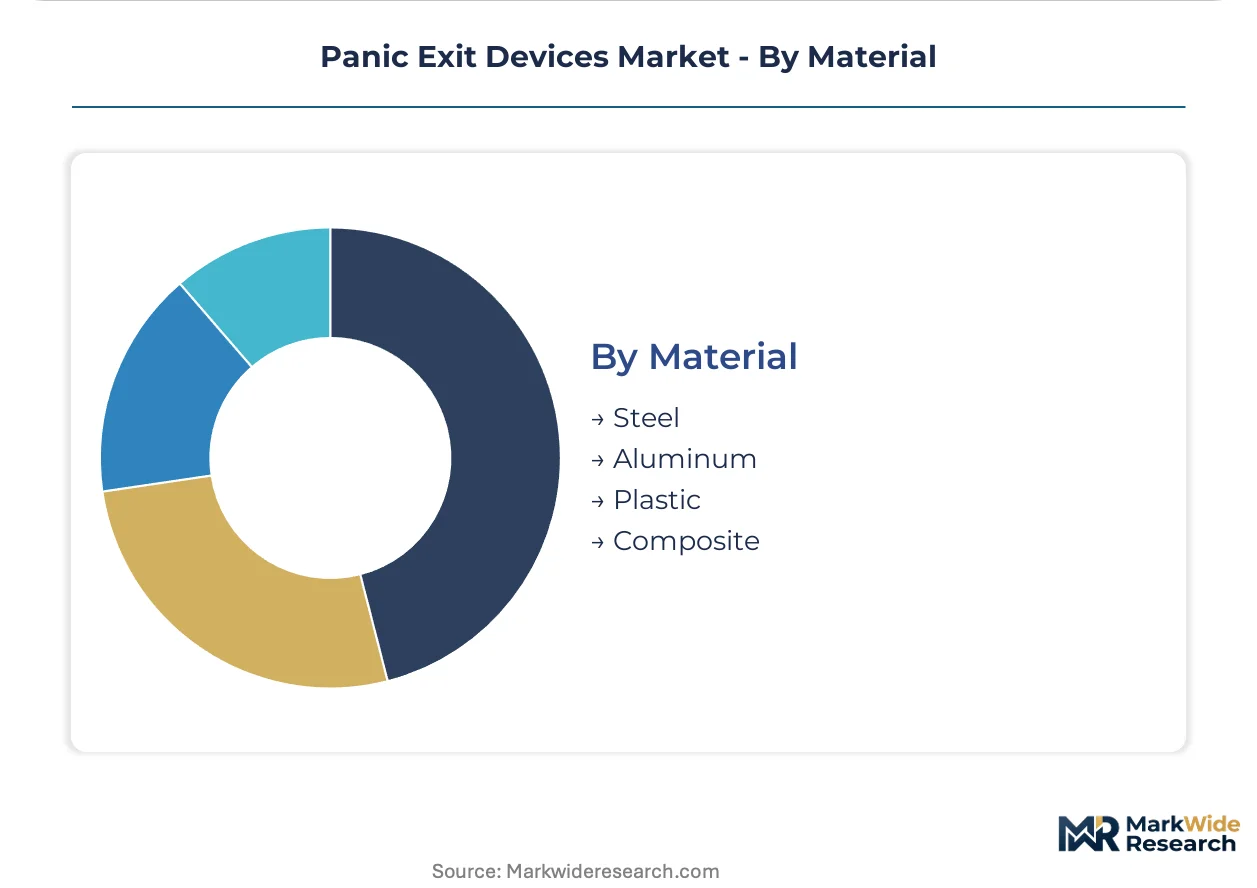
Material:
Supply concentration and raw material volatility differentiate margin profiles, with stainless steel dependency creating vulnerability for surface-mounted producers.
- Steel:Stainless and carbon steel alloys deliver durability for high-cycle applications. United States manufacturing plants and transportation terminals specify grade 316 stainless for corrosion resistance.
- Aluminum:Lightweight extrusions suit narrow stile glass doors and aesthetic-sensitive projects. Retail flagship construction in the United Arab Emirates favors anodized aluminum for climate-appropriate corrosion performance.
- Plastic:Glass-filled nylon and polycarbonate components reduce cost in low-security, low-cycle settings. Temporary event structures and modular classrooms in Australia deploy these for rapid deployment.
- Composite:Hybrid metal-polymer constructions balance strength with electromagnetic transparency for RFID and NFC credential transmission. Smart office developments in Singapore specify composites for seamless mobile access integration.
Steel leads volumes today; Composite is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs by shifting electromechanical assembly to jurisdictions with streamlined CE marking pathways while retaining mechanical fabrication in established industrial clusters. This migration pattern concentrates high-value component production in Germany and the United States while expanding final assembly footprints in Mexico and Poland.
United States
Retrofit demand from pre-2000 commercial stock drives hardware replacement cycles across aging office and retail properties. NFPA 101 Life Safety Code updates mandate listed panic hardware for assembly occupancies, tightening specification requirements. Chicago and Los Angeles facility managers prioritize rapid-install surface-mounted devices to minimize tenant downtime.
Germany
Embassy and consulate construction specifies multiple-point panic devices with anti-ram and blast-resistance ratings. The EU Cyber Resilience Act imposes vulnerability disclosure requirements on networked exit hardware. Munich and Frankfurt security integrators bundle door hardware within comprehensive access control packages for federal buildings.
India
Ayushman Bharat hospital construction creates specification pull for antimicrobial-finished panic hardware in psychiatric and pediatric wards. BIS certification requirements govern mechanical door hardware market access. Hyderabad and Chennai construction teams specify touchless actuation systems to meet infection control protocols.
Mexico
Distribution center and warehouse construction deploys vertical rod panic devices for loading dock egress compliance. Proximity to United States markets reduces logistics costs for North American retrofit supply. Nuevo León and Mexico City industrial developers specify grade 316 stainless steel for corrosion resistance in coastal and high-humidity environments.
Japan
Convention center and arena renovations specify horizontal rod mechanisms for wide corridor egress capacity. METI building standards govern fire safety hardware certification timelines. Osaka and Yokohama facility managers prioritize one-million-cycle durability ratings for high-traffic transit hub applications.
Panic Exit Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as mechanical hardware specialists acquire electromechanical capabilities and access control firms backward-integrate into egress hardware. The vendor base stratifies across three tiers: multinational conglomerates with full electromechanical portfolios, regional mechanical specialists with limited electrification, and emerging smart-building entrants with software-first architectures. Two competitive moves define current positioning: M&A activity consolidating distribution networks in North America, and strategic partnerships between hardware OEMs and building automation platforms for BACnet integration.
Within the multinational tier, ASSA ABLOY Group, Allegion plc, and Dormakaba Group exemplify divergent geographic anchoring strategies. ASSA ABLOY leverages Swedish industrial conglomerate scale across mechanical and electromechanical platforms. Allegion plc occupies a position as a Dublin-registered specialist with North American distribution depth. Dormakaba Group represents Swiss-German engineering heritage in modular system integration. These three entities collectively illustrate how regulatory compliance breadth and specification relationships with architectural firms determine competitive positioning in institutional construction markets.
| Leading Market Players |
|---|
| ASSA ABLOY Group |
| Allegion plc |
| Dormakaba Group |
| Ingersoll Rand |
| Detex Corporation |
| GEZE GmbH |
| ISEO Serrature Spa. |
| Von Duprin Inc. |
| Fapim S.p.A. |
| Others |
Value Network & Pricing Analysis
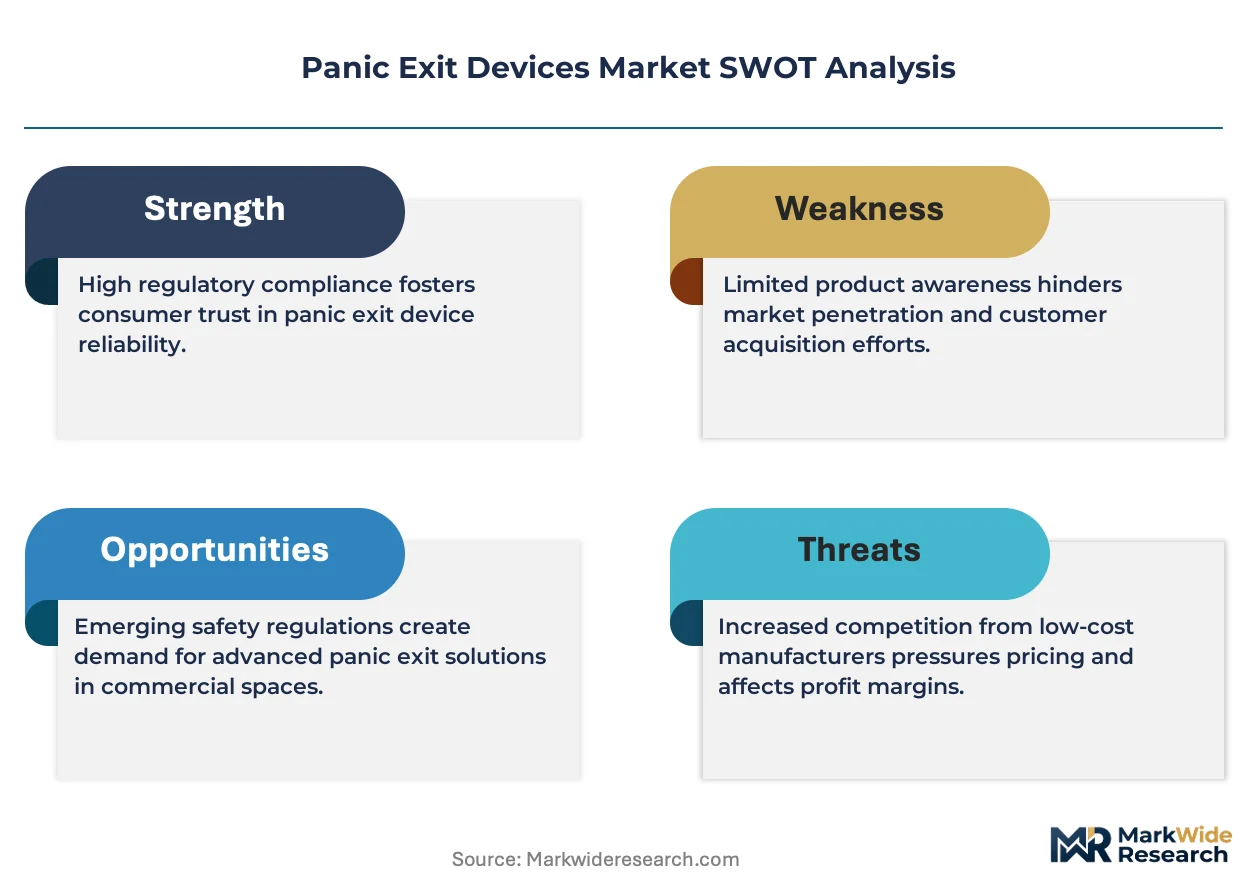
Backward integration into stainless steel machining and electromechanical component assembly anchors pricing power for multinational panic exit device manufacturers. Captive production of grade 316 stainless housings and in-house solenoid winding insulates margin buffers from raw material volatility and East Asian contract manufacturer concentration.
Pricing Analysis
Distributor margin compression runs through the United States commercial retrofit channel as facility managers prioritize rapid-install surface-mounted devices. Three-tier pricing structure across premium concealed systems, standard panic bar configurations, and economy-grade exit alarms separates specification-driven healthcare projects from budget-constrained retail renovations. Pricing pressure stems from stainless steel input volatility and solenoid module sourcing bottlenecks. Educational institutions exhibit highest price sensitivity due to procurement centralization; government facilities show lowest sensitivity given GSA-mandated Buy America compliance premiums.
Supply Chain Analysis
Stainless steel feedstock draws from United States, German, and Japanese specialty metal producers with grade 316 concentration in North American and European mills. Solenoid actuators, sensor modules, and IP-enabled credential readers rest on East Asian contract manufacturing clusters in Taiwan and mainland China. Single-source vulnerability concentrates in electromechanical component sourcing for networked exit devices. Distribution runs through security integrators and building automation consultants who bundle hardware within comprehensive access control packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panic exit devices represent a late-cycle quality story as healthcare construction specifications shift decisively toward antimicrobial finishes and touchless actuation systems. This demand migration favors manufacturers with electromechanical integration depth over pure mechanical players.
For Market Incumbents: To counter margin erosion from stainless steel volatility, secure captive supply through backward integration into grade 316 machining capacity in United States and German industrial clusters. Reinforce specification authority by embedding BACnet interoperability and over-the-air patching capability ahead of EU Cyber Resilience Act enforcement. For New Entrants and Emerging Players: Security integrators serve as the critical channel partner for penetrating United States commercial office retrofits where specification authority has migrated from general contractors. Target India healthcare infrastructure under Ayushman Bharat for antimicrobial-finished hardware with touchless actuation. Lead with software-first architectures that bundle panic devices within IoT occupancy platforms. For Investors and Strategic Acquirers: Roll-up economics work for regional mechanical specialists with limited electrification because specification authority consolidation among security integrators creates urgency for access control capability acquisition. Five-to-ten year viability hinges on electromechanical integration depth rather than mechanical durability alone. Watch electrified egress standard updates and cybersecurity certification timelines as inflection indicators for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Platform Integration | Merges mechanical egress reliability with BACnet and IoT occupancy sensing for smart building convergence. |
| Antimicrobial Surface Treatment Certification | Captures healthcare specification pull under NFPA 101 and infection control protocol mandates. |
| East Asian Component Supply Diversification | Reduces single-point vulnerability in solenoid and sensor module sourcing for networked devices. |
| Security Integrator Channel Partnership | Secures specification authority migration from traditional distributors in United States commercial developments. |
| EU Cyber Resilience Act Compliance Investment | Enables CE marking continuity for IP-connected exit devices under vulnerability disclosure mandates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hardware specification managers, security integrators, hospital procurement officers, and building automation consultants with secondary validation through ANSI/BHMA certification databases, NFPA 101 code revision records, and construction permit filings. Customs data on stainless steel alloy imports and electromechanical component trade flows supplemented demand-side triangulation. Bottom-up facility-level retrofit scheduling and top-down construction spending aggregates were cross-referenced for volume reconciliation.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand and post-code-update replacement cycles across assembly occupancies. Segmentation modeling spanned product architecture, installation type, end-use vertical, and material composition with regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to disclosed manufacturer capacity expansions and healthcare construction pipeline tracking. Electrification penetration rates and antimicrobial finish adoption curves served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel price volatility, East Asian supply chain disruption, and cybersecurity standard evolution. Projections reflect documented assumptions on code adoption timelines and hospital construction completion rates. A small set of named triggers warrants ongoing watch: NFPA 101 amendment cycles, EU Cyber Resilience Act implementation pace, and India BIS certification pathway streamlining.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market