
 Global Self Defense Products Market | 2026-2036
Global Self Defense Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self Defense Products Market Foresight
The capital-intensity divergence between established defense contractors and emerging non-lethal specialists is unwinding competitive stability in this sector. SABRE Security Equipment Corp. leverages integrated chemical manufacturing to control pepper spray supply chains from formulation to retail shelf. Axon Enterprise anchors its position through connected-cloud platforms that pair conducted electrical weapons with body-worn camera ecosystems. Byrna Technologies differentiates via compressed-air propulsion systems that circumvent firearm classification in multiple jurisdictions.
Self defense products encompass chemically active incapacitants, electroshock devices, kinetic impact tools, and acoustic deterrents engineered to neutralize threats without lethal force, typically operating at voltages below lethal thresholds or deploying oleoresin capsicum concentrations between 1.0% and 2.0% major capsaicinoids. These instruments serve personal protection, institutional security, and civil disturbance management functions across civilian and professional contexts. Pepper spray maintains the largest installed base among product types due to low cost and minimal training requirements, while stun guns capture expanding margin pools through rechargeable lithium-ion architectures and integrated LED targeting systems. The e-commerce distribution channel is accelerating fastest as direct-to-consumer brands bypass traditional sporting goods gatekeepers, though specialty stores retain premium positioning for law enforcement-grade specifications.
The US FDA regulates chemical irritant formulations through over-the-counter drug monographs, while the EU REACH framework restricts certain propellant chemistries and mandates comprehensive safety data sheets for cross-border shipment. Japan's METI enforces electrical safety certifications on stun devices through PSE marking requirements that limit import pathways. Stakeholders must monitor evolving state-level prohibitions on concealed electroshock devices alongside municipal ordinances governing pepper spray canister dimensions and discharge mechanisms.
Market Dynamics
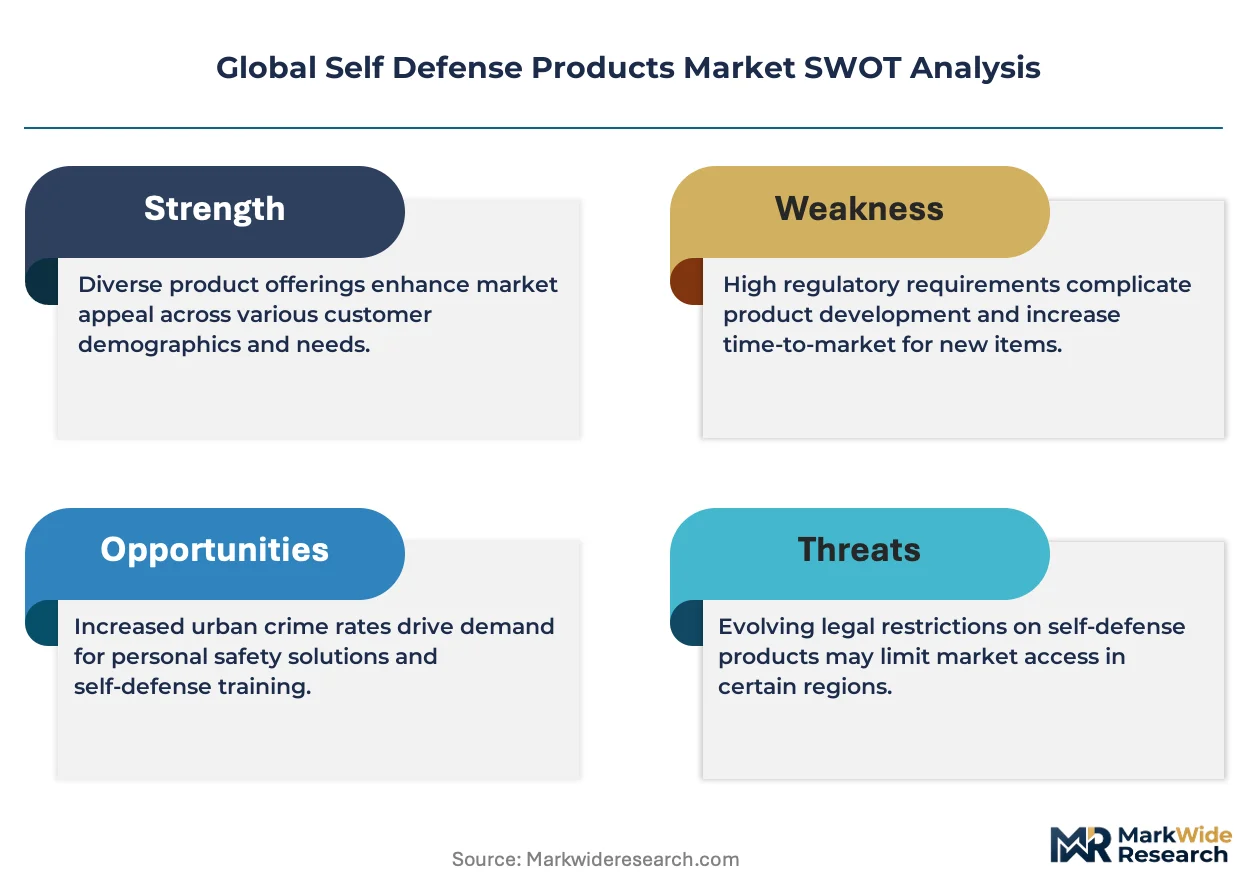
Regulatory fragmentation between chemical irritant classifications and electrical weapon jurisdictions is forcing manufacturers to maintain parallel compliance architectures, elevating fixed costs while compressing time-to-market for new formulations.
Growth Catalysts
- Campus safety mandates:US state legislatures are requiring K-12 and university security offices to stock less-lethal deterrents, institutionalizing procurement workflows that bypass traditional retail channels.
- REACH propellant restrictions:The EU ECHA framework is phasing out fluorinated propellants, creating first-mover advantage for manufacturers with compressed-air or nitrogen-based delivery systems already certified for cross-border shipment.
- Lithium-ion rechargeable architectures:Stun device manufacturers are migrating from disposable alkaline cells to integrated battery packs, reducing lifetime ownership costs and enabling firmware-updateable platforms.
Market Restraints
- Oleoresin capsicum supply concentration:Capsicum cultivation clusters in India and China expose formulators to monsoon-driven harvest volatility and pesticide residue testing failures at EU ports.
- Japan PSE marking requirements:METI electrical safety certifications require in-country testing facilities that most Western manufacturers lack, effectively capping import volumes through procedural friction.
- Smartphone-enabled personal safety apps:Location-sharing and emergency dispatch applications are capturing mindshare among urban professionals who previously represented the core stun gun demographic.
Strategic Opportunities
- Brazil ANVISA pathway acceleration:The regulator's 2023 irritant device reclassification created a formal registration route previously blocked by ambiguous pharmaceutical-cosmetic boundaries.
- Drone-mounted acoustic deterrents:Convergence of unmanned aerial platforms and directional sound projection enables perimeter security applications without ground personnel exposure.
- Direct-to-consumer subscription models:E-commerce native brands are bypassing sporting goods distributors through recurring canister replacement programs with embedded training content.
Industry Challenges
- Firmware security certification:Connected electrical weapons require IEC 62443 cybersecurity validation that extends development cycles by 8-14 months and demands scarce embedded systems talent.
- Propellant chemistry reformulation:Transitioning from HFC-134a to nitrogen or compressed CO2 requires retooling filling lines and revalidating shelf-life claims under accelerated aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self Defense Products Market |
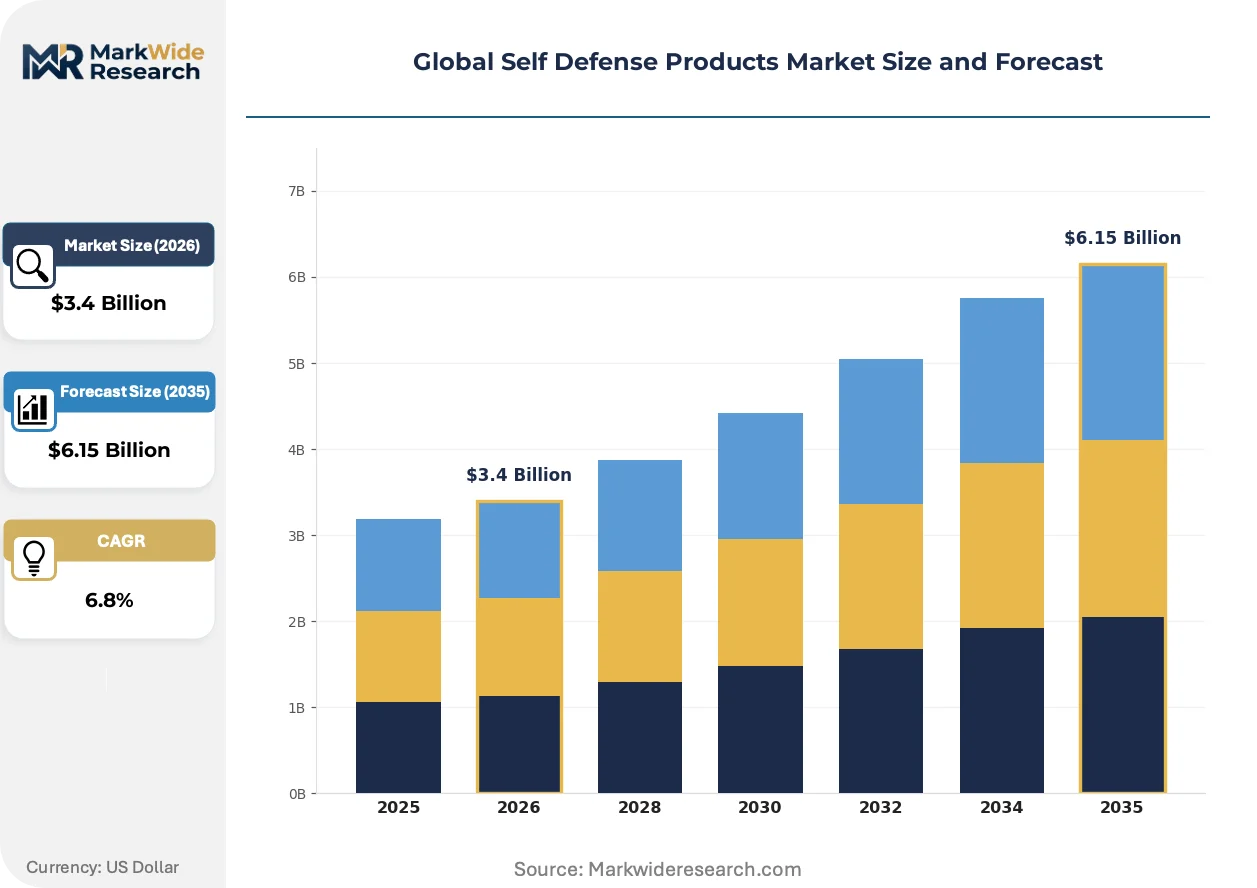
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
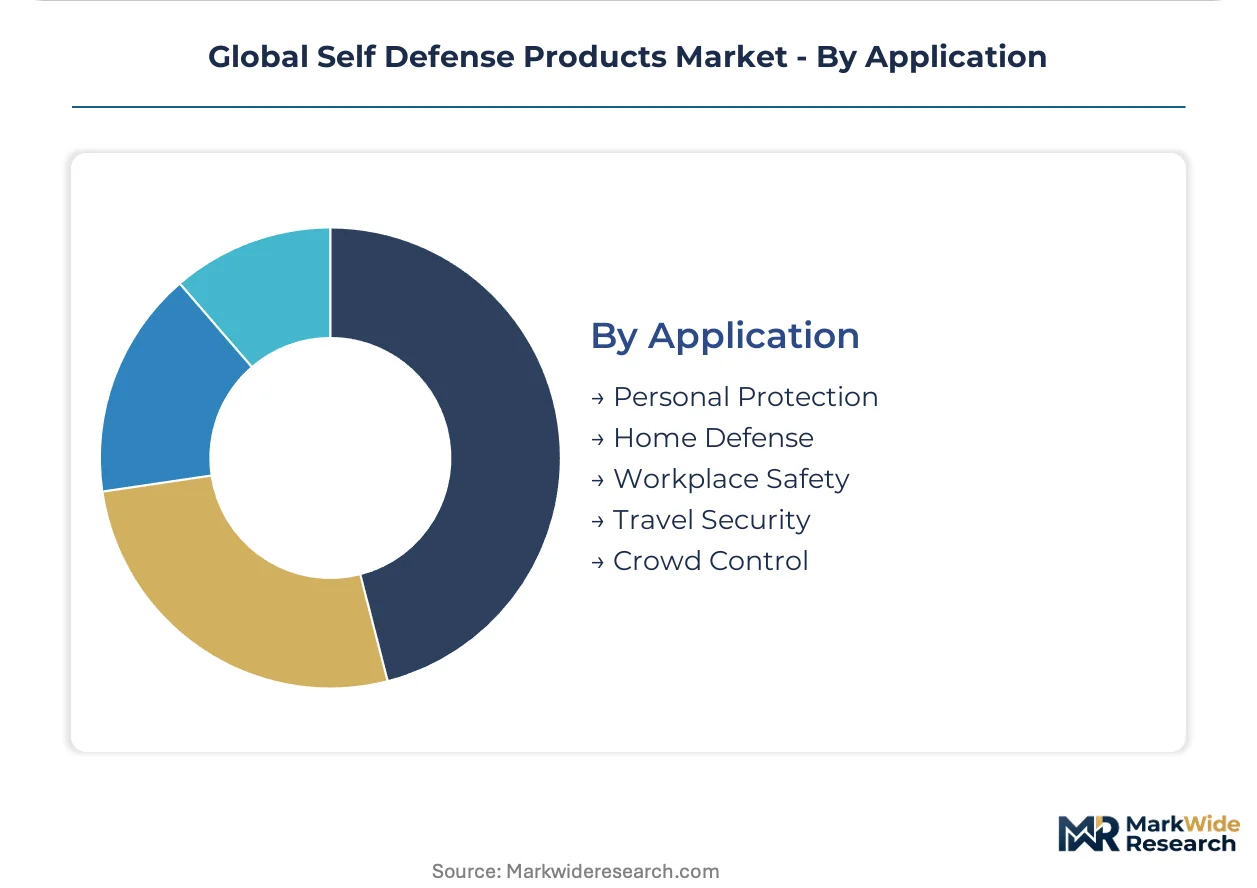
| Segmentation | Product Type: Pepper Spray, Stun Guns, Personal Alarms, Tactical Flashlights, Kubotans, Brass Knuckles End User: Law Enforcement Officials, Security Personnel, College Students, Outdoor Enthusiasts, Corporate Employees, Travelers Distribution Channel: Specialty Stores, E-commerce Platforms, Sporting Goods Retailers, Pharmacies, Direct Selling Application: Personal Protection, Home Defense, Workplace Safety, Travel Security, Crowd Control |
| Companies Covered | SABRE Security Equipment Corp., Axon Enterprise, Mace Security International, Gerber Gear, Victorinox, ASP, Spyderco, Byrna Technologies, Buck Knives, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self Defense Products Market Shifts & Advancements
Product intelligence and connectivity are migrating from premium law enforcement SKUs into civilian-accessible price bands, collapsing the traditional segmentation between professional and personal protection equipment.
Conducted electrical weapons with integrated GPS logging and cloud-synced discharge records are supplanting standalone stun devices in municipal police procurement. Departments in Texas and Florida are mandating connectivity as a condition of liability insurance coverage. This shift is compressing margins for legacy hardware-only vendors while elevating recurring software revenue pools.
The EU AI Act's risk classification framework for biometric-enabled threat detection is reshaping certification requirements for smart pepper spray systems with facial recognition targeting. Manufacturers must now submit conformity assessments to notified bodies in Germany and France before CE marking. Law enforcement-grade specifications are absorbing the compliance burden fastest, while consumer variants face delayed launch timelines.
Law enforcement agencies are consolidating vendor relationships through multi-year framework agreements that bundle less-lethal devices with body-worn cameras and evidence management software. This purchasing pattern concentrates volume with integrated platform providers and marginalizes standalone chemical irritant suppliers. The shift is most pronounced in US state police departments with centralized procurement authority.
Global Self Defense Products Market Segmentation
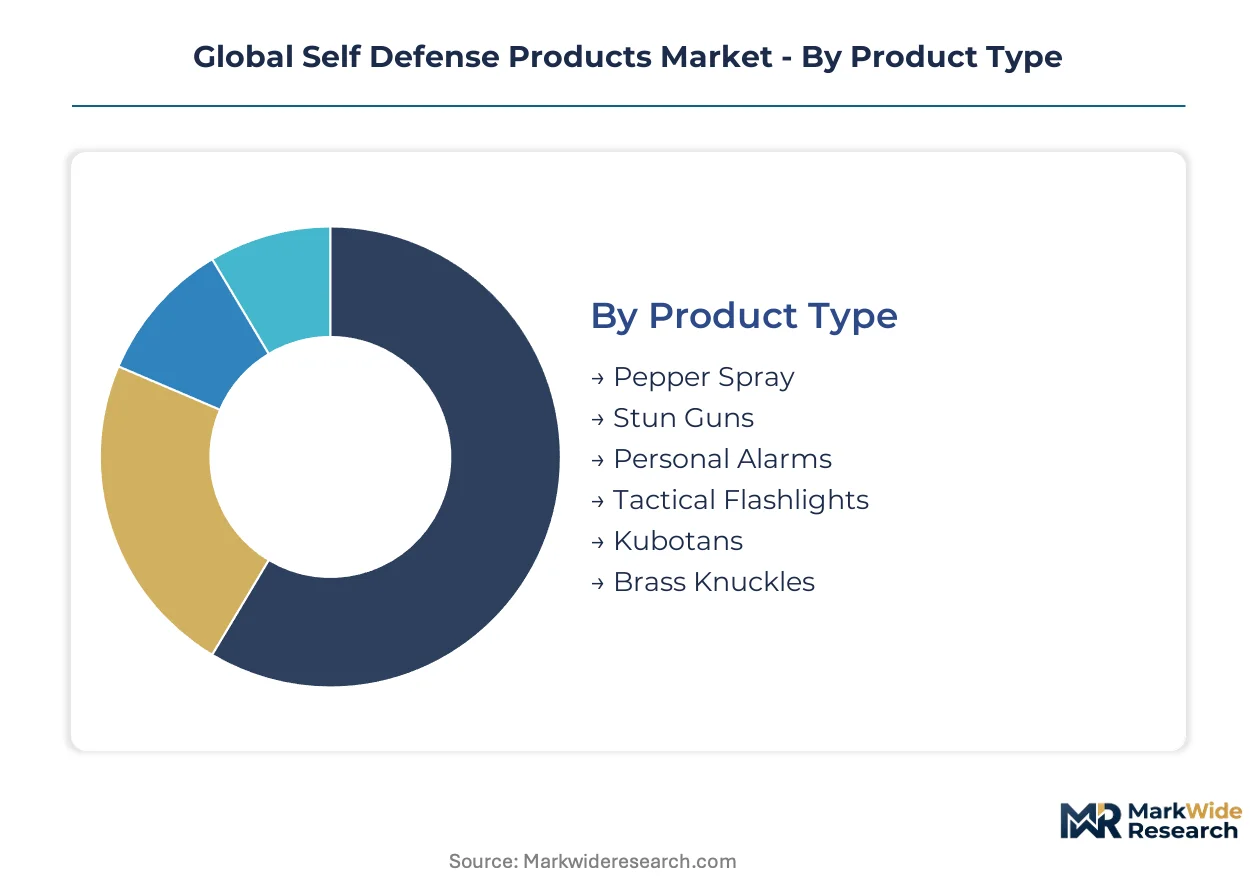
Segmentation in the self defense products market reveals how substitution pressures reshape competitive boundaries. Chemical irritants face encroachment from smartphone-enabled safety apps, while electrical weapons compete against connected-cloud security platforms. Understanding these cross-category dynamics illuminates where procurement budgets migrate and which specifications retain pricing power.
Product Type:
Oleoresin capsicum formulations confront the strongest substitution threat from acoustic deterrents and biometric-enabled threat detection systems, forcing manufacturers to defend shelf space through formulation patents and delivery mechanism patents.
- Pepper Spray:Oleoresin capsicum concentrations between 1.0% and 2.0% major capsaicinoids dominate civilian procurement due to minimal training requirements and FDA over-the-counter drug monograph accessibility. Demand concentrates in United States campus safety programs where state mandates institutionalize bulk purchasing.
- Stun Guns:Rechargeable lithium-ion architectures with integrated LED targeting systems capture expanding procurement from municipal police departments in Texas and Florida. Cloud-synced discharge records and GPS logging now feature in liability insurance compliance requirements.
- Personal Alarms:Compact decibel-emitting devices target urban professionals seeking non-confrontational deterrence.
- Tactical Flashlights:High-lumen output tools with strike bezels serve dual illumination and impact functions for outdoor enthusiasts.
- Kubotans:Handheld pressure-point implements require minimal regulatory clearance across most jurisdictions.
- Brass Knuckles:Kinetic impact tools face prohibitive state-level restrictions in California, New York, and Illinois.
Pepper spray retains volume leadership; stun guns hold the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement workflows from individual purchasing patterns, with framework agreements and centralized buying concentrating volume in law enforcement while fragmenting civilian acquisition.
- Law Enforcement Officials:Multi-year vendor consolidation bundles conducted electrical weapons with body-worn cameras and evidence management software. Procurement authority centralization in state police departments marginalizes standalone chemical irritant suppliers.
- Security Personnel:Corporate and private security contractors favor less-lethal devices with connected-cloud platforms enabling incident documentation.
- College Students:Campus safety mandates in United States K-12 and university systems institutionalize pepper spray stocking requirements.
- Outdoor Enthusiasts:Hiking and camping demographics prioritize lightweight, weather-resistant deterrent formats.
- Corporate Employees:Workplace safety protocols drive procurement of personal alarms and tactical flashlights for late-shift workers.
- Travelers:Airline carry-on restrictions and destination-country legality concerns complicate product selection.
Law enforcement officials command the premium pricing tier; college students represent the fastest-growing procurement volume.
Distribution Channel:
Geography determines channel viability, with e-commerce penetration varying sharply by regulatory environment and last-mile delivery infrastructure for hazardous materials.
- Specialty Stores:Law enforcement-grade specifications and training services sustain premium positioning despite e-commerce encroachment. Staff expertise and hands-on product evaluation retain value for security professionals.
- E-commerce Platforms:Direct-to-consumer brands bypass sporting goods gatekeepers through recurring canister replacement programs with embedded training content. Subscription models reduce customer acquisition costs.
- Sporting Goods Retailers:Outdoor enthusiast demographics drive seasonal purchasing patterns for tactical flashlights and personal alarms.
- Pharmacies:FDA over-the-counter drug monograph compliance enables pepper spray placement alongside first aid supplies.
- Direct Selling:Independent distributors target residential security seminars and corporate safety training events.
Specialty stores retain premium margin capture; e-commerce platforms are expanding most quickly.
Application:
Maturity differentiates established use cases from emerging demand pockets, with personal protection saturating while workplace safety and travel security applications absorb compliance-driven specification upgrades.
- Personal Protection:Civilian concealed-carry legislation in United States jurisdictions sustains baseline demand for portable deterrents. Smartphone-enabled safety apps capture mindshare among urban professionals.
- Home Defense:Perimeter security applications increasingly incorporate drone-mounted acoustic deterrents without ground personnel exposure.
- Workplace Safety:Late-shift retail and healthcare employers face liability pressure to equip isolated workers.
- Travel Security:Cross-border shipment restrictions under EU REACH and destination-country legality create procurement friction.
- Crowd Control:Municipal procurement of less-lethal devices for civil disturbance management requires specialized training infrastructure.
Personal protection retains installed base dominance; workplace safety shows the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where campus safety mandates and concealed-carry legislation institutionalize premium procurement, while Brazilian and Indian markets absorb cost-optimized formulations through regulatory arbitrage on propellant chemistries.
United States
K-12 and university security offices drive institutional procurement volumes through state-level stocking mandates. The FDA regulates pepper spray formulations through over-the-counter drug monographs that enable pharmacy distribution alongside first aid supplies. Texas and Florida municipal police departments concentrate demand for connected-cloud electrical weapons with GPS logging capabilities.
Germany
EU REACH propellant restrictions under ECHA jurisdiction are phasing out fluorinated chemistries and elevating nitrogen-based delivery systems. The EU AI Act's risk classification framework requires conformity assessments from German notified bodies for biometric-enabled threat detection systems. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized filling operations for cross-border chemical irritant shipment.
Brazil
ANVISA's 2023 irritant device reclassification established formal registration pathways previously blocked by pharmaceutical-cosmetic boundary ambiguity. State police procurement in São Paulo and Rio de Janeiro is consolidating vendor relationships through multi-year framework agreements. Domestic manufacturers exploit regulatory clarity to capture share from previously informal import channels.
Japan
METI enforces PSE electrical safety certifications on stun devices through in-country testing facilities that limit Western import volumes. Urban professionals in Tokyo and Osaka represent a contracting demographic as smartphone-enabled safety apps capture mindshare. Domestic distributors maintain premium positioning for law enforcement-grade specifications through specialized retail networks.
India
Capsicum cultivation clusters in Andhra Pradesh and Karnataka expose formulators to monsoon-driven harvest volatility and pesticide residue testing failures at EU ports. BIS standards govern electrical safety certifications for stun devices while state-level concealed-carry permissions vary across Maharashtra, Delhi, and Gujarat. E-commerce platforms are accelerating fastest in Bangalore and Hyderabad as direct-to-consumer brands bypass traditional sporting goods gatekeepers.
Global Self Defense Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated platform providers commanding law enforcement procurement while specialized chemical manufacturers dominate civilian retail channels. The market structures around three tiers: connected-cloud ecosystem vendors, integrated chemical formulators, and compressed-air propulsion specialists. Strategic moves concentrate on vendor consolidation through multi-year framework agreements and propellant chemistry reformulation to satisfy REACH compliance deadlines.
Within the integrated platform tier, Axon Enterprise anchors positions through body-worn camera ecosystem bundling. SABRE Security Equipment Corp. exemplifies backward integration into oleoresin capsicum supply chains. Byrna Technologies occupies a position among compressed-air propulsion specialists circumventing firearm classification across multiple jurisdictions.
| Leading Market Players |
|---|
| SABRE Security Equipment Corp. |
| Axon Enterprise |
| Mace Security International |
| Gerber Gear |
| Victorinox |
| ASP |
| Spyderco |
| Byrna Technologies |
| Buck Knives |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles for oleoresin capsicum concentrate in Andhra Pradesh and Karnataka directly tether pricing volatility to monsoon patterns, compressing margin buffers for formulators while amplifying procurement power for backward-integrated manufacturers with captive cultivation networks.
Pricing Analysis
Configured-to-order pricing for law enforcement-grade conducted electrical weapons commands a 40-60% premium over standard civilian SKUs, reflecting firmware customization and connected-cloud platform integration. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Price differentiation stems from FDA over-the-counter monograph accessibility versus EU REACH compliance burden. Cost compression in economy-tier pepper spray intensifies because of propellant chemistry reformulation investments. College students represent the most price-sensitive segment; municipal police departments with centralized procurement authority exhibit the least sensitivity.
Supply Chain Analysis
Just-in-time inventory preferences dominate civilian retail channels, while strategic stockpiling characterizes law enforcement framework agreements with multi-year canister replacement commitments. Geographic supply concentration centers on India and China for oleoresin capsicum, the United States for integrated electrical weapon assembly, and Germany for nitrogen-based propellant filling operations. Raw material dependencies include capsicum oleoresin, lithium-ion battery cells, and compressed CO2 cartridges. Single-source vulnerability in Indian cultivation clusters exposes formulators to climate-driven harvest failures. Distribution runs through specialty security retailers for premium tiers and direct-to-consumer e-commerce platforms for mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as body-worn camera ecosystems absorb less-lethal device procurement into bundled vendor relationships, collapsing standalone hardware margins and elevating recurring software revenue pools.
For Market Incumbents: Compound platform stickiness through deeper integration of conducted electrical weapons with evidence management software and cloud-synced discharge analytics. Defend against compressed-air propulsion specialists by accelerating firmware-updateable architectures with IEC 62443 cybersecurity certification. Prioritize captive supply of oleoresin capsicum through cultivation partnerships in Karnataka and Andhra Pradesh to neutralize harvest volatility. For New Entrants and Emerging Players: Differentiate on regulatory arbitrage by pursuing ANVISA registration pathways in Brazil ahead of incumbents still navigating pharmaceutical-cosmetic boundary ambiguity. Target workplace safety applications for isolated late-shift workers in retail and healthcare, where liability pressure outstrips procurement sophistication. Deploy direct-to-consumer subscription models with embedded training content to bypass sporting goods distributor gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant personal defense divisions lacking connected-cloud capabilities. Five-to-ten-year viability hinges on software revenue attachment rates exceeding hardware depreciation cycles. Watch for municipal police liability insurance mandates requiring GPS logging and cloud-synced discharge records as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Connected-Cloud Platform Integration | Axon Enterprise's body-worn camera bundling concentrates municipal procurement volume and marginalizes standalone vendors. |
| Propellant Chemistry Reformulation | Nitrogen-based delivery systems capture first-mover advantage under EU REACH fluorinated propellant phase-out deadlines. |
| Direct-to-Consumer Subscription Launch | Recurring canister replacement programs with embedded training content reduce customer acquisition costs for e-commerce native brands. |
| Backward Integration into Cultivation | SABRE Security Equipment Corp.'s captive oleoresin capsicum supply chains neutralize Indian monsoon-driven harvest volatility. |
| Cybersecurity Certification Investment | IEC 62443 validation for connected electrical weapons extends development cycles but satisfies Texas and Florida liability insurance mandates. |
Research Methodology
Desk research of customs/trade databases, FDA over-the-counter drug monographs, EU REACH registration dossiers, and SEC 10-K filings preceded structured interviews with procurement directors at municipal police departments, category managers at sporting goods retailers, plant managers at oleoresin capsicum extraction facilities, and regulatory affairs leads at electrical weapon manufacturers. Primary fieldwork combined with secondary validation through BIS standards documentation, ANVISA registration records, and METI PSE certification databases. Bottom-up SKU-level volume aggregation and top-down macroeconomic constraint modeling were triangulated against midpoint estimates.
Variance decomposition across product type, end-user segment, distribution channel, and application dimensions isolates growth contribution by category over the projection horizon. Segmentation dimensions modeled include chemical irritant concentration tiers, electrical weapon connectivity specifications, institutional versus civilian procurement workflows, and geographic regulatory clusters. CAGRs were derived from logistic adoption curves fitted to historical penetration data and adjusted for state-level campus safety mandate implementation schedules and EU AI Act conformity assessment timelines.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cell cost declines or accelerated EU REACH enforcement would require recalibration. Forecasts reflect assumptions regarding propellant chemistry transition timelines and municipal procurement centralization trajectories. Revision becomes warranted when smartphone-enabled safety app penetration crosses thresholds that materially displace stun gun demand among urban professionals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Safety
Life Jacket Market
Personal Safety
Road Safety Market
Personal Safety
Personal Safety Alarms Market
Personal Safety
Night Vision Goggles Market
Personal Safety
Concealable Vest Market
Personal Safety
Personal Safety Apps for Women Market
Personal Safety
Global Medical Alert System/Personal Emergency Response System Market
Personal Safety
China Travel Safety Kits Market
Personal Safety
Pepper Sprays Market
Personal Safety
Fall Detection System Market
Personal Safety
Child Leash Market
Personal Safety
Body Armor and Personal Protection Market
Personal Safety
Bulletproof Vest Market
Personal Safety
Child Safety Seat Market
Personal Safety
Asia-Pacific People Screening Market
Personal Safety
Global Personal Emergency Response Systems (PERS) Market