
 Global Air Sampling Pumps Market | 2026-2036
Global Air Sampling Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Sampling Pumps Market Analysis
Asset-light leasing models for precision monitoring equipment are reshaping competitive dynamics in air sampling, lowering capital barriers for mid-sized environmental consultancies. SKC Inc. leverages its deep catalog of calibration accessories to sustain recurring revenue streams across industrial accounts. Thermo Fisher Scientific anchors its position through backward integration into sensor manufacturing, while Sensidyne LP competes aggressively on channel control within the North American distributor network.
Air sampling pumps are electromechanical devices designed to draw precise volumes of air through collection media such as sorbent tubes, filter cassettes, or impingers, typically operating at flow rates from 0.5 to 5,000 liters per minute with calibrated accuracy within five percent. Their primary purpose spans occupational exposure assessment, ambient pollutant quantification, and controlled-environment contamination verification. Portable pumps lead equipment demand due to field-deployment flexibility across construction and chemical processing sites, while filter-based technology dominates routine particulate monitoring where cost-per-sample economics favor simplicity over spectral resolution. Fixed pump installations anchor revenue stability through long-term contracts with utility stack monitoring programs.
OSHA permissible exposure limit enforcement and EPA National Ambient Air Quality Standards compliance obligations directly shape procurement specifications for flow-calibrated pump systems in the United States. The EU Green Deal and associated Industrial Emissions Directive tighten traceability requirements for environmental monitoring data across German, French, and Dutch regulatory jurisdictions. Stakeholders must monitor evolving ISO 13137 performance standards for pump durability testing, as harmonized certification protocols will determine which manufacturers retain market access across multiple national approval frameworks.
Market Dynamics
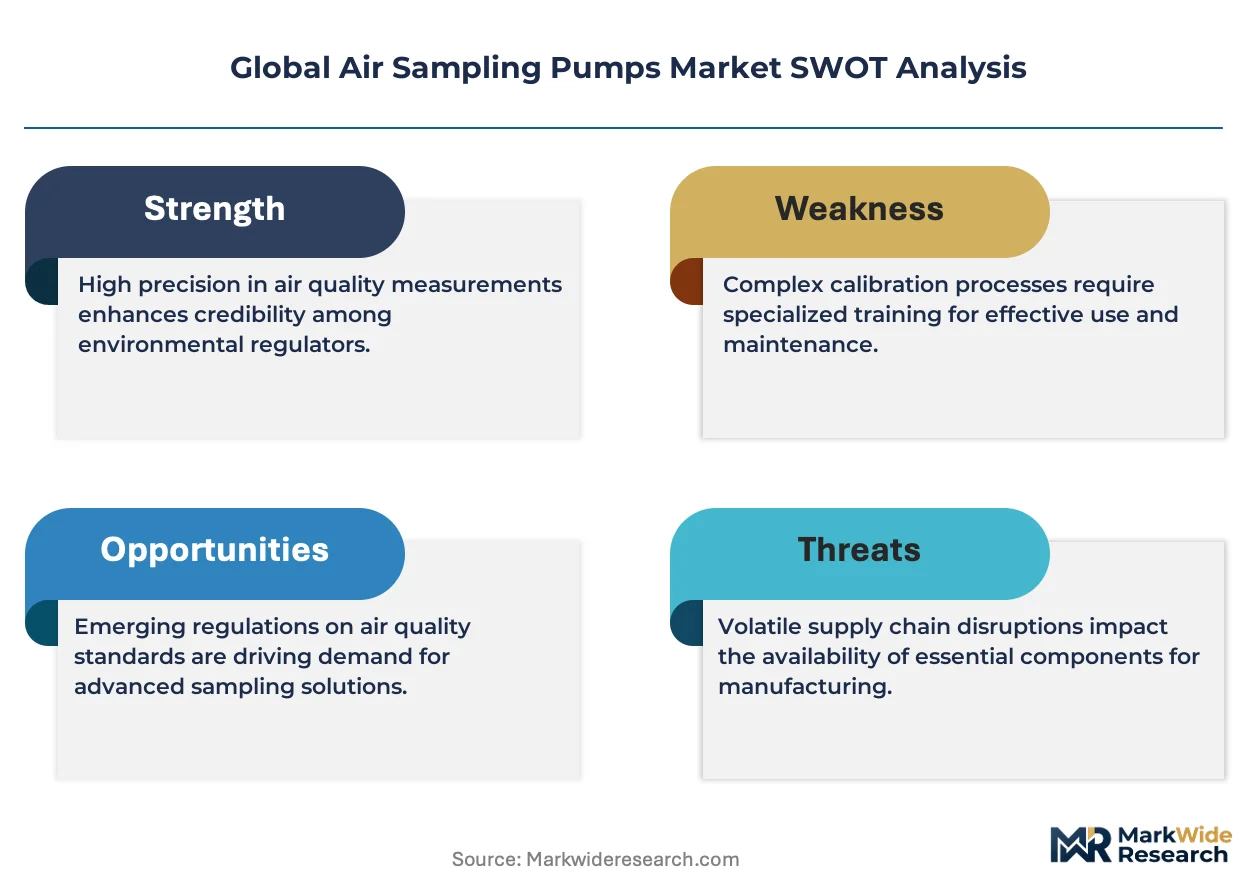
Calibration protocol harmonization under ISO 13137 is compressing supplier margins while elevating technical barriers for equipment manufacturers serving multi-jurisdictional industrial hygiene programs.
Growth Catalysts
- OSHA enforcement tightening:Workplace exposure limit audits in US manufacturing facilities are mandating pump recalibration cycles that shorten replacement intervals for precision flow-control equipment.
- EU Green Deal traceability mandates:Industrial Emissions Directive compliance across German chemical clusters requires continuous ambient monitoring infrastructure with certified data lineage.
- Filter-based particulate economics:Routine stack monitoring programs favor low-cost cassette technology over spectral instruments, sustaining volume demand for calibrated high-flow pump systems.
Market Restraints
- Sensor component concentration:Precision mass flow sensor supply concentrates among Japanese and German component specialists, exposing pump assemblers to allocation risk during demand spikes.
- Battery chemistry volatility:Lithium-ion cell price swings directly impact portable pump bill-of-materials, compressing margins on field-deployment equipment lines.
- REACH substance restrictions:Sorbent tube coatings face phase-out scrutiny under European chemical registration protocols, forcing reformulation of established collection media.
Strategic Opportunities
- Indian environmental enforcement:Central Pollution Control Board expansion of ambient air quality networks creates first-time demand for calibrated pump systems in secondary industrial cities.
- Cloud-integrated telemetry:Real-time flow data transmission to centralized compliance dashboards enables predictive maintenance contracts and recurring software revenue streams.
- Construction sector unbundling:Specialist environmental consultancies are displacing generalist safety providers on major infrastructure projects, creating channel openings for precision equipment specialists.
Industry Challenges
- Metrology talent scarcity:Certified flow calibration technicians command premium compensation in industrial hygiene markets, constraining service network expansion for equipment vendors.
- Legacy system integration:Fixed-stack monitoring installations running analog data protocols resist retrofit with digital pump interfaces, prolonging sales cycles for utility sector upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Sampling Pumps Market |
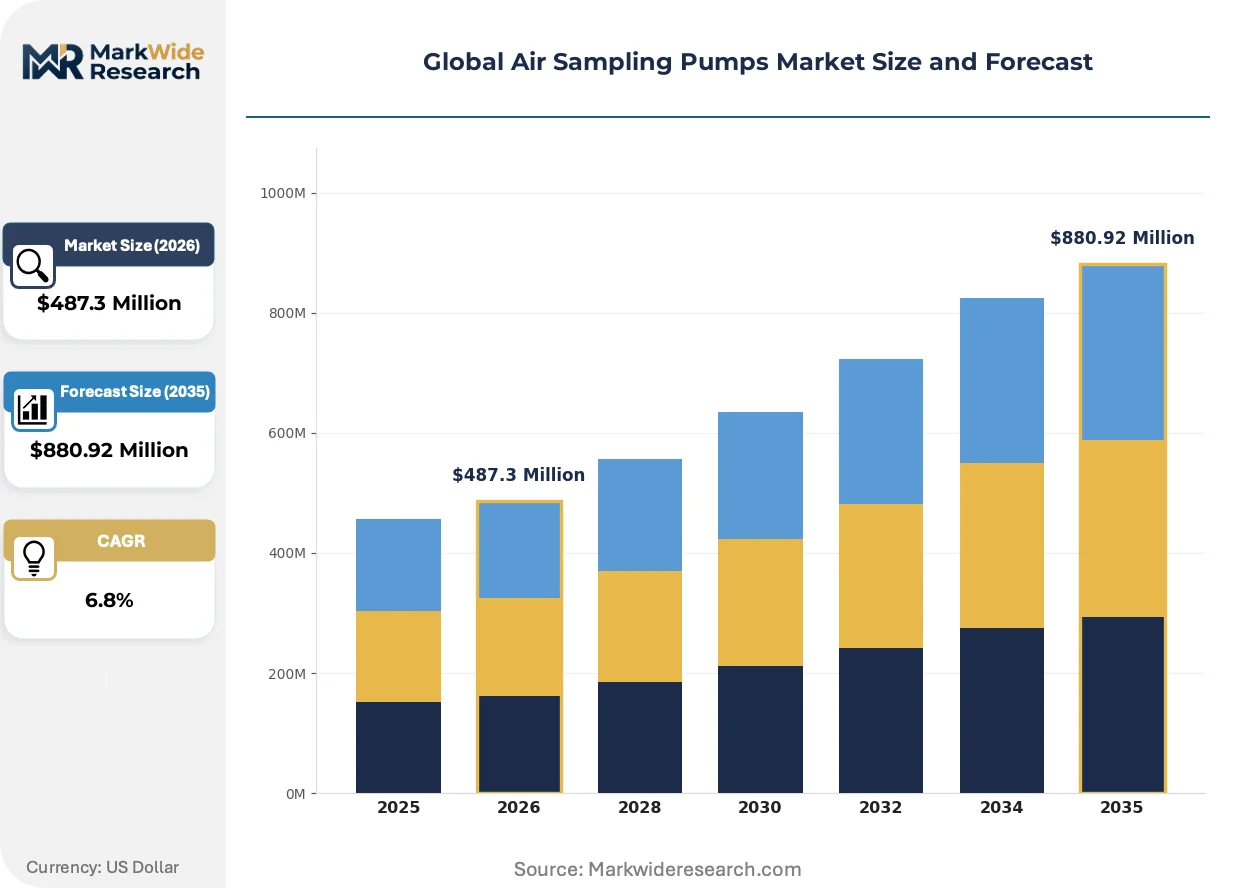
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pumps, Fixed Pumps, Calibration Pumps, High-Volume Pumps Technology: Electrochemical, Mass Spectrometry, Optical, Filter-Based Application: Industrial Emissions, Environmental Monitoring, Indoor Air Quality, Laboratory Analysis End User: Manufacturing Units, Research Institutions, Government Agencies, Healthcare Facilities |
| Companies Covered | Thermo Fisher Scientific Inc., PerkinElmer, SKC Inc., Sensidyne LP, GL Sciences, Casella, AP Buck Inc., SIBATA Scientific Technology Ltd., GASTEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Sampling Pumps Market Emerging Trajectories
Connectivity architectures and regulatory data architectures are converging to redefine equipment value propositions, shifting competitive advantage from hardware precision toward integrated compliance workflows.
Bluetooth-enabled pump diagnostics is digitizing field calibration workflows by transmitting real-time flow verification data directly to tablet-based audit applications. Environmental consultancies in North American construction and chemical processing sectors are adopting these interfaces to eliminate manual transcription errors. This connectivity layer is digitizing service revenue models, compressing the addressable market for third-party calibration houses while expanding manufacturer attach rates for software subscriptions.
REACH substance evaluation protocols are accelerating sorbent tube reformulation timelines as coating chemistries face authorization scrutiny. European industrial hygiene contractors must now validate alternative collection media against established occupational exposure benchmarks. German environmental agencies and French chemical manufacturers are absorbing the highest compliance burden, driving demand for pumps compatible with next-generation sorbent specifications.
Leasing structures for precision monitoring fleets are displacing capital purchase patterns among mid-sized environmental service providers. Equipment financiers and manufacturer captive finance units are capturing recurring revenue streams previously allocated to distributor inventory. This financing penetration concentrates in German industrial clusters and US Gulf Coast petrochemical corridors where project-based contracting favors operational expenditure treatment.
Global Air Sampling Pumps Market Segmentation
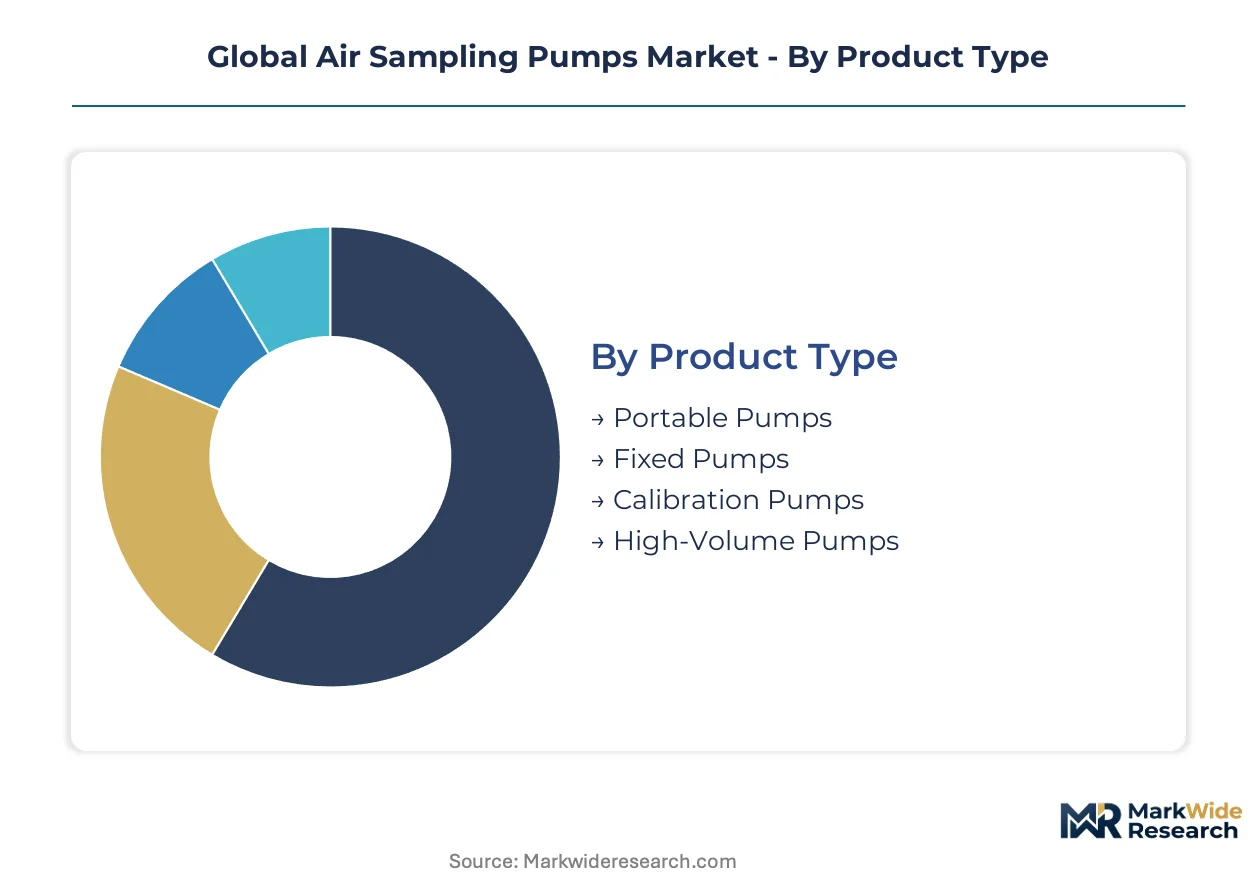
Air sampling pump procurement patterns diverge sharply across technical specifications and deployment contexts. Calibration service intensity, replacement cycle frequency, and regulatory compliance burden vary by segment, reshaping vendor go-to-market economics.
Product Type:
After-sales service intensity peaks with portable and high-volume pump categories, where field calibration demands and consumable replacement cycles generate recurring revenue pools that rival initial equipment margins.
- Portable Pumps:Battery-powered electromechanical units operating at 0.5-5 liters per minute, designed for personal exposure monitoring and construction site deployment. Demand concentrates in German chemical clusters and US Gulf Coast petrochemical corridors where OSHA workplace exposure audits mandate frequent field calibration. Leasing structures for precision monitoring fleets are displacing capital purchase patterns among mid-sized environmental service providers, compressing distributor margins while expanding manufacturer attach rates for software subscriptions.
- High-Volume Pumps:Stationary systems drawing 500-5,000 liters per minute for ambient air quality networks and stack monitoring programs. Procurement concentrates with German environmental agencies and French chemical manufacturers facing EU Green Deal traceability mandates for continuous emissions verification. Fixed installations anchor revenue stability through long-term service contracts, though legacy analog data protocols resist retrofit with digital interfaces.
- Fixed Pumps:Permanent installations for utility stack monitoring and industrial perimeter surveillance.
- Calibration Pumps:Precision reference standards for flow verification and metrology laboratory accreditation.
By volume, portable pumps lead. By growth pace, high-volume pumps are expanding most quickly.
Technology:
Component cost tiers stratify sharply across detection methodologies, with electrochemical and filter-based systems dominating procurement budgets while optical and mass spectrometry platforms capture premium pricing in laboratory settings.
- Filter-Based:Particulate collection on pre-weighed membrane media with gravimetric analysis, offering cost-per-sample economics that favor routine stack monitoring programs. Procurement concentrates with US manufacturing facilities facing EPA National Ambient Air Quality Standards compliance and Indian Central Pollution Control Board network expansion. Routine particulate monitoring favors this simplicity over spectral resolution, sustaining volume demand for calibrated high-flow pump systems.
- Electrochemical:Gas-specific sensors measuring target compound concentrations through redox reactions at electrode surfaces. Demand clusters in German industrial hygiene programs and Dutch environmental monitoring networks where ISO 13137 performance standards govern pump durability certification. Bluetooth-enabled pump diagnostics is digitizing field calibration workflows by transmitting real-time flow verification data directly to tablet-based audit applications.
- Optical:Light scattering and absorption methods for real-time particulate quantification.
- Mass Spectrometry:High-resolution molecular identification for research-grade laboratory analysis.
Filter-based technology commands the largest installed base. Electrochemical platforms are gaining share fastest as connectivity integration accelerates.
Application:
Regulatory enforcement intensity varies by monitoring context, with industrial emissions programs driving replacement cycles and indoor air quality applications opening new customer segments.
- Industrial Emissions:Continuous monitoring of stack effluents and perimeter ambient conditions for regulatory compliance documentation. Demand concentrates in German chemical clusters and US manufacturing facilities where tightening OSHA enforcement and EPA standards mandate shorter recalibration intervals. EU Industrial Emissions Directive compliance requires certified data lineage infrastructure.
- Environmental Monitoring:Ambient air quality network stations and mobile survey platforms for pollutant mapping. Procurement is accelerating with Indian Central Pollution Control Board expansion into secondary industrial cities and French regional agency network upgrades. Cloud-integrated telemetry enables real-time flow data transmission to centralized compliance dashboards.
- Indoor Air Quality:Building ventilation assessment and occupational exposure verification in commercial and institutional settings.
- Laboratory Analysis:Research-grade sampling for method development and reference standard validation.
Industrial emissions generates the highest equipment revenue per site. Environmental monitoring is climbing the fastest as national network buildouts accelerate.
End User:
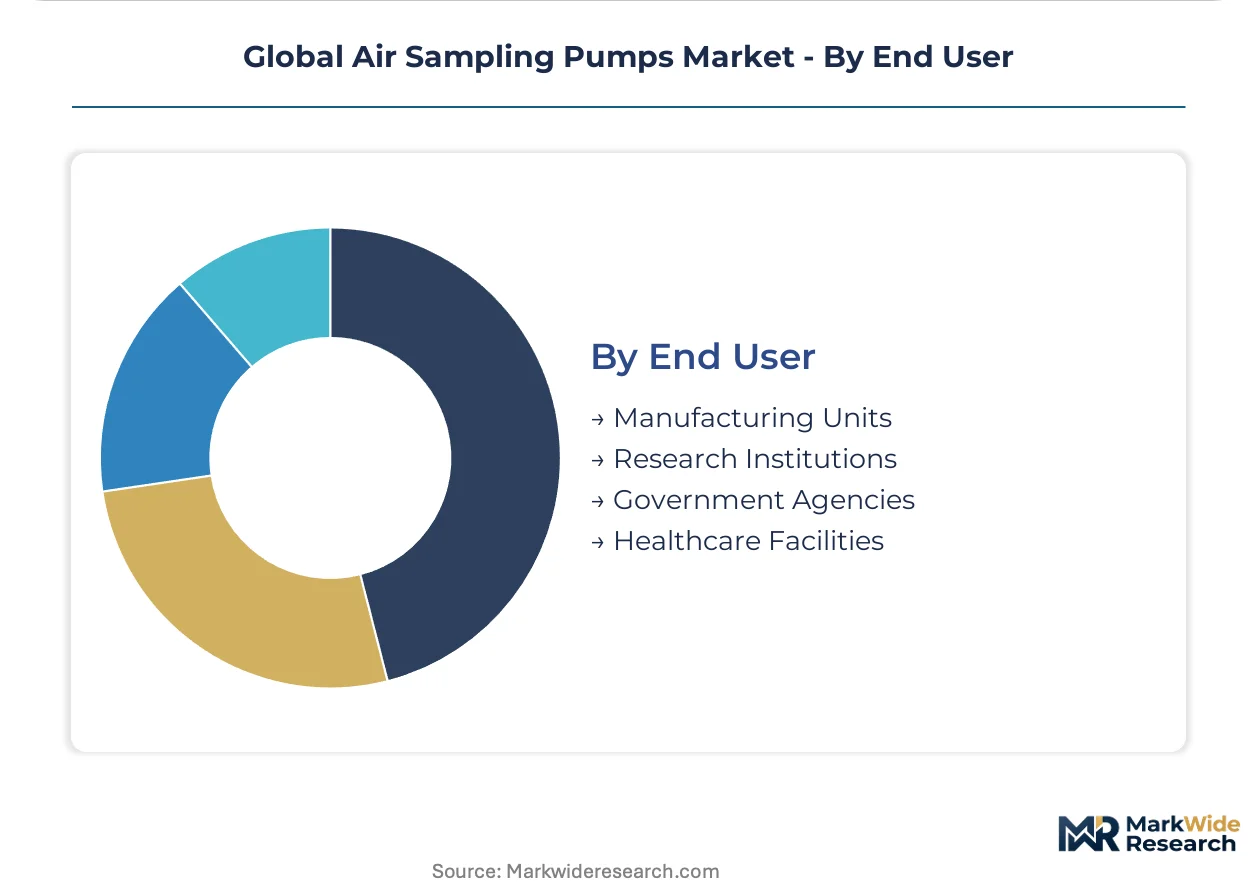
Customer sophistication and procurement authority diverge across institutional categories, with government agencies mandating certified data protocols and manufacturing units prioritizing operational expenditure flexibility.
- Manufacturing Units:In-house industrial hygiene teams and contracted environmental services at chemical processing, pharmaceutical, and heavy industrial facilities. Demand concentrates in US Gulf Coast petrochemical corridors and German Ruhr industrial clusters where project-based contracting favors leasing over capital purchase. Specialist environmental consultancies are displacing generalist safety providers on major infrastructure projects.
- Government Agencies:National environmental regulators and regional air quality management districts operating certified monitoring networks. Procurement in Germany, France, and the Netherlands prioritizes ISO 13137-compliant equipment with harmonized certification protocols for multi-jurisdictional market access. REACH substance evaluation protocols are accelerating sorbent tube reformulation timelines.
- Research Institutions:Universities and national laboratories conducting method development and exposure science studies.
- Healthcare Facilities:Hospital occupational health departments and infection control programs.
Government agencies deploy the most units per contract. Manufacturing units are expanding procurement fastest as environmental enforcement tightens across industrial jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial clusters where EU regulatory stringency commands premium equipment margins, while Indian procurement operates on cost-optimized specifications for network expansion programs.
United States
OSHA workplace exposure audits and EPA National Ambient Air Quality Standards enforcement drive replacement cycles for calibrated flow-control equipment. The tightening of permissible exposure limit verification mandates shorter recalibration intervals across manufacturing facilities. Gulf Coast petrochemical corridors absorb the highest equipment density as specialist environmental consultancies displace generalist safety providers on major infrastructure projects.
Germany
EU Green Deal traceability requirements and Industrial Emissions Directive compliance anchor demand for certified data lineage infrastructure. ISO 13137 performance standards govern pump durability certification protocols across multi-jurisdictional industrial hygiene programs. Ruhr industrial clusters and Bavarian chemical manufacturers drive replacement cycles for high-volume pump systems through continuous ambient monitoring obligations.
India
Central Pollution Control Board expansion into secondary industrial cities creates first-time demand for calibrated pump systems in ambient air quality networks. National ambient monitoring program buildouts prioritize cost-optimized procurement specifications for high-volume deployment. Maharashtra and Gujarat industrial belts concentrate equipment uptake as environmental enforcement tightens across chemical processing and pharmaceutical manufacturing zones.
France
Regional air quality management districts prioritize ISO 13137-compliant equipment with harmonized certification for multi-jurisdictional market access. EU Industrial Emissions Directive traceability mandates require continuous emissions verification infrastructure at chemical manufacturing sites. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur industrial zones absorb compliance burden as REACH substance evaluation accelerates sorbent tube reformulation timelines.
China
Dual carbon goals and Ministry of Ecology and Environment enforcement protocols expand stack monitoring obligations across heavy industrial facilities. National ambient air quality standards tighten calibration requirements for utility and manufacturing emissions verification. Yangtze River Delta and Pearl River Delta manufacturing clusters drive procurement volume as provincial environmental agencies upgrade continuous monitoring infrastructure.
Global Air Sampling Pumps Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with captive sensor supply and calibration accessory portfolios. Market structure consolidates around diversified instrumentation conglomerates with backward integration into sensor manufacturing, while mid-sized specialists compete through channel control and leasing model innovation. Three archetypes dominate: diversified laboratory instrumentation platforms, precision pump specialists with deep calibration catalogs, and regional fabricators with cost-optimized assembly. Competitive moves concentrate on strategic partnerships for cloud-integrated telemetry and geographic expansion through distributor network consolidation.
Within the diversified platform tier, Thermo Fisher Scientific Inc. anchors positioning through in-house sensor production capabilities. SKC Inc. and Sensidyne LP exemplify the precision specialist archetype, occupying positions defined by calibration service intensity and channel control within North American distribution networks. These three entities represent the competitive vectors shaping procurement patterns across industrial hygiene and environmental monitoring applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| PerkinElmer |
| SKC Inc. |
| Sensidyne LP |
| GL Sciences |
| Casella |
| AP Buck Inc. |
| SIBATA Scientific Technology Ltd. |
| GASTEC Corporation |
| Others |
Supply Flow & Price Mechanics
Japanese and German precision mass flow sensor suppliers anchor upstream concentration, capturing margin pools that pump assemblers struggle to reclaim through downstream integration. This component bottleneck shapes pricing power across portable and high-volume equipment tiers, with calibration service bundling emerging as the primary margin defense for finished-goods manufacturers.
Pricing Analysis
Configured-to-order pricing for ISO 13137-certified pumps commands spreads against standard-flow units, with certification-grade equipment carrying material premiums. Pricing stratifies across premium, standard, and economy tiers based on traceability documentation depth and after-sales calibration bundling. Cost compression in portable pump lines is intensifying because lithium-ion cell volatility feeds directly into bill-of-materials exposure. Manufacturing units in US Gulf Coast corridors exhibit highest price sensitivity, while German environmental agencies prioritize certified data lineage over unit economics.
Supply Chain Analysis
Export-control restrictions on precision sensor technology limit component flows from Japanese specialists to pump assemblers in India and China, constraining supply elasticity. Manufacturing concentrates in Germany, Japan, and the United States for high-specification units, with cost-optimized assembly gravitating toward Chinese facilities. The supply chain draws from lithium-ion cell production, precision machining for pump housings, and sorbent tube coatings facing REACH substance scrutiny. Single-source vulnerability concentrates in mass flow sensor supply. Distribution runs through industrial hygiene distributors and manufacturer-direct service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified flow calibration technicians command premium compensation that constrains service network expansion, creating a structural bottleneck around metrology capability. This scarcity shapes competitive positioning for vendors seeking to differentiate through field-service intensity rather than hardware margins alone.
For Market Incumbents: Insulate recurring revenue streams by deepening calibration accessory portfolios and captive sensor supply arrangements. Threat from cloud-integrated telemetry providers demands software subscription attach rates that displace third-party calibration houses. Priority lever: backward integration into precision mass flow sensor manufacturing to reclaim margin pools captured by Japanese and German component specialists.
For New Entrants and Emerging Players: Build out leasing-model infrastructure targeting mid-sized environmental consultancies in Indian secondary industrial cities where first-time demand outpaces established vendor presence. White-space concentrates in Maharashtra and Gujarat industrial belts facing Central Pollution Control Board enforcement expansion. Go-to-market angle: operational expenditure treatment with predictive maintenance contracts enabled by Bluetooth-enabled pump diagnostics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision pump specialists carrying deep calibration catalogs but limited geographic footprint beyond North American distributor networks. Long-term viability hinges on cloud-telemetry integration and multi-jurisdictional ISO 13137 certification access. Signal to watch: REACH substance evaluation acceleration forcing sorbent tube reformulation, which favors vendors with R&D capacity to validate alternative collection media.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Integrated Telemetry Development | Real-time flow data transmission enables predictive maintenance contracts with German environmental agencies. |
| Calibration Service Network Expansion | Certified technician scarcity in industrial hygiene markets creates defensive moats around incumbent positions. |
| Backward Integration into Sensor Manufacturing | In-house precision mass flow production reduces allocation risk from Japanese and German component specialists. |
| Leasing Model Infrastructure Buildout | Operational expenditure treatment captures mid-sized environmental consultancies in US Gulf Coast corridors. |
| Multi-Jurisdictional Certification Investment | Harmonized ISO 13137 compliance secures market access across German, French, and Dutch regulatory frameworks. |
Methodological Framework
Operator-level perspectives from industrial hygiene program managers, environmental consultancy procurement leads, calibration laboratory technicians, and OEM aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from EPA enforcement records, EU Industrial Emissions Directive compliance filings, Central Pollution Control Board network expansion announcements, and SEC 10-K disclosures from diversified instrumentation conglomerates. Bottom-up equipment shipment analysis and top-down regulatory mandate sizing provided cross-referenced triangulation.
Scenario-bracketing around OSHA enforcement intensity and EU Green Deal implementation pace bounded uncertainty across the projection horizon. Segmentation dimensions modeled include product type, detection technology, application context, end-user institutional category, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and compliance-driven procurement timing. Industry-specific inputs incorporated lithium-ion cell price trajectory assumptions and REACH substance evaluation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native telemetry providers or Chinese cost-optimized assemblers would shift outcomes. Material shifts in ISO 13137 harmonization timelines or REACH authorization protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Europe Hazardous Waste Handling Automation Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Noise Control System Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Industrial Noise Control Market