
 Cargo Container X-Ray Inspection Systems Market | 2026-2036
Cargo Container X-Ray Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Container X-Ray Inspection Systems Market Insights
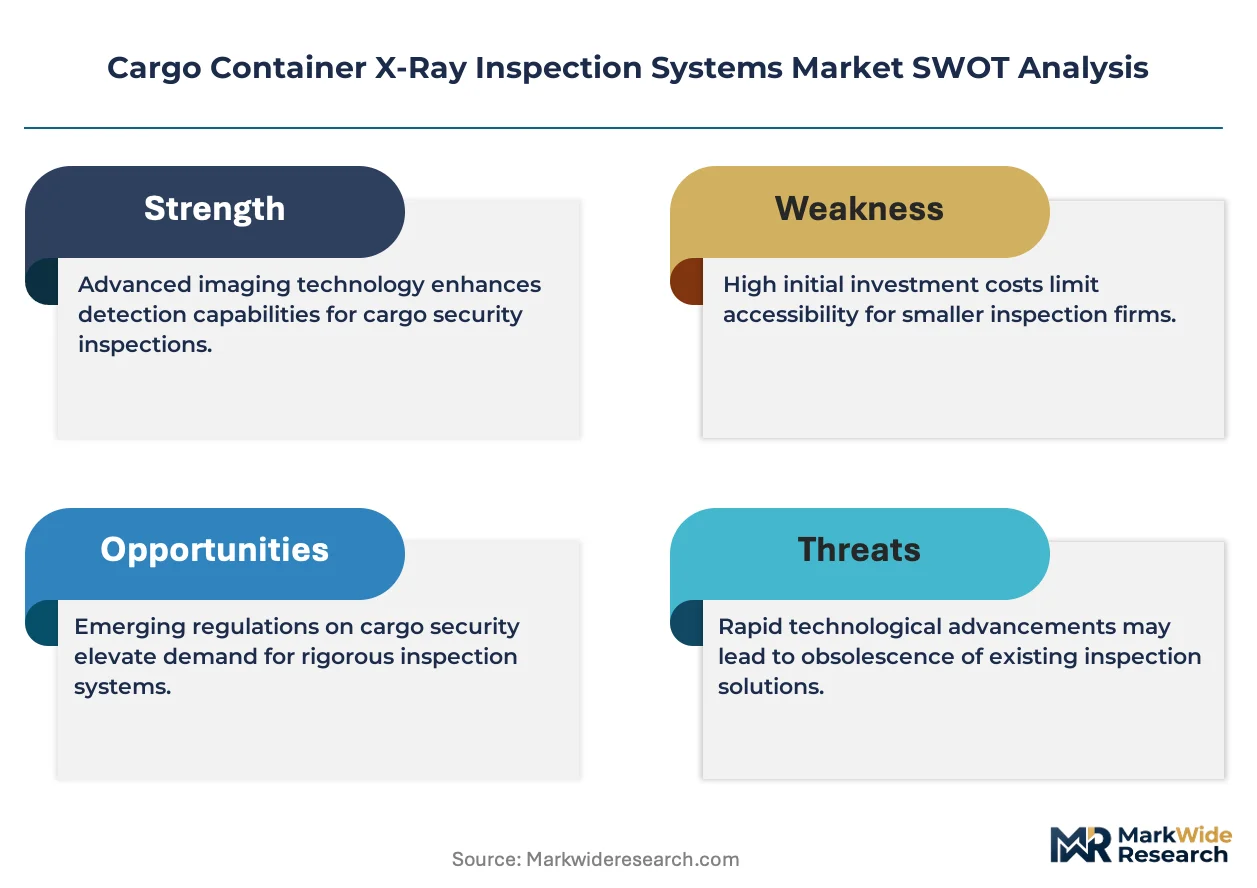
Multi-source procurement for detector arrays and linear accelerator subsystems is recalibrating how port authorities and customs agencies evaluate total cost of ownership against single-vendor lock-in. Smiths Detection Inc. leverages its installed base across British and Dutch port networks to sustain recurring service revenues. Nuctech Company Limited anchors its position through captive manufacturing of radiation sources and detector panels in Beijing and Hefei. OSI Systems, Inc. competes on dual-energy algorithm refinement for dense-cargo discrimination at North American land borders.
Cargo container X-ray inspection systems employ high-energy linear accelerators or cobalt-60 isotopes generating 1-9 MeV photon beams, with dual-energy material discrimination algorithms separating organic threats from inorganic cargo at throughput rates exceeding 25 containers per hour. Fixed X-Ray Systems dominate capital allocation at greenfield port terminals where civil infrastructure accommodates gantry-mounted architectures. Computed Tomography segments attract premium positioning as customs agencies in Rotterdam, Singapore, and Los Angeles mandate three-dimensional density mapping for targeted inspection protocols. Portal Inspection Systems occupy a mature replacement cycle at legacy land-border crossings with lower daily throughput requirements.
The U.S. Customs and Border Protection's adoption of ASTM F2921-21 performance standards shapes North American procurement specifications, while the EU's F-Gas Regulation constrains cooling system refrigerants deployed in mobile truck-mounted units across member states. China's SAMR enforces GB standards for radiation leakage limits at domestic manufacturing facilities, affecting export certification timelines for Nuctech and LINEV Systems. Stakeholders must monitor divergence between national radiation safety thresholds and emerging automated threat recognition mandates requiring algorithm retraining across heterogeneous customs databases.
Market Dynamics
Automated threat recognition algorithms are compressing inspection times while customs agencies simultaneously demand higher material discrimination accuracy, forcing suppliers to recalibrate hardware-software integration architectures without expanding physical footprint.
Growth Catalysts
- EU Security Screening Regulation:Mandates for higher throughput detection standards at major transshipment hubs are accelerating replacement cycles for legacy fixed-gantry systems.
- China port modernization:Civil infrastructure investments at greenfield terminals in Ningbo and Qingdao prioritize gantry-mounted architectures with integrated radiation monitoring.
- Dual-energy algorithm advancement:Dense-cargo discrimination capabilities are expanding addressable inspection volumes for high-value electronics and pharmaceutical shipments.
Market Restraints
- Cobalt-60 supply concentration:Isotope production clusters in Russia and Canada create procurement vulnerability for portal inspection systems at land-border crossings.
- F-Gas Regulation constraints:EU restrictions on refrigerants in mobile truck-mounted units limit thermal management options for detector arrays in Mediterranean climates.
- Linear accelerator cost structure:High-voltage power supply subsystems constitute 35-40% of capital expenditure, compressing margins for mid-tier port authorities.
Strategic Opportunities
- Computed tomography convergence:Three-dimensional density mapping integration with automated targeting protocols opens premium positioning at Rotterdam, Singapore, and Los Angeles.
- Southeast Asian logistics corridors:Vietnam's Cai Mep and Thailand's Laem Chabang underpenetration relative to container throughput creates first-mover installation windows.
- ASTM F2921-21 harmonization:US CBP performance standard adoption across North American land borders enables certification leverage for dual-energy system suppliers.
Industry Challenges
- Algorithm retraining complexity:Heterogeneous customs databases across Rotterdam, Singapore, and Los Angeles require jurisdiction-specific threat libraries, fragmenting R&D allocation.
- GB standard divergence:China's SAMR radiation leakage limits differ from IEC thresholds, extending export certification timelines for Beijing and Hefei manufacturing facilities.
- Legacy system integration:Portal inspection infrastructure at mature land-border crossings resists gantry-mounted architecture retrofits due to civil works constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Container X-Ray Inspection Systems Market |
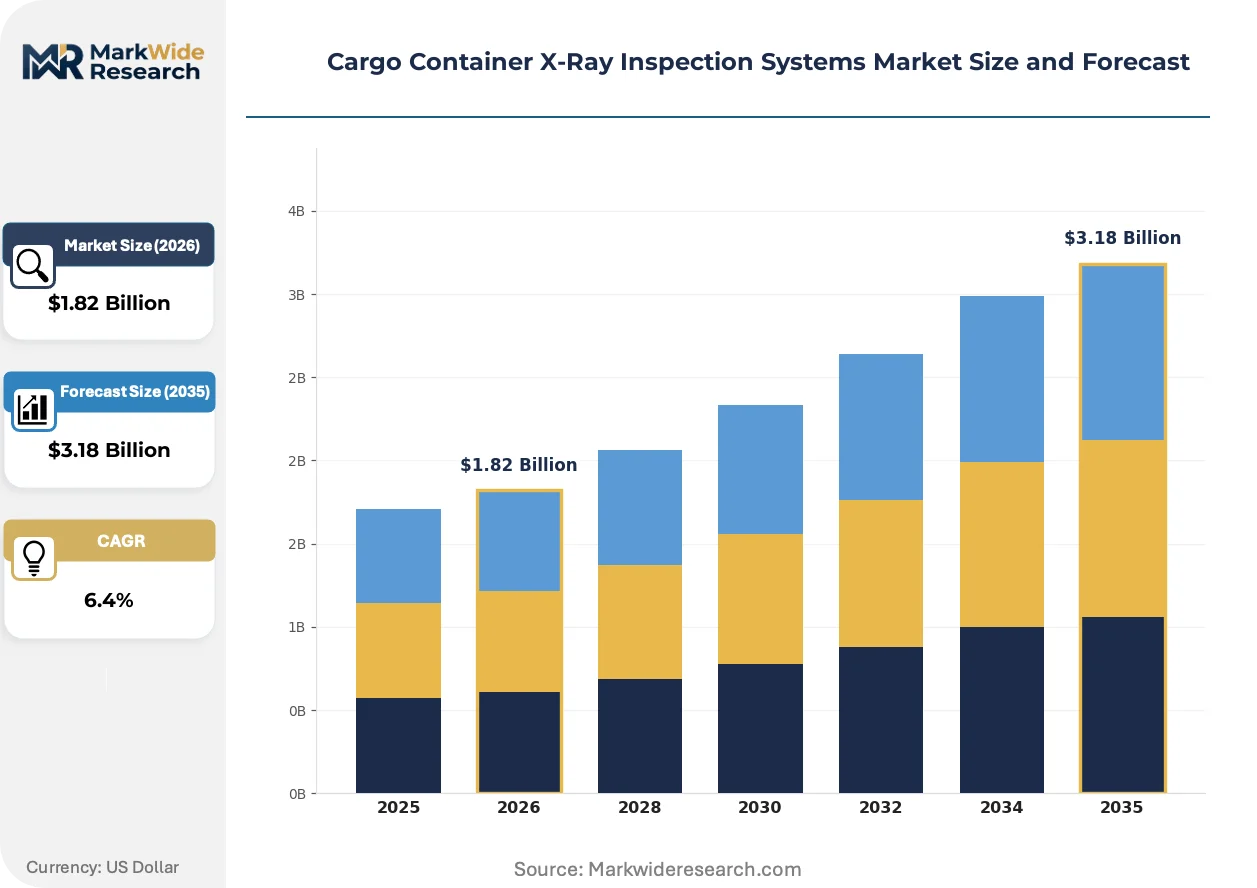
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed X-Ray Systems, Mobile X-Ray Systems, Portal Inspection Systems, Mobile Truck-Mounted Systems Technology: Single-Energy X-Ray, Dual-Energy X-Ray, Computed Tomography, Backscatter Technology Application: Counterterrorism, Border Security, Customs Control, Cargo Screening End User: Ports & Harbors, Airports, Logistic Service Providers, Law Enforcement Agencies |
| Companies Covered | Smiths Detection Inc., OSI Systems, Inc., Nuctech Company Limited, Leidos Holdings, Inc., Rapiscan Systems, Astrophysics Inc., L3Harris Technologies, Inc., LINEV Systems, Gilardoni S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Container X-Ray Inspection Systems Market Trends and Innovations
Machine learning inference at the edge is compressing decision latency while customs agencies unbundle hardware procurement from algorithm licensing, fragmenting traditional single-vendor relationships.
Computed tomography reconstruction for cargo screening is absorbing capital allocation from conventional radiographic systems as Rotterdam, Singapore, and Los Angeles customs agencies mandate three-dimensional density mapping for targeted inspection protocols. Port authorities in these jurisdictions are retiring fixed-gantry installations ahead of depreciation schedules. The technology is absorbing service revenue streams previously captured by maintenance-only contracts.
The EU's F-Gas Regulation is constraining cooling system refrigerant choices for mobile truck-mounted units, forcing detector array suppliers to redesign thermal management architectures for Mediterranean and Middle Eastern deployment conditions. Manufacturers are qualifying alternative cooling chemistries under accelerated lifecycle testing. Mobile inspection fleet operators in Spain, Italy, and Greece face compressed procurement timelines as legacy refrigerant phase-outs advance.
After-sales service unbundling is separating hardware maintenance contracts from algorithm update subscriptions, enabling port authorities to source threat-recognition software from specialists independent of original equipment manufacturers. Customs agencies in the Netherlands and United Kingdom are piloting multi-vendor support architectures. This restructuring is most visible at high-throughput terminals where annual algorithm retraining costs now exceed physical maintenance expenditures.
Cargo Container X-Ray Inspection Systems Market Segmentation
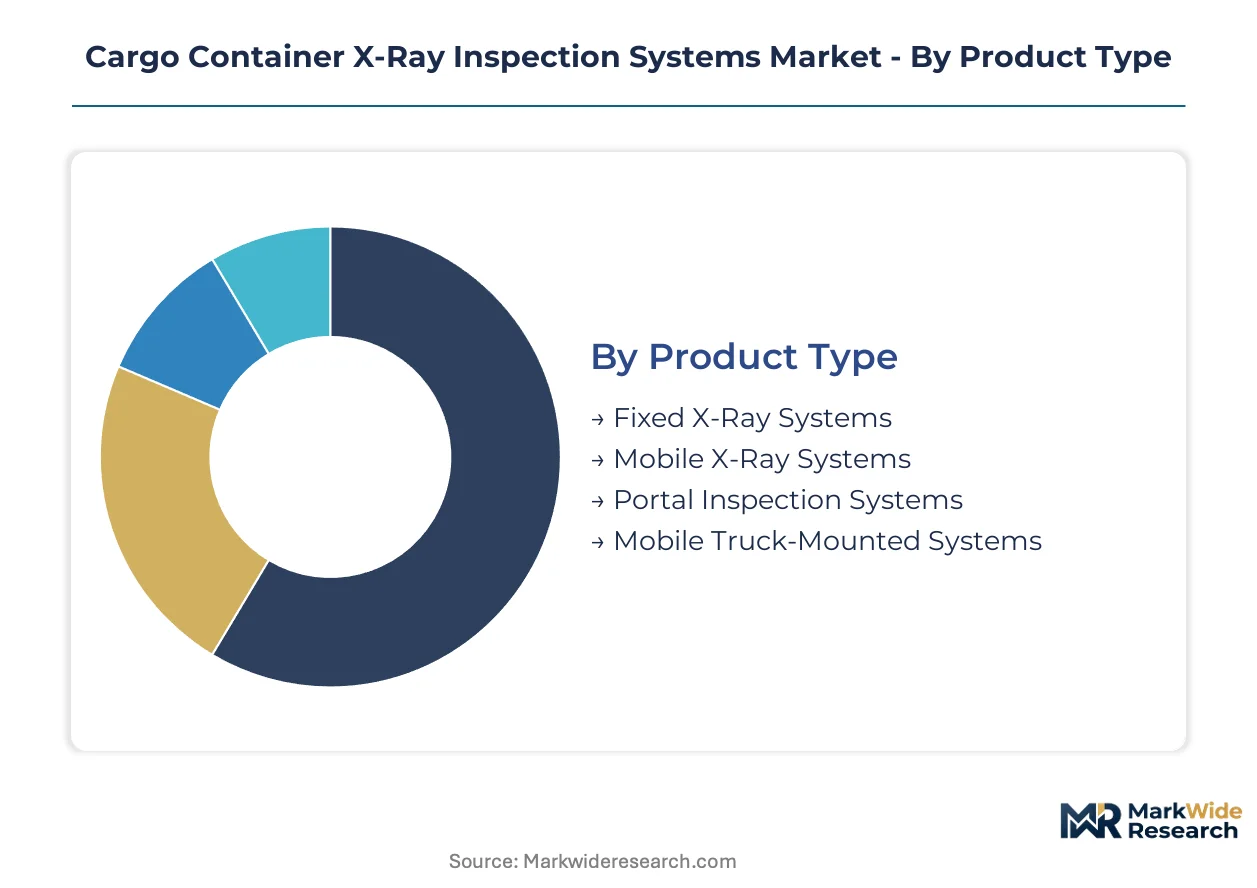
Procurement patterns across customs agencies and port authorities fragment sharply by deployment architecture and threat-detection capability. Upgrade cycles diverge between greenfield installations and legacy retrofit constraints, reshaping supplier contract structures and service revenue models.
Product Type:
Replacement timelines stretch from 8 years for gantry-mounted fixed installations to 4-5 years for mobile fleets exposed to harsher operational conditions.
- Fixed X-Ray Systems:Gantry-mounted architectures dominate capital allocation at greenfield terminals where civil infrastructure accommodates permanent foundations. Demand concentrates at China's Ningbo and Qingdao port modernization programs, driven by integrated radiation monitoring requirements and EU-mandated throughput standards.
- Mobile X-Ray Systems:Truck-mounted or trailer-deployed configurations enable rapid repositioning across inspection zones without permanent civil works. Border agencies in Spain, Italy, and Greece prioritize these units under compressed F-Gas refrigerant phase-out timelines, forcing thermal management redesigns.
- Portal Inspection Systems:Drive-through configurations serve mature land-border crossings with lower daily throughput requirements.
- Mobile Truck-Mounted Systems:Self-propelled units with onboard power generation address emergency response and temporary checkpoint scenarios.
Volume placements concentrate in Fixed X-Ray Systems; the faster expansion belongs to Mobile Truck-Mounted Systems.
Technology:
Algorithm licensing unbundling from hardware procurement is fragmenting supplier relationships across detection methodologies.
- Single-Energy X-Ray:Basic radiographic imaging using monoenergetic photon beams provides density mapping without material discrimination. Legacy installations at budget-constrained land borders in Eastern Europe and Central Asia delay replacement due to capital rationing.
- Dual-Energy X-Ray:Spectral separation of high and low-energy photon absorption enables organic-inorganic material classification for contraband detection. North American land border procurement under ASTM F2921-21 standards drives specification harmonization, with CBP mandating dense-cargo discrimination for electronics and pharmaceutical shipments.
- Computed Tomography:Three-dimensional density reconstruction with automated targeting protocols commands premium positioning. Rotterdam, Singapore, and Los Angeles customs agencies mandate CT integration, accelerating retirement of conventional radiographic systems ahead of depreciation schedules.
- Backscatter Technology:Compton scattering detection emphasizes low-Z organic materials including explosives and narcotics. Specialized deployment at vehicle checkpoints and small-package inspection nodes supplements primary screening architectures.
Dual-Energy X-Ray captures the largest installed base; Computed Tomography is climbing the fastest as three-dimensional reconstruction absorbs service revenue streams from maintenance-only contracts.
Application:
Threat vector prioritization by jurisdiction reshapes feature requirements across detection sensitivity and throughput trade-offs.
- Counterterrorism:Explosive device detection mandates drive highest-sensitivity configurations with automated threat recognition algorithms. Intelligence-led targeting protocols at Rotterdam and Los Angeles prioritize false-positive reduction over pure throughput.
- Border Security:Illicit migration and weapons interdiction requirements shape mobile deployment patterns. Land-border agencies in Texas and Arizona balance inspection depth against queue length management during peak crossing periods.
- Customs Control:Revenue protection and trade compliance verification emphasize manifest-to-image reconciliation. Vietnam's Cai Mep and Thailand's Laem Chabang underpenetration creates first-mover installation windows as container throughput outpaces screening capacity.
- Cargo Screening:General contraband detection across diverse commodity categories demands flexible material discrimination. Pharmaceutical and electronics shipments drive premium algorithm subscriptions due to high-value density and concealment sophistication.
Customs Control dominates current procurement volumes; Counterterrorism applications are gaining share fastest as algorithm retraining costs exceed physical maintenance expenditures at high-sensitivity nodes.
End User:
Ownership models diverge between direct agency procurement and third-party screening service contracts.
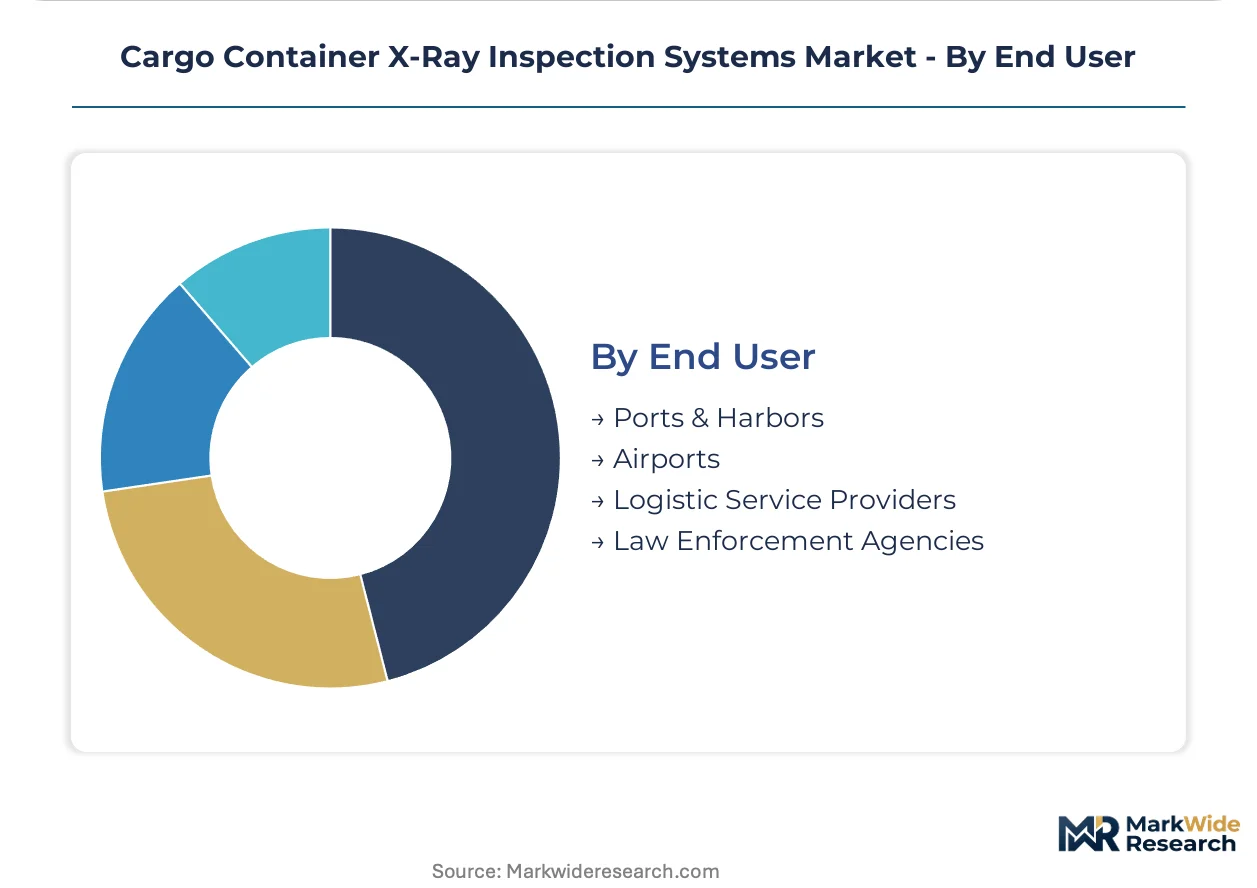
- Ports & Harbors:Terminal operators and port authorities bear primary responsibility for sea container inspection infrastructure. China's port modernization programs and Southeast Asian logistics corridors anchor demand concentration.
- Airports:Air cargo screening requirements under aviation security regulations drive compact, high-throughput installations. Integration with existing baggage handling systems constrains physical footprint expansion.
- Logistic Service Providers:Third-party screening contractors offer inspection-as-a-service to shippers seeking supply chain security certification. After-sales service unbundling enables multi-vendor support architectures independent of original equipment manufacturers.
- Law Enforcement Agencies:Mobile deployment for checkpoint operations and emergency response prioritizes rapid setup and breakdown capabilities.
Ports & Harbors account for the steepest expansion trajectory; Logistic Service Providers show the fastest growth in algorithm subscription revenue as service models fragment traditional vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cobalt-60 isotope production clusters in Russia and Canada anchor procurement vulnerability for portal inspection systems, while linear accelerator manufacturing concentrates in China, Germany, and the United States. Customs agencies across Rotterdam, Singapore, and Los Angeles drive specification convergence through automated threat recognition mandates.
United States
U.S. Customs and Border Protection procurement under ASTM F2921-21 standards shapes North American dense-cargo discrimination requirements. The FAA and TSA coordinate aviation cargo screening protocols with land-border inspection architectures. Texas and Arizona land-border crossings balance mobile deployment against queue management during peak crossing periods.
China
SAMR enforces GB standards for radiation leakage limits at Beijing and Hefei manufacturing facilities, extending export certification timelines. The MIIT prioritizes port modernization at Ningbo and Qingdao through integrated radiation monitoring requirements. Yangtze River Delta terminal operators anchor gantry-mounted fixed system demand for greenfield civil infrastructure.
Germany
The EU F-Gas Regulation constrains cooling system refrigerants for mobile truck-mounted units across Mediterranean deployment conditions. ECHA oversees alternative cooling chemistry qualification under accelerated lifecycle testing. Hamburg port authorities pilot multi-vendor support architectures separating hardware maintenance from algorithm subscriptions.
Netherlands
Rotterdam customs agencies mandate computed tomography integration with automated targeting protocols, accelerating retirement of conventional radiographic systems. The EU Security Screening Regulation drives replacement cycles for legacy fixed-gantry installations. Randstad terminal operators absorb service revenue streams previously captured by maintenance-only contracts.
Singapore
Maritime and Port Authority procurement prioritizes three-dimensional density mapping for high-throughput transshipment screening. The city-state's logistics corridor position creates first-mover installation windows for underpenetrated neighboring terminals. PSA Singapore anchors premium CT system deployment as regional customs agencies harmonize automated threat recognition standards.
Cargo Container X-Ray Inspection Systems Market Competitive Landscape
Technology licensing dominates the current landscape as customs agencies unbundle algorithm procurement from hardware maintenance contracts. The vendor base stratifies between integrated system architects, detector subsystem specialists, and software-centric threat recognition vendors. Three archetypes occupy distinct positions: captive radiation source manufacturers, dual-energy algorithm refiners, and CT reconstruction platform developers. M&A activity concentrates on software assets, while strategic partnerships bridge hardware-software integration gaps.
Within the integrated system tier, Smiths Detection Inc., Nuctech Company Limited, and OSI Systems, Inc. exemplify divergent geographic anchoring and supply chain configurations. Smiths Detection occupies a position tied to British and Dutch port network service revenues. Nuctech represents captive manufacturing of radiation sources and detector panels. OSI Systems sits within the North American land-border specification landscape. These three entities illustrate how procurement geography and regulatory certification timelines fragment competitive positioning across customs jurisdictions.
| Leading Market Players |
|---|
| Smiths Detection Inc. |
| OSI Systems, Inc. |
| Nuctech Company Limited |
| Leidos Holdings, Inc. |
| Rapiscan Systems |
| Astrophysics Inc. |
| L3Harris Technologies, Inc. |
| LINEV Systems |
| Gilardoni S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Major customs procurement programs at Rotterdam, Singapore, and Los Angeles anchor demand concentration for cargo container X-ray inspection systems, driving a contract-based pricing model where algorithm licensing unbundles from hardware maintenance to compress total cost of ownership negotiations.
Pricing Analysis
Service-bundling configurations separate hardware warranty terms from algorithm update subscriptions across the vendor base. Three-tier pricing structure across premium CT systems, standard dual-energy installations, and economy single-energy retrofits reflects certification grade differentiation under ASTM F2921-21 and EU Security Screening Regulation mandates. Cost compression in mid-tier port authorities intensifies as linear accelerator power supply subsystems constitute disproportionate capital expenditure. Budget-constrained land-border agencies in Eastern Europe exhibit highest price sensitivity; Rotterdam and Los Angeles customs agencies prioritize detection accuracy over unit economics.
Supply Chain Analysis
Refurbishment flows for cobalt-60 isotope sources and linear accelerator subsystems create secondary market circulation between Russia, Canada, and China production clusters. Manufacturing concentration in Beijing, Hefei, and German precision engineering hubs draws from detector panel substrates, high-voltage power electronics, and radiation shielding materials. Single-source vulnerability in cobalt-60 isotope supply from Russian and Canadian production facilities threatens portal inspection system availability. Distribution runs through direct government procurement channels and third-party screening service contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cargo container X-ray inspection systems market functions as a cost-of-compliance arena where EU Security Screening Regulation and ASTM F2921-21 certification requirements erect substantial barrier-to-entry moats for vendors lacking established regulatory relationships.
For Market Incumbents: Hedge against algorithm unbundling trends by deepening captive manufacturing positions in radiation sources and detector panels. Secure multi-year service contracts at British and Dutch port networks before third-party software vendors fragment maintenance revenue streams. Vertical integration into Beijing and Hefei production facilities insulates against export certification timeline extension under divergent GB and IEC radiation safety thresholds. For New Entrants and Emerging Players: The price-point gap between premium CT systems at Rotterdam and economy single-energy retrofits at legacy land borders presents white-space opportunity. Target Vietnam's Cai Mep and Thailand's Laem Chabang underpenetrated terminals where container throughput outpaces screening capacity. Pursue algorithm-specialist positioning independent of hardware OEM relationships to capture subscription revenue from Dutch and British customs pilot programs. For Investors and Strategic Acquirers: The window for entry favors software-centric threat recognition vendors with jurisdiction-specific algorithm libraries. Long-term viability hinges on automated threat recognition capability across heterogeneous customs databases rather than hardware manufacturing scale. Monitor divergence between national radiation safety thresholds and emerging automated targeting mandates as inflection signal for R&D allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Unbundling | Separates software subscriptions from hardware maintenance at Rotterdam and Los Angeles customs agencies. |
| CT System Retrofit Acceleration | Absorbs capital allocation from conventional radiographic systems ahead of depreciation schedules. |
| Cobalt-60 Supply Diversification | Mitigates procurement vulnerability from Russian and Canadian isotope production concentration. |
| F-Gas Alternative Qualification | Enables Mediterranean mobile deployment under EU refrigerant phase-out timelines. |
| Multi-Vendor Support Architecture | Fragments traditional single-vendor relationships at Hamburg and Netherlands port authorities. |
Research Methodology
Independent corroboration across port authority procurement officers, customs agency technical directors, and detector subsystem engineering leads underwrites the qualitative findings. Primary interviews with aftermarket service heads, algorithm development specialists, and radiation safety compliance officers combined with secondary validation from EU Security Screening Regulation filings, ASTM standard documentation, and SAMR GB certification records. Bottom-up installation data triangulates against top-down customs agency budget appropriations.
Comparable-period anchoring to historical replacement cycles for gantry-mounted fixed systems and mobile fleet deployments structures the projection horizon. Segmentation modeling spans product architecture, detection technology, threat application, and end-user ownership model dimensions. CAGRs derive from procurement pipeline analysis across the analysis window. Forecast inputs incorporate civil infrastructure investment timelines at Ningbo and Qingdao and F-Gas refrigerant phase-out schedules.
Inputs from Rotterdam, Singapore, and Los Angeles customs agencies were available through the study window; gaps in real-time algorithm retraining cost data introduce uncertainty bands. Forecasts reflect documented assumptions regarding EU Security Screening Regulation implementation pace and cobalt-60 isotope supply continuity. Practitioners should monitor GB standard divergence from IEC thresholds and automated threat recognition mandate harmonization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Security Policy Management Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Prison Management Systems Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
Home Security Sensors Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Private Security Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Global Physical Security Software Market