
 Global School and Campus Security Market | 2026-2036
Global School and Campus Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global School and Campus Security Market Outlook
Subscription-based managed security services and equipment leasing is reconfiguring capital deployment for cash-constrained school districts, allowing upfront-light procurement of integrated video and access platforms. Honeywell International Inc. leverages its building automation heritage to bundle HVAC, fire safety, and intrusion detection into unified campus contracts. Johnson Controls International plc anchors its position through deep integration of smart lock technology with existing building management infrastructure. Bosch Security Systems differentiates via European manufacturing scale and hardened edge-device portfolios purpose-built for outdoor campus perimeters.
School and campus security encompasses integrated physical protection systems—combining networked surveillance, credential-based access control, mass notification, and intrusion detection—designed to monitor, restrict, and respond to threats across educational facilities. These systems typically operate on IP-based architectures with centralized command interfaces, processing real-time video feeds and sensor data to trigger automated lockdowns or alert first responders. Surveillance cameras and video analytics represent the largest installed base, though cloud-based solutions are expanding fastest as districts seek remote manageability and reduced on-site server maintenance. Access control systems command premium margins where biometric authentication replaces legacy card readers, particularly in university research facilities and administrative buildings housing sensitive records.
FDA guidelines on emergency preparedness for educational institutions, alongside FCC regulations governing broadband-enabled safety communications, shape product certification requirements and procurement eligibility for US vendors. E.U. GDPR and the EU AI Act impose data governance constraints on facial recognition and behavioral analytics deployed in European campuses, compelling vendors to architect privacy-by-design features. Stakeholders must weigh interoperability standards against jurisdictional compliance as biometric and AI-driven technologies penetrate deeper into student-facing environments.
Market Dynamics
Cloud-native architectures are compressing capital cycles for K-12 districts and universities, converting multi-year server refresh programs into monthly SaaS expenditures that bypass municipal bond financing constraints.
Growth Catalysts
- State-Level Safety Mandates:Campus safety audit requirements in Texas, Florida, and California compel districts to deploy integrated video and access platforms. Federal grants flow through state education departments to fund facility hardening.
- Biometric Authentication:University research facilities and administrative buildings housing sensitive records drive replacement of legacy card readers. Fingerprint and facial recognition systems command premium margins in these high-security zones.
- Mass Notification Modernization:FCC regulations governing broadband-enabled emergency communications push districts to upgrade legacy analog PA systems. IP-based alert networks integrate with mobile applications and digital signage.
Market Restraints
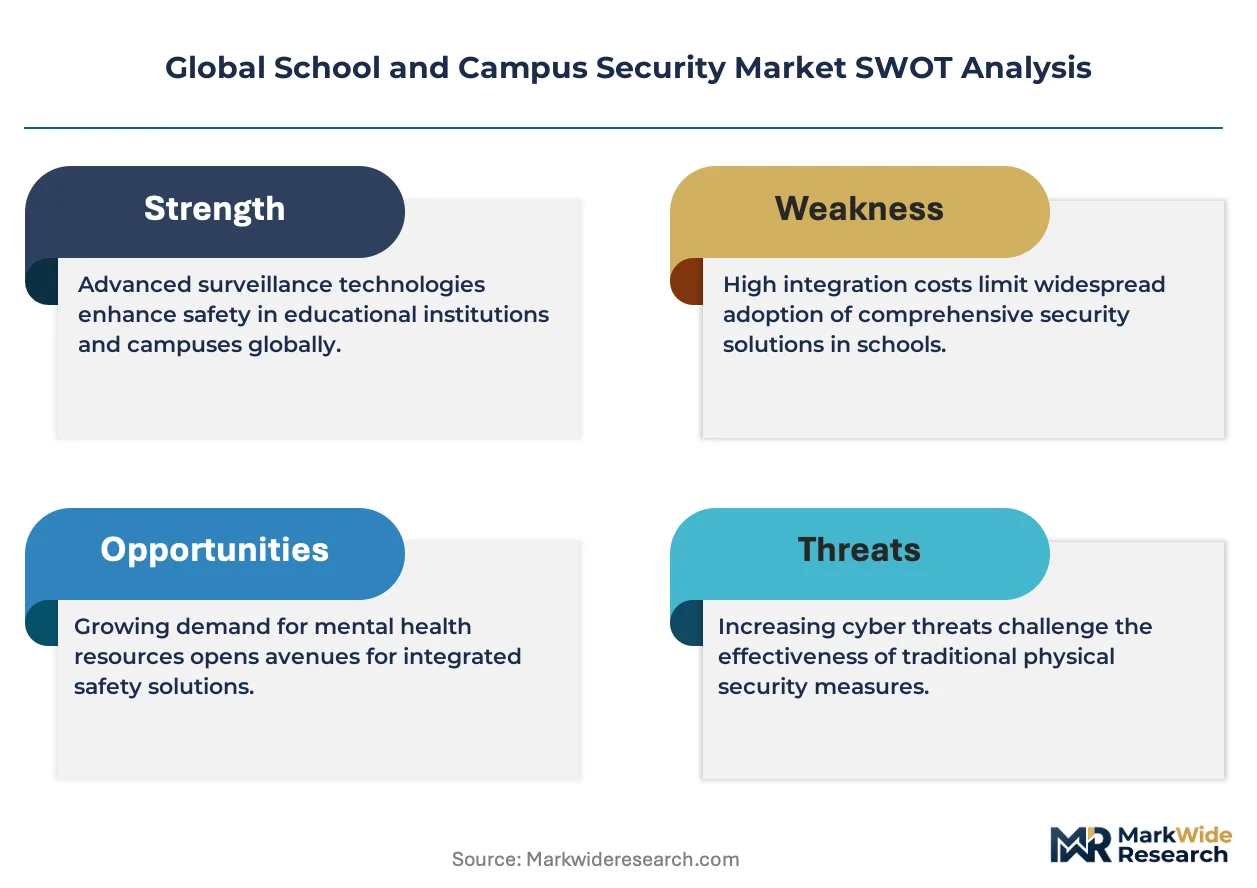
- GDPR and EU AI Act Constraints:European data governance rules impose privacy-by-design requirements on facial recognition and behavioral analytics. Vendors must architect anonymization features that increase development costs.
- Semiconductor Supply Concentration:Edge-device chip fabrication concentrates in Taiwan and South Korea. Geopolitical friction creates procurement lead-time volatility for camera SoCs and access control processors.
- Legacy System Entrenchment:On-premise DVR infrastructure from 2010-2015 refresh cycles remains operational in budget-constrained rural districts. Technical debt delays full IP migration.
Strategic Opportunities
- Subscription Managed Services:Cash-constrained districts seek upfront-light procurement through equipment leasing and managed security service contracts. Remote monitoring reduces on-site IT staffing requirements.
- Outdoor Perimeter Hardening:Edge-device portfolios purpose-built for exterior campus boundaries address intrusion detection gaps. Thermal imaging and radar augmentation expand addressable coverage.
- India EdTech Infrastructure:Private K-12 chains and university campuses in Mumbai, Bangalore, and Delhi invest in integrated security as competitive differentiation. Central government smart city funding channels into educational zone hardening.
Industry Challenges
- Cyber-Physical Integration Complexity:IT security teams and facilities management operate with misaligned KPIs. Converged command centers require cross-functional training that most districts lack budget to implement.
- Interoperability Certification Delays:ONVIF and PSIA standards evolve faster than vendor compliance testing. Procurement officers face specification ambiguity when evaluating multi-vendor integration claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global School and Campus Security Market |
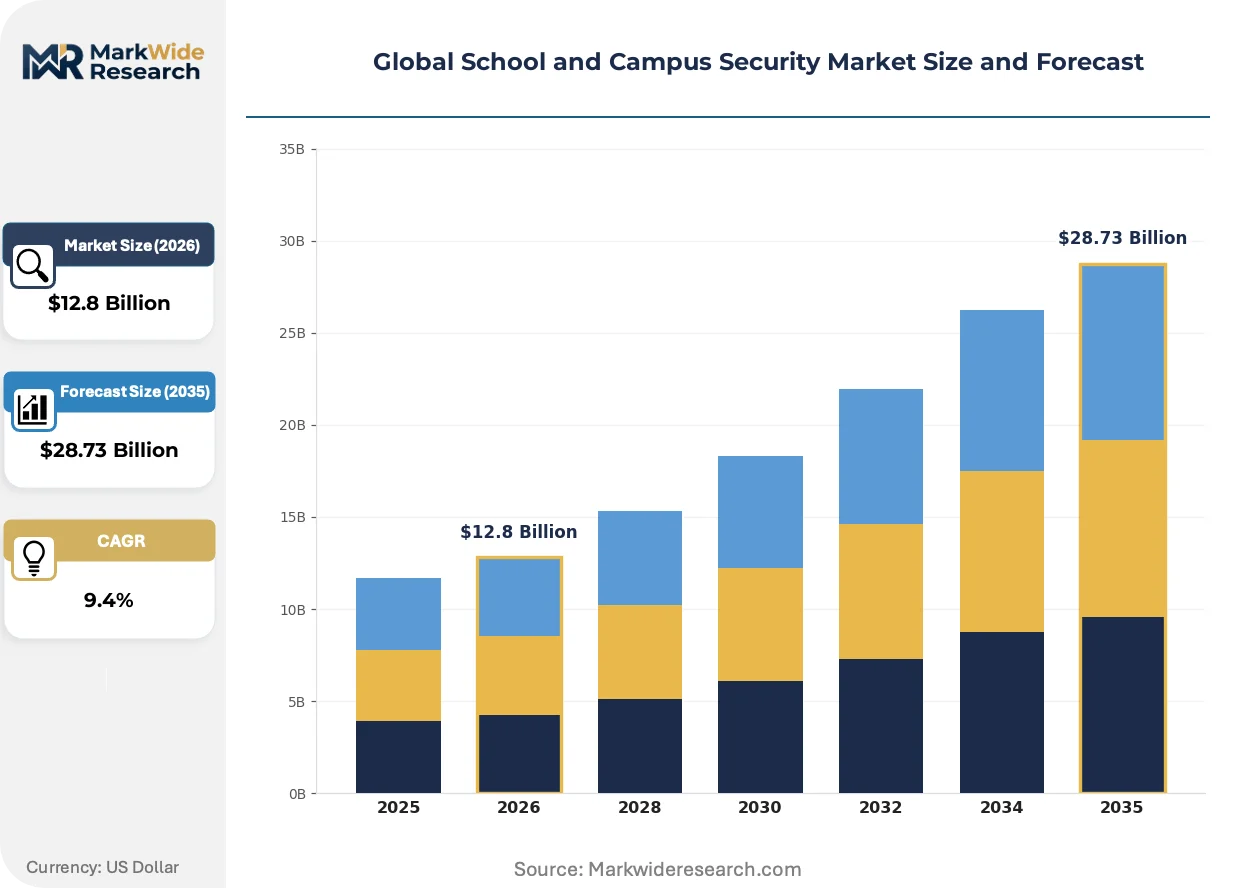
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Cameras, Alarm Systems, Emergency Notification Systems End User: Colleges, High Schools, Elementary Schools, Universities Service Type: Consulting Services, Installation Services, Managed Services, Maintenance Services Technology: Biometric Systems, Video Analytics, Smart Lock Technology, Cloud-Based Solutions |
| Companies Covered | Honeywell International Inc., Johnson Controls International plc, Bosch Security Systems, Axis Communications AB, Hikvision Digital Technology Co., Ltd., Genetec Inc., Cisco Systems, Inc., ADT Inc., Motorola Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global School and Campus Security Market Strategic Shifts
Video management infrastructure is shedding hardware dependencies, with processing and storage migrating to distributed cloud nodes that enable centralized oversight across dispersed campus portfolios.
Serverless video analytics is virtualizing the traditional VMS architecture. K-12 districts with limited IT staff adopt browser-based command interfaces that eliminate on-premise server maintenance. This compression of infrastructure requirements allows smaller rural systems to deploy capabilities previously restricted to university-scale budgets.
The EU AI Act imposes risk-classification requirements on biometric identification systems deployed in educational environments. Vendors serving European campuses must document algorithmic impact assessments and maintain human-in-the-loop review protocols. German and French universities now prioritize privacy-preserving alternatives such as on-device template matching over centralized facial databases.
District procurement officers increasingly unbundle hardware acquisition from installation and long-term service contracts. Texas and Florida K-12 systems favor three-to-five-year managed service agreements with refresh guarantees over capital purchases. This consumption-pattern shift rewards vendors with regional service technician networks and compresses margins for equipment-only suppliers.
Global School and Campus Security Market Segmentation

Segmentation in school and campus security reveals divergent procurement patterns between capital-constrained K-12 systems and research-intensive universities. Service intensity, technology maturity, and compliance exposure vary dramatically across product categories, reshaping vendor go-to-market strategies.
Product Type:
After-sales service intensity separates winners from commodity suppliers across hardware categories, with multi-year maintenance contracts often exceeding initial equipment value.
- Surveillance Cameras:IP-based cameras with edge analytics processing dominate new installations. Texas and Florida K-12 districts drive replacement of analog CCTV following state safety audit mandates, with cloud-managed camera networks reducing on-site IT staffing burdens.
- Access Control Systems:Credential-based entry management spans card readers, biometric terminals, and mobile-enabled locks. University research facilities in California and New York command premium biometric authentication for sensitive record repositories, replacing legacy magnetic stripe systems.
- Alarm Systems:Intrusion detection sensors and perimeter monitoring equipment address exterior campus boundaries.
- Emergency Notification Systems:Mass alert platforms integrate IP-based PA, digital signage, and mobile push notifications for lockdown coordination.
By volume, Surveillance Cameras leads. By growth pace, Access Control Systems is ahead.
End User:
Cost tier stratification creates distinct buying centers, from municipal bond-financed university capital projects to operating-budget-constrained elementary school principals.
- Universities:Multi-campus research institutions deploy integrated command centers combining video analytics, biometric access, and mass notification. Federal research grants and endowment returns fund facility hardening at selective private institutions in Massachusetts and Pennsylvania.
- Colleges:Two-year and community college systems prioritize scalable cloud architectures with minimal on-premise infrastructure. State funding formulas in Ohio and Illinois channel resources toward visible security investments that influence enrollment decisions.
- High Schools:Secondary campuses balance athletic event security with daily access control for 1,000-plus student populations.
- Elementary Schools:Younger student populations drive demand for non-threatening visible deterrence and rapid lockdown protocols.
By enrollment coverage, High Schools leads. By spending per student, Universities is ahead.
Service Type:
Volume concentration favors regional installation networks, while margin capture shifts toward recurring managed services with remote monitoring capabilities.
- Managed Services:Subscription-based remote monitoring and system administration converts capital expenditure to operating budgets. Rural districts in Georgia and Arizona adopt three-to-five-year service contracts with equipment refresh guarantees, bypassing municipal bond issuance delays.
- Maintenance Services:Preventive maintenance and break-fix support for surveillance, access control, and alarm hardware. University facilities departments in Michigan and Washington negotiate multi-year service level agreements to ensure uptime for critical research facility access systems.
- Installation Services:Physical deployment, cabling, and commissioning of security infrastructure.
- Consulting Services:Risk assessment, system design, and compliance audit preparation.
By contract value, Managed Services leads. By transaction frequency, Maintenance Services is ahead.
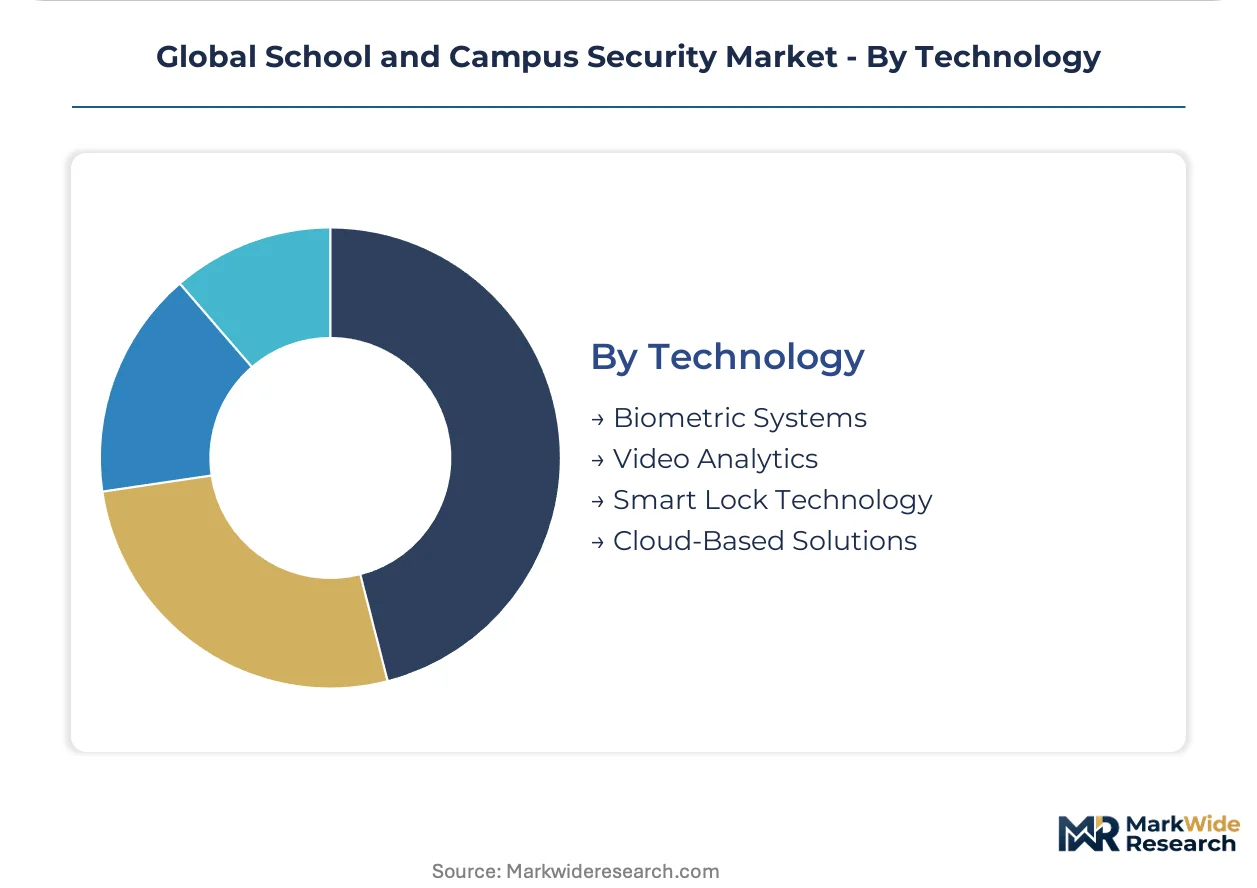
Technology:
Application maturity varies sharply, with biometric deployments facing GDPR and EU AI Act constraints while cloud architectures accelerate in North American markets.
- Cloud-Based Solutions:Browser-based command interfaces and distributed storage eliminate on-premise server dependencies. K-12 districts in Colorado and Utah with limited IT staff deploy capabilities previously restricted to university-scale budgets through serverless video management.
- Video Analytics:AI-driven behavioral detection and automated alert generation for intrusion, crowd formation, and abandoned object identification. German and French universities prioritize on-device template matching over centralized facial databases to satisfy privacy-by-design requirements.
- Biometric Systems:Fingerprint, facial recognition, and iris-based authentication for high-security zones.
- Smart Lock Technology:Networked electronic locks with mobile credentialing and audit trail capabilities.
By deployment velocity, Cloud-Based Solutions leads. By margin expansion, Video Analytics is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in security systems integration services while importing specialized camera sensors and biometric processors from Asian fabrication centers. Germany and France export privacy-compliant analytics software architectures. China and India represent net importers of campus security infrastructure, though domestic assembly capacity is expanding rapidly.
United States
Federal grants through state education departments fund facility hardening across Texas, Florida, and California K-12 districts. FCC regulations governing broadband-enabled emergency communications mandate IP-based mass notification upgrades. Dallas-Fort Worth and Houston metropolitan clusters concentrate regional installation contractor networks serving school district procurement cycles.
Germany
University research facilities in Bavaria and Baden-Württemberg drive demand for GDPR-compliant biometric authentication systems. The EU AI Act imposes risk-classification requirements on facial recognition deployments in educational environments. Munich and Stuttgart industrial corridors host edge-device manufacturers architecting privacy-by-design features for European campus markets.
China
Private K-12 chains in Beijing, Shanghai, and Shenzhen invest in integrated security as competitive differentiation for affluent parent demographics. MIIT standards govern network security certifications for cloud-based surveillance platforms. Yangtze River Delta manufacturing clusters produce camera system-on-chips and access control processors for domestic and export markets.
India
Central government smart city funding channels into educational zone hardening across Mumbai, Bangalore, and Delhi private campuses. BIS certification requirements shape procurement eligibility for surveillance and access control vendors. Karnataka and Maharashtra state education departments pilot integrated command center deployments in flagship public universities.
United Kingdom
University endowment-funded facility hardening concentrates in the Oxford-Cambridge-London research triangle. UK GDPR enforcement through the Information Commissioner's Office constrains behavioral analytics deployment in student-facing environments. Greater Manchester and West Midlands secondary schools prioritize visible deterrence systems following regional safety audit mandates.
Global School and Campus Security Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sensors, processors, and edge devices. The vendor base organizes around three strategic archetypes: building automation conglomerates bundling HVAC and fire safety with security, pure-play video surveillance manufacturers, and cloud-native software vendors displacing on-premise architectures. Dominant competitive moves include vertical integration into subscription managed services and geographic expansion through regional installation network acquisitions.
Within the building automation tier, Honeywell International Inc. and Johnson Controls International plc exemplify conglomerate positioning that leverages legacy infrastructure relationships. Bosch Security Systems anchors European manufacturing scale for hardened outdoor perimeter equipment. Among cloud-native specialists, Genetec Inc. and Axis Communications AB occupy positions in browser-based command interfaces and distributed storage architectures. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International plc |
| Bosch Security Systems |
| Axis Communications AB |
| Hikvision Digital Technology Co., Ltd. |
| Genetec Inc. |
| Cisco Systems, Inc. |
| ADT Inc. |
| Motorola Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on camera system-on-chips fabricated in Taiwan and South Korea compresses margin spreads between economy-tier analog replacements and premium biometric-integrated platforms while forcing K-12 districts toward longer procurement cycles. This single-source dependency for edge-device processors simultaneously widens pricing tiers and reshapes supplier financing terms across the vendor base.
Pricing Analysis
University facilities directors anchor a three-tier pricing structure across premium, standard, and economy levels, with biometric authentication systems commanding substantial premiums over card-reader baselines due to GDPR compliance certification and after-sales service bundling. Cost compression in the economy tier intensifies because rural districts delay IP migration and extend legacy DVR refresh timelines. Elementary school principals exhibit highest price sensitivity, constrained by operating budgets and municipal bond issuance delays, while research-intensive universities demonstrate lowest sensitivity given endowment-funded capital projects.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize procurement relationships as vendors absorb working capital pressure from semiconductor supply concentration in Taiwan, South Korea, and China. Camera SoCs, access control processors, and thermal imaging sensors draw from these fabrication centers, with geopolitical friction creating single-source vulnerability for edge-device components. Distribution runs through regional installation contractor networks concentrated in Texas, Florida, and California metropolitan clusters, bypassing traditional equipment-only suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The school and campus security market sits at a platform-economics inflection where ONVIF and PSIA interoperability standards are displacing proprietary lock-in, rewarding vendors with open-architecture cloud-native stacks over legacy on-premise incumbents.
For Market Incumbents: Pre-empt cloud-native challengers by acquiring regional managed service providers with established technician networks in Texas and Florida K-12 districts. Consolidate backward integration into edge-device manufacturing to reduce exposure to Taiwan semiconductor lead-time volatility. Prioritize GDPR and EU AI Act certification investment to defend European university research facility positions against privacy-by-design specialists.
For New Entrants and Emerging Players: Mid-market community college systems in Ohio and Illinois represent the most penetrable entry point given state funding formulas channeling resources toward visible security investments. Rural districts in Georgia and Arizona seeking three-to-five-year managed service contracts with equipment refresh guarantees offer second-wave expansion. Deploy browser-based serverless video management as the primary go-to-market wedge against legacy VMS incumbents.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors subscription-revenue archetypes with regional service density over equipment-only suppliers. Long-term viability across the analysis window hinges on recurring managed services margin capture rather than transactional hardware sales. Monitor state-level safety mandate expansion beyond Texas, Florida, and California as the primary inflection indicator for addressable market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Regional Service Networks | Builds technician density in Texas and Florida procurement cycles. |
| Cloud-Native Platform Migration | Eliminates on-premise server dependencies for rural district penetration. |
| GDPR Compliance Certification | Unlocks Bavaria and Baden-Württemberg university research facility contracts. |
| Biometric Authentication Integration | Captures premium margins in California and New York sensitive record repositories. |
| Managed Services Contract Expansion | Converts municipal bond-constrained K-12 capital expenditure to operating budgets. |
Study Parameters
Desk research of FCC regulatory filings, state education department procurement databases, and vendor SEC disclosures preceded structured interviews with K-12 district facilities directors, university campus security chiefs, and regional installation contractor principals. Primary fieldwork with cloud-native software vendors and building automation conglomerates validated secondary intelligence on subscription pricing migration. Bottom-up district-level procurement tracking and top-down vendor revenue analysis were triangulated to establish market sizing.
Assumptions held fixed across the projection horizon include continued federal grant flow through state education departments and sustained Taiwan semiconductor fabrication capacity. The analytical framework modeled deployment architecture, end-user institution type, service contract structure, and regional regulatory cluster as segmentation dimensions. CAGRs were derived from installed base replacement curves and new-build penetration rates, with cloud adoption velocity and biometric authentication replacement timelines as critical forecast inputs.
Practitioners should monitor state-level safety mandate adoption beyond Texas, Florida, and California, EU AI Act enforcement intensity, and Taiwan Strait geopolitical friction for early signals of forecast deviation. Macroeconomic contraction affecting municipal bond issuance, regulatory restriction on facial recognition in educational environments, or semiconductor supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Home Security Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
Air Cargo Screening Systems Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
Europe Baggage and Parcel Screening Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Sirens Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Europe Urban Security Screening Market
Security and Surveillance
Global Integration Security Services Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Destructible Security Labels Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Security Product Integration Services Market