
 Food Grade Stearic Acid Market | 2026-2036
Food Grade Stearic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Stearic Acid Market Foresight
Direct procurement from oleochemical refineries is tilting toward integrated palm oil processors in Southeast Asia. BASF SE leverages backward integration into renewable feedstock refining to secure supply continuity. Wilmar International Ltd. dominates plantation-to-derivative logistics across Indonesian and Malaysian operations. KLK OLEO sustains flake and powder output through vertical control over Malaysian palm kernel supply chains.
Food grade stearic acid is a saturated fatty acid with an eighteen-carbon chain, typically derived from vegetable oils through hydrolysis and hydrogenation, meeting purity thresholds above ninety percent for food contact applications. It functions primarily as a lubricant, emulsifier, and release agent in processed food matrices. Powder and flake formats lead volume due to handling efficiency in industrial bakery and confectionery settings, while granular grades command margin pools from pharmaceutical manufacturers seeking flow-control properties. Dairy and snack applications show structural expansion as clean-label emulsifier demand redirects procurement from synthetic alternatives.
EFSA, FDA, and BIS frameworks govern maximum iodine values and heavy metal limits, with EFSA's updated fatty acid purity protocols reshaping European import specifications. FDA food additive regulations under CFR 172.860 maintain access thresholds that Malaysian and Indonesian exporters must certify against. Stakeholders must monitor feedstock sustainability certification requirements from EU Deforestation Regulation enforcement and evolving BIS standards for Indian pharmaceutical-grade imports.
Market Dynamics
EFSA's updated fatty acid purity protocols are compressing import windows for Southeast Asian exporters while simultaneously redirecting procurement toward vertically integrated plantation operators with captive hydrogenation capacity.
Growth Catalysts
- Clean-label emulsifier mandates:European bakery and confectionery formulators are substituting synthetic alternatives with vegetable-derived stearic acid to meet EFSA guidance on additive transparency.
- India:FSSAI enforcement of refined vegetable fat standards in processed dairy is expanding addressable volume for pharmaceutical-grade flake imports.
- Fractionation technology advancement:Membrane-based separation systems are improving C18:0 yield rates from palm kernel oil, reducing hydrogenation intensity and energy input per ton.
Market Restraints
- Crude palm oil price volatility:Malaysian benchmark futures transmit directly to stearic acid contract pricing, compressing blender margins during feedstock spikes.
- Geographic supply concentration:Indonesian and Malaysian refineries control over seventy percent of exportable food-grade flake and powder, creating single-source vulnerability for European compounders.
- Iodine value technical floor:Partial hydrogenation limits achievable saturation levels without trans-fat generation, constraining applications requiring ultra-low unsaturation.
Strategic Opportunities
- Brazil:ANVISA's harmonization with Codex Alimentarius standards is opening import pathways previously blocked by non-tariff technical barriers.
- Cell-cultured fat convergence:Precision fermentation-derived stearic acid is approaching cost parity for pharmaceutical applications requiring chain-of-custody documentation.
- EU Deforestation Regulation:Mandatory geolocation traceability is creating first-mover advantage for plantation groups with blockchain-verified supply chain mapping.
Industry Challenges
- Specialized hydrogenation engineering talent:Catalytic process optimization requires expertise in nickel catalyst management that remains concentrated among retiring cohorts in European oleochemical hubs.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EFSA, and BIS registration for pharmaceutical-grade granular output extends commercialization cycles by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Stearic Acid Market |
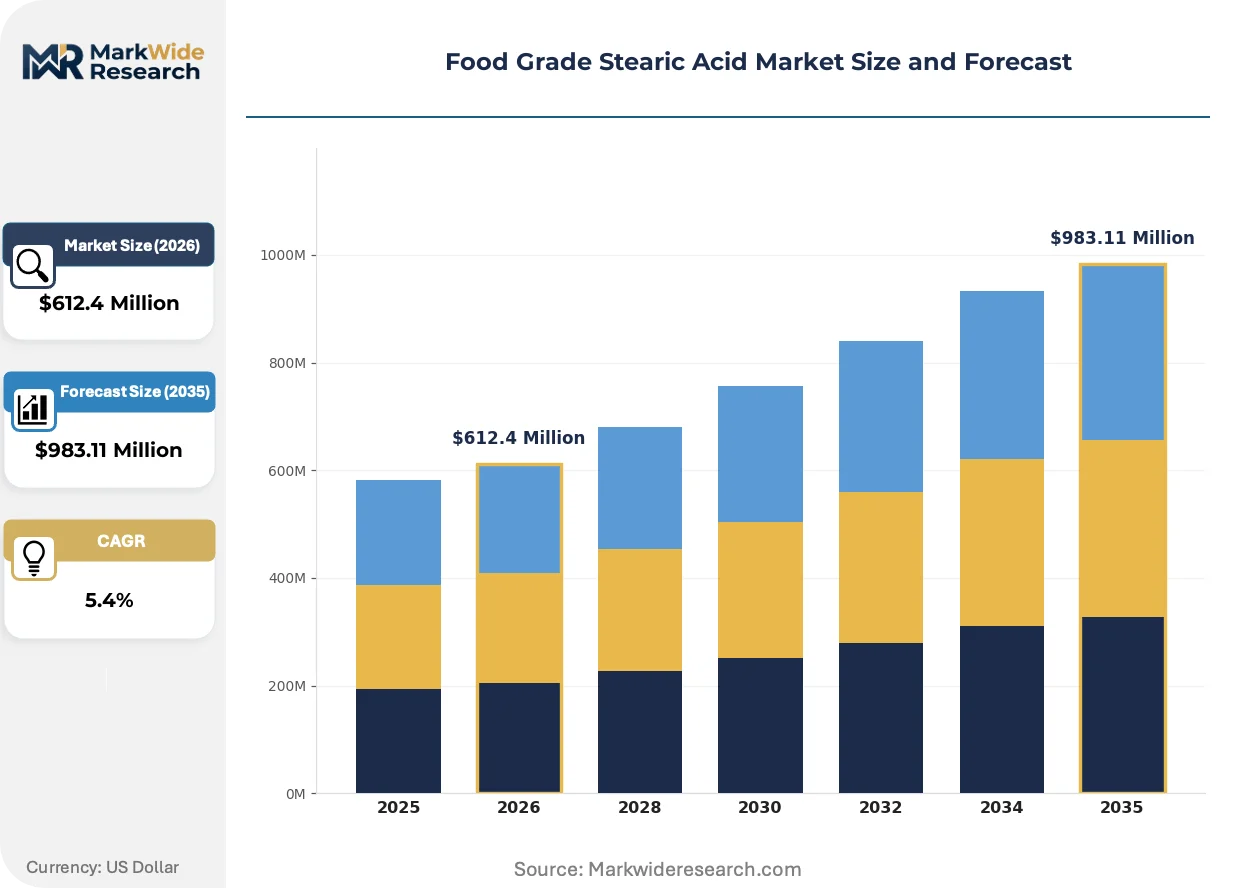
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $983.11 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flake, Granular, Block Application: Baking Ingredients, Confectionery, Dairy Products, Snacks, Cosmetics, Pharmaceuticals End User: Food Processing Units, Pharmaceutical Manufacturers, Personal Care Producers, Nutraceutical Companies Packaging Type: Paper Bags, Plastic Bags, Fiber Drums, Bulk Containers |
| Companies Covered | BASF SE, Wilmar International Ltd., Emery Oleochemicals Group, Kao Corporation, Godrej Industries Ltd., Pacific Oleochemicals Sdn Bhd, KLK OLEO, IOI Oleochemical, Oleon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Stearic Acid Market Shifts & Advancements
Digital traceability infrastructure is displacing paper-based chain-of-custody systems across Southeast Asian export corridors. Three concurrent developments are compressing traditional procurement patterns.
Blockchain-enabled batch tracking is digitizing plantation-to-destination verification for EU Deforestation Regulation compliance. German and Dutch importers are mandating real-time geolocation data for shipments exceeding fifty metric tons. This technology is compressing audit timelines from weeks to hours while excluding non-compliant intermediaries from qualified supplier lists.
REACH Annex XVII restrictions on persistent organic pollutants are tightening heavy metal thresholds for fatty acid derivatives used in food contact materials. The regulation is forcing hydrogenation facilities to retrofit filtration systems or exit pharmaceutical-grade segments. Belgian and French compounders are consolidating procurement toward refineries with dedicated food-grade production lines.
Direct contracting between plantation groups and European bakery chains is fragmenting traditional distributor networks. Large industrial confectioners in Germany and Italy are negotiating multi-year offtake agreements that bypass regional chemical distributors. This pattern is most visible in northern Italy's industrial bread and pastry manufacturing cluster, where volume buyers seek margin capture through elimination of intermediaries.
Food Grade Stearic Acid Market Segmentation
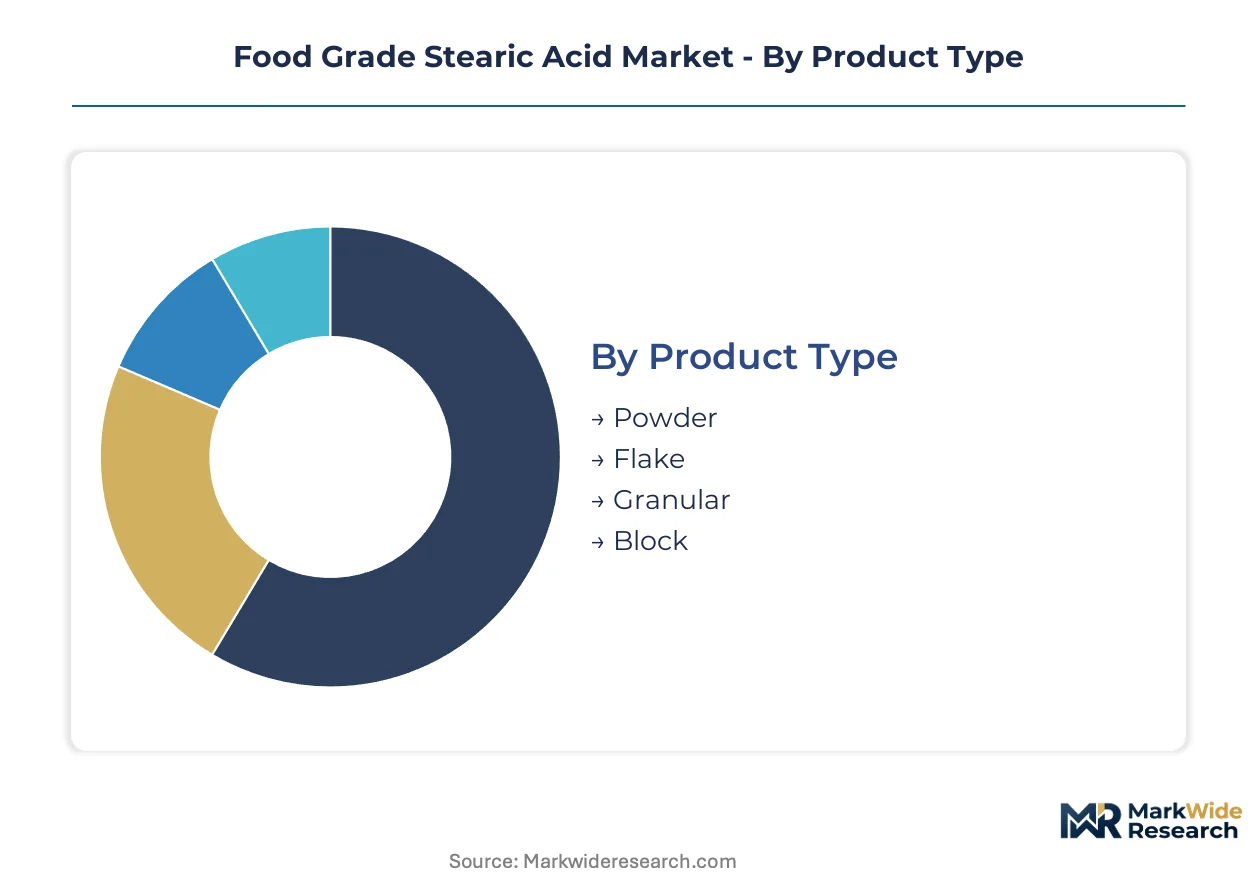
Segmentation in food grade stearic acid procurement reflects divergent handling requirements, purity thresholds, and supply chain security needs across industrial buyers. Manufacturers configure production lines around specific physical formats while end-use applications dictate certification grades and packaging protocols.
Product Type:
Mature formats dominate current procurement volumes while emerging specifications gain traction in pharmaceutical and clean-label segments.
- Powder:Fine-ground particles below 100 mesh enable rapid dispersion in industrial bakery dough conditioners and confectionery coatings. European compounders in Germany and Italy specify powder grades for automated metering systems in high-throughput bread manufacturing.
- Flake:Thin compressed sheets dissolve gradually in heated fat matrices, making them preferred for dairy fat replacers and snack seasoning adhesion. Malaysian refineries ship flake grades in 25-kilogram multiwall bags to Indian processed cheese manufacturers seeking FSSAI-compliant emulsifier inputs.
- Granular:Uniform bead structure supports precise dosing in pharmaceutical tablet pressing and flow-control applications. CDSCO-registered Indian pharmaceutical manufacturers import granular grades for excipient formulations requiring documented chain-of-custody.
- Block:Solid molded forms serve artisanal confectioners and small-batch food processors with manual cutting operations. Limited volume concentrates in specialty chocolate tempering applications across France and Belgium.
Powder retains volume leadership; granular holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity food processing from premium pharmaceutical and personal care segments demanding elevated purity documentation.
- Baking Ingredients:Dough conditioners and crumb softeners in industrial bread production consume powder and flake formats. German wholesale bakeries specify vegetable-derived stearic acid to meet EFSA clean-label guidance on additive transparency.
- Confectionery:Chocolate tempering agents and glazing compounds require precise melting point control. Italian industrial pastry manufacturers negotiate direct offtake agreements with Indonesian plantation groups to bypass distributor markups.
- Dairy Products:Processed cheese emulsifiers and whipped topping stabilizers drive flake demand. FSSAI enforcement of refined vegetable fat standards in India expands addressable volume for pharmaceutical-grade imports.
- Snacks:Seasoning adhesion and anti-caking functions in extruded products favor cost-optimized powder grades. Southeast Asian snack processors source from Malaysian integrated refineries with captive hydrogenation capacity.
- Cosmetics:Emollient and thickening applications in skincare formulations require cosmetic-grade certification. REACH Annex XVII heavy metal restrictions force compounders toward dedicated food-grade production lines.
- Pharmaceuticals:Tablet lubricants and sustained-release matrix binders demand granular formats with full regulatory documentation. Simultaneous FDA, EFSA, and BIS registration extends commercialization cycles for new suppliers.
Baking ingredients command the largest procurement volumes; pharmaceuticals generate the highest margin pools.
End User:
Customer type determines contract structure, with multinational food processors leveraging volume scale against pharmaceutical buyers prioritizing supply security.
- Food Processing Units:Industrial bakeries, confectionery manufacturers, and dairy processors constitute the core demand base. Direct contracting between plantation groups and European bakery chains is fragmenting traditional distributor networks.
- Pharmaceutical Manufacturers:Tablet and capsule producers require granular grades with comprehensive regulatory dossiers. Belgian and French compounders consolidate procurement toward refineries with dedicated pharmaceutical-grade production lines.
- Personal Care Producers:Skincare and cosmetic formulators specify cosmetic-grade stearic acid for emollient applications. ECHA restrictions on persistent organic pollutants tighten heavy metal thresholds for fatty acid derivatives.
- Nutraceutical Companies:Dietary supplement encapsulation and coating applications represent a developing segment. ANVISA harmonization with Codex Alimentarius standards in Brazil opens import pathways previously blocked by technical barriers.
Food processing units absorb the majority of tonnage; pharmaceutical manufacturers impose the most stringent qualification requirements.
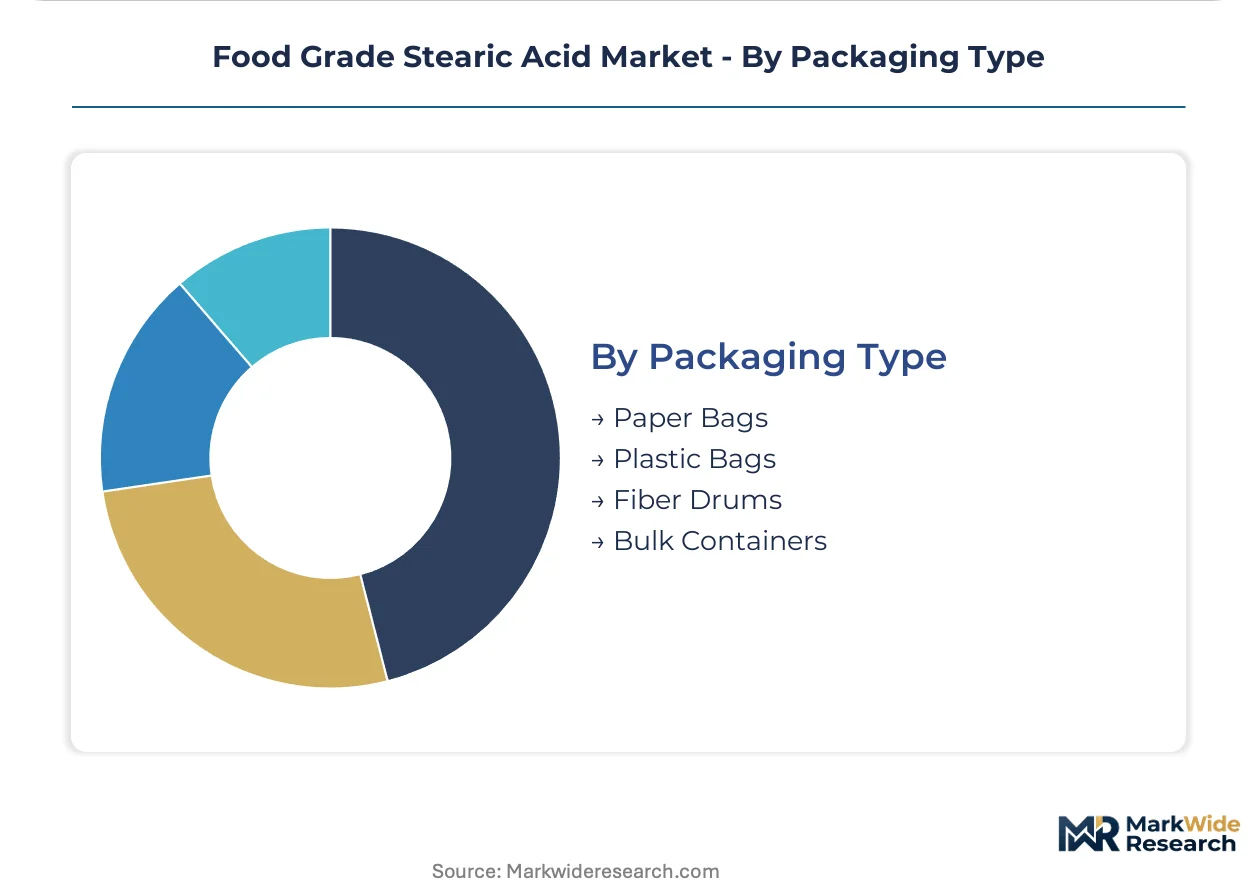
Packaging Type:
Supply chain configuration determines packaging selection, with bulk formats favored by integrated processors and unitized packaging serving fragmented downstream distribution.
- Paper Bags:Multiwall kraft constructions with polyethylene liners protect powder and flake from moisture during ocean freight. Standard 25-kilogram units dominate European import specifications.
- Plastic Bags:Heat-sealed polyethylene provides superior barrier properties for humid climates. Indonesian exporters specify plastic primary containment for shipments to Indian subcontinent ports.
- Fiber Drums:Rigid cylindrical containers with steel chimes protect granular grades from compression damage. Pharmaceutical manufacturers mandate fiber drum packaging for cleanroom transfer protocols.
- Bulk Containers:Flexible intermediate bulk containers and ISO tank deliveries serve high-volume compounders with dedicated receiving infrastructure. Northern Italy's industrial bread cluster receives bulk flake via dedicated tanker truck arrangements.
Paper bags retain procurement preference; bulk containers are climbing fastest as direct plantation-to-processor contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's updated fatty acid purity protocols anchor European import specifications, while FDA and FSSAI frameworks govern parallel certification requirements in the United States and India. Malaysian and Indonesian refineries control the majority of exportable food-grade flake and powder, creating geographic supply concentration that shapes procurement patterns across destination markets.
United States
Industrial bakeries and confectionery manufacturers drive powder and flake consumption for dough conditioning and chocolate tempering applications. FDA food additive regulations under CFR 172.860 maintain access thresholds that Malaysian and Indonesian exporters must certify against. Chicago and Minneapolis anchor Midwestern bread manufacturing clusters where clean-label emulsifier mandates redirect procurement from synthetic alternatives.
Germany
EFSA guidance on additive transparency propels vegetable-derived stearic acid substitution for synthetic emulsifiers in industrial bakery formulations. REACH Annex XVII restrictions on persistent organic pollutants tighten heavy metal thresholds for fatty acid derivatives used in food contact materials. Northern Germany's wholesale bakery networks negotiate direct offtake agreements with plantation groups to bypass distributor markups.
India
FSSAI enforcement of refined vegetable fat standards in processed dairy expands addressable volume for pharmaceutical-grade flake imports. CDSCO registration requirements govern pharmaceutical applications requiring documented chain-of-custody. Mumbai and Ahmedabad concentrate dairy processing capacity where snack seasoning adhesion applications favor cost-optimized powder grades from Malaysian integrated refineries.
Indonesia
Integrated palm oil processors leverage plantation-to-derivative logistics across Sumatran and Kalimantan operations to secure supply continuity. EU Deforestation Regulation enforcement mandates geolocation traceability that favors plantation groups with blockchain-verified supply chain mapping. Surabaya and Medan host hydrogenation facilities that ship flake grades in polyethylene-lined containers to Indian subcontinent ports.
Italy
Industrial pastry manufacturers in the Lombardy and Veneto regions negotiate multi-year offtake agreements that fragment traditional distributor networks. EFSA's updated purity protocols compress import windows while redirecting procurement toward vertically integrated operators with captive hydrogenation capacity. Milan's industrial bread cluster receives bulk flake via dedicated tanker truck arrangements that eliminate intermediary margins.
Food Grade Stearic Acid Market Competitive Landscape
Integrated plantation operators and independent oleochemical refiners split the market between captive supply security and merchant trading flexibility. Malaysian and Indonesian groups dominate upstream feedstock control, while European and Japanese players concentrate on downstream formulation and pharmaceutical-grade certification. Three archetypes define competitive positioning: plantation-integrated refiners with backward integration into renewable feedstock, merchant hydrogenation specialists serving spot markets, and pharmaceutical-grade compounders with dedicated production lines. Capacity expansion in membrane-based fractionation and strategic partnerships for blockchain traceability represent the dominant competitive moves.
Among plantation-integrated operators, Wilmar International Ltd. and KLK OLEO exemplify the archetype of upstream-controlled supply chains, while BASF SE occupies a position bridging European formulation expertise with renewable feedstock refining. These three companies represent contrasting geographic origins and corporate structures: Wilmar International Ltd. operates as a Singapore-listed agribusiness group, KLK OLEO functions as a Malaysian public limited company with vertical control over palm kernel supply chains, and BASF SE stands as a German societas Europaea with backward integration into oleochemical production.
| Leading Market Players |
|---|
| BASF SE |
| Wilmar International Ltd. |
| Emery Oleochemicals Group |
| Kao Corporation |
| Godrej Industries Ltd. |
| Pacific Oleochemicals Sdn Bhd |
| KLK OLEO |
| IOI Oleochemical |
| Oleon |
| Others |
Supply & Pricing Matrix
Malaysian and Indonesian plantation groups control over seventy percent of exportable food-grade flake and powder, concentrating margin capture upstream while European compounders face compressed blender margins during feedstock spikes. This supply architecture positions integrated refiners with captive hydrogenation capacity to dictate contract terms, leaving merchant buyers exposed to crude palm oil futures volatility transmitted directly into stearic acid pricing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between plantation groups and large industrial confectioners, creating geographic price spreads that favor direct buyers in Germany and Italy over spot-market purchasers. Pricing stratifies across pharmaceutical-grade granular, food-grade flake, and cost-optimized powder tiers, with certification level and volume scale as primary differentiation drivers. Cost compression in standard-grade powder runs through Malaysian benchmark futures exposure, while pharmaceutical manufacturers show least price sensitivity due to regulatory qualification requirements. Snack processors in India demonstrate highest price sensitivity, sourcing cost-optimized grades from integrated refineries.
Supply Chain Analysis
Wilmar International Ltd., KLK OLEO, and IOI Oleochemical hold concentrated hydrogenation and fractionation capacity across Sumatran and Kalimantan operations. Supply chains draw from palm kernel oil, nickel catalyst inputs, and polyethylene packaging materials, with membrane-based separation systems reducing energy intensity per ton. Single-source vulnerability from Indonesian and Malaysian refinery concentration creates structural risk for European compounders lacking qualified alternative suppliers. Distribution runs through direct tanker truck arrangements for northern Italy's industrial bread cluster and multiwall kraft shipments for standard European imports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large industrial confectioners and pharmaceutical manufacturers negotiating multi-year offtake agreements, fragmenting traditional distributor networks and compressing intermediary margins across European procurement channels.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA, EFSA, and BIS registration for pharmaceutical-grade granular output. Invest in blockchain-verified geolocation traceability to secure EU Deforestation Regulation compliance advantage. Expand captive hydrogenation capacity in Malaysian operations to defend against membrane-based fractionation technology disruption from emerging Asian competitors. For New Entrants and Emerging Players: Establish a beachhead in Brazilian nutraceutical applications where ANVISA harmonization with Codex Alimentarius standards has opened previously blocked import pathways. Target precision fermentation-derived stearic acid for pharmaceutical segments requiring chain-of-custody documentation. Partner with German and Dutch importers mandating real-time geolocation data to bypass established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed plantation-integrated refiners seeking exit liquidity amid EU Deforestation Regulation compliance investments. Long-term viability centers on feedstock sustainability certification and pharmaceutical-grade production line dedication. Watch for inflection in CDSCO registration timelines for Indian pharmaceutical-grade imports as signal for margin pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock Refining | BASF SE secures supply continuity through captive palm kernel oil processing in European oleochemical hubs. |
| Blockchain-Enabled Batch Tracking Implementation | Malaysian exporters compress EU Deforestation Regulation audit timelines from weeks to hours for German importers. |
| Membrane-Based Fractionation Capacity Expansion | Improved C18:0 yield rates from palm kernel oil reduce hydrogenation intensity and energy input per ton. |
| Pharmaceutical-Grade Production Line Dedication | Belgian compounders consolidate procurement toward refineries with dedicated lines to meet REACH Annex XVII thresholds. |
| Direct Long-Term Offtake Agreement Negotiation | Italian industrial pastry manufacturers bypass distributor markups through plantation group contracting. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC filings from listed plantation groups, and EFSA regulatory guidance documents. Primary interviews engaged hydrogenation facility managers, procurement leads at European bakery chains, pharmaceutical excipient formulators, and distribution channel partners across Southeast Asian export corridors. Secondary validation drew from Malaysian Palm Oil Board production statistics, Indian FSSAI enforcement circulars, and REACH Annex XVII restriction updates. Bottom-up volume modeling triangulated against top-down value estimates from refinery capacity assessments.
Forecast inputs considered grade tier stratification across powder, flake, granular, and block formats; end-use industry segmentation spanning baking, confectionery, dairy, snacks, cosmetics, and pharmaceuticals; packaging format differentiation; and regional production hub concentration in Malaysia and Indonesia. CAGRs were derived from production capacity expansion timelines and substitution elasticity estimates for clean-label emulsifier demand. Industry-specific inputs included crude palm oil futures volatility patterns and multi-jurisdiction certification timeline assumptions.
Sensitivities concentrate around EU Deforestation Regulation enforcement intensity, FSSAI refined vegetable fat standard expansion scope, and membrane fractionation technology adoption rates. Forecasts reflect assumptions on feedstock sustainability certification penetration and pharmaceutical-grade qualification success rates. Quarterly review of Malaysian benchmark futures spreads, CDSCO registration approval velocities, and EFSA purity protocol amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market