
 Russia Food Acidulants Market | 2026-2036
Russia Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Acidulants Market Analytics
Project finance tied to phosphoric acid derivative streams is reshaping competitive entry in Russia's food acidulant sector. Phosagro Group leverages captive phosphate rock access to anchor downstream citric acid competitiveness. DHZ – Dmitrievsky Chemical Plant sustains Soviet-era fermentation infrastructure that dominates bulk organic acid supply to domestic processors. Corbion NV navigates import substitution headwinds by positioning biobased lactic acid formulations for premium dairy applications.
Food acidulants comprise organic and inorganic compounds—typically citric, malic, lactic, and tartaric acids—that lower pH, enhance microbial stability, and modulate flavor profiles in processed foods, with titratable acidity measured between 0.5% and 2.5% in most commercial formulations. Citric acid occupies the largest production volume share due to established fermentation capacity and universal beverage compatibility. Malic acid represents the fastest-expanding category as confectionery manufacturers seek cleaner-label tartness without synthetic aftertaste. Powder form commands the dominant share in logistics and shelf-life terms, though liquid acidulants gain traction in automated beverage dosing systems.
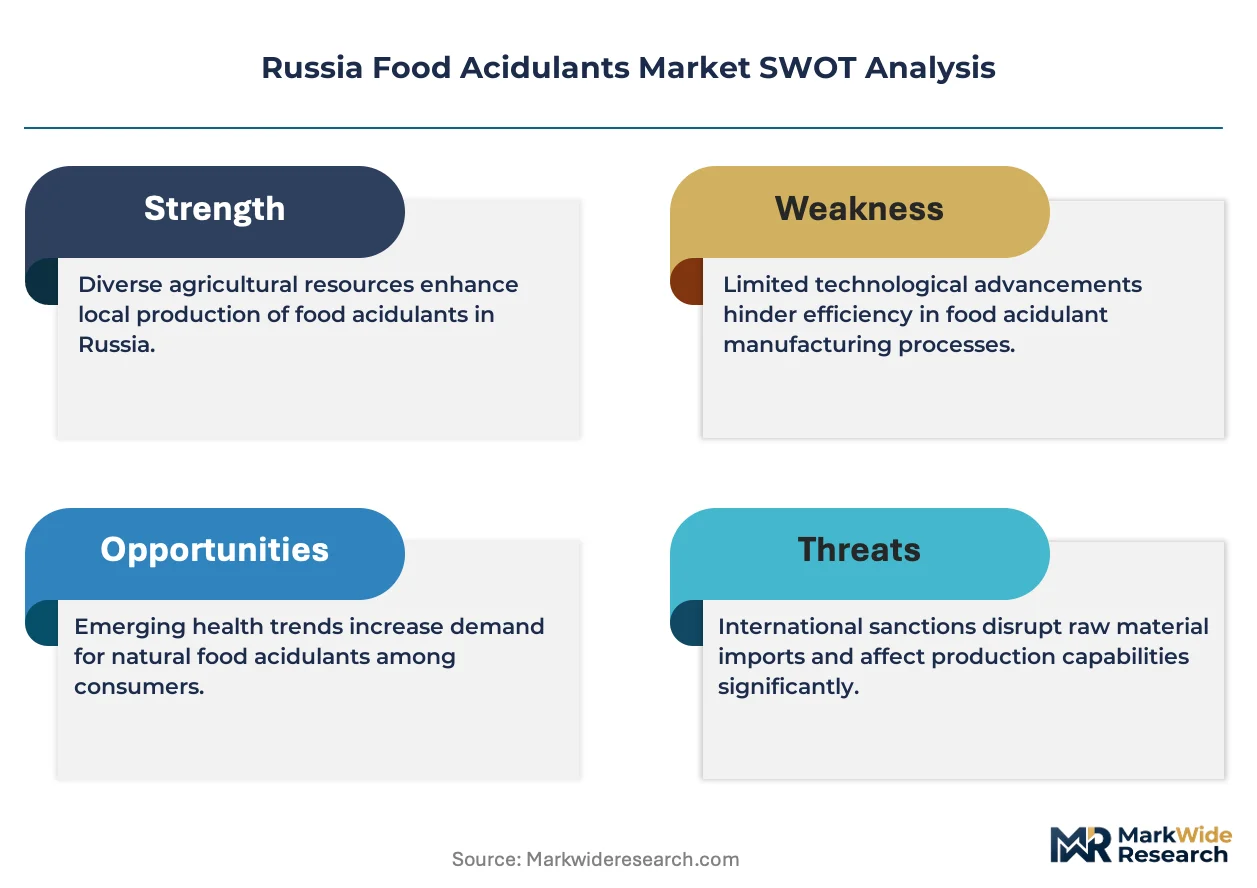
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces EAEU Technical Regulation 029/2012 on food additive safety, while the Federal Agency on Technical Regulating and Metrology (Rosstandart) certifies GOST compliance for acidulant purity grades. These frameworks compel domestic producers to maintain laboratory-grade quality documentation, elevating compliance costs for smaller importers and reinforcing established manufacturers with in-house analytical capabilities. Stakeholders must monitor pending EAEU harmonization amendments that could tighten residual solvent limits and redirect sourcing strategies toward fermentation-based rather than synthetic acidulant pathways.
Market Dynamics
Fermentation-based citric acid production is consolidating around captive phosphate feedstock access, tightening supply security for Moscow beverage processors while elevating capital barriers for new market entrants.
Growth Catalysts
- EAEU Technical Regulation 029/2012 Harmonization:Unified additive safety standards across member states reduce cross-border certification friction for Russian acidulant exporters targeting Belarus and Kazakhstan.
- Processed Beverage Expansion:Carbonated drink and juice manufacturers in the Central Federal District are scaling acidulant procurement to meet flavor stability requirements for extended shelf-life products.
- Phosphate Rock Integration:Domestic mining assets enable backward integration into phosphoric acid derivatives, insulating producers from imported feedstock volatility.
Market Restraints
- Fermentation Input Cost Volatility:Molasses and corn starch prices fluctuate with agricultural yields, compressing margins for citric acid producers lacking long-term supply contracts.
- Import Substitution Mandates:Federal incentives favor domestic sourcing, yet technical gaps in synthetic acidulant production force continued reliance on Chinese malic acid imports.
- Residual Solvent Scrutiny:Pending EAEU amendments to tighten solvent limits in extraction-based acidulants threaten synthetic production pathways against fermentation alternatives.
Strategic Opportunities
- Premium Dairy Formulation White Space:Biobased lactic acid demand from yogurt and cheese processors in Saint Petersburg exceeds domestic supply, creating entry points for fermentation specialists.
- Liquid Acidulant Automation:Beverage bottlers in the Volga Federal District are retrofitting dosing infrastructure, opening volume contracts for pump-ready acidulant deliveries.
- Confectionery Cleaner-Label Migration:Tartaric acid and malic acid substitution for synthetic acids in gummy and hard candy applications responds to retailer formulation guidelines.
Industry Challenges
- Analytical Laboratory Capacity:Rospotrebnadzor documentation requirements for batch-level purity testing strain quality control staffing at mid-scale processors.
- Soviet-Era Infrastructure Modernization:Fermentation tank corrosion and outdated separation equipment at legacy chemical plants demand capital deployment without guaranteed offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Acidulants Market |
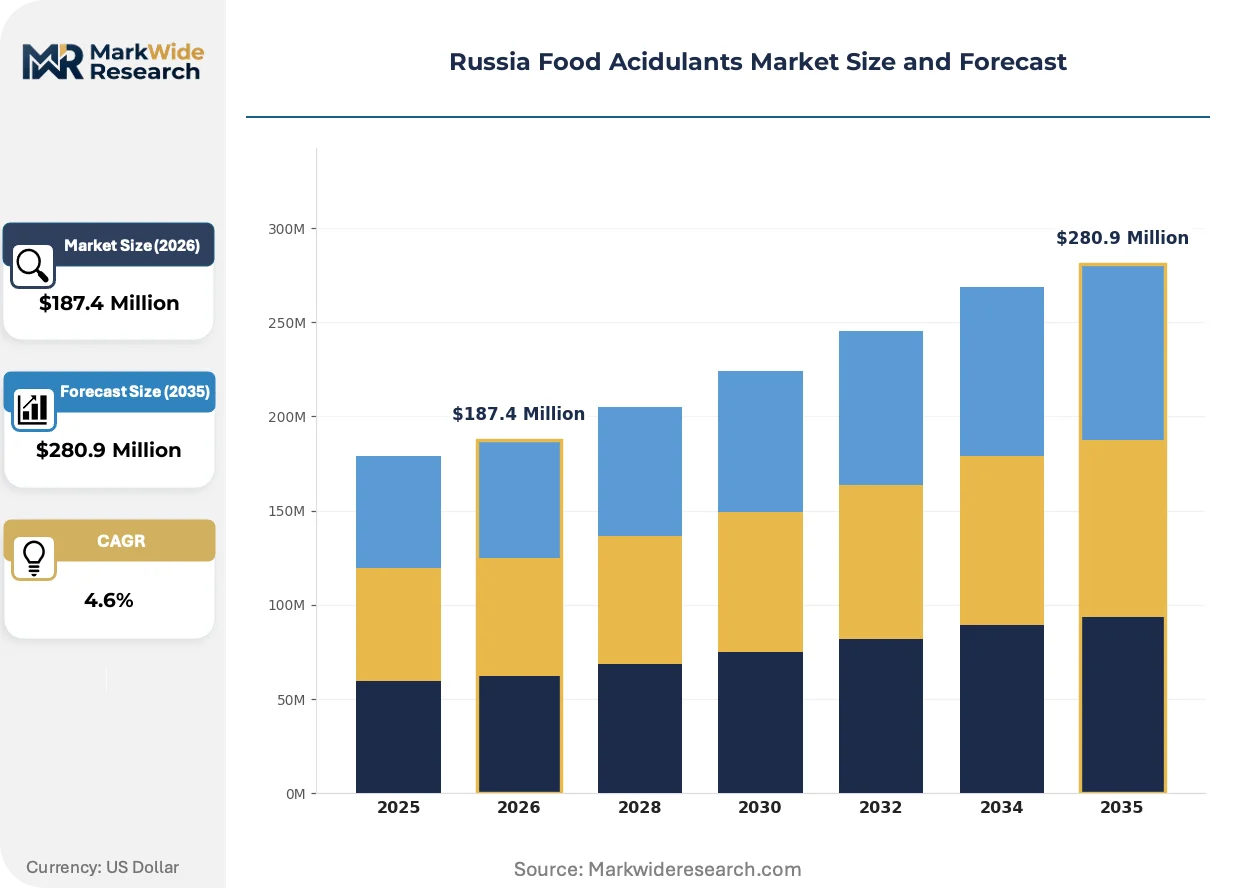
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Malic Acid, Lactic Acid, Tartaric Acid Application: Beverages, Bakery Products, Dairy, Confectionery Form: Powder, Liquid, Granular, Crystal End User: Food Manufacturers, Beverage Producers, Catering Services, Retailers |
| Companies Covered | Phosagro Group, Filtron Envirotech, DHZ – Dmitrievsky Chemical Plant, Brenntag AG, Tate & Lyle PLC, Archer Daniels Midland Co., Prayon Group, Corbion NV, Jungbunzlauer Suisse AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Acidulants Market Evolving Landscape
Bioprocess engineering and regulatory chemistry are converging to displace synthetic acidulant pathways, with fermentation-derived molecules capturing formulation preference across Russia's processed food sector.
Continuous fermentation technology for citric acid production is migrating from batch processing toward integrated bioreactor systems with real-time pH monitoring. Large-scale beverage manufacturers in Moscow Oblast are piloting these installations to reduce cycle times and contamination risk. The technology is migrating from pharmaceutical-grade applications into food-grade volume production, compressing capital recovery periods for equipment suppliers.
Rospotrebnadzor enforcement of EAEU Technical Regulation 029/2012 is tightening documentary evidence requirements for additive purity certifications. Domestic producers must now submit chromatographic analysis for every production lot, elevating laboratory infrastructure costs. Synthetic acidulant importers face heightened rejection rates at border inspection points, redirecting procurement toward fermentation-based domestic suppliers with established GOST compliance protocols.
Direct supplier relationships between acidulant producers and beverage formulators are displacing traditional distributor intermediaries in the Central Federal District. Category managers at major soft drink bottlers are negotiating annual volume contracts with fixed price escalation clauses. This pattern concentrates procurement leverage among three to four domestic fermentation specialists, marginalizing smaller traders dependent on spot market volumes.
Russia Food Acidulants Market Segmentation
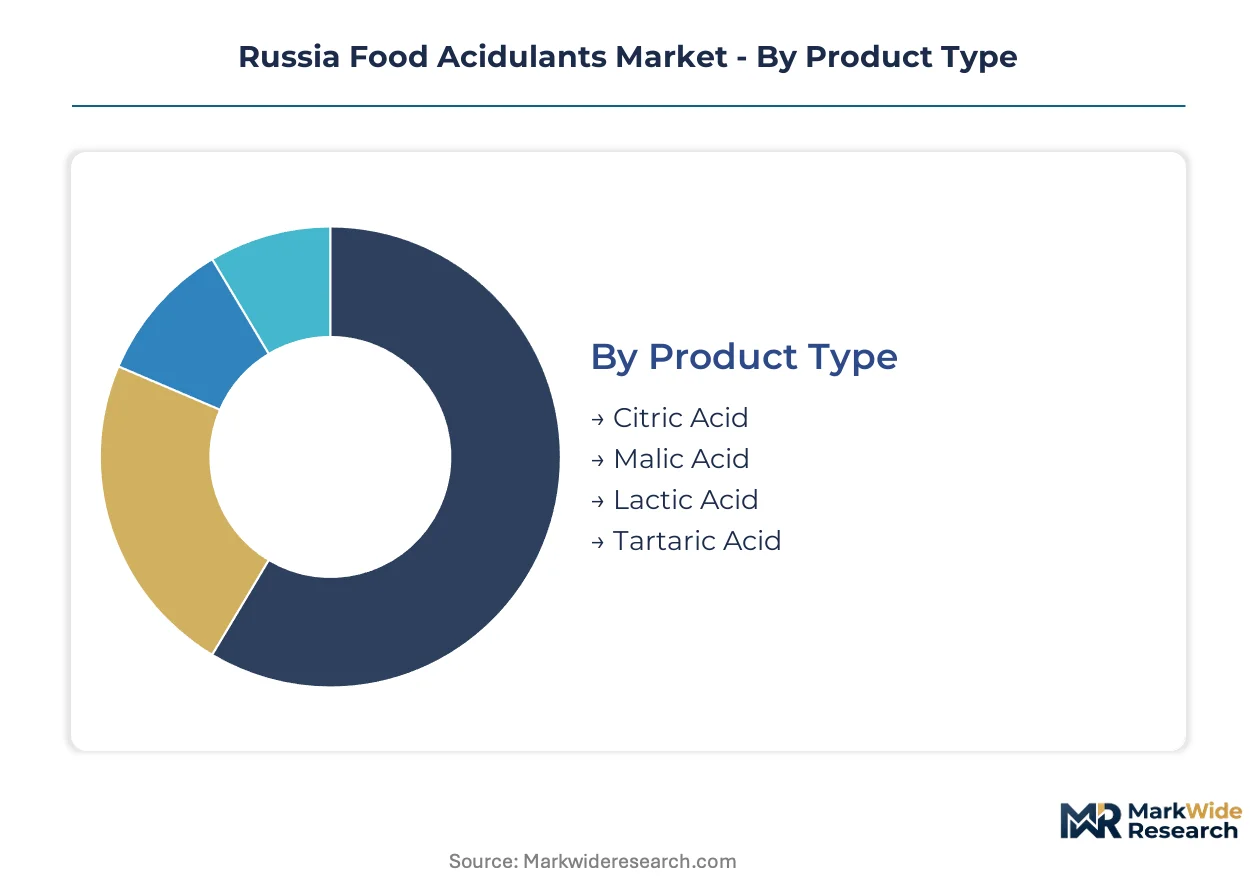
Acidulant procurement patterns in Russia diverge sharply across product chemistry, application requirements, and physical form factors. Each segmentation axis carries distinct regulatory, logistical, and formulation implications that reshape supplier relationships and manufacturing investment priorities.
Product Type:
Mature fermentation infrastructure dominates organic acid supply while synthetic alternatives face escalating purity documentation burdens under EAEU Technical Regulation 029/2012.
- Citric Acid:Aspergillus niger fermentation yields this tricarboxylic acid with titratable acidity specifications between 99.5% and 100.5% purity. Moscow beverage processors anchor procurement volumes, driven by carbonated drink and juice shelf-life extension requirements that demand consistent pH modulation across batch production.
- Malic Acid:This dicarboxylic acid delivers cleaner-label tartness without the metallic aftertaste associated with synthetic alternatives. Confectionery manufacturers in the Central Federal District are accelerating procurement as retailer formulation guidelines tighten against artificial acidulants, though domestic fermentation capacity lags demand and forces continued import reliance.
- Lactic Acid:Biobased C3H6O3 fermentation supplies dairy acidification for yogurt and cheese processing in Saint Petersburg, with optical isomer specifications critical for flavor profile consistency.
- Tartaric Acid:Potassium bitartrate derivative extraction serves wine industry acidification and baking powder activation, with grape-sourced supply chains concentrated in southern federal district agricultural zones.
Citric acid retains volume leadership; malic acid holds the steepest expansion curve.
Application:
End-use concentration patterns track Russia's processed food manufacturing geography, with procurement leverage clustering around federal district production hubs.
- Beverages:Carbonated soft drink and juice manufacturers in Moscow Oblast constitute the dominant acidulant demand pool. Automated dosing systems require liquid acidulant compatibility, pushing suppliers toward pump-ready formulation investments.
- Bakery Products:Chemical leavening systems depend on acidulant-bicarbonate reactions for CO2 generation. Tartaric acid and sodium acid pyrophosphate blends dominate premium segment formulations, with industrial bakeries in the Volga Federal District scaling procurement for extended shelf-life bread lines.
- Dairy:pH reduction for yogurt fermentation and fresh cheese curd formation drives lactic acid demand. Saint Petersburg processors report supply gaps between domestic biobased production and formulation requirements for probiotic strain compatibility.
- Confectionery:Hard candy and gummy acid coating applications favor malic acid for sustained sour release profiles. Cleaner-label migration pressures are redirecting procurement away from synthetic acid combinations toward fermentation-derived alternatives.
Beverages command procurement volume concentration; confectionery exhibits the most rapid formulation specification evolution.
Form:
Physical state selection hinges on handling infrastructure, dissolution kinetics, and contamination risk management across divergent manufacturing scales.
- Powder:Anhydrous and monohydrate crystalline grades dominate dry blend applications and long-distance logistics. Bulk silo storage at major beverage concentrate plants in Moscow reduces per-kilogram handling costs.
- Liquid:Aqueous solutions enable precision dosing in continuous flow processing. Volga Federal District bottlers retrofitting automated injection systems are driving contract volume growth for 50% concentration deliveries.
- Granular:Intermediate particle size distribution reduces dust generation versus fine powders while maintaining rapid dissolution characteristics. Mid-scale bakery compound manufacturers prefer this form for on-site blending operations.
- Crystal:Large-format crystalline grades serve specialty applications including direct acidulant tableting and controlled-release confectionery inclusions.
Powder form maintains logistics dominance; liquid acidulants are climbing the fastest in automated processing adoption.
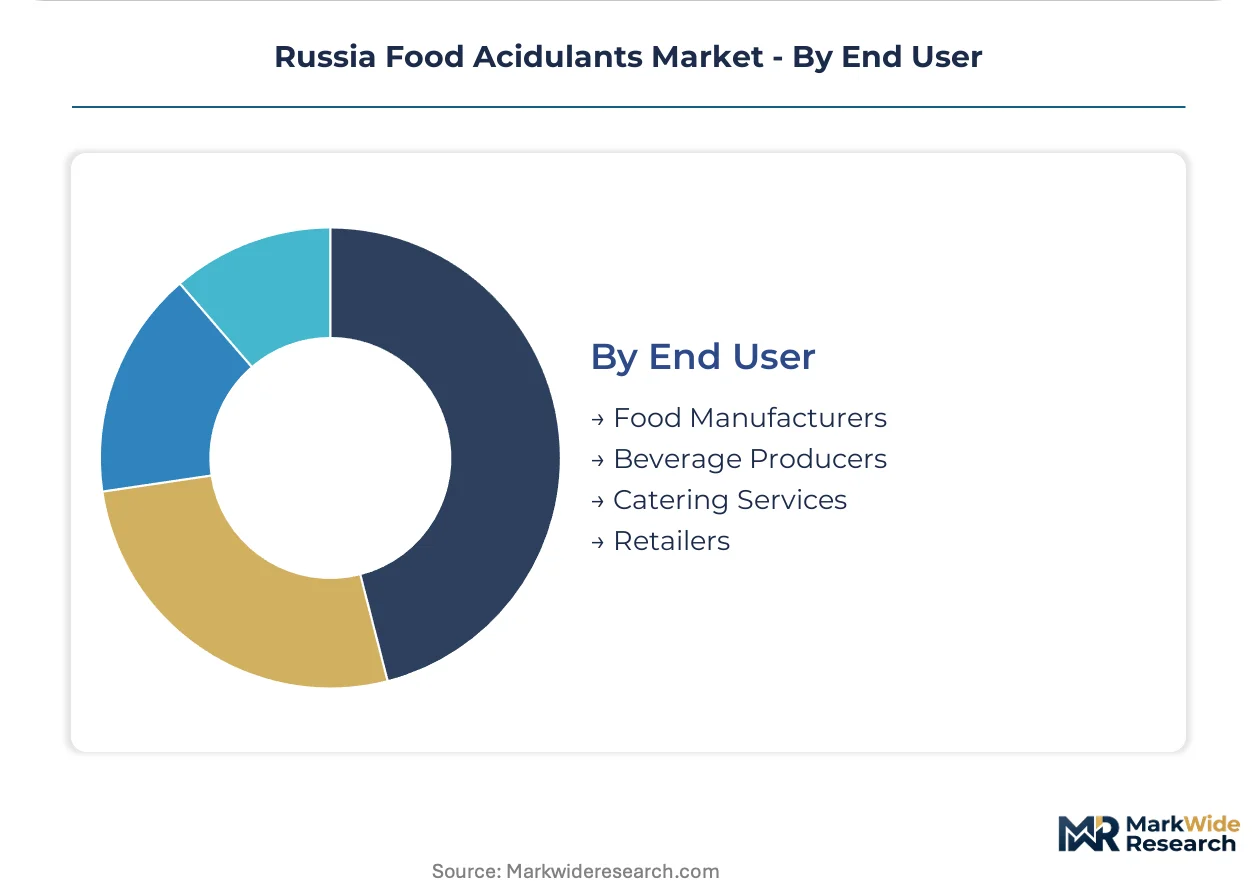
End User:
Customer scale and technical capability stratification creates distinct service requirements and contract structures across the procurement base.
- Food Manufacturers:Industrial-scale processors of sauces, dressings, and preserved vegetables require acidulants for microbial stability assurance. Rospotrebnadzor batch documentation requirements elevate supplier qualification barriers.
- Beverage Producers:Concentrate and ready-to-drink bottlers negotiate annual volume contracts with fixed price escalation clauses, concentrating procurement leverage among domestic fermentation specialists.
- Catering Services:Institutional and commercial foodservice operations procure acidulants through distribution intermediaries for marinade and preservation applications, with smaller lot sizes and less stringent purity documentation.
- Retailers:Private-label food product development teams specify acidulant grades for contract manufacturers, with formulation decisions increasingly influenced by consumer-facing clean-label positioning.
Food manufacturers anchor procurement volume; beverage producers are driving the steepest contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal import substitution mandates and EAEU harmonization protocols are redistributing acidulant production capacity across Russia's federal districts. Procurement leverage clusters around legacy chemical infrastructure and beverage manufacturing hubs.
Central Federal District
Moscow Oblast beverage processors drive citric acid procurement volumes for carbonated drink shelf-life extension. Rospotrebnadzor enforces EAEU Technical Regulation 029/2012 batch documentation requirements that elevate laboratory infrastructure costs. The Dmitrievsky Chemical Plant in Kursk anchors organic acid supply to regional concentrate manufacturers.
Northwestern Federal District
Saint Petersburg dairy processors report biobased lactic acid supply gaps for yogurt fermentation applications. The city's national food safety regulator maintains strict additive purity thresholds under technical regulations aligned with EAEU standards. Local cheese curd formation facilities are negotiating direct supplier contracts to bypass distribution intermediaries.
Volga Federal District
Bottlers in this region are retrofitting automated dosing infrastructure for liquid acidulant compatibility. Federal incentives favor domestic sourcing, yet technical gaps in synthetic acidulant production force continued reliance on imports. Kazan-based beverage compound manufacturers are scaling procurement for extended shelf-life bread lines.
Southern Federal District
Grape-sourced tartaric acid extraction serves wine industry acidification from agricultural zones in Krasnodar Krai. The region's fermentation input costs fluctuate with agricultural yields, compressing margins for producers lacking long-term supply contracts. Rostov-on-Don food manufacturers are expanding acidulant procurement as flavor stability becomes critical.
Ural Federal District
Phosphate rock mining assets in this region enable backward integration into phosphoric acid derivatives. Domestic producers leverage captive feedstock access to insulate against imported input volatility. Yekaterinburg chemical processors are consolidating fermentation-based citric acid production around captive phosphate supply.
Russia Food Acidulants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Russia's acidulant procurement base. The market structure concentrates around three to four domestic fermentation specialists with established GOST compliance protocols, while smaller traders dependent on spot market volumes face marginalization. Two strategic archetypes dominate: phosphate-integrated chemical conglomerates with captive mining assets, and biobased fermentation specialists targeting premium dairy applications. Competitive moves center on direct supplier relationships displacing distributor intermediaries, and continuous fermentation technology investments compressing capital recovery periods.
Among phosphate-integrated producers, Phosagro Group exemplifies the backward-integrated archetype through captive phosphate rock access anchoring downstream competitiveness. DHZ – Dmitrievsky Chemical Plant occupies a position within the legacy fermentation infrastructure tier, sustaining Soviet-era tank systems that dominate bulk organic acid supply. Corbion NV represents the biobased specialist archetype, navigating import substitution headwinds by positioning fermentation-derived formulations for premium segment procurement.
| Leading Market Players |
|---|
| Phosagro Group |
| Filtron Envirotech |
| DHZ – Dmitrievsky Chemical Plant |
| Brenntag AG |
| Tate & Lyle PLC |
| Archer Daniels Midland Co. |
| Prayon Group |
| Corbion NV |
| Jungbunzlauer Suisse AG |
| Others |
Value Network & Pricing Analysis
Phosphate rock mining concentration in the Ural Federal District anchors margin pools with beverage processors in Moscow Oblast, where backward-integrated producers extract rents from fermentation-dependent competitors facing molasses cost volatility.
Pricing Analysis
Certification level under EAEU Technical Regulation 029/2012 creates the primary spread between laboratory-grade fermentation batches and import-reliant synthetic alternatives. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade purity levels segments procurement leverage. Cost compression in standard-grade citric acid is intensifying because Chinese malic acid imports face heightened Rospotrebnadzor rejection rates. Small-scale confectionery manufacturers in the Central Federal District exhibit highest price sensitivity, while Moscow beverage bottlers with annual volume contracts demonstrate lowest sensitivity due to fixed price escalation clauses.
Supply Chain Analysis
Export control regimes limiting fermentation technology transfers from EU member states constrain domestic capacity expansion for Russian producers seeking continuous bioreactor upgrades. Geographic supply concentration centers on China for malic acid, Kazakhstan for phosphate rock transit, and Belarus for cross-border EAEU trade. Raw material dependencies rest on molasses from Southern Federal District sugar beet processing, phosphate rock from Ural mining assets, and corn starch from Volga Federal District agricultural zones. Single-source vulnerability permeates synthetic acidulant procurement channels. Distribution runs through direct supplier relationships displacing traditional distributor intermediaries in the Central Federal District.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as cleaner-label formulation requirements splinter procurement specifications across confectionery, dairy, and beverage segments, creating niches for fermentation specialists and biobased suppliers.
For Market Incumbents: Insulate market position by deepening captive phosphate feedstock integration at Ural mining assets and accelerating GOST certification documentation automation to neutralize Rospotrebnadzor batch testing burdens. Threat from Corbion NV's biobased lactic acid positioning in Saint Petersburg premium dairy demands defensive capacity addition in lactic acid fermentation infrastructure. For New Entrants and Emerging Players: Establish a beachhead in liquid acidulant automation contracts with Volga Federal District beverage bottlers retrofitting dosing infrastructure. White-space targets include malic acid fermentation capacity to displace Chinese imports and tartaric acid extraction partnerships with Krasnodar Krai wine producers. Go-to-market angle centers on pump-ready formulation technical service bundled with annual volume commitments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Soviet-era fermentation infrastructure operators requiring capital deployment for corrosion-resistant tank replacement and separation equipment modernization. Long-term viability over a five-to-ten year horizon hinges on EAEU regulatory harmonization sustaining domestic preference. Signal to watch is pending amendment tightening residual solvent limits in extraction-based acidulants, which would accelerate fermentation pathway capture.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Deployment | Reduces cycle times for Moscow Oblast beverage processors piloting integrated bioreactor systems with real-time pH monitoring. |
| Backward Integration into Phosphate Rock Mining | Phosagro Group leverages captive Ural assets to insulate citric acid production from imported feedstock price volatility. |
| Biobased Lactic Acid Capacity Expansion | Addresses supply gaps reported by Saint Petersburg yogurt processors seeking probiotic strain compatibility. |
| Liquid Acidulant Formulation Investment | Enables pump-ready deliveries for Volga Federal District bottlers retrofitting automated injection systems. |
| Direct Supplier Relationship Consolidation | Concentrates procurement leverage among three to four domestic fermentation specialists with established GOST compliance protocols. |
Research Methodology
Cross-validation between primary interviews with fermentation plant managers, beverage procurement leads at Moscow concentrate manufacturers, Rospotrebnadzor regulatory affairs specialists, and distribution channel partners anchors the qualitative findings. Secondary validation draws from EAEU technical regulation amendments, Russian customs trade data, GOST certification records, and SEC filings of multinational acidulant suppliers. Bottom-up production capacity modeling triangulates with top-down procurement volume estimates from federal district manufacturing surveys.
Calibration against historical price formation patterns and batch documentation cost structures shapes the analytical framework across the analysis window. Segmentation dimensions span acid chemistry type, physical form factor, end-use application, and federal district production hub. CAGRs derive from demand elasticity modeling tied to beverage shelf-life extension requirements and confectionery cleaner-label migration. Forecast inputs include molasses price volatility indices and phosphate rock extraction cost curves from Ural mining operations.
Sensitivities concentrate around EAEU residual solvent limit amendments, Chinese malic acid import rejection rate trends, and fermentation input agricultural yield fluctuations. Forecasts reflect documented assumptions on regulatory harmonization pace and domestic substitution incentive durability. Material shifts in EAEU technical regulation enforcement stringency or phosphate rock export policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Global Calcium Propionate Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
China Food Acidulants Market