
 Latin America Frozen Bakery Market | 2026-2036
Latin America Frozen Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Frozen Bakery Market Analysis
Subscription-based freezer-to-oven service packages is rebalancing how commercial buyers procure frozen bakery items, shifting capital from equipment ownership to operational flexibility. Grupo Bimbo S.A.B leverages its vertical integration across wheat sourcing and distribution to sustain margin control in Mexico. Europastry S.A anchors its position through frozen dough specialization for European-style cafes. Associated British Foods Plc competes via brand strength in retail channels across Chile and Colombia.
Latin America frozen bakery encompasses dough, par-baked, and fully baked products preserved at sub-zero temperatures, typically formulated with modified starches and emulsifiers to ensure post-thaw structural integrity and sensory consistency for foodservice operators. Bread and pastries dominate current volume, with croissants representing the fastest-growing product type as cafe culture expands in São Paulo and Buenos Aires. Bakeries and supermarkets capture the deepest margin pools, while restaurants drive throughput volume; online distribution channels gain traction as cold-chain reliability improves.
Brazil's ANVISA and Mexico's COFEPRIS enforce frozen food safety standards that shape formulation requirements and import clearance protocols across the region. Argentina's national food code adds layer-specific compliance for trans-fat labeling and shelf-life declarations. Stakeholders must monitor evolving Mercosur harmonization talks, as unified standards would reshape cross-border manufacturing footprints and supplier qualification criteria.
Market Dynamics
Cold chain infrastructure expansion across Brazil and Mexico is compressing logistics costs and enabling frozen bakery penetration into secondary cities previously unreachable due to temperature-control gaps.
Growth Catalysts
- ANVISA frozen food safety standards:Brazil's unified labeling and shelf-life protocols reduce cross-state compliance friction, accelerating national distribution networks for frozen dough suppliers.
- Quick-service restaurant labor cost pressures:Par-baked croissants and pre-proofed bread eliminate overnight bakery staffing needs, driving adoption among São Paulo and Rio de Janeiro franchise operators.
- Supermarket in-store bakery expansion:Mexico's urban corridor retailers are dedicating floor space to freezer-to-oven sections, creating dedicated procurement channels for frozen pastry suppliers.
Market Restraints
- Wheat price volatility:Argentina's drought-prone Pampas region supplies regional flour mills; climate-induced harvest variability compresses margins for frozen dough formulators dependent on local wheat.
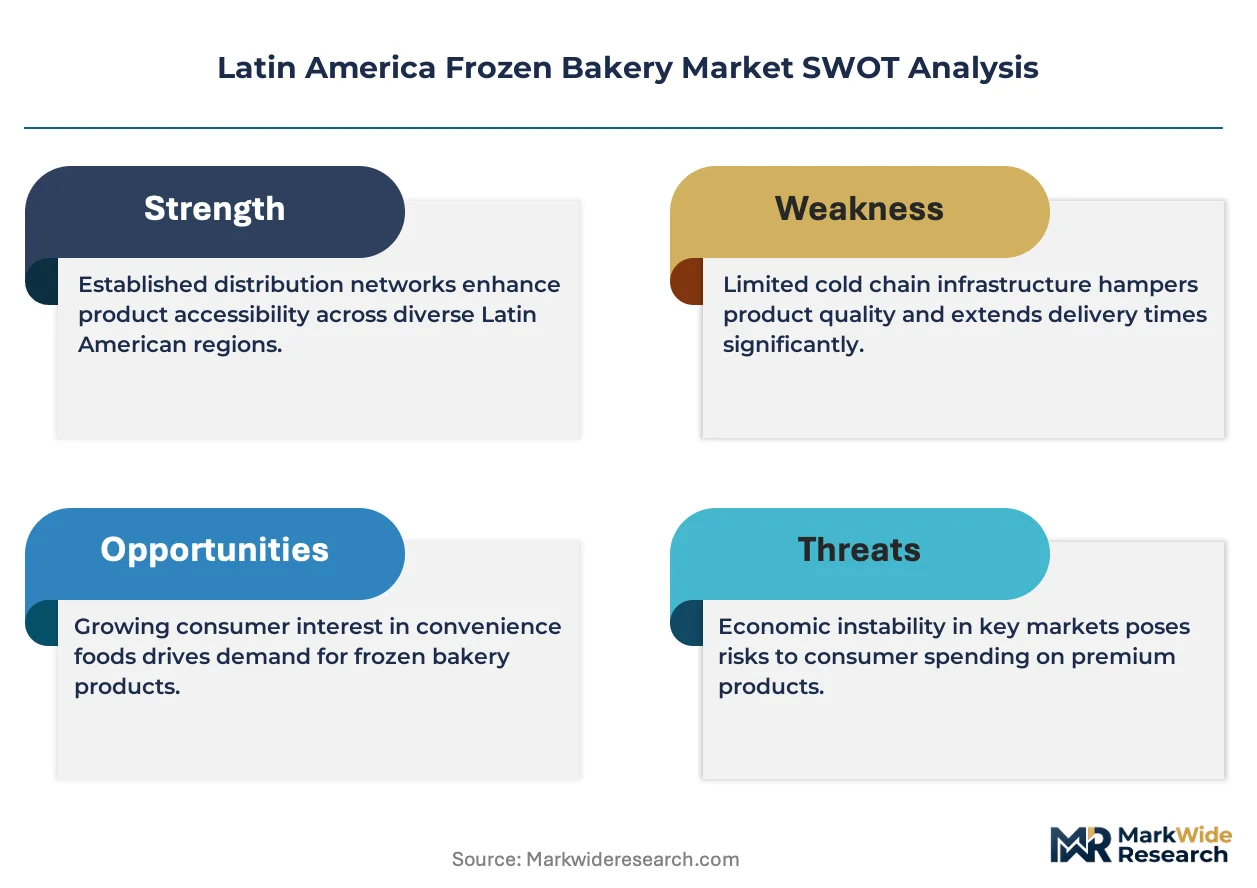
- Cold chain fragmentation:Last-mile refrigerated transport remains concentrated among three logistics providers in Colombia and Peru, creating bottleneck risk for temperature-sensitive bakery distribution.
- Fresh bakery substitution:Traditional panaderías in Mexican neighborhoods retain consumer preference for same-day baked goods, limiting frozen product penetration in heritage retail formats.
Strategic Opportunities
- Colombian secondary city penetration:Medellín and Cali lack dedicated frozen bakery distributors; cold chain investments by Bogotá-based logistics firms open white-space territory for par-baked product lines.
- Cafe culture acceleration in Buenos Aires:European-style espresso bars require consistent croissant supply; frozen dough specialization addresses skilled baker shortages in Argentina's capital.
- COFEPRIS streamlined import protocols:Mexico's regulator is harmonizing frozen food clearance with US FDA standards, reducing time-to-market for cross-border bakery suppliers.
Industry Challenges
- Refrigerated warehousing capex intensity:Blast freezing capacity requires specialized equipment investments that strain mid-sized bakery processors in Chile and Ecuador.
- Modified starch formulation expertise:Post-thaw texture consistency demands specialized food science capabilities scarce among traditional Latin American bakery operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Frozen Bakery Market |
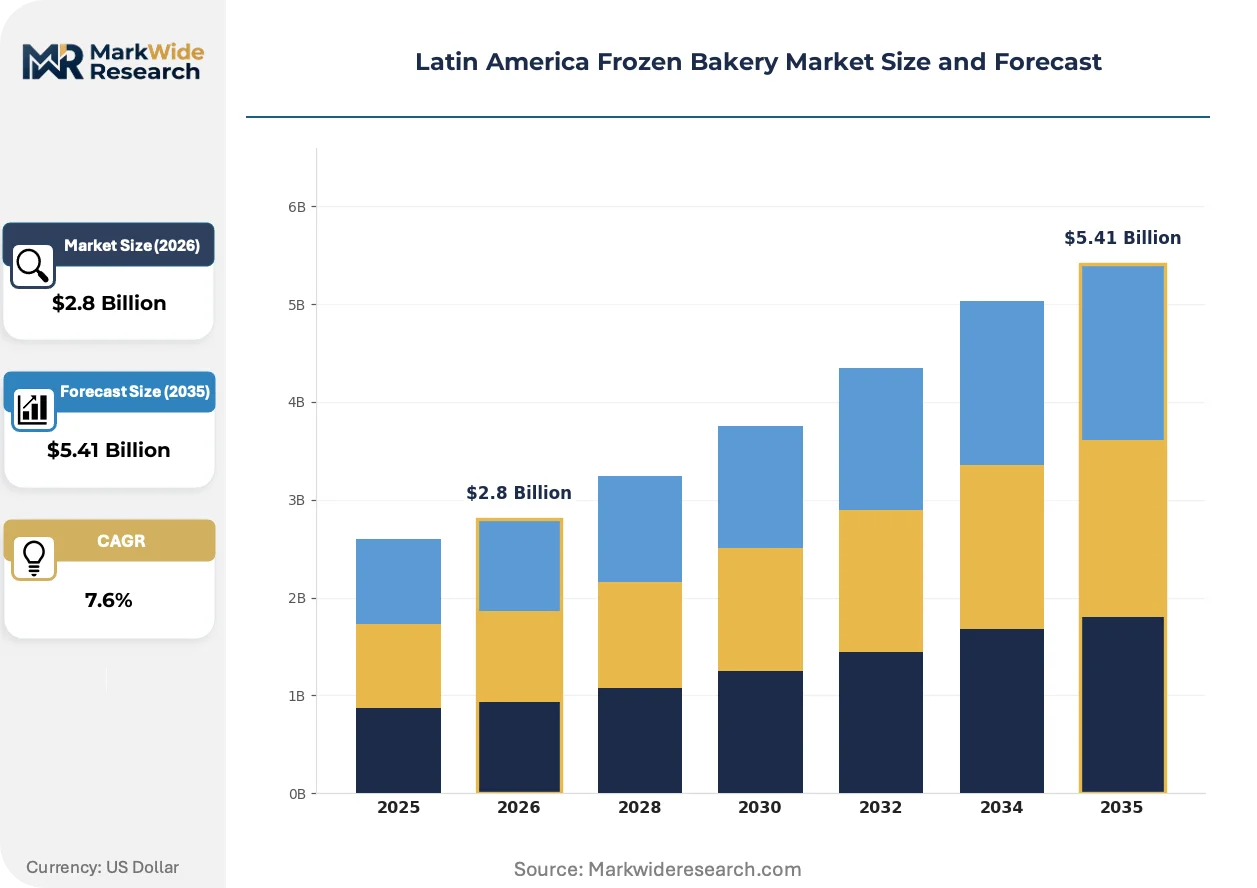
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Croissants End User: Restaurants, Supermarkets, Cafes, Bakeries Distribution Channel: Online, Direct Sales, Wholesalers, Retail Stores Packaging Type: Wrapped, Bags, Boxes, Trays |
| Companies Covered | Grupo Bimbo S.A.B, General Mills Inc, Europastry S.A, Aryzta AG, Lantmannen Unibake, Vandemoortele, Associated British Foods Plc, Bridgford Foods Corp, Conagra Brands Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Frozen Bakery Market Emerging Trajectories
Automation and formulation science are compressing production timelines while regulatory harmonization and procurement model evolution reshape how frozen bakery products reach foodservice and retail endpoints.
Modified starch and emulsifier blends are integrating into frozen dough formulations to maintain cellular structure through freeze-thaw cycles. Large-scale bakery processors in Brazil and Mexico are adopting these ingredient systems at accelerating rates. The technology is integrating quality consistency across geographically dispersed production facilities, reducing batch-to-batch variation that previously limited national brand expansion.
COFEPRIS and ANVISA are converging frozen food labeling requirements around trans-fat disclosure and shelf-life transparency mandates. Industrial bakery operators must reformulate legacy recipes to meet dual-jurisdiction compliance. Par-baked bread categories face the steepest reformulation timelines as both regulators prioritize processed food nutritional disclosure.
Subscription freezer-to-oven service packages are displacing equipment ownership models among mid-sized restaurant chains. Foodservice operators in São Paulo and Mexico City are outsourcing frozen inventory management to specialized distributors with captive cold storage. Chilean hotel chains represent the fastest-adopting segment, trading capital expenditure for per-unit operational flexibility.
Latin America Frozen Bakery Market Segmentation
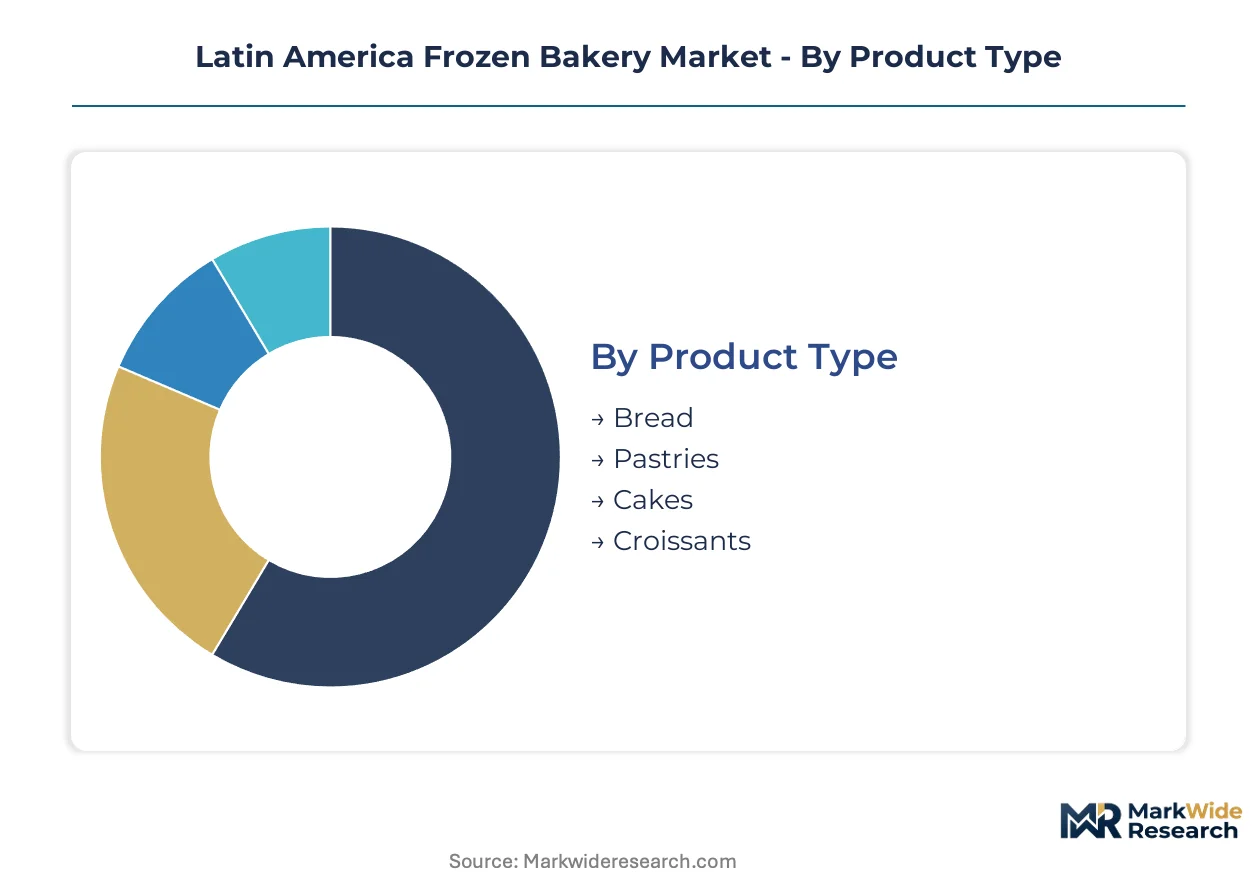
Segmentation in Latin America frozen bakery reveals how capital allocation, temperature sensitivity, and procurement workflows fragment commercial opportunity across distinct operational models. Understanding these divides allows suppliers to match formulation investments with channel-specific margin structures.
Product Type:
Capital intensity varies sharply across product categories, with croissant lines requiring laminated dough equipment and precision temperature control that bread operations can bypass.
- Bread:Par-baked and fully-baked loaves dominate current production volumes, formulated with modified starches to withstand freeze-thaw cycles without crumb degradation. Brazil's quick-service restaurant chains absorb the majority of regional par-baked bread supply as labor cost pressures eliminate overnight bakery staffing.
- Croissants:Laminated frozen dough demands specialized sheeting equipment and extended cold-chain integrity through distribution. São Paulo and Buenos Aires cafe operators drive demand as European-style espresso bar expansion outpaces skilled artisan baker availability.
- Pastries:Empanadas, danishes, and sweet rolls serve institutional foodservice and retail freezer-to-oven sections across Mexican urban corridors.
- Cakes:Fully-frozen layer cakes and sheet cakes concentrate in supermarket in-store bakery programs and hotel banquet operations.
Bread absorbs the bulk of installed capacity; croissants are expanding most quickly.
End User:
Customer procurement sophistication separates segments, with supermarkets demanding just-in-time inventory systems that restaurants rarely maintain.
- Supermarkets:In-store bakery expansion across Mexico City, Guadalajara, and Monterrey creates dedicated procurement channels for frozen pastry suppliers. Retailers specify freezer-to-oven products with extended shelf-life declarations to minimize shrinkage.
- Restaurants:Quick-service franchise operators in Rio de Janeiro and São Paulo prioritize par-baked items that eliminate proofing labor. ANVISA frozen food safety standards shape supplier qualification protocols for national chain distribution.
- Cafes:European-style espresso bars in Buenos Aires require consistent croissant supply despite skilled baker shortages.
- Bakeries:Traditional panaderías in Mexican neighborhoods retain preference for same-day baked goods, limiting frozen penetration in heritage retail formats.
Supermarkets command the steepest supplier qualification requirements; restaurants generate the highest throughput volumes.
Distribution Channel:
Channel selection determines cold-chain liability allocation, with direct sales forcing producers to maintain captive refrigerated fleets.
- Direct Sales:Large bakery processors in Brazil and Mexico operate dedicated refrigerated transport to quick-service restaurant chains, trading margin for volume commitment and demand forecasting visibility.
- Wholesalers:Bogotá-based logistics firms with blast freezing capacity serve as gatekeepers for Colombian secondary city penetration into Medellín and Cali.
- Online:Cold-chain reliability improvements enable emerging digital procurement platforms targeting mid-sized restaurant operators in Santiago and Mexico City.
- Retail Stores:Traditional cash-and-carry outlets remain significant for small bakery operators in Peru and Ecuador with limited cold storage investment.
Direct sales capture the largest contract values; online channels are climbing the fastest as digital procurement platforms mature.
Packaging Type:
Packaging specification drives formulation constraints, with modified atmosphere requirements varying by product moisture content and shelf-life target.
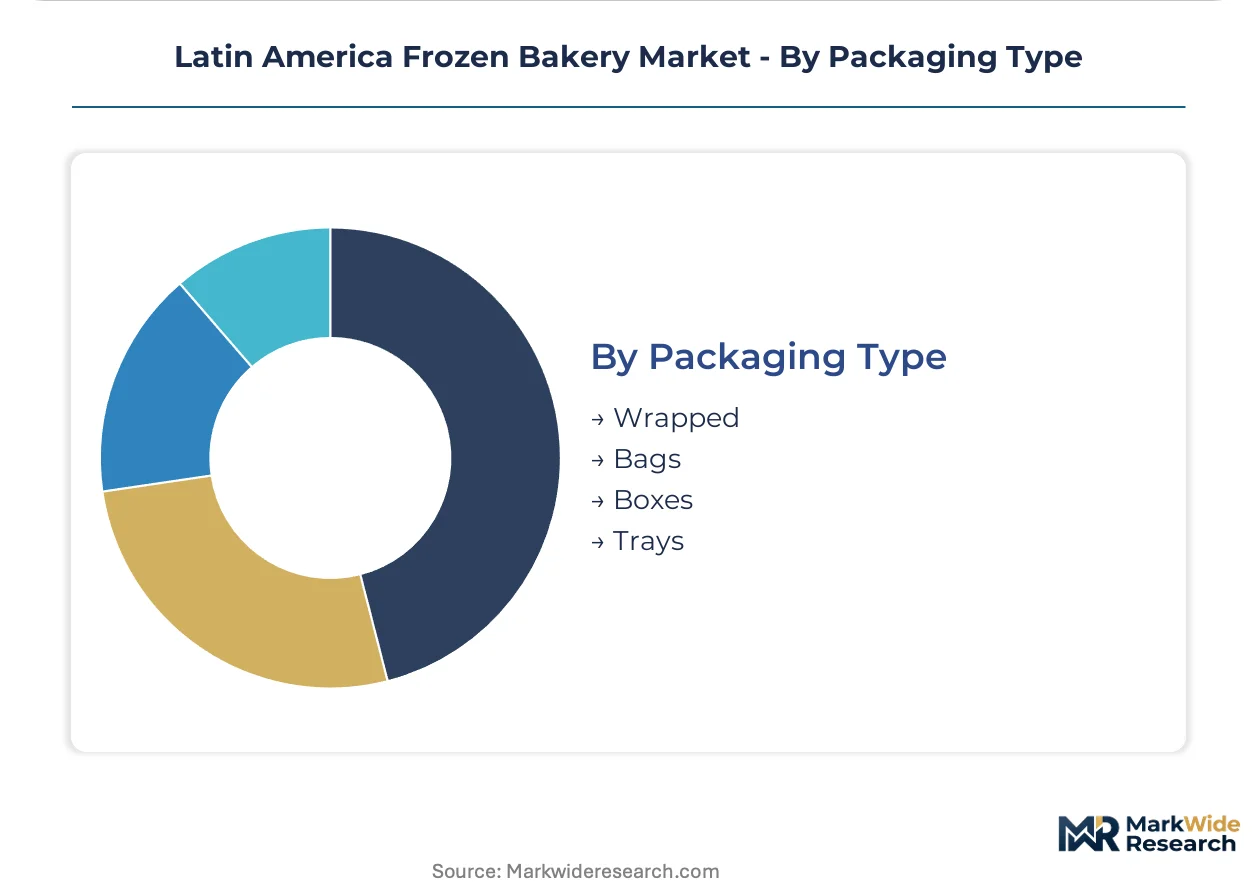
- Wrapped:Individual film wrapping dominates croissant and pastry categories, preserving laminated structure through freeze-thaw cycles for cafe and restaurant delivery.
- Bags:Multi-unit polypropylene bags serve par-baked bread distribution to quick-service restaurant chains with high-velocity inventory turns.
- Boxes:Corrugated containers with moisture barriers protect fully-frozen cakes through extended distribution timelines to supermarket distribution centers.
- Trays:Reusable plastic trays support bakery-to-bakery direct delivery in Chilean and Argentine foodservice corridors with established return logistics.
Wrapped formats command premium positioning; bag packaging handles the highest unit volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors frozen bakery demand across Latin America, with its dense quick-service restaurant corridor absorbing par-baked bread volumes that cascade through Brazil's southeastern logistics network. Cold chain investments radiating from this metro enable secondary city penetration previously blocked by temperature-control gaps.
Brazil
São Paulo and Rio de Janeiro quick-service franchise operators drive par-baked croissant adoption as labor cost pressures eliminate overnight bakery staffing. ANVISA's unified frozen food labeling and shelf-life protocols reduce cross-state compliance friction, accelerating national distribution networks for frozen dough suppliers. Curitiba's foodservice cluster hosts expanding blast freezing capacity serving the southern Mercosur corridor.
Mexico
Mexico City Metro, Guadalajara, and Monterrey supermarkets dedicate expanding floor space to freezer-to-oven bakery sections, creating dedicated procurement channels for frozen pastry suppliers. COFEPRIS harmonizes frozen food clearance protocols with US FDA standards, compressing time-to-market for cross-border bakery suppliers. Bajío Region logistics firms invest in captive cold storage to capture supermarket just-in-time inventory contracts.
Argentina
Buenos Aires cafe culture expansion outpaces skilled artisan baker availability, driving frozen croissant demand among European-style espresso bars. The national food code enforces trans-fat labeling and shelf-life declaration requirements that reshape formulation specifications for industrial bakery operators. Mendoza's wine tourism corridor generates hotel banquet demand for frozen layer cakes and pastry assortments.
Colombia
Bogotá-based logistics firms with blast freezing capacity serve as gatekeepers for secondary city penetration into Medellín and Cali, opening white-space territory for par-baked product lines. The national pharmaceutical and food regulator shapes import clearance protocols for frozen dough formulations entering through Caribbean ports. Barranquilla's port infrastructure supports temperature-controlled warehousing investments targeting Andean distribution.
Chile
Santiago hotel chains represent the fastest-adopting segment for subscription freezer-to-oven service packages, trading capital expenditure for per-unit operational flexibility. The national economic prosecutor enforces competition standards that shape distributor consolidation patterns across the central valley. Valparaíso's port cluster enables refrigerated export logistics for bakery processors serving Pacific Rim markets.
Latin America Frozen Bakery Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across Latin America's frozen bakery sector. Integrated wheat-to-retail conglomerates maintain margin control through captive supply chains, while specialized frozen dough formulators rely on third-party cold logistics. Three archetypes dominate: vertically integrated food conglomerates with flour milling assets, European-origin frozen dough specialists, and North American packaged food multinationals. Competitive moves concentrate on cold chain partnerships and formulation licensing rather than capacity expansion.
Among Mexico-based integrated food conglomerates, Grupo Bimbo S.A.B exemplifies backward integration into wheat sourcing and distribution infrastructure. European-origin specialists Europastry S.A and Aryzta AG occupy positions anchored in frozen dough formulation capabilities for cafe and foodservice channels. Associated British Foods Plc represents brand-driven retail channel competition across Andean markets. These three archetypes illustrate how geographic origin and supply chain configuration shape competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Grupo Bimbo S.A.B |
| General Mills Inc |
| Europastry S.A |
| Aryzta AG |
| Lantmannen Unibake |
| Vandemoortele |
| Associated British Foods Plc |
| Bridgford Foods Corp |
| Conagra Brands Inc |
| Others |
Supply Flow & Price Mechanics
Quick-service restaurant labor cost pressures across São Paulo and Rio de Janeiro are forcing frozen bakery suppliers to absorb efficiency gains into pricing, compressing margins for processors lacking captive wheat sourcing or blast freezing capacity. This demand-side squeeze reshapes how regional producers configure ingredient procurement and cold logistics investments.
Pricing Analysis
Margin tightening in par-baked bread reflects wheat price volatility from Argentina's drought-prone Pampas region and the capital intensity of refrigerated warehousing. Three-tier pricing structure across premium laminated croissants, standard par-baked loaves, and economy frozen pastries separates formulation complexity tiers. Pricing pressure stems from quick-service restaurant chains consolidating procurement volumes. Mid-sized restaurant operators exhibit highest price sensitivity; hotel banquet buyers accept premium positioning for consistent supply.
Supply Chain Analysis
Domestic-content mandates under Mercosur harmonization talks are reshaping sourcing patterns, pressuring multinational suppliers to localize wheat milling and emulsifier blending. Supply concentrates in Brazil, Mexico, and Argentina as regional flour mill hubs. Modified starches, specialized emulsifiers, and laminated dough equipment feed from global chemical and machinery suppliers. Single-source vulnerability pervades last-mile refrigerated transport in Colombia and Peru. Distribution runs through direct sales to quick-service chains, wholesalers with captive cold storage, and emerging digital procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blast freezing capacity scarcity across Chile and Ecuador props pricing for processors with installed equipment, creating a supply-constrained market where cold infrastructure ownership determines competitive viability.
For Market Incumbents: Anchor market position through backward integration into wheat sourcing and distribution infrastructure, mirroring Grupo Bimbo's captive supply chain model. Defend against Europastry's frozen dough specialization by investing in modified starch formulation R&D. Prioritize certification investments for ANVISA and COFEPRIS dual-jurisdiction compliance as regulatory harmonization accelerates.
For New Entrants and Emerging Players: Enter via Colombian secondary city corridors where Bogotá-based logistics firms lack dedicated frozen bakery distributors, opening white-space territory for par-baked product lines. Target Medellín and Cali foodservice clusters with subscription freezer-to-oven service packages that eliminate capital expenditure barriers for mid-sized restaurant operators.
For Investors and Strategic Acquirers: The window for entry favors logistics firms with blast freezing assets and regional distribution networks. Long-term viability hinges on cold chain infrastructure ownership rather than brand equity alone. Monitor Mercosur harmonization implementation as the inflection signal for cross-border manufacturing footprint consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Blast freezing investments in Curitiba and Bajío Region unlock secondary city penetration previously blocked by temperature-control gaps. |
| Backward Integration into Wheat Sourcing | Captive flour milling insulates margins from Argentina Pampas harvest variability and compresses input cost exposure. |
| Subscription Service Model Launch | Freezer-to-oven packages displace equipment ownership among São Paulo and Mexico City restaurant chains, trading capex for recurring revenue. |
| Regulatory Compliance Certification | ANVISA and COFEPRIS dual-jurisdiction qualification accelerates national distribution network access for frozen dough suppliers. |
| Modified Starch Formulation Licensing | Technology partnerships address post-thaw texture consistency demands scarce among traditional Latin American bakery operations. |
Methodological Framework
Multi-period observation of cold chain infrastructure investments, quick-service restaurant procurement patterns, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with frozen bakery plant managers, quick-service franchise operators, supermarket category buyers, and logistics firm executives. Secondary validation drew from ANVISA and COFEPRIS regulatory databases, customs and trade flow records, and SEC filings of publicly traded food conglomerates. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting across product type, end user, distribution channel, and packaging format calibrated volume and value outputs over the projection horizon. CAGRs derived from modeled adoption curves for par-baked bread in Brazilian quick-service chains and frozen croissant penetration in Buenos Aires cafe culture. Industry-specific inputs included wheat price volatility indices and cold storage capacity utilization rates by metropolitan corridor.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mercosur regulatory harmonization delays or Argentina harvest disruption scenarios. Assumptions reflect documented cold chain investment pipelines and supermarket in-store bakery expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bread Dough Improver Market
Bakery Products
Fondant Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Low Calorie Flour Market
Bakery Products
Gluten-Free Bakery Premixes Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Soft Biscuit Market
Bakery Products
United States Bread Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Instant Cake Emulsifier Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Bake Stable Pastry Fillings Market