
 Food Additives Market | 2026-2036
Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Food Additives Market Analysis
Clean-label fermentation technology is fragmenting traditional synthetic additive supply chains. Cargill, Incorporated leverages its integrated fermentation platforms to anchor natural preservative output. Kerry Group plc competes through specialized clean-label flavor systems for beverage clients. Chr. Hansen Holding A/S dominates dairy culture and natural colorant segments with sustained R&D intensity.
Food additives comprise substances added to food products to preserve flavor, enhance taste, improve appearance, or maintain safety and shelf stability, including compounds such as benzoates, sorbates, lecithin, and annatto extracts manufactured through chemical synthesis, microbial fermentation, or solvent extraction. Their primary commercial purpose centers on enabling mass-scale food processing while meeting sensory and safety specifications across distributed supply chains. Preservatives command the largest volume position due to shelf-life requirements in emerging retail channels, while flavor enhancers capture expanding margin pools as beverage brands reformulate around reduced-sodium and umami profiles. Emulsifiers are gaining fastest in dairy alternatives and plant-based beverages where fat-protein stabilization proves critical.
EFSA operates the centralized risk assessment framework governing additive approvals across European markets, while the FDA maintains the GRAS self-affirmation pathway that shapes US market entry dynamics. China's NMPA and SAMR enforce GB standard compliance for imported additive formulations, creating divergent testing and documentation requirements. Stakeholders must monitor regulatory divergence between jurisdictions to prioritize reformulation investments and avoid market access disruptions.
Market Dynamics
Fermentation-derived clean-label additives are fragmenting legacy synthetic supply chains as beverage manufacturers accelerate reformulation timelines to meet retailer clean-shelf policies.
Growth Catalysts
- EFSA Re-evaluation Mandate:The European Union's additive safety review program is forcing manufacturers toward natural preservative alternatives, expanding addressable demand for microbial fermentation platforms.
- Plant-based beverage expansion:Dairy alternatives in China and Southeast Asia require specialized emulsifier systems for fat-protein stabilization, driving technical additive innovation.
- Reduced-sodium formulation:Umami-enhancer demand from processed snack and ready-meal producers is pulling flavor modifier volumes as salt-replacement strategies mature.
Market Restraints
- Natural extract supply volatility:Annatto, beet, and turmeric colorant harvests face climate-driven yield fluctuations, compressing margin stability for natural colorant suppliers.
- Regulatory documentation burden:China's SAMR enforces divergent GB standard testing protocols for imported additives, extending market entry timelines and compliance costs.
- Technical performance gaps:Clean-label preservatives demonstrate shorter effective shelf-life windows than synthetic benzoates in ambient-distribution channels.
Strategic Opportunities
- India processed dairy penetration:FSSAI-compliant emulsifier systems for paneer, yogurt, and ice cream applications remain underdeveloped relative to volume potential.
- Fermentation-as-a-service platforms:Contract manufacturing infrastructure for natural preservative production enables capital-light market entry for ingredient innovators.
- EU Green Deal alignment:Bio-based additive production pathways qualify for preferential financing and public procurement scoring under sustainability taxonomy rules.
Industry Challenges
- Microbiome characterization expertise:Strain selection and metabolic pathway optimization for fermentation-derived additives requires scarce synthetic biology talent pools.
- Multi-jurisdiction dossier management:Parallel FDA GRAS self-affirmation, EFSA scientific opinion, and NMPA registration processes strain regulatory affairs bandwidth.
- Legacy equipment retrofit costs:Synthetic additive production lines require substantial capital reconfiguration to handle live culture fermentation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Additives Market |
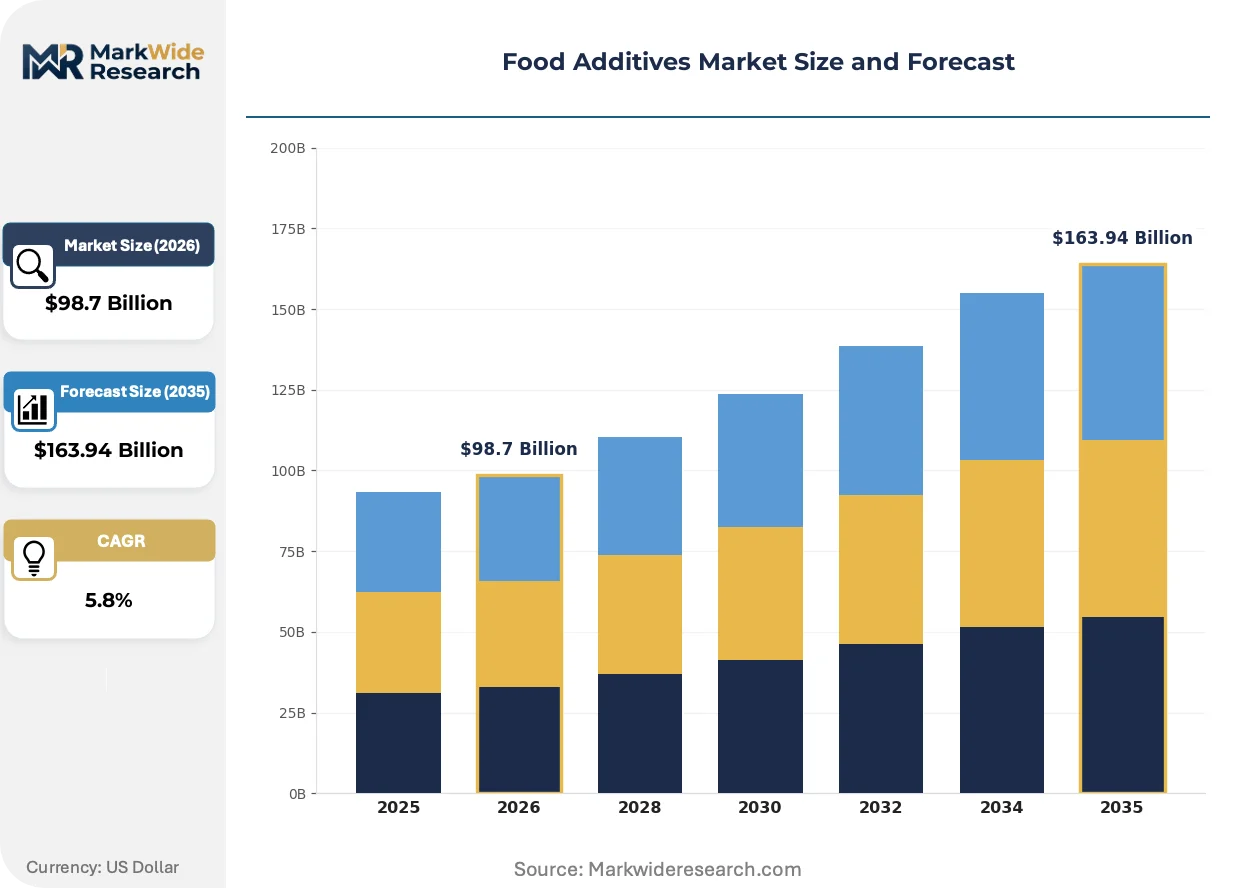
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colorants, Emulsifiers Application: Beverages, Bakery Products, Dairy Products, Snacks End User: Food Processing, Food Service, Retail, Households Form: Powder, Liquid, Granulated, Concentrate |
| Companies Covered | International Flavors and Fragrances Inc., Ingredion Incorporated, Cargill, Incorporated, Givaudan, Tate & Lyle, BASF SE, Kerry Group plc, Chr. Hansen Holding A/S, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Additives Market Emerging Trajectories
Digital formulation platforms and precision fermentation are compressing additive development cycles while regulatory reclassification pressures accelerate technical substitution across preservative and colorant categories.
Precision fermentation for natural preservative production is virtualizing traditional chemical synthesis pathways. Beverage and clean-label dairy manufacturers in Western Europe and North America are scaling procurement of nisin and natamycin from microbial sources. This biotechnology shift is virtualizing capital allocation away from petrochemical feedstock dependencies toward bioreactor infrastructure.
REACH authorization requirements for synthetic colorants are tightening industrial substitution timelines. ECHA's sunset date enforcement for azo dyes and titanium dioxide nanoparticles is redirecting R&D expenditure toward plant-extract alternatives. Confectionery and beverage applications in Germany, France, and Italy are experiencing the most acute formulation pressure as existing stockpiles deplete.
Direct-supplier relationships between additive producers and retail private-label brands are compressing traditional distributor intermediaries. Large-format grocery chains in the United States and United Kingdom are building in-house technical teams to specify custom preservative and flavor systems. This channel restructuring is most visible in store-brand beverage and snack categories where speed-to-shelf determines competitive positioning.
Food Additives Market Segmentation
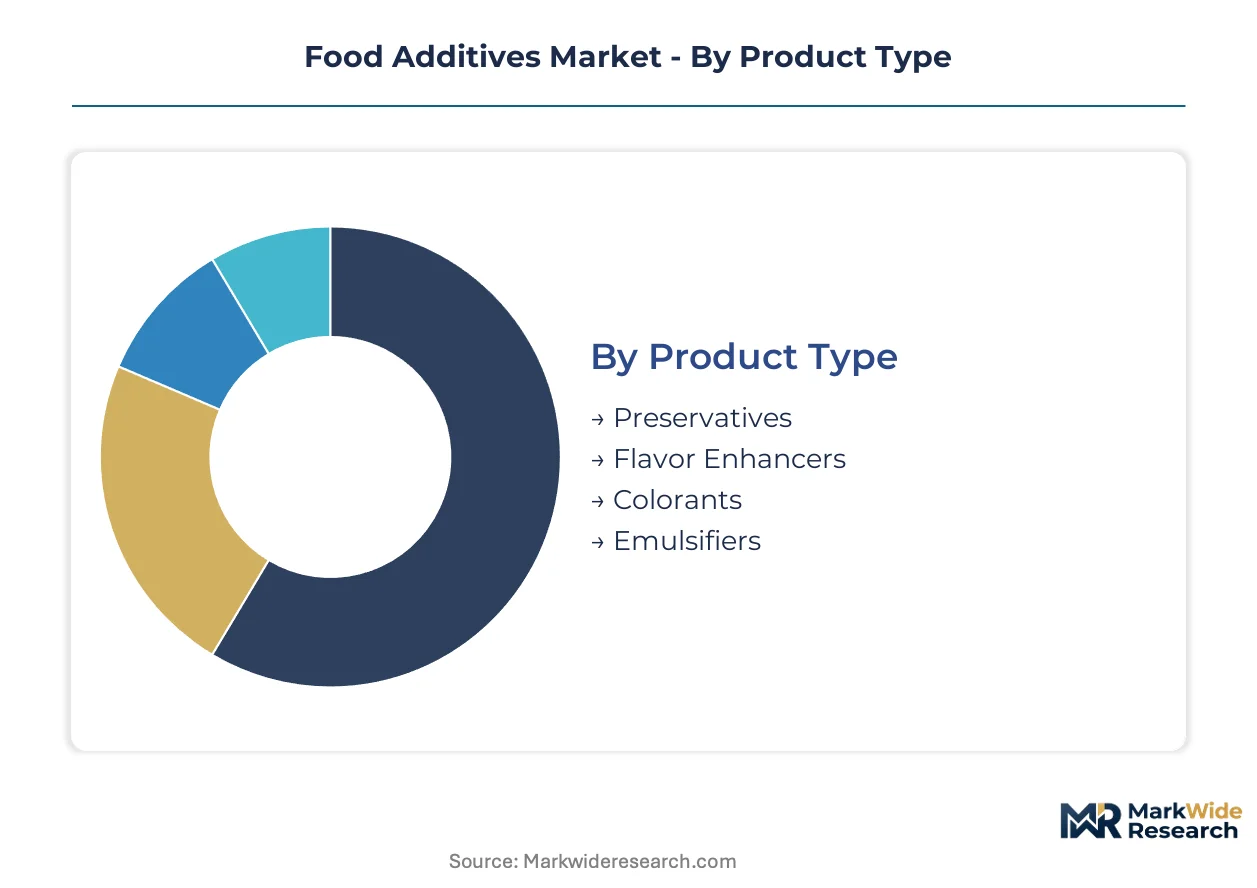
Segmentation in food additives reveals distinct performance profiles across functional chemistry, end-use processing requirements, and delivery formats. Manufacturers align R&D portfolios and fermentation capacity against these dimensions to capture margin pools in reformulation-driven markets.
Product Type:
Functional chemistry determines manufacturing infrastructure requirements and regulatory dossier complexity across preservative, flavor, colorant, and emulsifier platforms.
- Preservatives:Benzoates, sorbates, and fermentation-derived nisin and natamycin inhibit microbial spoilage in ambient-distribution products. Beverage manufacturers in Germany and France are accelerating procurement of microbial alternatives as EFSA re-evaluation tightens synthetic approval thresholds.
- Flavor Enhancers:Monosodium glutamate, yeast extracts, and nucleotides amplify umami perception in reduced-sodium formulations. Processed snack producers in China are pulling volumes for salt-replacement strategies in instant noodle and savory cracker applications.
- Colorants:Annatto, turmeric, beet, and anthocyanin extracts provide hue stability without synthetic azo dyes. REACH sunset dates for titanium dioxide nanoparticles are redirecting confectionery R&D toward plant-extract alternatives.
- Emulsifiers:Lecithin, mono- and diglycerides, and polysorbates stabilize fat-protein matrices in dairy alternatives. Oat and almond beverage processors require specialized systems for mouthfeel consistency.
Preservatives hold installed capacity. Emulsifiers are rotating up the share rankings.
Application:
End-use processing conditions dictate additive specification, thermal stability requirements, and clean-label compliance thresholds.
- Beverages:Carbonated soft drinks, juices, and functional waters demand acid-stable preservatives and natural colorants with light-fastness. Clean-shelf policies at US and UK retail chains are compressing reformulation timelines for private-label suppliers.
- Bakery Products:Bread, cakes, and pastries require mold inhibitors and emulsifiers for crumb structure and shelf-life extension. Artisan and industrial bakeries diverge on synthetic versus natural preservative tolerance.
- Dairy Products:Yogurt, cheese, and ice cream applications depend on cultures, stabilizers, and colorants for texture and visual appeal. Plant-based dairy alternatives in China and Southeast Asia are driving emulsifier innovation for fat-protein stabilization.
- Snacks:Savory crackers, chips, and extruded products utilize flavor enhancers and colorants for sensory differentiation. Reduced-sodium formulation mandates are expanding umami-modifier procurement from processed snack producers.
Beverages anchor current formulation expenditure. Snacks are climbing the fastest on flavor-system reinvestment.
End User:
Customer type shapes volume scale, technical service intensity, and specification authority in additive procurement.
- Food Processing:Large-scale manufacturers of packaged goods operate direct-supplier relationships and custom formulation programs. These buyers specify preservative systems and emulsifier blends for multi-SKU portfolios.
- Food Service:Restaurant chains and institutional caterers require pre-mixed seasoning and colorant solutions for menu consistency. Procurement concentrates on shelf-stable concentrates and liquid delivery formats.
- Retail:Private-label brands at grocery chains are building in-house technical teams to specify custom additive systems. This channel compression is most visible in store-brand beverages and snacks.
- Households:Consumer-packaged additives for home baking and preservation represent a niche convenience segment. Powder and small-format liquid products dominate this channel.
Food Processing holds installed capacity. Retail is rotating up the share rankings.
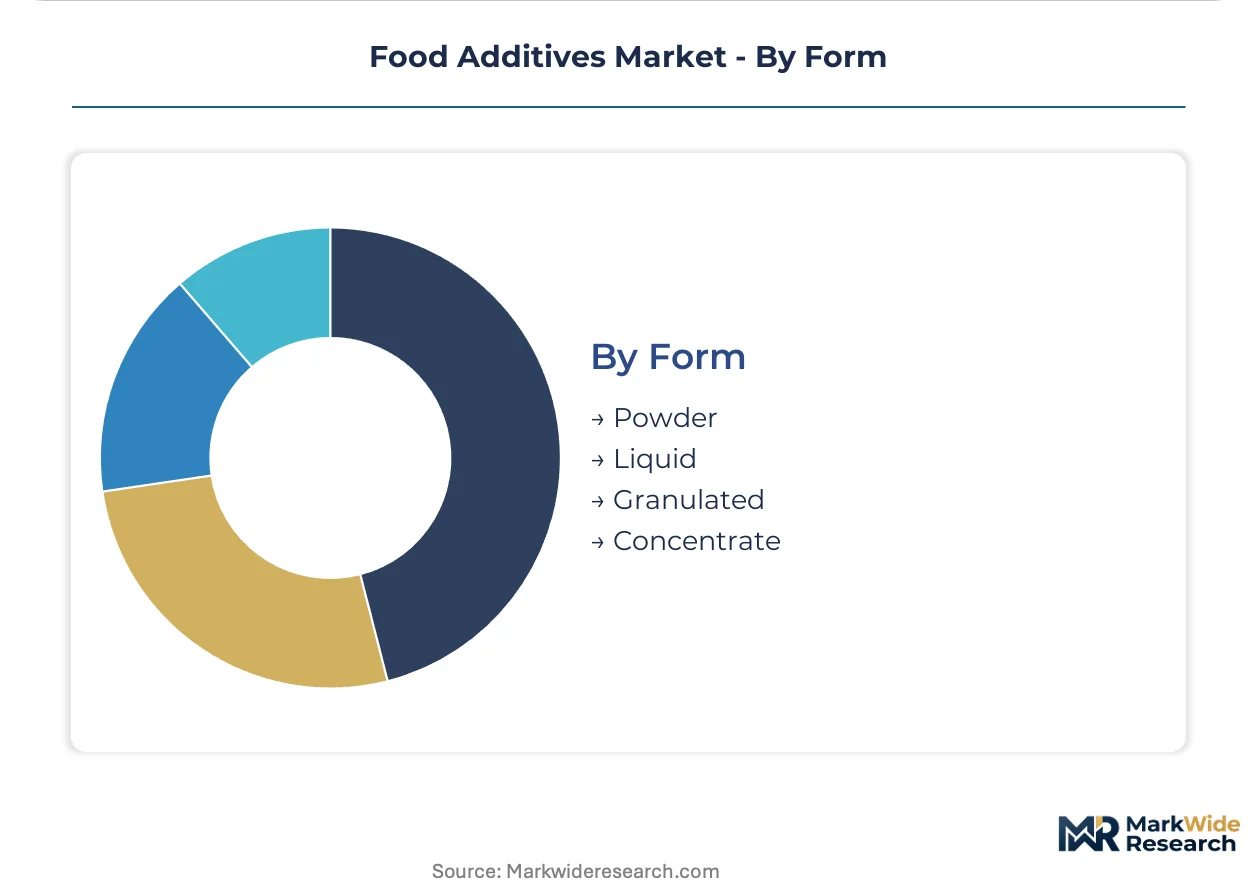
Form:
Physical delivery format determines handling equipment compatibility, dissolution kinetics, and stability during distribution.
- Powder:Spray-dried preservatives, flavor enhancers, and colorants offer extended shelf stability and bulk handling efficiency. Dry blending operations in bakery and snack manufacturing favor this format for precise dosing.
- Liquid:Aqueous and oil-based solutions enable rapid incorporation into beverage and dairy processing lines. Pumpable delivery reduces dust exposure and improves worker safety in high-volume plants.
- Granulated:Agglomerated particles improve flowability and reduce caking in humid storage conditions. This format bridges powder handling efficiency with liquid dissolution speed.
- Concentrate:High-potency formulations minimize transport costs and require dilution at point of use. Food service and industrial processors favor concentrates for inventory optimization.
Powder holds installed capacity. Liquid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese emulsifier and flavor enhancer exports flow into Southeast Asian dairy processing plants and European beverage reformulation programs. German natural preservative platforms supply French and Italian clean-label manufacturers facing EFSA re-evaluation deadlines. US fermentation-derived colorant production serves Mexican and Canadian private-label retail chains.
China
Processed dairy and plant-based beverage expansion in Shanghai and Guangdong provinces drives emulsifier procurement for oat and almond milk stabilization. SAMR enforces GB standard compliance for imported additive formulations, extending documentation timelines for foreign suppliers. Yangtze River Delta concentration of dairy alternative manufacturers anchors regional technical service demand.
Germany
Beverage clean-shelf policies at Aldi and Lidl headquarters accelerate natural preservative substitution for synthetic benzoates. EFSA-led additive re-evaluation tightens approval thresholds for azo dyes and titanium dioxide nanoparticles. Cologne-Düsseldorf corridor hosts fermentation platform investments serving pan-European dairy culture supply.
United States
Private-label retail chains in Chicago and Minneapolis build in-house technical teams for custom preservative specification in store-brand beverages. FDA GRAS self-affirmation pathway shapes faster market entry for microbial-derived colorants versus EFSA timelines. California-based precision fermentation startups supply natamycin to national snack producers.
India
FSSAI-compliant emulsifier systems for paneer, yogurt, and ice cream applications remain underdeveloped against volume potential in Maharashtra and Gujarat. Central food safety regulator mandates additive labeling disclosure exceeding current supplier documentation capacity. Mumbai-Pune industrial corridor concentrates dairy processing investment requiring technical additive partnerships.
Brazil
Processed meat and snack manufacturers in São Paulo state pull flavor enhancer volumes for reduced-sodium formulation strategies. ANVISA maintains additive approval pathways divergent from FDA and EFSA dossier requirements, complicating multinational portfolio standardization. Campinas cluster anchors South American distribution for imported emulsifier systems.
Food Additives Market Vendor Landscape
On the supply side, the industry is consolidating around integrated fermentation platforms and specialized clean-label flavor systems. Tiered competitive structure separates multinational ingredient conglomerates with captive bioreactor capacity from regional specialists in single functional categories. Two strategic archetypes dominate: biotechnology-anchored natural preservative producers and dairy-culture specialists with sustained R&D intensity. Dominant competitive moves include backward integration into microbial strain development and geographic expansion through fermentation-as-a-service licensing.
Within the integrated biotechnology tier, Cargill, Incorporated and Chr. Hansen Holding A/S exemplify divergent scale-positioning strategies. Kerry Group plc occupies a specialist position in clean-label flavor systems for beverage sector clients. These three entities anchor competitive intensity around fermentation platform deployment and regulatory dossier management across FDA, EFSA, and NMPA jurisdictions.
| Leading Market Players |
|---|
| International Flavors and Fragrances Inc. |
| Ingredion Incorporated |
| Cargill, Incorporated |
| Givaudan |
| Tate & Lyle |
| BASF SE |
| Kerry Group plc |
| Chr. Hansen Holding A/S |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Fermentation platform concentration in Germany and Denmark concentrates margin capture for natural preservatives, while downstream beverage manufacturers in France and Italy absorb reformulation premiums. Synthetic benzoate producers in China face margin compression as EFSA re-evaluation redirects procurement toward microbial-derived alternatives.
Pricing Analysis
Synthetic-to-natural technology-generation pricing gaps stratify the market into three tiers: legacy petrochemical preservatives, mid-range fermentation-derived alternatives, and premium precision-fermentation specialty actives. Price differentiation rests on certification tier—EFSA-approved natural preservatives command substantial premiums over self-affirmed GRAS equivalents—and volume scale, with industrial-scale beverage contracts compressing unit economics. Pricing pressure stems from annatto and turmeric harvest volatility, which squeezes natural colorant margins. Large-format retail chains exhibit highest price sensitivity, while specialized dairy culture buyers prioritize performance over cost.
Supply Chain Analysis
Upstream feedstock dependence on corn-derived dextrose and sugar beet molasses ties fermentation capacity to agricultural commodity cycles in the United States, Brazil, and Ukraine. Raw material procurement draws from petrochemical naphtha streams for synthetic benzoates, phospholipid-rich oilseeds for lecithin emulsifiers, and annatto seed harvests from Brazil and Kenya for natural colorants. Single-source vulnerability concentrates in microbial strain banks held by Chr. Hansen and specialized culture collections. Distribution runs through integrated ingredient distributors serving food processing conglomerates, with direct-supplier relationships compressing traditional intermediary tiers at large retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strategic advantage in food additives accrues to entities commanding scarce fermentation microbiology expertise and multi-jurisdiction regulatory dossier capabilities, with synthetic biology talent pools constraining platform expansion timelines.
For Market Incumbents: Entrench market position through backward integration into proprietary strain development programs and captive bioreactor capacity additions in the Cologne-Düsseldorf corridor. Cargill and Chr. Hansen must defend against precision-fermentation startups by accelerating EFSA natural preservative approval timelines and locking exclusive supply contracts with Aldi and Lidl clean-shelf programs. Regulatory dossier bandwidth represents the critical lever for multi-market presence. For New Entrants and Emerging Players: Pursue fermentation-as-a-service licensing models to bypass capital-heavy infrastructure requirements and target India's underdeveloped FSSAI-compliant emulsifier segment for paneer and yogurt applications. White-space concentration sits in contract manufacturing for natural preservatives, with technical service partnerships offering the strongest go-to-market pathway against integrated multinational incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward precision-fermentation platforms with demonstrated strain optimization capabilities and existing GRAS self-affirmation pathways. Long-term viability across the projection horizon favors biotechnology-anchored natural preservative producers over legacy synthetic chemical operations. Watch EFSA re-evaluation sunset date announcements as the inflection signal for accelerated substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive microbial libraries reduce licensing costs and accelerate proprietary natural preservative pipelines for EFSA submission. |
| Fermentation-as-a-Service Licensing | Capital-light expansion enables regional specialists to access bioreactor capacity without fixed asset commitment in Germany. |
| EFSA-NMPA Parallel Dossier Filing | Simultaneous regulatory approval processes compress market entry timelines across European and Chinese dairy additive demand. |
| Direct-Supplier Relationship with Retail Chains | Bypassing distributor intermediaries secures specification authority in Aldi and Lidl private-label beverage reformulation programs. |
| Precision Fermentation Platform Investment | Bioreactor infrastructure virtualizes capital allocation away from petrochemical dependencies toward nisin and natamycin output. |
Methodological Framework
Cross-validation between primary interviews with fermentation platform executives, regulatory affairs directors at multinational ingredient suppliers, and dairy processing procurement leads anchors the qualitative findings in operational reality. Secondary validation draws from EFSA scientific opinion databases, FDA GRAS notification filings, SAMR GB standard publications, and customs trade flow records for emulsifier and preservative categories. Bottom-up triangulation across individual additive functional segments and top-down reconciliation against aggregate food processing demand completes the analytical foundation.
Calibration against historical volume trajectories in preservatives, flavor enhancers, colorants, and emulsifiers shapes the projection framework across the analysis window. Segmentation dimensions span functional chemistry, application processing requirements, end-user procurement archetypes, and physical delivery formats, with CAGRs derived from slope-intercept modeling against regulatory re-evaluation timelines and clean-label adoption curves. Fermentation capacity expansion announcements and EFSA sunset date schedules feed directly into forecast sensitivity scenarios.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, energy costs for bioreactor operations, and currency volatility for cross-border strain licensing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory approval timelines and substitution elasticity in beverage reformulation. Cross-checking against EFSA re-evaluation publication schedules and SAMR import registration backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Nutraceutical Excipients Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Food Grade Calcium Lactate Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Preservatives Market