
 Fat-Replacing Starch Market | 2026-2036
Fat-Replacing Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Fat-Replacing Starch Market Foresight
North American modified starch production capacity is hardening as grain processors expand output. Cargill Incorporated leverages its integrated corn supply chain to secure feedstock cost advantages across multiple processing sites. Ingredion Incorporated sustains technology leadership through specialty starch innovation for reduced-fat dairy systems. Tate & Lyle PLC anchors its competitive position with advanced texturizing solutions for bakery applications.
Fat-replacing starch comprises physiochemically or enzymatically altered native starches that mimic the mouthfeel, viscosity, and water-binding properties of lipids in food matrices, typically achieving fat-mimetic functionality at inclusion rates of three to five percent by weight. Modified starch dominates current volume owing to established functionality in emulsion stabilization and freeze-thaw stability, while resistant starch commands premium positioning in gut-health-positioned products and dietary supplements. Baking and dairy applications absorb the majority of demand, with sauces representing a faster-growing outlet as clean-label dressing formulations proliferate.
The FDA governs fat-replacing starch labeling under food additive and GRAS frameworks, while EFSA evaluates novel starch modifications for safety and nutritional claims validity within the EU. BIS standards in India and GB standards in China further shape product specifications for export-oriented manufacturers. Stakeholders must monitor evolving clean-label definitions and regional regulatory divergence when prioritizing R&D investment and geographic expansion sequencing.
Market Dynamics
Clean-label mandates from EFSA and the FDA are forcing food manufacturers to accelerate fat-reduction timelines while preserving sensory performance, creating simultaneous pressure on ingredient functionality and disclosure transparency.
Growth Catalysts
- EFSA clean-label frameworks:Disclosure requirements for modified food starches in the European Union are compelling manufacturers to source enzymatically treated alternatives that meet both functionality and transparency standards.
- Dairy reformulation intensity:Reduced-fat cheese and yogurt systems are absorbing specialty starch volumes as processors target saturated fat reduction without compromising melt and mouthfeel.
- China processed food cluster expansion:GB standards alignment for export-oriented production is concentrating demand for freeze-thaw stable fat replacers in Shandong and Guangdong provinces.
Market Restraints
- Corn price volatility:Feedstock cost swings for waxy maize and tapioca roots are compressing margin structures for modified starch processors without captive agricultural supply.
- Technical ceiling in high-fat replication:Current enzymatic modification protocols fail to replicate lipid crystallization behavior above 40% fat replacement rates in premium bakery applications.
- Resistant starch supply concentration:Production of high-amylose corn varieties for resistant starch extraction concentrates in limited North American germplasm programs, creating germplasm access bottlenecks.
Strategic Opportunities
- India FSSAI clean-label pathway:Emerging domestic processed food capacity in Maharashtra and Karnataka is creating first-mover positioning for enzymatically modified starch suppliers ahead of anticipated disclosure mandates.
- Sauce and dressing white space:Cold-prepared emulsion systems represent an underpenetrated application where clean-label fat replacers can displace gum-stabilized formulations without viscosity trade-offs.
- Dual carbon goals in China:SAMR incentives for reduced-carbon food processing are accelerating interest in physically modified starches that eliminate chemical cross-linking reagents from production.
Industry Challenges
- Enzymologist talent scarcity:Food-grade amylase engineering expertise concentrates in Danish and Dutch biotechnology clusters, constraining R&D velocity for new market entrants.
- Freeze-thaw certification timelines:EFSA novel food consultations for new starch modifications extend 18-24 months, delaying commercialization of next-generation resistant starch variants.
- Legacy dairy equipment incompatibility:High-shear processing requirements for some fat-replacing starch dispersions conflict with existing homogenization infrastructure at mid-scale cheese operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat-Replacing Starch Market |
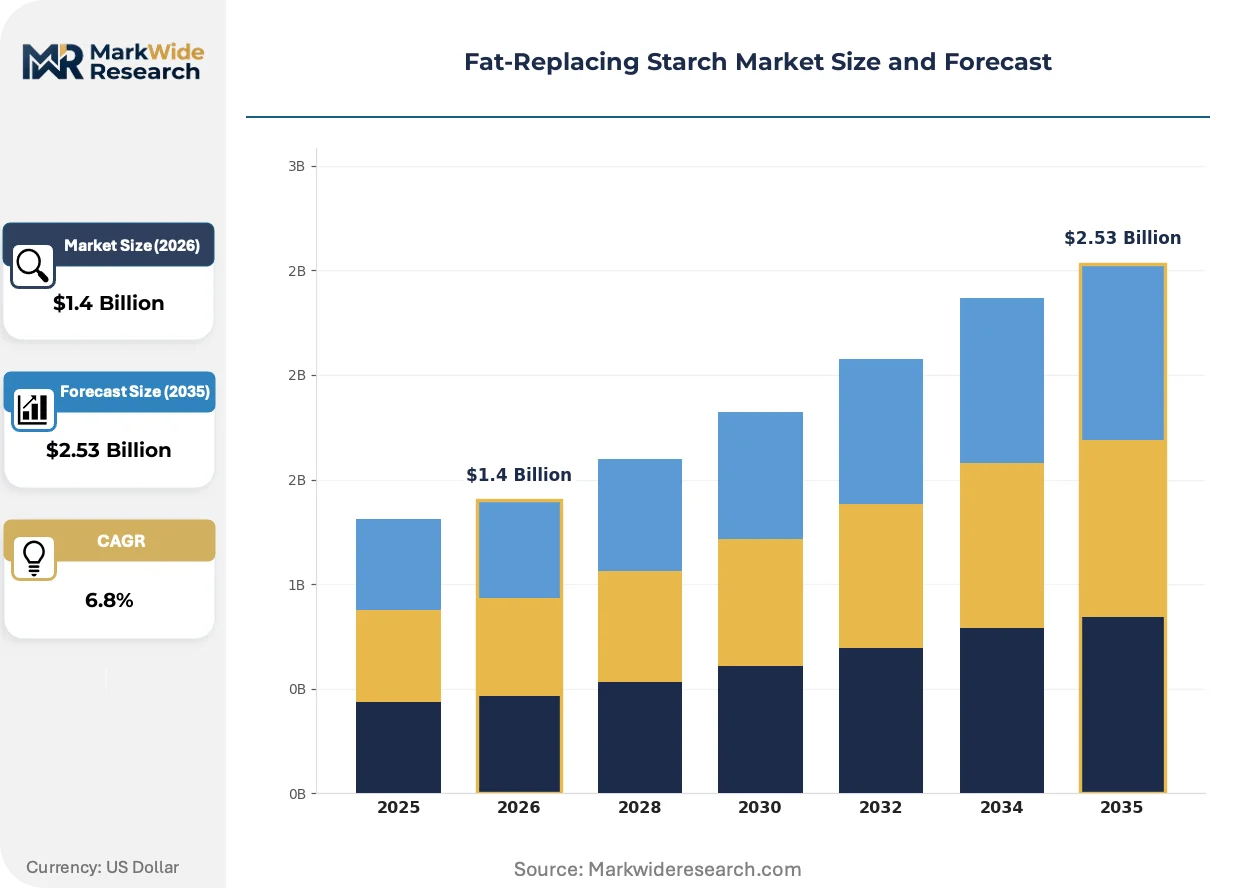
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Resistant Starch, High-Amylose Starch, Other Starches Application: Baking, Dairy Products, Confectionery, Sauces End User: Food Manufacturers, Beverage Producers, Snack Companies, Dietary Supplements Distribution Channel: Online Sales, Direct Sales, Supermarkets, Wholesale Distributors |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Roquette Frères, Royal Avebe UA, Grain Processing Corporation, ADM, Avebe U.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat-Replacing Starch Market Shifts & Advancements
Enzymatic debranching technologies are fragmenting the traditional modified-resistant starch dichotomy, enabling intermediate functionality grades that respond to application-specific viscosity and digestibility requirements.
Enzymatic debranching is modularizing how starch manufacturers configure amylopectin chain lengths for targeted mouthfeel replication. Bakery and dairy formulators in Germany and the United States are adopting these intermediate-grade starches at accelerating pace for reduced-fat croissants and cream cheese alternatives. This technology is compressing the historical gap between commodity modified starch and premium resistant starch price tiers by enabling single-process, multi-functionality outputs.
REACH registration requirements for chemical cross-linking agents used in traditional modified starch production are elevating enzymatic and physical modification methods across EU-based processing. Industrial consequence includes accelerated capital redeployment toward shear-pressure and thermal treatment systems that avoid epichlorohydrin and phosphorus oxychloride reagents. Bakery applications, particularly frozen dough systems, are most affected as manufacturers reformulate to maintain freeze-thaw stability without REACH-registered chemical modifiers.
Specification-driven procurement is consolidating buyer power among multinational food manufacturers who now mandate dual-certified (organic + clean-label) starch supply for premium product lines. Traditional ingredient distributors in France and the United Kingdom are losing share to direct mill relationships as Cargill and Ingredion establish dedicated account structures for strategic dairy and bakery customers. This pattern is most visible in the United States, where private-label retail chains are compressing supplier panels to single-source fat-replacing starch agreements with integrated traceability documentation.
Fat-Replacing Starch Market Segmentation
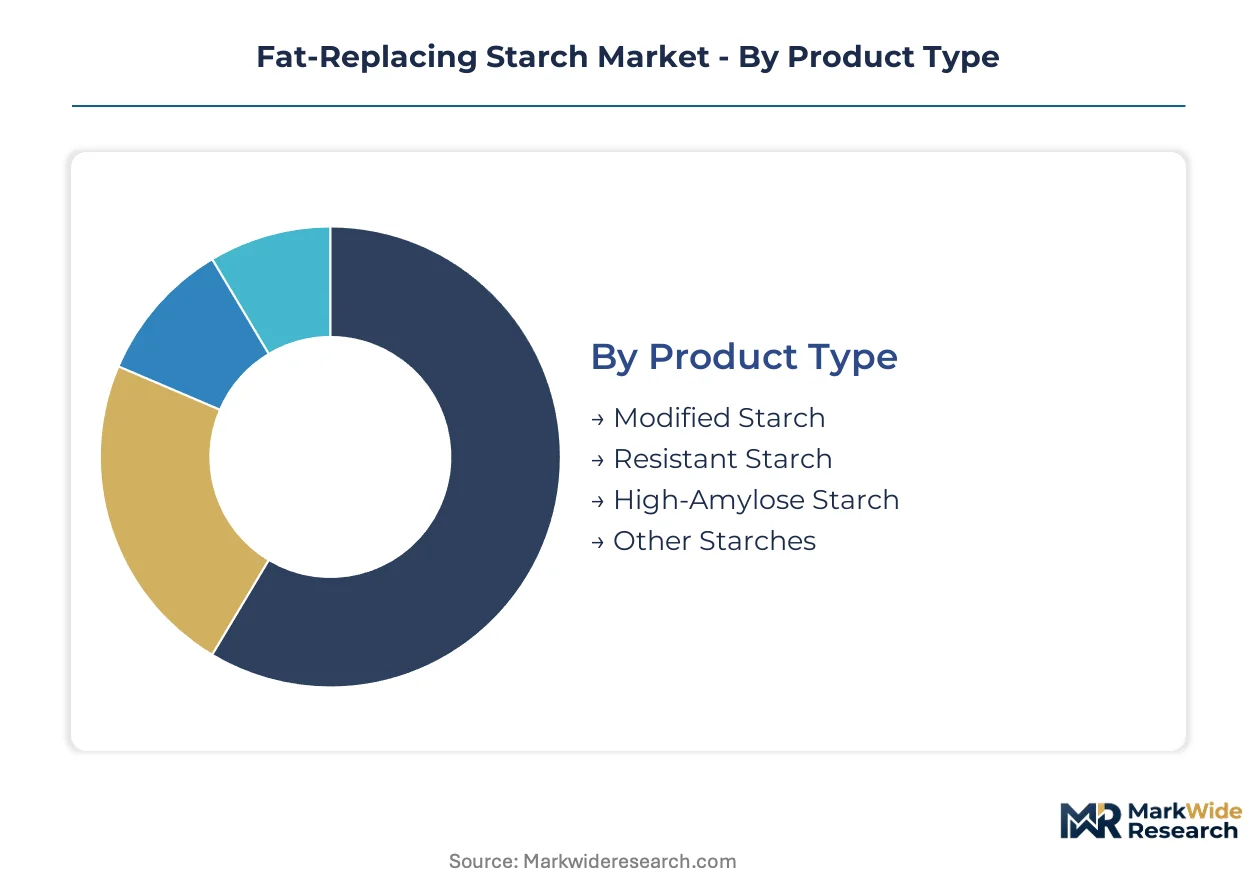
Product differentiation in fat-replacing starches hinges on modification chemistry and amylose content, which determine viscosity profiles and regulatory classification. Procurement teams segment suppliers by functional equivalence to target lipid reduction rates in specific food matrices.
Product Type:
Supply concentration clusters around enzymatic modification capabilities in North American and European grain processing hubs.
- Modified Starch:Physicochemically altered native starches using cross-linking or substitution reactions achieve fat-mimetic functionality at 3-5% inclusion rates. Baking and dairy applications in the United States and Germany absorb the majority of volume as clean-label reformulation accelerates. EFSA disclosure requirements are forcing migration toward enzymatically treated variants that satisfy transparency mandates without sacrificing freeze-thaw stability.
- Resistant Starch:High-amylose extraction and retrogradation techniques yield Type 2 and Type 3 resistant fractions with documented prebiotic effects. Dietary supplement positioning in North America commands premium pricing as gut-health claims proliferate. Germplasm access bottlenecks for high-amylose corn varieties concentrate production among limited North American breeding programs.
- High-Amylose Starch:Amylose content exceeding 50% enables firm gel formation and slow digestibility for controlled-energy applications.
- Other Starches:Native tapioca, potato, and rice starches with minimal modification serve cost-sensitive regional formulators.
Modified starch absorbs the bulk of installed capacity; resistant starch is expanding most quickly.
Application:
Application selection determines shear tolerance requirements and hydration kinetics for starch dispersion systems.
- Baking:Laminated dough systems and cake batters demand starches that replicate shortening plasticity and aeration stability. Frozen dough manufacturers in Germany prioritize freeze-thaw resistant variants as clean-label mandates eliminate chemical cross-linkers from REACH-regulated formulations.
- Dairy Products:Reduced-fat cheese and yogurt matrices require starches that restore melt elasticity and mouthfeel creaminess lost to fat removal. High-shear processing infrastructure at mid-scale operations creates compatibility constraints for certain starch dispersion protocols.
- Confectionery:Fat bloom inhibition and texture modulation in chocolate coatings drive specialty starch adoption.
- Sauces:Cold-prepared emulsion systems represent underpenetrated territory where clean-label starches displace gum stabilizers.
Baking commands the largest share of specialty starch procurement; sauces are climbing the fastest as dressing reformulation proliferates.
End User:
End-user procurement sophistication varies by scale and certification requirements for ingredient traceability.
- Food Manufacturers:Multinational processed food producers mandate dual-certified organic and clean-label supply with integrated documentation. Direct mill relationships are displacing traditional distributors in France and the United Kingdom as specification-driven procurement consolidates buyer power.
- Beverage Producers:Reduced-fat creamers and flavored milk systems require starches with emulsion stabilization and opacity control.
- Snack Companies:Extruded and baked snack applications prioritize cost-efficient modified starches for texture modification.
- Dietary Supplements:Resistant starch positioning for metabolic health claims drives premium sourcing from verified high-amylose supply chains.
Food manufacturers dominate volume contracting; dietary supplements are gaining share fastest on gut-health positioning.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and documentation needs for regulatory compliance.
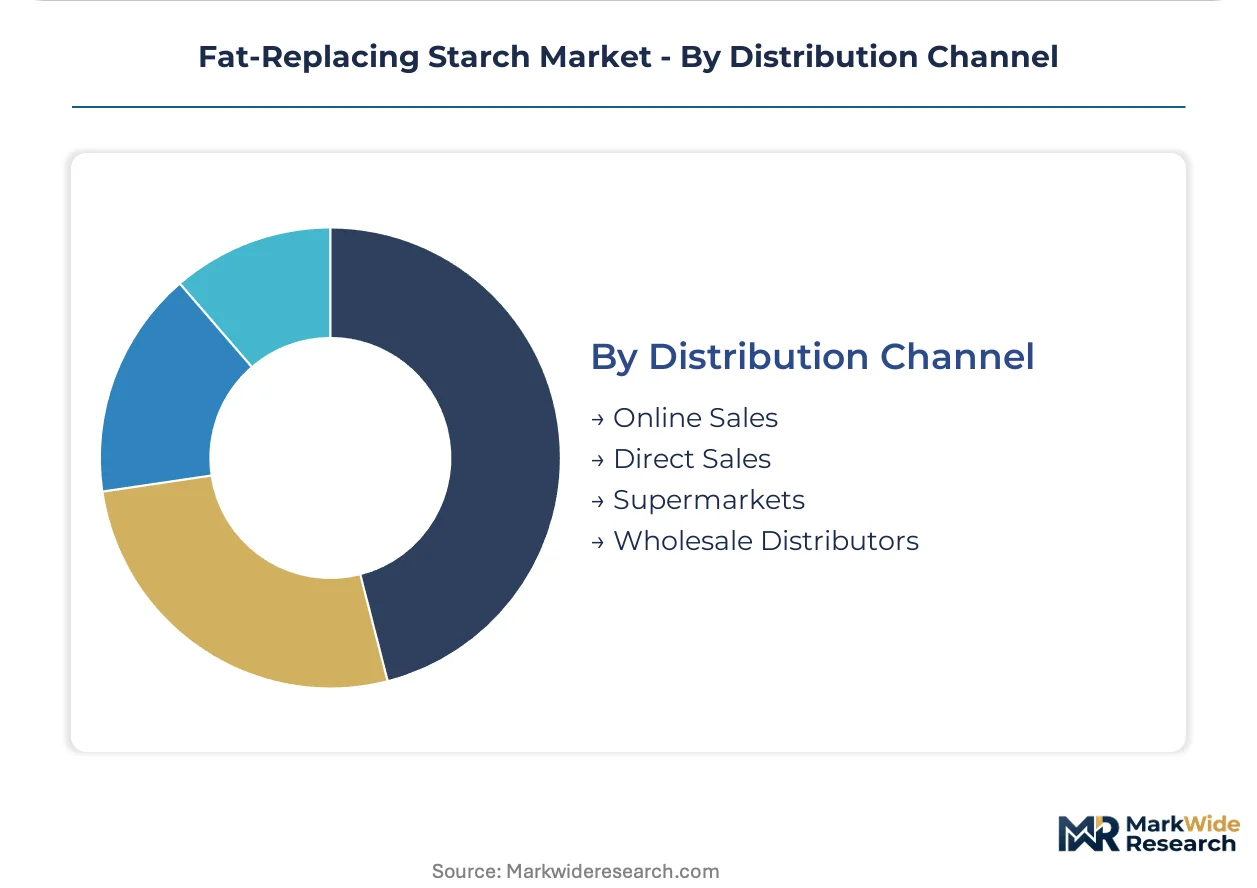
- Direct Sales:Strategic dairy and bakery accounts receive dedicated technical support and custom formulation collaboration. Cargill and Ingredion have established direct account structures that bypass traditional distribution layers for high-volume customers.
- Wholesale Distributors:Regional ingredient distributors serve mid-tier processors with standardized specifications and shorter lead times.
- Online Sales:E-commerce platforms capture small-batch artisan producers and R&D sampling requirements.
- Supermarkets:Limited retail channel presence for industrial-grade fat-replacing starches.
Direct sales anchor the largest contract values; online channels are expanding most quickly for sampling and small-volume procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn and tapioca feedstock availability concentrates starch processing capacity across North American grain belts and Southeast Asian root crop zones. Regulatory divergence between FDA disclosure frameworks and EFSA clean-label mandates shapes geographic investment sequencing. Industrial clusters in the United States, Germany, and China absorb the majority of specialty starch procurement for reduced-fat food reformulation.
United States
Reduced-fat dairy and bakery reformulation drives specialty starch absorption across Midwestern and Northeastern processing corridors. FDA GRAS notification pathways govern novel starch modifications while accelerating enzymatic treatment adoption. Cargill and Ingredion operate integrated processing sites in Iowa and Illinois where captive corn supply secures feedstock cost positioning.
Germany
Frozen dough manufacturers prioritize freeze-thaw stable starches as REACH regulations eliminate chemical cross-linkers from bakery formulations. EFSA disclosure mandates for modified food starches compel migration toward enzymatically treated alternatives. Industrial concentration in Bavaria and North Rhine-Westphalia hosts major dairy and baked goods production clusters demanding clean-label fat replacers.
China
GB standards alignment for export-oriented production concentrates demand in Shandong and Guangdong provinces where processed food manufacturing scales rapidly. SAMR incentives for reduced-carbon food processing accelerate interest in physically modified starches eliminating chemical reagents. Domestic reformulation programs target saturated fat reduction in cheese and yogurt systems for urban consumer bases.
India
Maharashtra and Karnataka processed food capacity expansion creates first-mover positioning for enzymatically modified starch suppliers ahead of anticipated FSSAI disclosure mandates. BIS standards shape product specifications for export-oriented manufacturers supplying Middle Eastern and African markets. Dairy and bakery application growth concentrates in Mumbai-Pune and Bengaluru industrial corridors.
Netherlands
Enzymologist talent scarcity concentrates food-grade amylase engineering expertise in Dutch biotechnology clusters constraining R&D velocity for new market entrants. REACH registration requirements elevate enzymatic modification methods across EU-based processing operations. Rotterdam-Antwerp logistics hubs facilitate starch trade flows between North American suppliers and European formulators.
Fat-Replacing Starch Market Competitive Landscape
Global majors compete with regional champions across supply chain integration and specialty formulation capabilities. The vendor base structures around three tiers: integrated grain processors with captive agricultural supply, specialty starch innovators with dedicated R&D infrastructure, and regional distributors serving mid-tier processors with standardized specifications. Dominant competitive moves include backward integration into germplasm programs for high-amylose corn varieties and direct account structures bypassing traditional distribution layers for strategic dairy and bakery customers.
Among North American integrated processors, Cargill Incorporated and Ingredion Incorporated exemplify the supply-chain-anchored archetype with multi-site processing networks. Tate & Lyle PLC represents the European specialty formulation tier with advanced texturizing solutions positioning. These three entities occupy positions defining competitive intensity through technology leadership and direct customer collaboration structures.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Roquette Frères |
| Royal Avebe UA |
| Grain Processing Corporation |
| ADM |
| Avebe U.A. |
| Others |
Supply & Pricing Matrix
Clean-label procurement mandates from multinational food manufacturers are forcing starch processors to reconfigure production lines toward enzymatic modification methods, compressing margin structures for operators without captive corn supply or integrated technical service capabilities.
Pricing Analysis
Technical service bundling separates contract structures in this market, with integrated suppliers embedding formulation support and freeze-thaw certification assistance into long-term offtake agreements while commodity distributors offer unbundled per-kilogram pricing. Three-tier pricing structure across premium resistant starch, specialty modified grades, and commodity native starches tracks certification level and amylose content. Cost compression in standard modified starch is intensifying because REACH-registered chemical cross-linkers face substitution pressure. Mid-scale dairy processors show highest price sensitivity due to legacy equipment retrofit requirements, while dietary supplement brands absorb premium positioning for gut-health claims.
Supply Chain Analysis
Waxy maize and tapioca root supply rests on North American grain belts and Southeast Asian root crop zones, with germplasm access for high-amylose varieties concentrated in limited United States breeding programs. Key inputs include specialty amylase enzymes, thermal-shear processing equipment, and dual-certified organic supply streams. Single-source vulnerability runs through Dutch and Danish biotechnology clusters where food-grade amylase engineering expertise concentrates. Distribution runs through direct mill relationships for strategic dairy and bakery accounts, with regional distributors serving mid-tier processors on shorter lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic debranching technologies are displacing traditional chemical modification protocols, creating transition-phase positioning for suppliers capable of delivering intermediate-functionality grades that bridge commodity and premium starch tiers.
For Market Incumbents: Extend captive corn supply advantages through backward integration into high-amylose germplasm programs, securing access bottlenecks that constrain resistant starch competitors. Deepen direct account structures with freeze-thaw certification capabilities to defend against enzymatic specialists targeting German frozen dough manufacturers. For New Entrants and Emerging Players: E-commerce sampling platforms offer lower-friction entry for artisan bakery and small-batch sauce formulators seeking clean-label alternatives without minimum order constraints. Target Maharashtra and Karnataka processed food corridors ahead of anticipated FSSAI disclosure mandates, positioning enzymatically treated starches for first-mover advantage in India reformulation programs. For Investors and Strategic Acquirers: The window for entry favors integrated grain processors with existing enzymatic modification infrastructure and established dairy sector relationships. Watch EFSA novel food consultation timelines as inflection indicators, with 18-24 month certification delays creating acquisition opportunities for approved-resistant-starch inventory positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Amylose Germplasm | Captive supply of resistant starch feedstock bypasses North American breeding program bottlenecks. |
| Enzymatic Modification Capacity Expansion | Eliminates REACH-registered chemical reagents from production, aligning with EU clean-label mandates. |
| Direct Technical Service Account Structures | Bypasses traditional French and UK distributors for strategic dairy and bakery procurement consolidation. |
| Freeze-Thaw Certification Investment | Accelerates EFSA novel food pathway velocity for next-generation resistant starch variants. |
| India Market Entry Partnership | Positions ahead of FSSAI disclosure mandates in Maharashtra and Karnataka industrial corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with grain processing plant managers, dairy formulation technologists, starch procurement leads at multinational food manufacturers, and enzymatic modification R&D directors. FDA GRAS notifications, EFSA novel food consultations, BIS standards documentation, and GB compliance records provided regulatory validation. Bottom-up volume modeling triangulated against top-down expenditure analysis across modified and resistant starch categories.
Granularity-level modeling tracked product type, application matrix, end-user procurement sophistication, and distribution channel structure at country-level resolution. CAGRs were derived from segment-specific volume trajectories and value-per-unit trends across the projection horizon. Industry-specific forecast inputs included EFSA consultation timeline assumptions, corn futures volatility bands, and clean-label mandate implementation schedules.
Inputs from grain processor disclosures and regulatory consultation databases were available through the study window; gaps in proprietary enzymatic treatment yield data introduce uncertainty bands around resistant starch supply projections. Forecasts reflect documented assumptions regarding germplasm program expansion rates and REACH substitution timelines. Regulatory divergence between FDA and EFSA frameworks, enzymologist talent scarcity in biotechnology clusters, and corn price volatility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fruit and Vegetable Processing Enzymes Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Distilled Monoglycerides Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Australia Food Colorants Market