
 Egg Stabilizer Market | 2026-2036
Egg Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Egg Stabilizer Market Foresight
Multi-source procurement among industrial bakeries is consolidating around fewer qualified ingredient suppliers with integrated quality systems. Cargill Inc. leverages its global oilseed processing network to secure lecithin feedstocks for emulsifier production. Kerry Group anchors European supply through specialized texture systems tailored to regional bakery traditions. ADM competes on manufacturing scale, operating multiple North American plants that convert egg derivatives into standardized stabilizer blends.
Egg stabilizers comprise functional ingredient systems—typically incorporating phospholipids, proteins, and hydrocolloids—that maintain structural integrity in aerated and emulsified food matrices through controlled viscosity and interfacial tension reduction. Powder stabilizers dominate commercial volumes due to extended shelf stability and lower transport costs versus liquid alternatives, though emulsifiers command premium positioning in clean-label formulations where lecithin and mono-diglyceride blends replace synthetic alternatives. Foam stabilization leads application demand, driven by sponge cake and meringue production requiring consistent overrun control, while thickening applications in custard and sauce bases represent a mature, price-sensitive segment with thinner margin pools.
The FDA governs egg product safety under 21 CFR Part 118, mandating refrigeration standards that shape cold-chain distribution requirements for liquid stabilizer formats. EFSA evaluates emulsifier additives under Regulation 1333/2008, with recent reclassifications of certain phosphates affecting reformulation timelines across EU food processors. China's SAMR implements GB standards for food-grade emulsifiers that foreign suppliers must meet for import clearance. Stakeholders must monitor evolving additive approvals and regional maximum-level restrictions that determine product registration feasibility and reformulation investment cycles.
Market Dynamics
Industrial bakeries are consolidating supplier relationships around integrated quality systems as clean-label mandates intensify reformulation cycles for extended shelf-life products.
Growth Catalysts
- Clean-Label Mandates:EFSA Regulation 1333/2008 reclassifications are accelerating phospholipid adoption in sponge cake and meringue production across EU food processors.
- Cold-Chain Expansion:China's SAMR GB standards for food-grade emulsifiers are unlocking import clearance pathways for liquid stabilizer formats in premium bakery segments.
- Foam Stabilization Demand:Aerated dessert applications in Germany's industrial baking clusters require consistent overrun control, pulling specialized lecithin-protein blends.
Market Restraints
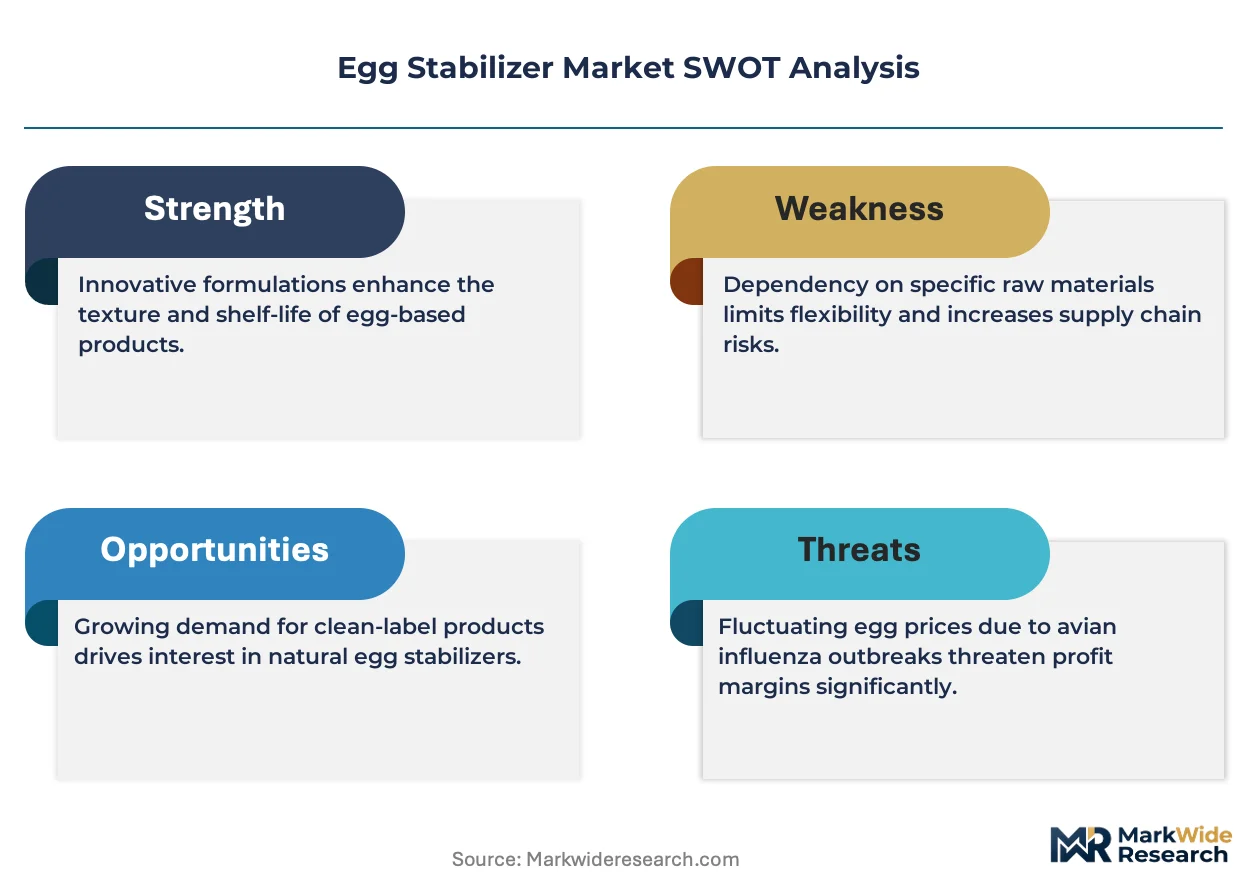
- Feedstock Volatility:Egg-derived phospholipid costs fluctuate with avian influenza cycles and grain pricing, compressing margin pools for standardized stabilizer blends.
- Regulatory Friction:FDA 21 CFR Part 118 refrigeration mandates create distribution cost premiums for liquid formats versus powder alternatives.
- Substitution Pressure:Plant-based emulsifiers from microbial fermentation and algal sources are capturing share in vegan-certified bakery applications.
Strategic Opportunities
- Underpenetrated Geographies:India's FSSAI emulsifier approvals lag EU timelines, creating first-mover windows for phospholipid suppliers establishing local technical service.
- Technology Convergence:Encapsulation systems combining hydrocolloids with modified starches enable heat-stable foam structures for microwaveable bakery products.
- Channel Innovation:Direct-to-bakery technical service models bypass traditional ingredient distributors, capturing formulation data and shortening development cycles.
Industry Challenges
- Formulation Expertise Gap:Industrial bakeries lack in-house emulsion science capability, forcing stabilizer suppliers to absorb technical service costs.
- Certification Timelines:Novel hydrocolloid approvals under FDA GRAS self-determination and EFSA food additive petitions extend commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egg Stabilizer Market |
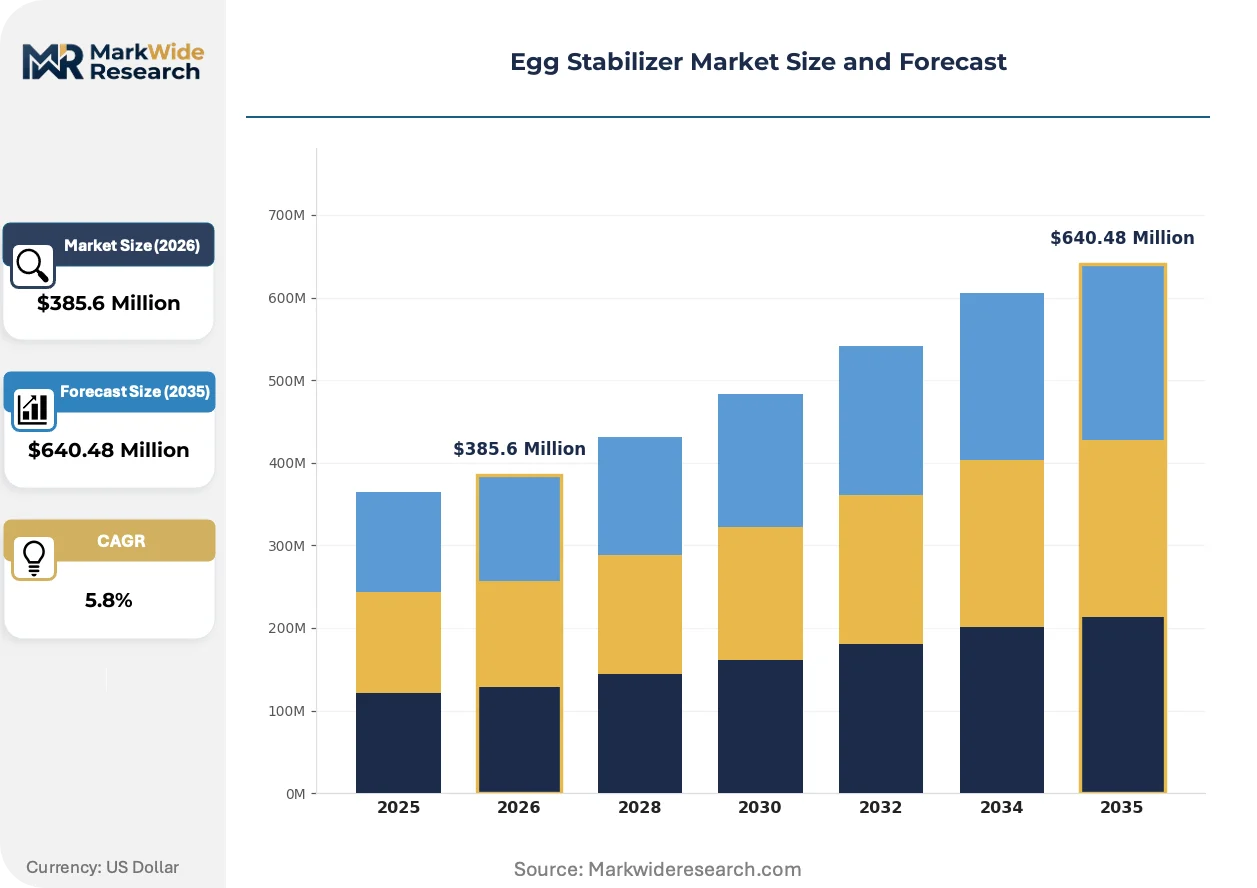
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Stabilizers, Powder Stabilizers, Emulsifiers, Gels End Use Industry: Food Processing, Bakery, Confectionery, Dairy Application: Foam Stabilization, Emulsification, Thickening, Texturizing Packaging Type: Bottles, Pouches, Tubs, Bulk Containers |
| Companies Covered | ADM, J and K Ingredients, Cargill Inc., TIC Gums, Holton Food Products, Ingredion Incorporated, Kerry Group, Merck KGaA, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egg Stabilizer Market Shifts & Advancements
Formulation science is pivoting toward hybrid stabilizer systems that reconcile clean-label positioning with functional performance in heat-stressed applications.
Enzyme-modified lecithin is consolidating its position as the preferred phospholipid source for premium bakery applications. Artisan and industrial bakers in France and Italy are adopting these variants at accelerating rates for improved emulsion stability in high-fat sponge formulations. This consolidation is compressing demand for standard fluid lecithin while elevating supplier technical differentiation.
REACH compliance requirements for emulsifier manufacturing are tightening impurity thresholds for solvent residues in lecithin extraction processes. EU-based processors face reformulation investments to meet updated ECHA guidance on processing aids. German and Dutch stabilizer blenders are most affected, accelerating partnerships with certified oilseed processors.
Specification-driven procurement is shortening supplier qualification cycles as industrial bakeries centralize ingredient decisions under technical directors. Regional distributors with formulation support capabilities are displacing commodity traders in France, Spain, and Poland. This shift is most visible in mid-cap bakery groups consolidating multi-site contracts for cost and quality consistency.
Egg Stabilizer Market Segmentation
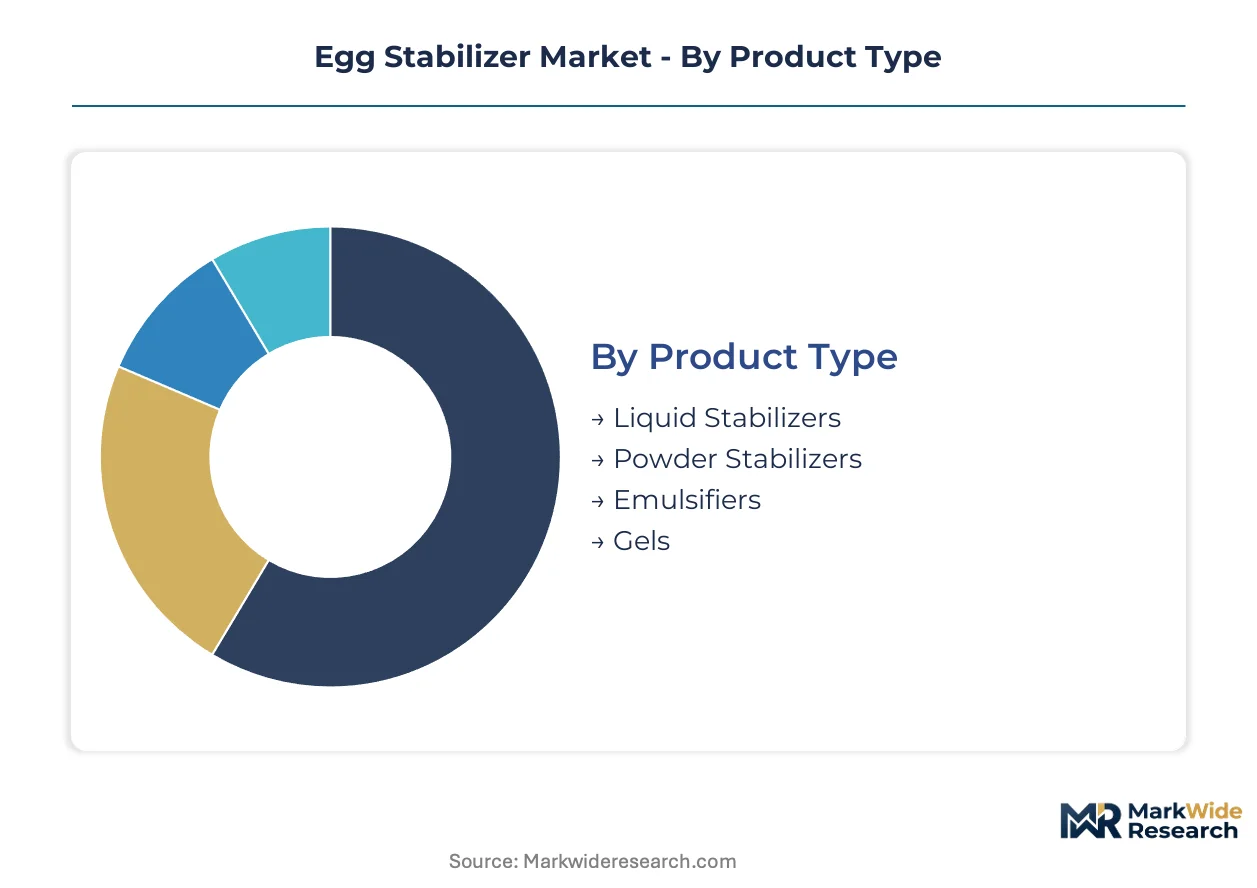
Egg stabilizer procurement patterns diverge sharply across product formats and end-use specifications, with industrial buyers segmenting suppliers by cold-chain capability, clean-label certification, and regional formulation support.
Product Type:
Supply concentration in lecithin extraction and spray-drying infrastructure favors processors with backward integration into oilseed crushing and egg processing operations.
- Powder Stabilizers:Spray-dried phospholipid and protein matrices deliver extended shelf stability and reduced transport costs versus liquid alternatives. Germany's industrial baking clusters source these formats for sponge cake production requiring consistent overrun control amid EFSA clean-label mandates.
- Emulsifiers:Mono-diglyceride and lecithin blends command premium positioning in reformulated bakery applications. France and Italy are adopting enzyme-modified variants at accelerating rates for improved emulsion stability in high-fat sponge formulations.
- Liquid Stabilizers:Cold-chain dependent formats face distribution cost premiums under FDA 21 CFR Part 118 refrigeration mandates.
- Gels:Hydrocolloid-protein matrices serve niche texturizing applications in custard and sauce bases.
Powder stabilizers absorb the bulk of installed capacity; emulsifiers are expanding most quickly.
End Use Industry:
Cost tier stratification separates premium artisan bakeries from price-sensitive industrial processors, with specification depth determining supplier qualification requirements.
- Bakery:Aerated dessert production in Germany, France, and Italy requires consistent foam structure control, pulling specialized lecithin-protein blends. Clean-label reformulation cycles are accelerating phospholipid adoption as EFSA Regulation 1333/2008 reclassifications tighten additive restrictions.
- Food Processing:Extended shelf-life sauce and ready-meal applications demand heat-stable emulsion systems. India's FSSAI emulsifier approval lags create first-mover windows for phospholipid suppliers establishing local technical service.
- Confectionery:Chocolate and coating applications depend on tempered fat crystal control through phospholipid interference.
- Dairy:Custard and cream applications represent mature, price-sensitive segments with thinner margin pools.
Bakery commands the deepest specification requirements; food processing is climbing the fastest as clean-label mandates penetrate prepared meals.
Application:
Volume concentration in foam stabilization reflects the structural demands of aerated bakery matrices, with thickening applications showing slower technology turnover.
- Foam Stabilization:Controlled overrun in sponge cake and meringue production requires precise phospholipid-protein ratios at air-water interfaces. Germany's industrial baking clusters anchor demand for specialized blends meeting EFSA emulsifier standards.
- Thickening:Starch-hydrocolloid hybrid systems dominate custard and sauce bases, with enzyme-modified variants gaining traction in microwaveable products.
- Emulsification:Fat-water interface stabilization in mayonnaise and dressing applications depends on lecithin and mono-diglyceride functionality.
- Texturizing:Gelation and mouthfeel modification in premium desserts utilizes hydrocolloid-protein synergies.
Foam stabilization anchors procurement volumes; thickening is gaining share fastest through heat-stable hybrid system adoption.
Packaging Type:
Customer type stratification separates artisan bakeries requiring small-format flexibility from industrial processors optimizing for bulk handling efficiency.
- Bulk Containers:Tote and drum formats serve high-volume industrial bakeries with integrated dosing systems. Cargill and ADM compete on manufacturing scale through multiple North American plants converting egg derivatives into standardized blends.
- Pouches:Flexible packaging addresses mid-cap bakery groups consolidating multi-site contracts for cost and quality consistency across France, Spain, and Poland.
- Bottles:Liquid stabilizer distribution for premium segments faces FDA cold-chain compliance premiums.
- Tubs:Semi-bulk formats serve regional distributor networks with formulation support capabilities.
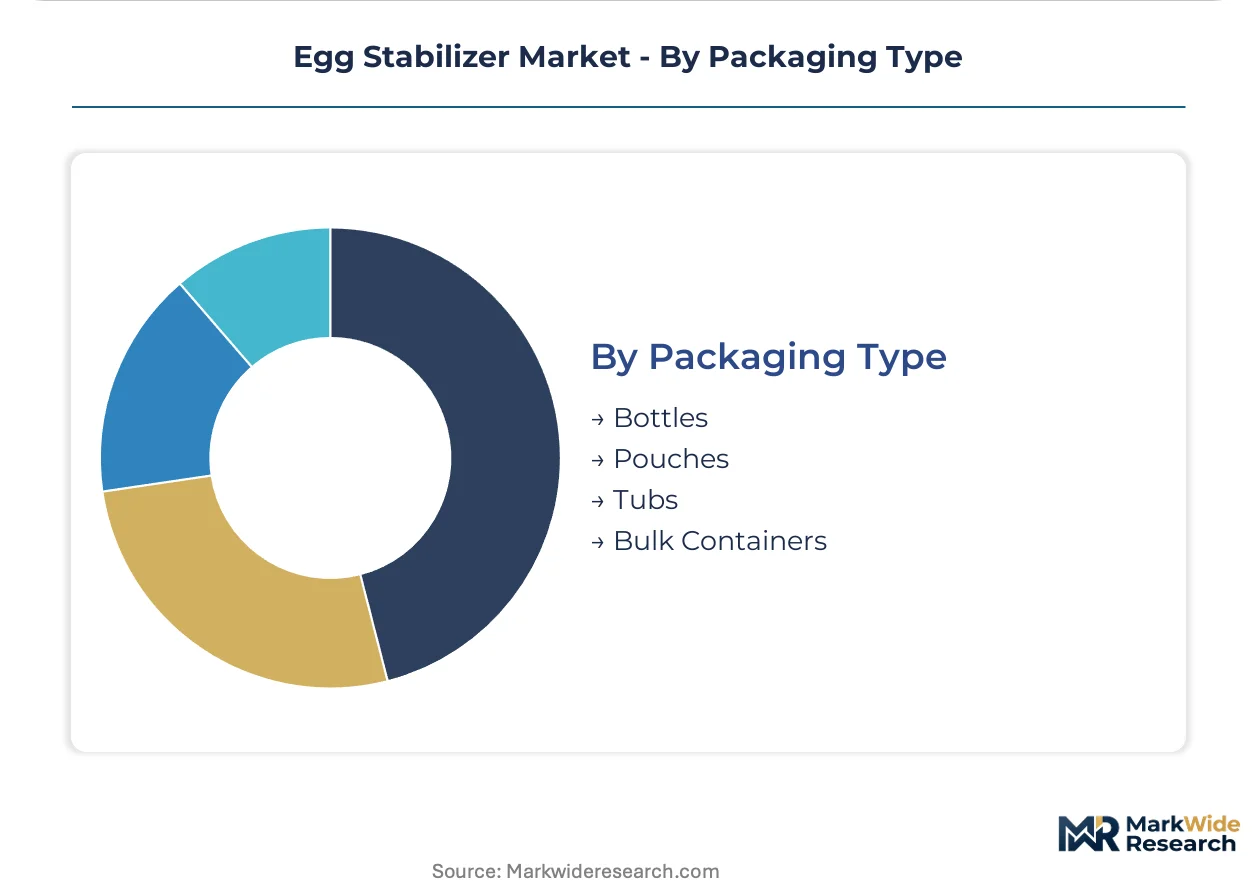
Bulk containers capture the greatest throughput; pouches are expanding most quickly as specification-driven procurement shortens supplier qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Avian influenza surveillance zones in Iowa and Minnesota anchor North American egg-derived phospholipid supply chains, while industrial baking clusters in Germany and artisan producers in France and Italy shape demand specifications for specialized stabilizer blends.
Germany
Industrial baking clusters in Lower Saxony and Bavaria drive demand for extended shelf-life sponge cake formulations. EFSA Regulation 1333/2008 reclassifications are accelerating phospholipid adoption as clean-label mandates tighten additive restrictions. Frankfurt-Rhine-Main logistics hubs coordinate cold-chain distribution for liquid stabilizer formats serving mid-cap bakery groups.
United States
FDA 21 CFR Part 118 refrigeration standards shape distribution economics for liquid stabilizer formats across industrial bakery networks. Iowa and Minnesota egg processing belts supply phospholipid feedstocks amid avian influenza monitoring protocols. Chicago-area ingredient distributors consolidate multi-site contracts for standardized powder blends.
France
Artisan and industrial bakers in Île-de-France and Auvergne-Rhône-Alpes are adopting enzyme-modified lecithin variants for high-fat sponge formulations. REACH compliance requirements are tightening impurity thresholds for solvent residues in lecithin extraction processes. Lyon-based stabilizer blenders are accelerating partnerships with certified oilseed processors.
China
SAMR GB standards for food-grade emulsifiers are unlocking import clearance pathways for premium bakery segments. Yangtze River Delta industrial zones concentrate microwaveable bakery production demanding heat-stable foam structures. Shanghai technical service centers are shortening supplier qualification cycles for phospholipid blends.
India
FSSAI emulsifier approvals lag EU timelines, creating first-mover windows for phospholipid suppliers establishing local technical service. Maharashtra and Gujarat food processing corridors demand heat-stable emulsion systems for extended shelf-life ready meals. Mumbai ingredient distributors are displacing commodity traders with formulation support capabilities.
Egg Stabilizer Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and formulation specialization. The vendor base clusters around three tiers: integrated agribusiness conglomerates with captive oilseed processing, mid-cap texture system specialists with regional formulation labs, and commodity distributors pivoting toward technical service. Dominant competitive moves include backward integration into lecithin feedstock security and direct-to-bakery technical partnerships that bypass traditional distribution.
Among integrated agribusiness conglomerates, Cargill Inc. and ADM occupy positions anchored by North American oilseed processing networks and multi-plant manufacturing scale. Kerry Group exemplifies the texture system specialist archetype with European regional formulation capabilities. Merck KGaA represents the diversified chemical-industrial tier with pharmaceutical-grade emulsifier expertise transferable to food applications.
| Leading Market Players |
|---|
| ADM |
| J and K Ingredients |
| Cargill Inc. |
| TIC Gums |
| Holton Food Products |
| Ingredion Incorporated |
| Kerry Group |
| Merck KGaA |
| Tate & Lyle |
| Others |
Supply & Pricing Matrix
Phospholipid feedstock costs trace from Iowa and Minnesota egg processing belts through three distinct pricing tiers, with enzyme-modified lecithin variants commanding premiums over standard fluid grades while cold-chain liquid formats absorb FDA refrigeration compliance premiums.
Pricing Analysis
Technical service bundling separates premium supplier contracts from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and formulation support intensity. Price differentiation hinges on EFSA clean-label compliance tiers and volume scale commitments from industrial baking clusters. Pricing pressure stems from plant-based emulsifier substitution in vegan-certified applications, compressing margins for egg-derived standard grades. Mid-cap bakery groups in France and Poland exhibit highest price sensitivity, while Germany's industrial clusters prioritize specification consistency over unit cost.
Supply Chain Analysis
Direct-to-bakery channels handle formulation-intensive demand from Germany's industrial baking clusters, while regional distributors with technical capabilities serve mid-cap groups across France, Spain, and Poland. Supply concentration anchors in Germany, the United States, and China, with Iowa-Minnesota egg belts feeding North American phospholipid extraction. Raw material dependencies center on egg-derived phospholipids, oilseed lecithin, and hydrocolloid stabilizers. Single-source vulnerability runs through avian influenza surveillance zones disrupting egg processing capacity. Distribution runs through Frankfurt-Rhine-Main logistics hubs coordinating cold-chain liquid stabilizer movement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EFSA reclassifications force reformulation investments that weaker players cannot fund, accelerating exits among commodity distributors lacking technical service infrastructure.
For Market Incumbents: Anticipate plant-based emulsifier substitution by deepening backward integration into certified oilseed processing and anchoring direct-to-bakery technical partnerships that bypass traditional distribution. Cargill and Kerry Group demonstrate this pattern through captive lecithin feedstock security and regional formulation labs. Defend margin position by accelerating enzyme-modified lecithin capacity in Germany and France where clean-label premiums persist. For New Entrants and Emerging Players: Launch via technical service partnerships with India's FSSAI approval-lagged food processing corridors, where phospholipid penetration trails EU timelines by 24-36 months. Target Maharashtra and Gujarat ready-meal manufacturers demanding heat-stable emulsion systems. Penetrate through Shanghai technical service centers shortening supplier qualification cycles for microwaveable bakery applications. For Investors and Strategic Acquirers: EFSA phosphate reclassifications accelerating phospholipid adoption are the leading indicator that formulation-specialist mid-caps will command acquisition premiums over commodity traders. Long-term viability favors texture system specialists with regional labs and clean-label certification pipelines. Monitor FSSAI approval timelines as inflection signal for India market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill secures lecithin feedstocks through North American crushing network, insulating against avian influenza volatility. |
| Direct-to-Bakery Technical Partnerships | Kerry Group bypasses distributors to capture formulation data from Germany's industrial baking clusters. |
| Enzyme-Modified Lecithin Capacity Expansion | France and Italy adoption rates for high-fat sponge applications justify premium positioning investments. |
| Regional Formulation Lab Establishment | India FSSAI lag creates first-mover advantage for phospholipid suppliers with Mumbai technical service. |
| Clean-Label Certification Pipeline Investment | REACH compliance tightening drives partnerships with certified processors in Germany and Netherlands. |
Research Methodology
Independent corroboration across FDA 21 CFR Part 118 compliance officers, EFSA additive evaluation panels, and industrial bakery technical directors underwrites the qualitative findings. Primary interviews with procurement leads at German industrial baking clusters, formulation scientists at French artisan cooperatives, and distribution channel partners across Spain and Poland combined with secondary validation from ECHA REACH guidance documents, SAMR GB standard filings, and customs trade data. Bottom-up segment sizing triangulates against top-down market construction across powder stabilizer, emulsifier, liquid, and gel format categories.
Historical reference periods spanning avian influenza cycles and EFSA reclassification waves anchor the projection horizon. The analytical framework models volume and value across product type, end-use industry, application, and packaging format dimensions, with regional regulatory clusters as an additional cross-cutting variable. CAGRs derive from elasticity-adjusted demand curves incorporating clean-label mandate penetration rates and substitution coefficients for plant-based alternatives. Forecast inputs include phospholipid feedstock cost volatility indices and industrial bakery consolidation trajectories.
Avian influenza resurgence, EFSA additive reclassifications, and FSSAI approval delays are the dominant revision risks. Forecasts reflect assumptions about regulatory timeline stability and substitution technology cost curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Lutein and Lutein Esters Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Caramel Food Colors Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market