
 India Food Additives Market | 2026-2036
India Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Additives Market Foresight
Fragmentation among regional dairy cooperatives and mid-tier snack brands is recalibrating procurement patterns across the additive supply base. Cargill Incorporated leverages its oilseed processing footprint to anchor emulsifier supply into western India's dairy belt. Kerry Group PLC competes through flavor specialization tailored to masala and ethnic taste profiles. BASF SE sustains vitamin premix dominance via technical service partnerships with large food manufacturers.
Food additives comprise substances added to food to preserve flavor, enhance taste, improve appearance, or maintain nutritional value, with specifications covering purity thresholds, maximum usage levels, and carrier compositions defined under codex and national standards. Preservatives and flavoring agents command the largest current volume positions, while nutritional additives represent the fastest-expanding margin pool as fortified foods penetrate deeper into mass-market retail. Colorants face structural pressure from natural extract alternatives, though synthetic variants retain cost advantages in beverage applications.
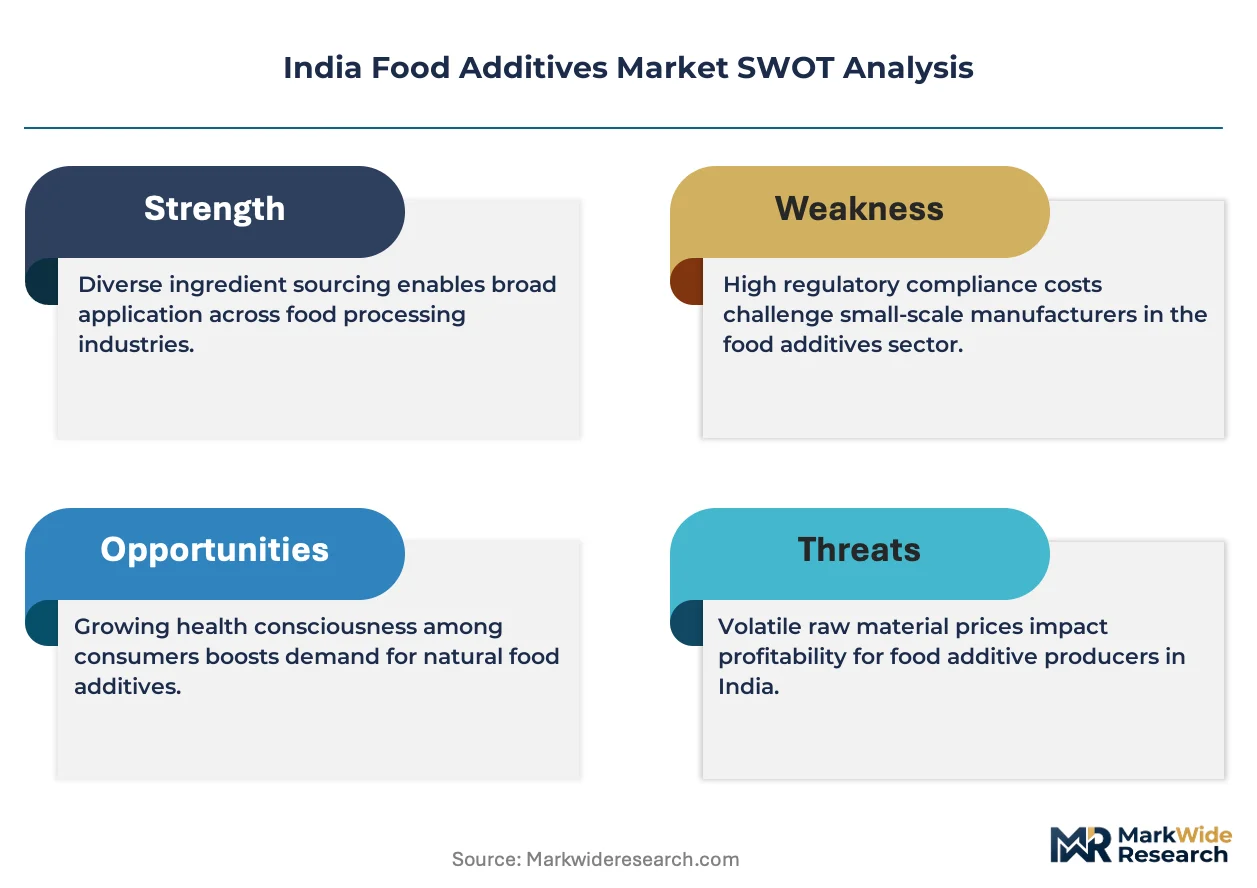
FSSAI mandates govern additive approval, maximum permissible limits, and label declarations across all packaged food categories, with BIS standards providing complementary product quality benchmarks. CDSCO oversight intersects where additives carry therapeutic or nutraceutical claims, creating dual compliance pathways for functional ingredient suppliers. Stakeholders must monitor evolving FSSAI notification cycles and state-level enforcement intensity to anticipate formulation reformulation costs and certification timelines.
Market Dynamics
FSSAI's tightening of synthetic colorant labeling norms is compressing formulation cycles across Maharashtra's beverage processing belt, forcing rapid supplier recalibration.
Growth Catalysts
- Clean-label mandates:FSSAI's disclosure requirements for synthetic additives are accelerating natural extract adoption in Mumbai-Pune corridor beverage plants.
- Fortification push:India's PLI scheme incentives for nutritional foods are expanding vitamin premix volumes into mass-market dairy cooperatives.
- Ethnic flavor localization:Masala and regional taste specialization is opening dedicated R&D investment from flavor houses serving snack brands.
Market Restraints
- Natural extract cost premiums:Turmeric and annatto sourcing volatility is squeezing margin structures for mid-tier confectionery makers.
- Import dependency for specialty emulsifiers:Western India's dairy belt relies on concentrated Southeast Asian lecithin supply channels.
- Dual compliance burden:CDSCO therapeutic claim oversight intersects with FSSAI additive rules, lengthening functional ingredient approval timelines.
Strategic Opportunities
- Untapped Northeastern processing:Assam and Tripura food manufacturing corridors lack localized additive technical service coverage.
- Clean-label preservation:Fermented cultures and vinegar-based systems are displacing benzoates in emerging sauce and pickle applications.
- E-commerce ingredient sourcing:Direct-to-manufacturer platforms are compressing distributor layers for Tier-2 city snack startups.
Industry Challenges
- Formulation scientist scarcity:Food chemistry expertise gaps in Gujarat and Rajasthan are delaying clean-label reformulation projects.
- Legacy equipment retrofit costs:Natural colorant stability requirements demand capital outlays for UV-protection and temperature-controlled blending lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Additives Market |
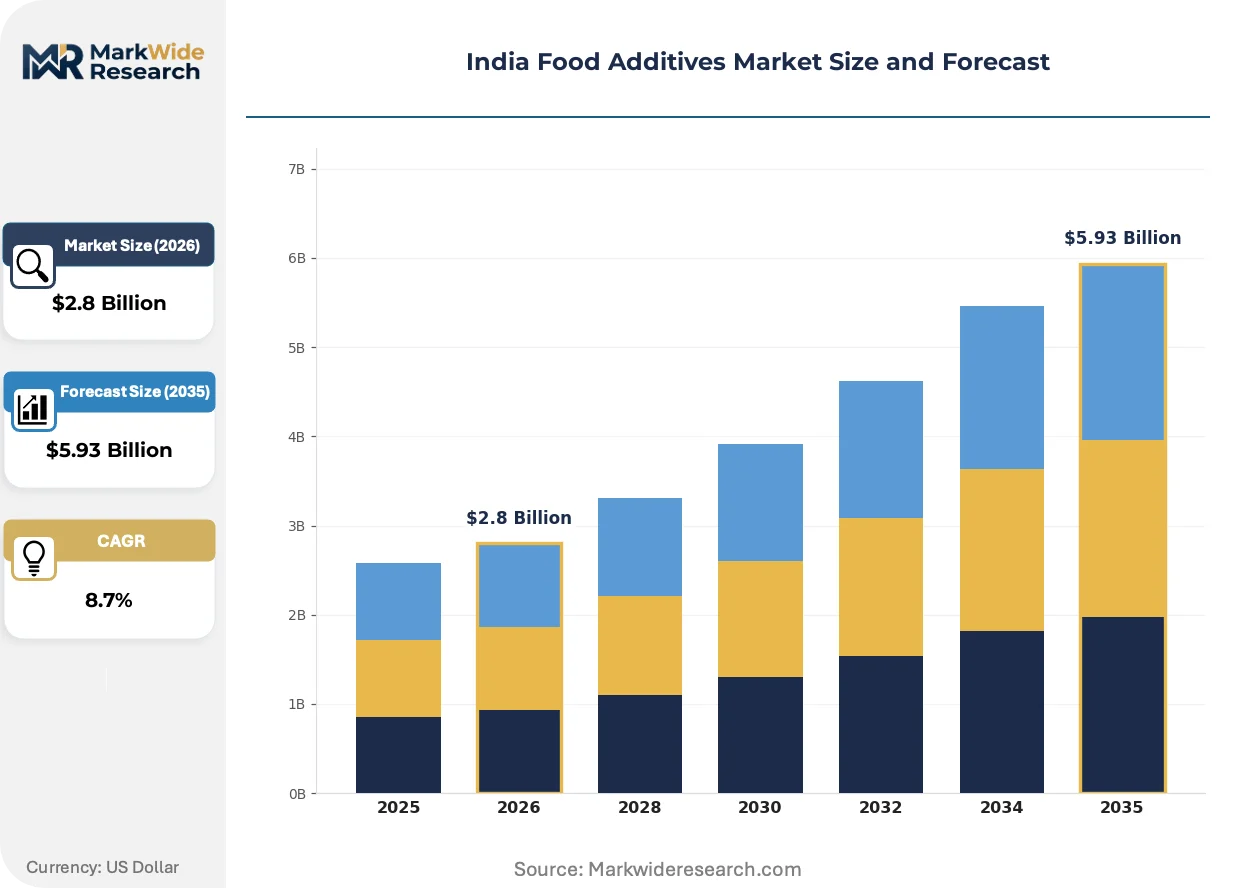
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agents, Preservatives, Colorants, Nutritional Additives Application: Beverages, Bakery & Confectionery, Dairy Products, Snacks End User: Food Manufacturers, Retail Chains, Restaurants, Catering Services Form: Powder, Liquid, Granules, Emulsions |
| Companies Covered | DSM-Firmenich, Tate & Lyle PLC, Cargill Incorporated, Corbion NV, Archer Daniels Midland Company, BASF SE, Kerry Group PLC, Sunshine Chemicals (India), Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Additives Market Shifts & Advancements
Encapsulation technologies and fermentation-derived ingredients are compressing the performance gap between synthetic and natural additives, reshaping procurement criteria across India's processed food sector.
Microencapsulation of omega fatty acids and probiotics is unifying shelf-life extension with nutritional enhancement in single-ingredient systems. Dairy cooperatives in Maharashtra are adopting these complexes at pilot scale. This convergence is compressing supplier lists as ingredient houses bundle multiple functional claims.
FSSAI's 2023 notification on quantum satis limits for artificial sweeteners is forcing beverage reformulators toward stevia-monk fruit blends. Large manufacturers are accelerating stability testing investments. Carbonated soft drink and flavored water categories face the steepest label redesign cycles.
Direct technical service engagement is displacing traditional distributor relationships for mid-tier snack brands. Ingredient houses now embed application scientists with Gujarat and Karnataka manufacturers. This pattern concentrates most visibly in ethnic savory segments requiring rapid masala customization.
India Food Additives Market Segmentation
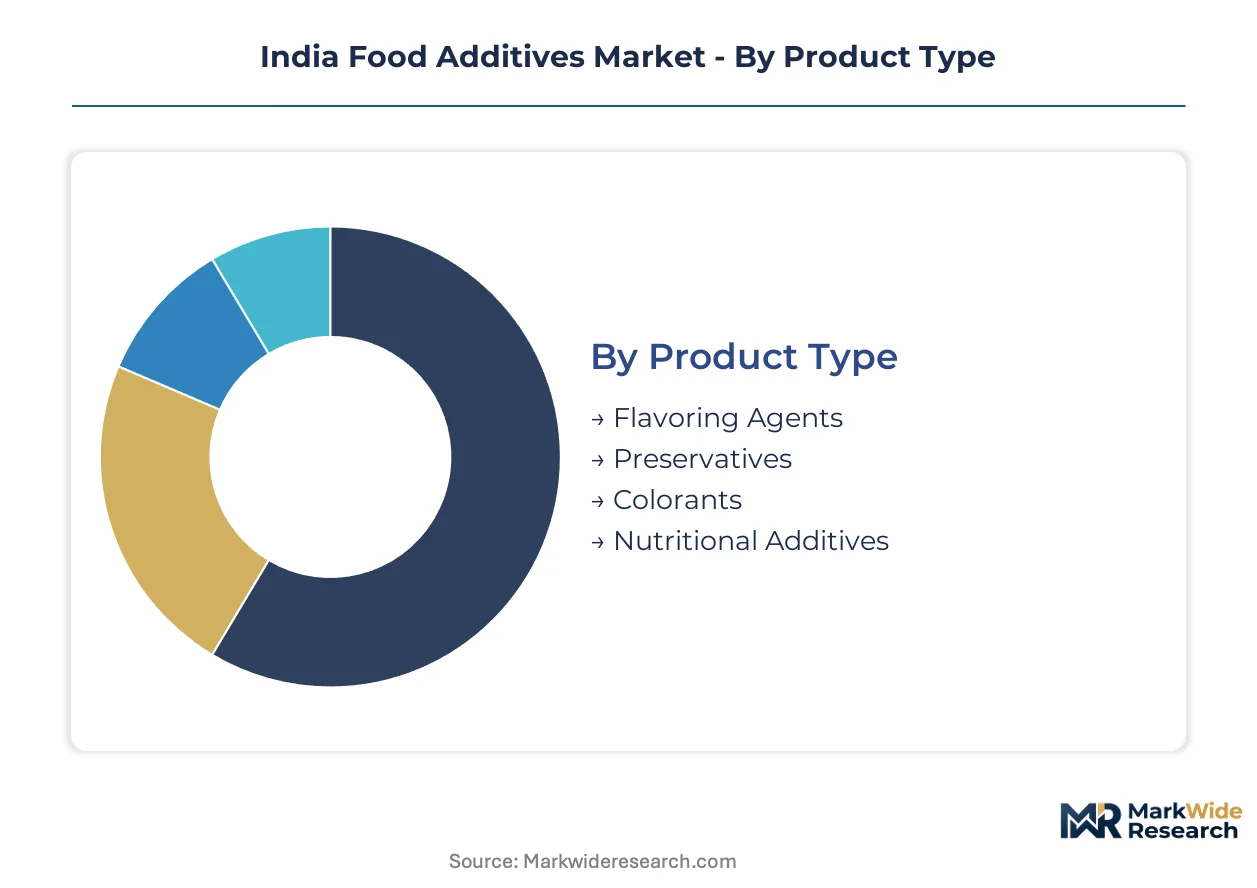
Segmentation in India's food additives market maps directly to compliance intensity and procurement scale. FSSAI notification cycles and BIS certification requirements vary sharply across product categories, creating divergent margin structures and supplier qualification timelines for additive manufacturers.
Product Type:
Certification burdens concentrate heaviest in nutritional additives requiring CDSCO therapeutic claim validation alongside FSSAI approval, while colorants face escalating purity testing under tightened synthetic labeling norms.
- Flavoring Agents:These comprise natural extracts, nature-identical compounds, and artificial formulations standardized under FSSAI purity specifications. Demand clusters in Gujarat's savory snack manufacturing belt around Ahmedabad, where masala customization cycles compress supplier response times to under four weeks for regional taste launches.
- Preservatives:Benzoates, sorbates, and emerging fermented culture systems serve shelf-life extension mandates across India's tropical distribution environment. Mumbai-Pune corridor beverage plants are accelerating clean-label reformulation toward vinegar-based and cultured preservation as FSSAI disclosure requirements tighten on synthetic variants.
- Colorants:Natural extracts from turmeric and annatto compete with certified synthetic variants in confectionery applications.
- Nutritional Additives:Vitamin premixes and mineral fortificants require dual FSSAI-CDSCO pathway navigation for therapeutic positioning.
Leading the category by volume: Preservatives. Growing fastest: Nutritional Additives.
Application:
Application segments diverge by processing intensity and temperature stability requirements, with thermal processing categories demanding encapsulated and heat-stable additive formats.
- Beverages:Carbonated soft drinks, flavored waters, and functional drinks rely on acid-stable colorants and artificial sweetener blends now facing FSSAI quantum satis limit revisions. Maharashtra's processing corridor accounts for disproportionate reformulation investment as label redesign cycles accelerate.
- Bakery & Confectionery:Emulsifier and lecithin demand concentrates in Karnataka's biscuit and chocolate manufacturing clusters around Bengaluru.
- Dairy Products:Fortification mandates drive vitamin premix volumes into cooperative processing networks across Gujarat and Rajasthan.
- Snacks:Ethnic savory applications require rapid flavor customization cycles with embedded technical service from ingredient houses.
Highest processing intensity: Bakery & Confectionery. Steepest clean-label transition: Beverages.
End User:
End user segments separate by procurement scale and technical service requirements, with direct manufacturer engagement displacing distributor relationships at the mid-tier threshold.
- Food Manufacturers:Large integrated processors and mid-tier brands constitute the core volume base, with procurement shifting toward direct technical partnerships for application development. Gujarat and Maharashtra manufacturers now embed ingredient house scientists for masala and ethnic flavor customization.
- Retail Chains:Private label programs drive consolidated additive sourcing for bakery and beverage categories.
- Restaurants:Quick-service chains standardize supplier relationships across franchise networks for consistency enforcement.
- Catering Services:Institutional volume concentrates in bulk preservative and flavoring procurement for centralized kitchen operations.
Dominant procurement scale: Food Manufacturers. Fastest relationship model shift: Retail Chains.
Form:
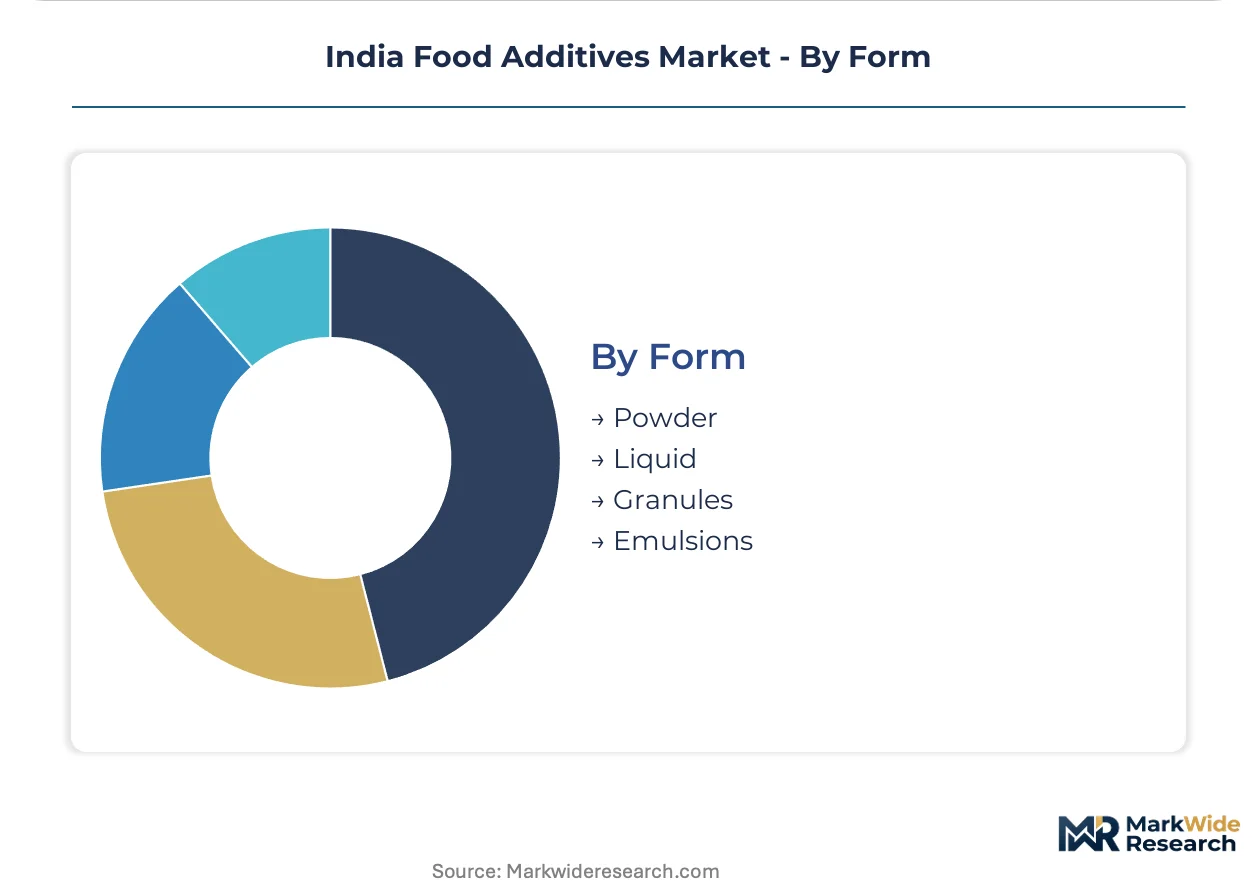
Form selection tracks equipment compatibility and dispersion requirements, with powder dominance giving way to liquid and emulsion growth in continuous processing environments.
- Powder:Dry blending compatibility and extended shelf stability maintain volume leadership across bakery and dry mix applications. Rajasthan and Gujarat dairy cooperatives favor powder vitamin premixes for fortification consistency in milk powder reconstruction.
- Liquid:Pumpable delivery systems suit high-volume beverage and sauce manufacturing with automated dosing infrastructure.
- Granules:Controlled dissolution rates serve specialized confectionery and seasoning applications requiring gradual release profiles.
- Emulsions:Oil-in-water systems provide uniform dispersion for colorants and fat-soluble vitamins in liquid food matrices.
Highest volume form: Powder. Fastest equipment-driven transition: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oilseed processing clusters in western India anchor domestic emulsifier supply chains, while spice cultivation belts in the south feed natural extract demand for colorant and flavoring applications.
Maharashtra
Mumbai-Pune corridor beverage plants drive acid-stable colorant and artificial sweetener consumption. FSSAI's 2023 quantum satis notification on synthetic sweeteners has triggered intensive reformulation cycles across carbonated soft drink manufacturers. Pune's food technology institutes are embedding application scientists with mid-tier processors seeking clean-label transitions.
Gujarat
Ahmedabad's savory snack manufacturing belt compresses masala customization cycles to under four weeks for regional taste launches. The state's dairy cooperative networks favor powder vitamin premixes for milk fortification consistency. BIS certification requirements for nutritional additives create extended qualification timelines for new suppliers entering Gandhinagar's processing zones.
Karnataka
Bengaluru's biscuit and chocolate manufacturing clusters concentrate emulsifier and lecithin demand for thermal processing applications. Karnataka's food processing policy incentives are attracting encapsulated ingredient trials from dairy cooperatives. Mysuru's emerging sauce manufacturers are piloting fermented culture preservation systems as benzoate alternatives.
Rajasthan
Dairy cooperatives across Jaipur and Jodhpur rely on powder premix formats for milk powder reconstruction and fortification programs. Formulation chemistry expertise gaps in the state are delaying clean-label reformulation timelines for mid-tier brands. Udaipur's confectionery makers face margin pressure from annatto and turmeric sourcing volatility.
Tamil Nadu
Chennai's beverage bottling infrastructure supports flavoring agent volumes into South Indian markets. The state's spice extraction facilities supply turmeric-derived colorants to national confectionery chains. Coimbatore's dairy processing expansion is creating new vitamin premix demand from cooperative networks.
India Food Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label specialization and regional technical service embedding. The supplier base stratifies across multinational ingredient houses, domestic extract processors, and cooperative-affiliated premix blenders. Three archetypes dominate: emulsifier-lecithin processors anchored near oilseed crush capacity; flavor houses with embedded application laboratories; and vitamin-mineral premix specialists navigating dual FSSAI-CDSCO compliance pathways. Capacity expansion and direct technical partnerships represent the dominant competitive vectors as distributor relationships erode at the mid-tier threshold.
Within the multinational tier, Cargill Incorporated, Kerry Group PLC, and BASF SE exemplify divergent anchoring strategies. Cargill leverages proximity to western India's oilseed processing infrastructure. Kerry occupies the flavor specialization position with masala customization capabilities. BASF represents the premix-dominant archetype sustained by technical service partnerships with large manufacturers. Domestic specialists including Sunshine Chemicals (India) compete on regional sourcing agility and compressed certification timelines for mid-tier snack brands.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Tate & Lyle PLC |
| Cargill Incorporated |
| Corbion NV |
| Archer Daniels Midland Company |
| BASF SE |
| Kerry Group PLC |
| Sunshine Chemicals (India) |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap extract processors across Maharashtra and Gujarat anchor supply behavior through generational spice-sourcing relationships, tightening pricing discipline as FSSAI disclosure mandates force reformulation investments. Their concentrated ownership patterns limit price transparency, compressing margin negotiations for mid-tier snack brands seeking natural colorant alternatives.
Pricing Analysis
Volume concentrates in synthetic preservatives and standard-grade flavoring agents, while margin pools accrue to nutritional premixes and encapsulated natural extracts. Three-tier pricing structure across premium certified-organic, standard FSSAI-compliant, and economy synthetic tiers separates buyers by certification burden and technical service intensity. Cost compression in mid-tier natural colorants is intensifying because turmeric and annatto harvest volatility feeds raw material instability. Bulk dairy cooperatives exhibit highest price sensitivity; multinational beverage manufacturers absorb premiums for clean-label transition speed.
Supply Chain Analysis
Regional distribution centers in Mumbai, Ahmedabad, and Bengaluru coordinate hub-and-spoke delivery to Tier-2 processing clusters, compressing lead times for just-in-time masala launches. Manufacturing concentrates in India, with specialty lecithin and encapsulated vitamin inputs drawing from concentrated Southeast Asian and European supply channels. Single-source vulnerability runs through Malaysian and Indonesian lecithin corridors serving western India's dairy belt. Distribution runs through direct technical partnerships displacing traditional distributor layers at the mid-tier threshold.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where FSSAI's accelerating notification cycles and certification cost burdens force sub-scale natural extract processors toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through captive backward integration into turmeric and annatto cultivation belts in Maharashtra and Karnataka, securing supply against harvest volatility. Deepen technical service embedding with Gujarat snack manufacturers to lock in masala customization relationships before specialty flavor houses displace commodity suppliers. Prioritize CDSCO dual-pathway certification investment for vitamin premix portfolios ahead of fortification mandate expansion. For New Entrants and Emerging Players: Begin with Assam and Tripura food manufacturing corridors, where additive technical service coverage remains sparse and regional taste profiles demand localized R&D. Target fermented culture preservation systems for sauce and pickle applications, capitalizing on benzoate displacement momentum. Pursue direct-to-manufacturer e-commerce platforms for Tier-2 city snack startups, compressing distributor markups and accelerating customer acquisition. For Investors and Strategic Acquirers: Distressed-cycle entries favor family-owned natural extract processors in Rajasthan and Tamil Nadu facing working capital strain from FSSAI purity testing investments. Long-term viability hinges on certification infrastructure and technical service density rather than commodity scale. Monitor FSSAI notification velocity as the critical inflection signal; accelerating synthetic additive disclosure mandates will determine winners in the clean-label transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive turmeric and annatto supply secures margin stability against harvest volatility for natural colorant processors. |
| Technical Service Laboratory Embedding | Application scientists co-located with Gujarat snack manufacturers compress masala customization cycles below four weeks. |
| Dual-Pathway Certification Investment | Simultaneous FSSAI-CDSCO navigation unlocks therapeutic positioning for vitamin premix portfolios in cooperative dairy networks. |
| Fermented Culture Preservation Scale-Up | Vinegar-based and cultured systems displace benzoates in Maharashtra and Karnataka sauce manufacturing corridors. |
| E-Commerce Platform Development | Direct-to-manufacturer sourcing compresses distributor layers for emerging Tier-2 city snack brand procurement. |
Research Methodology
Independent corroboration across FSSAI notification records, BIS certification databases, and cooperative dairy procurement disclosures underwrites the qualitative findings. Primary interviews with formulation scientists at Maharashtra beverage processors, procurement leads at Gujarat snack manufacturers, FSSAI regulatory affairs specialists, and Kerala spice extraction facility managers combined with secondary validation from customs import records, FSSAI gazette notifications, and CDSCO therapeutic claim filings. Bottom-up additive volume estimates triangulate against top-down processed food production data across the analysis window.
Rate-of-change decomposition separates volume expansion from value migration across product type, application category, and end-user procurement scale dimensions. CAGRs derive from segmented growth trajectory modeling calibrated to FSSAI regulatory cycle timing, PLI scheme incentive disbursement patterns, and clean-label adoption velocity in Maharashtra's beverage corridor. Forecast inputs incorporate spice harvest yield variability, lecithin import corridor stability, and cooperative dairy fortification program rollout intensity throughout the projection horizon.
Underlying measurement precision varies by segment; nutritional additives with dual FSSAI-CDSCO pathways carry tighter precision than emerging fermented culture preservation categories. Forecasts reflect documented assumptions regarding regulatory notification velocity, PLI scheme continuity, and natural extract cost normalization. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that FSSAI acceleration of synthetic additive disclosure mandates or sustained turmeric harvest disruption could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Australia Feed Additives Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Europe Food Acidulants Market