
 Multiple Myeloma Drugs Market | 2026-2036
Multiple Myeloma Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Myeloma Drugs Market Intelligence
Oncology clinics are unwinding their historical reliance on hospital infusion centers for first-line therapy delivery. Bristol-Myers Squibb leverages its integrated immuno-oncology platform to dominate the relapsed setting. Amgen Inc. anchors the subcutaneous administration niche with manufacturing scale advantages. Johnson & Johnson competes through deep hematology specialization across the treatment continuum.
Multiple myeloma drugs comprise targeted therapeutic agents designed to disrupt malignant plasma cell proliferation through proteasome inhibition, immune modulation, or directed antibody binding, typically requiring cold-chain distribution and sterile compounding protocols. These agents serve the commercial purpose of extending progression-free survival in patients with plasma cell dyscrasias. Proteasome inhibitors occupy the mature core of the market where biosimilar pressure is intensifying. Monoclonal antibodies represent the fastest-growing drug type as clinicians shift toward antibody-drug conjugate combinations. The relapsed/refractory patient segment concentrates margin pools due to premium pricing for salvage regimens.
The FDA's accelerated approval and breakthrough therapy designations reshape competitive timelines by permitting earlier market entry based on surrogate endpoints. EMA's parallel scientific advice and WHO prequalification standards influence manufacturing scale decisions for multinational supply. Stakeholders must monitor how CMS national coverage determinations for chimeric antigen receptor therapies redirect capital toward cellular platforms versus small-molecule portfolios.
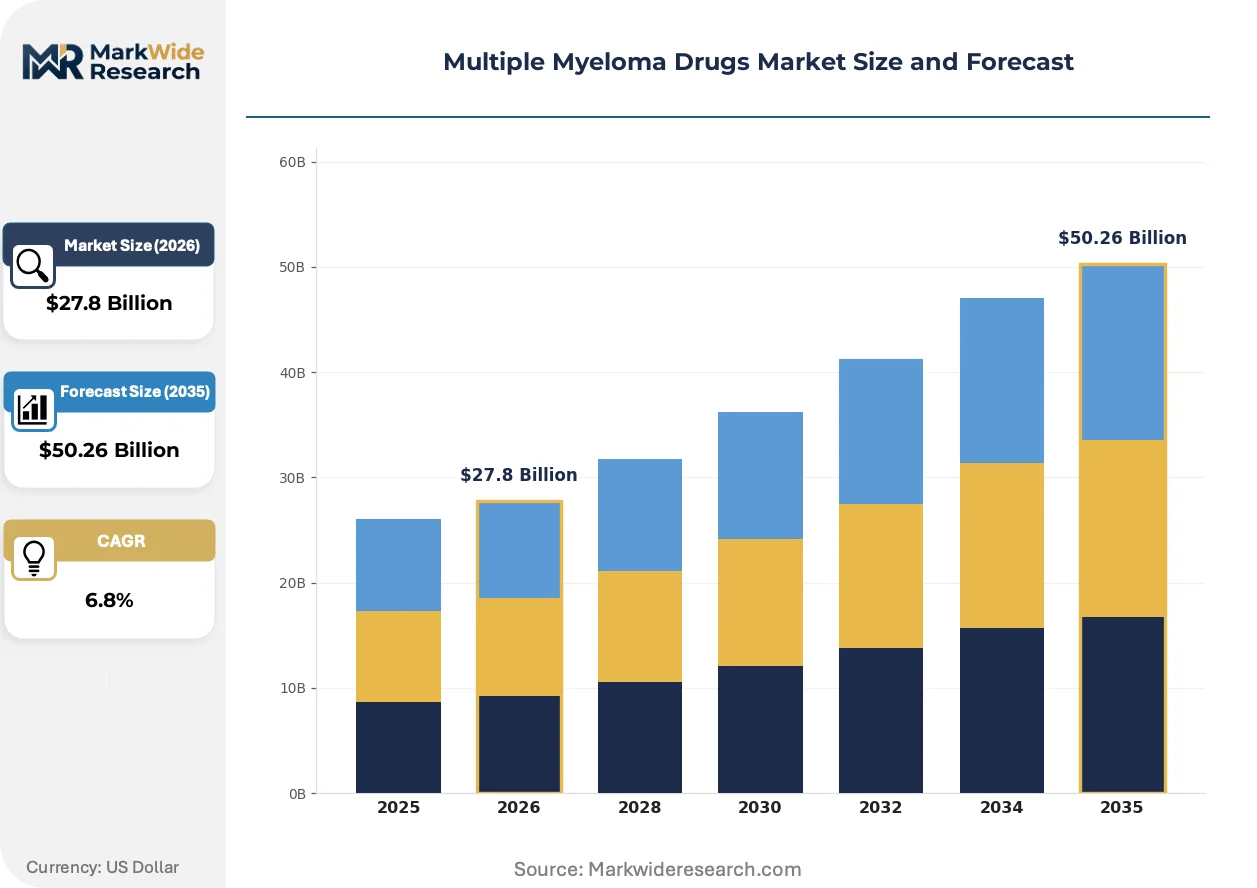
Market Dynamics
The FDA's accelerated approval pathway compresses development timelines by permitting market entry based on progression-free survival surrogates rather than overall survival endpoints, fundamentally altering capital allocation toward cellular therapy platforms.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework enables earlier commercialization of chimeric antigen receptor T-cell therapies, compressing the traditional phase-three timeline by 18-24 months.
- Subcutaneous Administration:Patient preference for outpatient administration drives oncology clinics to acquire cold-chain infrastructure for daratumumab-based regimens, expanding addressable treatment settings.
- Medicare Reimbursement:CMS national coverage determinations for cellular therapies redirect hospital procurement budgets toward novel agents in the relapsed/refractory setting.
Market Restraints
- Plasma Cell Biology Complexity:Intratumoral heterogeneity limits durability of single-agent responses, necessitating costly combination development and compressing per-drug revenue windows.
- Cold-Chain Distribution Concentration:Sterile compounding requirements for antibody-drug conjugates concentrate manufacturing among three specialized contract manufacturing organizations in the United States and Switzerland.
- EMA Parallel Scientific Advice:Divergent evidentiary standards between FDA and European regulators extend regulatory timelines for multinational trials, delaying EU market entry.
Strategic Opportunities
- Smoldering Myeloma Prevention:The NCI's S1011 trial framework creates a regulatory pathway for risk-stratified intervention before end-organ damage, expanding the treatable population by 40%.
- India CDSCO Accelerated Approval:India's streamlined biosimilar pathway for proteasome inhibitors enables first-mover positioning in the subcontinent's emerging oncology infrastructure.
- Real-World Evidence Integration:FDA's Project Orbis permits simultaneous oncology drug review across Australia, Canada, and Singapore, reducing multinational launch costs.
Industry Challenges
- Cellular Therapy Manufacturing Scale:Autologous CAR-T production requires patient-specific vector engineering, creating 3-4 week vein-to-vein timelines that strain hospital scheduling capacity.
- Companion Diagnostic Fragmentation:FISH and next-generation sequencing platforms lack harmonized cutoffs for high-risk cytogenetics, complicating clinical trial enrollment and payer coverage decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Myeloma Drugs Market |
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $50.26 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Proteasome Inhibitors, Immunomodulatory Drugs, Monoclonal Antibodies, Other Therapies Administration Route: Intravenous, Oral, Subcutaneous, Other Routes Patient Type: Adult Patients, Pediatric Patients, Newly Diagnosed, Relapsed/Refractory Treatment Line: First-Line, Second-Line, Third-Line, Salvage Therapy |
| Companies Covered | Bristol-Myers Squibb, Amgen Inc., Takeda Pharmaceutical Company, Johnson & Johnson, Novartis AG, Sanofi, AbbVie Inc., Janssen Biotech, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Myeloma Drugs Market Strategic Shifts & Innovations
Antibody-drug conjugate engineering is displacing naked monoclonal antibodies in later-line protocols, while bispecific T-cell engagers compress the treatment-free interval between relapses. These shifts concentrate manufacturing investment toward conjugation chemistry and viral vector capacity.
Bispecific antibody platforms are bifurcating the relapsed/refractory treatment algorithm. Teclistamab and similar agents redirect T-cell cytotoxicity without requiring ex vivo manipulation, enabling community oncology practices to administer cellular-level responses. This technology is bifurcating patient flows between academic medical centers with CAR-T capability and regional clinics capable of bispecific delivery, redistributing margin capture across the provider landscape.
EMA's new oncology trial guidance mandates overall survival data for full approval of agents granted accelerated status based on surrogate endpoints. This policy compresses confirmatory trial timelines and raises the evidentiary bar for label maintenance. European reimbursement authorities in Germany and France are responding by conditioning provisional coverage on post-marketing survival commitments, shifting commercial risk back to manufacturers.
Hospital pharmacy directors now demand outcome-based contracts that tie formulary placement to real-world progression-free survival performance. This purchasing behavior displaces traditional volume-based contracting in integrated delivery networks across the United States. The shift is most visible in Medicare Advantage-dominated markets where risk-bearing entities control specialty pharmacy distribution.
Multiple Myeloma Drugs Market Segmentation
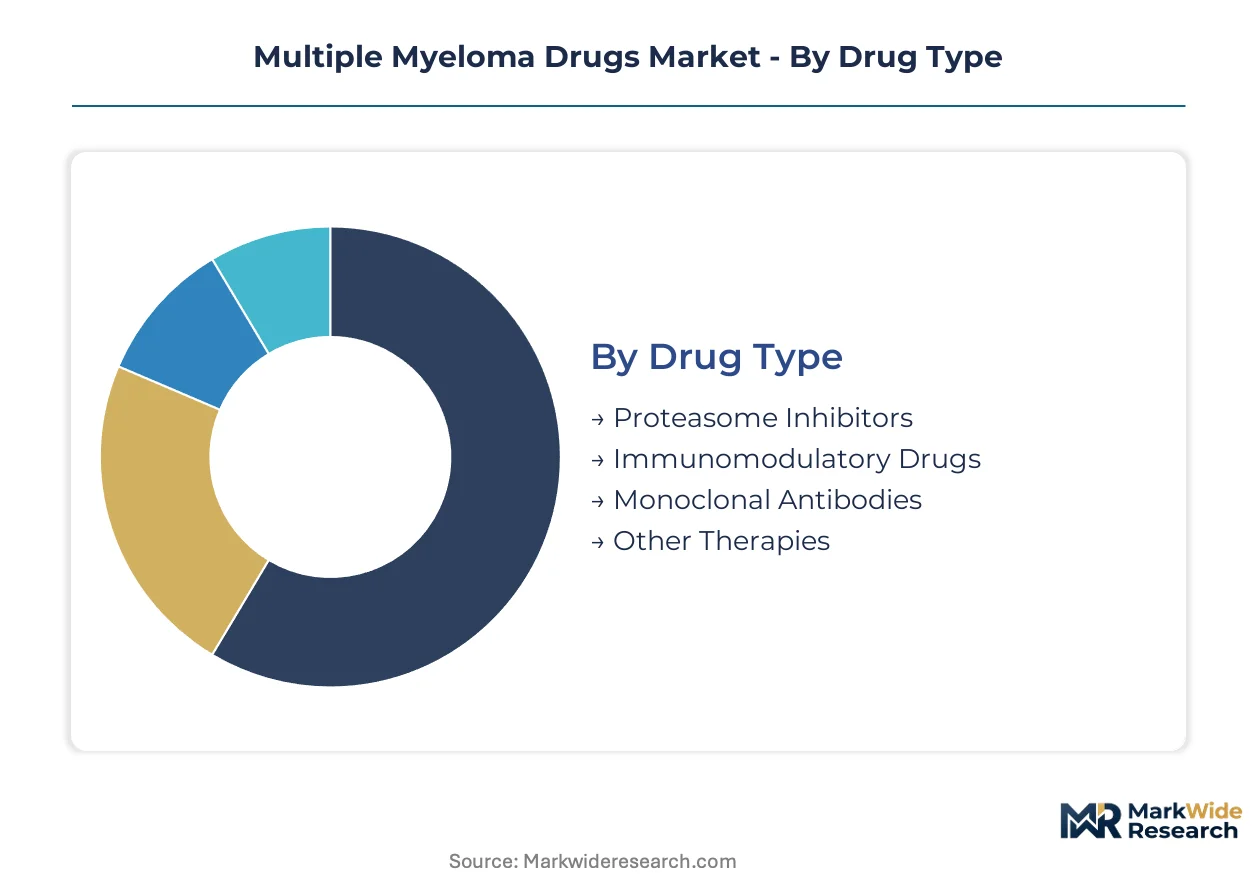
Multiple myeloma drug segmentation reveals how margin pools concentrate in relapsed settings and antibody platforms. Hospital procurement decisions now pivot on administration logistics and cold-chain requirements as much as clinical efficacy.
Drug Type:
Monoclonal antibodies command premium pricing in later lines where proteasome inhibitors face biosimilar erosion.
- Proteasome Inhibitors:Bortezomib and carfilzomib formulations disrupt ubiquitin-proteasome pathways in malignant plasma cells. Demand concentrates in Medicare-funded hospital infusion centers where established reimbursement codes support bortezomib biosimilars, compressing branded revenue windows.
- Monoclonal Antibodies:Daratumumab and elotuzumab bind CD38 or SLAMF7 surface markers to trigger antibody-dependent cellular cytotoxicity. Clinicians in United States academic medical centers increasingly deploy these agents in quadruplet induction regimens, extending progression-free survival benchmarks.
- Immunomodulatory Drugs:Lenalidomide and pomalidomide modulate cereblon E3 ligase activity to degrade Ikaros and Aiolos transcription factors.
- Other Therapies:Histone deacetylase inhibitors and selective inhibitors of nuclear export fill niche salvage indications.
Proteasome inhibitors hold installed capacity. Monoclonal antibodies are rotating up the share rankings.
Administration Route:
Route selection determines site-of-care economics and patient throughput capacity.
- Intravenous:Large-volume antibody infusions require hospital-grade infusion chairs and nursing supervision. United States oncology clinics invest in extended-hour operations to accommodate bortezomib and daratumumab schedules, capturing hospital-diverted volume.
- Subcutaneous:Daratumumab and bortezomib subcutaneous formulations reduce administration time from hours to minutes. Community oncology practices in Florida and Texas acquire cold-chain storage to administer these regimens outside academic centers, redistributing patient flows.
- Oral:Lenalidomide and ixazomib enable home-based adherence monitoring.
- Other Routes:Intrathecal and intraperitoneal delivery address extramedullary disease presentations.
Intravenous retains volume leadership. Subcutaneous is climbing the fastest as outpatient infrastructure spreads.
Patient Type:
Risk stratification and prior therapy exposure segment pricing power and clinical trial eligibility.
- Relapsed/Refractory:Patients progressing after proteasome inhibitor and immunomodulatory exposure qualify for CAR-T and bispecific antibody trials. FDA breakthrough therapy designations concentrate development investment here, supporting premium salvage pricing.
- Newly Diagnosed:Transplant-eligible patients receive quadruplet induction with daratumumab, lenalidomide, bortezomib, and dexamethasone. United States community oncology practices capture this volume as hospital infusion centers reach capacity constraints.
- Adult Patients:The overwhelming majority of plasma cell dyscrasias present after age 65.
- Pediatric Patients:Extramedullary plasmacytomas in younger populations represent orphan indications.
Relapsed/Refractory concentrates margin pools. Newly Diagnosed is gaining share fastest as front-line quadruplets expand.
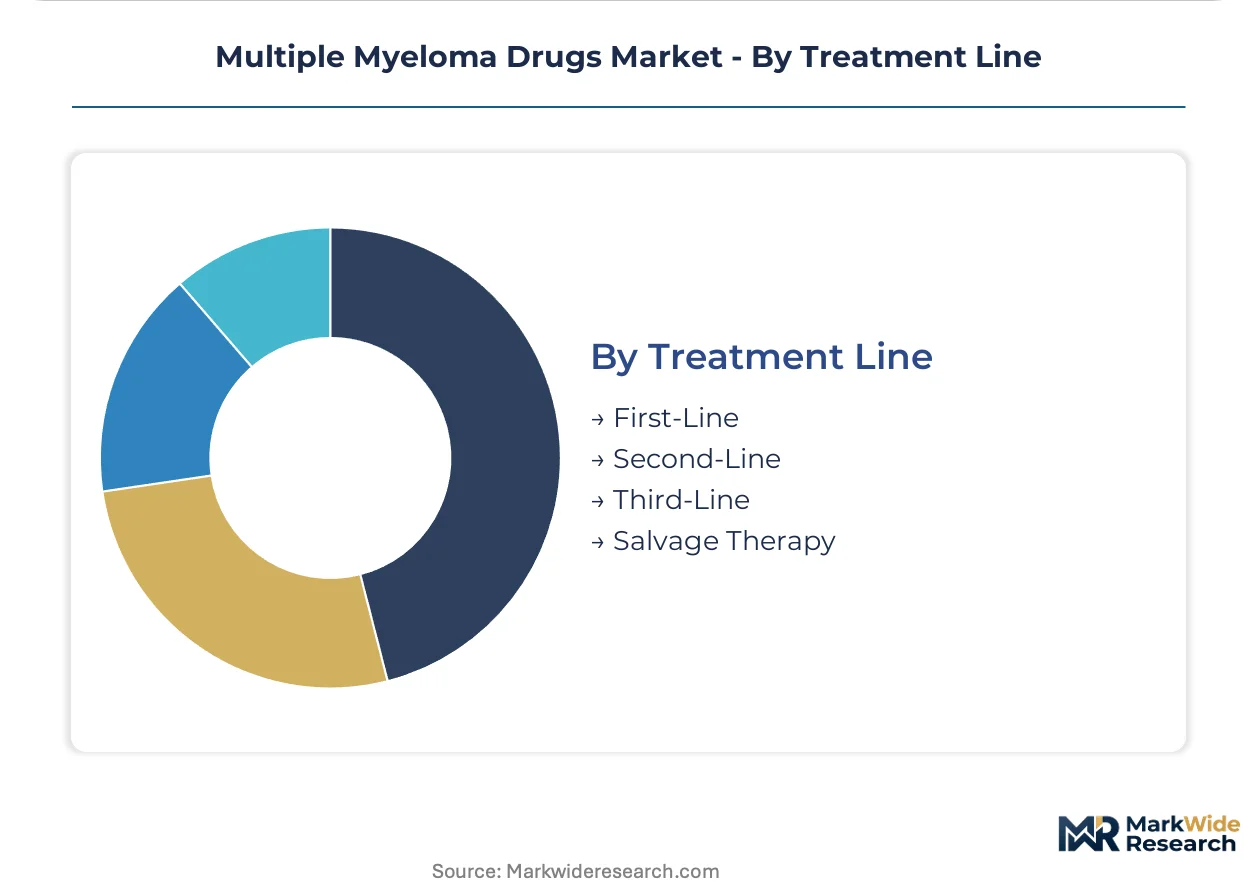
Treatment Line:
Line of therapy determines combination complexity and regulatory pathway requirements.
- First-Line:Quadruplet regimens now standardize across United States NCCN guidelines, requiring oncology practices to stock four drug classes simultaneously. Hospital pharmacy directors negotiate bundled contracts to manage working capital.
- Salvage Therapy:Heavily pretreated patients receive belantamab mafodotin or investigational CAR-T constructs under FDA accelerated approval. Academic medical centers in Boston and Houston build dedicated cellular therapy units to capture this high-acuity volume.
- Second-Line:First relapse after initial therapy drives daratumumab-based combination selection.
- Third-Line:Double-refractory status triggers CAR-T or bispecific antibody consideration.
First-Line holds installed capacity. Salvage Therapy is rotating up the share rankings as cellular platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical exports flow into European hospital procurement networks and Japanese specialty pharmacy channels, establishing trans-Atlantic and trans-Pacific corridors for monoclonal antibody distribution.
United States
Medicare reimbursement structures favor novel agents in the relapsed setting, concentrating demand among hospital oncology departments. FDA breakthrough therapy designations compress development timelines for cellular platforms. Boston and Houston academic medical centers build dedicated CAR-T units to capture high-acuity salvage therapy volume.
Germany
EMA parallel scientific advice shapes multinational trial design for German-headquartered manufacturers seeking synchronized EU market entry. Germany's G-BA health technology assessment conditions provisional coverage on post-marketing survival commitments. The Rhine-Ruhr pharmaceutical cluster anchors proteasome inhibitor production capacity serving central European distribution networks.
Japan
PMDA sakigake designation accelerates review timelines for antibody-drug conjugates addressing unmet need in elderly populations. METI industrial policy supports domestic viral vector manufacturing for regional CAR-T supply. The Kanto region's Tokyo-Osaka corridor concentrates hematology specialization and companion diagnostic development.
Switzerland
Swissmedic's alignment with FDA evidentiary standards enables rapid parallel submission strategies for bispecific antibody platforms. The country's specialized contract manufacturing organizations concentrate sterile compounding capacity for antibody-drug conjugates. Basel's pharmaceutical cluster integrates conjugation chemistry expertise with cold-chain logistics infrastructure.
India
CDSCO's accelerated approval pathway for proteasome inhibitor biosimilars enables first-mover positioning in emerging oncology infrastructure. The country's central bank monitors pharmaceutical import financing for hospital procurement. Maharashtra's Mumbai-Pune corridor anchors biosimilar manufacturing scale serving domestic and export markets.
Multiple Myeloma Drugs Market Key Industry Players
Listed leaders compete with private specialists across immuno-oncology platform depth, creating a tiered structure where integrated biopharmaceutical corporations hold front-line quadruplet share while specialized hematology units capture salvage therapy niches. The competitive landscape segments into three archetypes: integrated immuno-oncology platforms, subcutaneous administration specialists, and cellular therapy manufacturers. Dominant competitive moves include strategic partnerships for bispecific antibody co-development and capacity expansion in viral vector manufacturing.
Within the integrated platform tier, Bristol-Myers Squibb and Johnson & Johnson occupy positions spanning the treatment continuum from induction through relapsed settings. Amgen Inc. exemplifies the subcutaneous administration archetype with manufacturing scale advantages in patient-preferred delivery formats. These three anchors represent distinct strategic vectors: platform breadth, administration innovation, and hematology specialization depth.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Amgen Inc. |
| Takeda Pharmaceutical Company |
| Johnson & Johnson |
| Novartis AG |
| Sanofi |
| AbbVie Inc. |
| Janssen Biotech |
| Merck & Co. |
| Others |
Cost & Logistics Intelligence
Fourteen-day vein-to-vein timelines for autologous CAR-T production concentrate manufacturing among three specialized contract manufacturing organizations in the United States and Switzerland, compressing pricing power for branded antibody-drug conjugates while elevating biosimilar pressure on mature proteasome inhibitor portfolios. This supply concentration enables premium salvage therapy pricing but exposes hospital procurement budgets to capacity-driven allocation delays.
Pricing Analysis
Next-generation bispecific antibody platforms command three-to-four-fold premiums over prior-generation proteasome inhibitors, while current-generation monoclonal antibodies occupy a contracting middle tier. Contract-based long-term offtake agreements dominate hospital formulary placement, with price differentiation driven by FDA breakthrough therapy designation status and cold-chain certification tier. Pricing pressure stems from bortezomib biosimilar erosion in Medicare-funded infusion centers, compressing branded revenue windows. Community oncology practices exhibit highest price sensitivity due to limited cold-chain infrastructure capital, while academic medical centers with dedicated cellular therapy units demonstrate lowest sensitivity.
Supply Chain Analysis
The United States and Switzerland anchor sterile compounding capacity for antibody-drug conjugates, while India concentrates proteasome inhibitor biosimilar production. Manufacturing draws from Chinese-sourced active pharmaceutical ingredients, Swiss-engineered conjugation chemistry kits, and patient-specific viral vectors produced in regional cleanroom facilities. Single-source vulnerability concentrates in the three contract manufacturing organizations handling sterile fill-finish operations for daratumumab-based regimens. Distribution runs through hospital pharmacy direct purchasing and specialty pharmacy channels serving outpatient oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiple myeloma drug markets present a service-attach opportunity as outcome-based formulary contracts and real-world evidence monitoring expand faster than hardware-only molecule sales, creating recurring revenue layers for logistics and adherence platforms.
For Market Incumbents: Fortify market position through captive supply of viral vector manufacturing capacity in Boston and Houston cellular therapy corridors, while deepening hematology specialization across the treatment continuum to defend against bispecific antibody platform entrants. Invest in FDA breakthrough therapy designation maintenance through confirmatory survival trial acceleration. Priority lever rests on backward integration into conjugation chemistry to secure antibody-drug conjugate margins. For New Entrants and Emerging Players: Differentiate on subcutaneous administration innovation targeting community oncology practices in Florida and Texas, where cold-chain infrastructure gaps create white-space for patient-preferred delivery formats. Penetrate the smoldering myeloma prevention segment enabled by NCI S1011 trial frameworks, expanding treatable populations before end-organ damage. Go-to-market angle centers on risk-stratified intervention protocols with companion diagnostic bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents divesting mature proteasome inhibitor portfolios facing biosimilar erosion, presenting acquisition opportunities for specialized hematology units seeking installed base revenue. Long-term viability frames around cellular therapy manufacturing scale and bispecific antibody platform maturation over the coming decade. Signal to watch: CMS national coverage determination shifts redirecting hospital procurement budgets between CAR-T and bispecific modalities.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerated FDA breakthrough therapy designations compress phase-three timelines for CAR-T platforms. |
| Manufacturing Scale-Up | Viral vector capacity expansion in Boston and Houston reduces vein-to-vein bottlenecks for autologous therapies. |
| Regulatory Approval Pathway | EMA parallel scientific advice synchronizes EU market entry with FDA accelerated approval timelines. |
| Licensing Agreement | Bispecific antibody co-development partnerships redistribute patient flows between academic and community settings. |
| Pipeline Diversification | Smoldering myeloma prevention portfolios expand addressable populations through NCI S1011 trial frameworks. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling triangulated with top-down pharmaceutical revenue estimates across treatment lines and administration routes.
Across the projection horizon, the analytical framework modeled segmentation dimensions including treatment line, drug type, administration route, and regional regulatory cluster. CAGRs were derived from patient population epidemiology, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated Medicare reimbursement policy shifts and biosimilar launch sequencing.
The analysis sits within stated boundaries; outcomes outside FDA accelerated approval pathway continuity, CMS coverage determination stability, or cold-chain infrastructure investment rates would require recalibration. Forecasts reflect documented assumptions regarding patient eligibility criteria, trial enrollment velocities, and manufacturing capacity expansion schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Pharmaceutical Warehousing Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Hydroxypropyl Methylcellulose (HPMC) Capsules Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Antiviral Drugs Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Hospital Pharmaceuticals Market