
 Global Chickenpox Vaccine Market | 2026-2036
Global Chickenpox Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chickenpox Vaccine Market Foresight
Combination vaccine bundling is consolidating buyer preference around measles-mumps-rubella-varicella (MMRV) formulations rather than standalone varicella shots. Merck & Co. leverages decades of live-attenuated virus expertise to anchor North American supply contracts. GlaxoSmithKline plc competes through differentiated adjuvant platforms that extend shelf stability in tropical climates. Serum Institute of India Pvt. Ltd. dominates public-sector procurement across South Asia with cost-optimized manufacturing scale.
Chickenpox vaccines contain live attenuated varicella-zoster virus (Oka strain) at minimum titers of 10^3.3 plaque-forming units per dose, formulated with stabilizers such as sucrose, hydrolyzed gelatin, and monosodium glutamate to maintain potency during frozen storage at -15°C or colder. Live attenuated products lead volume due to proven duration of cellular immunity and established cold-chain protocols. Subunit and recombinant platforms represent the fastest-growing technology segment as manufacturers seek thermostable alternatives for last-mile distribution. Pediatric clinics and public health centers capture the deepest margin pools through recurring birth-cohort demand and government-reimbursed administration fees.
The FDA mandates lot-release potency testing under 21 CFR 630, while the WHO prequalification program sets international standards for varicella vaccine stability and immunogenicity benchmarks. India's CDSCO enforces local clinical bridging studies for imported live vaccines, shaping market access timelines for multinational suppliers. Stakeholders must monitor evolving combination-product labeling requirements and decide between standalone versus bundled portfolio investments before regulatory deadlines tighten.
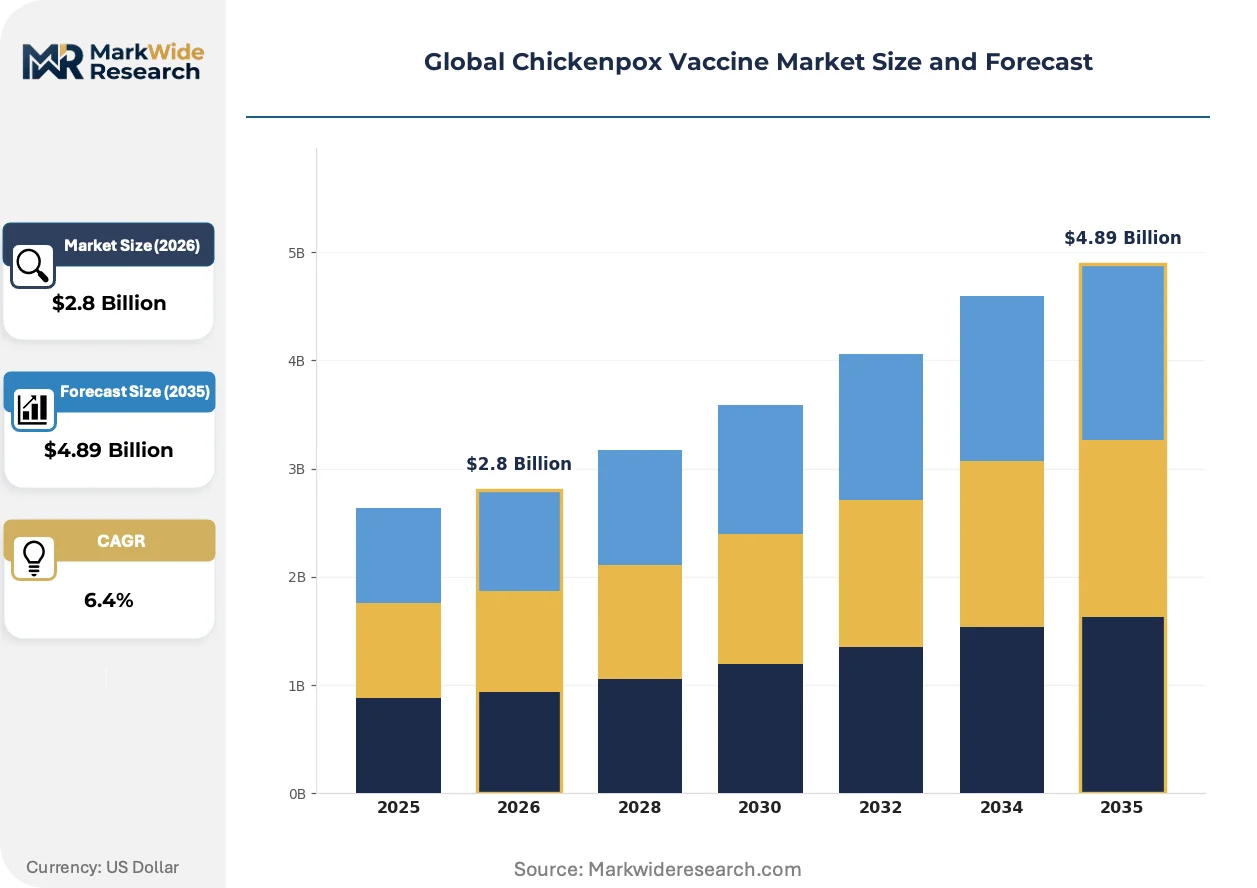
Market Dynamics
The transition from standalone varicella vaccines to combination MMRV formulations is restructuring procurement patterns and manufacturing capacity allocation across immunization programs worldwide. Regulatory agencies in multiple geographies are tightening stability requirements for live-attenuated products, forcing reformulation investments and cold-chain upgrades.
Growth Catalysts
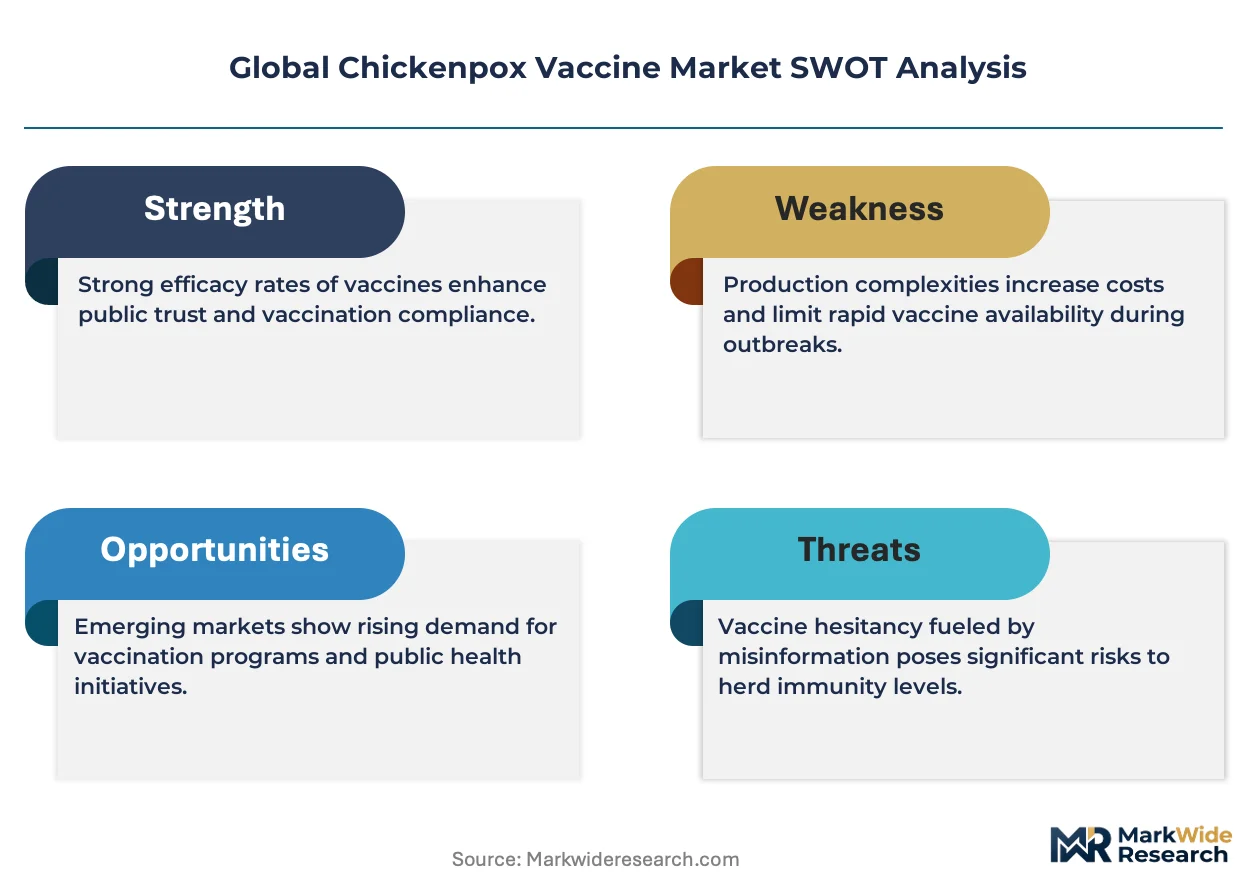
- National immunization program expansions:India's Universal Immunization Programme is adding second-dose varicella schedules for adolescents, creating sustained birth-cohort demand through public-sector procurement channels.
- WHO prequalification pathway:Manufacturers pursuing WHO prequalification for varicella-containing combination vaccines gain accelerated access to Gavi-eligible countries and UNICEF tender processes.
- Lyophilization advances:Improved freeze-drying technologies are extending shelf stability of live-attenuated doses, reducing wastage rates in tropical climates with intermittent cold-chain reliability.
Market Restraints
- MRC-5 cell substrate dependence:Continued reliance on human diploid cell lines for virus propagation creates supply concentration risk with limited qualified global suppliers.
- Frozen storage infrastructure gaps:Last-mile distribution in rural Indonesia, Nigeria, and Bangladesh lacks -15°C or colder capacity, constraining live-attenuated product reach.
- EMA combination-product labeling friction:Tightened stability-testing requirements for MMRV formulations are extending approval timelines and raising regulatory compliance costs for new entrants.
Strategic Opportunities
- Thermostable recombinant platforms:Subunit vaccines eliminating cold-chain dependence can penetrate last-mile gaps in sub-Saharan Africa where frozen storage is unavailable.
- Adult revaccination segments:Susceptible adult populations in Japan and South Korea represent underpenetrated cohorts as childhood vaccination coverage approaches saturation.
- CDSCO local bridging study waivers:India's regulator is piloting abbreviated approval pathways for varicella vaccines with established WHO prequalification, compressing market access timelines.
Industry Challenges
- Cell culture specialist scarcity:Qualified personnel for live virus propagation in MRC-5 or WI-38 substrates are concentrated among legacy manufacturers, constraining capacity expansion.
- 21 CFR 630 lot-release testing timelines:FDA-mandated potency verification creates batch-to-batch release delays that complicate just-in-time supply contracts with national immunization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chickenpox Vaccine Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, Subunit, Conjugate, Recombinant End User: Hospitals, Pediatric Clinics, Public Health Centers, Immunization Programs, School Health Services Distribution Channel: Pharmacies, Hospital Pharmacies, Online Pharmacies, Vaccine Wholesalers, Government Supplies Application Setting: Routine Immunization, Outbreak Control, Travel Vaccination, Workplace Programs, Maternal Immunization |
| Companies Covered | CSL Limited, Serum Institute of India Pvt. Ltd., Merck & Co., GlaxoSmithKline plc, Bharat Biotech, Sanofi Pasteur, Pfizer Inc., Emergent BioSolutions Inc., Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chickenpox Vaccine Market Shifts & Advancements
Manufacturers are redirecting R&D investment toward thermostable formulations and combination platforms that reduce cold-chain burden while simplifying immunization schedules. These shifts are compressing the viability window for standalone varicella products and rewarding integrated vaccine portfolios.
Recombinant subunit platforms incorporating varicella-zoster virus glycoprotein E are absorbing development resources previously allocated to improved live-attenuated strains. Pediatric clinics in Southeast Asia are piloting these candidates in controlled-temperature chain trials. The technology is absorbing market share projections from conventional frozen products in regions with unreliable cold infrastructure.
FDA's tightened interpretation of 21 CFR 630 for combination varicella-containing products is mandating enhanced stability validation protocols. Manufacturers must now demonstrate potency maintenance through accelerated degradation studies under variable humidity conditions. MMRV formulations from European suppliers face the steepest compliance burden as they seek US market entry.
Public-sector buyers are consolidating procurement around bundled combination schedules rather than standalone varicella doses. UNICEF and PAHO tender processes now preference MMRV over monovalent options where national programs have adopted measles-mumps-rubella baselines. This preference shift is most visible in Latin American ministries of health transitioning from separate administration to single-visit protocols.
Global Chickenpox Vaccine Market Segmentation
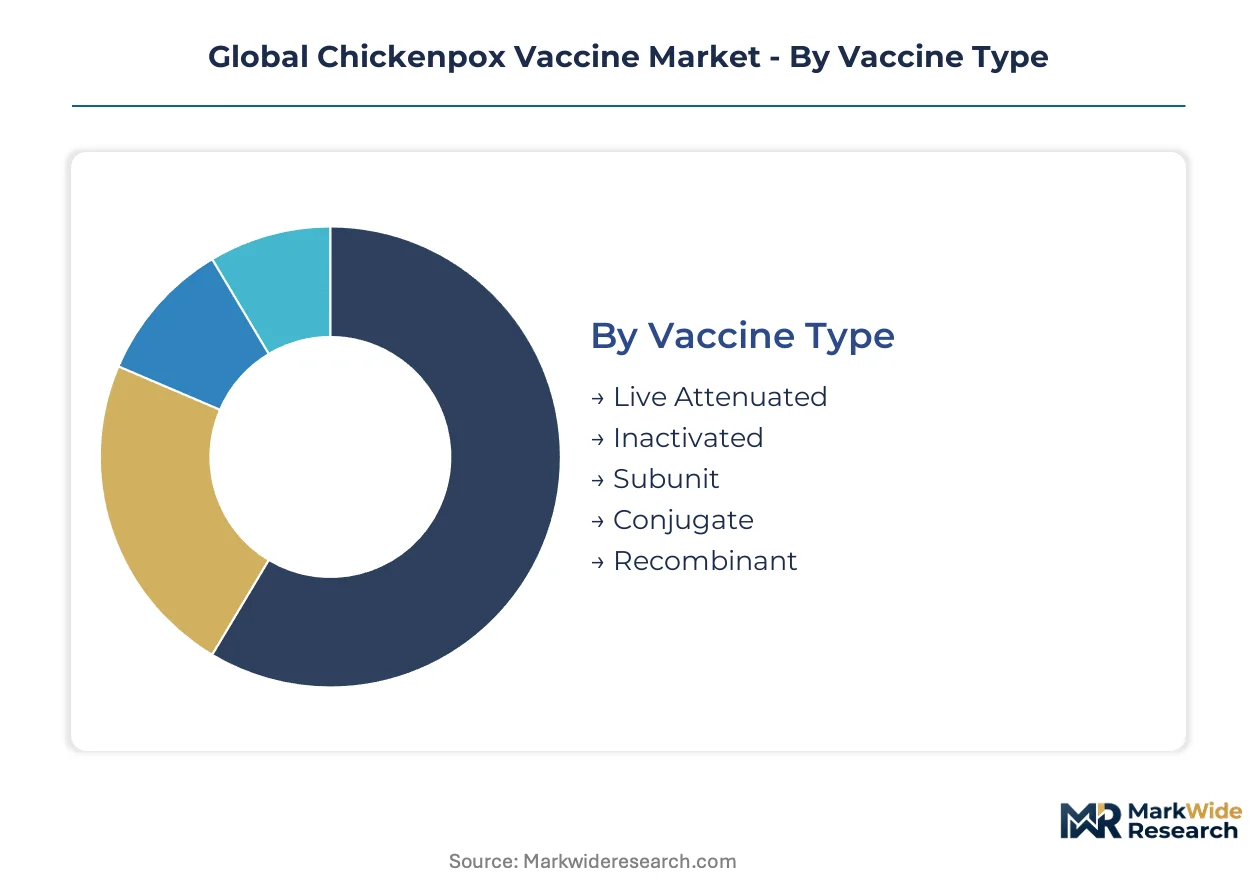
Chickenpox vaccine procurement patterns diverge sharply between standalone varicella products and combination formulations bundled with measles-mumps-rubella antigens. Understanding these segment boundaries clarifies where manufacturers must invest in cold-chain infrastructure versus thermostable platform development.
Vaccine Type:
Live-attenuated formulations dominate current procurement volumes through established immunization schedules, while recombinant platforms are displacing legacy products in tropical distribution environments.
- Live Attenuated:Contains Oka-strain varicella-zoster virus at minimum 10^3.3 plaque-forming units per dose, formulated with sucrose and hydrolyzed gelatin stabilizers. Demand concentrates in India's Universal Immunization Programme and Southeast Asian national programs where -15°C frozen storage infrastructure exists; cold-chain reliability gaps in rural Indonesia and Nigeria constrain penetration.
- Recombinant:Glycoprotein E-based subunit platforms eliminate frozen storage requirements through protein-engineered thermostability. Pediatric clinics in Bangladesh and sub-Saharan Africa are piloting controlled-temperature chain trials; WHO prequalification pathways accelerate Gavi-eligible country access.
- Inactivated:Heat-killed whole-virus preparations with reduced immunogenicity profiles suit immunocompromised populations excluded from live-virus schedules.
- Subunit:Purified viral protein formulations bridge efficacy and stability requirements for intermediate climate zones.
- Conjugate:Polysaccharide-protein linked constructs remain experimental for varicella applications with limited commercial deployment.
Volume placements concentrate in Live Attenuated; the faster expansion belongs to Recombinant.
End User:
Margin capture varies across administration settings based on reimbursement structures and birth-cohort predictability.
- Pediatric Clinics:Private-sector administration in urban India and Vietnam generates premium pricing through insured families seeking convenient scheduling outside public-sector queues.
- Public Health Centers:Government-reimbursed volume in Brazil and Mexico operates on tender-based procurement with thin per-dose margins offset by scale.
- Hospitals:Specialized immunization units manage breakthrough varicella cases and adult susceptibility screening in Japan's aging demographic.
- Immunization Programs:National program procurement across Gavi-eligible countries drives UNICEF tender participation with stringent WHO prequalification requirements.
- School Health Services:Mandatory vaccination verification for enrollment in South Korea and parts of Australia creates predictable adolescent-cohort demand.
Revenue pools are deepest in Pediatric Clinics; Immunization Programs deliver the steepest volume trajectory.
Distribution Channel:
Cold-chain integrity requirements shape channel viability for temperature-sensitive live-attenuated products versus ambient-stable alternatives.
- Government Supplies:Direct national program procurement in India, Indonesia, and Nigeria bypasses retail markup through centralized cold-chain depots.
- Vaccine Wholesalers:Regional distributors with validated -15°C storage capacity serve private hospitals and clinics across Latin American metropolitan corridors.
- Hospital Pharmacies:Captive dispensing within integrated health systems manages inventory for immediate administration in US and European acute care settings.
- Pharmacies:Retail access points in Thailand and Malaysia support out-of-pocket purchases for second-dose schedules outside public program timing.
- Online Pharmacies:Digital procurement platforms emerging in South Korea and UAE face regulatory scrutiny for cold-chain custody documentation.
Shipment volumes flow heaviest through Government Supplies; Vaccine Wholesalers are climbing the fastest as private-sector coverage expands.
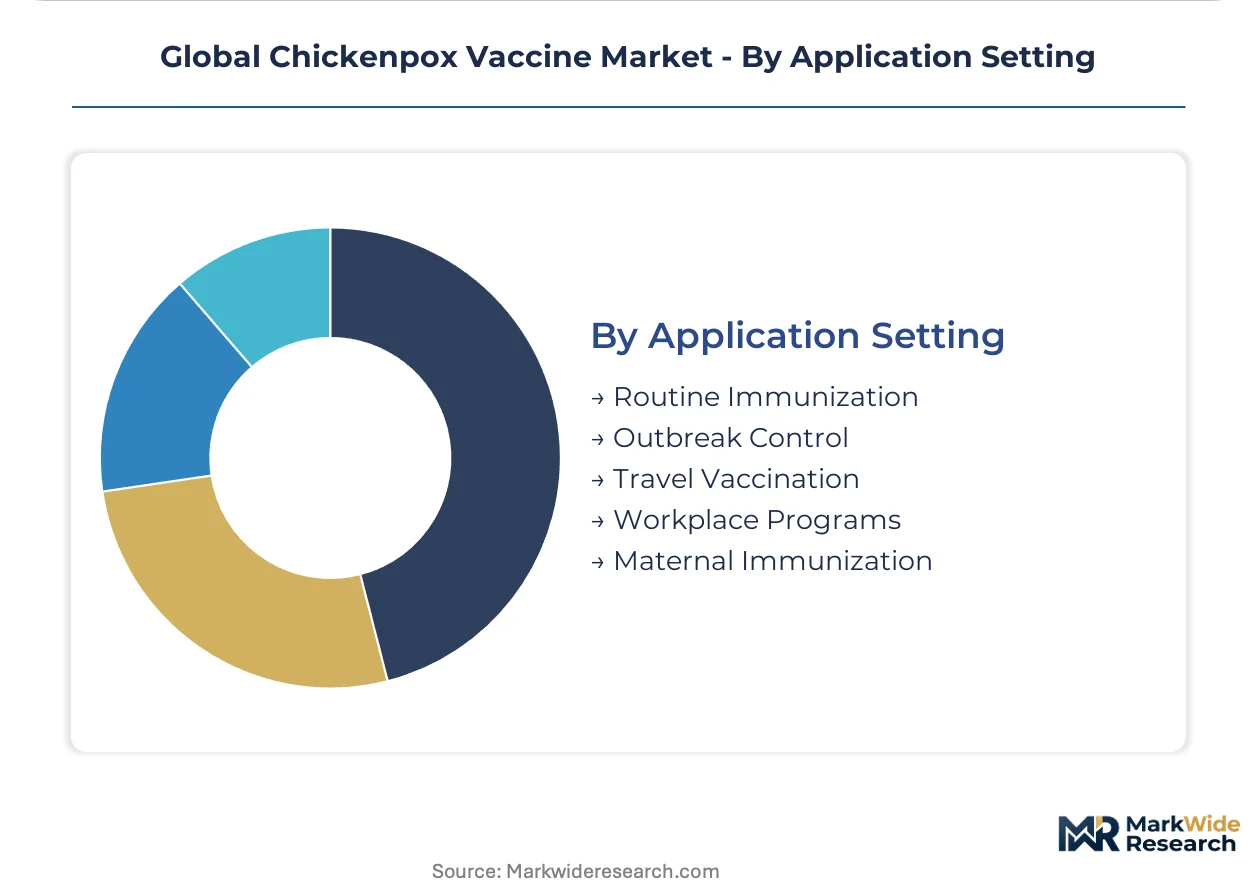
Application Setting:
Program design determines whether doses deploy through scheduled routine visits or reactive campaign modalities.
- Routine Immunization:Birth-cohort scheduling in India's expanded adolescent varicella program and Southeast Asian second-dose introductions sustains predictable manufacturer offtake.
- Outbreak Control:Reactive ring-vaccination campaigns in institutional settings such as schools and military barracks demand rapid cold-chain mobilization.
- Travel Vaccination:Pre-departure requirements for varicella-susceptible adults visiting endemic regions generate sporadic private-clinic demand in Japan and Western Europe.
- Workplace Programs:Healthcare worker susceptibility screening and vaccination in US hospital systems addresses occupational exposure liability.
- Maternal Immunization:Antenatal varicella serology testing and postpartum catch-up dosing in Australian and Canadian protocols protects neonates from congenital exposure.
Dose volumes anchor in Routine Immunization; Outbreak Control applications are gaining share fastest as surveillance sensitivity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in India and the United States while consumption accelerates across Southeast Asian national immunization programs. Cold-chain infrastructure gaps in tropical zones are redirecting investment toward thermostable formulation R&D. Regulatory divergence between FDA stability mandates and CDSCO bridging requirements is fragmenting approval pathways.
United States
Pediatric clinics in Texas and Florida drive private-sector volume through insured second-dose schedules. FDA enforces 21 CFR 630 lot-release potency testing that extends batch verification timelines. The Research Triangle Park cluster in North Carolina anchors live-attenuated virus propagation expertise for domestic supply security.
India
Universal Immunization Programme expansion into adolescent varicella cohorts sustains public-sector procurement at scale. CDSCO requires local clinical bridging studies for imported live vaccines, compressing market access for multinational entrants. Pune and Hyderabad manufacturing corridors dominate cost-optimized bulk antigen production for Gavi-eligible tenders.
Indonesia
National program adoption of two-dose schedules generates birth-cohort demand across Java and Sumatra. The national pharmaceutical regulator mandates cold-chain custody documentation for all varicella-containing products entering government supply channels. Jakarta's metropolitan immunization depots struggle with last-mile -15°C reliability, constraining live-attenuated penetration into Eastern provinces.
Germany
EMA combination-product labeling requirements for MMRV formulations are extending approval timelines for European suppliers seeking US market entry. Bavaria's vaccine manufacturing corridor specializes in adjuvant-stabilized platforms for tropical climate distribution. The Standing Committee on Vaccination recommends varicella catch-up protocols for susceptible adolescents in federal school health programs.
Brazil
PAHO tender preferences for bundled measles-mumps-rubella-varicella schedules are consolidating procurement around combination platforms. ANVISA enforces stability validation protocols aligned with WHO prequalification standards for public-sector supply. São Paulo's immunization program anchors national rollout infrastructure, with Rio de Janeiro piloting controlled-temperature chain trials for thermostable candidates.
Global Chickenpox Vaccine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and distribution capabilities. The structure consolidates around three tiers: legacy live-attenuated manufacturers with decades of cold-chain expertise, emerging recombinant platform developers, and public-sector cost-optimized suppliers. Archetypes include integrated vaccine portfolios spanning multiple antigens, standalone varicella specialists, and regional tender-focused manufacturers. Competitive moves center on thermostable formulation licensing and strategic partnerships for last-mile distribution in tropical climates.
Within the diversified pharmaceutical tier, Merck & Co. and GlaxoSmithKline plc occupy positions anchored by decades of live-attenuated virus expertise and combination product portfolios. Serum Institute of India Pvt. Ltd. exemplifies the cost-optimized public-sector archetype, leveraging manufacturing scale to dominate South Asian immunization program tenders. These three entities represent distinct strategic positions: legacy innovation capacity, integrated adjuvant platforms, and volume-driven emerging market access.
| Leading Market Players |
|---|
| CSL Limited |
| Serum Institute of India Pvt. Ltd. |
| Merck & Co. |
| GlaxoSmithKline plc |
| Bharat Biotech |
| Sanofi Pasteur |
| Pfizer Inc. |
| Emergent BioSolutions Inc. |
| Takeda Pharmaceutical Company Limited |
| Others |
Supply & Pricing Matrix
WHO prequalification mandates and FDA stability-testing requirements gate qualified supply and premium-tier pricing access for varicella-containing products. Manufacturers lacking validated cold-chain documentation or accelerated degradation data face exclusion from government tenders and private-sector premium positioning.
Pricing Analysis
Price erosion across public-sector tenders traces to UNICEF and Gavi procurement consolidation around volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified MMRV bundles from standalone varicella doses and non-prequalified regional alternatives. Cost-down pressure on economy-tier suppliers accelerates because India's CDSCO and Indonesia's national pharmaceutical regulator mandate local bridging studies that extend approval timelines. Pediatric clinics in urban India and Vietnam exhibit lowest price sensitivity through insured out-of-pocket purchases, while immunization programs in Gavi-eligible countries drive hardest bargain terms.
Supply Chain Analysis
Dual-sourcing requirements from UNICEF and PAHO tender processes mandate multi-supplier qualification for MRC-5 cell substrates and live-attenuated virus seeds. Manufacturing gravity centers on India, the United States, and Germany for bulk antigen production and adjuvant formulation. Supply chains draw from qualified human diploid cell lines, sucrose stabilizer grades, and gelatin hydrolysate inputs. Single-source vulnerability concentrates in MRC-5 substrate suppliers with limited global qualification. Distribution runs through government cold-chain depots in India and Indonesia, validated wholesaler networks in Brazil and Mexico, and hospital pharmacy captives in US integrated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with thermostable platform capabilities and WHO prequalification credentials, as EMA combination-product labeling friction and FDA 21 CFR 630 enforcement force subscale players toward exit.
For Market Incumbents: Anticipate regulatory deadline compression by accelerating lyophilization investments and combination-product stability validation before EMA and FDA tighten interpretation windows. Cell culture specialist scarcity threatens capacity expansion timelines; secure qualified personnel through backward integration into training partnerships with Indian and German biotechnology institutes. Defensive consolidation moves should prioritize thermostable recombinant platform licensing to neutralize last-mile distribution advantages of emerging entrants. For New Entrants and Emerging Players: Launch via controlled-temperature chain pilot programs in Bangladesh and sub-Saharan Africa where frozen infrastructure gaps exclude legacy live-attenuated suppliers. Adult revaccination segments in Japan and South Korea offer most penetrable white-space as childhood coverage saturates. CDSCO abbreviated approval pathways for WHO-prequalified products compress market access timelines; pursue prequalification submission before India's pilot program expands. For Investors and Strategic Acquirers: Thermostable recombinant platform Phase III trial initiations are the leading indicator that subunit technology is displacing live-attenuated market share in tropical distribution environments. Long-term viability over the coming decade favors manufacturers with integrated combination portfolios and established cold-chain partnerships rather than standalone varicella specialists. Acquisition target archetype: mid-scale recombinant developers with WHO prequalification submission readiness and regional distribution partnerships in Gavi-eligible countries.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Submission | Unlocks UNICEF tender access and Gavi-eligible country procurement channels. |
| Thermostable Formulation Development | Eliminates frozen storage dependence for last-mile penetration in Indonesia and Nigeria. |
| Combination Product Licensing | Aligns with PAHO and UNICEF preference shifts toward MMRV bundled schedules. |
| Cold-Chain Infrastructure Partnership | Secures validated distribution capacity for live-attenuated products in tropical climates. |
| Regulatory Bridging Study Investment | Accelerates CDSCO market access for multinational suppliers entering India's Universal Immunization Programme. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with vaccine development executives, regulatory affairs leads at multinational manufacturers, national immunization program managers, and hospital procurement directors combined with secondary validation from FDA 21 CFR 630 filings, EMA combination-product submissions, WHO prequalification assessment reports, and CDSCO approval databases. Bottom-up dose-volume modeling and top-down market sizing triangulation reconciled manufacturer shipment data with national program procurement disclosures.
Data-stream reconciliation across production capacity disclosures, tender award announcements, and cold-chain infrastructure investment tracking informed the analytical framework. Segmentation dimensions modeled include vaccine type, end-user setting, distribution channel, and application setting across the projection horizon. CAGRs derived from birth-cohort demand projections, second-dose schedule adoption curves, and replacement rates for thermostable alternatives. Industry-specific forecast inputs incorporated lyophilization technology maturation timelines and regulatory approval pathway duration estimates.
Regulatory interpretation shifts, cold-chain infrastructure buildout delays, and recombinant platform clinical trial outcomes are the dominant revision risks to the outlook. Deviation in WHO prequalification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Alkaptonuria Drugs Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Dermatological Drugs Market