
 In-Home Senior Care Franchises Market | 2026-2036
In-Home Senior Care Franchises Market Size, Share, and Industry Trends Forecast 2026-2036
In-Home Senior Care Franchises Market Foresight
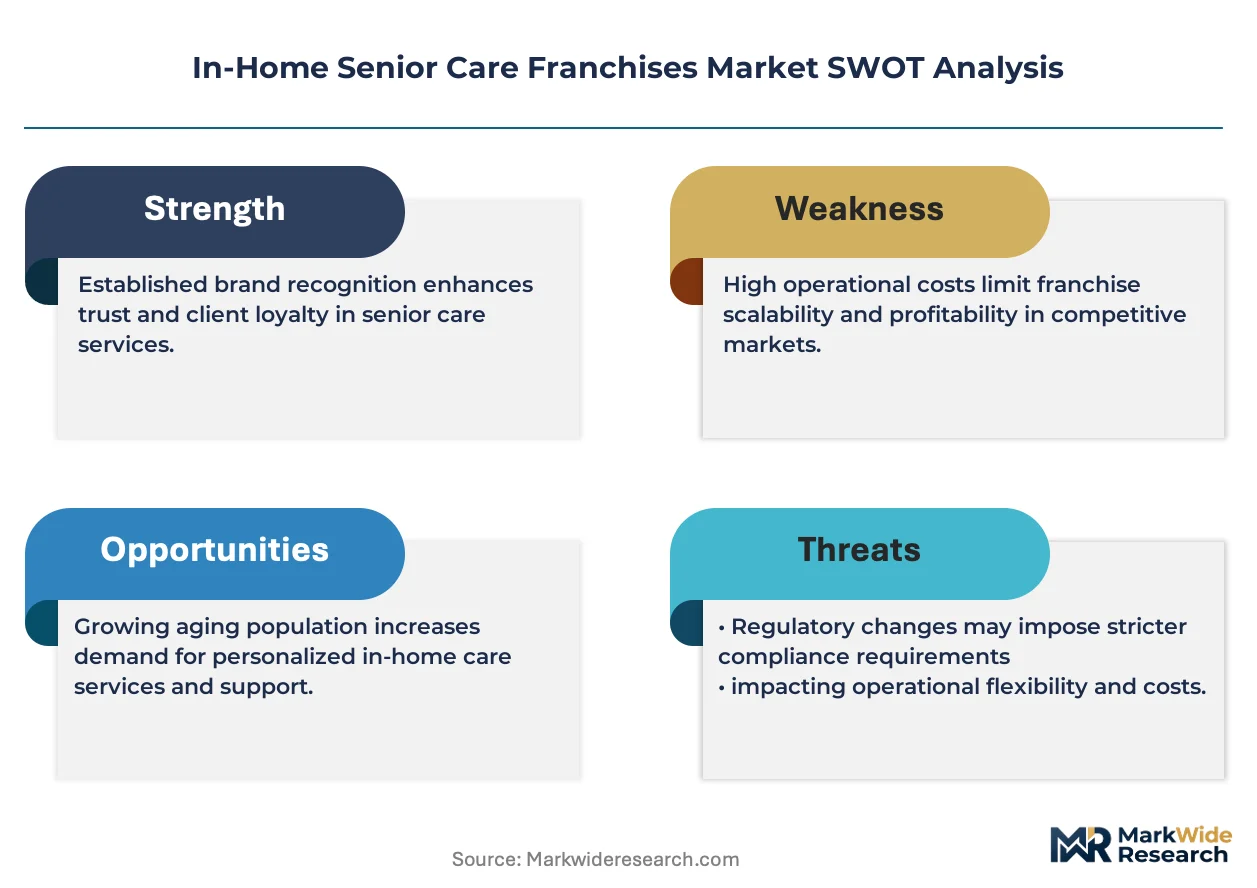
Subscription-based care planning is expanding how franchisees monetize ongoing client relationships beyond hourly service blocks. Home Instead Senior Care leverages its caregiver training infrastructure to sustain quality consistency across dispersed territories. Visiting Angels anchors its competitive position through national brand recognition and localized owner-operator models. Right at Home differentiates via specialized dementia care protocols that command premium service tiers.
In-home senior care franchises deliver non-medical and skilled health services to aging individuals within private residences, encompassing assistance with activities of daily living, medication reminders, mobility support, and companionship supervision delivered by trained caregivers under standardized operational protocols. The primary commercial purpose centers on enabling aging-in-place while reducing institutional care costs for families and public payers. Personal care and companionship segments dominate current revenue composition due to lower regulatory barriers and faster caregiver onboarding cycles. Home health services capture concentrated margin pools where Medicare certification and licensed nursing staff create defensible positioning. Multi-unit franchise models attract private equity interest through portfolio-scale operational efficiencies and centralized back-office functions.
State Medicaid agencies, the Centers for Medicare and Medicaid Services, and the Department of Veterans Affairs collectively shape reimbursement eligibility, caregiver background check mandates, and service documentation standards that determine franchise market access. OSHA guidelines and state-specific home care licensing boards further regulate worker classification, training hour minimums, and liability exposure for franchise operators. Stakeholders must monitor evolving state waiver program expansions and workforce classification rulings that could reshape unit economics across franchise networks.
Market Dynamics
Medicaid waiver program expansions across multiple states are restructuring reimbursement pathways for non-medical home care services, forcing franchise operators to reconfigure credentialing workflows and caregiver training protocols to maintain payment eligibility.
Growth Catalysts
- Sun Belt Retiree Migration:Interstate relocation patterns concentrate demand in Florida, Arizona, and Texas metropolitan corridors, creating dense service territories that reduce per-client acquisition costs for franchisees.
- 1915(c) Medicaid Waivers:State-level home and community-based services waivers expand eligibility for personal care assistance, opening public payer revenue streams previously restricted to institutional providers.
- Remote Caregiver Monitoring:GPS-enabled visit verification and electronic documentation systems reduce administrative overhead while satisfying state audit requirements for hours-based billing.
Market Restraints
- Labor Supply Compression:Tightening immigration enforcement and competing retail wages constrict available caregiver pools in suburban and exurban markets, elevating recruitment costs.
- Worker Classification Risk:State-level ABC test applications and Department of Labor overtime rulings threaten the independent contractor models that underpin variable cost structures in franchise networks.
- Skilled Nursing Substitution:Hospital-at-home programs and Medicare-certified home health agencies capture higher-acuity cases that might otherwise transition to private-pay personal care.
Strategic Opportunities
- Veterans Affairs Pension Benefit:The VA Aid and Attendance program remains underutilized by eligible seniors, presenting untapped third-party payment capacity for franchises with benefits counseling capabilities.
- Dementia Care Specialization:Teepa Snow and other standardized behavioral intervention certifications enable premium rate tiers for Alzheimer's and related dementias clients.
- Hospital Discharge Integration:Partnerships with accountable care organizations and bundled payment participants position franchises as preferred post-acute transitional care vendors.
Industry Challenges
- Caregiver Retention Velocity:Annual turnover rates exceeding sixty percent in direct care roles exhaust training investments and destabilize client relationship continuity.
- State Licensure Fragmentation:Non-uniform training hour requirements, supervisor ratios, and background check standards across fifty state jurisdictions multiply compliance architecture costs for multi-unit operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Home Senior Care Franchises Market |
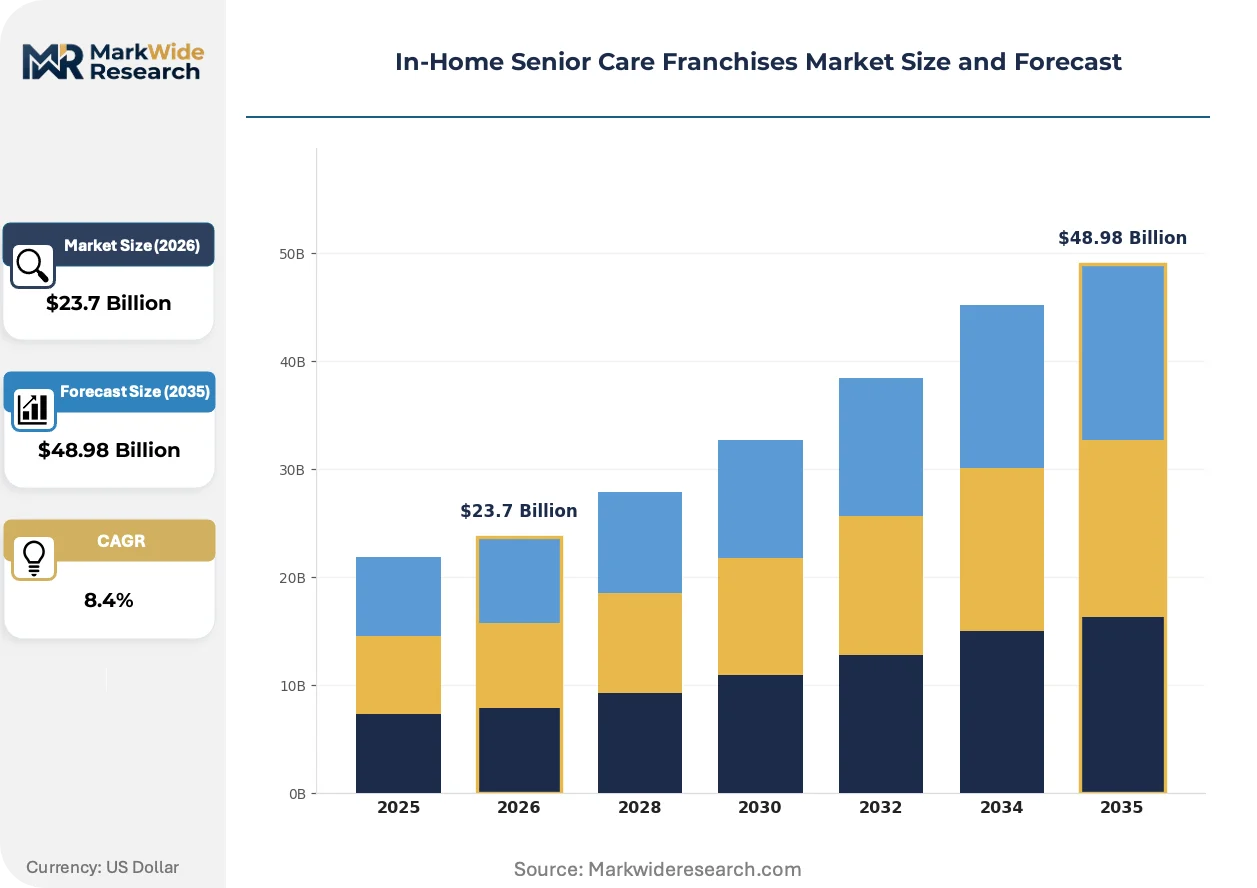
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Care, Companionship, Home Health, Respite Care End User: Individuals, Families, Seniors, Disabled Persons Funding Source: Private Pay, Insurance, Medicaid, Veteran Affairs Franchise Model: Single Unit, Multi-Unit, Master Franchise, Conversion Franchise |
| Companies Covered | Comfort Keepers, Senior Helpers, Home Instead Senior Care, Always Best Care, Synergy HomeCare, Visiting Angels, BrightStar Care, FirstLight Home Care, Right at Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Home Senior Care Franchises Market Shifts & Advancements
Digital workforce management platforms and predictive scheduling algorithms are compressing the gap between caregiver availability and real-time client demand, while regulatory pressure on worker classification accelerates operational model experimentation across franchise networks.
Telehealth-integrated care coordination is consolidating remote patient monitoring data streams with in-home caregiver visit logs, enabling real-time escalation protocols for vital sign anomalies. Medicare Advantage plans and risk-bearing primary care groups are piloting these hybrid models in competitive metropolitan markets. The technology is consolidating previously siloed medical and non-medical care records into unified longitudinal profiles that justify outcome-based reimbursement contracts.
OSHA's renewed emphasis on bloodborne pathogen exposure controls and ergonomic injury prevention in home care settings is elevating mandatory training burdens and workers compensation premiums. State licensing boards are incorporating these federal guidelines into renewal requirements, particularly for agencies serving ventilator-dependent or bariatric clients. Franchise operators in California, New York, and Illinois face the steepest compliance cost escalations as these states adopt the most stringent interpretations.
Subscription-based care planning is displacing purely episodic hourly purchasing among adult children coordinating care for parents with progressive conditions. Adult children in tech-sector employment clusters around Seattle, Austin, and Raleigh-Durham demonstrate the highest adoption of these predictable budgeting models. The shift compresses revenue volatility for franchisees while lengthening average client lifetime value through embedded upsell pathways for specialized services.
In-Home Senior Care Franchises Market Segmentation
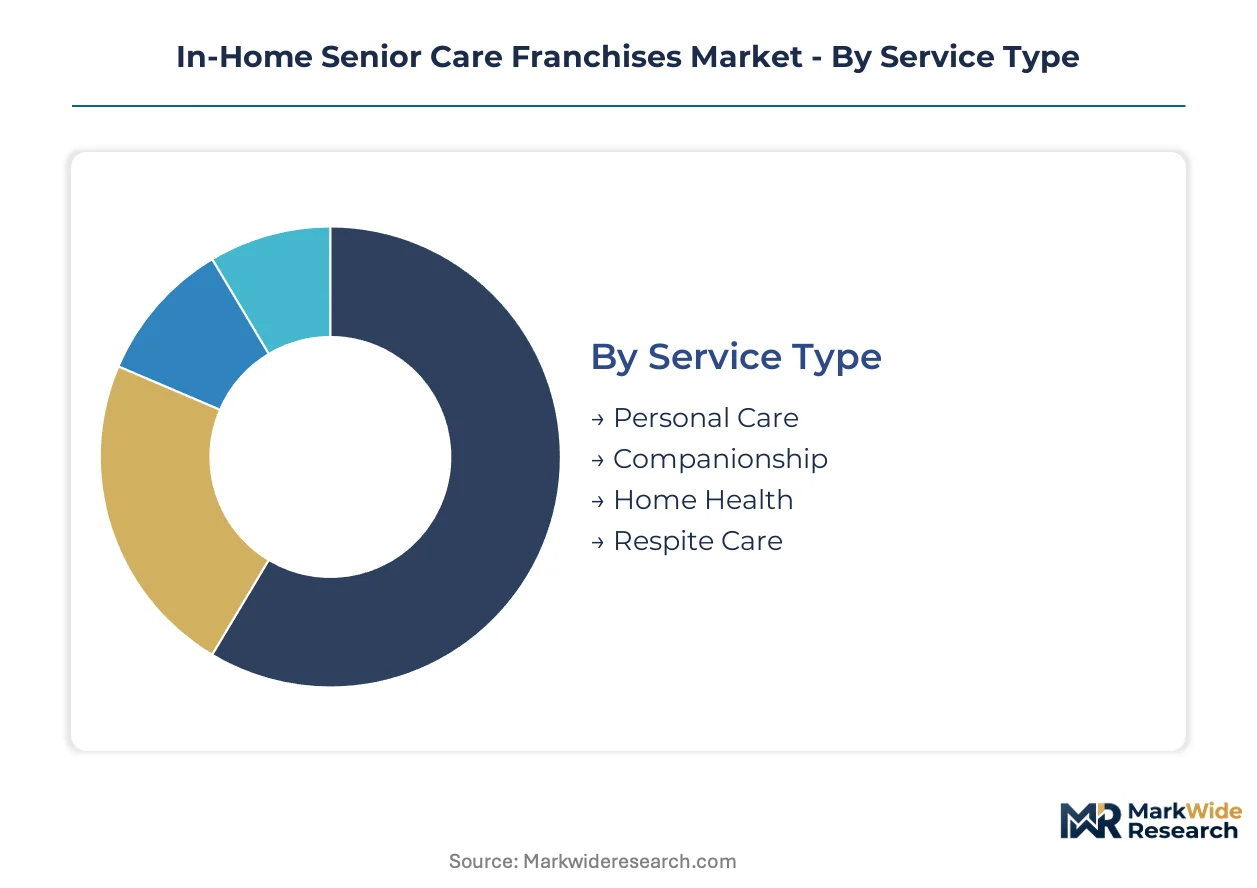
Segmentation reveals how franchise operators configure service portfolios to match divergent reimbursement pathways and client acuity profiles. Distinct operational models emerge across funding mechanisms and ownership structures, each demanding specialized compliance architecture and caregiver credentialing protocols.
Service Type:
Technology intensity and clinical sophistication define the service spectrum, ranging from unskilled assistance to licensed medical intervention requiring specialized equipment and documentation systems.
- Personal Care:Assistance with activities of daily living—bathing, dressing, grooming, toileting—delivered by certified nursing assistants under state-mandated supervision ratios. Demand concentrates in Florida and Arizona suburban corridors where retiree migration patterns cluster, driven by adult children seeking predictable hourly support for parents with mobility limitations but preserved cognitive function.
- Companionship:Non-hands-on supervision, meal preparation, medication reminders, and social engagement provided by caregivers without clinical certification. This segment expands most quickly in tech-sector employment clusters around Seattle and Austin, where subscription-based care planning models gain traction among time-constrained adult children.
- Home Health:Skilled nursing, physical therapy, and wound care requiring Medicare certification and licensed clinical staff. The segment captures concentrated margin pools where hospital-at-home program partnerships create preferred vendor status.
- Respite Care:Temporary relief coverage for family caregivers, typically structured in 4-hour minimum blocks or overnight shifts. Demand spikes correlate with state Medicaid waiver program expansions covering family caregiver support.
Mature deployment sits with Personal Care. Newer deployment is concentrated in Home Health as Medicare Advantage plans pilot outcome-based reimbursement contracts.
End User:
Client acuity and decision-making authority shape service customization, from self-directed seniors to proxy-arranged care for cognitively impaired individuals.
- Individuals:Self-paying seniors arranging services directly, typically exhibiting high health literacy and price sensitivity. This segment clusters in Sun Belt metropolitan areas with established retiree infrastructure.
- Families:Adult children coordinating care for aging parents, often across state lines, with purchasing authority concentrated in professional employment centers. The segment drives adoption of digital care coordination platforms and real-time visit verification systems.
- Seniors:The core demographic with progressive care needs spanning independent living through end-of-life support. Demand fragmentation across rural, suburban, and urban settings forces territory-specific caregiver recruitment strategies.
- Disabled Persons:Working-age adults with physical or developmental disabilities requiring long-term personal assistance. State Medicaid waiver programs dominate funding, with eligibility criteria varying substantially across jurisdictions.
Volume concentration rests with Seniors. Margin expansion is steepest among Families adopting premium subscription tiers.
Funding Source:
Reimbursement pathway determines credentialing burden, documentation intensity, and collection risk exposure for franchise operators.
- Private Pay:Direct client or family payment with highest margin realization and lowest administrative overhead. This segment anchors competitive positioning in affluent suburban territories where three-tier pricing structures separate premium dementia care from standard personal assistance.
- Insurance:Long-term care insurance claims processing with variable approval timelines and benefit caps. The segment demands specialized benefits counseling capabilities to navigate elimination periods and coverage exclusions.
- Medicaid:State-administered home and community-based services waivers with stringent caregiver background check mandates and electronic visit verification requirements. Reimbursement rates vary by state, compressing unit economics in jurisdictions with the lowest hourly allocations.
- Veteran Affairs:VA Aid and Attendance pension benefits and contracted home care services. This pathway remains underutilized relative to eligible population size, presenting untapped third-party payment capacity for franchises with accredited benefits advisors.
Operational stability is strongest in Private Pay. Public payer complexity is expanding fastest in Medicaid as 1915(c) waiver programs proliferate.
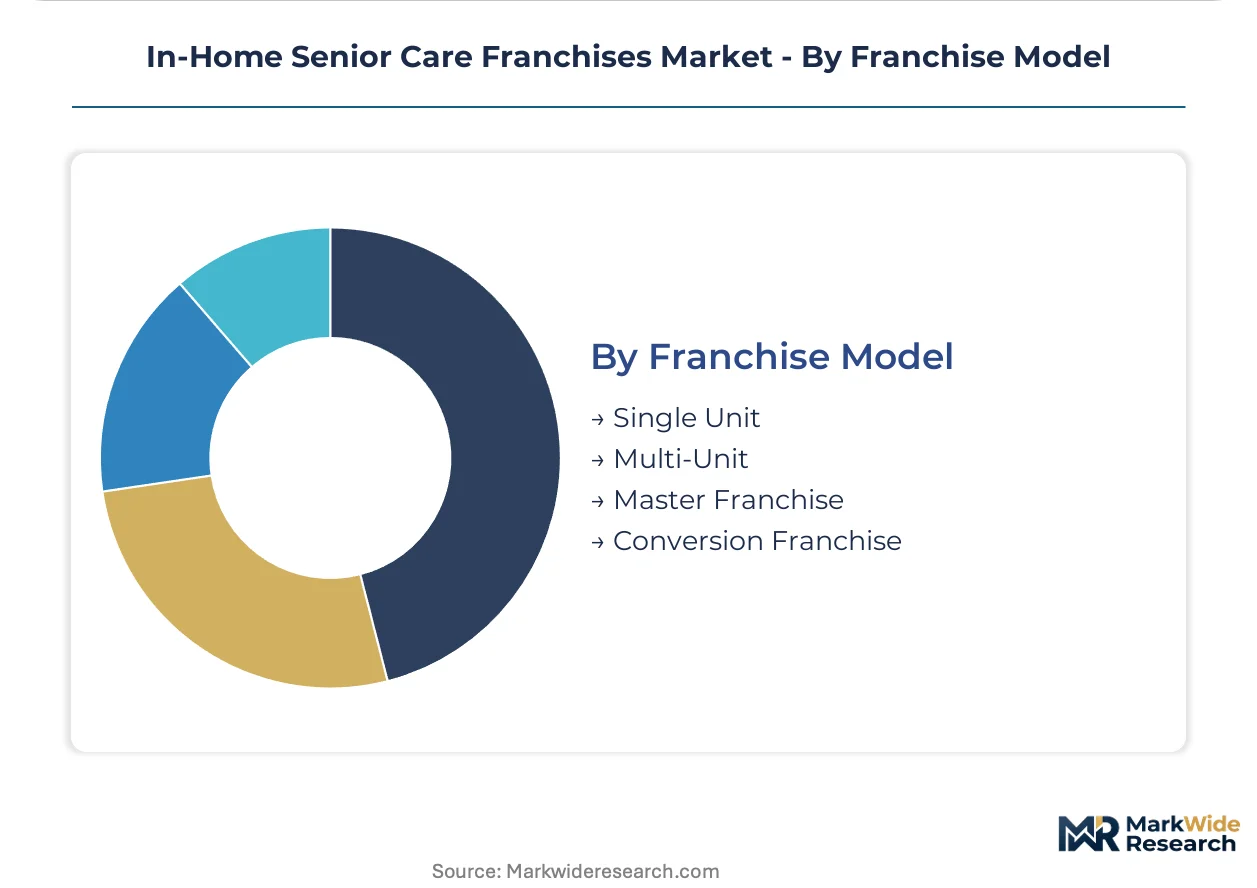
Franchise Model:
Capital deployment and operational control scale differentiate ownership structures, from single-territory entrepreneurs to portfolio-scale private equity platforms.
- Single Unit:Individual owner-operators managing one franchise territory with direct caregiver supervision. This model dominates entry-level franchise investment, with break-even timelines sensitive to local labor market conditions and client acquisition costs.
- Multi-Unit:Owners operating 3-15 territories with centralized back-office functions and shared caregiver pools. The structure attracts private equity interest through portfolio-scale operational efficiencies and cross-territory scheduling optimization.
- Master Franchise:Regional developers granted exclusive rights to sub-franchise within defined geographies, typically requiring substantial development schedules and infrastructure investment. The model concentrates in emerging markets with fragmented independent agency competition.
- Conversion Franchise:Existing independent home care agencies adopting franchise brand systems and operational protocols. This pathway accelerates network expansion while incorporating established client relationships and caregiver workforces.
Franchisor royalty dependence rests with Single Unit operators. Private equity capital is concentrating in Multi-Unit rollups with demonstrated compliance infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors franchise expansion across the Sun Belt corridor, where retiree migration concentrates demand for aging-in-place services. Interstate relocation patterns from the Northeast and Midwest funnel seniors into metropolitan clusters with established care infrastructure. State Medicaid waiver configurations determine reimbursement access and shape territory profitability.
United States
Florida, Arizona, and Texas metropolitan corridors absorb the highest inbound retiree flows, compressing client acquisition costs in dense suburban territories. The 1915(c) Medicaid Home and Community-Based Services waiver program expands eligibility for personal care assistance, opening public payer revenue streams. Dallas-Fort Worth operators leverage centralized back-office functions across multi-unit portfolios to optimize caregiver scheduling across dispersed territories.
Canada
Provincial health authority contracts dominate funding in Ontario and British Columbia, where aging demographics outpace institutional capacity expansion. Health Canada guidelines on home care licensing create uniform training standards that reduce compliance fragmentation. Toronto-area franchises concentrate on hospital discharge integration partnerships with accountable care organizations managing bundled payment contracts.
United Kingdom
Local authority commissioning frameworks reshape competitive positioning in England's metropolitan counties, where privatized domiciliary care markets mature. Care Quality Commission inspection regimes enforce standardized operational protocols across franchise networks. Southeast England operators, particularly around London commuter belts, command premium private-pay rates from affluent adult children coordinating parental care remotely.
Australia
Home Care Package funding reforms concentrate purchasing power with consumers in New South Wales and Victoria, accelerating franchise penetration against independent agencies. Aged Care Quality and Safety Commission registration requirements elevate barrier-to-entry for new market entrants. Sydney metropolitan franchises pilot subscription-based care planning models among tech-sector employment clusters seeking predictable budgeting structures.
Germany
Long-term care insurance (Pflegeversicherung) claims processing dominates reimbursement in Bavaria and North Rhine-Westphalia, where aging demographics drive service demand. Federal Ministry of Health training hour mandates standardize caregiver credentialing across state jurisdictions. Munich-area operators integrate specialized dementia care certifications to access premium rate tiers within the statutory insurance framework.
In-Home Senior Care Franchises Market Competitive Landscape
Capital-heavy multi-unit operators compete with asset-light single-territory owner-operators for regional market share. The vendor base stratifies across three tiers: national brands with centralized training infrastructure, regional consolidators with private equity backing, and independent agencies converting to franchise systems. Dominant competitive moves include multi-unit rollup acquisitions and hospital discharge partnership formations that secure preferred vendor status.
Within the national brand tier, Home Instead Senior Care and Visiting Angels exemplify divergent approaches to quality consistency across dispersed territories. Right at Home anchors specialized positioning through dementia care protocol differentiation. BrightStar Care occupies a position bridging non-medical personal care and Medicare-certified skilled nursing services. The competitive dynamic centers on caregiver retention velocity and state licensure compliance architecture as primary differentiation vectors.
| Leading Market Players |
|---|
| Comfort Keepers |
| Senior Helpers |
| Home Instead Senior Care |
| Always Best Care |
| Synergy HomeCare |
| Visiting Angels |
| BrightStar Care |
| FirstLight Home Care |
| Right at Home |
| Others |
Supply & Pricing Matrix
Adult children in tech-sector employment clusters anchor the dominant pricing model through subscription-based care planning adoption that compresses revenue volatility for franchise operators. This buyer concentration shifts purchasing patterns from episodic hourly blocks toward predictable monthly retainers that embed upsell pathways for specialized dementia care protocols.
Pricing Analysis
Value-based pricing anchored to client outcome stability and caregiver continuity commands premium positioning in the franchise tier. Three-tier pricing structure across premium dementia-certified care, standard personal assistance, and economy companionship levels separates rate bands by Teepa Snow certification status and supervisor ratio compliance. Pricing pressure stems from Medicaid reimbursement rate compression in states with the lowest hourly waiver allocations. Private-pay families in Sun Belt metropolitan corridors exhibit the lowest price sensitivity, while state Medicaid-dependent segments face acute cost consciousness.
Supply Chain Analysis
Caregiver labor supply rests on immigration policy enforcement levels and competing retail wage benchmarks in suburban and exurban markets. Recruitment infrastructure draws from Philippines-based training pipelines, Mexican border-state labor pools, and domestic certified nursing assistant programs. Single-source vulnerability concentrates in electronic visit verification software vendors serving multi-state franchise networks. Distribution runs through centralized caregiver scheduling platforms that optimize cross-territory deployment across multi-unit portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caregiver retention velocity below sustainable thresholds props pricing power for operators with demonstrated training infrastructure, creating supply-constrained margin protection for quality-focused incumbents.
For Market Incumbents: To counter annual turnover rates exceeding sixty percent exhausting training investments, franchise networks should deepen in-house production of caregiver certification programs through Teepa Snow behavioral intervention licensing. Channel control over hospital discharge integration partnerships with accountable care organizations secures preferred vendor status in bundled payment corridors. For New Entrants and Emerging Players: Begin with VA Aid and Attendance benefits counseling capabilities as the most penetrable white-space target, where eligible senior populations remain dramatically underutilized relative to program capacity. Geographic concentration in Texas suburban corridors outside Dallas-Fort Worth multi-unit saturation offers territory acquisition advantages. Go-to-market positioning through dementia care specialization enables premium rate tier access from launch. For Investors and Strategic Acquirers: Distressed-cycle entries favor multi-unit operators with demonstrated compliance architecture in California, New York, and Illinois where regulatory burden elevation filters marginal competitors. Long-term viability across the projection horizon hinges on portfolio-scale operational efficiencies and cross-territory scheduling optimization capabilities. Watch state-level ABC test applications and Department of Labor overtime rulings as inflection indicators threatening independent contractor model economics.| Strategic Initiative | Industry Significance |
|---|---|
| Caregiver Certification Infrastructure | Teepa Snow behavioral intervention licensing reduces turnover costs and enables premium rate tiers. |
| Hospital Discharge Partnership | Accountable care organization integration secures preferred vendor status in bundled payment markets. |
| VA Benefits Counseling Capability | Accredited Aid and Attendance advisors unlock underutilized third-party payment capacity. |
| Electronic Visit Verification Deployment | GPS-enabled documentation systems satisfy state audit requirements for hours-based Medicaid billing. |
| Multi-Unit Portfolio Rollup | Centralized back-office functions optimize caregiver scheduling across dispersed suburban territories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with franchise operations directors, state licensing board administrators, VA benefits advisors, and caregiver training program coordinators. Home Care Association of America membership databases, CMS Medicaid waiver expenditure reports, and state-level electronic visit verification procurement records provided bottom-up validation. Top-down triangulation against franchise disclosure document revenue ranges cross-checked segment-level assumptions.
Granularity-level modeling deployed service type, funding source, and franchise model dimensions at the metropolitan statistical area level across the projection horizon. Personal care, companionship, home health, and respite care segments carried distinct caregiver credentialing cost assumptions. CAGRs derived from territory-level unit economics modeling incorporating state Medicaid reimbursement rate trajectories and labor force participation trends. Medicare Advantage plan penetration and hospital-at-home program expansion served as demand-side sensitivity inputs.
Underlying measurement precision varies by segment; private-pay and multi-unit franchise models carry tighter precision than Medicaid-dependent single-unit operations. Forecasts reflect assumptions regarding state waiver program expansion velocity and workforce classification ruling trajectories that could materially revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Sterilization Services Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
Global Cath Lab Services Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Global Healthcare Contract Development and Manufacturing Organization Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Hospice Market
Healthcare Services
Audiology Services Market