
 Asia-Pacific Contraceptives Market | 2026-2036
Asia-Pacific Contraceptives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Contraceptives Market Insights
Modular contraceptive service bundles that combine product supply with counseling and follow-up monitoring is realigning buyer choice across the Asia-Pacific region. Bayer AG leverages its integrated pharmaceutical-manufacturing footprint to sustain consistent supply of hormonal implants and intrauterine devices across Southeast Asian distribution networks. HLL Lifecare Limited anchors public-sector procurement in India through its dominant position in condom production for government family planning programs. Pfizer competes in the oral contraceptive segment through established brand strength and channel control within pharmacy-led markets.
Asia-Pacific contraceptives comprise pharmaceutical and device-based systems engineered to prevent pregnancy through hormonal suppression, barrier mechanisms, or copper-mediated spermicidal action, with specifications ranging from 99% efficacy for long-acting implants to typical-use rates near 87% for oral pill regimens requiring daily adherence. Their primary commercial purpose centers on enabling reproductive autonomy while reducing maternal and infant mortality burdens across diverse healthcare infrastructures. Intrauterine devices command the leading position within product type segmentation due to decade-long efficacy profiles and minimal user compliance requirements, while implants represent the fastest-growing category as healthcare providers in the Philippines and Bangladesh expand insertion capacity. The transdermal delivery method occupies a narrower but higher-margin niche, with patch formulations differentiating through convenience positioning in Australia and South Korean pharmacy channels.
India's CDSCO, Australia's TGA, and South Korea's MFDS collectively shape product standards through divergent clinical trial requirements and post-market surveillance protocols that determine market access timelines for hormonal and device-based contraceptives. The EU MDR's extraterritorial influence on CE-marked manufacturers indirectly elevates quality benchmarks for devices distributed across Asia-Pacific import-dependent markets. Stakeholders must monitor regulatory harmonization initiatives between ASEAN member states, as mutual recognition agreements could compress registration timelines and reshape competitive entry dynamics for multinational suppliers.
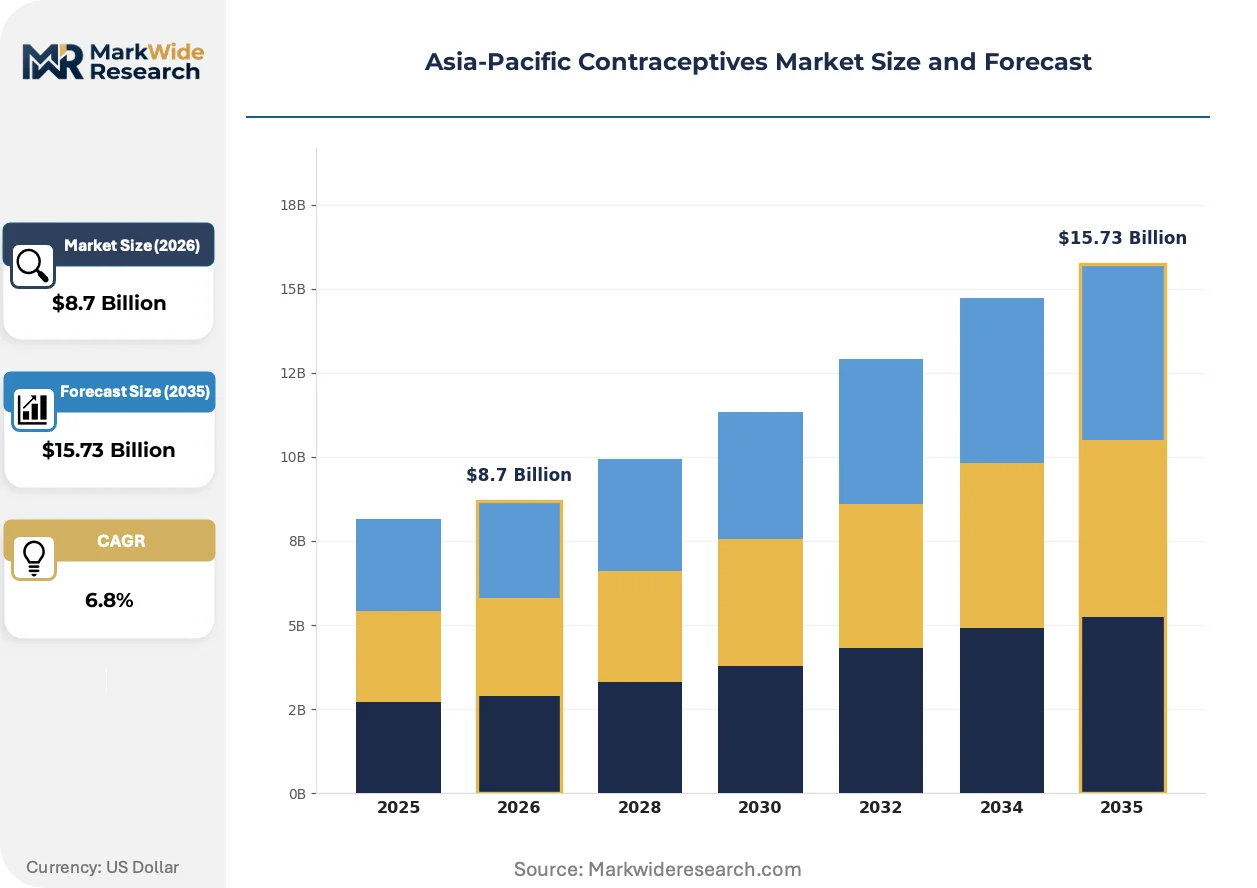
Market Dynamics
Long-acting reversible contraceptives are displacing oral pill regimens across Asia-Pacific public health systems as healthcare administrators prioritize adherence-independent efficacy and reduced follow-up burdens on clinic infrastructure.
Growth Catalysts
- CDSCO pathway streamlining:India's pharmaceutical regulator has compressed hormonal implant registration timelines, accelerating market entry for device manufacturers targeting government procurement channels.
- Telehealth platform expansion:Pharmacy chains and digital health providers across Indian urban corridors are extending contraceptive access beyond traditional clinic settings, capturing demand from time-constrained working populations.
- ASEAN mutual recognition momentum:Harmonization initiatives between Southeast Asian member states are compressing cross-border registration timelines, enabling faster product rollout across Indonesia, Vietnam, and the Philippines.
Market Restraints
- Copper and hormone raw material concentration:Active pharmaceutical ingredient supply for levonorgestrel implants concentrates among a limited set of European and Indian chemical manufacturers, creating input vulnerability.
- Insertion capacity bottlenecks:Healthcare provider training programs for intrauterine device and implant insertion lag product availability, particularly in Bangladesh and Philippine rural health units.
- EU MDR extraterritorial compliance costs:CE-marked device manufacturers face elevated quality documentation requirements that propagate into Asia-Pacific import markets, extending cost structures to non-EU suppliers.
Strategic Opportunities
- Vietnam public clinic network expansion:Government-run family planning facilities are scaling long-acting contraceptive procurement, creating concentrated demand pools for device suppliers with public-sector registration.
- Transdermal patch channel development:Convenience-positioned hormonal delivery systems are penetrating Australian and South Korean pharmacy retail, capturing premium-seeking segments dissatisfied with daily adherence requirements.
- Modular service bundling:Product-plus-counseling-plus-follow-up monitoring packages are realigning buyer choice criteria, enabling differentiation beyond commodity device pricing in competitive tenders.
Industry Challenges
- Trained insertion workforce scarcity:Competent healthcare providers for implant and intrauterine device placement remain concentrated in urban tertiary facilities, limiting rural and peri-urban access expansion.
- Divergent national surveillance protocols:Australia's TGA, South Korea's MFDS, and India's CDSCO maintain non-harmonized post-market adverse event reporting requirements, multiplying compliance overhead for multi-country suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Contraceptives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Pills, Condoms, Intrauterine Devices, Implants Delivery Method: Oral, Transdermal, Intravaginal, Injectable End User: Women, Healthcare Providers, Family Planning Clinics, Pharmacies Market Dynamics: Demand Trends, Regulatory Policies, Cultural Acceptance, Pricing Strategies |
| Companies Covered | Bayer AG, Pfizer, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Church & Dwight Co., Inc., CooperSurgical, Inc., Reckitt Benckiser plc, AbbVie, HLL Lifecare Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Contraceptives Market Trends and Innovations
Hormonal delivery technologies and regulatory harmonization initiatives are restructuring competitive entry patterns across Asia-Pacific contraceptive markets, while channel evolution is fragmenting traditional clinic-centric distribution models.
Biodegradable subdermal implants are integrating sustained-release polymer matrices that eliminate removal procedures, compressing total cost-of-ownership for public health systems. Bangladesh's Ministry of Health and Family Welfare is piloting these systems in selected districts. The technology is integrating long-term adherence monitoring with reduced provider contact requirements.
ASEAN medical device directive alignment is creating mutual recognition pathways that reduce redundant clinical testing for intrauterine devices already approved in Singapore or Thailand. Manufacturers with existing registrations in reference jurisdictions are redirecting regulatory investment toward faster secondary market entry. Philippine and Indonesian distributors are consolidating supplier relationships to exploit compressed approval timelines.
Subscription-based contraceptive delivery is displacing episodic pharmacy purchasing among Australian and South Korean urban consumers, with telehealth consultations bundled into recurring shipments. Pharmacy chains are responding with loyalty program integration and automated refill systems. This pattern is most visible in Seoul and Sydney metropolitan corridors where digital health platform penetration exceeds regional averages.
Asia-Pacific Contraceptives Market Segmentation
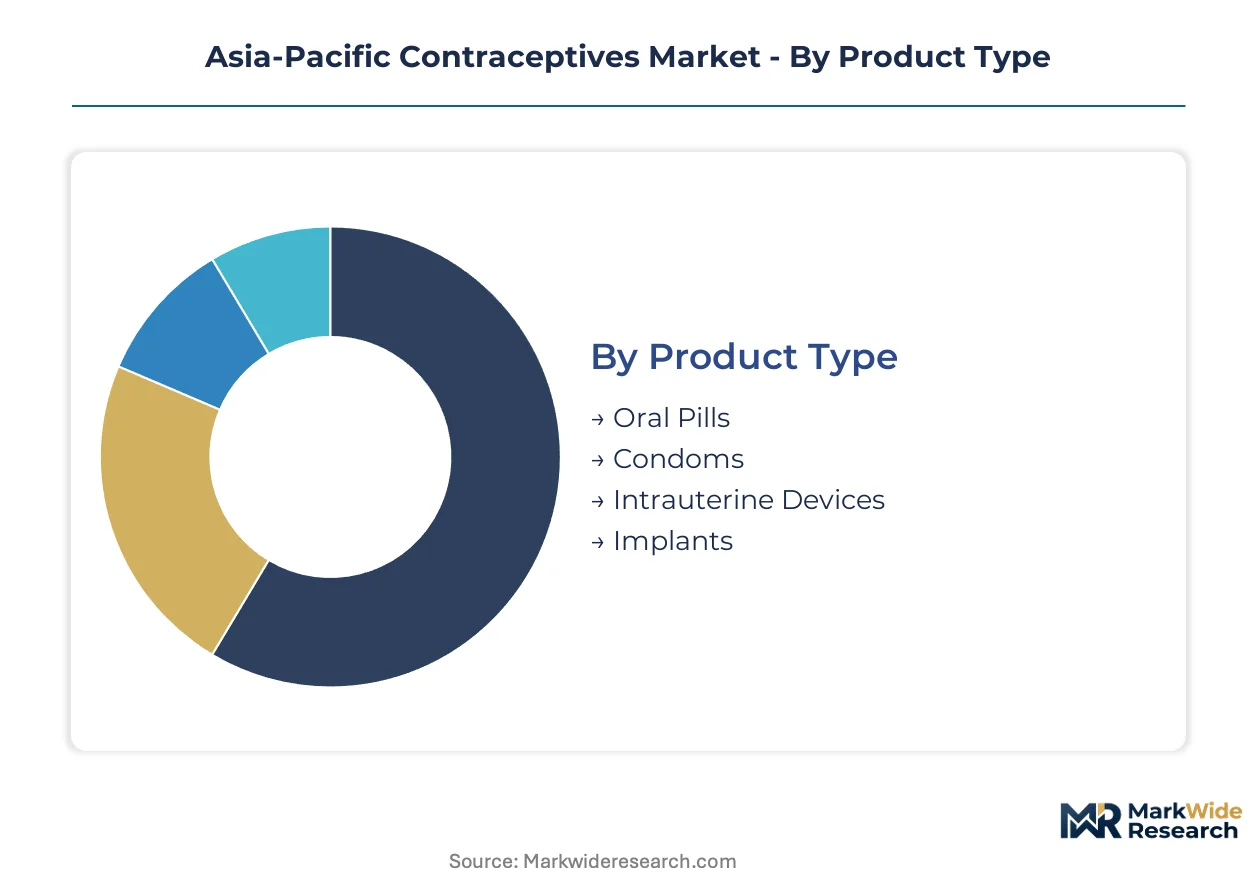
Asia-Pacific contraceptive segmentation reveals how regulatory pathways, insertion infrastructure, and channel economics concentrate commercial opportunity across distinct product and delivery categories. Buyers prioritize adherence profiles, reimbursement eligibility, and provider accessibility when selecting among hormonally active and mechanical alternatives.
Product Type:
CDSCO, TGA, and MFDS impose divergent clinical trial burdens across hormonal and mechanical categories, with long-acting devices requiring extended safety surveillance versus oral formulations with abbreviated bioequivalence pathways.
- Intrauterine Devices:Copper-bearing and hormonal intrauterine systems deliver decade-long efficacy through localized spermicidal or endometrial suppression mechanisms. Demand concentrates in Vietnam and Indonesian government procurement channels where healthcare administrators prioritize adherence-independent outcomes and reduced clinic follow-up burdens.
- Implants:Subdermal levonorgestrel rods provide multi-year protection through sustained-release polymer matrices. Bangladesh and Philippine rural health units are expanding insertion capacity as training programs accelerate, though provider scarcity limits peri-urban rollout velocity.
- Oral Pills:Daily combination or progestin-only regimens dominate Indian pharmacy and telehealth channels where convenience-positioned consumers accept typical-use efficacy trade-offs.
- Condoms:Barrier products anchor public-sector distribution through HLL Lifecare's government contract manufacturing for India's family planning programs.
Intrauterine devices sit at the top of the volume ranking, with implants climbing the fastest as insertion training programs scale across Southeast Asian public health systems.
Delivery Method:
Cost tier stratification separates premium convenience-positioned systems from economy access programs, with transdermal and injectable formats commanding margin premiums over oral generics in Australian and South Korean retail pharmacy.
- Injectable:Depot medroxyprogesterone formulations delivered quarterly through intramuscular administration dominate Bangladesh and Philippine government clinic procurement where provider contact frequency aligns with existing maternal health visit patterns.
- Transdermal:Weekly hormonal patches penetrate Seoul and Sydney metropolitan pharmacy channels through subscription-based delivery models bundled with telehealth consultations.
- Oral:Tablet regimens remain the lowest-cost entry point across Indian urban corridors where pharmacy chain density and digital platform penetration enable episodic and automated refill purchasing.
- Intravaginal:Rings and barrier films occupy narrower niches with concentrated uptake in Australian private healthcare settings where out-of-pocket reimbursement structures favor patient-controlled alternatives.
Oral delivery maintains the broadest installed base, though transdermal formats are expanding most quickly through Australian and South Korean pharmacy loyalty program integration.
End User:
Customer type determines channel configuration and service bundling requirements, with direct-to-consumer telehealth platforms fragmenting traditional clinic-centric distribution models across Indian and Australian urban markets.
- Women:Individual consumers selecting self-administered or provider-inserted alternatives based on autonomy preferences, side effect profiles, and partner involvement dynamics. Indian telehealth platforms and Australian subscription services target this segment with bundled counseling and automated resupply.
- Family Planning Clinics:Government-operated facilities across Indonesia and Vietnam concentrate procurement of long-acting reversible contraceptives where adherence-independent efficacy reduces program administrative burdens.
- Healthcare Providers:Tertiary hospital gynecologists and trained primary care nurses control insertion access for implants and intrauterine devices, with urban concentration creating rural access gaps in Bangladesh and Philippine provincial health units.
- Pharmacies:Retail and hospital pharmacy chains across Indian urban corridors and Australian metro areas are capturing oral and condom demand through extended hours and digital platform integration.
Women as direct purchasers represent the fastest-growing engagement model, with family planning clinics retaining the largest procurement volume through concentrated government program demand.
Market Dynamics:
Geographic variation in regulatory enforcement intensity and cultural acceptance creates asymmetric competitive terrain, with multinational suppliers prioritizing reference jurisdiction approvals for ASEAN mutual recognition leverage.
- Regulatory Policies:CDSCO pathway streamlining for hormonal implants, TGA post-market surveillance requirements, and ASEAN medical device directive alignment collectively determine product entry sequencing and compliance cost allocation.
- Cultural Acceptance:Religious and community-level attitudes toward fertility control vary across Indonesian provinces, Philippine regions, and Indian states, necessitating localized counseling protocols and provider training curricula.
- Pricing Strategies:Public-sector tendering in Vietnam and Indonesia rewards suppliers with manufacturing scale and registration efficiency, while Australian and South Korean retail channels support premium positioning for convenience-differentiated formats.
- Demand Trends:Urban working populations across Indian metro corridors and Seoul are shifting toward adherence-independent methods as telehealth platforms reduce clinic visit friction.
Regulatory policies command the most strategic attention from multinational suppliers, with demand trends showing the steepest trajectory shift as digital health platforms restructure access patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific contraceptive markets trace their modern commercial lineage to post-war family planning programs that institutionalized government procurement channels across Southeast Asia. India's pharmaceutical manufacturing base subsequently scaled hormonal production through the 1980s and 1990s. Today, regulatory divergence and digital health platform penetration are fragmenting historically clinic-centric distribution models.
India
Urban corridor demand concentrates in Mumbai, Delhi-NCR, and Bengaluru where pharmacy chains and telehealth platforms capture working-age women seeking adherence-independent methods. CDSCO pathway streamlining for hormonal implants compresses registration timelines for device manufacturers targeting government procurement. HLL Lifecare anchors public-sector condom supply through its dominant position in national family planning tenders.
China
Domestic pharmaceutical manufacturers supply the bulk of oral contraceptive demand through hospital pharmacy channels and expanding retail networks. NMPA regulatory requirements for long-acting devices maintain higher clinical evidence thresholds than abbreviated pathways for hormonal tablets. Manufacturing clusters in Jiangsu and Zhejiang provinces produce active pharmaceutical ingredients for regional export markets.
Australia
Subscription-based contraceptive delivery penetrates Sydney and Melbourne metropolitan corridors through telehealth-integrated pharmacy platforms. TGA post-market surveillance requirements for intrauterine devices exceed regional norms, extending compliance timelines for new market entrants. Transdermal patch formulations capture premium positioning among convenience-seeking consumers dissatisfied with daily adherence regimens.
Vietnam
Government-run family planning clinics scale procurement of long-acting reversible contraceptives as healthcare administrators prioritize adherence-independent efficacy. Provincial health departments in the Red River Delta and Mekong Delta regions expand insertion capacity for implants and intrauterine devices. Ministry of Health procurement tenders reward suppliers with established public-sector registration and manufacturing scale.
South Korea
MFDS regulatory harmonization with ASEAN medical device directives accelerates cross-border approval timelines for multinational suppliers. Seoul Capital Area pharmacy chains integrate automated refill systems and loyalty programs for oral contraceptive regimens. Convenience-positioned transdermal patches penetrate premium retail channels through subscription-based delivery models bundled with telehealth consultations.
Asia-Pacific Contraceptives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and service bundling dimensions. The market structure fragments between multinational pharmaceutical manufacturers with integrated device portfolios and regional specialists concentrating on single-format production. Three archetypes dominate: integrated pharmaceutical-device conglomerates with manufacturing footprints spanning hormonal and mechanical categories; public-sector contract manufacturers anchored in government family planning tenders; and telehealth-integrated platform operators capturing direct-to-consumer demand. Competitive moves concentrate on regulatory registration efficiency for multi-country entry and modular service packaging that combines product supply with counseling protocols.
Among integrated pharmaceutical manufacturers, Bayer AG and Pfizer occupy positions exemplifying divergent strategic emphases—Bayer representing the device-hormonal integration archetype across Southeast Asian distribution networks, Pfizer anchoring oral contraceptive brand strength within pharmacy-led markets. HLL Lifecare Limited sits within the public-sector contract manufacturing tier, its position deriving from sustained government procurement relationships rather than retail channel penetration. These three entities collectively illustrate how regulatory registration capacity, manufacturing scale, and channel configuration determine competitive positioning across divergent national market structures.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Church & Dwight Co., Inc. |
| CooperSurgical, Inc. |
| Reckitt Benckiser plc |
| AbbVie |
| HLL Lifecare Limited |
| Others |
Pricing and Supply Chain Analysis
Trained insertion specialists concentrated in Vietnamese and Indonesian urban tertiary facilities create labor-cost differentials that widen pricing spreads between premium device-insertion bundles and economy oral contraceptive tiers. CDSCO registration efficiency for hormonal implants compresses cost structures for manufacturers qualifying government tenders, while telehealth platform markups in Indian pharmacy channels sustain margin premiums for convenience-positioned delivery formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Asia-Pacific contraceptive procurement, with certification grade under TGA and MFDS protocols and manufacturing scale determining tier placement. Cost compression in economy oral pill segments intensifies as Indian pharmaceutical manufacturers expand levonorgestrel API capacity. Government family planning clinics in Vietnam and Indonesia exhibit highest price sensitivity through volume tendering, while Australian subscription-based telehealth consumers show lowest sensitivity to convenience premiums.
Supply Chain Analysis
Dual-sourcing requirements mandated by ASEAN procurement guidelines force distributors to qualify secondary suppliers for copper-bearing intrauterine devices and hormonal implant rods. Active pharmaceutical ingredient production concentrates in India and China, with polymer matrix components for sustained-release formulations drawing from South Korean specialty chemical manufacturers. Single-source vulnerability persists for levonorgestrel API given limited European qualified suppliers. Distribution runs through government clinic networks in Southeast Asia and pharmacy chain partnerships in Indian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific contraceptives function as a regulatory compounder where CDSCO pathway streamlining for hormonal implants is accelerating product registration velocity and reshaping competitive entry economics.
For Market Incumbents: Lock in insertion capacity partnerships with Vietnamese and Indonesian provincial health departments before training program saturation erodes provider scarcity premiums. Backward integration into levonorgestrel API production hedges against European supply concentration risk. Anchor public-sector tender positioning through modular service bundling that combines device supply with counseling protocols and follow-up monitoring systems. For New Entrants and Emerging Players: ASEAN medical device directive alignment opens a window for Singapore-registered manufacturers to compress secondary market entry timelines across Indonesia, Vietnam, and the Philippines. Target biodegradable subdermal implant pilots in Bangladesh where Ministry of Health district trials create first-mover qualification pathways. Lead with telehealth-integrated subscription models in Australian and South Korean metropolitan pharmacy channels where convenience positioning commands premium capture. For Investors and Strategic Acquirers: Integrated pharmaceutical-device conglomerates are the most active acquirer in this space, seeking regional specialists with established CDSCO or MFDS registrations to fill portfolio gaps. Five-to-ten year viability hinges on regulatory registration asset durability rather than manufacturing scale alone. Monitor ASEAN mutual recognition agreement ratification velocity as the signal to watch for cross-border approval timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Compressed approval timelines enable faster government tender qualification for hormonal implant manufacturers. |
| Insertion Capacity Expansion | Training program scaling in Bangladesh and Philippine rural health units addresses provider bottlenecks limiting implant rollout. |
| Telehealth Platform Integration | Subscription-based delivery models in Seoul and Sydney capture premium-seeking segments through automated refill systems. |
| Biodegradable Implant Development | Sustained-release polymer matrices eliminate removal procedures, reducing total cost-of-ownership for public health systems. |
| ASEAN Mutual Recognition Leverage | Reference jurisdiction approvals in Singapore or Thailand compress redundant clinical testing for multi-country entry. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at CDSCO and MFDS, procurement managers at Vietnamese provincial health departments, biomedical engineers at Indonesian family planning clinics, and pharmacy chain category buyers in Indian urban corridors with secondary validation against CDSCO registration databases, ASEAN medical device directive filings, TGA post-market surveillance reports, and hospital procurement contract disclosures. Bottom-up demand modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring tied projection assumptions to historical registration timelines and procurement volume patterns across the analysis window. Segmentation dimensions modeled included product type, delivery method, end user category, and national regulatory cluster. CAGRs derived from weighted average of segment growth trajectories calibrated to insertion capacity expansion rates, telehealth platform penetration curves, and government tender award velocities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory harmonization delays or raw material supply disruption scenarios. Deviation in ASEAN mutual recognition ratification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Sarcoma Drugs Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Saline Laxative Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Immunoglobulin Products Market