
 Oncology Adjuvants Market | 2026-2036
Oncology Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Adjuvants Market Outlook
Market Context
North American biopharmaceutical manufacturing capacity is broadening for sterile injectable adjuvant formulations. Pfizer Inc. leverages integrated biologics manufacturing networks across the United States to secure supply continuity for monoclonal antibody adjuvants. Roche Holding AG anchors its adjuvant portfolio through sustained R&D investment in companion diagnostic-linked therapies. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor adjuvant programs in melanoma and lung cancer.
Technical Definition and Segment Structure
Oncology adjuvants comprise pharmaceutical agents administered after primary tumor resection or definitive local therapy to eliminate residual micrometastatic disease, including cytotoxic chemotherapy agents formulated at specific dose-intensity schedules and immune checkpoint inhibitors engineered for sustained PD-1/PD-L1 pathway blockade. The product type dimension shows chemotherapy agents retaining the largest revenue pool while immune checkpoint inhibitors capture the fastest expansion trajectory in adjuvant settings. Delivery mode analysis reveals intravenous administration dominating current hospital throughput, with subcutaneous formulations gaining share in homecare settings where patient convenience drives formulary decisions.
Regulatory Framework and Outlook
FDA breakthrough therapy designation and EMA conditional approval frameworks shape adjuvant development economics by enabling earlier commercial access based on disease-free survival endpoints. The EPA and OSHA jointly govern manufacturing facility emissions and worker exposure limits for cytotoxic compound production, raising compliance costs for multi-product facilities. Stakeholders must monitor evolving payer evidence requirements for adjuvant indications, where progression-free survival data increasingly determines reimbursement positioning against neoadjuvant alternatives.
Market Dynamics
FDA breakthrough therapy designation and EMA conditional approval frameworks compress development timelines by accepting disease-free survival endpoints, fundamentally restructuring how sponsors prioritize adjuvant pipeline assets against neoadjuvant alternatives.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation enables earlier commercial access based on disease-free survival data, compressing traditional randomized trial requirements for adjuvant indications.
- Companion Diagnostic Integration:Biomarker-linked patient selection protocols expand addressable populations for checkpoint inhibitor adjuvants by identifying residual disease risk with greater precision.
- Homecare Infusion Migration:Subcutaneous formulation advances shift administration from hospital outpatient units to home health settings, extending therapy duration and adherence monitoring capabilities.
Market Restraints
- Platinum-Based Input Volatility:Cytotoxic chemotherapy production depends on platinum group metal supply concentrated in South Africa and Russia, exposing formulation costs to geopolitical disruption.
- Multi-Product Facility Constraints:EPA and OSHA joint governance of cytotoxic emissions and worker exposure limits raises compliance capital requirements for sterile injectable manufacturing sites serving multiple oncology programs.
- Neoadjuvant Substitution Pressure:Pre-surgical systemic therapy demonstrates superior pathological complete response rates in triple-negative breast cancer and muscle-invasive bladder cancer, diverting R&D investment from adjuvant development.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan and South Korea exhibit lagging adjuvant therapy integration into standard-of-care pathways relative to United States and Western European benchmarks, creating first-mover positioning for checkpoint inhibitor sponsors.
- Real-World Evidence Mandates:EMA's expanded conditional approval framework incentivizes post-market surveillance infrastructure investment, enabling label expansion through registry-derived efficacy data.
- Digital Therapeutic Convergence:Remote patient monitoring platforms paired with subcutaneous administration protocols enable toxicity-managed dose escalation, differentiating portfolio assets through adherence optimization.
Industry Challenges
- Biostatistical Talent Scarcity:Disease-free survival endpoint analysis requires specialized biostatistical expertise in immuno-oncology trial design, with qualified personnel concentrated among a limited set of academic medical centers and contract research organizations.
- Cold Chain Infrastructure Capex:mRNA-based personalized neoantigen vaccines entering adjuvant trials demand ultra-low temperature distribution networks, requiring substantial capital deployment for last-mile logistics capabilities.
- Cross-Border Data Harmonization:Divergent evidentiary standards between FDA and EMA for adjuvant approval create protocol complexity, forcing sponsors to maintain separate statistical analysis plans and increasing regulatory submission preparation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Adjuvants Market |
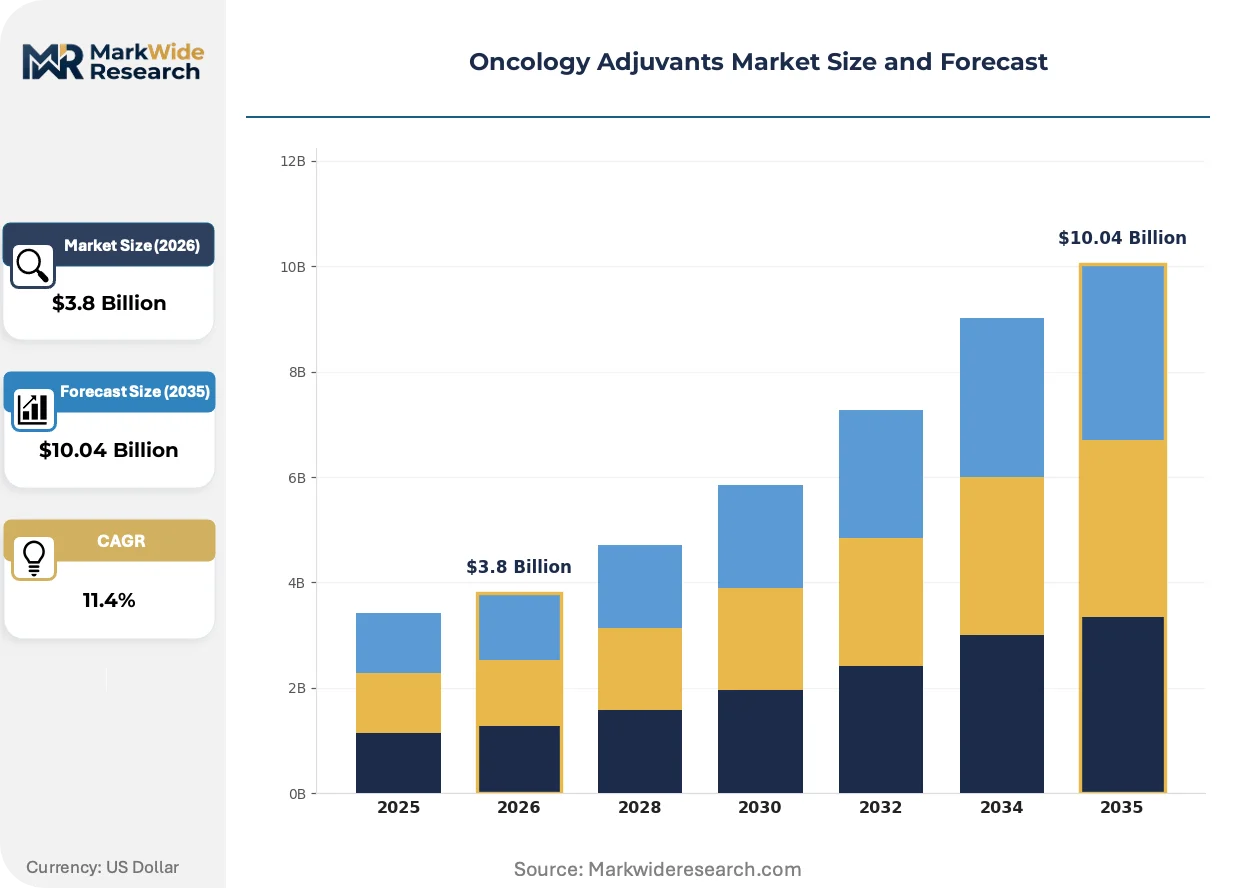
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Hormonal Therapies, Monoclonal Antibodies, Immune Checkpoint Inhibitors Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Homecare Settings, Research Institutions Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Roche Holding AG, Merck & Co. Inc., Bayer AG, Bristol-Myers Squibb Company, AstraZeneca PLC, Novartis AG, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Adjuvants Market Strategic Shifts
Adjuvant therapy development is pivoting from empirical cytotoxic scheduling toward precision immuno-oncology platforms, with biomarker stratification and administration convenience emerging as the primary vectors of competitive differentiation.
Artificial intelligence-driven patient selection algorithms are converging with next-generation sequencing panels to identify micrometastatic disease signatures predictive of adjuvant therapy benefit. Academic medical centers in the United States and Germany deploy these integrated platforms to refine clinical trial enrollment criteria. The convergence compresses screening timelines and reduces screen-failure rates, reallocating site resources toward treatment administration rather than eligibility assessment.
EMA's expanded conditional marketing authorization framework now permits adjuvant approvals based on intermediate clinical endpoints with post-authorization efficacy studies mandated. This regulatory evolution reduces time-to-revenue for sponsors with robust pharmacovigilance infrastructure. Oncology divisions with established European registry partnerships capture accelerated access advantages over competitors dependent solely on traditional randomized trial pathways.
Hospital procurement committees increasingly unbundle adjuvant therapy purchasing from bundled oncology service contracts, creating direct manufacturer-negotiation channels for high-cost checkpoint inhibitors. United States-based integrated delivery networks lead this disintermediation, establishing formulary committees with dedicated immuno-oncology sub-specialization. The shift concentrates volume among preferred vendors capable of delivering companion diagnostic co-development commitments alongside drug supply agreements.
Oncology Adjuvants Market Segmentation
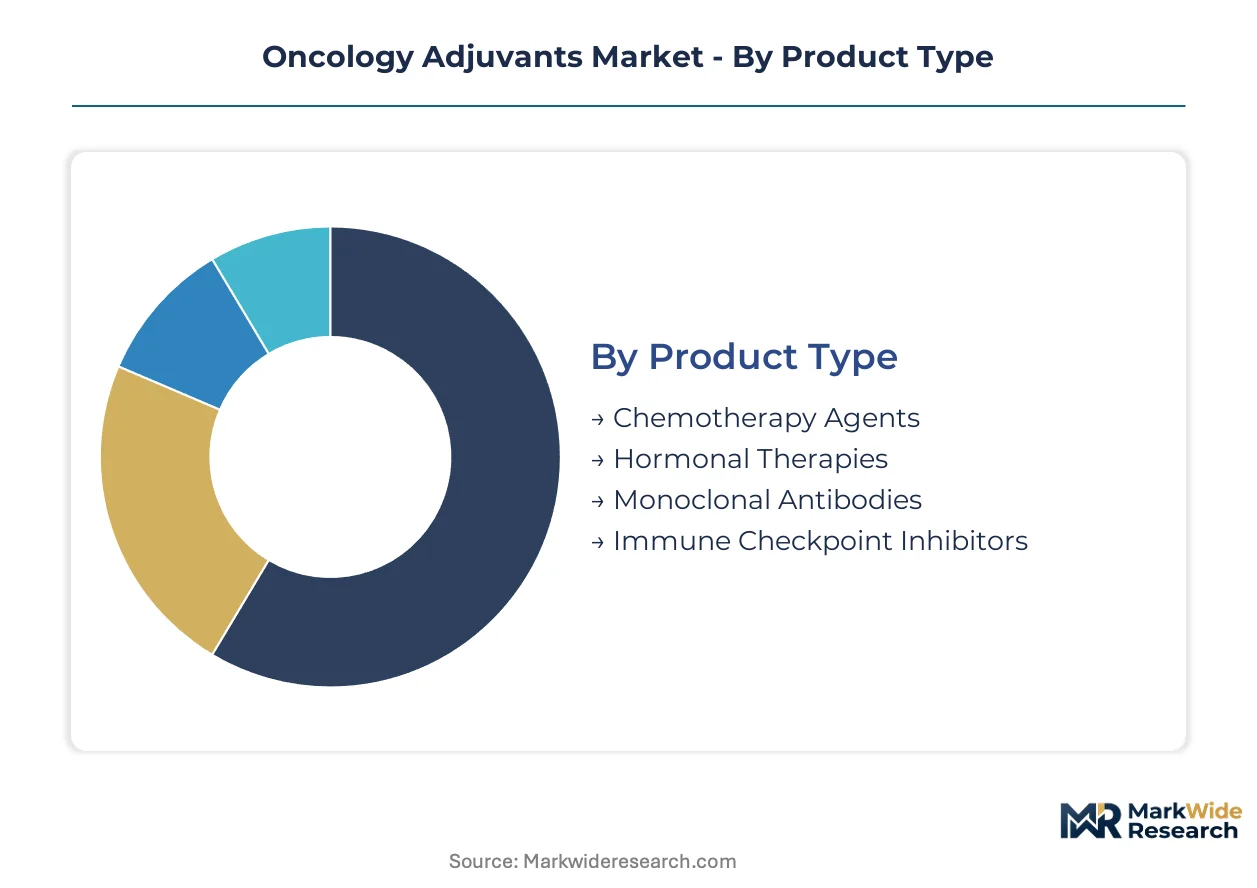
Adjuvant therapy selection hinges on tumor biology, patient performance status, and site-of-care capabilities. Segmentation reveals how formulation science and administration logistics determine competitive positioning across oncology settings.
Product Type:
Cytotoxic potency and immunological mechanism define the therapeutic axis for residual disease elimination.
- Chemotherapy Agents:Platinum-based and anthracycline formulations target rapidly dividing micrometastatic cells through DNA cross-linking and topoisomerase inhibition. Demand concentrates in hospital outpatient departments across the United States and Germany, where infusion infrastructure supports dose-intensity protocols.
- Immune Checkpoint Inhibitors:Engineered monoclonal antibodies sustain PD-1/PD-L1 pathway blockade to activate T-cell surveillance against residual tumor deposits. United States academic medical centers drive adoption, leveraging companion diagnostic infrastructure to stratify patient selection.
- Monoclonal Antibodies:HER2-directed and anti-VEGF agents interrupt growth factor signaling in specific molecular subtypes.
- Hormonal Therapies:Aromatase inhibitors and selective estrogen receptor modulators suppress endocrine-driven recurrence in hormone-sensitive malignancies.
Chemotherapy agents lead on scale; immune checkpoint inhibitors lead on momentum.
Delivery Mode:
Patient convenience and pharmacokinetic requirements shape administration route selection across care settings.
- Intravenous:Hospital-based infusion delivers precise bioavailability for cytotoxic agents with narrow therapeutic indices. United States integrated delivery networks optimize throughput through dedicated oncology infusion centers.
- Subcutaneous:Home health nursing enables sustained immunotherapy administration outside acute care facilities. Formulary committees in Germany and France prioritize subcutaneous checkpoint inhibitors for reduced hospital bed utilization.
- Oral:Capecitabine and hormonal agents support patient self-administration with adherence monitoring.
- Intramuscular:Long-acting hormonal depot formulations reduce injection frequency in prostate and breast cancer protocols.
Intravenous administration dominates current throughput; subcutaneous delivery is expanding most quickly.
End User:
Site-of-care economics and clinical trial access determine patient flow across provider types.
- Hospitals:Academic medical centers anchor adjuvant protocol development through NCI-designated cancer center networks. Surgical oncology departments in the United States coordinate multidisciplinary tumor boards to integrate adjuvant therapy into definitive local therapy pathways.
- Oncology Clinics:Community-based practices deliver standardized adjuvant regimens with centralized pharmacy support. United States oncology practice networks aggregate purchasing volume for checkpoint inhibitor access.
- Homecare Settings:Subcutaneous administration migration shifts infusion delivery to home health agencies with remote monitoring capabilities.
- Research Institutions:Phase III trial enrollment concentrates at sites with biomarker stratification infrastructure and longitudinal follow-up registries.
Hospitals lead on scale; homecare settings lead on momentum.
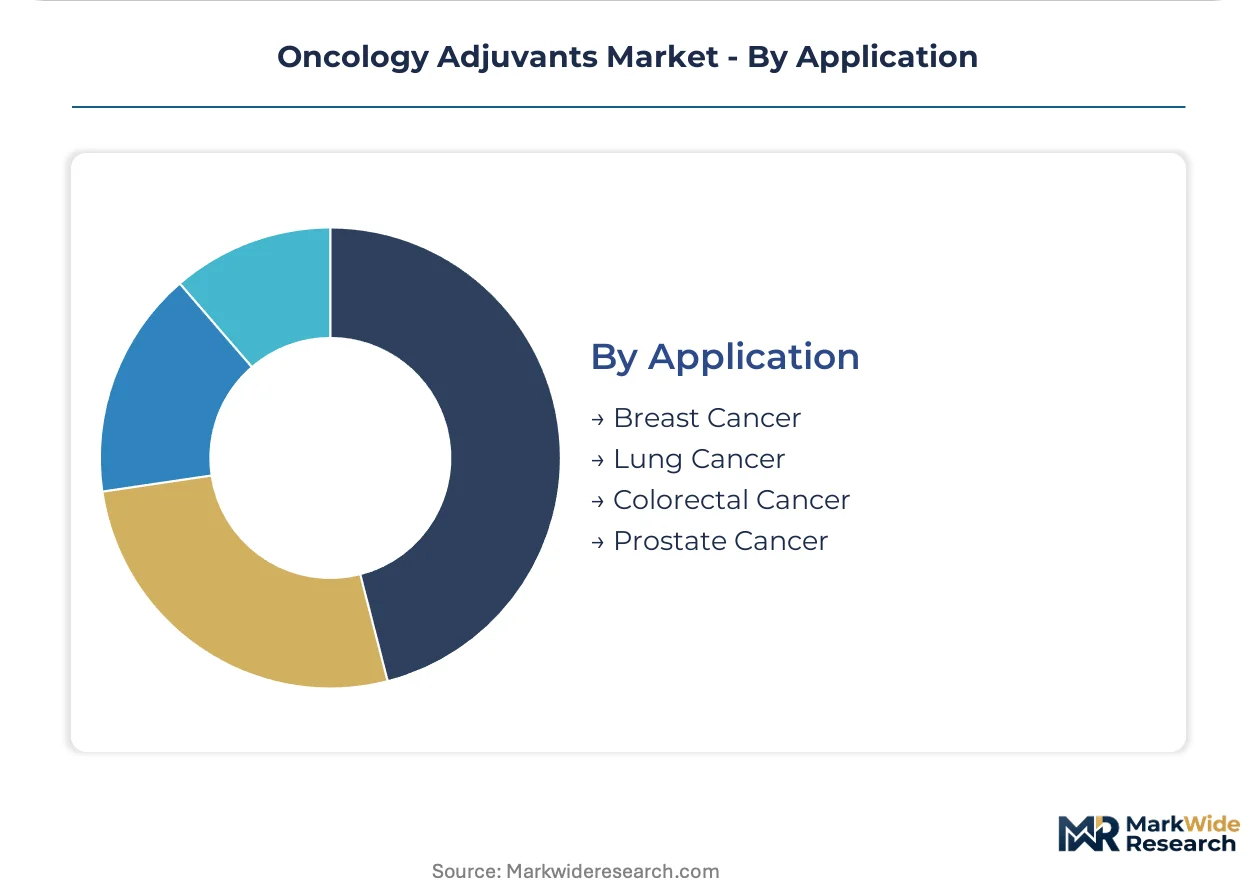
Application:
Tumor-specific recurrence patterns and biomarker prevalence determine addressable patient populations.
- Breast Cancer:Hormonal and HER2-directed adjuvants target molecular subtypes with established recurrence risk stratification. United States screening mammography programs generate early-stage diagnoses amenable to adjuvant intervention.
- Lung Cancer:Adjuvant immunotherapy following surgical resection addresses high recurrence rates in resectable non-small cell histologies. FDA breakthrough designations have accelerated checkpoint inhibitor approvals in this indication.
- Colorectal Cancer:Oxaliplatin-based regimens and immune therapy for microsatellite instability-high tumors define current standards.
- Prostate Cancer:Androgen deprivation therapy and novel hormonal agents suppress biochemical recurrence after radical prostatectomy.
Breast cancer leads on scale; lung cancer leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting sterile injectable manufacturing toward jurisdictions with streamlined environmental compliance frameworks, as EPA and OSHA joint governance in the United States elevates capital requirements for multi-product cytotoxic facilities.
United States
FDA breakthrough therapy designation for adjuvant indications compresses development timelines and attracts sponsor headquarters concentration. The Inflation Reduction Act's Medicare price negotiation provisions reshape commercial forecasting for checkpoint inhibitors. NCI-designated cancer centers in Boston and Houston anchor clinical trial enrollment for disease-free survival endpoints.
Germany
EMA centralized approval pathways enable simultaneous market access across member states for adjuvant immunotherapies. The country's national pharmaceutical regulator maintains stringent pharmacovigilance requirements for conditional marketing authorizations. Frankfurt and Munich host manufacturing clusters for monoclonal antibody sterile fill-finish operations serving European distribution networks.
Switzerland
Swissmedic's alignment with EMA scientific advice procedures accelerates adjuvant development program timelines for sponsors seeking dual-continent approval strategies. Federal coordination of healthcare technology assessment integrates companion diagnostic reimbursement with therapeutic access. Basel anchors biologics manufacturing infrastructure with specialized containment facilities for cytotoxic compound handling.
Japan
PMDA's sakigake designation system creates accelerated review pathways analogous to FDA breakthrough therapy status for adjuvant oncology assets. METI industrial policy supports domestic biologics manufacturing capacity expansion to reduce import dependency. Tokyo and Osaka metropolitan areas concentrate academic medical center networks with biomarker stratification infrastructure for immuno-oncology trials.
India
CDSCO accelerated approval frameworks for oncology products are converging with PLI scheme incentives for active pharmaceutical ingredient manufacturing. Domestic production of platinum-based chemotherapy inputs reduces exposure to South African and Russian supply concentration. Hyderabad and Ahmedabad clusters specialize in cytotoxic formulation science with EPA-equivalent environmental compliance capabilities.
Oncology Adjuvants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital therapeutic convergence and real-world evidence infrastructure. The vendor base stratifies across three maturity tiers: integrated pharmaceutical conglomerates with companion diagnostic capabilities, mid-scale biologics specialists focused on subcutaneous formulation science, and platform technology licensors enabling personalized neoantigen vaccine development. Competitive positioning hinges on two dominant moves: backward integration into platinum-group metal supply chains to hedge input volatility, and strategic partnerships with academic medical centers to secure disease-free survival endpoint trial enrollment.
Among United States-based integrated pharmaceutical enterprises, Pfizer Inc. and Bristol-Myers Squibb Company exemplify the conglomerate archetype with checkpoint inhibitor adjuvant portfolios. Roche Holding AG represents the European-based competitor with sustained R&D anchoring in companion diagnostic-linked therapy development. These three entities collectively illustrate how geographic diversification of manufacturing networks and regulatory submission capabilities determines market access velocity across FDA and EMA jurisdictions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Roche Holding AG |
| Merck & Co. Inc. |
| Bayer AG |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Novartis AG |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal spot indices cascade through oncology adjuvant supply chains, compressing margins for cytotoxic chemotherapy manufacturers while concentrating pricing power among integrated biologics producers with captive metal sourcing. This input-cost asymmetry stratifies the market into three tiers: premium checkpoint inhibitor portfolios commanding formulary preference, standard platinum-based regimens facing procurement pressure, and economy-tier hormonal therapies competing on access programs.
Pricing Analysis
Direct-to-hospital contracting discounts dominate checkpoint inhibitor transactions, bypassing traditional wholesale distribution for integrated delivery network formulary placement. Price differentiation separates companion diagnostic-linked immunotherapies from unstratified cytotoxic agents, with biomarker precision commanding premium positioning against commodity chemotherapy. Pricing pressure stems from Medicare price negotiation provisions intensifying scrutiny of high-cost adjuvant regimens. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical trial access over unit cost.
Supply Chain Analysis
Unused cytotoxic vial return programs and temperature excursion protocols govern reverse logistics for high-value biologics, with specialized couriers handling cold chain recovery. Manufacturing concentrates in the United States, Germany, and Switzerland, where sterile fill-finish capabilities cluster near regulatory agency headquarters. Platinum group metal supply draws from South African mining operations and Russian refining capacity, exposing formulation costs to geopolitical disruption. Single-source vulnerability concentrates in platinum salt precursors for oxaliplatin production. Distribution runs through hospital-centric channels with direct manufacturer contracting displacing traditional distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in oncology adjuvants rests on subcutaneous formulation science reducing hospital administration costs and enabling premium homecare pricing tiers against intravenous commodity alternatives.
For Market Incumbents: Lock in companion diagnostic co-development partnerships with academic medical centers to secure disease-free survival endpoint trial enrollment against emerging subcutaneous specialists. Backward integration into platinum-group metal supply chains hedges input volatility threatening cytotoxic portfolio margins. Priority lever: manufacturing capacity addition in Switzerland or Germany to capture EMA conditional approval pathway advantages. For New Entrants and Emerging Players: AI-driven patient selection algorithms offer technology-first wedge positioning against established empiric prescribing protocols. White-space targets concentrate in Japan and South Korea, where adjuvant immunotherapy integration lags United States benchmarks. Most penetrable segment: subcutaneous checkpoint inhibitors for lung cancer adjuvant settings with biomarker stratification infrastructure. Go-to-market angle: remote patient monitoring platform bundling with home health nursing networks. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale biologics specialists lack companion diagnostic capabilities to compete for integrated delivery network formulary contracts. Long-term viability favors sponsors with robust pharmacovigilance infrastructure enabling EMA conditional marketing authorization label expansion. Acquisition target archetype: subcutaneous formulation science platforms with existing sterile manufacturing assets. Signal to watch: FDA breakthrough therapy designation frequency in adjuvant lung cancer as inflection indicator for checkpoint inhibitor market velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Biomarker stratification secures formulary preference at NCI-designated cancer centers. |
| Subcutaneous Formulation Advancement | Homecare administration migration reduces hospital bed utilization and extends therapy duration. |
| Platinum Supply Chain Integration | Captive sourcing of group metal inputs insulates margins from South African supply disruption. |
| EMA Conditional Approval Pathway | Disease-free survival endpoints accelerate European market access ahead of traditional trials. |
| Real-World Evidence Infrastructure | Post-market surveillance registries enable label expansion through registry-derived efficacy data. |
Study Parameters
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary sources included FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored market sizing across the analysis window.
Granularity-level modeling operated at the intersection of product type, delivery mode, end-user site-of-care, and tumor-specific application dimensions. Treatment line positioning and regional regulatory cluster variations informed segment-level projections throughout the forecast period. CAGRs were derived from epidemiological incidence trajectories, therapy penetration assumptions, and pricing evolution patterns. Forecast inputs incorporated biomarker prevalence data and companion diagnostic adoption curves specific to checkpoint inhibitor adjuvant settings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to neoadjuvant therapy substitution rates and platinum supply disruption scenarios. Projections reflect assumptions regarding FDA breakthrough therapy designation frequency and EMA conditional approval framework stability. Practitioners should monitor pathological complete response rate differentials between neoadjuvant and adjuvant protocols, as well as South African platinum mining output reports, for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pharmaceuticals Preservative Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Fibromyalgia Antidepressant Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market