
 US Companion Animal Diagnostics Market | 2026-2036
US Companion Animal Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
US Companion Animal Diagnostics Market Insights
The US companion animal diagnostics market is consolidating around a widening gap between premium reference-laboratory services and commodity point-of-care testing. IDEXX Laboratories leverages its installed base of chemistry and hematology analyzers to lock in recurring consumable revenue. Zoetis anchors its position through vertical integration spanning vaccines, therapeutics, and complementary diagnostics. Thermo Fisher Scientific competes by extending its human-clinical molecular platforms into veterinary infectious-disease panels.
Companion animal diagnostics encompasses laboratory instruments, reagents, and imaging systems that detect hematologic, biochemical, immunologic, and genetic abnormalities in dogs, cats, and other household pets, with most analyzers operating on 50–200 µL sample volumes optimized for small patient size. Molecular diagnostics and point-of-care devices represent the fastest-expanding product categories as clinics seek same-day turnaround for vector-borne disease and oncology markers. Among applications, oncology and endocrinology command the strongest margin pools due to chronic monitoring requirements and specialized test complexity. Veterinary hospitals and reference laboratories dominate end-user demand, though mobile diagnostic services are carving out share in rural and suburban markets.
FDA Center for Veterinary Medicine oversight shapes premarket requirements for diagnostic test kits, while USDA APHIS regulates interstate movement and disease-reporting standards that drive surveillance testing volumes. CLIA-waived status for certain point-of-care assays accelerates clinic adoption by reducing laboratory personnel requirements. Stakeholders must monitor evolving state veterinary practice acts that determine whether non-veterinarian staff may operate diagnostic equipment, as this directly affects addressable instrument placement and service revenue models.
Market Dynamics
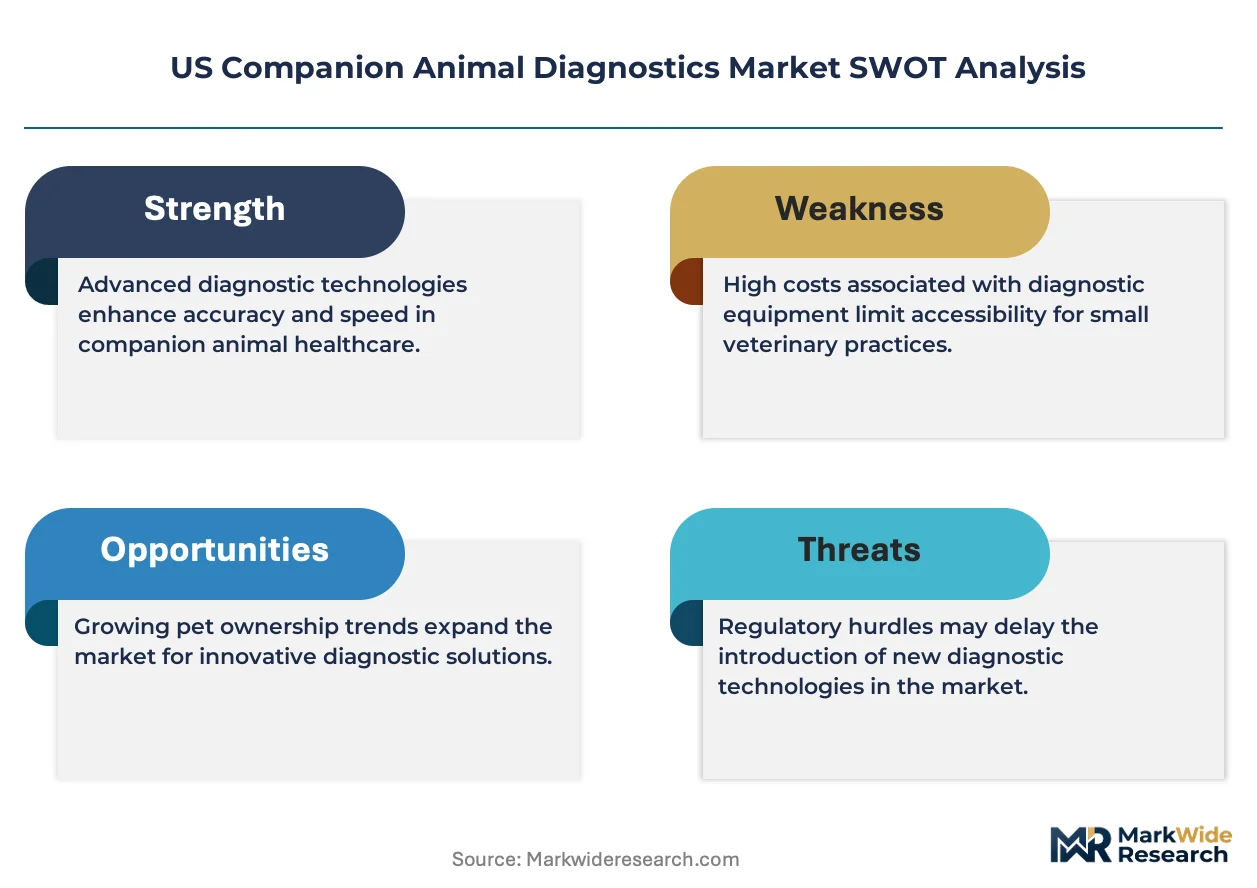
Veterinary hospitals across California and Texas are accelerating in-house diagnostic investments as pet owners demand same-day pathology results, compressing the traditional reference laboratory channel and forcing equipment vendors to restructure service revenue models around consumable pull-through rather than capital placement.
Growth Catalysts
- CLIA-waived assay expansion:The FDA Center for Veterinary Medicine's streamlined premarket pathway for moderate-complexity tests enables point-of-care chemistry panels in general practice clinics without dedicated laboratory personnel.
- Vector-borne disease surveillance:USDA APHIS interstate reporting mandates for Lyme disease and ehrlichiosis sustain recurring testing volumes in endemic regions, particularly the Northeast and Upper Midwest.
- Oncology biomarker proliferation:Liquid biopsy platforms targeting canine lymphoma and mast cell tumors are penetrating specialty referral centers in Florida and New York metropolitan corridors.
Market Restraints
- Reagent supply concentration:Three domestic distributors control bulk antibody and enzyme conjugate flows for veterinary immunoassays, creating vulnerability to cold-chain disruptions.
- State practice act fragmentation:Variation in veterinary technician scope-of-practice regulations across Texas, California, and Florida limits standardized point-of-care deployment models.
- Reference laboratory pricing power:Regional reference chains in the Northeast maintain 40-60% discounts on send-out panels that undercut in-house test economics for low-volume clinics.
Strategic Opportunities
- Rural mobile diagnostics:Veterinary service vans equipped with hematology and chemistry analyzers address veterinary deserts across Montana, Wyoming, and the Dakotas where brick-and-mortar specialty access is limited.
- Pharmacogenomic integration:Cytochrome P450 testing for drug metabolism in canine patients creates pull-through for both diagnostic and therapeutic product lines within integrated animal health platforms.
- Telemedicine-triage protocols:State veterinary medical board relaxations on telehealth prescribing in Arizona and Colorado enable remote interpretation of point-of-care results, expanding addressable clinic base.
Industry Challenges
- Dual-credential technical staffing:Veterinary technicians qualified for both sample processing and imaging system operation command 25-35% wage premiums in tight labor markets, squeezing clinic operating margins.
- Legacy analyzer interoperability:Proprietary data formats from installed chemistry and hematology platforms resist integration with cloud-based practice management systems, complicating centralized quality control.
- Proficiency testing logistics:External quality assurance programs for in-house immunoassays require frozen serum shipments that degrade in summer transit through the Southwest, compromising result validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Companion Animal Diagnostics Market |
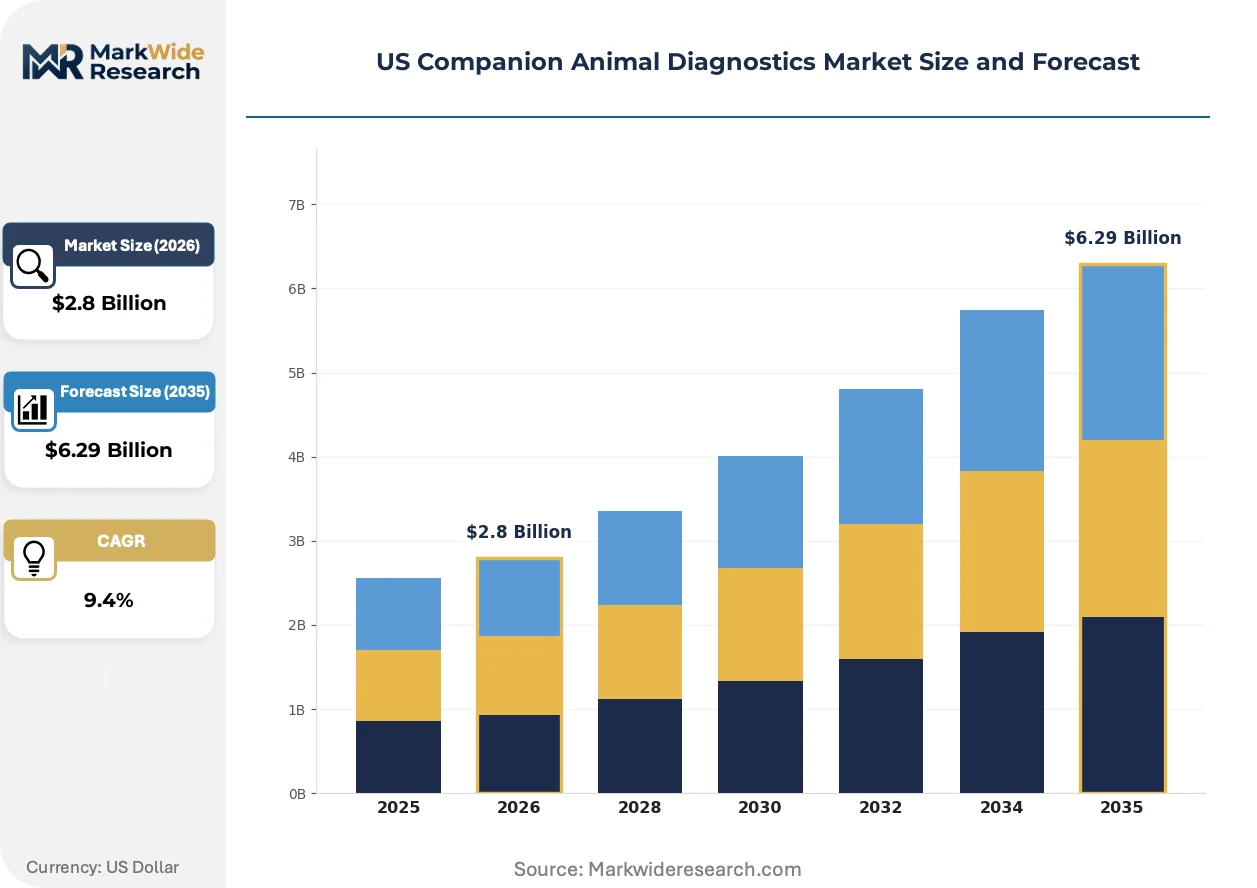
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematology Analyzers, Immunoassay Analyzers, Biochemistry Analyzers, Molecular Diagnostics, Point-of-Care Devices Application: Infectious Disease, Endocrinology, Oncology, Cardiology, Dermatology End User: Veterinary Hospitals, Diagnostic Laboratories, Veterinary Clinics, Research Institutes Distribution Channel: Veterinary Distributors, Direct Sales, Online Retailers, Mobile Diagnostic Services |
| Companies Covered | IDEXX Laboratories, Zoetis, Antech Diagnostics, Thermo Fisher Scientific, FUJIFILM SonoSite, Neogen Corporation, Heska Corporation, bioMérieux, Virbac, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Companion Animal Diagnostics Market Trends and Innovations
Digital pathology and artificial intelligence scoring algorithms are redefining diagnostic workflow economics, shifting histopathology from centralized reference laboratories toward distributed slide scanning networks that enable remote specialist consultation within hours rather than days.
Multiplex PCR panels for respiratory and gastrointestinal pathogens are consolidating previously fragmented infectious disease testing workflows. Specialty emergency hospitals in metropolitan Texas and California markets are adopting these platforms to replace sequential single-pathogen screens. The technology is consolidating reference laboratory market share into vertically integrated instrument-reagent-service bundles that lock in multi-year consumable commitments.
USDA APHIS revised interstate health certificate requirements now mandate specific PCR or serologic documentation for canine brucellosis and feline leukemia virus in commercial breeding operations. This regulatory tightening expands surveillance testing volumes beyond traditional clinical practice into breeder and shelter screening segments. The Southeast and Southwest, where large-scale breeding facilities concentrate, are experiencing the most pronounced compliance-driven demand inflection.
Pet insurance penetration exceeding 25% in Massachusetts and Washington is altering owner payment behavior at the point of care. Insured clients in these states demonstrate higher authorization rates for advanced imaging and molecular diagnostics compared to cash-pay counterparts. This behavioral shift is most visible in oncology and orthopedic pre-surgical workups, where guaranteed reimbursement reduces owner price sensitivity and expands addressable testing menus in specialty practices.
US Companion Animal Diagnostics Market Segmentation
Diagnostic equipment purchasing decisions in the US companion animal market hinge on whether instruments operate as standalone capital investments or integrate into broader laboratory workflows. Understanding these integration patterns reveals where vendors can capture recurring consumable revenue versus one-time placement fees.
Product Type:
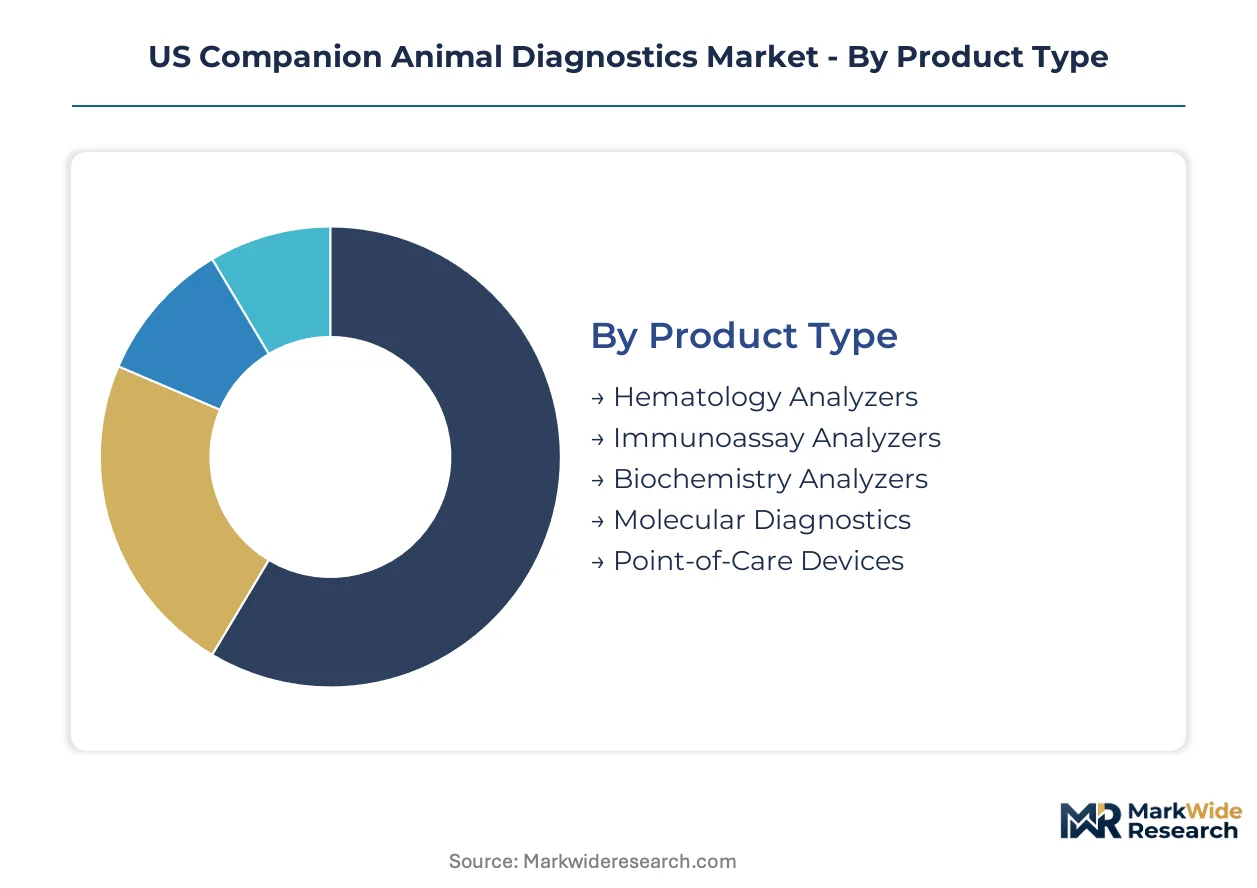
Hematology and biochemistry platforms anchor in-house laboratory suites with embedded reagent contracts, while molecular diagnostics and point-of-care devices often deploy as modular additions to existing infrastructure.
- Hematology Analyzers:These systems quantify red cell, white cell, and platelet parameters using impedance and laser scatter technologies. Veterinary hospitals across Texas and California favor five-part differential instruments that integrate with practice management software for automated result flagging.
- Molecular Diagnostics:Multiplex PCR platforms detect vector-borne pathogens and oncologic markers with same-day turnaround. Specialty emergency hospitals in Florida and New York metropolitan areas drive demand for respiratory and gastrointestinal pathogen panels that replace sequential single-target testing.
- Immunoassay Analyzers:Chemiluminescent and ELISA-based systems quantify endocrine markers and infectious disease antibodies.
- Biochemistry Analyzers:Wet chemistry and dry-slide systems measure metabolic panels on 100-200 µL sample volumes optimized for small patients.
- Point-of-Care Devices:Handheld and benchtop instruments deliver immediate results without dedicated laboratory space.
Volume placements concentrate in Hematology Analyzers; the faster expansion belongs to Molecular Diagnostics.
Application:
Margin profiles diverge sharply between acute infectious disease testing and chronic condition monitoring that demands longitudinal biomarker tracking.
- Oncology:Liquid biopsy platforms targeting canine lymphoma and mast cell tumors command premium pricing due to specialized pathology interpretation requirements. Specialty referral centers in Massachusetts and Washington authorize these tests more frequently where pet insurance penetration exceeds 25 percent.
- Endocrinology:Thyroid panels, cortisol assays, and insulin monitoring support chronic disease management with recurring quarterly testing. General practice clinics in suburban California markets deploy CLIA-waived chemistry analyzers to capture this monitoring revenue internally.
- Infectious Disease:Vector-borne pathogen screening responds to USDA APHIS surveillance mandates and seasonal tick exposure patterns.
- Cardiology:NT-proBNP and cardiac troponin assays support pre-anesthetic screening and congestive heart failure staging.
- Dermatology:Allergen-specific IgE testing and fungal culture diagnostics address atopic conditions in companion animals.
Revenue concentration sits with Oncology; Endocrinology is climbing the fastest as chronic monitoring protocols extend patient lifespans.
End User:
Capital deployment strategies vary between institutions that prioritize instrument ownership versus those favoring fee-per-test outsourcing arrangements.
- Veterinary Hospitals:Multi-doctor specialty practices and emergency centers maintain in-house laboratories with dedicated technical staff. These facilities in Texas and California metropolitan corridors generate the highest per-clinic consumable pull-through due to 24-hour operation and complex case density.
- Diagnostic Laboratories:Regional reference chains consolidate esoteric testing and histopathology services that require specialized equipment and board-certified pathologist oversight.
- Veterinary Clinics:Single-doctor and small group practices increasingly adopt point-of-care platforms to reduce send-out volumes.
- Research Institutes:Academic veterinary medical centers and pharmaceutical development facilities utilize diagnostic instruments for clinical trial endpoints and translational research protocols.
Instrument placements concentrate in Veterinary Hospitals; the steepest expansion trajectory belongs to Veterinary Clinics adopting CLIA-waived platforms.
Distribution Channel:
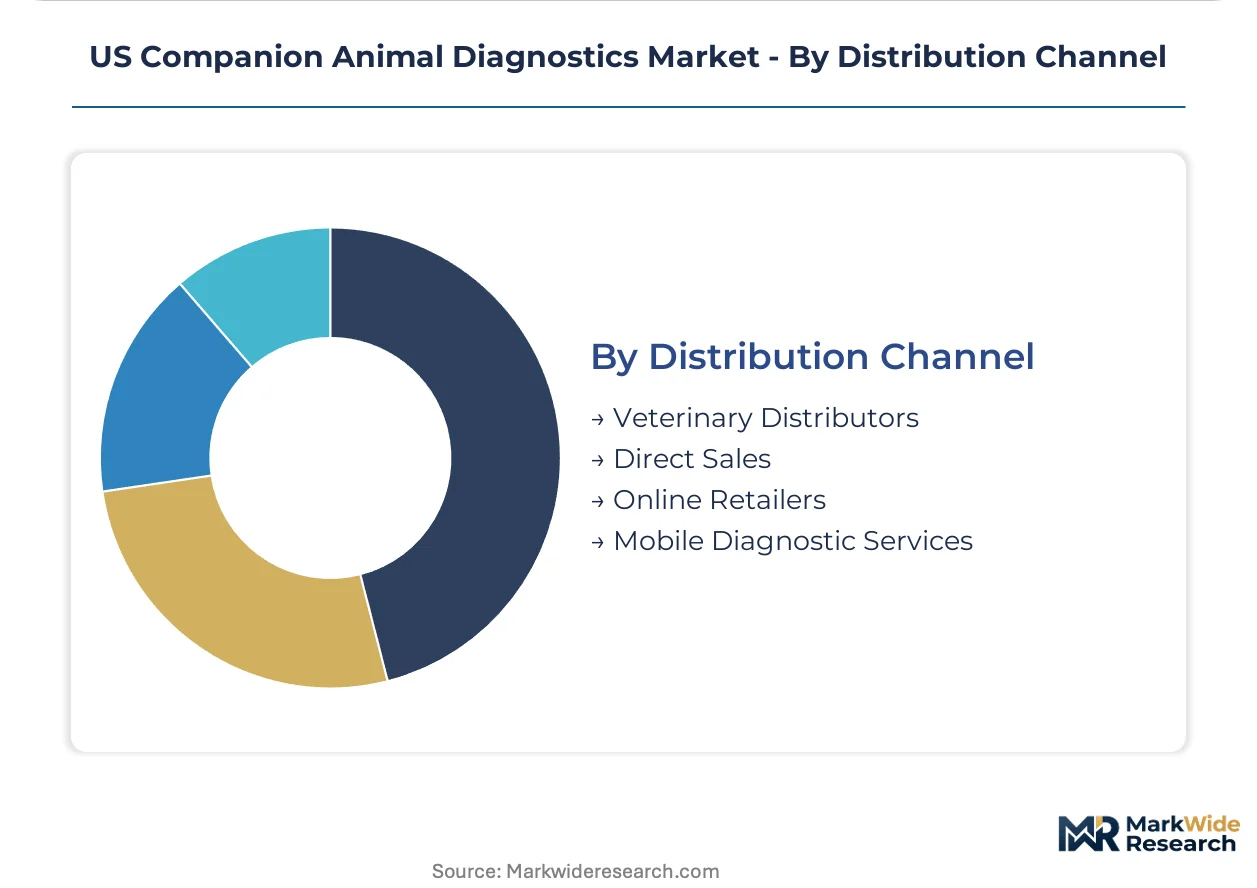
Channel selection reflects customer scale, geographic isolation, and the importance of technical service support for complex instrumentation.
- Veterinary Distributors:National and regional distributors maintain cold-chain logistics for reagents and provide field service engineering. These intermediaries dominate capital equipment sales to independent practices across the Midwest and Southeast where manufacturer direct coverage remains thin.
- Direct Sales:Manufacturers deploy specialized diagnostic sales representatives for high-volume hospital accounts and multi-site corporate groups. IDEXX and Zoetis field organizations target top-tier specialty practices with integrated instrument-reagent-service bundles.
- Online Retailers:E-commerce platforms supply consumables, control materials, and smaller point-of-care instruments to price-sensitive clinics.
- Mobile Diagnostic Services:Service vans equipped with hematology and chemistry analyzers address veterinary deserts across Montana, Wyoming, and the Dakotas.
Transaction volume concentrates through Veterinary Distributors; the fastest channel expansion belongs to Mobile Diagnostic Services penetrating underserved rural markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas metropolitan corridors anchor US companion animal diagnostics demand, with specialty veterinary hospitals in Los Angeles, San Diego, Houston, and Dallas-Fort Worth driving the highest concentration of in-house analyzer placements and reference laboratory send-outs.
California
Pet insurance penetration exceeding 25 percent in the San Francisco Bay Area and Greater Los Angeles accelerates authorization rates for advanced oncology and orthopedic diagnostics. The California Department of Consumer Affairs Veterinary Medical Board enforces scope-of-practice regulations that determine whether veterinary technicians may operate point-of-care equipment. San Diego County hosts the densest cluster of specialty emergency hospitals deploying multiplex PCR platforms for same-day vector-borne disease screening.
Texas
Large-scale veterinary corporate groups in the Dallas-Fort Worth and Houston metropolitan areas consolidate purchasing power for integrated instrument-reagent bundles. The Texas State Board of Veterinary Medical Examiners regulates telemedicine protocols that increasingly incorporate remote interpretation of point-of-care results. Austin and San Antonio specialty practices drive demand for liquid biopsy platforms targeting canine lymphoma monitoring.
New York Metropolitan Area
High-density specialty referral centers in Manhattan, Long Island, and northern New Jersey maintain 24-hour emergency services with dedicated in-house laboratory technical staff. New York State Education Department Office of the Professions oversees veterinary facility licensure requirements that mandate quality assurance programs for in-house immunoassays. The Hudson Valley corridor connects urban specialty demand with exurban general practices adopting CLIA-waived chemistry analyzers.
Florida
Year-round tick exposure patterns in the Tampa Bay and Miami metropolitan areas sustain recurring vector-borne disease testing volumes for ehrlichiosis and anaplasmosis. The Florida Department of Business and Professional Regulation Division of Professions enforces continuing education requirements for laboratory personnel operating diagnostic equipment. Orlando and Jacksonville emergency hospitals lead adoption of respiratory pathogen multiplex panels replacing sequential single-target screens.
Pacific Northwest
Pet insurance penetration in Washington and Oregon approaches Massachusetts levels, reducing owner price sensitivity for advanced imaging and molecular diagnostics. Washington State Department of Health regulates laboratory quality standards through its environmental health division. Seattle and Portland metropolitan areas concentrate independent specialty practices that maintain hybrid models combining in-house hematology with reference laboratory outsourcing for esoteric testing.
US Companion Animal Diagnostics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the US companion animal diagnostics landscape. Full-service reference laboratories with embedded pathologist networks and proprietary logistics infrastructure face competition from modular point-of-care device manufacturers outsourcing manufacturing to contract producers. The market structure stratifies into three archetypes: vertically integrated animal health conglomerates spanning vaccines through diagnostics; specialized diagnostic pure-plays concentrating on instrument-reagent consumable models; and diversified life science tools companies extending human clinical platforms into veterinary applications. Dominant competitive moves include strategic partnerships between equipment vendors and veterinary corporate groups for multi-site standardization, and technology licensing agreements that accelerate molecular assay menu expansion without internal R&D investment.
Within the vertically integrated tier, IDEXX Laboratories and Zoetis occupy positions defined by captive distribution networks and recurring revenue lock-in through reagent contracts. Thermo Fisher Scientific represents the life science tools archetype, leveraging scale advantages in PCR platform manufacturing to serve both human and veterinary infectious disease testing workflows. These three entities exemplify how competitive positioning in US companion animal diagnostics depends less on instrument innovation than on securing multi-year consumable commitments across expanding veterinary hospital networks.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Antech Diagnostics |
| Thermo Fisher Scientific |
| FUJIFILM SonoSite |
| Neogen Corporation |
| Heska Corporation |
| bioMérieux |
| Virbac |
| Others |
Pricing and Supply Chain Analysis
Veterinary hospital consolidation across Texas and California is forcing reagent vendors toward all-inclusive consumable contracts that bundle instruments, service, and per-test pricing into multi-year commitments with penalty clauses for volume shortfalls.
Pricing Analysis
Throughput-based pricing anchors veterinary diagnostic equipment economics, with IDEXX and Zoetis structuring per-test fees that decline with monthly sample volume commitments. Price differentiation rests on CLIA-waiver status and integration depth with practice management systems. Pricing pressure stems from regional reference laboratories offering 40-60% discounts on send-out panels that undercut in-house test economics for low-volume clinics. Corporate veterinary groups exhibit lowest price sensitivity due to standardized procurement, while independent single-doctor practices negotiate aggressively on capital placement terms.
Supply Chain Analysis
Domestic-content preferences in USDA APHIS-funded surveillance programs are redirecting antibody and enzyme conjugate sourcing toward US-based production facilities. Bulk reagent manufacturing concentrates in China, Germany, and the USA, with cold-chain logistics for temperature-sensitive components drawing from specialized distributors in the Midwest and Southeast. Single-source vulnerability pervades veterinary immunoassay enzyme supply, where three domestic distributors control bulk flows. Distribution runs through national veterinary distributors with field service engineering capabilities, supplemented by direct manufacturer relationships for high-volume hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US companion animal diagnostics market is becoming a vertical-integration race, with players pursuing captive control over reagent manufacturing to lock in margin pools and secure supply continuity against cold-chain disruptions.
For Market Incumbents: Anticipate margin compression from regional reference laboratory pricing wars by deepening backward integration into antibody production and enzyme conjugate manufacturing. Secure multi-year exclusive reagent contracts with expanding corporate veterinary groups before competitors can displace installed instrument bases. The threat of modular PCR platform entrants from human clinical diagnostics demands rapid menu expansion through technology licensing rather than internal R&D timelines. For New Entrants and Emerging Players: The price-point gap between premium reference laboratory services and economy point-of-care devices creates entry space for mid-tier platforms targeting suburban general practice clinics with CLIA-waived chemistry panels. Rural veterinary deserts across Montana, Wyoming, and the Dakotas represent the most penetrable geography, where mobile diagnostic services can establish presence before brick-and-mortar competitors. A telemedicine-integrated go-to-market angle, pairing remote result interpretation with point-of-care hardware, bypasses the technician staffing constraints that limit incumbent deployment models. For Investors and Strategic Acquirers: The window for entry favors diagnostic pure-plays with established CLIA-waived assay menus and contracted relationships with mid-size corporate veterinary groups. Long-term viability hinges on consumable revenue predictability rather than instrument placement velocity. The signal to watch is state veterinary medical board telehealth policy evolution, as remote diagnostic interpretation authorization would expand addressable clinic bases and validate platform economics for remote-enabled entrants.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Assay Expansion | FDA Center for Veterinary Medicine streamlined pathways accelerate point-of-care deployment without dedicated laboratory personnel. |
| Mobile Diagnostic Service Buildout | Service vans equipped with hematology and chemistry analyzers penetrate veterinary deserts across Montana, Wyoming, and the Dakotas. |
| Reagent Manufacturing Integration | Captive antibody and enzyme conjugate production secures margin pools against cold-chain disruption vulnerabilities. |
| Telemedicine-Triage Protocol Development | State veterinary medical board relaxations on remote result interpretation expand addressable clinic bases in Arizona and Colorado. |
| Pharmacogenomic Testing Integration | Cytochrome P450 platforms for canine drug metabolism create pull-through for both diagnostic and therapeutic product lines. |
Research Methodology
Document review covered FDA Center for Veterinary Medicine premarket filings, USDA APHIS disease surveillance program documentation, and state veterinary practice act regulations, complemented by interviews with veterinary diagnostic laboratory directors, corporate group procurement officers, reference laboratory operations managers, and point-of-care device field service engineers. Secondary validation drew from SEC 10-K filings of publicly traded animal health companies, veterinary trade association membership data, and pet insurance penetration statistics by state. Bottom-up instrument placement estimates and top-down market size triangulation cross-validated segment-level demand projections.
Market size and growth trajectory outputs reflect segmentation across product type, application, end user, and distribution channel dimensions, with geographic clustering by state regulatory environment and veterinary corporate group concentration. CAGRs were derived from instrument placement run rates, consumable pull-through per installed unit, and reference laboratory send-out volume trends. Forecast inputs incorporated CLIA-waiver expansion timelines, telemedicine regulatory evolution, and pet insurance penetration growth patterns across the projection horizon.
Inputs from state veterinary medical boards and USDA APHIS program administrators were available through the study window; gaps in real-time corporate group procurement contract terms introduce uncertainty bands around instrument placement velocity assumptions. Forecasts reflect documented regulatory trajectories and stakeholder interview perspectives, with revision risk concentrated in telehealth policy timing and reagent supply disruption scenarios. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Hospitals Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Global Animal Model Market
Veterinary
Feline Atopic Dermatitis Treatment Market
Veterinary
Veterinary Vaccines Market
Veterinary
Global Canine Influenza Vaccine Market
Veterinary
Veterinary Biologicals Biobank Market
Veterinary
Bovine Mastitis Treatment System Market
Veterinary
Veterinary Scales Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Milking Salve Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Mexico Veterinary Healthcare Market
Veterinary
Veterinary Endotracheal Tubes Market
Veterinary
Pet Veterinary Diet Market
Veterinary
Global Porcine Vaccine Market