
 Pet DNA Testing Market | 2026-2036
Pet DNA Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pet DNA Testing Market Analytics
Veterinary clinic procurement is consolidating as regional practice groups standardize genetic testing protocols across their networks. Mars Petcare leverages its integrated veterinary services platform to anchor recurring testing volumes within corporate-affiliated clinics. Zoetis Inc. competes through its diagnostics division, sustaining R&D intensity in species-specific genomic panels. Embark Veterinary, Inc. differentiates by controlling proprietary breed reference databases that strengthen consumer-facing brand loyalty.
Pet DNA testing analyzes canine and feline genetic material extracted from saliva or cheek swab samples, employing targeted amplification and sequencing protocols to detect breed composition, heritable disease markers, and phenotypic trait variations. The primary commercial purpose centers on enabling predictive health interventions and informed breeding decisions that reduce lifetime veterinary expenditure. Health screening panels command premium positioning due to their clinical utility in detecting pathogenic variants for conditions such as degenerative myelopathy and hypertrophic cardiomyopathy, while breed identification retains volume leadership through accessible direct-to-consumer pricing. Next-generation sequencing occupies the fastest-expanding technology tier as throughput gains and reagent cost reductions displace microarray methods in comprehensive panel designs.
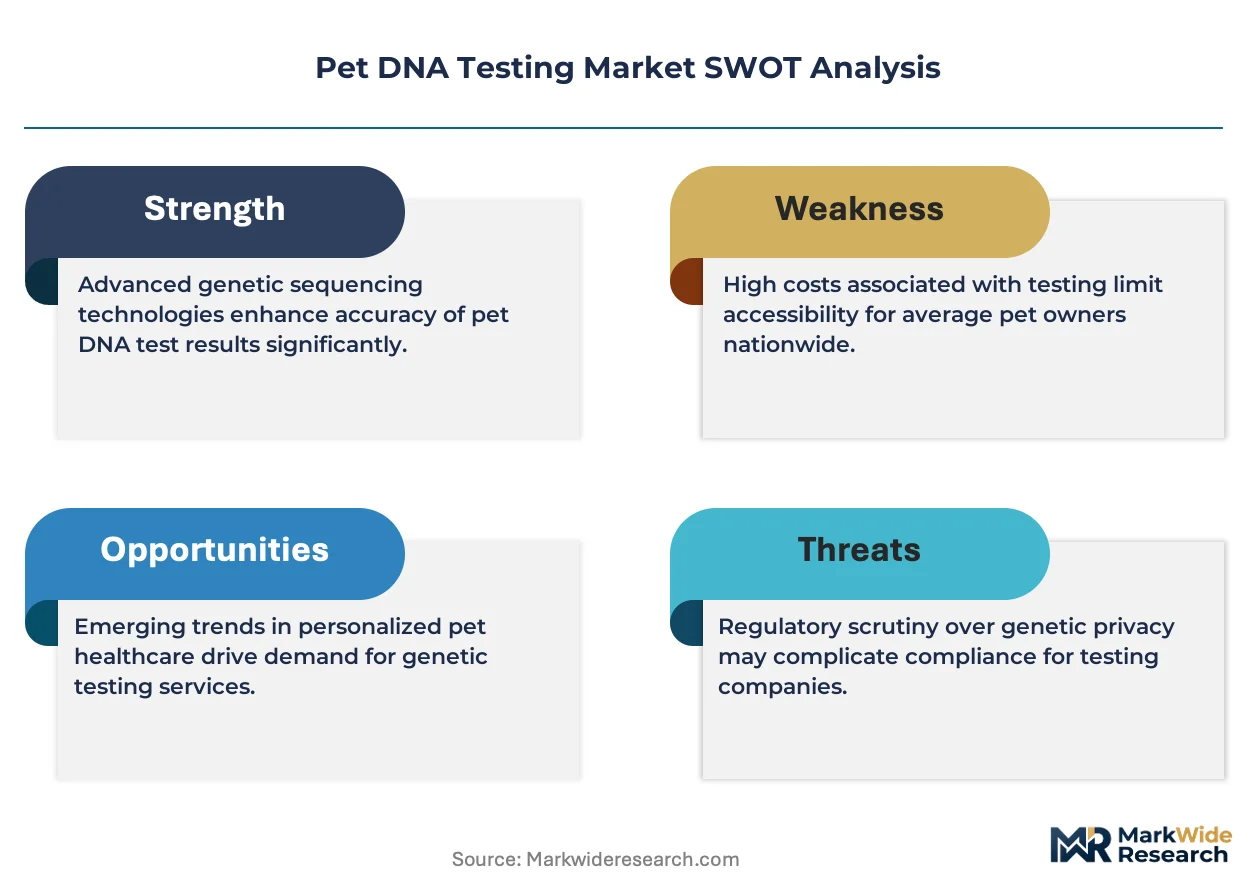
The FDA exercises oversight of laboratory-developed tests through discretionary enforcement policies that influence validation standards for clinical-grade health screening offerings. The USDA's Animal and Plant Health Inspection Service coordinates with state veterinary boards to establish practitioner authorization requirements for diagnostic sample collection. ISO 17025 accreditation functions as a de facto market access credential for laboratories serving international distribution channels. Stakeholders must monitor regulatory convergence between human and veterinary diagnostic frameworks as genomic medicine standards migrate across species boundaries.
Market Dynamics
Next-generation sequencing is compressing turnaround times and per-sample costs, forcing microarray-dependent laboratories to retool capital equipment or cede comprehensive health screening segments to sequencing-native competitors.
Growth Catalysts
- ISO 17025 accreditation mandates:International distributors now require accredited laboratory credentials for cross-border sample logistics, accelerating certification investments among regional testing providers.
- Veterinary clinic network consolidation:Corporate practice groups standardize genetic testing protocols across multi-site operations, generating recurring panel volumes that stabilize laboratory revenue forecasting.
- CRISPR-based validation workflows:Gene-editing confirmation methods reduce variant interpretation error rates, strengthening clinical utility claims for heritable disease screening panels.
Market Restraints
- Illumina sequencer reagent lock-in:Proprietary consumable pricing and supply allocation protocols concentrate instrument-dependent laboratories on single-vendor chemistry ecosystems.
- FDA discretionary enforcement uncertainty:Laboratory-developed test classification ambiguity creates validation cost inflation for health screening products targeting clinical decision support.
- Reference database asymmetry:Proprietary breed and variant catalog control by incumbent providers raises barriers for new entrants developing competitive ancestry algorithms.
Strategic Opportunities
- USDA-APHIS practitioner authorization harmonization:Federal-state coordination on telemedicine sample collection protocols opens remote rural markets previously constrained by veterinary physical presence requirements.
- Feline genomic panel underdevelopment:Canine-dominated product portfolios leave hypertrophic cardiomyopathy and polycystic kidney disease screening for purebred cats as a whitespace segment.
- Direct-to-consumer subscription bundling:Annual health monitoring re-tests combined with nutrition recommendations create recurring revenue streams beyond one-time breed identification purchases.
Industry Challenges
- Bioinformatics variant curation backlog:Veterinary geneticists face persistent hiring gaps against accelerating VCF file volumes from high-throughput sequencing platforms.
- CLIA laboratory certification timelines:State-by-state inspection queue variability delays commercial launch schedules for multi-site testing networks.
- Multi-omics data integration complexity:Combining SNP arrays with microbiome and metabolite profiles requires cross-functional teams spanning genomics, nutrition science, and software engineering.
Report Scope
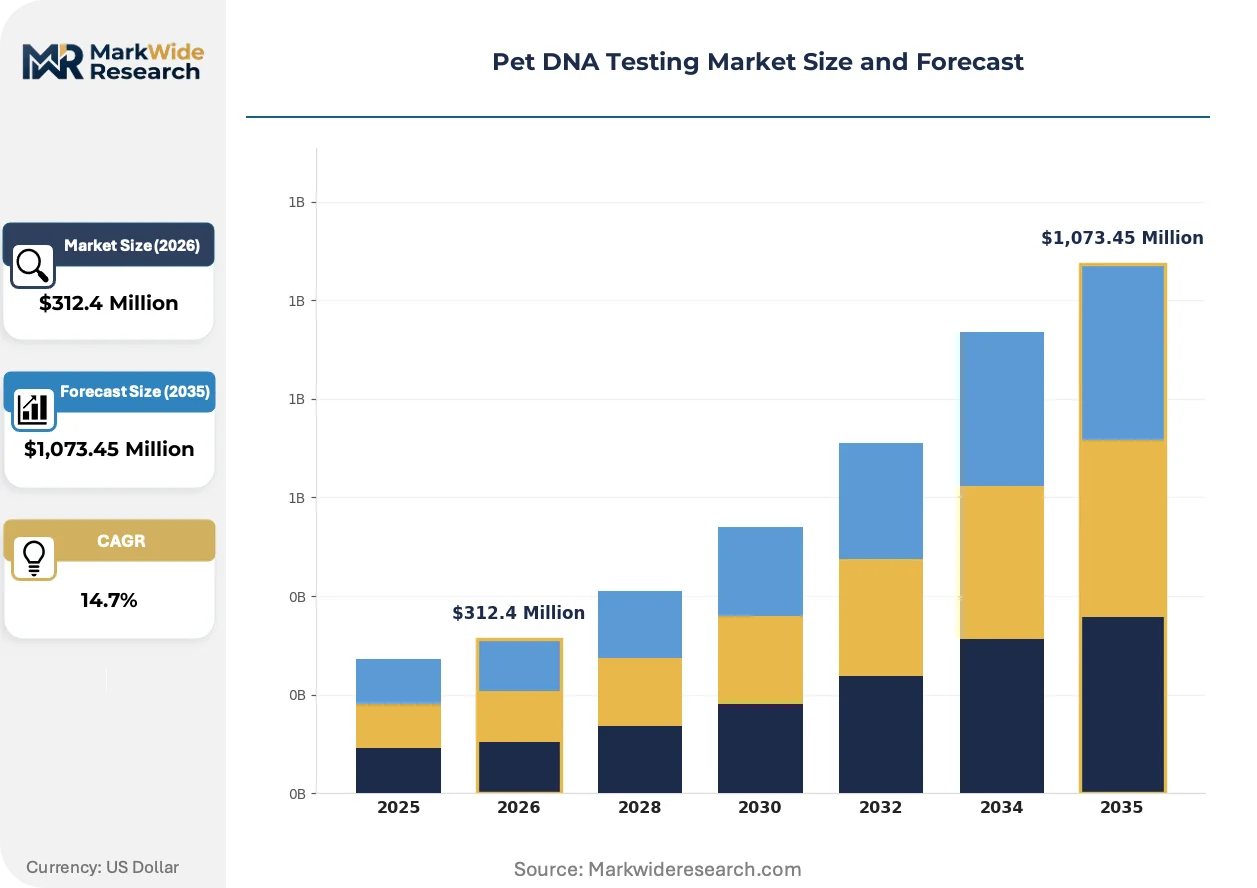
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet DNA Testing Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breed Identification, Ancestry Analysis, Health Screening, Trait Testing End User: Pet Owners, Veterinarians, Research Institutions, Animal Shelters Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Microarray, SNP Analysis Service Type: In-Home Testing, Lab Testing, Consultation Services, Subscription Services |
| Companies Covered | Embark Veterinary, Inc., Mars Petcare, Zoetis Inc., DNA My Dog, Orivet Genetic Pet Care, Neogen Corporation, Basepaws, Inc., Dognomics, Wisdom Panel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet DNA Testing Market Evolving Landscape
Three intersecting developments are restructuring competitive advantage in pet genetic services: sequencing chemistry evolution, regulatory boundary clarification, and buyer relationship model transformation.
Whole-genome sequencing is expanding into clinical veterinary workflows as reagent costs fall below microarray parity for comprehensive disease screening. Specialist referral hospitals adopt 30x coverage protocols for complex phenotype-genotype correlation studies. This expansion is compressing the addressable market for targeted SNP panels limited to breed ancestry and single-gene disorders.
The FDA's evolving oversight posture on laboratory-developed tests is forcing health screening providers to document analytical validity through prospective clinical studies. Diagnostic divisions must now maintain veterinary clinical trial capabilities previously unnecessary for direct-to-consumer ancestry products. US-based laboratories are responding by segregating clinical-grade and recreational product lines under separate quality management systems.
Pet owners increasingly expect actionable health interventions rather than static genetic risk reports. Veterinary clinics are replacing one-time test-and-forget transactions with longitudinal monitoring programs that schedule follow-up diagnostics based on variant-specific penetrance timelines. This behavioral shift is most pronounced in US metropolitan markets where pet insurance reimbursement covers predictive screening as a preventive care benefit.
Pet DNA Testing Market Segmentation
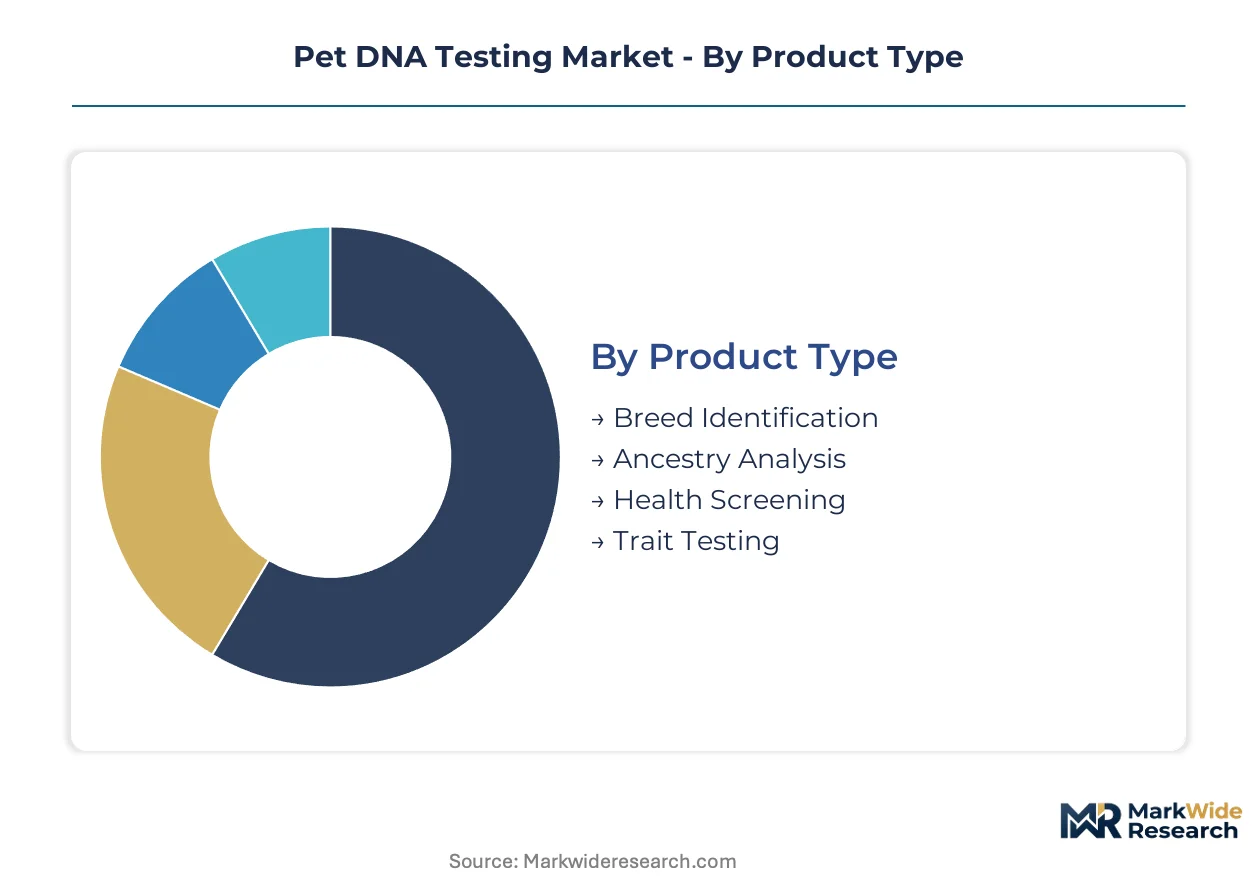
Segmentation in pet DNA testing reveals how laboratory capacity, regulatory pathways, and buyer procurement patterns fragment across distinct commercial configurations. Each dimension—product, end user, technology, and service model—carries unique margin structures and capital intensity requirements that shape competitive positioning.
Product Type:
Supply concentration in high-complexity health panels has concentrated CLIA-certified laboratory capacity among providers with veterinary clinical trial capabilities, while breed identification kits flow through less regulated direct-to-consumer fulfillment networks.
- Health Screening:Multi-gene panels detecting pathogenic variants for degenerative myelopathy, hypertrophic cardiomyopathy, and drug sensitivities require CLIA laboratory certification and veterinary clinical validation. Demand concentrates in US metropolitan veterinary referral hospitals where pet insurance reimbursement covers predictive screening as a preventive care benefit, though FDA discretionary enforcement on laboratory-developed tests inflates validation costs.
- Breed Identification:SNP-based ancestry algorithms comparing against proprietary reference databases deliver accessible price points through retail and e-commerce channels. Volume leadership in the United States reflects direct-to-consumer channel maturity and pet humanization trends that outpace other national markets.
- Ancestry Analysis:Extended pedigree reconstruction and geographic origin mapping serve niche breeder and enthusiast segments with higher willingness-to-pay for detailed lineage documentation.
- Trait Testing:Coat color, body size, and behavioral marker panels target breeding program selection criteria with faster turnaround requirements than comprehensive health screening.
Health Screening absorbs the bulk of installed capacity; Health Screening is expanding most quickly as veterinary clinics integrate predictive genomics into preventive care protocols.
End User:
Procurement patterns diverge sharply between subscription-oriented pet owners seeking longitudinal monitoring and corporate veterinary groups standardizing protocols across multi-site operations.
- Veterinarians:Corporate practice groups and regional networks generate recurring panel volumes through standardized genetic testing protocols, with procurement consolidating around laboratories offering integrated practice management system connectivity. CLIA certification and rapid turnaround times drive supplier selection in the United States.
- Pet Owners:Direct-to-consumer purchasers prioritize accessible pricing, intuitive result interpretation, and actionable health recommendations over technical specifications. US market concentration reflects mature e-commerce fulfillment infrastructure and pet insurance penetration covering preventive screening.
- Research Institutions:Academic veterinary programs and genomic research centers demand comprehensive datasets with raw data access permissions for phenotype-genotype correlation studies.
- Animal Shelters:High-throughput breed identification for intake classification operates on constrained budgets with volume-discounted pricing and simplified result formats.
Veterinarians command the highest per-test revenue; Veterinarians are gaining share fastest as clinic network consolidation redirects procurement toward contracted laboratory partners.
Technology:
Capital equipment decisions lock laboratories into multi-year reagent supply agreements that constrain flexibility as sequencing chemistry evolution accelerates.
- Next-Generation Sequencing:Whole-genome and targeted panel sequencing at 30x coverage enables comprehensive variant detection with falling per-sample costs displacing microarray methods. Specialist referral hospitals in the United States adopt these protocols for complex diagnostic cases.
- Microarray:SNP genotyping arrays retain cost advantages for high-volume breed identification but face market share erosion as sequencing reagent costs approach parity.
- Polymerase Chain Reaction:Single-gene and limited panel testing persists in point-of-care veterinary settings requiring rapid turnaround without laboratory logistics.
- SNP Analysis:Targeted variant confirmation workflows support breeding program selection and parentage verification with standardized interpretive frameworks.
Next-Generation Sequencing dominates capital investment; Next-Generation Sequencing is climbing the fastest as throughput gains and reagent cost reductions expand addressable applications.
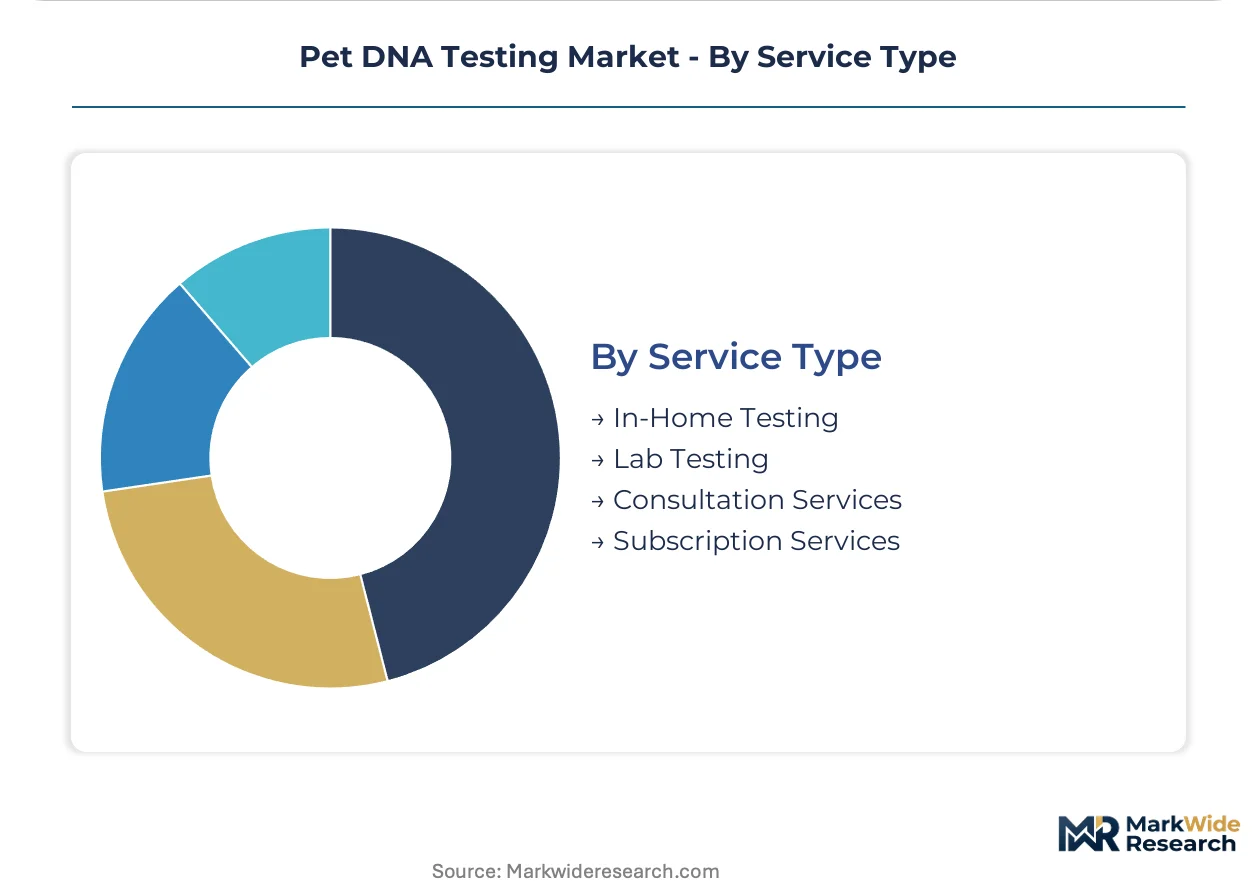
Service Type:
Margin structures stratify between one-time transactional testing and recurring subscription models that transform customer lifetime value calculations.
- Subscription Services:Annual health monitoring re-tests combined with nutrition and lifestyle recommendations create predictable revenue streams and deepen customer retention. US direct-to-consumer markets show strongest adoption where pet owners expect longitudinal health interventions.
- Lab Testing:Centralized CLIA-certified laboratory processing maintains quality control and regulatory compliance for clinical-grade health screening, with logistics networks optimized for veterinary clinic and shelter volume.
- In-Home Testing:Saliva and cheek swab collection kits with prepaid return shipping reduce friction for direct-to-consumer breed identification purchases.
- Consultation Services:Veterinary geneticist interpretation and breeding counseling add professional service margins to commoditized test results.
Lab Testing retains volume leadership; Subscription Services are gaining share fastest as providers bundle predictive screening with ongoing health monitoring programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households drive the bulk of commercial demand, with veterinary clinic consolidation and pet insurance reimbursement creating concentrated procurement corridors that outpace other national markets.
United States
FDA discretionary enforcement on laboratory-developed tests shapes validation requirements for clinical-grade health screening panels. Corporate veterinary groups in Texas and California standardize genetic testing protocols across multi-site networks, generating recurring panel volumes. The Greater Boston corridor hosts specialist referral hospitals adopting 30x whole-genome coverage protocols for complex diagnostic cases.
Germany
EMA-aligned veterinary pharmaceutical regulation influences diagnostic validation standards for cross-border EU distribution. ISO 17025 accreditation functions as a de facto market access credential for laboratories serving international sample logistics. The Munich-Stuttgart corridor concentrates precision livestock and companion animal genomics research institutions driving panel development.
United Kingdom
Pet insurance penetration in London and Southeast England covers predictive screening as a preventive care benefit, accelerating veterinary clinic adoption. The country's national pharmaceutical regulator maintains oversight coordination with veterinary clinical trial frameworks. The Cambridge-Oxford arc anchors academic veterinary programs demanding comprehensive phenotype-genotype datasets.
Japan
PMDA veterinary division guidance shapes clinical validation requirements for imported health screening technologies. METI industrial policy supports genomic medicine translation across species boundaries. The Kanto region around Tokyo concentrates specialty veterinary hospitals integrating predictive genomics into preventive care protocols.
Australia
TGA veterinary medical device frameworks influence diagnostic import and validation pathways for international testing providers. State veterinary boards establish practitioner authorization requirements for diagnostic sample collection. The Sydney-Melbourne corridor hosts high-throughput breed identification services for animal shelter intake classification.
Pet DNA Testing Market Competitive Landscape
United States producers anchor the premium health screening tier; European and Asia-Pacific specialists hold positions in breed identification and reference database development. Market structure stratifies between vertically integrated veterinary service platforms and independent testing laboratories. Three archetypes dominate: corporate-affiliated diagnostic divisions, direct-to-consumer ancestry specialists, and CLIA-certified clinical laboratories. Competitive dynamics center on proprietary reference database control and veterinary practice management system integration.
Within the integrated veterinary services tier, Mars Petcare exemplifies platform consolidation through captive clinic network procurement. Embark Veterinary, Inc. occupies a position in the direct-to-consumer ancestry segment through proprietary breed reference database control. Zoetis Inc. anchors the animal health pharmaceutical archetype with diagnostics division capabilities.
| Leading Market Players |
|---|
| Embark Veterinary, Inc. |
| Mars Petcare |
| Zoetis Inc. |
| DNA My Dog |
| Orivet Genetic Pet Care |
| Neogen Corporation |
| Basepaws, Inc. |
| Dognomics |
| Wisdom Panel |
| Others |
Value Network & Pricing Analysis
Illumina sequencing reagent pricing indices cascade through laboratory cost structures, compressing margins for microarray-dependent providers while rewarding sequencing-native competitors with tiered pricing flexibility across clinical-grade and direct-to-consumer product lines.
Pricing Analysis
Volume leadership in breed identification trades at per-unit transactional pricing, while health screening panels command subscription-based premiums through recurring veterinary clinic procurement. Price differentiation hinges on CLIA certification grade and proprietary reference database depth. Pricing pressure stems from CRISPR-based validation workflows reducing variant interpretation costs. Direct-to-consumer pet owners exhibit highest price sensitivity; corporate veterinary groups prioritize turnaround reliability over unit economics.
Supply Chain Analysis
Sequencing instrument supply rests on Illumina's San Diego production footprint and Thermo Fisher's Massachusetts operations, with reagent chemistry anchored in Singapore and German specialty chemical facilities. Laboratories draw from proprietary oligo synthesis, fluorophore conjugates, and polymerase enzyme inputs. Single-source vulnerability concentrates in Illumina's consumable allocation protocols. Distribution runs through CLIA-certified laboratory networks for clinical-grade panels and direct-to-consumer e-commerce fulfillment for ancestry products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CLIA-certified laboratory capacity constraints prop pricing premiums for clinical-grade health screening, creating supply-constrained conditions favoring incumbents with validated veterinary trial capabilities.
For Market Incumbents: Acquire proprietary feline genomic reference databases to preempt whitespace competition in hypertrophic cardiomyopathy screening. Consolidate backward integration into oligo synthesis capabilities to offset Illumina reagent lock-in. Defend against sequencing-native entrants by embedding practice management system connectivity across corporate veterinary networks. For New Entrants and Emerging Players: The mid-tier pricing gap between premium health panels and economy breed identification offers entry positioning through targeted trait testing bundles. Feline genomic panels remain underdeveloped relative to canine saturation. Pursue USDA-APHIS telemedicine authorization harmonization to access rural veterinary markets without physical clinic presence requirements. For Investors and Strategic Acquirers: The window for entry favors CLIA-certified clinical laboratories with veterinary geneticist staffing. Long-term viability centers on subscription service models transforming transactional testing into recurring revenue. Watch for FDA laboratory-developed test classification clarity as inflection signal for clinical-grade validation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Database Acquisition | Control over breed and variant catalogs strengthens algorithmic differentiation against sequencing-native competitors. |
| CLIA Laboratory Certification Investment | Certification unlocks veterinary clinic procurement channels requiring regulatory-compliant health screening protocols. |
| Subscription Service Launch | Annual re-test bundling transforms one-time breed identification into predictable recurring revenue streams. |
| Practice Management System Integration | Embedded workflow connectivity secures recurring panel volumes within consolidating corporate veterinary networks. |
| Feline Genomic Panel Development | Hypertrophic cardiomyopathy and polycystic kidney disease screening addresses whitespace in canine-dominated portfolios. |
Research Methodology
Document review covered FDA veterinary guidance documents, ISO 17025 accreditation registries, and corporate veterinary network procurement disclosures, complemented by interviews with laboratory operations directors, veterinary geneticists, and practice management system vendors. Secondary validation drew from USDA-APHIS regulatory filings, state veterinary board authorization records, and pet insurance reimbursement policy databases. Bottom-up laboratory capacity estimates and top-down veterinary clinic panel adoption rates underwent triangulation.
Market sizing outputs segmented across product type, end user archetype, technology platform, and service model dimensions throughout the projection horizon. CAGRs derived from laboratory reagent cost decline curves and veterinary clinic network expansion trajectories. Forecast inputs incorporated Illumina sequencer placement data and corporate practice group standardization timelines.
Inputs from CLIA certification databases and veterinary geneticist employment surveys were available through the study window; gaps in proprietary reference database completeness introduce uncertainty bands around ancestry algorithm accuracy claims. Forecasts reflect documented assumptions on regulatory convergence timelines and reagent cost parity achievement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Global Porcine Vaccine Market
Veterinary
Global Swine Vaccines Market
Veterinary
Veterinary Scales Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Milking Salve Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Europe Veterinary Vaccine Market
Veterinary
Canine Parvovirus Market
Veterinary
Orthopedic Dog Bed Market
Veterinary
United Kingdom Veterinary Healthcare Market
Veterinary
Bovine Respiratory Disease Treatment Market
Veterinary
Global Animal Vaccine Market
Veterinary
Animal Antibiotics Market
Veterinary
Animal Drug Compounding Market
Veterinary
Rabies Veterinary Vaccines Market
Veterinary
Global Veterinary Telemetry Systems Market