
 Veterinary Contract Development and Manufacturing Organizations (CDMO) Market | 2026-2036
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market Insights
Asset-light contract structures and third-party leasing of sterile fill-finish suites is narrowing the capital barrier for mid-tier entrants. Charles River Laboratories leverages its integrated discovery-to-manufacturing footprint to anchor large-molecule veterinary programs. Lonza sustains competitive position through biologics manufacturing scale across multi-product facilities. Evonik differentiates via specialized formulation expertise in complex small-molecule delivery.
Veterinary Contract Development and Manufacturing Organizations provide outsourced pharmaceutical development and commercial production services for animal health products, encompassing sterile injectable filling, tablet compression, and analytical method validation under species-specific pharmacokinetic requirements. These organizations serve the primary purpose of enabling animal health innovators to access regulated manufacturing capacity without owning fixed assets. Formulation Development commands the deepest margin pools due to high technical barriers in species-specific bioavailability optimization. Biologics represents the fastest-expanding technology segment as monoclonal antibodies and gene therapies migrate from human to companion animal applications. Packaging Solutions remains comparatively mature, with competition centered on cold-chain compliance and serialization capabilities.
The FDA's Center for Veterinary Medicine enforces cGMP standards that shape facility qualification timelines and batch release protocols for U.S.-bound products. The EU's EMA and its coordinated national regulators apply the Veterinary Medicines Regulation, which harmonizes manufacturing authorization across member states and elevates documentation burdens for non-EU CDMOs. The USDA's Center for Veterinary Biologics maintains separate oversight for vaccine antigen production, creating a dual-track compliance environment. Stakeholders must monitor how converging FDA and EMA data integrity expectations will reshape audit frequencies and remediation costs for multi-jurisdictional manufacturers.
Market Dynamics
Biologics manufacturing capacity scarcity is compressing contract timelines and forcing animal health innovators into longer-term partnerships with veterinary CDMOs possessing mammalian cell culture suites. The shift from small-molecule tablets to monoclonal antibodies for companion animals concentrates demand on facilities with single-use bioreactor infrastructure.
Growth Catalysts
- USDA Center for Veterinary Biologics oversight:The dual-track regulatory environment for vaccines versus pharmaceuticals creates specialized demand for antigen production facilities that few in-house operations can justify building.
- Monoclonal antibody pipeline migration:Human biologic platforms are being repurposed for canine and feline oncology applications, requiring CDMOs with existing mammalian expression systems.
- Specialty veterinary practice consolidation:Large referral hospitals in the United States are driving demand for sterile injectable formulations that require aseptic fill-finish capabilities beyond general practice needs.
Market Restraints
- Single-use consumables cost volatility:Bioprocess bags and connectors face resin supply fluctuations that compress margins for biologics-focused CDMOs.
- Qualified personnel scarcity:Aseptic processing technicians with veterinary pharmacology training command wage premiums that inflate fixed cost structures.
- EMA Veterinary Medicines Regulation documentation:Non-EU manufacturers face elevated batch record scrutiny that extends qualification timelines for European-bound products.
Strategic Opportunities
- Gene therapy manufacturing white space:AAV vector production for inherited diseases in purebred dogs remains underserved by existing mammalian cell culture facilities.
- India's animal health export incentives:The country's PLI scheme for pharmaceuticals extends to veterinary products, attracting investment in multi-species formulation capacity.
- Cold-chain serialization convergence:Track-and-trace mandates across the EU and United States create demand for integrated packaging and distribution services.
Industry Challenges
- Cross-species pharmacokinetic modeling:Translating bioavailability data between canine, feline, and equine patients requires specialized formulation scientists that outpace current training pipelines.
- Facility reconfiguration timelines:Switching between small-molecule oral solids and biologic parenterals demands lengthy cleaning validation protocols that compress asset utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Contract Development and Manufacturing Organizations (CDMO) Market |
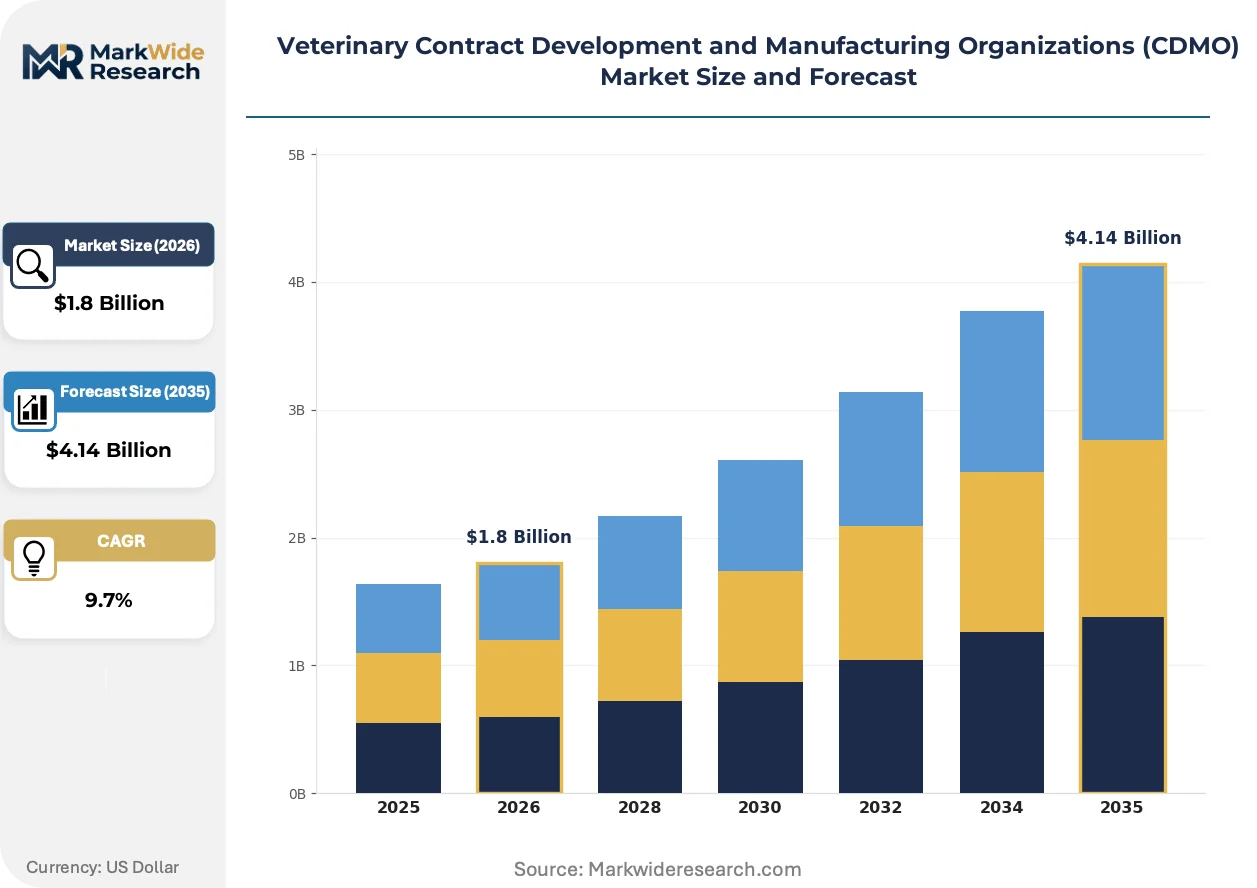
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Analytical Testing, Packaging Solutions, Clinical Trials End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Veterinary Clinics Technology: Biologics, Small Molecules, Vaccines, Companion Animal Treatments Product Type: Injectables, Tablets, Topicals, Oral Solutions |
| Companies Covered | TriRx Pharmaceutical Services, LABIANA Group, Charles River Laboratories, Lonza, Clinvet, Argenta, Aenova Group, Evonik, Vetio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market Trends and Innovations
Process analytical technology is reshaping how veterinary CDMOs demonstrate batch consistency to regulators. Real-time release testing is compressing quality control timelines from weeks to days.
Continuous manufacturing platforms for oral solid dosage forms are digitizing batch record management and enabling real-time deviation detection. Mid-tier CDMOs in the United States are adopting these systems to compete with larger integrated players on documentation speed. The technology is digitizing compliance workflows and reducing manual transcription errors that trigger FDA Form 483 observations.
REACH chemical registration requirements in the European Union are forcing reformulation of excipients used in companion animal topicals. Manufacturers are substituting petroleum-derived carriers with bio-based alternatives to satisfy substance volume tracking mandates. The regulation is elevating documentation burdens for CDMOs serving European clients with dermatology pipelines.
Consolidated procurement by veterinary hospital networks is displacing fragmented distributor purchasing. Large specialty practice groups in the United States are negotiating direct manufacturing agreements that bypass traditional animal health distribution. The behavior is concentrating volume with CDMOs capable of serialized unit-dose packaging for in-clinic dispensing.
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market Segmentation
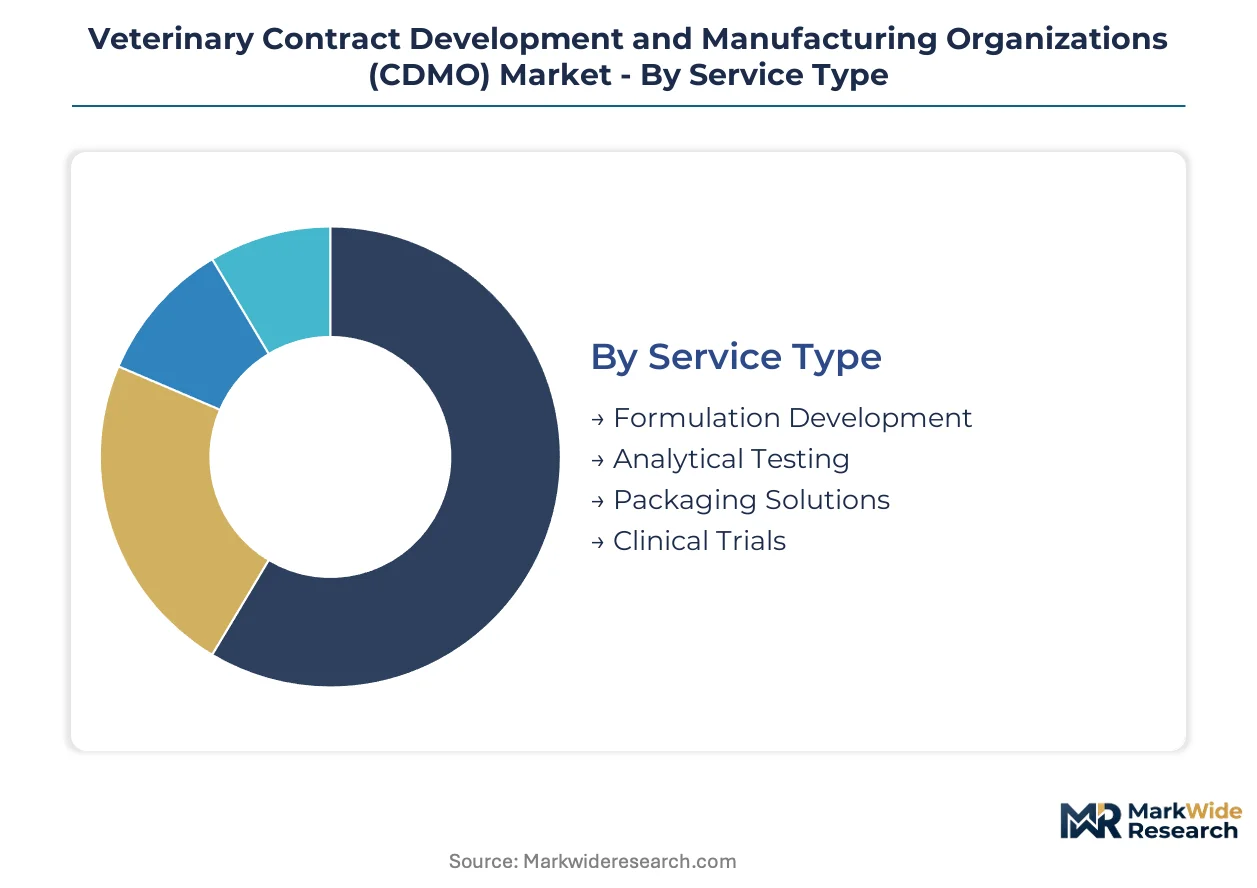
Veterinary CDMO segmentation reveals divergent margin profiles and capital intensity across service tiers. Contract structures vary dramatically between high-touch formulation partnerships and commoditized packaging runs.
Service Type:
Cycle times compress from years in early-phase formulation to weeks in routine analytical batches, creating distinct working capital demands across the service stack.
- Formulation Development:Species-specific bioavailability optimization demands pharmacokinetic modeling capabilities that few CDMOs maintain in-house. United States-based innovators concentrate purchasing power here as companion animal pipelines migrate toward complex delivery systems.
- Analytical Testing:Method validation and stability studies operate under FDA cGMP and EMA Veterinary Medicines Regulation documentation standards. Batch release timelines extend when multi-jurisdictional filings require harmonized data packages.
- Packaging Solutions:Cold-chain serialization and unit-dose configuration for veterinary clinic dispensing.
- Clinical Trials:Field efficacy studies across canine, feline, and equine populations with species-specific endpoint validation.
Formulation Development anchors the volume base while Analytical Testing gains share at the steepest rate.
End User:
Customer sophistication tiers separate capital-backed biotech ventures from institution-funded academic programs.
- Pharmaceutical Companies:Integrated animal health divisions outsource capacity peaks and specialized biologics runs. These buyers negotiate multi-year master service agreements that lock in mammalian cell culture suite access.
- Biotech Firms:Venture-funded developers of monoclonal antibody therapies for canine oncology represent the most price-insensitive demand segment. Their programs require single-use bioreactor infrastructure that in-house manufacturing cannot justify.
- Research Institutions:Grant-funded exploratory programs with irregular batch frequencies.
- Veterinary Clinics:Compounding demand for personalized formulations in specialty referral hospitals.
Pharmaceutical Companies dominate contract value while Biotech Firms expand most quickly.
Technology:
Platform switching costs create stickiness that favors CDMOs with flexible multi-modal facilities.
- Biologics:Monoclonal antibodies and gene therapies require mammalian expression systems with single-use bioreactor trains. The USDA Center for Veterinary Biologics maintains separate antigen production oversight, creating dual-track compliance complexity.
- Small Molecules:Tablet and capsule formulations for chronic companion animal conditions leverage established oral solid dosage infrastructure with lower regulatory burden than biologics.
- Vaccines:Attenuated and recombinant antigen production with USDA batch release protocols.
- Companion Animal Treatments:Palatability-optimized formulations for canine and feline adherence.
Small Molecules retains the broadest installed base while Biologics climbs the fastest.
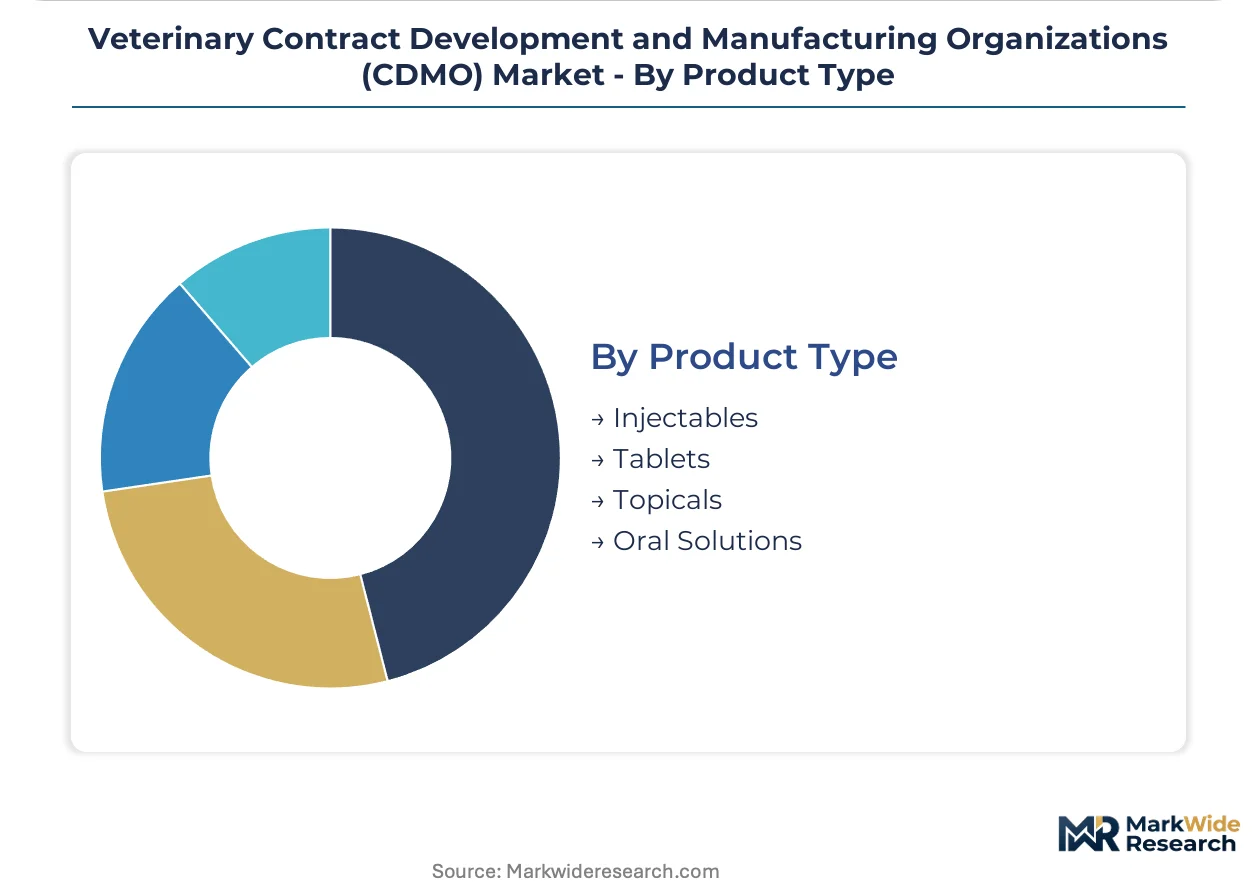
Product Type:
Delivery form selection dictates facility qualification requirements and cleaning validation protocols.
- Injectables:Sterile fill-finish operations demand aseptic processing suites with isolator technology. Specialty veterinary hospitals in the United States drive demand for preservative-free multidose vials.
- Tablets:Continuous manufacturing platforms enable real-time release testing that compresses quality control timelines. Mid-tier CDMOs adopt these systems to compete on documentation speed.
- Topicals:Transdermal and otic formulations with REACH-compliant excipient substitution for European markets.
- Oral Solutions:Palatable liquid formulations for feline medication compliance.
Tablets sustain the highest throughput volumes while Injectables commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for pharmaceutical manufacturing are reshaping where veterinary CDMO capacity locates. Export credit programs in India and tax advantages in Ireland are pulling investment from traditional North American hubs. Regulatory divergence between FDA and EMA standards forces multi-site qualification strategies.
United States
Specialty veterinary hospital consolidation in Texas and Florida is concentrating demand for sterile injectable capacity. The FDA's Center for Veterinary Medicine enforces cGMP standards that extend facility qualification timelines. Greater Boston anchors mammalian cell culture investment as monoclonal antibody pipelines migrate from human to companion animal oncology.
Germany
Integrated animal health divisions at Bayer and Boehringer Ingelheim outsource biologics peaks to regional CDMOs. The EMA's Veterinary Medicines Regulation harmonizes manufacturing authorization across EU member states. Baden-Württemberg hosts formulation specialists serving European dermatology pipelines facing REACH excipient compliance.
Switzerland
Gene therapy developers target purebred canine inherited diseases through AAV vector platforms. Swissmedic maintains batch release protocols aligned with FDA data integrity expectations. Basel's biotech cluster concentrates CDMOs with single-use bioreactor trains qualified for multi-jurisdictional filings.
India
The PLI scheme for pharmaceuticals extends to veterinary products, attracting investment in multi-species formulation capacity. CDSCO and DGFT coordinate export incentives that undercut European manufacturing costs. Hyderabad and Ahmedabad emerge as sterile injectable hubs serving Southeast Asian and African animal health markets.
United Kingdom
Post-Brexit divergence from EMA standards creates dual-track compliance costs for CDMOs serving EU and UK clients. The Veterinary Medicines Directorate maintains separate manufacturing authorization requirements. Southeast England concentrates analytical testing capacity supporting field efficacy studies across canine and feline populations.
Veterinary Contract Development and Manufacturing Organizations (CDMO) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated discovery-to-manufacturing organizations anchor the premium tier through multi-year master service agreements. Mid-tier entrants leverage asset-light contract structures and third-party leasing of sterile fill-finish suites to narrow capital barriers. Consolidation concentrates volume with CDMOs capable of serialized unit-dose packaging for direct veterinary hospital dispensing. Capacity expansion and strategic partnerships dominate competitive moves as biologics manufacturing scarcity compresses contract timelines.
Within the integrated tier, Charles River Laboratories and Lonza exemplify archetypes of end-to-end service provision. Charles River leverages its footprint across discovery biology and safety assessment to anchor large-molecule veterinary programs from candidate selection through commercial production. Lonza sustains position through biologics manufacturing scale across multi-product facilities with single-use infrastructure. Evonik occupies a distinct specialization vector, differentiating via formulation expertise in complex small-molecule delivery systems rather than biologics capacity.
| Leading Market Players |
|---|
| TriRx Pharmaceutical Services |
| LABIANA Group |
| Charles River Laboratories |
| Lonza |
| Clinvet |
| Argenta |
| Aenova Group |
| Evonik |
| Vetio |
| Others |
Pricing and Supply Chain Analysis
Single-use bioreactor capacity scarcity in the United States and Switzerland compresses contract timelines and elevates pricing power for qualified mammalian cell culture providers. This utilization squeeze forces animal health innovators into longer-term offtake agreements that lock in premium rates while suppliers defer spot-market commitments.
Pricing Analysis
Certification level creates the primary spread across contract tiers, with FDA cGMP-qualified suites commanding substantial premiums over facilities holding only national authorizations. Project-based pricing dominates formulation partnerships, while per-batch transactional structures govern routine analytical and packaging services. Biotech firms developing canine oncology monoclonals prove least price-sensitive, absorbing premium rates for expedited access to single-use infrastructure. Cost compression intensifies in oral solid dosage manufacturing as continuous processing platforms proliferate among mid-tier competitors.
Supply Chain Analysis
Upstream resin and film suppliers in Germany, the United States, and Japan feed bioprocess bag and connector manufacturing for single-use bioreactor trains. Specialty chemical inputs for species-specific formulation work draw from Swiss and Indian API intermediates. Single-source vulnerability concentrates in cell culture media components, where qualification protocols resist supplier switching. Distribution runs through direct manufacturing agreements with consolidated veterinary hospital networks, displacing traditional animal health distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across service tiers and technology platforms creates entry niches for specialists as biologics manufacturing scarcity fragments purchasing power. The migration of monoclonal antibody pipelines from human to companion animal applications splinters demand across multiple qualified providers rather than concentrating with integrated giants.
For Market Incumbents: Entrench mammalian cell culture capacity through multi-year master service agreements that preempt competitor access to biotech venture funding rounds. Lock in sterile fill-finish suite utilization via third-party leasing structures that lower capital barriers for mid-tier challengers. Prioritize backward integration into single-use consumables to buffer resin cost volatility. For New Entrants and Emerging Players: Build out gene therapy manufacturing capabilities targeting AAV vector production for purebred canine inherited diseases, a white space underserved by existing mammalian facilities. India's PLI scheme for veterinary pharmaceuticals offers the most penetrable geographic entry point, with Hyderabad and Ahmedabad emerging as export hubs. Pursue direct dispensing partnerships with consolidated specialty veterinary hospital networks as the primary go-to-market channel. For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained services play because biologics manufacturing scarcity will persist as pipeline migration outpaces facility construction. Target acquisition profiles center on CDMOs with qualified mammalian suites and existing FDA cGMP relationships. Watch USDA Center for Veterinary Biologics antigen production facility approvals as the inflection signal for vaccine-specialist valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mammalian Cell Culture Capacity Expansion | Addresses biologics scarcity as monoclonal antibody pipelines migrate to companion animal oncology. |
| Single-Use Bioreactor Infrastructure Investment | Reduces cross-contamination risk and accelerates batch turnaround for multi-product facilities. |
| USDA Antigen Production Facility Qualification | Unlocks dual-track regulatory access for vaccine developers requiring separate oversight pathways. |
| Continuous Manufacturing Platform Adoption | Compresses quality control timelines through real-time release testing for oral solid dosage forms. |
| Direct Veterinary Hospital Network Partnership | Bypasses distributor fragmentation through serialized unit-dose packaging for in-clinic dispensing. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary regulatory filings anchors the qualitative findings. Conversations with CDMO business development executives, regulatory affairs specialists at animal health innovators, veterinary hospital procurement directors, and single-use consumables suppliers informed demand-side dynamics. Secondary sources include FDA Center for Veterinary Medicine cGMP guidance documents, EMA Veterinary Medicines Regulation submissions, USDA Center for Veterinary Biologics facility inspection records, and trade data from CDSCO and DGFT. Bottom-up capacity utilization estimates triangulate against top-down pipeline value projections.
Calibration against historical contract value disclosures and announced facility investments shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology platform, animal species, and regional regulatory cluster. CAGRs derive from capacity expansion announcements, pipeline migration rates from human to veterinary applications, and pet insurance penetration trajectories. Species-specific pharmacokinetic modeling complexity and facility reconfiguration downtime assumptions feed directly into margin projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by gene therapy specialists or Indian PLI-funded entrants would shift outcomes beyond modeled ranges. Cross-checking against disclosed CDMO contract values and announced facility utilization rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Veterinary Clostridium Vaccine Market
Veterinary
Veterinary Endodontics Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Animal Drug Compounding Market
Veterinary
Swine Respiratory Diseases Treatment Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Global Veterinary Artificial Insemination Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Canine Parvovirus Market
Veterinary
Veterinary Vaccine Adjuvants Market
Veterinary
Veterinary and Animal Healthcare Logistics Market
Veterinary
Mastitis Market
Veterinary
Global Veterinary Hematology Analyzers Market
Veterinary
USA Animal Model Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
United Kingdom Veterinary Healthcare Market