
 Global Prophylactic HIV Drugs Market | 2026-2036
Global Prophylactic HIV Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prophylactic HIV Drugs Market Foresight
India's active pharmaceutical ingredient manufacturing corridor is rewriting regional supply dynamics for tenofovir-based regimens. Gilead Sciences leverages its integrated API-to-finished-dose pipeline to sustain pricing leverage across emerging markets. ViiV Healthcare anchors long-acting injectable development through concentrated R&D spending on cabotegravir formulations. Cipla competes aggressively on generic oral PrEP volumes, extending its reach into public procurement channels across East and Southern Africa.
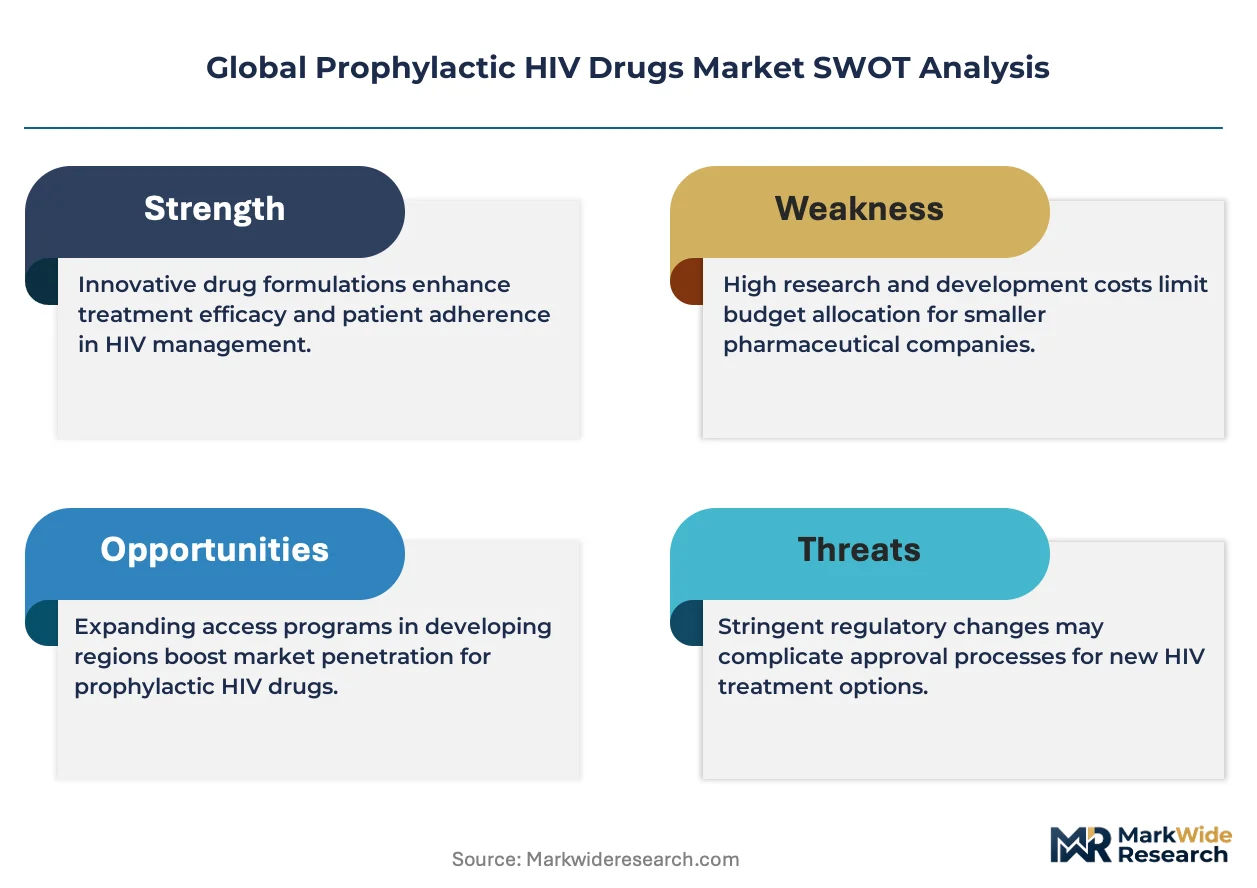
Prophylactic HIV drugs comprise antiretroviral agents administered before or after potential exposure to prevent viral establishment, with tenofovir disoproxil fumarate/emtricitabine representing the benchmark oral combination requiring strict adherence protocols. These therapies function primarily to interrupt mucosal transmission at cellular entry points, serving public health infrastructure and individual risk-reduction strategies. Pre-Exposure Prophylaxis dominates current prescription volumes while long-acting injectable delivery modes capture the fastest expansion trajectory due to adherence advantages over daily oral regimens. Oral Tablets still occupy the largest margin pool through mature generic competition, though Injectable formats command premium positioning in high-income settings.
FDA accelerated approval pathways and EMA conditional marketing authorizations shape product entry timelines for novel prevention modalities, while WHO prequalification standards determine access to low-income country procurement systems. The EU AI Act increasingly governs algorithmic tools used in adherence prediction and risk stratification platforms deployed alongside drug distribution. Stakeholders must monitor evolving national reimbursement decisions for long-acting formulations versus oral generics, as these policy choices will determine portfolio prioritization across geographic markets.
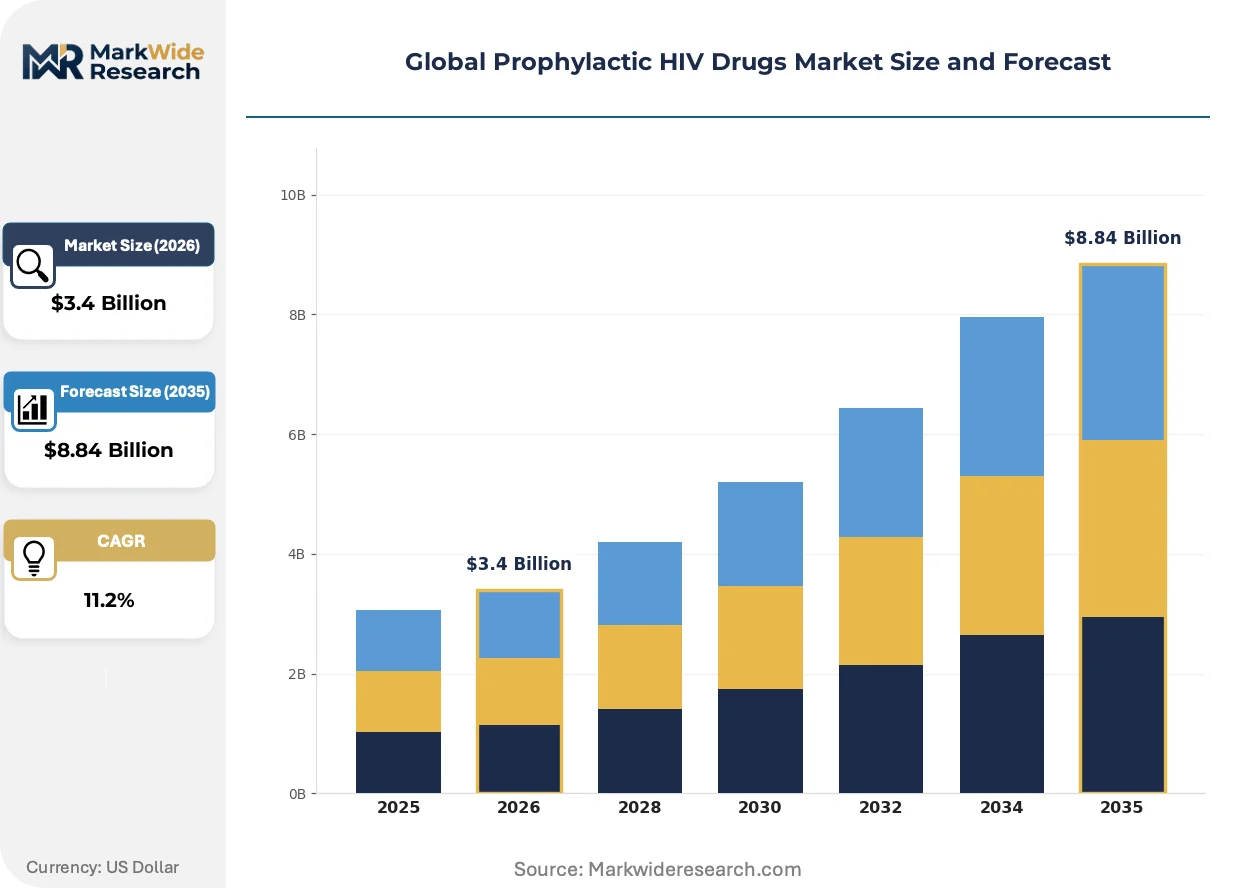
Market Dynamics
Long-acting injectable formulations are compressing the adherence advantage gap between daily oral PrEP and next-generation prevention modalities, forcing portfolio reallocation across multinational pharmaceutical pipelines.
Growth Catalysts
- FDA Accelerated Approval Pathways:Expedited review timelines compress commercialization cycles for novel antiretroviral combinations, enabling faster patient access to breakthrough prevention therapies in the United States.
- Community Health Programs in Sub-Saharan Africa:National prevention initiatives in South Africa, Kenya, and Nigeria drive oral PrEP tablet distribution through decentralized clinic networks and mobile health platforms.
- Tenofovir Alafenamide Substitution:Improved renal and bone safety profiles over tenofovir disoproxil fumarate expand prescriber comfort for long-term prophylaxis in aging patient populations.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for tenofovir-based regimens clusters in Indian manufacturing corridors, creating single-source vulnerability for generic formulation supply.
- Cold Chain Requirements:Long-acting injectable cabotegravir formulations require sustained temperature-controlled distribution infrastructure absent in rural clinic networks across low-income settings.
- Reimbursement Fragmentation:Divergent national formulary decisions between oral generic PrEP and premium injectable alternatives limit patient access consistency across public health systems.
Strategic Opportunities
- Underpenetrated Southeast Asian Markets:Thailand, Vietnam, and Indonesia present expansion corridors where national HIV prevention programs remain in early scaling phases for oral PrEP access.
- Event-Driven Dosing Protocols:On-demand pre-exposure regimens for episodic risk exposure attract pharmaceutical investment as an adherence-flexible alternative to daily tablet burden.
- WHO Prequalification Acceleration:Streamlined quality assessment pathways for generic manufacturers unlock procurement eligibility across Global Fund and PEPFAR distribution channels.
Industry Challenges
- Adherence Monitoring Integration:Digital pill bottles, smartphone applications, and biometric tracking systems require seamless interoperability with existing electronic health record architectures in diverse clinical settings.
- Stigma Mitigation Infrastructure:Community-based distribution models demand trained peer counselor networks capable of navigating disclosure barriers and retention support in marginalized populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prophylactic HIV Drugs Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $8.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Pre-Exposure Prophylaxis, Post-Exposure Prophylaxis, Microbicides, Vaccines Therapy Area: HIV Prevention, Sexual Health, Maternal Health, High-Risk Population Care End User: Healthcare Clinics, Research Institutions, Community Health Programs, NGOs Delivery Mode: Oral Tablets, Topical Gels, Injectable, Implantable Devices |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Inc., Cipla, Bristol-Myers Squibb Company, Johnson & Johnson, AbbVie, Viatris, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prophylactic HIV Drugs Market Shifts & Advancements
Prevention technology trajectories are bifurcating between ultra-long-acting depot formulations and user-controlled on-demand options, with adherence science increasingly driving regulatory and reimbursement prioritization.
Biodegradable implantable antiretroviral depots are collapsing the dosing frequency paradigm from monthly injections toward semi-annual or annual administration intervals. HIV prevention programs in high-burden African nations are piloting these subdermal systems through implementation science partnerships. The technology is collapsing the infrastructure burden of clinic-based medication adherence monitoring by decoupling protection from daily behavioral compliance.
The EU AI Act now governs algorithmic risk stratification tools deployed alongside PrEP eligibility screening and retention prediction platforms. Machine learning models for adherence forecasting face mandatory transparency and bias audit requirements before deployment in European healthcare systems. Pharmaceutical sponsors integrating these digital companions must revalidate their training datasets and documentation practices to maintain market access.
Direct-to-consumer telehealth prescribing for oral PrEP is displacing traditional clinic-based initiation protocols in North American and Western European urban markets. Subscription pharmacy models bundle laboratory monitoring, medication delivery, and virtual consultation into consolidated monthly fees. This channel shift concentrates in metropolitan corridors with established LGBTQ+ health service infrastructure and permissive telemedicine prescribing regulations.
Global Prophylactic HIV Drugs Market Segmentation
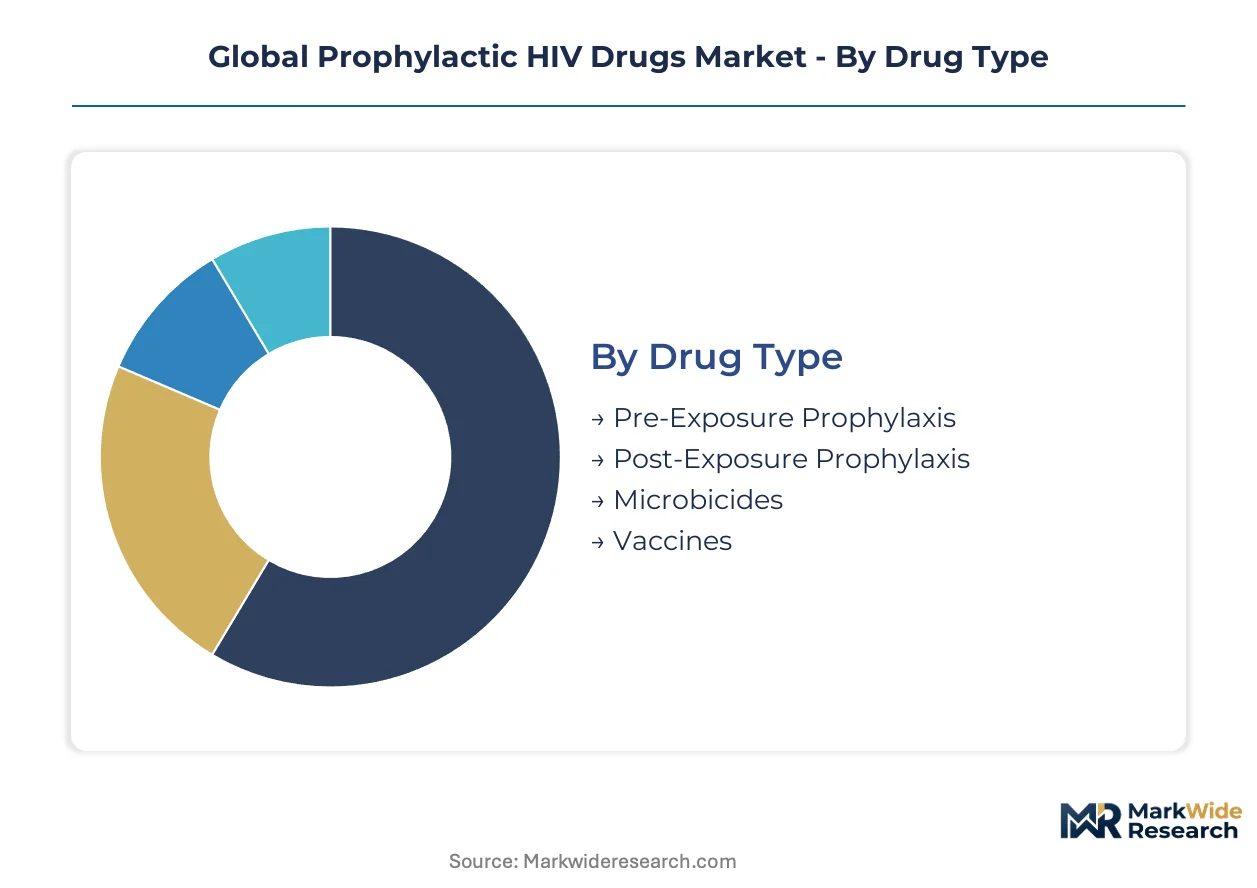
Prophylactic HIV drugs fragment across four critical dimensions that determine pricing power, distribution complexity, and patient adherence requirements. Drug type and delivery mode classifications drive the steepest portfolio reallocation among manufacturers, while therapy area and end-user segmentation shape procurement channel strategy.
Drug Type:
Cost tier positioning varies sharply across prevention modalities, with daily oral regimens anchoring the generic-accessible base and investigational vaccines commanding premium development investment.
- Pre-Exposure Prophylaxis:Daily or event-driven antiretroviral regimens—tenofovir disoproxil fumarate/emtricitabine remains the benchmark—interrupt mucosal transmission before viral establishment. Demand concentrates in South Africa, Kenya, and Nigeria where national programs scale oral tablet distribution through decentralized clinic networks.
- Post-Exposure Prophylaxis:Time-critical 28-day antiretroviral courses initiated within 72 hours of potential exposure, administered through emergency departments and occupational health services. PEP protocols face adherence drop-off after day 14 across healthcare worker populations in high-burden settings.
- Microbicides:Topical antiretroviral gels and rings providing user-controlled protection without systemic drug exposure. Clinical development focuses on tenofovir-containing vaginal rings for women in sub-Saharan Africa with limited partner negotiation capacity.
- Vaccines:Investigational immunization candidates targeting broadly neutralizing antibody induction, currently in Phase II/III efficacy trials. No licensed product exists; pipeline assets attract concentrated R&D investment from public-private partnerships.
Pre-Exposure Prophylaxis commands the established base. The steepest expansion runs through long-acting injectable iterations of antiretroviral prophylaxis.
Therapy Area:
Application focus determines regulatory pathway complexity and reimbursement eligibility across divergent patient risk profiles.
- HIV Prevention:Primary indication encompassing serodiscordant couples, men who have sex with men, transgender women, and people who inject drugs. FDA accelerated approval pathways and WHO prequalification standards shape product entry timelines for novel modalities.
- Sexual Health:Integrated service delivery combining PrEP with STI screening, contraception counseling, and behavioral interventions. Community health programs in sub-Saharan Africa drive adoption through mobile clinic platforms reaching marginalized populations.
- Maternal Health:Periconception and antenatal prophylaxis to prevent vertical transmission and protect serodiscordant couples planning pregnancy. Tenofovir alafenamide substitution improves renal safety profiles for long-term use in aging reproductive-age women.
- High-Risk Population Care:Targeted outreach to sex workers, incarcerated populations, and people who inject drugs requiring trauma-informed service models. Stigma mitigation infrastructure demands trained peer counselor networks capable of navigating disclosure barriers.
HIV Prevention anchors volume concentration. Sexual Health integration services are gaining share fastest as health systems consolidate prevention programming.
End User:
Customer type segmentation fragments procurement authority between public health systems, research sponsors, and community-based implementers with divergent technical requirements.
- Healthcare Clinics:Hospital-based infectious disease departments, primary care networks, and sexual health centers prescribing oral PrEP with laboratory monitoring protocols. Direct-to-consumer telehealth prescribing displaces traditional clinic-based initiation in North American urban markets.
- Research Institutions:Academic medical centers and implementation science partnerships piloting biodegradable implantable depots and adherence prediction algorithms. The EU AI Act governs machine learning models for retention forecasting deployed in European healthcare systems.
- Community Health Programs:Government-funded national prevention initiatives and NGO-led peer distribution models reaching populations avoiding clinical settings. Cold chain requirements for long-acting injectable cabotegravir limit rural clinic network penetration in low-income settings.
- NGOs:International development organizations and community-based organizations procuring generic oral PrEP through Global Fund and PEPFAR channels. Cipla extends reach into public procurement across East and Southern Africa through aggressive generic volume competition.
Healthcare Clinics command the established base. Community Health Programs show the steepest expansion trajectory as decentralization accelerates access in high-burden regions.
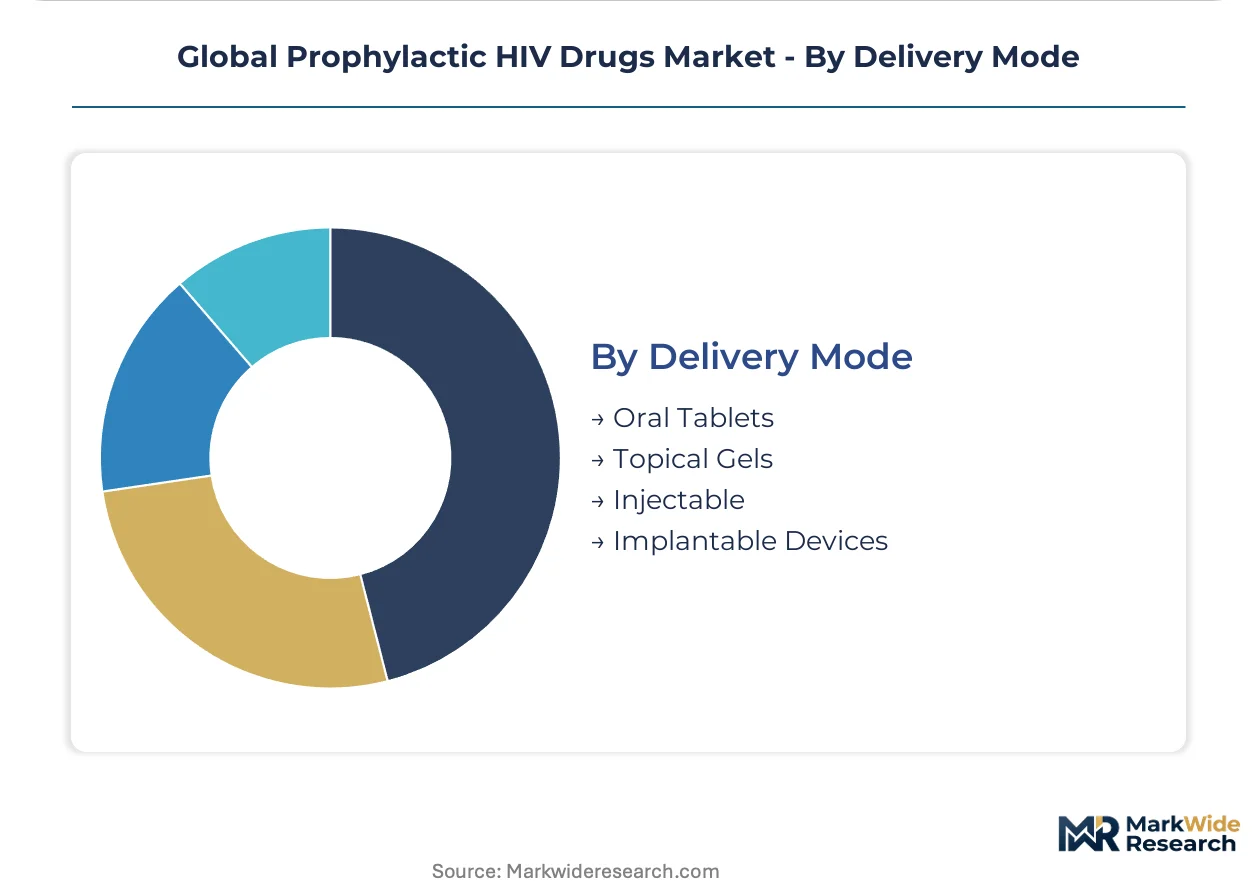
Delivery Mode:
Supply concentration and margin structure diverge dramatically across administration routes, with oral generics facing commoditization pressure while injectable and implantable formats capture premium positioning.
- Oral Tablets:Daily tenofovir-based regimens requiring strict adherence protocols, manufactured through India's active pharmaceutical ingredient corridor. Generic competition concentrates supply vulnerability in single-source API production for tenofovir disoproxil fumarate.
- Injectable:Long-acting cabotegravir formulations administered monthly or bimonthly, developed through ViiV Healthcare's concentrated R&D spending. Premium pricing in high-income settings contrasts with cold chain infrastructure gaps limiting low-income country access.
- Topical Gels:User-controlled vaginal or rectal tenofovir gels providing discreet protection without systemic exposure. Adherence challenges persist due to application timing requirements and acceptability barriers in partner negotiation contexts.
- Implantable Devices:Biodegradable subdermal antiretroviral depots collapsing dosing frequency toward semi-annual or annual intervals. Pilot programs in high-burden African nations test implementation feasibility through partnership with national prevention programs.
Oral Tablets command the established base. Injectable formats are climbing the fastest as adherence advantages reshape prescriber preference in reimbursed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between high-income markets favoring long-acting injectable premiums and low-income regions scaling oral generic volumes through public procurement. South Africa deploys cabotegravir through private channels while Kenya distributes tenofovir-based tablets via community health workers. Thailand pilots event-driven dosing protocols distinct from Brazil's clinic-centered model.
South Africa
National Department of Health programs distribute oral PrEP through 3,500 primary care facilities, with Johannesburg and Cape Town private clinics offering injectable alternatives. The South African Health Products Regulatory Authority streamlined approval for long-acting formulations in 2023. KwaZulu-Natal province operates Africa's largest decentralized prevention network reaching rural corridors.
United States
Commercial payers and Medicaid programs drive prescription volumes for both daily oral and bimonthly injectable regimens, with telehealth platforms displacing traditional clinic initiation in urban centers. FDA accelerated approval pathways compress commercialization timelines for novel antiretroviral combinations. The Boston-Cambridge biotech corridor hosts concentrated implementation science research on adherence prediction algorithms.
Kenya
National AIDS Control Council targets 300,000 oral PrEP users through county health departments and mobile clinic platforms reaching serodiscordant couples and adolescent girls. Pharmacy and Poisons Board registration requirements align with WHO prequalification standards for generic procurement eligibility. Nairobi's Eastleigh district hosts NGO-led peer distribution networks serving key populations outside formal health facilities.
Thailand
Bureau of AIDS, TB and STIs integrates PrEP into sexual health services through 900 government hospitals, with Bangkok's Silom district pioneering event-driven dosing for men who have sex with men. Thai FDA conditional approvals enable faster market entry for tenofovir alafenamide formulations. Chiang Mai province serves as the northern hub for cross-border prevention programming with Myanmar and Laos.
Brazil
Ministry of Health distributes oral tenofovir/emtricitabine through 5,000 public health centers under unified national formulary coverage, with São Paulo and Rio de Janeiro municipalities testing injectable pilot programs. ANVISA streamlined registration for products with WHO prequalification or FDA approval. The São Paulo metropolitan corridor concentrates private pharmacy dispensing for insured populations seeking alternatives to public clinic queues.
Global Prophylactic HIV Drugs Market Competitive Landscape
Capability concentration sits with integrated innovators commanding API-to-finished-dose pipelines; scale advantage sits with generic manufacturers capturing public procurement volumes. The market structures around three tiers: originator developers of novel delivery modes, vertically integrated multinational pharmaceutical firms, and regional generic specialists. Dominant competitive moves include strategic partnerships for cold chain distribution in emerging markets and portfolio diversification into long-acting formulations.
Within the originator tier, Gilead Sciences and ViiV Healthcare exemplify integrated development models spanning molecular innovation through commercial execution. Cipla occupies a distinct position as a scale-driven generic manufacturer with established presence across East and Southern African procurement channels. These three entities represent the archetypal competitive positions shaping portfolio allocation decisions across prevention modalities.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co., Inc. |
| Cipla |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| AbbVie |
| Viatris |
| Roche |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian active pharmaceutical ingredient manufacturing corridors is compressing supplier margins and forcing portfolio reallocation toward differentiated finished-dose formulations. This utilization dynamic simultaneously erodes pricing power for generic oral tenofovir suppliers while reinforcing premium positioning for long-acting injectable developers with captive API pipelines.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between generic manufacturers and Global Fund or PEPFAR distribution channels, insulating volume commitments from spot price volatility. Three-tier pricing structure across premium injectable, standard branded oral, and economy generic levels reflects FDA approval status and WHO prequalification tier. Pricing pressure stems from Indian API overcapacity feeding commoditization of tenofovir disoproxil fumarate tablets. Public health systems in sub-Saharan Africa exhibit highest price sensitivity; private clinics in South Africa and the United States show lowest.
Supply Chain Analysis
Export-control regimes for controlled precursor chemicals under international narcotics conventions limit cross-border flows of certain antiretroviral synthesis intermediates. API production concentrates in India, China, and the United States; finished-dose formulation draws from these hubs plus regional secondary sites. Key dependencies include tenofovir disoproxil fumarate intermediate, emtricitabine base, and cabotegravir long-acting nanosuspension technology. Single-source vulnerability clusters in Indian API corridors for tenofovir derivatives. Distribution runs through temperature-controlled logistics networks with cold chain requirements for injectable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as biodegradable implantable depots threaten to displace both daily oral tablets and monthly injectables with semi-annual administration intervals. Long-acting formulation convergence demands preemptive portfolio positioning.
For Market Incumbents: Pre-empt implantable depot displacement by accelerating R&D partnerships with biodegradable polymer specialists before second-generation entrants capture formulation expertise. Secure backward integration into tenofovir alafenamide API production to defend margin position against Indian generic API price erosion. Cold chain infrastructure investments in East African distribution networks represent critical channel control leverage.
For New Entrants and Emerging Players: Southeast Asian national prevention programs in Vietnam, Indonesia, and the Philippines offer white-space expansion corridors where oral PrEP penetration remains below saturation thresholds. Event-driven dosing protocols for episodic risk exposure present the most penetrable adherence-flexible segment with lower regulatory barriers than novel delivery modes. Telehealth subscription bundling provides viable go-to-market positioning in metropolitan corridors with established LGBTQ+ health infrastructure.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated API-to-finished-dose manufacturers with WHO prequalification eligibility and established Global Fund procurement relationships. Long-term viability across the projection horizon hinges on exposure to long-acting formulation pipelines rather than commoditized oral generic volumes. Acquisition targets should demonstrate cabotegravir formulation capability or biodegradable implant partnerships. Watch FDA accelerated approval decisions for novel prevention modalities as inflection indicators for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Acceleration | Unlocks Global Fund and PEPFAR procurement eligibility for generic manufacturers across African distribution channels. |
| Long-Acting Injectable Manufacturing Scale-Up | Addresses cold chain infrastructure gaps limiting rural clinic penetration in low-income settings. |
| Biodegradable Implant R&D Partnership | Positions developers for semi-annual dosing paradigms collapsing adherence monitoring burdens. |
| Telehealth Platform Integration | Captures direct-to-consumer prescribing displacement in North American and Western European urban markets. |
| API Backward Integration | Defends margin compression from Indian generic overcapacity through captive tenofovir production. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, hospital procurement managers, and community health program implementers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocols, WHO prequalification databases, and national AIDS control council procurement reports. Bottom-up prescription volume modeling triangulated against top-down market sizing across geographic clusters.
Calibration anchored quantitative outputs to historical prescription trajectories and implementation science partnership disclosures without forward-year specificity. Segmentation dimensions spanned drug type, delivery mode, therapy area, and end-user category across the projection horizon. CAGRs derived from regression analysis of adoption curve parameters and reimbursement policy elasticity. Forecast inputs incorporated national prevention program scale-up commitments and regulatory approval pathway timelines.
Macroeconomic conditions sit as an overlay; deviation in currency volatility affecting Indian API export pricing or Global Fund contribution levels would shift the trajectory. Forecasts reflect documented assumptions regarding WHO prequalification throughput and national formulary expansion rates. Material shifts in FDA accelerated approval stringency or EMA conditional marketing authorization criteria would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
US Transdermal Drug Delivery System Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
US Compounding Pharmacies Market
Pharmaceuticals
Sitagliptin Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Human Combination Vaccines Market