
 Europe Transfection Technologies Market | 2026-2036
Europe Transfection Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Transfection Technologies Market Intelligence
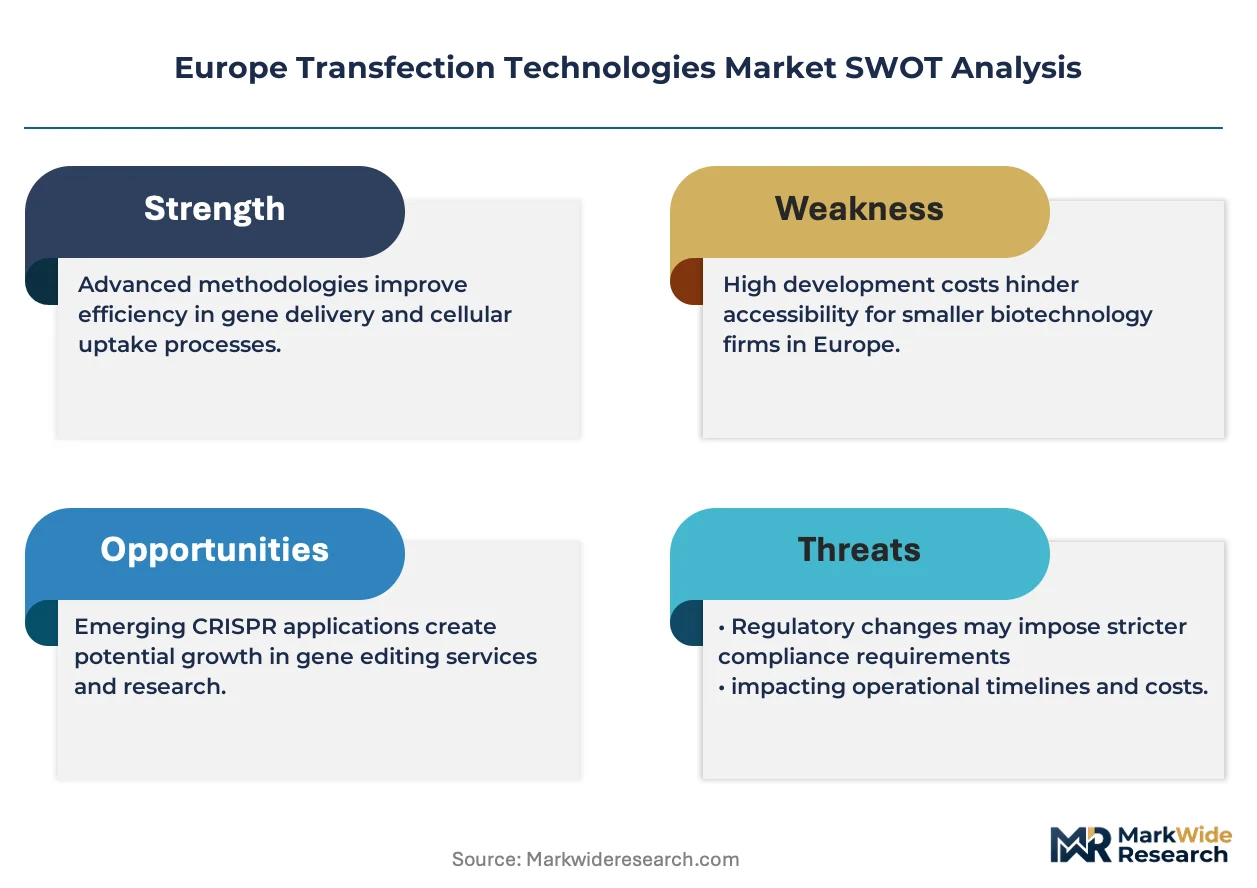
Synthetic lipid formulations is recalibrating cost structures across nucleic acid delivery systems. Lonza Group AG anchors European manufacturing capacity for GMP-grade transfection reagents. Thermo Fisher Scientific Inc. extends its instrumentation portfolio through electroporation system specialization. QIAGEN differentiates via sample-to-insight workflow integration spanning reagent and software layers.
Transfection technologies encompass methods for introducing nucleic acids into eukaryotic cells using chemical carriers, physical force, or viral particles, with lipid nanoparticle formulations typically ranging 50-200 nm in diameter and requiring optimized nitrogen-to-phosphate ratios for complex stability. These systems enable gene silencing, protein expression, and genome editing across therapeutic and research contexts. Reagent and kit segments command recurring revenue streams due to consumable replenishment cycles, while electroporation instrumentation captures premium pricing through programmable pulse parameters. Viral vector delivery retains dominance in clinical-stage gene therapy applications despite higher biosafety classification requirements.
The EMA governs advanced therapy medicinal product approvals, while the EU Clinical Trials Regulation streamlines cross-border investigator-initiated studies, and REACH mandates chemical safety documentation for synthetic carrier compounds. These frameworks elevate validation burdens for new market entrants while reinforcing incumbent quality systems. Stakeholders must evaluate manufacturing scale-up pathways against evolving GMP annex guidance for genetically modified organism handling.
Market Dynamics
Synthetic lipid nanoparticle formulations are compressing manufacturing timelines across nucleic acid delivery workflows, forcing established reagent suppliers to reconfigure production architectures around scalable GMP-grade output.
Growth Catalysts
- EU Clinical Trials Regulation:Harmonized multi-national protocols accelerate investigator-initiated gene therapy studies across Germany, France, and the Netherlands. Cross-border patient recruitment pools expand addressable trial populations.
- Rhine-Main biotech corridor:Pharmaceutical concentration in Frankfurt's surrounding cluster generates concentrated demand for high-throughput transfection instrumentation and consumable reagent streams.
- Electroporation parameter programming:Precision pulse control enables fine-tuned delivery into primary cells and organoids, opening previously refractory cell types to genetic modification.
Market Restraints
- Specialized lipid input concentration:Ionizable lipid manufacturing concentrates among a handful of European chemical suppliers, creating vulnerability to batch variability and qualified source constraints.
- REACH documentation burdens:Novel synthetic carrier compounds require extensive chemical safety dossiers before commercial distribution, extending time-to-market for formulation innovations.
- Viral vector biosafety classification:Higher containment requirements for lentiviral and adenoviral delivery systems elevate facility capital costs and operational complexity relative to non-viral alternatives.
Strategic Opportunities
- Central and Eastern Europe expansion:Poland and Czech Republic biotech incubators remain undersupplied with GMP-grade transfection reagents, presenting first-mover positioning for compliant suppliers.
- EMA advanced therapy medicinal product pathway:Streamlined ATMP approval frameworks incentivize sponsors to advance gene-edited cell therapies, expanding demand for clinical-grade delivery systems.
- CRISPR-electroporation convergence:Ribonucleoprotein complex delivery via optimized electrical pulsing is displacing viral approaches in ex vivo cell engineering workflows.
Industry Challenges
- GMP annex compliance timelines:Genetically modified organism handling requirements under evolving European guidance demand facility revalidation cycles that compress operational windows.
- Complex formulation workforce scarcity:Lipid nanoparticle characterization and stability testing require specialized analytical chemists whose training pipelines lag market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Transfection Technologies Market |
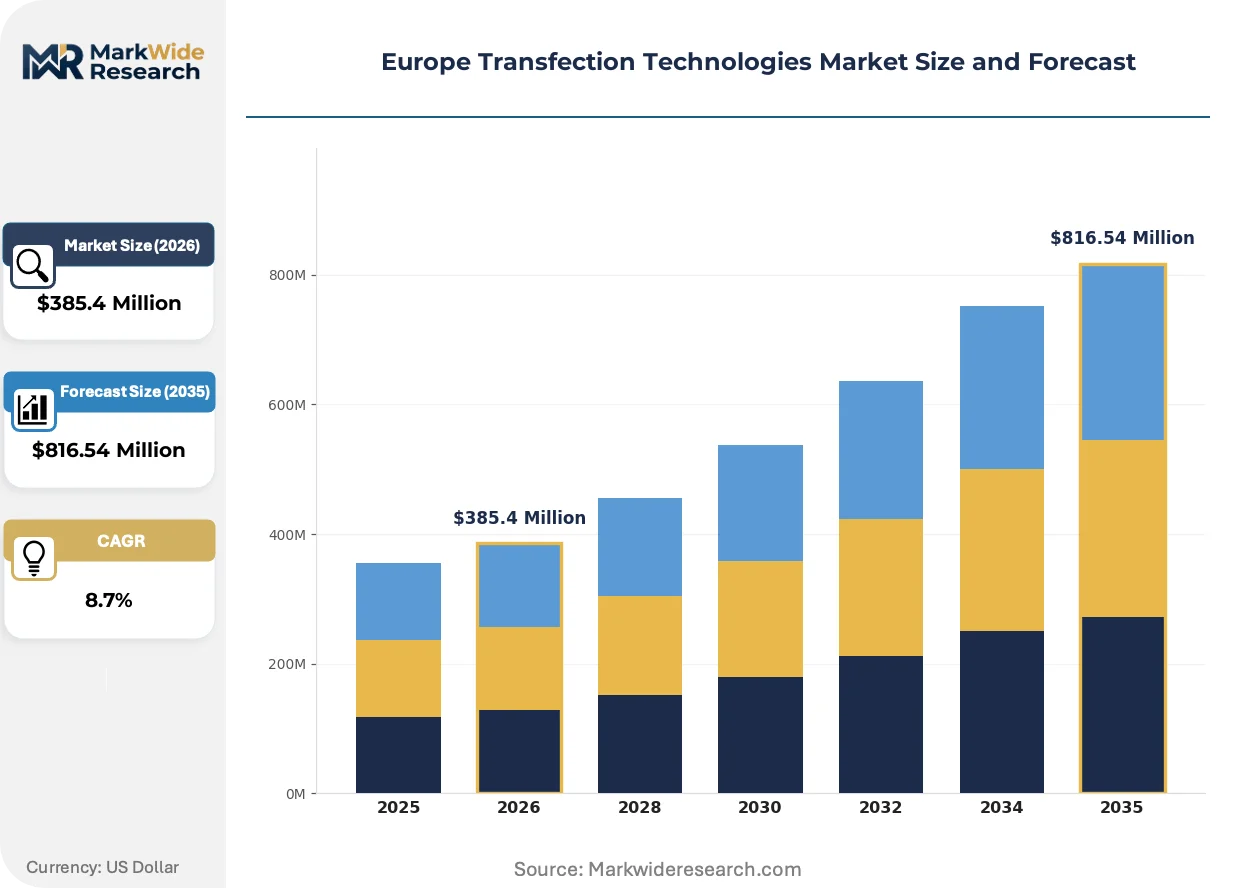
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Instruments, Software Delivery Method: Microinjection, Electroporation, Viral Vectors, Lipofection End User: Academic Institutions, Pharmaceutical Companies, Biotech Firms, Contract Research Organizations Application: Gene Therapy, Vaccine Development, Protein Production, Stem Cell Research |
| Companies Covered | Lonza Group AG, Bio-Rad Laboratories Inc., Thermo Fisher Scientific Inc., QIAGEN, Merck KGaA, Polyplus-transfection SA, Promega Corporation, MaxCyte Inc., Roche Holding AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Transfection Technologies Market Strategic Shifts & Innovations
Microfluidic manufacturing integration is compressing lipid nanoparticle polydispersity while enabling continuous production modes that challenge batch-reactor economics across European contract manufacturing organizations.
Microfluidic mixing architectures are converging with precision flow chemistry to achieve sub-100 nm lipid nanoparticle populations with tight size distributions. Dutch and German CDMOs are retrofitting legacy batch vessels with continuous processing skids to secure ATMP supply contracts. This convergence is compressing unit economics for clinical-grade material while elevating quality system requirements for process analytical technology deployment.
EMA guidance on quality and non-clinical aspects of ATMPs is tightening specifications for replication-competent virus detection in viral vector preparations. Sponsors must now implement next-generation sequencing-based adventitious agent testing earlier in development cycles. German gene therapy developers are responding by integrating in-house analytical capabilities rather than relying solely on external reference laboratories.
Consolidated procurement through centralized biobank and core facility networks is displacing individual laboratory reagent purchasing across European academic medical centers. France's national infrastructure for translational research coordinates bulk purchasing agreements that extract volume discounts from suppliers. This channel concentration is most visible in Paris-Saclay and Lyon health clusters, where shared electroporation instrumentation pools reduce per-laboratory capital burdens.
Europe Transfection Technologies Market Segmentation
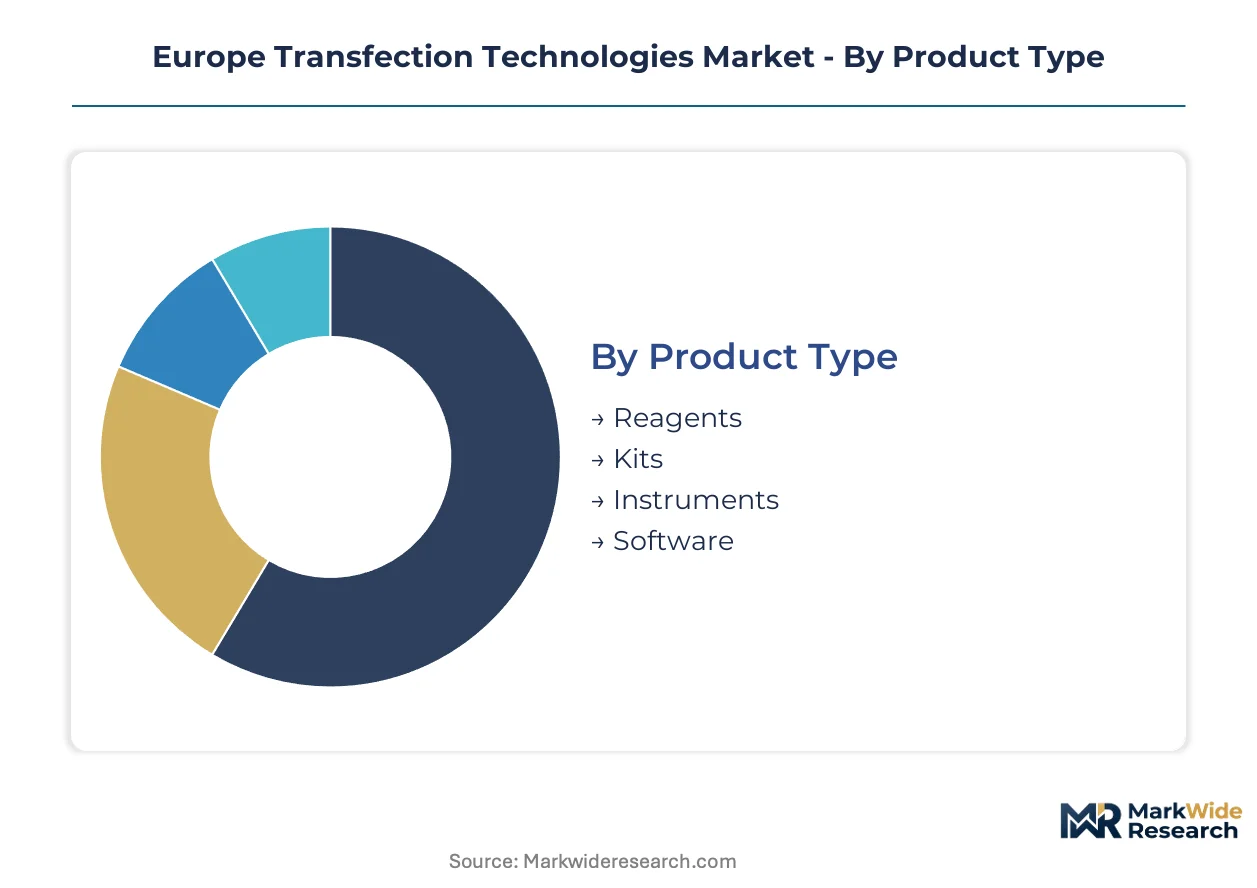
Segmentation in the Europe Transfection Technologies Market reveals distinct procurement patterns across product formats, delivery modalities, and institutional buyer types. Chemical reagent streams generate recurring revenue through replenishment cycles, while physical delivery systems capture capital expenditure budgets with longer replacement horizons.
Product Type:
Buyers in this category differentiate primarily by experimental throughput requirements and regulatory compliance obligations rather than absolute price sensitivity.
- Reagents:Lipid and polymer-based formulations dominate consumable procurement across European academic core facilities. German pharmaceutical manufacturers in the Rhine-Main corridor maintain qualified supplier agreements for GMP-grade ionizable lipids to support gene therapy pipelines.
- Kits:Pre-optimized plasmid-carrier combinations reduce protocol development time for multi-site clinical trials under the EU Clinical Trials Regulation. French biotech incubators around Paris-Saclay leverage standardized kit formats to accelerate investigator-initiated study timelines.
- Instruments:Electroporation systems with programmable pulse parameters command premium positioning for primary cell and organoid applications.
- Software:Protocol optimization platforms integrate with liquid handling robotics to enable high-throughput screening workflows.
Reagents lead volumes today; kits are gaining share fastest through centralized biobank procurement consolidation.
Delivery Method:
Selection here hinges on cell type permissiveness and biosafety infrastructure availability, with viral approaches requiring elevated containment capital.
- Lipofection:Cationic lipid formulations achieve 80-90% transfection efficiency in adherent cell lines with minimal cytotoxicity. Dutch CDMOs deploy microfluidic-manufactured lipid nanoparticles for clinical-grade mRNA vaccine production under EMA quality guidance.
- Electroporation:Precision electrical pulsing enables direct ribonucleoprotein delivery into CRISPR-editing workflows without viral packaging. German gene therapy developers in Heidelberg and Munich favor electroporation for ex vivo T-cell engineering to bypass lentiviral biosafety classification requirements.
- Viral Vectors:Lentiviral and adeno-associated virus systems retain dominance in in vivo gene therapy despite higher facility capital burdens.
- Microinjection:Single-cell precision delivery supports transgenic animal model generation and embryonic stem cell manipulation.
Viral vectors lead volumes today; electroporation is expanding most quickly through CRISPR-electroporation convergence in cell therapy manufacturing.
End User:
Procurement authority and volume scale separate institutional buyers, with pharmaceutical companies consolidating vendor relationships through enterprise agreements.
- Pharmaceutical Companies:Sanofi and Roche anchor European demand for scalable GMP-grade transfection systems to support commercial gene therapy manufacturing. These organizations negotiate multi-year supply agreements with qualified reagent manufacturers to secure batch-to-batch consistency for ATMP submissions.
- Academic Institutions:Shared core facility models across France's national translational research infrastructure extract volume discounts from suppliers. Paris-Saclay and Lyon health clusters coordinate centralized electroporation instrumentation pools to reduce per-laboratory capital burdens.
- Biotech Firms:Emerging developers in Poland and Czech Republic incubators seek flexible reagent sourcing without minimum order constraints.
- Contract Research Organizations:Multi-site service providers standardize on transfection platforms that transfer seamlessly between preclinical and clinical manufacturing scales.
Pharmaceutical companies lead volumes today; biotech firms are climbing the fastest through Central and Eastern Europe expansion.
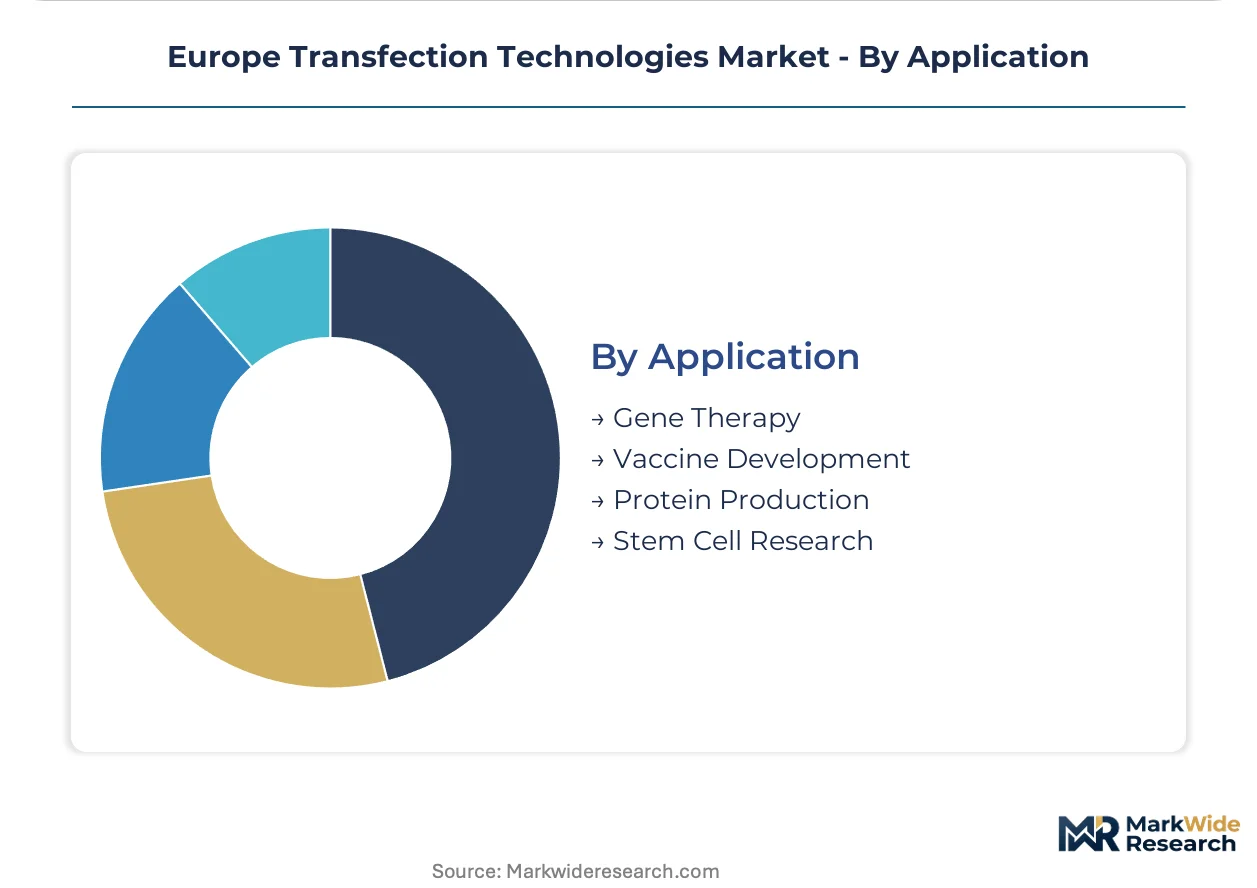
Application:
Regulatory pathway maturity and reimbursement certainty drive allocation decisions, with gene therapy commanding disproportionate R&D investment relative to current revenue contribution.
- Gene Therapy:EMA advanced therapy medicinal product approvals for CAR-T and gene-edited therapies expand demand for clinical-grade delivery validation. German developers integrate in-house next-generation sequencing-based adventitious agent testing to meet tightening replication-competent virus detection specifications.
- Vaccine Development:mRNA lipid nanoparticle manufacturing expertise established during recent pandemic response now pivots toward personalized neoantigen vaccines. Belgian and Dutch CDMOs retrofit legacy batch vessels with continuous processing skids to secure ATMP supply contracts.
- Protein Production:Transient expression systems in CHO and HEK293 cells support rapid biologic candidate generation for early-stage pharmacokinetic studies.
- Stem Cell Research:Non-viral delivery into induced pluripotent stem cells enables footprint-free genetic modification for disease modeling applications.
Protein production leads volumes today; gene therapy shows the steepest expansion trajectory through streamlined ATMP approval frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main biotech corridor anchors European transfection technology demand through concentrated pharmaceutical manufacturing and gene therapy development activity.
Germany
Sanofi and Roche maintain multi-year supply agreements for GMP-grade reagents to support commercial ATMP manufacturing. The Paul-Ehrlich-Institut oversees advanced therapy medicinal product approvals under harmonized EU frameworks. Heidelberg and Munich clusters favor electroporation systems for ex vivo T-cell engineering to bypass lentiviral biosafety requirements.
France
Paris-Saclay and Lyon health clusters coordinate centralized biobank procurement that extracts volume discounts from reagent suppliers. ANSM enforces chemical safety documentation under REACH mandates for novel synthetic carrier compounds. The national translational research infrastructure consolidates electroporation instrumentation pools across academic medical centers.
Netherlands
Dutch CDMOs deploy microfluidic-manufactured lipid nanoparticles for clinical-grade mRNA production under EMA quality guidance. The Dutch Medicines Evaluation Board aligns with centralized EU procedures for gene therapy approvals. Belgian and Dutch facilities retrofit batch vessels with continuous processing skids to secure ATMP manufacturing contracts.
Switzerland
Swissmedic maintains stringent quality specifications for replication-competent virus detection in viral vector preparations. Basel-based pharmaceutical operations anchor demand for scalable transfection systems in protein production workflows. The country's precision manufacturing heritage supports specialized analytical chemistry workforce development for lipid nanoparticle characterization.
Poland
Biotech incubators in Warsaw and Krakow seek flexible reagent sourcing without minimum order constraints as gene therapy pipelines expand. The national pharmaceutical regulator implements EU Clinical Trials Regulation protocols for cross-border investigator-initiated studies. Central and Eastern European expansion presents first-mover positioning for GMP-grade transfection suppliers.
Europe Transfection Technologies Market Key Industry Players
Global majors compete with regional champions across manufacturing scale and regulatory compliance capabilities. The vendor base separates into three tiers: diversified life science conglomerates with full workflow integration, specialized reagent manufacturers with GMP-grade certification, and electroporation instrumentation developers with programmable pulse technology. Strategic moves concentrate on capacity expansion for clinical-grade lipid nanoparticle output and technology licensing for CRISPR-electroporation convergence.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA occupy positions spanning reagent, instrumentation, and software layers. Lonza Group AG exemplifies the specialized manufacturing archetype with European GMP-grade production anchoring. QIAGEN represents workflow integration specialists connecting sample preparation through analytical interpretation. These three company structures illustrate the competitive positioning spectrum without exhaustively mapping the field.
| Leading Market Players |
|---|
| Lonza Group AG |
| Bio-Rad Laboratories Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Merck KGaA |
| Polyplus-transfection SA |
| Promega Corporation |
| MaxCyte Inc. |
| Roche Holding AG |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up contract manufacturing organizations across the Netherlands and Belgium have consolidated lipid nanoparticle production capacity, tightening supply discipline while extracting volume premiums from pharmaceutical buyers locked into multi-year ATMP supply agreements. This ownership concentration feeds directly into pricing power for GMP-grade ionizable lipids, where qualified supplier status under EMA guidance creates switching costs that insulate incumbent margins from spot-market volatility.
Pricing Analysis
Input-cost pass-through from specialized ionizable lipid manufacturing dominates pricing dynamics, with nitrogen-to-phosphate ratio optimization and microfluidic production scale-up driving cost differentials between clinical-grade and research-use formulations. Pricing stratifies across GMP-certified premium tiers, ISO-compliant standard grades, and economy research-use reagents based on batch documentation depth and regulatory filing support. Cost compression in the research-use tier intensifies as Chinese suppliers expand direct distribution into European academic core facilities. Biotech incubators in Poland and Czech Republic exhibit highest price sensitivity due to minimum order constraints, while Sanofi and Roche anchor the least sensitive segment through enterprise procurement agreements that prioritize batch consistency over unit cost.
Supply Chain Analysis
Ionizable lipid supply rests on German and Dutch specialty chemical producers, with downstream formulation capacity concentrating in Belgian CDMOs retrofitting legacy batch vessels with continuous processing skids. Critical inputs span synthetic cholesterol from Swiss manufacturers, polyethylene glycol derivatives from German suppliers, and ionizable amino-lipid precursors requiring REACH-compliant safety documentation. Single-source vulnerability permeates the qualified supplier tier where EMA filing cross-references lock sponsors into specific lipid lots. Distribution runs through centralized biobank networks across France's national translational research infrastructure, displacing individual laboratory purchasing and extracting volume discounts that compress supplier margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European transfection technologies hinges on microfluidic manufacturing scale-up, where continuous processing skids deliver 40-60% unit cost reduction against batch reactors while qualifying suppliers for premium ATMP contract pricing.
For Market Incumbents: Extend GMP-grade capacity in the Rhine-Main corridor to capture Roche and Sanofi multi-year supply agreement renewals, while integrating in-house analytical capabilities for next-generation sequencing-based adventitious agent testing to meet tightening EMA replication-competent virus detection specifications. CRISPR-electroporation convergence threatens viral vector incumbents; priority investment in programmable pulse parameter platforms secures positioning in ex vivo T-cell engineering workflows displacing lentiviral approaches. For New Entrants and Emerging Players: Launch via flexible reagent sourcing models targeting Polish and Czech Republic biotech incubators, where minimum order constraints exclude established suppliers and first-mover positioning in GMP-grade qualification opens ATMP pipeline partnerships. Central and Eastern European expansion represents the most penetrable geography; gene therapy developers in Warsaw and Krakow seek compliant suppliers without legacy pharmaceutical enterprise procurement rigidities. Direct distribution partnerships with national translational research infrastructures bypass channel concentration risks. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with gene therapy manufacturing gaps are the most active acquirer in this space, seeking electroporation instrumentation developers with programmable pulse technology and lipid nanoparticle formulation specialists with EMA-qualified status. Long-term viability centers on CRISPR-electroporation convergence displacing viral vectors across ex vivo cell engineering. Acquisition target archetype: mid-cap CDMOs with microfluidic manufacturing integration and existing ATMP supply contracts. Watch CRISPR therapeutic approval velocity as inflection indicator for ribonucleoprotein delivery system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Manufacturing Integration | Dutch and Belgian CDMOs retrofit batch vessels to secure EMA ATMP supply contracts with compressed unit economics. |
| GMP-Grade Capacity Expansion | Rhine-Main corridor investments capture Roche and Sanofi multi-year reagent supply agreement renewals. |
| CRISPR-Electroporation Convergence | German Heidelberg and Munich clusters favor programmable pulse systems to bypass lentiviral biosafety requirements. |
| Central and Eastern European Distribution | Polish and Czech biotech incubators seek flexible sourcing without minimum order constraints from incumbent suppliers. |
| In-House Analytical Capability Integration | German gene therapy developers deploy next-generation sequencing to meet tightening EMA replication-competent virus detection specifications. |
Research Approach
Bottom-up gene therapy pipeline modeling reconciled against top-down lipid nanoparticle manufacturing capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at EMA national competent authorities, GMP facility managers at Dutch and Belgian CDMOs, procurement directors at Sanofi and Roche, and core facility coordinators across France's Paris-Saclay and Lyon health clusters combined with secondary validation against EMA ATMP submission databases, REACH chemical safety dossiers, ClinicalTrials.gov gene therapy protocol registrations, and European customs trade data for ionizable lipid imports.
Input-output matrices connect transfection reagent production volumes to downstream ATMP manufacturing demand across pharmaceutical, biotech, and academic end-use segments over the projection horizon. Segmentation dimensions span product type, delivery method, end-user institutional category, and application area, with CAGRs derived from regression analysis against gene therapy clinical trial advancement rates and electroporation system installation trajectories in European academic medical centers. Forecast inputs incorporate EMA approval pathway timelines and EU Clinical Trials Regulation harmonization impacts on cross-border patient recruitment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH documentation burden intensification or ionizable lipid supplier consolidation. Projections reflect assumptions on microfluidic manufacturing adoption velocity and CRISPR-electroporation displacement rates in cell therapy workflows. Regulatory guidance evolution on genetically modified organism handling requirements and qualified supplier qualification timelines warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market