
 United States Transfection Technologies Market | 2026-2036
United States Transfection Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
United States Transfection Technologies Market Intelligence
Platform licensing revenue is rewriting margin distribution across the transfection value chain. Thermo Fisher Scientific extends its reach through integrated reagent-instrument bundles that lock in recurring consumable spend. Lonza Group anchors high-value cell therapy manufacturing partnerships with proprietary nucleofection workflows. Promega Corporation competes in the research-use segment with flexible chemical transfection kits optimized for academic budgets.
Transfection technologies encompass methods for introducing nucleic acids into eukaryotic cells through chemical, physical, or viral-mediated mechanisms, with electroporation applying controlled electrical pulses at 100-300V to transiently permeabilize lipid bilayers for macromolecule entry. These platforms serve as indispensable tools for gene expression studies, therapeutic protein production, and clinical-grade vector manufacturing under current Good Manufacturing Practice conditions. Lipofection reagents retain the largest installed base among product types due to their operational simplicity and broad cell line compatibility, though electroporation systems are capturing accelerated capital investment as gene therapy pipelines mature. Among end users, pharmaceutical firms command the highest per-site spending on validated transfection platforms, while contract research organizations are expanding capacity fastest to support outsourced cell therapy process development.
FDA oversight of cell and gene therapy products under 21 CFR Part 1271 and evolving guidance on human gene editing applications are elevating the bar for transfection platform validation, traceability, and documentation. The National Institutes of Health's recombinant DNA advisory committee framework and overlapping USDA-APHIS regulations for veterinary biologics further complicate multi-jurisdictional product development pathways. Stakeholders must weigh the pace of FDA's emerging guidance on in vivo delivery systems against their own platform standardization timelines to avoid stranded capital in non-compliant instrumentation.
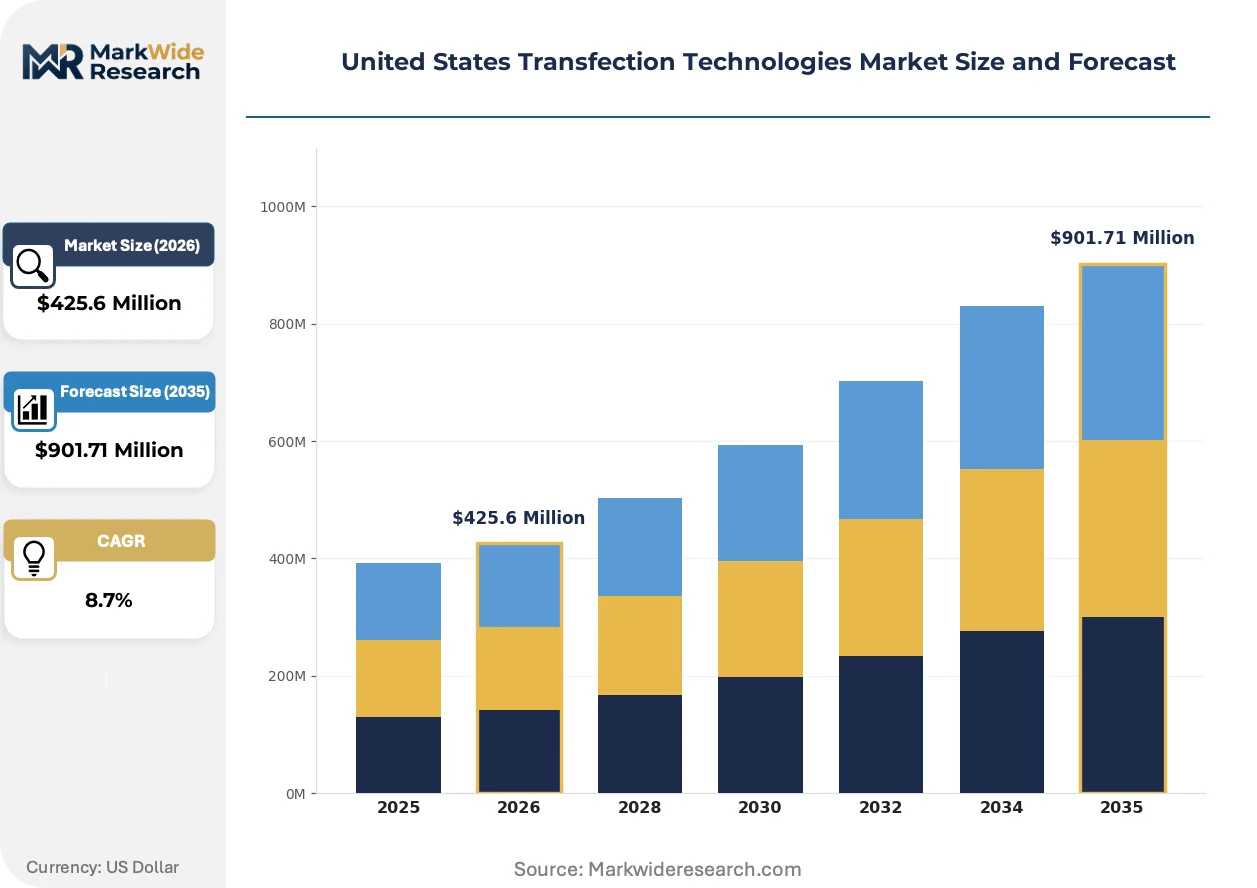
Market Dynamics
Electroporation systems are capturing capital investment from gene therapy developers as FDA validation requirements tighten for clinical-grade vector manufacturing platforms.
Growth Catalysts
- 21 CFR Part 1271:FDA oversight of cell and gene therapy products elevates demand for validated, traceable transfection platforms with compliant documentation workflows.
- Massachusetts biotech cluster:Gene therapy developers in Boston's corridor expand electroporation uptake for clinical-scale plasmid delivery and CAR-T manufacturing.
- CRISPR-mediated editing:Precise gene editing applications require high-efficiency physical delivery methods, pulling investment toward advanced electroporation instrumentation.
Market Restraints
- Platinum electrode supply:Electroporation cuvette manufacturing depends on concentrated precious metal sourcing, creating input cost volatility for consumable producers.
- Reagent kit standardization:Lipofection chemistry lacks cross-platform interoperability, locking research users into single-vendor ecosystems and limiting switching flexibility.
- USDA-APHIS overlap:Veterinary biologics development faces dual jurisdiction with FDA, complicating transfection platform qualification for agricultural gene therapy applications.
Strategic Opportunities
- California cell therapy manufacturing:San Diego and San Francisco biotech hubs underutilize automated electroporation for allogeneic cell line engineering, presenting whitespace for platform deployment.
- NIH recombinant DNA advisory framework:Evolving institutional biosafety guidelines create compliance service opportunities around transfection protocol documentation and training.
- Microfluidic-electroporation convergence:Integration of continuous flow processing with pulsed electrical delivery enables scalable ex vivo cell engineering for commercial manufacturing.
Industry Challenges
- GMP-grade nucleic acid supply:Qualified plasmid DNA sourcing creates bottlenecks for cell therapy developers scaling transfection workflows under current Good Manufacturing Practice conditions.
- Platform validation timelines:FDA's emerging guidance on in vivo delivery systems forces developers to freeze instrumentation selections before final regulatory clarity, risking stranded capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Transfection Technologies Market |
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $901.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lipofection, Electroporation, Viral Vectors, Microinjection End User: Academic Research, Biotechnology Companies, Pharmaceutical Firms, Contract Research Organizations Application: Gene Therapy, Vaccine Development, Stem Cell Research, Protein Production Technology: Nucleofection, Chemical Methods, Physical Methods, Acoustofluidic Techniques |
| Companies Covered | Lonza Group, Promega Corporation, Thermo Fisher Scientific Inc., OriGene Technologies, Inc., MaxCyte, Bio-Rad Laboratories, Inc., Merck KGaA, Altogen Biosystems, QIAGEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Transfection Technologies Market Strategic Shifts & Innovations
Physical delivery methods are displacing chemical reagents in high-value therapeutic applications as manufacturing scale and regulatory stringency reshape platform selection criteria.
Electroporation is migrating from research-scale batch processing toward closed-system continuous flow architectures purpose-built for cell therapy manufacturing. Gene therapy developers in California and Massachusetts adopt these platforms at accelerating pace for clinical-grade vector production. This migration is compressing the addressable market for legacy chemical transfection kits in commercial manufacturing settings while expanding service revenue attached to instrument validation and workflow optimization.
FDA guidance on human gene editing applications under 21 CFR Part 1271 tightens documentation requirements for delivery platform traceability and lot release testing. Cell therapy sponsors must now demonstrate electroporation parameter reproducibility across manufacturing sites, elevating demand for instrument qualification services. Northeast corridor developers respond by embedding platform validation earlier in clinical development timelines to avoid regulatory submission delays.
Academic laboratories and small biotechs unbundle instrument purchases from consumable supply agreements, pressuring vendors toward flexible procurement models. Contract research organizations capitalize on this shift by offering transfection-as-a-service, capturing demand from developers avoiding capital commitment. This pattern concentrates most visibly in Boston's Kendall Square cluster, where shared manufacturing infrastructure reduces individual platform ownership requirements.
United States Transfection Technologies Market Segmentation
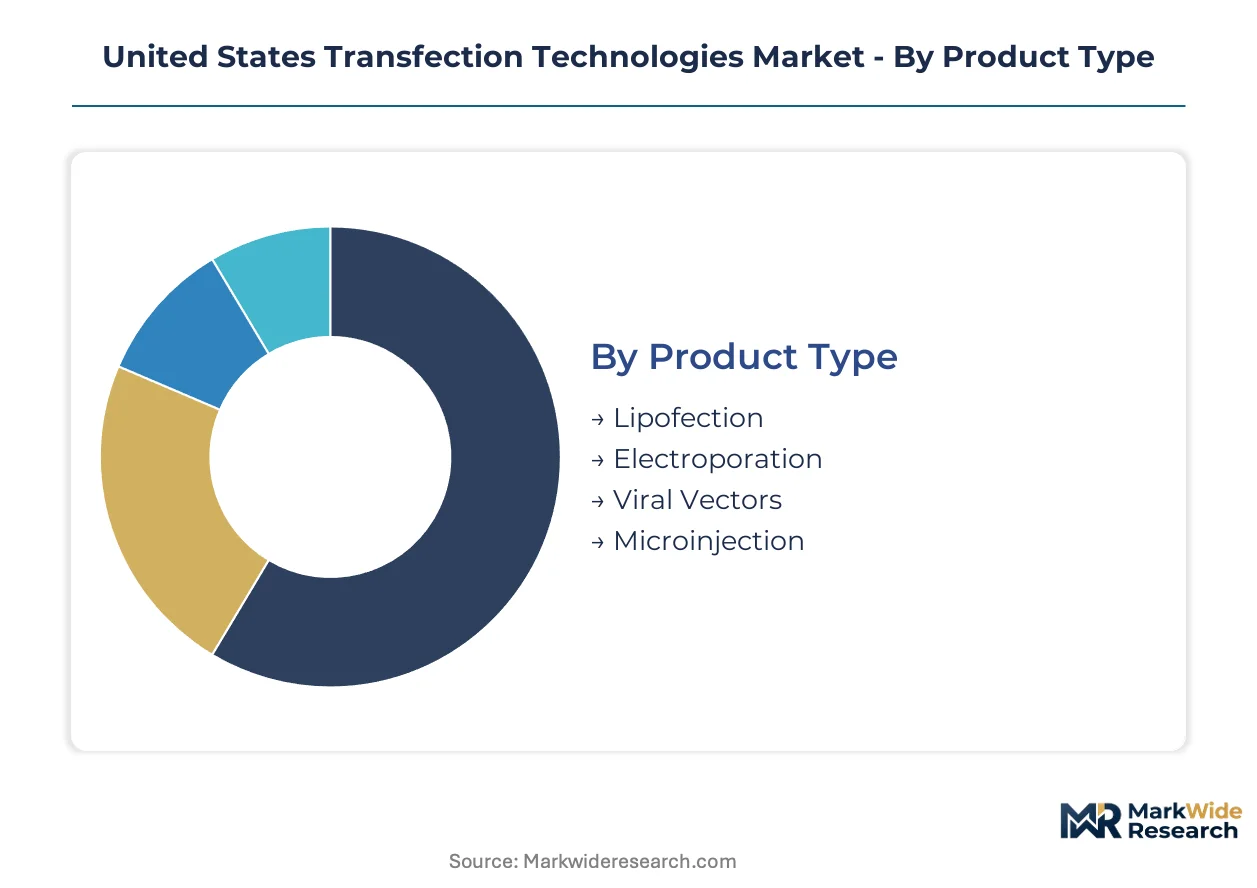
Platform selection in the United States transfection technologies market hinges on regulatory compliance thresholds, manufacturing scale requirements, and cell type compatibility constraints. Segmentation reveals how capital allocation concentrates across mature chemical methods versus emerging physical delivery systems as gene therapy pipelines advance toward commercial validation.
Product Type:
Mature lipofection chemistries dominate installed base metrics while electroporation systems command accelerating capital deployment across clinical manufacturing settings.
- Lipofection:Cationic lipid formulations complex nucleic acids into liposomes that fuse with plasma membranes through endocytosis. Massachusetts biotech clusters favor these reagents for early-stage discovery workflows where operational simplicity outweighs efficiency optimization.
- Electroporation:Controlled electrical pulses at 100-300V transiently permeabilize lipid bilayers for macromolecule entry. California gene therapy developers in San Diego and San Francisco corridors are expanding automated electroporation capacity for allogeneic cell line engineering under FDA 21 CFR Part 1271 guidance.
- Viral Vectors:Adeno-associated and lentiviral delivery systems integrate genetic cargo through receptor-mediated entry mechanisms.
- Microinjection:Direct cytoplasmic or nuclear puncture using fine glass capillaries enables precise delivery into individual cells.
Lipofection handles the majority of throughput; electroporation is gaining share fastest as manufacturing scales tighten.
End User:
Customer type segmentation tracks procurement authority from decentralized academic purchasing through centralized pharmaceutical platform validation.
- Academic Research:University laboratories prioritize flexible chemical transfection kits optimized for budget constraints and broad cell line compatibility. NIH recombinant DNA advisory framework compliance shapes protocol documentation requirements across Boston's Kendall Square cluster institutions.
- Pharmaceutical Firms:Large developers command highest per-site spending on validated transfection platforms with traceable lot release testing. FDA oversight of cell and gene therapy products elevates demand for instrument qualification services and compliant documentation workflows.
- Biotechnology Companies:Venture-backed developers balance platform standardization against emerging regulatory guidance to avoid stranded capital.
- Contract Research Organizations:CROs are expanding transfection capacity fastest to capture outsourced cell therapy process development from developers avoiding capital commitment.
Pharmaceutical firms anchor revenue concentration; contract research organizations are expanding most quickly on capacity metrics.
Application:
Application segmentation reflects therapeutic modality maturity from established protein production through emerging in vivo gene editing.
- Gene Therapy:Viral and non-viral delivery of therapeutic nucleic acids for inherited disease intervention. Massachusetts developers embed electroporation validation earlier in clinical timelines to preempt FDA submission delays.
- Vaccine Development:DNA and mRNA transfection for antigen expression in immunization protocols. Physical delivery methods displace chemical reagents as manufacturing stringency reshapes platform selection for clinical-grade vector production.
- Stem Cell Research:Pluripotent and somatic cell modification for differentiation studies and regenerative applications.
- Protein Production:Transient expression systems for recombinant biologic manufacturing and research-grade material supply.
Gene therapy commands the steepest investment trajectory; protein production retains the broadest installed base.
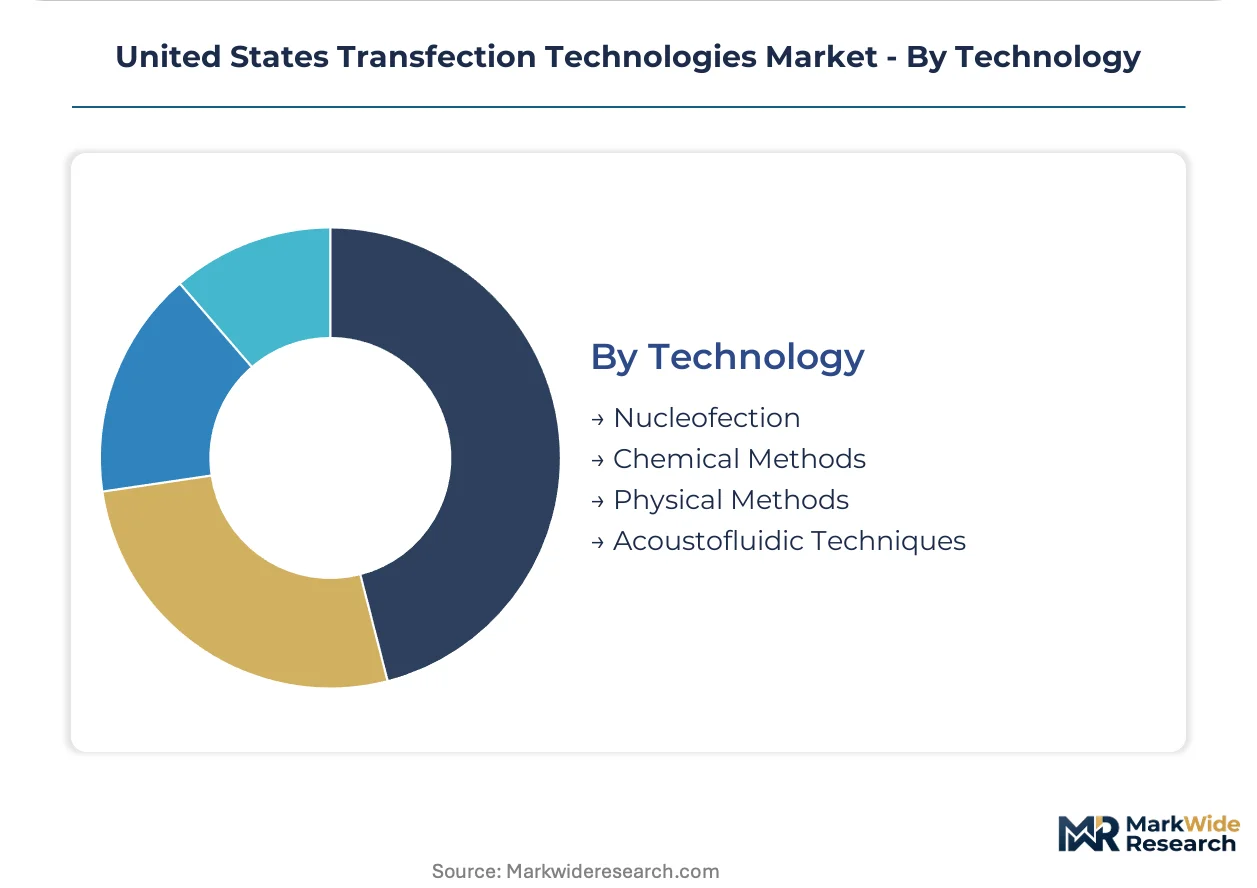
Technology:
Technology segmentation distinguishes proprietary electroporation variants from legacy chemical approaches and emerging acoustic modalities.
- Nucleofection:Proprietary electroporation workflows optimized for primary cell and stem cell applications with specialized buffer systems. Lonza Group anchors high-value cell therapy manufacturing partnerships through platform-specific instrumentation and consumable bundles.
- Chemical Methods:Lipid-based and polymer-based transfection reagents relying on endosomal escape mechanisms. Thermo Fisher Scientific extends market reach through integrated reagent-instrument bundles that lock in recurring consumable spend.
- Physical Methods:Electroporation, biolistics, and hydrodynamic injection approaches bypass endosomal trafficking limitations.
- Acoustofluidic Techniques:Ultrasound-mediated membrane permeabilization integrated with microfluidic flow architectures for continuous processing.
Chemical methods retain volume leadership; nucleofection is climbing fastest on therapeutic manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic buyers in the Mountain West exhibit highest price elasticity for transfection reagents, while pharmaceutical sponsors in Greater Boston absorb premium pricing for validated electroporation platforms without volume reduction.
Greater Boston
Massachusetts biotech sponsors command the steepest per-site spending on clinical-grade transfection instrumentation. FDA 21 CFR Part 1271 oversight elevates demand for traceable lot release documentation across Kendall Square cell therapy developers. Cambridge and Somerville electroporation deployment accelerates as gene therapy pipelines advance toward commercial validation.
California Corridor
San Diego and San Francisco developers underutilize automated electroporation capacity for allogeneic cell line engineering. NIH recombinant DNA advisory framework compliance shapes protocol standardization across Stanford and UCSF affiliate laboratories. South San Francisco biotech manufacturing clusters expand nucleofection partnerships to preempt FDA submission delays.
Midwest Manufacturing Belt
Illinois and Michigan contract research organizations expand transfection-as-a-service capacity fastest to capture outsourced process development. USDA-APHIS dual jurisdiction for veterinary biologics complicates platform qualification for agricultural gene therapy applications near Chicago. Purdue and University of Michigan research foundations anchor flexible chemical transfection procurement for budget-constrained discovery workflows.
Pacific Northwest
Seattle and Portland academic laboratories prioritize lipofection reagents for broad cell line compatibility in early-stage studies. Washington State biosafety guidelines align with NIH institutional review requirements for CRISPR-mediated editing protocols. Fred Hutchinson Cancer Center anchors electroporation validation for CAR-T manufacturing under tightening FDA guidance.
Southeast Growth Corridor
North Carolina Research Triangle pharmaceutical sponsors concentrate validated platform spending for therapeutic protein production. Duke and UNC institutional biosafety committees enforce documentation standards exceeding federal baselines for physical delivery methods. RTP contract manufacturers expand nucleic acid transfection capacity to serve venture-backed gene therapy developers avoiding capital commitment.
United States Transfection Technologies Market Key Industry Players
Capability concentration sits with integrated life science conglomerates; scale advantage sits with specialized cell therapy manufacturing partners. The market structures around three tiers: diversified conglomerates bundling reagent-instrument workflows, mid-cap specialists anchoring high-value therapeutic partnerships, and research-focused suppliers serving academic price sensitivity. Strategic moves concentrate on integrated consumable-instrument bundles and platform validation services that lock in recurring revenue.
Within the integrated conglomerate tier, Thermo Fisher Scientific Inc. and Merck KGaA exemplify scale-driven positioning through captive consumable supply chains. Lonza Group occupies a specialized manufacturing partnership position anchored by proprietary buffer-system workflows. Among research-use specialists, Promega Corporation and QIAGEN sit within flexible procurement segments serving budget-constrained discovery laboratories. Bio-Rad Laboratories, Inc. and MaxCyte represent instrumentation-focused archetypes competing on parameter reproducibility for clinical-grade applications.
| Leading Market Players |
|---|
| Lonza Group |
| Promega Corporation |
| Thermo Fisher Scientific Inc. |
| OriGene Technologies, Inc. |
| MaxCyte |
| Bio-Rad Laboratories, Inc. |
| Merck KGaA |
| Altogen Biosystems |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
I-95 freight corridors linking Boston's Kendall Square biotech cluster to Philadelphia pharmaceutical hubs transmit cost volatility from fuel surcharges and cold-chain logistics directly into consumable pricing. Electroporation cuvette manufacturers absorb platinum electrode sourcing premiums while pharmaceutical sponsors in Massachusetts accept premium instrument validation bundles that embed logistics costs into lifetime service contracts.
Pricing Analysis
Consumable reagent subscriptions and extended validation service contracts generate higher lifetime value than standalone instrument sales. Three-tier pricing structure across GMP-validated, research-grade, and academic-economy levels separates FDA 21 CFR Part 1271-compliant platforms from discovery-use kits. Cost compression in chemical transfection reagents is intensifying because academic buyers unbundle purchases and force vendor flexibility. Contract research organizations exhibit highest price sensitivity; gene therapy developers in California and Massachusetts absorb premiums without volume reduction.
Supply Chain Analysis
Lonza Group and Thermo Fisher Scientific anchor contract-manufacturing concentration for clinical-grade transfection consumables with proprietary buffer production. Germany, Switzerland, and the United States feed specialized electroporation instrumentation assembly. Platinum electrode sourcing from South Africa and Russia, plus cationic lipid feedstocks from Chinese chemical manufacturers, creates single-source vulnerability in consumable inputs. Distribution runs through direct field service teams for pharmaceutical accounts and distributor networks for academic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform validation services and recurring consumable subscriptions expand faster than capital instrument sales, converting one-time hardware transactions into multi-year revenue streams. FDA documentation workflows and GMP-grade reagent supply agreements represent the fastest-growing attach layers.
For Market Incumbents: Pre-empt margin erosion from unbundled academic procurement by embedding instrument purchases within multi-site enterprise agreements that lock in consumable minimums. Consolidate fragmented CRO service offerings through acquisition of regional transfection-as-a-service providers in the Midwest Manufacturing Belt. Threat substitution from microfluidic-electroporation convergence demands accelerated R&D in continuous flow architectures.
For New Entrants and Emerging Players: Build out automated electroporation capacity in California's underutilized San Diego and San Francisco corridors where allogeneic cell line engineering whitespace persists. California biotechnology sponsors seek outsourced manufacturing partnerships without capital commitment. Go-to-market through shared manufacturing infrastructure models reduces individual platform ownership barriers for venture-backed developers.
For Investors and Strategic Acquirers: Specialized cell therapy manufacturing partners with proprietary nucleofection workflows and captive buffer supply chains command scarcity premiums. Long-term viability rests on FDA 21 CFR Part 1271 compliance depth and GMP-grade plasmid DNA sourcing relationships. Signal to watch is acceleration of NIH recombinant DNA advisory framework enforcement triggering platform standardization mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Validation Service Expansion | FDA 21 CFR Part 1271 compliance documentation creates recurring revenue from gene therapy sponsors. |
| GMP-Grade Reagent Supply Agreement | Lonza Group and Thermo Fisher Scientific lock in consumable spend through captive buffer production. |
| Microfluidic-Electroporation Integration | Continuous flow processing enables scalable ex vivo cell engineering for commercial manufacturing. |
| California Manufacturing Footprint Expansion | San Diego and San Francisco biotech hubs underutilize automated capacity for allogeneic engineering. |
| CRO Transfection-as-a-Service Launch | Midwest contract research organizations capture outsourced process development from capital-averse developers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 1271 guidance documents, NIH recombinant DNA advisory committee filings, and electroporation instrument qualification protocols. Primary interviews with gene therapy manufacturing executives, regulatory affairs leads at Massachusetts biotechnology sponsors, GMP facility managers, and academic laboratory procurement officers were cross-validated against SEC 10-K disclosures from life science conglomerates and customs data on platinum electrode imports. Bottom-up site-level capacity estimates and top-down market sizing were triangulated to produce volume and value outputs.
Forecast inputs include electroporation system deployment rates across the analysis window, lipofection reagent consumption per active research site, and gene therapy pipeline progression by therapeutic modality. Segmentation dimensions modeled encompass product type, end user archetype, application area, and regional regulatory cluster density. CAGRs were derived from instrument replacement cycles, consumable attach rates, and service contract renewal patterns specific to cell therapy manufacturing scale-up.
Stress conditions across platinum price volatility, FDA guidance timeline acceleration, and GMP-grade plasmid DNA supply bottlenecks were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory enforcement consistency and therapeutic pipeline maturation without clinical trial failure rate projection. Quarterly review of FDA 21 CFR Part 1271 draft guidance releases and NIH institutional biosafety committee enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market