
 Bioadhesive Microspheres Market | 2026-2036
Bioadhesive Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
Bioadhesive Microspheres Market Analysis
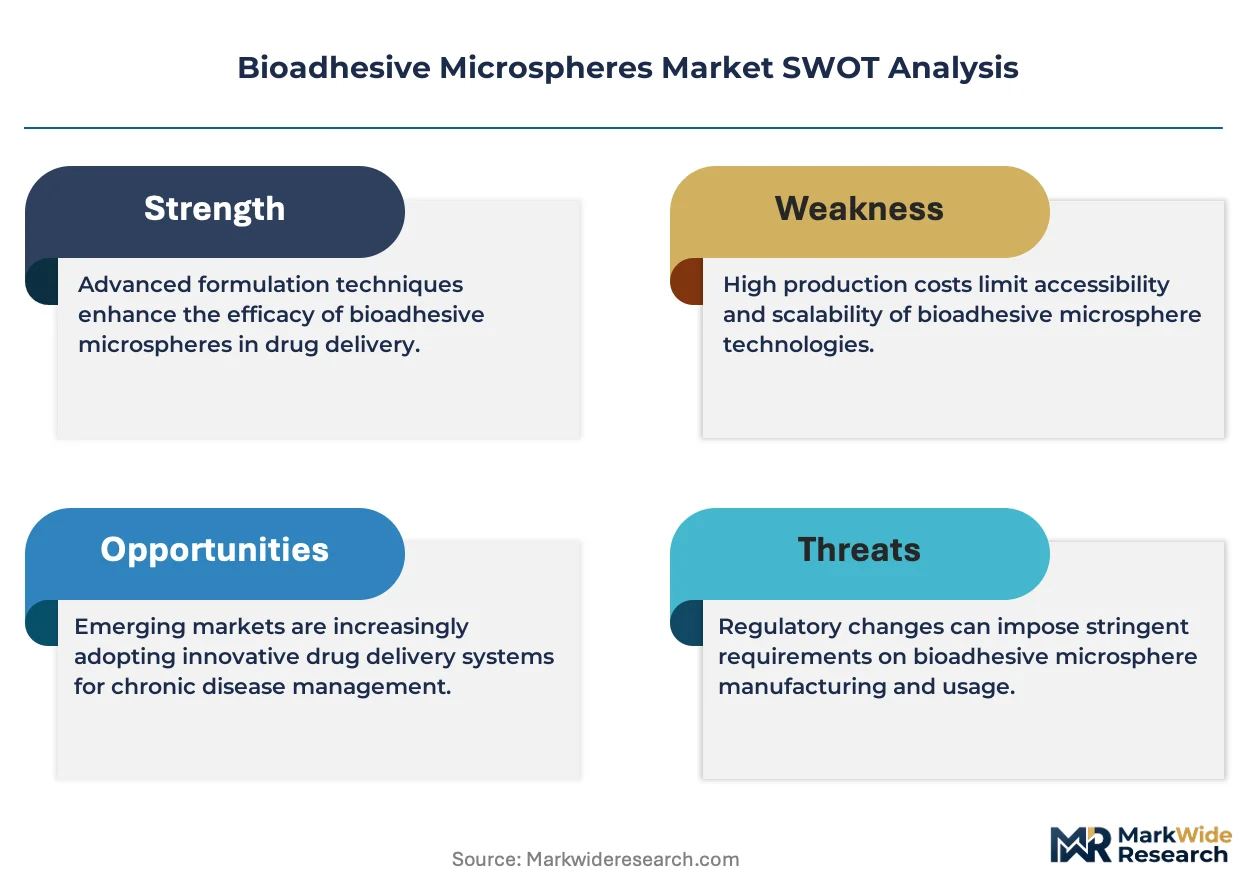
Platform licensing revenue from proprietary polymer modification technologies is reshaping competitive economics in bioadhesive formulations. Evonik leverages its specialty excipient portfolio to anchor high-margin supply relationships with multinational pharmaceutical clients. Ashland sustains technology leadership through controlled-release polymer platforms that dominate oral and injectable mucoadhesive applications. Adhesives Research, Inc. competes in niche transdermal and buccal delivery segments where custom synthesis capabilities command premium positioning.
Bioadhesive microspheres are spherical particulate carriers, typically 1–1000 micrometers in diameter, engineered from natural or synthetic polymers to adhere to biological membranes and enable sustained release of active compounds. Their primary purpose centers on enhancing drug bioavailability, localizing therapeutic action at mucosal sites, and protecting biological payloads from enzymatic degradation during transit. Natural polymers, including chitosan and alginate derivatives, occupy the largest volume share due to established biocompatibility profiles and favorable regulatory pathways. Synthetic polymers, particularly PLGA and polycaprolactone variants, represent the fastest-expanding category as manufacturers demand tunable degradation kinetics for long-acting injectables. Drug delivery applications concentrate the dominant margin pool, though tissue engineering segments attract accelerating R&D investment for regenerative scaffold applications.
FDA combination product regulations, EMA quality guidelines for particulate drug carriers, and ISO 10993 biocompatibility standards collectively govern market access and clinical translation timelines for bioadhesive microsphere developers. These frameworks elevate barriers for new entrants while rewarding manufacturers with validated quality management systems and established pharmacokinetic dossiers. Stakeholders must monitor evolving regulatory expectations for complex generic equivalence and nanoscale material characterization as agencies tighten scrutiny on particulate delivery systems.
Market Dynamics
Pharmaceutical manufacturers are consolidating mucosal delivery programs around platform technologies that reduce formulation cycle times and regulatory resubmission risk. This consolidation favors suppliers with validated polymer libraries and established pharmacokinetic dossiers.
Growth Catalysts
- EMA Quality Guidelines:The European Medicines Agency's particulate carrier standards accelerate adoption of pre-qualified bioadhesive platforms by reducing technical documentation burdens for sponsors filing in the European Union.
- Long-acting injectables:PLGA microsphere formulations for psychiatric and endocrine indications are expanding manufacturing capacity commitments from contract development organizations serving North American and Japanese sponsors.
- Buccal delivery expansion:Pediatric and geriatric patient populations are driving demand for taste-masked, mucoadhesive dosage forms that bypass hepatic first-pass metabolism.
Market Restraints
- Specialized polymer supply concentration:Medical-grade PLGA and polycaprolactone production concentrates among a limited set of European and North American specialty chemical suppliers, creating input bottlenecks.
- ISO 10993 biocompatibility testing costs:Extended cytotoxicity and sensitization study timelines for novel polymer modifications extend development budgets and compress early-stage margins.
- Lipid nanoparticle substitution:mRNA delivery infrastructure investments are diverting R&D capital and technical talent away from polymeric microsphere platforms in some therapeutic areas.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building dedicated bioadhesive formulation suites to capture outsourced work from Western pharmaceutical sponsors.
- Tissue engineering convergence:Regenerative scaffold applications combining bioadhesive microspheres with stem cell payloads represent an adjacent revenue stream with distinct reimbursement pathways.
- Complex generic equivalence pathways:FDA guidance on bioadhesive nasal spray generics creates first-mover advantages for sponsors with established in vitro release testing methodologies.
Industry Challenges
- Formulation scientist scarcity:The intersection of polymer chemistry, pharmacokinetics, and mucosal physiology requires specialized expertise that outpaces current graduate program output.
- Scale-up validation timelines:Transferring laboratory-scale microsphere production to commercial batch sizes demands extended process analytical technology implementation and regulatory pre-approval inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioadhesive Microspheres Market |
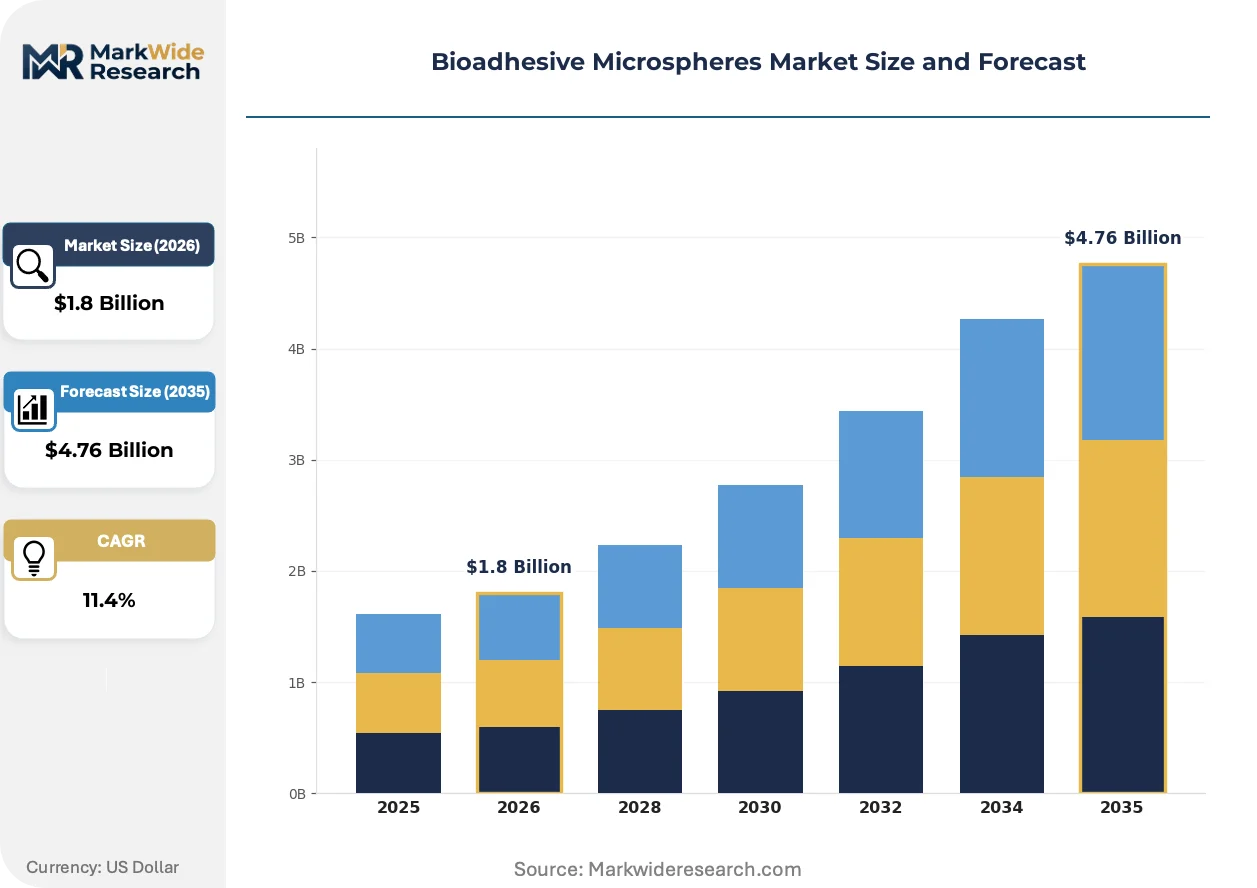
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymers, Natural Polymers, Synthetic Polymers, Biodegradable Microspheres Application: Drug Delivery, Gene Therapy, Diagnostics, Tissue Engineering End User: Pharmaceutical Companies, Research Institutions, Clinical Laboratories, Biotechnology Firms Size: Nanospheres, Microspheres, Macrospheres, Others |
| Companies Covered | Adhesives Research, Inc., EcoSynthetix Inc., Camurus AB, Phosphorex, Evonik, Henkel Adhesives Technologies India Private Limited, The Compound Company BV, Oakwood Laboratories, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioadhesive Microspheres Market Emerging Trajectories
Formulation science is converging with process analytical technology to enable real-time release testing of bioadhesive microsphere critical quality attributes. This shift compresses batch release timelines and reduces offline analytical burdens.
Multilayered core-shell microsphere architectures are migrating from academic research into commercial development pipelines. These structures enable incompatible active pharmaceutical ingredients to coexist within single dosage forms. Large-molecule sponsors in oncology and immunology are adopting this approach to combine cytotoxic payloads with immune-modulating adjuvants. The technology is migrating from exploratory feasibility studies into formal pre-IND programs, compressing traditional formulation development timelines by 12 to 18 months.
FDA draft guidance on complex generic equivalence for nasal and buccal products is tightening in vitro-in vivo correlation requirements. This regulatory precision elevates barriers for abbreviated new drug application sponsors lacking established pharmacokinetic reference standards. Generic divisions of multinational pharmaceutical companies are responding by acquiring specialized bioadhesive formulation capabilities through technology licensing rather than internal development.
Hospital procurement consortia in Germany and Japan are consolidating supplier qualification processes around pre-audited manufacturing sites. This buyer concentration reduces vendor management overhead but compresses margins for mid-tier contract manufacturers excluded from approved supplier lists. The shift is most visible in injectable long-acting formulations where batch consistency directly impacts therapeutic outcomes and liability exposure.
Bioadhesive Microspheres Market Segmentation
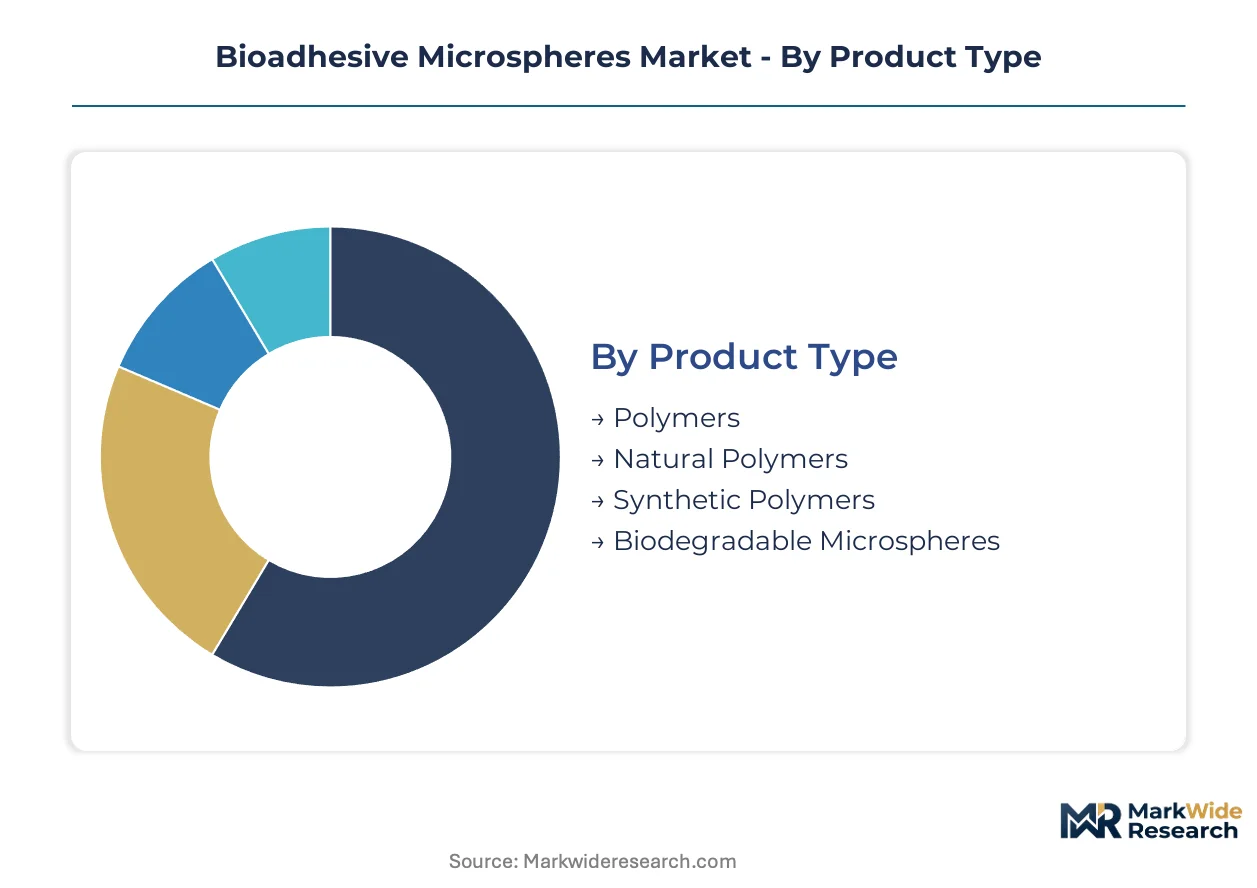
Segmentation in bioadhesive microspheres reveals distinct technical requirements and procurement patterns across polymer chemistry, therapeutic application, and end-user sophistication. Each dimension carries implications for formulation complexity, regulatory pathway, and manufacturing scale.
Product Type:
After-sales technical support intensity varies sharply by polymer class, with synthetic formulations demanding sustained analytical collaboration and natural polymers requiring biocompatibility troubleshooting.
- Natural Polymers:Chitosan, alginate, and gelatin derivatives dominate current volume due to established safety profiles and streamlined FDA biologics pathways. Demand concentrates in United States and German pharmaceutical manufacturing where EMA quality guidelines for particulate carriers accelerate qualification timelines. These materials require intensive supplier technical support for batch-to-batch viscosity consistency.
- Synthetic Polymers:PLGA and polycaprolactone variants enable tunable degradation kinetics critical for psychiatric and endocrine long-acting injectables. Japanese sponsors in Osaka and Tokyo drive specialized orders requiring precise molecular weight distributions. Technical service intensity peaks during scale-up validation as sponsors navigate ISO 10993 biocompatibility testing protocols.
- Biodegradable Microspheres:Engineered for complete physiological absorption without surgical retrieval, these formulations command premium positioning in pediatric and geriatric mucosal applications.
- Polymers:Broad category encompassing both natural and synthetic base materials used in foundational research and early-stage formulation screening.
By volume, natural polymers lead. By growth pace, synthetic polymers are expanding most quickly.
Application:
Margin structure diverges across therapeutic use cases, with drug delivery capturing established revenue pools and tissue engineering attracting venture-funded development programs.
- Drug Delivery:Sustained-release formulations for buccal, nasal, and injectable routes represent the commercial core, with FDA combination product regulations governing platform validation. Demand clusters around Minneapolis, Basel, and Osaka where specialized manufacturing infrastructure supports cGMP microsphere production. Sponsors prioritize suppliers with established pharmacokinetic dossiers to reduce regulatory resubmission risk.
- Tissue Engineering:Regenerative scaffold applications combining bioadhesive microspheres with stem cell payloads represent an adjacent revenue stream with distinct reimbursement pathways. German hospital procurement consortia in Munich and Berlin are consolidating supplier qualification around pre-audited manufacturing sites for these advanced therapies.
- Gene Therapy:Viral and non-viral vector encapsulation demands ultra-pure polymer grades with minimal endotoxin content, creating input bottlenecks among qualified European specialty chemical suppliers.
- Diagnostics:Imaging agent carriers and biosensor substrates require precise size distribution control, favoring contract manufacturers with implemented process analytical technology systems.
Drug delivery commands the dominant revenue share. Tissue engineering demonstrates the steepest expansion trajectory among emerging applications.
End User:
Procurement sophistication scales with organizational scale, from multinational pharmaceutical quality agreements to research institution material transfer arrangements.
- Pharmaceutical Companies:Multinational sponsors in United States, Germany, and Japan consolidate mucosal delivery programs around platform technologies, favoring suppliers with validated polymer libraries and established regulatory dossiers. These buyers negotiate multi-year supply agreements with technical service riders covering formulation troubleshooting.
- Biotechnology Firms:Venture-backed developers in Boston and San Diego pursue novel indications requiring custom polymer modifications, accepting higher per-gram costs for rapid iteration cycles.
- Research Institutions:Academic laboratories in Hyderabad and Ahmedabad access catalog-grade materials through distributor networks with limited technical support.
- Clinical Laboratories:Diagnostic developers prioritize lot-to-lot consistency for regulatory compliance, sourcing through qualified contract manufacturing organizations.
Pharmaceutical companies anchor procurement volume. Biotechnology firms are gaining share fastest through platform licensing arrangements.
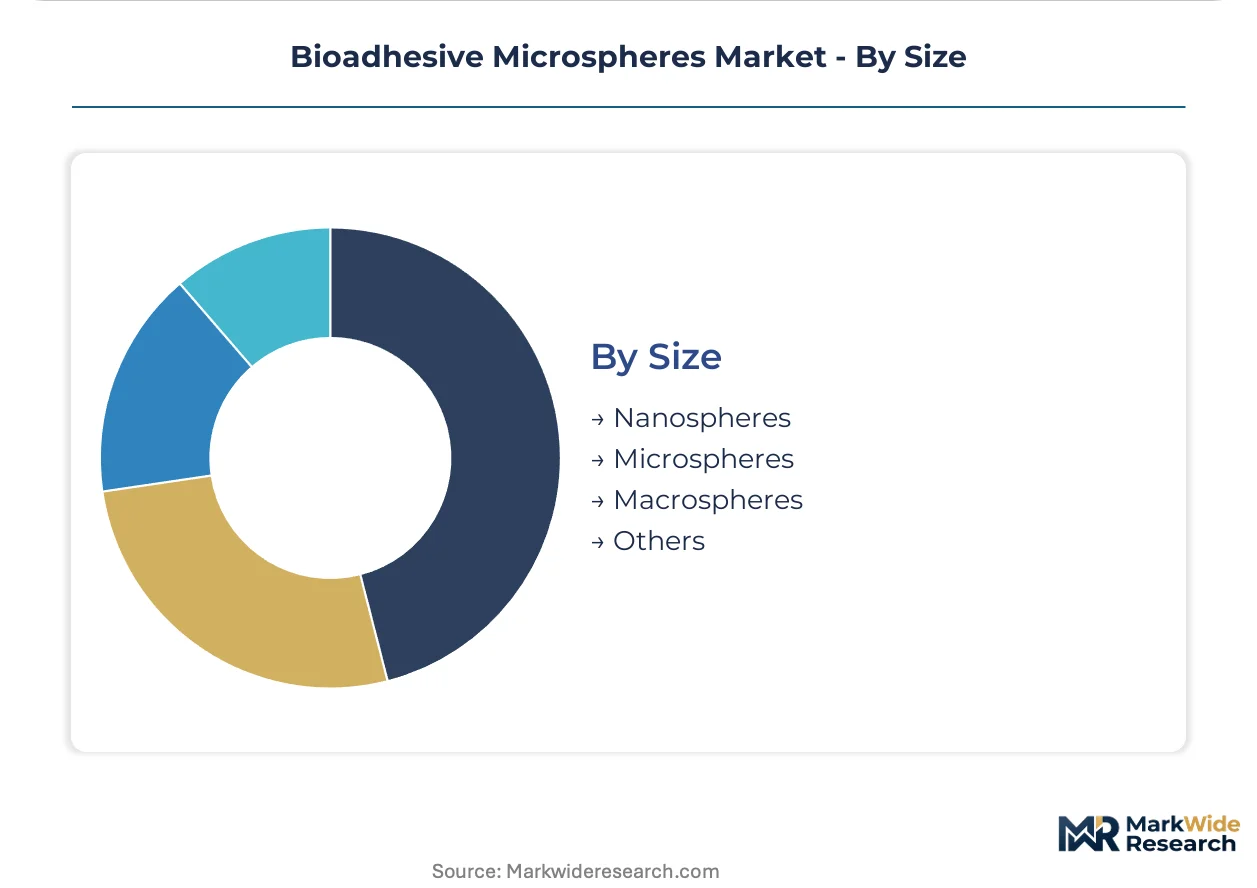
Size:
Manufacturing process selection and analytical validation burden correlate directly with particle dimension specifications.
- Microspheres:The 1–1000 micrometer diameter range dominates commercial production, with spray drying and emulsion techniques established at contract development organizations serving North American and Japanese sponsors. Size distribution validation via laser diffraction represents standard quality control.
- Nanospheres:Sub-micron formulations for intracellular delivery and enhanced permeation require specialized equipment and extended stability testing, concentrating production among European and North American specialty suppliers.
- Macrospheres:Millimeter-scale particles for tissue engineering scaffolds and implantable depots occupy niche applications with distinct surgical handling requirements.
- Others:Irregular and custom geometries for specialized research applications fall outside standard commercial specifications.
Microspheres lead by manufacturing volume. Nanospheres are climbing the fastest as oncology and immunology programs advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade PLGA and polycaprolactone production concentrates among European and North American specialty chemical suppliers, creating input bottlenecks that shape regional competitive dynamics. FDA combination product regulations, EMA quality guidelines, and PMDA manufacturing standards collectively govern market access timelines across developed pharmaceutical markets.
United States
Multinational pharmaceutical sponsors in Minneapolis and Boston consolidate mucosal delivery programs around platform technologies with validated polymer libraries. FDA draft guidance on complex generic equivalence for nasal and buccal products tightens in vitro-in vivo correlation requirements. CDMOs in the Research Triangle and San Diego corridor are expanding dedicated bioadhesive formulation suites to capture outsourced development work.
Germany
Hospital procurement consortia in Munich and Berlin consolidate supplier qualification processes around pre-audited manufacturing sites for long-acting injectables. EMA quality guidelines for particulate carriers accelerate adoption of pre-qualified bioadhesive platforms by reducing technical documentation burdens. Specialty excipient manufacturers in the Rhine-Ruhr region anchor high-margin supply relationships with multinational pharmaceutical clients.
Japan
PMDA manufacturing standards for controlled-release formulations drive specialized orders from sponsors in Osaka and Tokyo requiring precise molecular weight distributions. METI industrial policy supports domestic production of medical-grade biodegradable polymers for psychiatric and endocrine indications. The Kansai pharmaceutical cluster maintains dedicated microsphere production infrastructure serving regional long-acting injectable programs.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad are building dedicated bioadhesive formulation suites to capture outsourced work from Western pharmaceutical sponsors. CDSCO regulatory pathways for complex generics create first-mover advantages for sponsors with established in vitro release testing methodologies. The Gujarat pharmaceutical corridor attracts technology licensing arrangements from venture-backed developers seeking rapid iteration cycles.
Switzerland
Swissmedic biocompatibility standards for novel polymer modifications extend development budgets and compress early-stage margins for innovative formulations. Basel-based multinational sponsors prioritize suppliers with established pharmacokinetic dossiers to reduce regulatory resubmission risk. The country's precision manufacturing infrastructure supports ultra-pure polymer grades with minimal endotoxin content for gene therapy applications.
Bioadhesive Microspheres Market Vendor Landscape
Specialty chemical conglomerates and focused excipient technology firms split the market into distinct capability tiers. The vendor base organizes around polymer chemistry depth, regulatory dossier maturity, and manufacturing scale rather than pure size. Three archetypes dominate: diversified material science conglomerates with validated quality management systems, mid-cap polymer specialists with custom synthesis capabilities, and regional CDMOs with implemented process analytical technology. Competitive moves concentrate on technology licensing arrangements and multi-year supply agreements with technical service riders.
Within the diversified conglomerate tier, Evonik and Ashland exemplify positioning anchored by specialty excipient portfolios and controlled-release polymer platforms. Among focused specialists, Adhesives Research, Inc. occupies a position in niche transdermal and buccal delivery segments where custom synthesis capabilities command premium positioning. These three companies represent the strategic archetypes—material science breadth, formulation technology leadership, and application-specific specialization—that define competitive boundaries in bioadhesive microsphere supply.
| Leading Market Players |
|---|
| Adhesives Research, Inc. |
| EcoSynthetix Inc. |
| Camurus AB |
| Phosphorex |
| Evonik |
| Henkel Adhesives Technologies India Private Limited |
| The Compound Company BV |
| Oakwood Laboratories |
| Ashland |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp pharmaceutical logistics corridor shapes cost dynamics for medical-grade polymer feedstocks, amplifying pricing power among European specialty chemical suppliers while forcing downstream differentiation between multinational sponsors and mid-tier contract manufacturers.
Pricing Analysis
FDA combination product regulations dictate the pricing tier structure across bioadhesive microsphere supply. Three-tier pricing separates GMP-validated platforms from pilot-scale batches and research-grade materials. Price differentiation rests on ISO 10993 certification completeness and established pharmacokinetic dossiers. Cost compression in standard-grade PLGA is intensifying because hospital procurement consortia in Germany and Japan are consolidating supplier lists. Biotechnology firms in Boston and San Diego show lowest price sensitivity due to venture-funded iteration cycles, while research institutions in India face acute budget constraints.
Supply Chain Analysis
Medical-grade lactic acid and glycolide monomer production concentrates in Germany, the United States, and Japan. Feedstock supply draws from petrochemical derivatives and fermentation-based bioplastics, with polymerization catalysts and endotoxin-controlled solvents as critical inputs. Single-source vulnerability concentrates among European suppliers qualified for gene therapy-grade materials. Distribution runs through validated contract development organizations with implemented process analytical technology systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioadhesive microsphere supply is transitioning toward service-attach revenue models, with after-sales technical support and regulatory dossier licensing expanding faster than base polymer sales.
For Market Incumbents: Pre-empt lipid nanoparticle substitution in psychiatric and endocrine indications by accelerating multilayered core-shell microsphere development timelines. Secure backward integration into medical-grade PLGA production to reduce input bottlenecks from European specialty chemical suppliers. Anchor platform licensing arrangements with multi-year technical service riders covering formulation troubleshooting and scale-up validation. For New Entrants and Emerging Players: Establish a beachhead in tissue engineering scaffold applications where regenerative medicine reimbursement pathways remain underdeveloped and incumbent dossiers are sparse. Target CDMO partnerships in Hyderabad and Ahmedabad serving Western sponsors seeking rapid iteration cycles. Lead with custom synthesis capabilities for buccal delivery segments where taste-masking expertise commands premium positioning. For Investors and Strategic Acquirers: Regional CDMOs with implemented process analytical technology and pre-audited manufacturing sites represent the most defensible acquisition profile for exposure to long-acting injectable growth. Monitor FDA draft guidance finalization on complex generic equivalence as the critical inflection signal for abbreviated new drug application sponsor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Licensing | Platform licensing revenue from proprietary polymer modifications reshapes competitive economics for multinational pharmaceutical clients. |
| Process Analytical Technology Implementation | Real-time release testing of critical quality attributes compresses batch release timelines at contract development organizations. |
| CDMO Capacity Expansion | Dedicated bioadhesive formulation suites in Hyderabad and Ahmedabad capture outsourced work from Western sponsors. |
| Multilayered Core-Shell Architecture Development | Large-molecule oncology sponsors adopt incompatible active ingredient co-encapsulation for cytotoxic-immune adjuvant combinations. |
| Hospital Procurement Consortium Qualification | Pre-audited manufacturing site consolidation in Munich and Berlin reduces vendor management overhead for long-acting injectables. |
Methodological Framework
Initial hypotheses were tested against primary input from formulation science directors, regulatory affairs leads at multinational sponsors, contract manufacturing organization executives, and hospital procurement managers, then refined against FDA filings, EMA quality guidelines, ClinicalTrials.gov mucosal delivery protocols, and ISO 10993 biocompatibility standards. Bottom-up polymer demand modeling and top-down pharmaceutical excipient market sizing were cross-validated to establish segment boundaries.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions included polymer chemistry class, therapeutic application route, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from normalized growth rate convergence across independent modeling approaches. Forecast inputs incorporated PMDA manufacturing standard evolution and METI industrial policy support for domestic biodegradable polymer production.
Sensitivities concentrate around FDA complex generic equivalence guidance finalization, EMA particulate carrier quality guideline revisions, and lipid nanoparticle platform substitution rates in psychiatric indications. Cross-checking against CDSCO regulatory pathway announcements and hospital procurement consortium supplier list publications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Global Optogenetics Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Cell Cycle Analysis Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Brain Biomarkers Market