
 Nucleic Acid Aptamers Market | 2026-2036
Nucleic Acid Aptamers Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Aptamers Market Outlook
A capital-intensity divergence between platform owners and service providers is rotating competitive advantage toward integrated SELEX operators. Aptamer Group PLC leverages its automated selection platform to sustain recurring diagnostic partnerships across Europe. SomaLogic Inc. anchors its position through proteomics-scale aptamer arrays that dominate biomarker discovery workflows. Base Pair Biotechnologies Inc. competes on custom synthesis turnaround, occupying a niche in rapid-target validation services for academic clients.
Nucleic acid aptamers are single-stranded DNA or RNA oligonucleotides that fold into defined three-dimensional structures capable of binding specific molecular targets with affinities comparable to antibodies; they are synthesized through solid-phase chemical methods that enable precise sequence modification and batch-to-batch reproducibility. Their primary purpose spans therapeutic modulation, diagnostic recognition, and targeted cargo delivery in pharmaceutical and clinical settings. DNA aptamers currently lead commercial volume due to lower synthesis costs and superior nuclease stability, while modified aptamers with 2'-fluoro or 2'-O-methyl substitutions capture expanding therapeutic margins as regulatory familiarity with chemically stabilized oligonucleotides deepens. Diagnostic applications grow fastest among end-use categories, driven by point-of-care assay development and companion diagnostic mandates.
FDA oversees aptamer therapeutics through its Office of Therapeutic Biologics and Products, while EMA applies its centralized procedure for oligonucleotide-based medicines under the Committee for Medicinal Products for Human Use; both frameworks increasingly recognize aptamers as distinct from traditional biologics, accelerating review timelines. ISO 13485 quality standards and CLSI guidelines shape diagnostic aptamer manufacturing protocols, particularly for clinical laboratory deployment. Stakeholders must monitor evolving FDA guidance on immunogenicity assessment and EMA updates to chemistry-manufacturing-controls requirements for modified nucleic acid constructs.
Market Dynamics
Automated SELEX platforms are compressing selection timelines from months to weeks, redistributing competitive advantage toward operators with integrated bioinformatics and high-throughput screening infrastructure.
Growth Catalysts
- FDA Office of Therapeutic Biologics:Streamlined review pathways for oligonucleotide therapeutics reduce clinical entry friction for modified aptamer candidates.
- Point-of-care diagnostics:Companion diagnostic mandates from oncology trials drive demand for rapid, stable recognition elements in decentralized testing workflows.
- 2'-fluoro substitution chemistry:Enhanced nuclease stability enables extended circulation half-lives in therapeutic applications without complex formulation.
Market Restraints
- Modified nucleotide input costs:Specialty phosphoramidite chemistries for therapeutic-grade aptamers carry 3-5x synthesis premiums versus standard DNA monomers.
- SELEX platform concentration:Core selection infrastructure clusters in Germany and the United States, creating geographic dependency for contract research access.
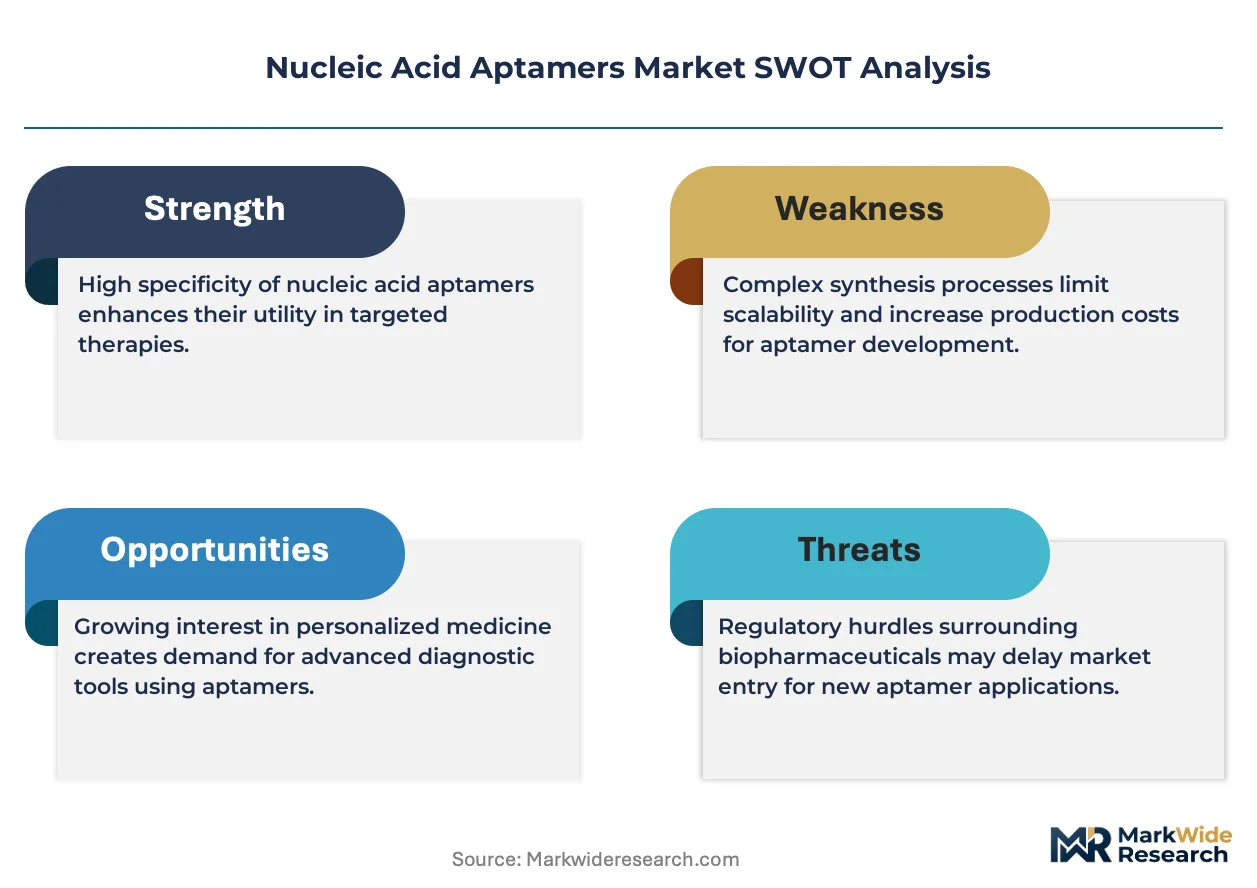
- Antibody substitution threat:Established biologics with deeper clinical validation and manufacturing scale retain preference in chronic disease indications.
Strategic Opportunities
- India CDMO expansion:Contract development capacity for oligonucleotide synthesis remains underdeveloped relative to small-molecule and biologics infrastructure.
- CRISPR-aptamer convergence:Programmable nucleic acid tools enable cell-specific delivery of gene editing cargo through dual-function constructs.
- EMA centralized procedure alignment:Chemistry-manufacturing-controls harmonization across EU member states accelerates multi-country therapeutic launches.
Industry Challenges
- SELEX bioinformatics talent scarcity:Computational biologists capable of integrating next-generation sequencing data with structure prediction algorithms command premium compensation.
- ISO 13485 diagnostic certification timelines:Quality management system implementation for clinical-grade aptamer production extends 18-24 months before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Aptamers Market |
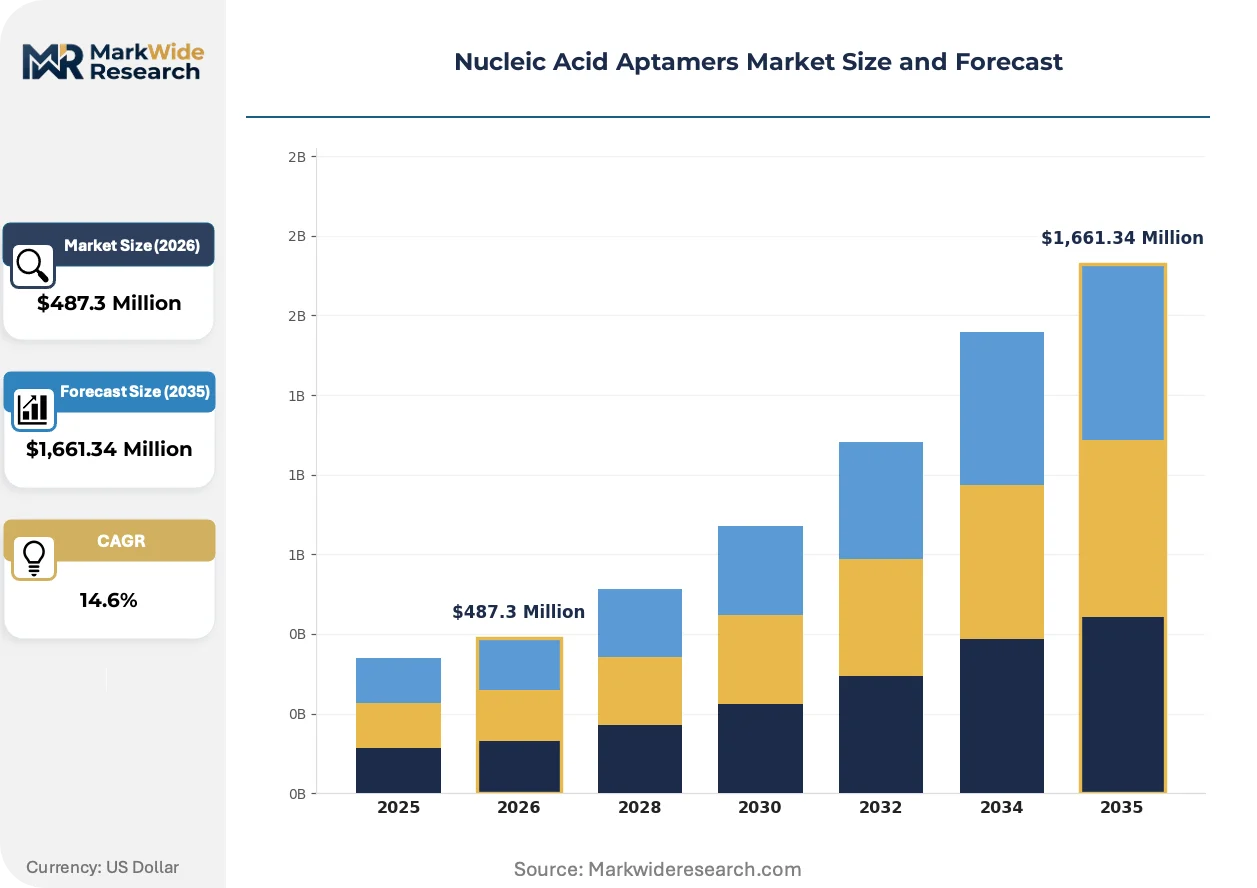
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RNA Aptamers, DNA Aptamers, Modified Aptamers, Universal Aptamers Application: Therapeutic Applications, Diagnostic Applications, Research Purposes, Drug Delivery End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutions, Clinical Laboratories Technology: SELEX, Microfluidics, Nanotechnology, High-Throughput Screening |
| Companies Covered | Base Pair Biotechnologies Inc., AM Biotechnologies LLC, SomaLogic Inc., TriLink BioTechnologies LLC, NeoVentures Biotechnology Inc., Aptamer Group PLC, Aptamer Sciences Inc., Vivonics Inc., NOXXON Pharma AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Aptamers Market Strategic Shifts
Next-generation selection methodologies and regulatory clarity are reconfiguring how aptamer developers capture value across therapeutic and diagnostic verticals.
Cell-SELEX and in vivo selection protocols are fragmenting the traditional purified-target paradigm by enabling discovery against membrane-bound proteins and complex cellular environments. Biopharmaceutical discovery groups adopt these methods to access previously intractable targets. The shift compresses validation cycles and expands addressable target space beyond recombinant protein limitations.
EMA updates to chemistry-manufacturing-controls requirements for modified nucleic acid constructs clarify stability testing protocols for therapeutic submissions. Sponsors gain predictability in regulatory preparation. European oligonucleotide developers accelerate pipeline investments as submission pathways standardize.
Academic research groups increasingly bypass traditional service providers through direct access to commercial SELEX kits and cloud-based sequence analysis platforms. Equipment manufacturers capture margin from consumable recurring revenue. Germany and the United States exhibit the fastest channel migration as institutional core facilities expand in-house aptamer capabilities.
Nucleic Acid Aptamers Market Segmentation
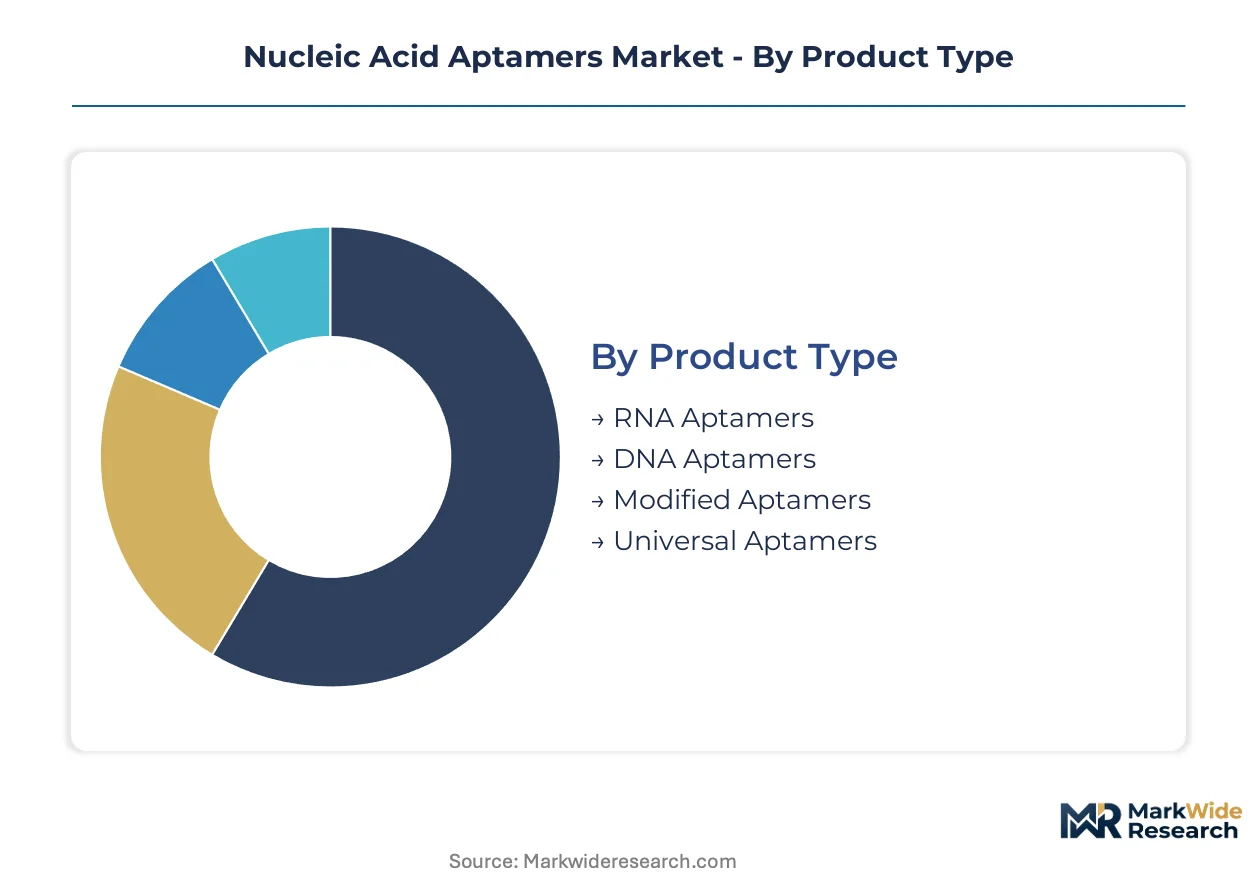
Segmentation in the nucleic acid aptamers market reveals how technical specifications and end-use requirements reshape procurement patterns across therapeutic and diagnostic workflows. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Antibody substitution pressure concentrates most intensely on unmodified DNA and RNA aptamers, where cost parity with polyclonal sera drives commoditization risk.
- RNA Aptamers:Single-stranded oligonucleotides with ribose sugar backbones that fold into complex tertiary structures for high-affinity target binding. Demand clusters in academic research settings across Germany and the United States, constrained by inherent nuclease susceptibility that limits serum stability without extensive chemical modification.
- DNA Aptamers:Deoxyribose-based sequences offering superior nuclease resistance and lower synthesis costs through standard phosphoramidite chemistry. Therapeutic developers in the United States prioritize DNA scaffolds for chronic administration protocols where manufacturing scalability outweighs binding kinetics advantages of RNA counterparts.
- Modified Aptamers:2'-fluoro, 2'-O-methyl, or locked nucleic acid substitutions extending circulation half-life for therapeutic applications.
- Universal Aptamers:Broad-specificity recognition elements designed for multiplex detection platforms and adaptable biosensor architectures.
DNA Aptamers retain volume leadership; Modified Aptamers hold the steepest expansion curve.
Application:
Margin concentration follows diagnostic assay validation timelines, with point-of-care deployment commanding premium pricing over research-grade reagents.
- Therapeutic Applications:Systemic administration of aptamer ligands for target modulation, exemplified by pegaptanib's ophthalmic vascular endothelial growth factor inhibition. Clinical-stage programs in the United States face FDA Office of Therapeutic Biologics review pathways, where chemistry-manufacturing-controls documentation requirements extend development timelines relative to diagnostic counterparts.
- Diagnostic Applications:Recognition elements in immunoassays, biosensors, and companion diagnostic platforms requiring batch-to-batch reproducibility under ISO 13485 protocols. German clinical laboratories drive demand for stabilized aptamer reagents in decentralized oncology testing workflows mandated by EMA companion diagnostic guidance.
- Research Purposes:Target validation, pull-down assays, and imaging probe development in academic and biopharmaceutical discovery settings.
- Drug Delivery:Aptamer-guided nanoparticle targeting and cell-specific cargo transport exploiting nucleic acid programmability.
Diagnostic Applications capture margin expansion; Therapeutic Applications absorb the largest absolute R&D investment.
End User:
Procurement sophistication divides sharply between regulated manufacturing environments and grant-funded research operations with distinct quality tolerance thresholds.
- Pharmaceutical Companies:Integrated drug developers pursuing aptamer therapeutics through internal SELEX platforms or strategic partnerships with automated selection providers. United States-based sponsors concentrate investment in modified aptamer candidates with established regulatory precedents, prioritizing candidates with clear FDA approval pathways over novel scaffolds.
- Biotechnology Firms:Specialized developers leveraging aptamer technology for niche therapeutic indications or diagnostic platform differentiation.
- Academic Research Institutions:Discovery-focused users with flexible sourcing requirements and sensitivity to per-oligonucleotide synthesis costs.
- Clinical Laboratories:High-throughput testing facilities requiring certified reagents with documented stability and traceability under clinical laboratory standards.
Pharmaceutical Companies dominate value capture; Clinical Laboratories represent the most price-sensitive procurement segment.
Technology:
Platform automation intensity determines competitive moat durability, with capital investment requirements filtering participant entry.
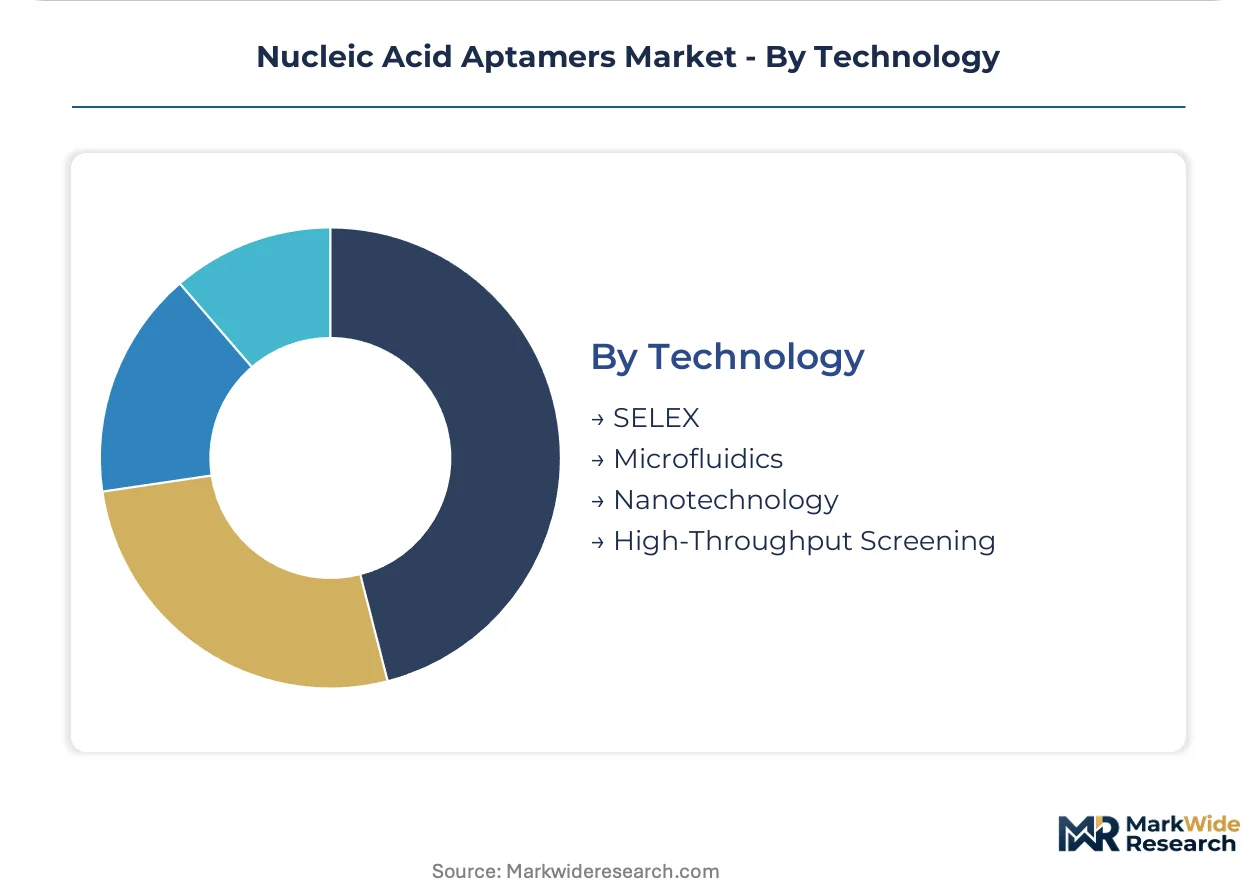
- SELEX:Systematic evolution of ligands by exponential enrichment remains the foundational selection methodology, now accelerated through next-generation sequencing integration and robotic liquid handling. German contract research organizations cluster around automated SELEX infrastructure, serving European biopharmaceutical clients with compressed selection timelines measured in weeks rather than months.
- Microfluidics:Droplet-based and continuous-flow selection formats enabling compartmentalized target-aptamer interactions with reduced reagent consumption.
- Nanotechnology:Gold nanoparticle and quantum dot conjugation for signal amplification in diagnostic readout systems.
- High-Throughput Screening:Parallel evaluation of synthesized aptamer libraries against target panels using array formats and automated binding assays.
SELEX maintains infrastructure dominance; Microfluidics gains adoption fastest among platform diversification strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical laboratories in Germany exhibit the lowest price elasticity for certified diagnostic aptamers, while academic buyers in India negotiate aggressively on per-oligonucleotide synthesis costs. Therapeutic developers in the United States absorb premium pricing for modified aptamer candidates with established FDA approval pathways.
United States
FDA Office of Therapeutic Biologics maintains streamlined review pathways for oligonucleotide therapeutics, reducing clinical entry friction for modified aptamer candidates. The agency's evolving guidance on immunogenicity assessment shapes sponsor preparation strategies. Greater Boston and San Diego host concentrated SELEX technology hubs where automated selection platforms serve contract research demand.
Germany
EMA centralized procedures under the Committee for Medicinal Products for Human Use govern oligonucleotide-based medicine approvals, with chemistry-manufacturing-controls harmonization accelerating multi-country launches. ISO 13485 certification requirements extend 18-24 months for clinical-grade production. Munich and Heidelberg cluster automated SELEX infrastructure serving European biopharmaceutical clients.
China
NMPA regulatory frameworks for nucleic acid therapeutics mature as domestic sponsors expand modified aptamer pipelines. The country's national pharmaceutical regulator issues stability testing protocols that align with international oligonucleotide standards. Shanghai and Suzhou concentrate contract development capacity for phosphoramidite chemistry scale-up.
India
CDSCO oversight of nucleic acid-based diagnostics creates compliance benchmarks for point-of-care assay manufacturers. The country's national pharmaceutical regulator streamlines import licensing for research-grade aptamer reagents. Bangalore and Hyderabad develop oligonucleotide synthesis infrastructure lagging behind small-molecule and biologics CDMO maturity.
United Kingdom
Medicines and Healthcare products Regulatory Agency pathways for advanced therapy medicinal products encompass aptamer therapeutic classifications. MHRA post-Brexit alignment with EMA chemistry-manufacturing-controls standards preserves export market access. Cambridge and Oxford anchor academic SELEX capabilities migrating toward commercial service provision.
Nucleic Acid Aptamers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with automated platform operators commanding premium positioning while synthesis-focused providers compete on turnaround velocity. The vendor base separates into three functional tiers: integrated SELEX platform owners, specialized oligonucleotide manufacturers, and discovery-service boutiques. Platform automation and regulatory certification capacity constitute the primary competitive moats. Consolidation pressure favors operators with captive bioinformatics talent and ISO 13485 diagnostic manufacturing credentials.
Among platform-integrated developers, Aptamer Group PLC and SomaLogic Inc. exemplify divergent specialization vectors within the technology-leadership tier. Base Pair Biotechnologies Inc. occupies a position within the rapid-turnover synthesis segment serving validation-intensive research workflows. AM Biotechnologies LLC and NeoVentures Biotechnology Inc. sit within the contract research provider cluster where geographic proximity to SELEX infrastructure determines client access.
| Leading Market Players |
|---|
| Base Pair Biotechnologies Inc. |
| AM Biotechnologies LLC |
| SomaLogic Inc. |
| TriLink BioTechnologies LLC |
| NeoVentures Biotechnology Inc. |
| Aptamer Group PLC |
| Aptamer Sciences Inc. |
| Vivonics Inc. |
| NOXXON Pharma AG |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification requirements simultaneously gate supplier qualification and stratify price tiers by locking uncertified manufacturers out of clinical-grade contracts while enabling certified operators to command synthesis premiums. Pharmaceutical sponsors in the United States absorb elevated pricing for modified aptamer candidates with established FDA approval pathways, whereas academic buyers in India negotiate aggressively on per-oligonucleotide synthesis costs.
Pricing Analysis
Consumable recurring revenue from SELEX kit resupply and cloud-based sequence analysis subscriptions drives lifetime value beyond initial platform sales. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified clinical-grade production from research-grade synthesis and unmodified DNA commodity reagents. Cost compression in standard-tier DNA aptamers is intensifying because automated phosphoramidite synthesis platforms expand capacity in Germany and the United States. Academic research institutions exhibit the highest price sensitivity, while clinical laboratories in Germany demonstrate the lowest elasticity for certified diagnostic reagents.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for specialty phosphoramidite chemistries sourced from Asian manufacturers. Supply concentrates in Germany, the United States, and China, with Munich and Heidelberg clustering automated SELEX infrastructure, Greater Boston and San Diego anchoring therapeutic development, and Shanghai and Suzhou scaling phosphoramidite chemistry production. The supply chain draws from 2'-fluoro and 2'-O-methyl modified nucleotide inputs, solid-phase synthesis resins, and next-generation sequencing consumables. Single-source vulnerability concentrates in specialty phosphoramidite suppliers for therapeutic-grade modifications. Distribution runs through contract research organizations, direct platform sales to academic core facilities, and certified reagent distributors serving clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nucleic acid aptamers sit in early-cycle expansion as automated SELEX platforms compress selection timelines from months to weeks, accelerating adoption across diagnostic and therapeutic workflows. Companion diagnostic mandates from oncology trials create immediate demand pull for stable recognition elements.
For Market Incumbents: Consolidate automated SELEX platform ownership with captive bioinformatics talent to defend against academic institutions bypassing traditional service providers through direct kit access. Acquire ISO 13485-certified manufacturing capacity in Germany to preempt EMA chemistry-manufacturing-controls harmonization advantages. Capacity addition in automated selection infrastructure represents the critical lever for sustaining recurring diagnostic partnerships. For New Entrants and Emerging Players: Differentiate on rapid-turnaround custom synthesis for target validation services, occupying the white space between platform-integrated developers and commoditized DNA aptamer suppliers. Target India's underdeveloped oligonucleotide CDMO capacity, where contract development infrastructure lags small-molecule and biologics maturity. A go-to-market angle anchored in CRISPR-aptamer convergence for cell-specific gene editing delivery captures programmable nucleic acid tool demand. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical parent companies divesting non-core aptamer therapeutic pipelines as regulatory clarity on oligonucleotide drugs matures. Long-term viability hinges on platform automation intensity and regulatory certification capacity rather than single-asset programs. Watch FDA guidance evolution on immunogenicity assessment as the signal for therapeutic submission volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Automated SELEX Platform Deployment | Robotic liquid handling integration compresses selection timelines from months to weeks for contract research clients. |
| ISO 13485 Certification Investment | Quality management system implementation unlocks clinical-grade aptamer production for decentralized oncology testing workflows. |
| Modified Aptamer Pipeline Advancement | 2'-fluoro substitution chemistry extends circulation half-life for therapeutic candidates under FDA Office of Therapeutic Biologics review. |
| CRISPR-Aptamer Convergence Development | Dual-function constructs enable cell-specific delivery of gene editing cargo through programmable nucleic acid architecture. |
| EMA Centralized Procedure Alignment | Chemistry-manufacturing-controls harmonization accelerates multi-country therapeutic launches across EU member states. |
Study Parameters
Desk research of FDA filings, EMA submissions, ClinicalTrials.gov records, and ISO certification databases preceded structured interviews with drug development executives, regulatory affairs leads, and hospital procurement managers. Secondary validation drew from SEC 10-K disclosures, patent assignment records, and contract research organization capacity announcements. Bottom-up segment sizing triangulated against top-down market envelope estimates from oligonucleotide synthesis capacity and SELEX platform deployment counts.
Variance decomposition across product type, application, end user, and technology dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate distributions anchored in therapeutic pipeline stage transitions and diagnostic assay validation timelines. Modeled inputs incorporated SELEX automation penetration curves, modified nucleotide substitution adoption rates, and point-of-care deployment regulatory clearance velocities.
Material uncertainties — regulatory guidance revisions, immunogenicity assessment standard changes, and phosphoramidite chemistry supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions on EMA-FDA pathway convergence and automated platform cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Live Cell RNA Detection Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Neuro Immunoassay Market
Biomedical Technology
Bead-Based Flow Cytometry Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Global Transcriptomics Market