
 Europe Exosome Research Products Market | 2026-2036
Europe Exosome Research Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Exosome Research Products Market Foresight
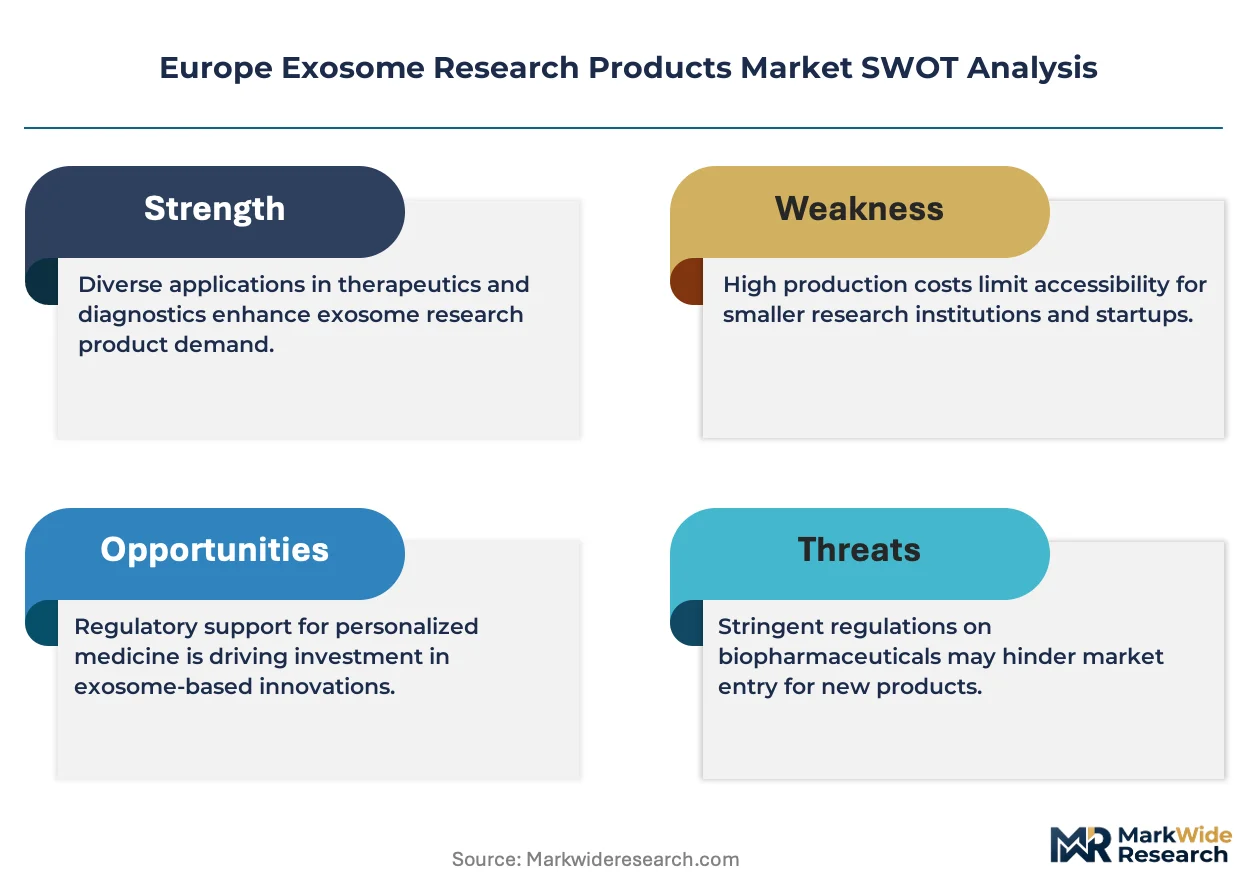
CE marking under the EU In Vitro Diagnostic Regulation is bifurcating the competitive landscape into qualified kit suppliers and unverified entrants. Thermo Fisher Scientific leverages its pan-European distribution infrastructure to sustain shelf presence in major research clusters. Lonza Group Ltd anchors its position through captive bioproduction expertise that extends into exosome manufacturing workflows. QIAGEN N.V. differentiates via nucleic acid purification heritage applied to exosomal RNA isolation protocols.
Europe exosome research products comprise specialized reagents, instruments, and consumables designed for the isolation, characterization, and functional study of extracellular vesicles ranging from 30 to 150 nanometers in diameter, typically recovered through ultracentrifugation, size-exclusion chromatography, or precipitation-based methods. These products enable downstream applications in liquid biopsy development, therapeutic payload engineering, and intercellular communication research across academic and commercial laboratories. Exosome isolation kits currently command the largest revenue share due to recurring purchase patterns tied to protocol standardization efforts, while exosome analysis instruments represent the fastest-expanding category as multiplexed detection platforms displace single-parameter western blotting. Drug delivery applications concentrate the highest margin pools, reflecting pharmaceutical sponsor funding for engineered exosome programs targeting oncology and rare disease indications.
The European Medicines Agency maintains active scientific advice pathways for exosome-derived medicinal products, while the EU Medical Device Regulation imposes clinical evidence requirements on diagnostic-grade characterization kits. REACH compliance adds material sourcing constraints for nanoparticle tracking analysis reagents and fluorescent labeling compounds. Stakeholders must monitor upcoming EMA qualification opinions on extracellular vesicle reference standards, as these determinations will reshape competitive access for kit manufacturers serving regulated therapeutic development pipelines.
Market Dynamics
The EU In Vitro Diagnostic Regulation's CE marking requirements are forcing kit manufacturers to consolidate characterization workflows or exit diagnostic-grade segments entirely, concentrating procurement among qualified suppliers.
Growth Catalysts
- EMA scientific advice pathways:Pharmaceutical sponsors now access structured regulatory guidance for exosome-derived medicinal products, de-risking therapeutic development pipelines and sustaining reagent demand.
- German research cluster density:Max Planck Institutes and Helmholtz centers in Munich, Heidelberg, and Berlin generate concentrated procurement volumes for isolation and analysis workflows.
- Engineered exosome manufacturing:Bioproduction scale-up for oncology and rare disease drug delivery programs is pulling through high-margin characterization and quality control consumables.
Market Restraints
- REACH compliance costs:Nanoparticle tracking analysis reagents and fluorescent labeling compounds face material sourcing constraints and substitution testing burdens.
- Ultracentrifuge supply concentration:High-speed rotor manufacturing concentrates among specialized German and Swiss precision engineering suppliers, creating equipment lead time vulnerability.
- Reference standard absence:EMA has not yet issued qualification opinions on extracellular vesicle reference materials, leaving kit validation protocols without regulatory anchor points.
Strategic Opportunities
- France's ANSM early engagement:The national pharmaceutical regulator maintains flexible scientific advice frameworks for academic spinouts developing diagnostic-grade exosome assays.
- Multiplexed detection convergence:Integration of single-particle interferometry with next-generation sequencing readouts enables multi-parameter exosome profiling from minimal sample volumes.
- Swissmedic therapeutic product pathway:Switzerland's streamlined advanced therapy medicinal product designation attracts engineered exosome developers seeking faster European market access.
Industry Challenges
- Exosome biogenesis expertise gap:Academic laboratories lack personnel trained in GMP-compatible isolation protocols, slowing translation to therapeutic manufacturing standards.
- IVDR technical documentation burden:CE marking for characterization kits requires clinical evidence generation that extends certification timelines beyond typical product development cycles.
- Cross-platform data interoperability:Proprietary file formats from nanoparticle tracking, flow cytometry, and mass spectrometry systems impede multi-instrument workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Exosome Research Products Market |
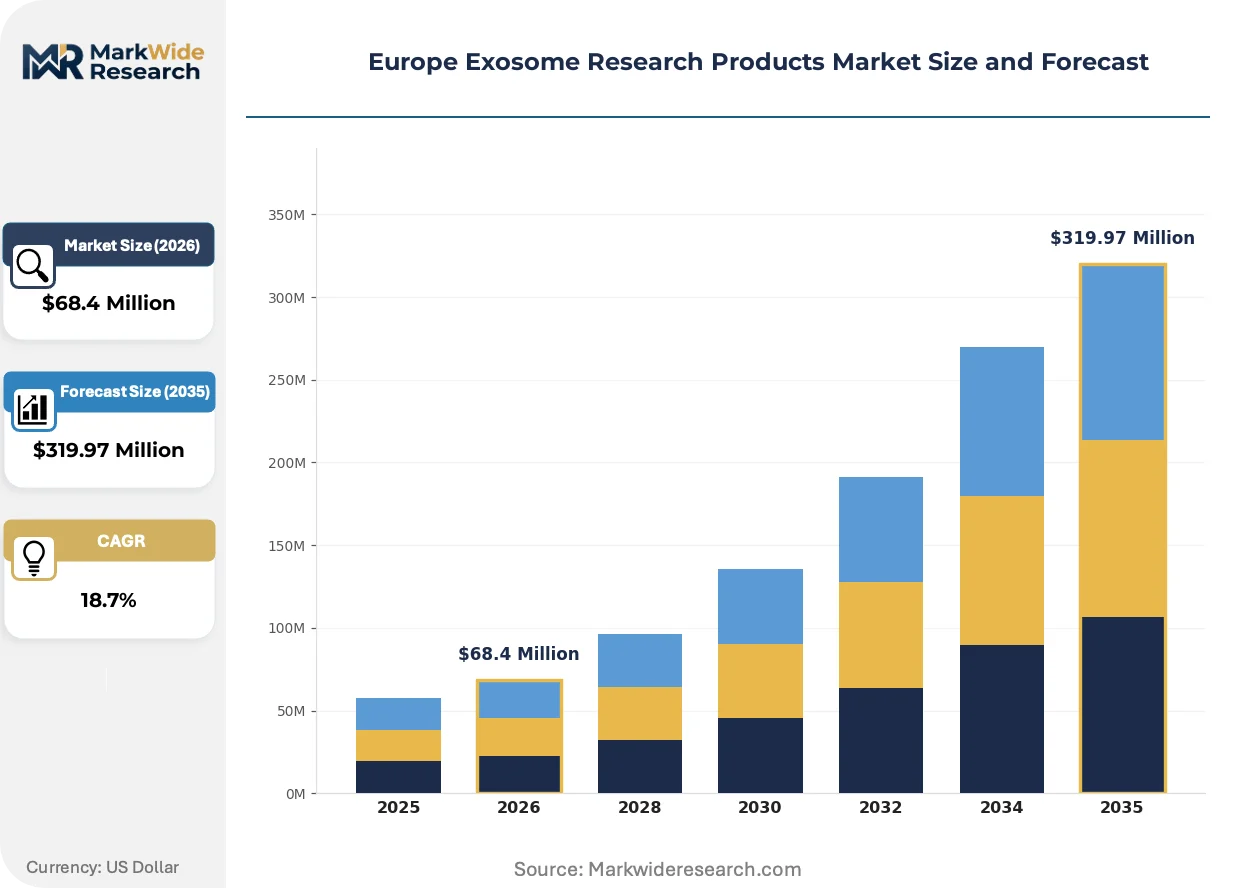
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $319.97 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exosome Isolation Kits, Exosome Characterization Kits, Exosome Analysis Instruments, Exosome Storage Solutions Application: Drug Delivery, Biomarker Discovery, Cancer Research, Regenerative Medicine End User: Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Research Laboratories Delivery Mode: Online Sales, Direct Sales, Distributors, Third-party Retailers |
| Companies Covered | Lonza Group Ltd, Miltenyi Biotec, QIAGEN N.V., Thermo Fisher Scientific Inc, Bio-Techne Corp, ReNeuron Group plc, Evox Therapeutics Ltd, EXO Biologics, Creative Proteomics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Exosome Research Products Market Shifts & Advancements
Size-exclusion chromatography automation is compressing isolation workflow timelines while regulatory pressure on diagnostic kit performance claims intensifies analytical rigor requirements.
Automated size-exclusion chromatography systems with integrated fraction collection and real-time UV-Vis monitoring are supplanting manual ultracentrifugation protocols in high-throughput academic screening operations. Core facilities at Dutch and Belgian universities have adopted these platforms to reduce operator time per sample from four hours to under thirty minutes. This shift is compressing the addressable market for benchtop ultracentrifuge consumables while expanding recurring revenue streams for pre-packed chromatography columns.
REACH substance authorization requirements for persistent organic pollutants are tightening supply chain scrutiny on fluorophore compounds used in exosome labeling workflows. ECHA's 2023 restriction proposals on per- and polyfluoroalkyl substances have forced reformulation of several commercial nanoparticle tracking analysis reagents. Kit manufacturers serving regulated therapeutic development pipelines are responding by qualifying alternative dye chemistries and submitting updated safety data sheets ahead of enforcement deadlines.
Consortium-based procurement through European research infrastructure networks is displacing individual laboratory purchasing for high-value analysis instruments. The Euro-BioImaging and EATRIS distributed infrastructure programs negotiate centralized service contracts for multiplexed detection platforms, concentrating vendor selection decisions at the network governance level. This pattern is most visible in Nordic countries and the Netherlands, where national funding agencies mandate participation in pan-European research infrastructure initiatives as a condition of capital equipment grants.
Europe Exosome Research Products Market Segmentation
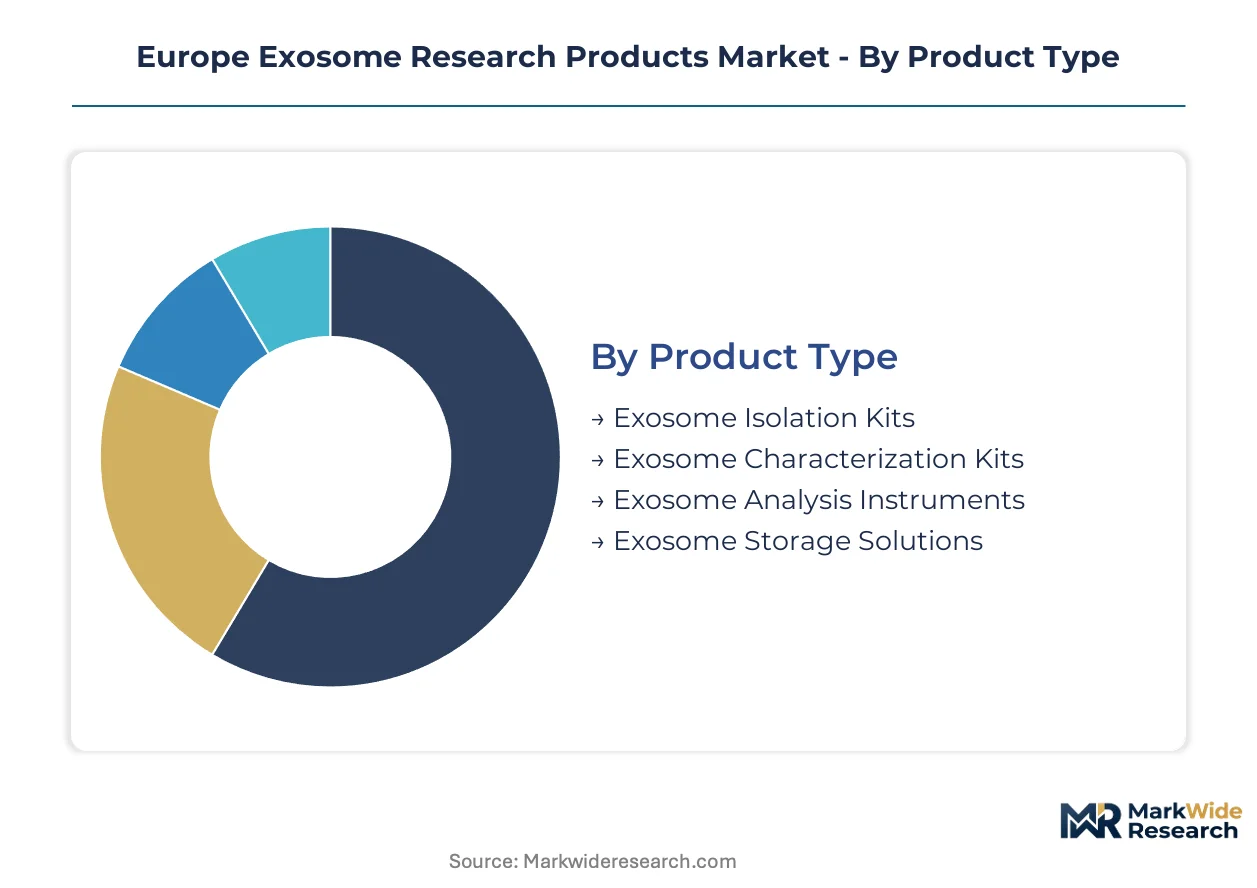
Exosome research products serve heterogeneous workflows across discovery and therapeutic development, with procurement patterns diverging sharply between exploratory academic screening and regulated pharmaceutical manufacturing. Segmentation reveals how regulatory pressure, automation requirements, and funding sources reshape vendor access across product categories.
Product Type:
CE marking under EU IVDR bifurcates kit suppliers into qualified diagnostic-grade providers and research-use-only vendors, concentrating procurement among documented performers.
- Exosome Isolation Kits:Precipitation-based and size-exclusion chromatography formats dominate European procurement, with German Max Planck Institutes and Helmholtz centers driving recurring purchase volumes tied to protocol standardization mandates. REACH compliance on reagent formulations adds qualification overhead that favors established suppliers with dedicated regulatory affairs teams.
- Exosome Analysis Instruments:Nanoparticle tracking analyzers and single-particle interferometry platforms displace western blotting in high-throughput operations. Dutch and Belgian core facilities have compressed per-sample processing from four hours to thirty minutes through automation, pulling demand toward integrated detection systems with multi-parameter readout capability.
- Exosome Characterization Kits:Surface marker profiling and cargo analysis reagents face IVDR clinical evidence requirements that extend certification timelines beyond typical development cycles.
- Exosome Storage Solutions:Cryopreservation media and stabilizing buffers support biobanking workflows across academic and commercial repositories.
Exosome Isolation Kits handle the majority of throughput; Exosome Analysis Instruments is the fastest mover on share.
Application:
Funding concentration determines segment hierarchy, with pharmaceutical sponsorship concentrating in high-margin therapeutic development while academic grants sustain discovery-phase biomarker work.
- Drug Delivery:Engineered exosome programs for oncology and rare disease indications command premium pricing for GMP-compatible characterization and quality control consumables. EMA scientific advice pathways de-risk therapeutic pipelines, sustaining reagent demand from sponsors seeking qualified supply chains.
- Cancer Research:Liquid biopsy development for early detection and monitoring applications drives multiplexed detection platform adoption. French ANSM maintains flexible scientific advice frameworks for academic spinouts developing diagnostic-grade assays, accelerating translation timelines.
- Biomarker Discovery:Exploratory profiling of exosomal RNA and protein cargo supports precision medicine initiatives across European research infrastructure networks.
- Regenerative Medicine:Cell-free therapeutic approaches leverage exosome-mediated intercellular communication for tissue repair applications.
Drug Delivery captures the highest margin pools; Cancer Research is expanding most quickly as diagnostic-grade assay development accelerates.
End User:
Procurement authority and technical specification requirements diverge between grant-funded academic laboratories and sponsor-backed pharmaceutical operations.
- Academic Institutions:Max Planck Institutes, Helmholtz centers, and university core facilities generate concentrated demand for isolation and analysis workflows. Euro-BioImaging and EATRIS infrastructure programs consolidate vendor selection at network governance levels, particularly in Nordic countries and the Netherlands where national funding agencies mandate pan-European participation.
- Pharmaceutical Companies:Engineered exosome manufacturing for therapeutic development requires GMP-compatible protocols and documented supply chains. Swissmedic's streamlined advanced therapy medicinal product designation attracts developers seeking faster European market access.
- Biotechnology Firms:Mid-stage developers bridge discovery and clinical phases, pulling through hybrid procurement patterns.
- Research Laboratories:Contract research and dedicated screening operations sustain demand for standardized kit formats.
Academic Institutions handle the majority of throughput; Pharmaceutical Companies is climbing the fastest on procurement value.
Delivery Mode:
Channel configuration reflects customer scale and technical support requirements, with direct relationships dominating high-value instrument placements.
- Direct Sales:Pan-European distribution infrastructure sustains shelf presence for complex instrumentation and high-volume consumables in major research clusters. Field application scientists support workflow integration and protocol optimization.
- Distributors:National and regional partners serve fragmented academic accounts with localized inventory and technical service capabilities.
- Online Sales:Standardized kits and reagents move through e-commerce portals for routine replenishment.
- Third-party Retailers:Limited role in specialized exosome research products due to technical consultation requirements.
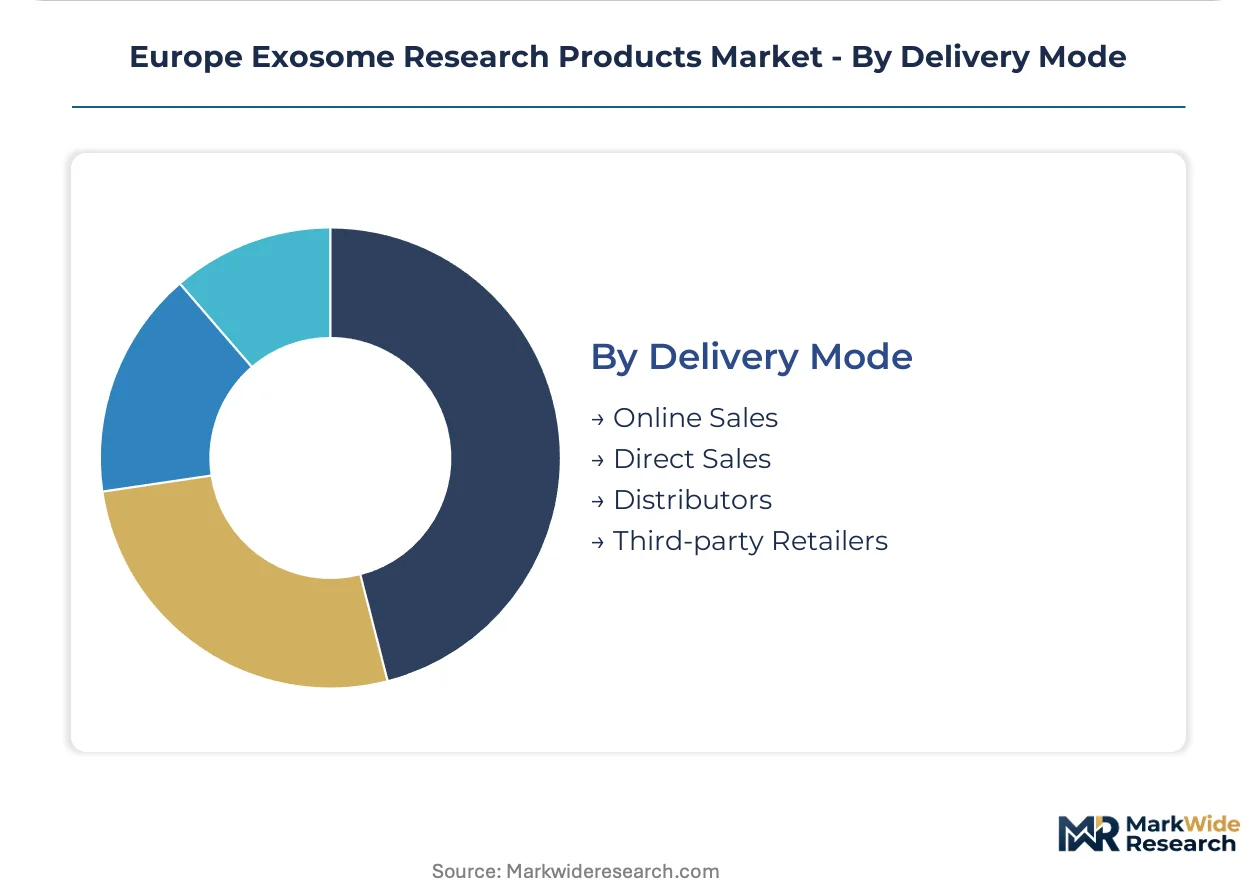
Direct Sales handles the majority of throughput; Distributors is gaining share fastest as procurement consolidates through infrastructure networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU research infrastructure funding and national biotechnology initiatives are concentrating procurement authority within networked academic consortia and pharmaceutical manufacturing hubs across the continent.
Germany
Max Planck Institutes and Helmholtz centers in Munich, Heidelberg, and Berlin drive concentrated demand for isolation kits and analysis workflows. REACH compliance requirements on reagent formulations favor established suppliers with dedicated regulatory affairs teams. Bavaria's biotechnology corridor anchors GMP-compatible exosome manufacturing scale-up for therapeutic programs.
France
ANSM maintains flexible scientific advice frameworks for academic spinouts developing diagnostic-grade exosome assays, accelerating translation timelines from biomarker discovery to clinical validation. The Île-de-France research cluster concentrates liquid biopsy development operations. Paris-Saclay University's core facilities have adopted automated size-exclusion chromatography platforms, compressing per-sample processing timelines.
United Kingdom
London and Cambridge biotech corridors sustain demand for engineered exosome characterization reagents tied to oncology drug delivery programs. The Medicines and Healthcare products Regulatory Agency's alignment with EMA scientific advice pathways de-risks therapeutic development pipelines. Oxford and Imperial College core facilities participate in Euro-BioImaging infrastructure procurement, consolidating vendor selection at network governance levels.
Netherlands
Dutch universities and Belgian core facilities have compressed isolation workflows from four hours to thirty minutes through automated chromatography adoption. National funding agencies mandate participation in EATRIS and Euro-BioImaging pan-European research infrastructure initiatives as a condition of capital equipment grants. The Leiden biotech cluster anchors exosome-mediated regenerative medicine research programs.
Switzerland
Swissmedic's streamlined advanced therapy medicinal product designation attracts engineered exosome developers seeking faster European market access. Basel's pharmaceutical manufacturing density sustains demand for GMP-compatible quality control consumables. ETH Zurich and University of Geneva core facilities generate procurement volumes for multiplexed detection platforms serving precision medicine initiatives.
Europe Exosome Research Products Market Competitive Landscape
Player mix skews toward diversified life sciences conglomerates with pan-European distribution infrastructure, supplemented by specialized bioproduction service providers and nucleic acid purification heritage companies. Market structure concentrates procurement authority among qualified kit suppliers holding CE marking under EU IVDR, while unverified entrants face exit pressure from diagnostic-grade segments. Strategic archetypes include captive bioproduction extenders, distribution-anchored shelf-presence players, and regulatory compliance aggregators. Dominant competitive moves encompass infrastructure network partnerships and REACH-compliant reagent portfolio qualification.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc and QIAGEN N.V. exemplify distribution-anchored and nucleic acid heritage positioning respectively. Lonza Group Ltd occupies the captive bioproduction extender archetype, leveraging manufacturing workflow expertise into exosome-related service offerings. These three entities represent distinct strategic vectors: pan-European field application scientist networks, purification protocol intellectual property, and GMP-compatible scale-up infrastructure.
| Leading Market Players |
|---|
| Lonza Group Ltd |
| Miltenyi Biotec |
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc |
| Bio-Techne Corp |
| ReNeuron Group plc |
| Evox Therapeutics Ltd |
| EXO Biologics |
| Creative Proteomics |
| Others |
Supply & Pricing Matrix
CE marking under the EU In Vitro Diagnostic Regulation gates both supplier qualification and price differentiation, bifurcating kit vendors into premium diagnostic-grade providers and discounted research-use-only alternatives while concentrating procurement authority among documented performers with dedicated regulatory affairs teams.
Pricing Analysis
Certification level creates the primary spread between qualified CE-marked characterization kits and research-grade alternatives. Three-tier pricing structure across diagnostic-grade, pre-clinical, and exploratory levels reflects IVDR clinical evidence investments, with pharmaceutical sponsors absorbing premium positioning for GMP-compatible workflows while academic laboratories gravitate toward economy tiers. Cost compression in mid-grade isolation kits intensifies because REACH-compliant reagent reformulations add qualification overhead. Biotechnology firms exhibit highest price sensitivity due to grant-dependent funding cycles.
Supply Chain Analysis
Extended lead times for high-speed ultracentrifuge rotors from German and Swiss precision engineering suppliers constrain equipment availability for core facility expansions. Manufacturing concentrates in Germany, Switzerland, and the Netherlands for chromatography systems, while fluorophore compounds draw from specialized chemical suppliers facing ECHA restriction proposals. Single-source vulnerability concentrates in rotor manufacturing, with no qualified secondary sources for therapeutic-grade GMP applications. Distribution runs through pan-European field application scientist networks for complex instrumentation, with national distributors serving fragmented academic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU regulatory fragmentation creates white-space opportunities as IVDR implementation timelines diverge across member states, enabling niche specialists to capture underserved diagnostic-grade assay development segments before consolidation accelerates.
For Market Incumbents: Consolidate procurement relationships through Euro-BioImaging and EATRIS infrastructure network partnerships, locking in multi-year service contracts before qualification requirements harden. Deepen captive bioproduction capabilities to capture engineered exosome manufacturing workflows, as Lonza Group Ltd has demonstrated. Threat substitution from automated chromatography platforms demands rapid ultracentrifuge consumable portfolio repositioning toward premium rotor maintenance services. For New Entrants and Emerging Players: GMP-compatible protocol training services represent an under-served layer where incumbents lack dedicated personnel deployment. France's ANSM flexible scientific advice frameworks offer the most penetrable regulatory entry point for academic spinouts developing diagnostic-grade assays. Target mid-tier biotechnology firms in the Leiden and Basel clusters with hybrid research-to-GMP transition support bundles. For Investors and Strategic Acquirers: EMA qualification opinions on extracellular vesicle reference standards reshape the acquisition landscape, elevating kit manufacturers with validated protocols toward strategic premium. Long-term viability centers on regulatory compliance aggregation capabilities rather than raw technology differentiation. Target acquisition candidates combine CE-marked portfolios with active EMA scientific advice engagements. Signal concentration: monitor EMA publication of qualification opinions for reference material standardization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | IVDR clinical evidence generation secures diagnostic-grade kit market access before consolidation accelerates. |
| Research Infrastructure Partnership | Euro-BioImaging network contracts concentrate vendor selection authority at governance levels across Nordic and Dutch facilities. |
| REACH-Compliant Reagent Qualification | Alternative dye chemistry portfolios preempt ECHA enforcement deadlines on per- and polyfluoroalkyl substance restrictions. |
| GMP Manufacturing Scale-Up | Swissmedic advanced therapy medicinal product designation attracts engineered exosome developers seeking faster European access. |
| Multiplexed Detection Platform Launch | Single-particle interferometry with next-generation sequencing integration displaces western blotting in high-throughput operations. |
Research Methodology
Initial hypotheses were tested against primary input from exosome manufacturing directors, regulatory affairs leads at kit suppliers, core facility managers at Max Planck Institutes, and pharmaceutical sponsor procurement officers, then refined through secondary validation against EMA scientific advice pathway documentation, ECHA restriction proposal filings, Euro-BioImaging infrastructure procurement records, and REACH compliance safety data sheets. Bottom-up reagent volume estimates and top-down pharmaceutical R&D spending allocations were triangulated to constrain forecast ranges.
Variance decomposition across product type, application, end user, and delivery mode segmentation dimensions drove analytical framework construction over the projection horizon. CAGRs derived from pharmaceutical pipeline progression rates and academic infrastructure investment cycles, with engineered exosome therapeutic development intensity and IVDR implementation pace as industry-specific forecast inputs.
Underlying assumptions cover EMA qualification opinion timing, REACH enforcement consistency, and research infrastructure funding continuity, with deviation risk concentrated in regulatory standardization delays and fluorophore supply substitution failures. Revision becomes warranted when EMA reference material opinions or ECHA restriction enforcement thresholds cross predetermined uncertainty bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Lateral Flow Immunoassay (LFIA) Based Rapid Test Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Europe Serine Proteases Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Multiplex Biomarker Imaging Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Nano-Silicon Drug Delivery Platform Market
Biomedical Technology
Europe Transfection Technologies Market