
 Lipid Transfer Proteins Market | 2026-2036
Lipid Transfer Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Transfer Proteins Market Foresight
The capital-intensity divergence between large-scale chromatography equipment owners and contract research specialists is bifurcating competitive tiers in this space. Merck KGaA leverages its integrated filtration and purification portfolio to anchor high-volume pharmaceutical supply agreements. Thermo Fisher Scientific sustains broad geographic coverage through its analytical instrumentation and reagent distribution network. Bio-Rad Laboratories differentiates via specialized protein assay platforms that support LTP characterization workflows.
Lipid transfer proteins constitute a family of small, basic proteins approximately 9 kDa in size that facilitate the in vitro and in vivo movement of phospholipids, glycolipids, and fatty acids between membrane bilayers without energy-dependent transport mechanisms. These proteins serve critical functions in food processing as allergen markers, in pharmaceutical formulations as stabilizing excipients for liposomal drug delivery, and in cosmetic emulsification systems. The LTP1 and LTP2 product categories dominate current manufacturing output due to established expression systems and purification protocols. Pharmaceutical applications represent the fastest-expanding demand segment as liposomal and lipid nanoparticle therapeutics require precisely characterized transfer protein inputs. Powder and liquid forms split the market based on end-user formulation requirements, with powder formats commanding preference among food manufacturers seeking extended shelf stability.
The FDA oversees protein excipient safety through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use evaluates LTP-containing formulations under the EU's pharmaceutical quality guidelines. ISO 10993 biocompatibility testing standards further constrain material selection for medical-grade applications, elevating compliance costs for new entrants. REACH registration requirements in Europe impose additional toxicological documentation burdens on suppliers targeting cosmetic and pharmaceutical channels. Stakeholders must monitor evolving regulatory convergence between food-contact and pharmaceutical-grade protein specifications, as jurisdictional overlaps intensify qualification complexity for multi-sector suppliers.
Market Dynamics
Pharmaceutical formulation standards for protein-based excipients are tightening procurement specifications and compressing supplier qualification timelines across the value chain. The FDA's updated guidance on protein-based excipients and EMA's pharmaceutical quality guidelines are forcing manufacturers to upgrade characterization protocols and documentation systems.
Growth Catalysts
- Liposomal drug delivery expansion:Pharmaceutical firms are scaling recombinant LTP procurement for lipid nanoparticle therapeutics. Demand concentrates in Germany's biotechnology corridor around Heidelberg and Munich.
- ISO 10993 compliance:Biocompatibility testing standards for medical-grade applications are elevating material qualification requirements. Suppliers meeting these specifications capture premium positioning in pharmaceutical channels.
- REACH registration:Europe's toxicological documentation framework is consolidating supplier bases as smaller players exit due to compliance cost burdens. Surviving suppliers gain channel access across cosmetic and pharmaceutical segments.
Market Restraints
- Chromatography equipment concentration:Large-scale purification asset ownership limits contract research specialists from scaling production. Capital requirements for GMP-grade manufacturing create tiered competitive access.
- Regulatory jurisdictional overlap:Convergence between food-contact and pharmaceutical-grade protein specifications intensifies qualification complexity. Multi-sector suppliers face duplicated compliance burdens.
- Expression system limitations:Established yeast and bacterial platforms for LTP1 and LTP2 production constrain yield improvements. Alternative expression technologies remain pre-commercial for industrial scale.
Strategic Opportunities
- Cosmetic emulsification systems:Premium skincare formulations are incorporating LTPs for enhanced lipid stabilization. Suppliers with REACH-registered cosmetic-grade outputs access this adjacent demand pool.
- Food allergen detection protocols:LTP markers are expanding into validated diagnostic workflows for food safety testing. Regulatory validation in EU food safety frameworks creates standardized demand.
- Cell-free protein synthesis:Converging synthetic biology and continuous manufacturing technologies enable rapid LTP variant production. Early adopters in contract manufacturing organizations are piloting these systems.
Industry Challenges
- Analytical characterization expertise:Specialized protein assay workflows require rare technical capabilities. Talent scarcity in mass spectrometry and lipid-binding kinetics slows product development cycles.
- Multi-jurisdiction certification timelines:Parallel FDA and EMA qualification processes extend time-to-revenue for new entrants. Documentation requirements for protein excipient master files compress working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Transfer Proteins Market |
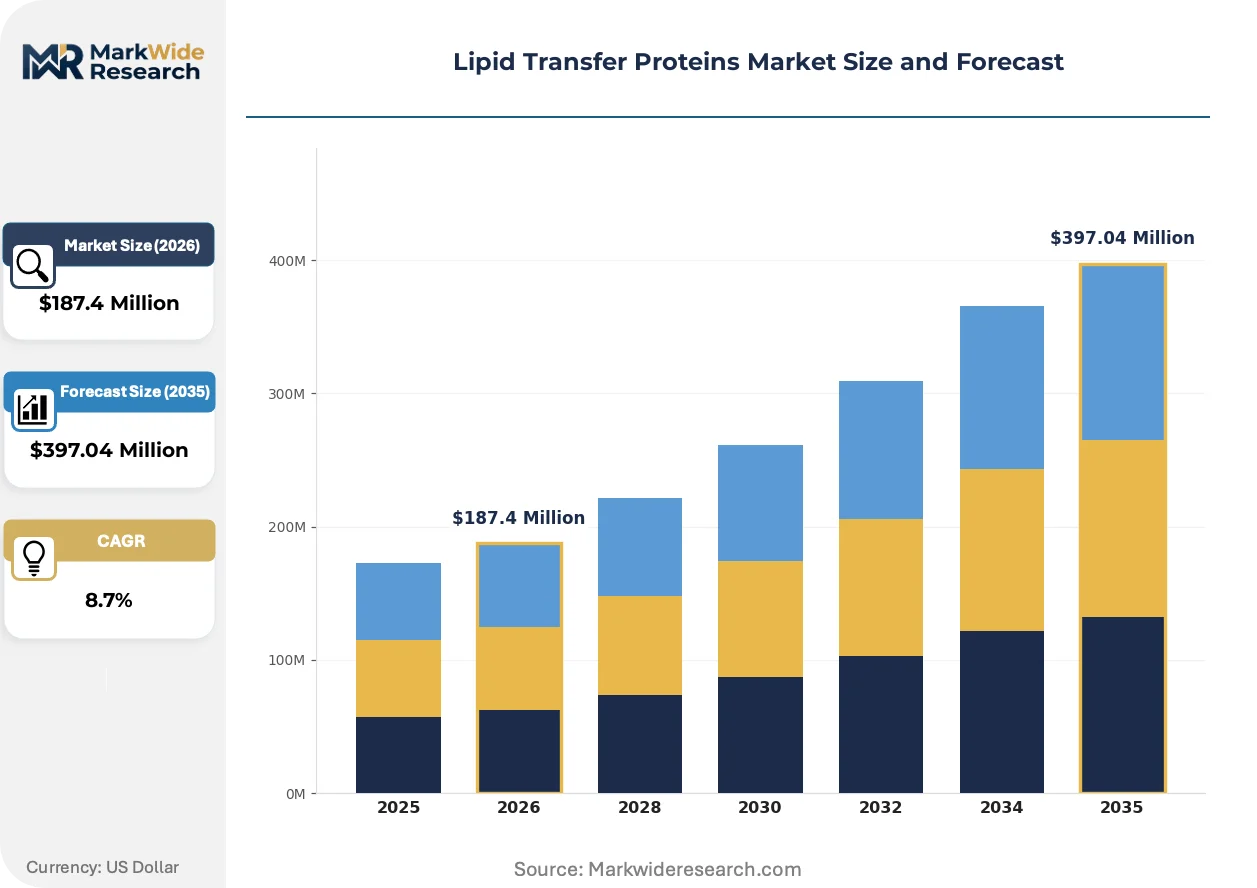
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LTP1, LTP2, LTP3, LTP4 Application: Food Industry, Pharmaceuticals, Cosmetics, Animal Feed End User: Food Manufacturers, Pharmaceutical Firms, Cosmetic Companies, Agricultural Producers Form: Liquid, Powder, Emulsion, Granule |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Bio-Rad Laboratories, GE Healthcare, PerkinElmer, Advansta, GVS, Pall Corporation, Cytiva, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Transfer Proteins Market Shifts & Advancements
Continuous processing technologies and advanced analytical platforms are restructuring how LTP variants are manufactured, characterized, and qualified for regulated applications. These shifts are compressing development timelines while elevating technical barriers to market participation.
High-resolution mass spectrometry coupled with automated lipid-binding assays is bifurcating quality assurance capabilities across the supplier base. Large pharmaceutical manufacturers are deploying these integrated platforms for in-house LTP characterization. The technology gap between integrated analytical laboratories and conventional suppliers is widening competitive positioning.
EMA's pharmaceutical quality guidelines and FDA's protein excipient guidance are converging on stricter impurity profiling requirements. Manufacturers must now document post-translational modifications and aggregation states with greater granularity. Suppliers targeting both European and US pharmaceutical channels are harmonizing qualification protocols to avoid duplicated testing.
Direct supply agreements between pharmaceutical formulators and specialized LTP producers are displacing distributor-mediated procurement in high-volume segments. Contract research organizations with captive manufacturing capabilities are capturing preferred supplier status. This channel consolidation is most visible in Germany's biotechnology clusters where proximity reduces logistics complexity for temperature-sensitive protein shipments.
Lipid Transfer Proteins Market Segmentation
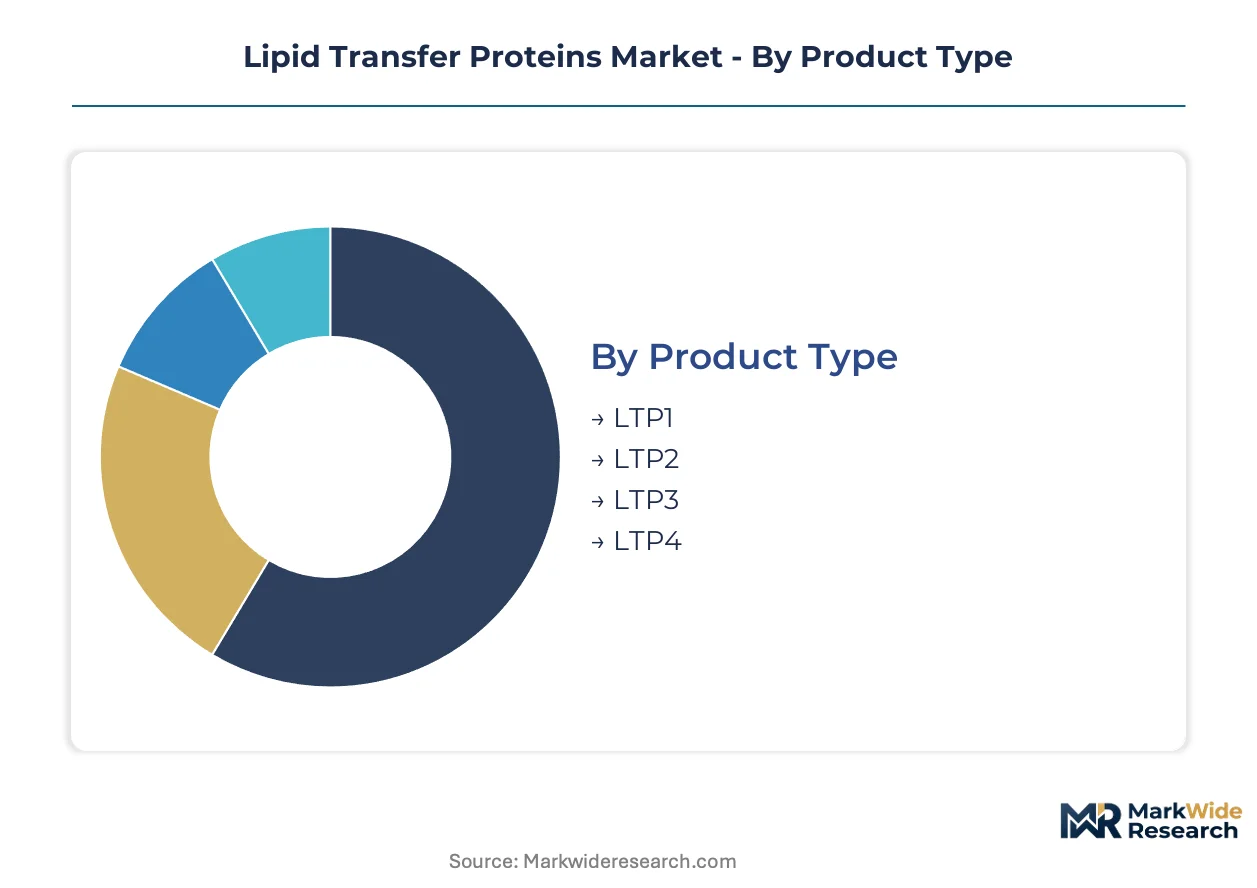
Segmentation in lipid transfer proteins reflects divergent qualification requirements across regulated industries. Pharmaceutical-grade specifications impose stricter impurity profiling than food-contact applications, creating tiered pricing and supplier access patterns. Understanding these segment boundaries enables targeted positioning for multi-sector suppliers.
Product Type:
FDA and EMA protein excipient guidance differentiates LTP variants by post-translational modification documentation requirements. Higher-grade variants demand mass spectrometry characterization that smaller producers cannot sustain.
- LTP1:The 9 kDa isoform dominates current manufacturing output through established yeast expression systems. Pharmaceutical procurement in Germany's Heidelberg-Munich corridor concentrates demand for GMP-grade LTP1 inputs in liposomal drug delivery formulations. ISO 10993 biocompatibility testing elevates material qualification costs for medical-grade applications.
- LTP2:This variant shares structural homology with LTP1 but exhibits distinct lipid-binding kinetics relevant to cosmetic emulsification. REACH-registered cosmetic-grade production in Europe accesses premium skincare formulation demand. Suppliers with dual pharmaceutical-cosmetic certification capture margin advantages across adjacent channels.
- LTP3:Emerging recombinant variants require alternative expression platforms still pre-commercial at industrial scale.
- LTP4:Research-grade applications currently dominate with limited validated manufacturing protocols.
LTP1 handles the majority of throughput; LTP2 is the fastest mover on share.
Application:
Cost tier stratification separates commodity food processing from premium pharmaceutical excipient markets. Pharmaceutical applications command 3-5x unit pricing premiums over food-grade equivalents due to documentation and testing burdens.
- Pharmaceuticals:Liposomal and lipid nanoparticle therapeutics require precisely characterized transfer protein inputs with documented aggregation states. Direct supply agreements between formulators and specialized producers are displacing distributor-mediated procurement in high-volume segments. Cell-free protein synthesis pilots in contract manufacturing organizations promise accelerated variant production timelines.
- Food Industry:LTP markers serve as validated allergen detection targets in EU food safety frameworks. Powder formats dominate procurement among manufacturers seeking extended shelf stability for processed food applications. Regulatory validation creates standardized demand pools for diagnostic workflow suppliers.
- Cosmetics:Premium skincare formulations incorporate LTPs for enhanced lipid stabilization in emulsion systems.
- Animal Feed:Agricultural producers utilize LTPs for nutrient delivery optimization with lower characterization requirements than human-grade applications.
Food Industry maintains volume leadership; Pharmaceuticals expands most quickly.
End User:
Customer type determines procurement modality and technical support intensity. Pharmaceutical firms demand captive analytical capabilities that agricultural producers do not require.
- Pharmaceutical Firms:These buyers drive recombinant LTP procurement volumes for drug delivery formulations with stringent impurity profiling requirements. In-house high-resolution mass spectrometry platforms enable direct supplier qualification, compressing third-party testing timelines. Temperature-sensitive protein shipments favor regional supplier proximity in Germany's biotechnology clusters.
- Food Manufacturers:Extended shelf stability requirements drive powder format preferences with lower unit pricing sensitivity than pharmaceutical channels. Allergen detection protocol standardization in EU frameworks creates predictable demand for LTP marker suppliers.
- Cosmetic Companies:REACH registration requirements constrain supplier bases as compliance costs eliminate smaller players.
- Agricultural Producers:Feed-grade applications tolerate broader specification ranges with minimal regulatory documentation.
Food Manufacturers represent the largest addressable base; Pharmaceutical Firms are gaining share fastest.
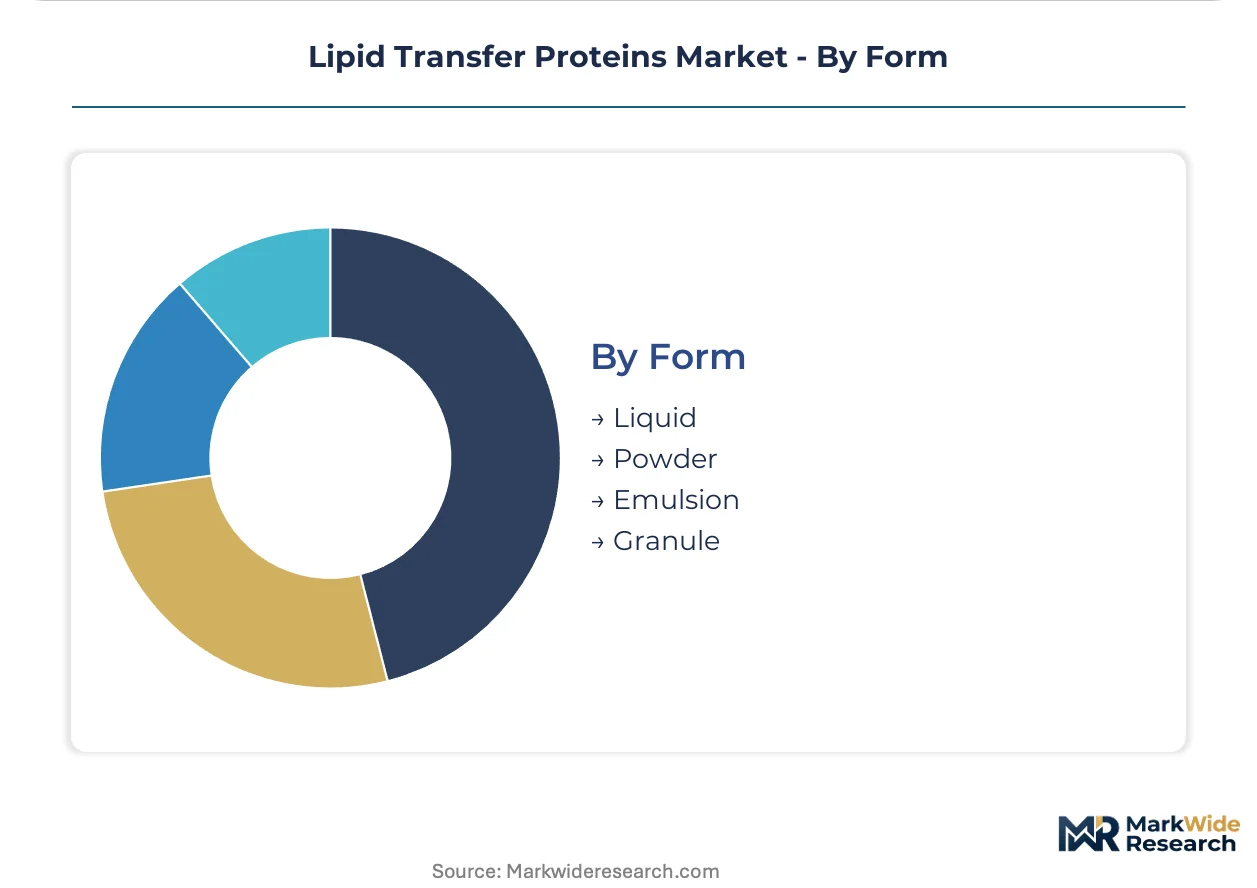
Form:
Supply concentration in large-scale chromatography equipment owners favors liquid and powder production over specialized emulsion or granule formats. Capital requirements create tiered competitive access by form type.
- Powder:Spray-dried formulations command preference among food manufacturers seeking extended shelf stability and reduced cold-chain logistics burdens. Powder production scales efficiently on existing lyophilization assets common across established suppliers. Germany's biotechnology corridor shows concentrated powder demand for export-oriented food processing.
- Liquid:Pharmaceutical formulators prefer liquid LTPs for direct incorporation into liposomal drug delivery systems without reconstitution steps. Cold-chain requirements limit geographic sourcing radius, favoring regional manufacturing proximity to Heidelberg and Munich demand centers.
- Emulsion:Cosmetic applications utilize pre-formulated emulsion systems for simplified manufacturing integration.
- Granule:Animal feed applications favor granule formats for blending compatibility with existing production lines.
Powder handles the majority of throughput; Liquid shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's biotechnology corridor while contract manufacturers in India compete on cost-sensitive food-grade volumes. The FDA's protein excipient guidance and EMA's pharmaceutical quality standards create divergent compliance cost structures across Atlantic markets. Regional procurement patterns split between pharmaceutical-grade precision and commodity food processing efficiency.
United States
Pharmaceutical firms in Greater Boston and the San Francisco Bay Area drive recombinant LTP procurement for liposomal drug delivery systems. FDA oversight through the Center for Drug Evaluation and Research mandates stringent impurity profiling for protein-based excipients. Direct supply agreements between formulators and specialized producers are displacing distributor channels in these coastal biotechnology clusters.
Germany
The Heidelberg-Munich corridor anchors European demand for GMP-grade LTP1 inputs in lipid nanoparticle therapeutics. REACH registration requirements under ECHA jurisdiction impose toxicological documentation burdens that consolidate supplier bases. Temperature-sensitive protein shipments favor regional manufacturing proximity, with contract research organizations capturing preferred supplier status.
Switzerland
Swissmedic-regulated pharmaceutical quality standards attract premium excipient suppliers serving multinational drug formulators. Basel and Zurich house concentrated analytical instrumentation capabilities for LTP characterization workflows. Suppliers meeting Swiss biocompatibility specifications access margin advantages across adjacent EU pharmaceutical channels.
India
CDSCO-registered contract manufacturers compete on yeast-expression LTP production for food allergen detection markets. FSSAI food safety frameworks standardize demand for LTP markers in processed food exports from Maharashtra and Gujarat. Powder format production scales efficiently on existing lyophilization assets serving domestic and Middle Eastern food processing customers.
China
NMPA pharmaceutical guidelines and GB standards bifurcate domestic supply between medical-grade and food-contact applications. Yangtze River Delta biopharmaceutical clusters pilot cell-free protein synthesis for rapid LTP variant production. Shanghai-based analytical service providers are deploying high-resolution mass spectrometry platforms for in-house supplier qualification.
Lipid Transfer Proteins Market Competitive Landscape
Concentration sits with diversified life science conglomerates owning integrated filtration and purification portfolios. The supplier base fragments between chromatography equipment owners and specialized assay platform developers. Strategic archetypes include scale-driven pharmaceutical supply anchors, analytical instrumentation distributors, and protein characterization workflow specialists. Capacity expansion in Germany's biotechnology corridor and strategic partnerships for REACH-registered cosmetic-grade outputs represent dominant competitive moves.
Among diversified conglomerates, Merck KGaA exemplifies the integrated filtration and purification archetype, while Thermo Fisher Scientific occupies the analytical instrumentation and reagent distribution position. Bio-Rad Laboratories represents the specialized protein assay platform tier supporting characterization workflows. These three anchors illustrate how competitive positioning splits between captive manufacturing capabilities and distributed analytical service networks.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| GE Healthcare |
| PerkinElmer |
| Advansta |
| GVS |
| Pall Corporation |
| Cytiva |
| Others |
Supply & Pricing Matrix
Cell-free protein synthesis adoption in contract manufacturing organizations is displacing traditional yeast-expression platforms, simultaneously shifting production geography toward Germany's biotechnology corridor and compressing cost structures for rapid LTP variant development. This substitution dynamic concentrates pricing power with suppliers mastering continuous manufacturing technologies while marginalizing conventional batch producers.
Pricing Analysis
The customization-premium spread separates GMP-grade pharmaceutical LTP1 configured to precise impurity specifications from standard food-grade powder formats. Three-tier pricing structure across premium pharmaceutical, standard cosmetic, and economy food-contact levels reflects documentation burden differentials. Cost compression in food-grade segments intensifies because Indian contract manufacturers compete on yeast-expression scale. Pharmaceutical firms show least price sensitivity due to liposomal drug delivery performance requirements.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive liquid LTP shipments from Heidelberg and Munich to Swiss and US pharmaceutical clusters hinge on cold-chain container availability across North Atlantic trade lanes. Supply concentrates in Germany, Switzerland, and India, with raw material dependencies on chromatography resins, expression media, and lipid assay reagents. Single-source vulnerability around GMP-grade filtration equipment ownership constrains new entrant scaling. Distribution runs through direct supply agreements between specialized producers and pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against synthetic lipid stabilizers and cell-free manufacturing platforms that threaten established recombinant production economics.
For Market Incumbents: Compound analytical service capabilities through integrated mass spectrometry and lipid-binding assay platforms to defend against synthetic stabilizer substitution. Secure REACH-registered cosmetic-grade capacity additions in Germany's biotechnology corridor to capture adjacent premium skincare demand. Channel control through direct pharmaceutical supply agreements limits distributor-mediated price erosion. For New Entrants and Emerging Players: FDA protein excipient master file fast-track programs offer regulatory entry points for specialized LTP characterization workflows. White-space concentration exists in food allergen detection protocol validation for EU FSSAI frameworks. Cosmetic emulsification systems in REACH-registered European markets present the most penetrable segment. Go-to-market through contract research organizations with captive manufacturing capabilities accelerates qualification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding GMP-grade chromatography infrastructure in Germany. Long-term viability centers on cell-free synthesis technology maturation and pharmaceutical liposomal delivery expansion. Acquisition targets feature dual pharmaceutical-cosmetic certification with analytical instrumentation integration. The signal to watch is FDA-EMA regulatory convergence on impurity profiling requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Captures pharmaceutical procurement volumes from Heidelberg-Munich lipid nanoparticle developers. |
| REACH Cosmetic-Grade Registration | Opens premium skincare formulation channels across ECHA-regulated European markets. |
| Cell-Free Synthesis Pilot Investment | Accelerates LTP variant production timelines for contract manufacturing organizations. |
| Analytical Platform Integration | Enables direct pharmaceutical customer qualification through mass spectrometry capabilities. |
| Food Allergen Detection Partnership | Validates LTP marker protocols for EU FSSAI-standardized diagnostic workflows. |
Research Methodology
A standing panel of pharmaceutical formulation scientists, regulatory affairs specialists, contract manufacturing procurement managers, and analytical instrumentation vendors provided ongoing calibration throughout data collection. Primary interviews with these stakeholders combined with secondary validation from FDA protein excipient guidance documents, EMA pharmaceutical quality guidelines, ISO 10993 biocompatibility standards, and REACH toxicological registration databases. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled product type, application, end user, and form segmentation dimensions with regional regulatory cluster overlays. CAGRs derived from fitted growth curves incorporating pharmaceutical liposomal delivery expansion rates, cosmetic emulsification system adoption patterns, and food allergen detection protocol standardization timelines.
Underlying assumptions cover regulatory stability in FDA and EMA protein excipient frameworks, with deviation risk concentrated in cell-free synthesis technology commercialization pace and synthetic lipid stabilizer performance improvements. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Protein Expression Technology Market
Biomedical Technology
Neoantigen Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Nucleic Acid Electrophoresis and Blotting Market
Biomedical Technology
Human Reproductive Technologies Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Tissue Clearing Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Rat and Mouse Model Market