
 DNA Forensics Market | 2026-2036
DNA Forensics Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Forensics Market Analysis
The capability gap between high-throughput sequencing infrastructure and legacy capillary electrophoresis systems is unwinding competitive dynamics across the sector. Thermo Fisher Scientific leverages its integrated reagent-to-instrument portfolio to dominate contract forensic laboratories. Illumina sustains technology leadership in whole genome sequencing applications for complex kinship analysis. QIAGEN anchors its position through specialized DNA extraction chemistries that reduce contamination risk in degraded samples.
DNA forensics encompasses the collection, extraction, amplification, and analysis of genetic material from biological evidence to establish identity, kinship, or biological source attribution with statistical certainty. The discipline relies on polymerase chain reaction amplification of short tandem repeat loci, typically 13-20 core loci, generating probability-of-match statistics that meet Daubert evidentiary standards. STR analysis remains the workhorse methodology for criminal DNA databasing, while whole genome sequencing commands premium pricing in disaster victim identification where fragmented remains challenge conventional approaches. Mitochondrial DNA sequencing occupies a specialized niche for maternal lineage tracing in historical or highly degraded specimens. Software platforms represent an emerging margin pool as laboratories seek automated interpretation pipelines for complex mixture deconvolution.
The FBI's Quality Assurance Standards and the DNA Identification Act shape laboratory accreditation requirements and dictate which technologies qualify for federal database uploads. The European Network of Forensic Science Institutes enforces ENFSI guidelines that create divergent validation protocols across Atlantic markets. Stakeholders must monitor legislative momentum around familial search restrictions and rapid DNA statutory frameworks, as these policy inflection points will determine which product architectures capture the next wave of institutional procurement cycles.
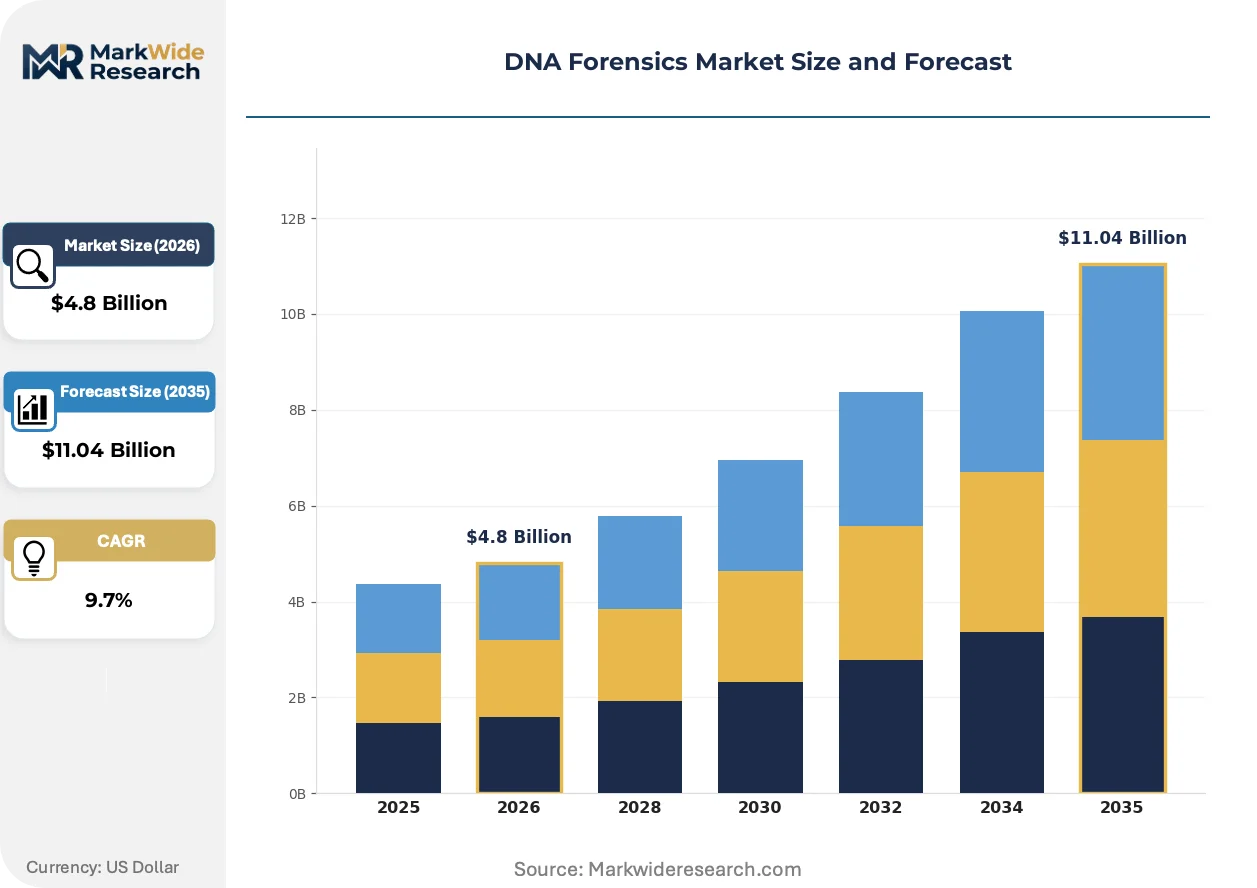
Market Dynamics
The transition from capillary electrophoresis to massively parallel sequencing platforms is compressing turnaround times while fragmenting laboratory procurement patterns. Federal mandates for rapid DNA processing are forcing infrastructure upgrades that favor integrated workflow solutions over point-product purchasing.
Growth Catalysts
- CODIS Database Expansion:The FBI's mandated upload requirements for forensic profiles are driving replacement cycles in state crime laboratories across the United States.
- Cold Case Backlogs:Law enforcement agencies are prioritizing genetic genealogy approaches to resolve dormant investigations, creating sustained demand for kinship analysis capabilities.
- Rapid DNA Statutes:Legislative frameworks permitting booking-station analysis are expanding the addressable market beyond centralized laboratories into field-deployable applications.
Market Restraints
- Reagent Supply Concentration:Proprietary chemistries for STR amplification remain concentrated among a handful of specialized suppliers, creating single-source vulnerability.
- Validation Burden:ENFSI guidelines in Europe impose divergent quality assurance protocols that fragment product development roadmaps.
- Substitution from Biometric Surveillance:Facial recognition and digital identity systems are capturing budget share in border security and immigration applications.
Strategic Opportunities
- Disaster Victim Identification:Fragmented remains from mass casualty events are creating demand for whole genome sequencing where conventional STR analysis fails.
- Direct-to-Consumer Genealogy Crossover:Consumer database participation is enabling familial search methodologies that expand investigative reach beyond government repositories.
- Environmental DNA Forensics:Wildlife trafficking enforcement and biosecurity monitoring represent underpenetrated applications for species-level genetic attribution.
Industry Challenges
- Mixture Interpretation Expertise:Complex DNA profiles from multiple contributors require specialized bioinformatics training that outpaces current workforce supply.
- Legacy System Integration:LIMS migration from capillary electrophoresis data formats to sequencing-native architectures creates operational friction during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Forensics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: STR Analysis, Mitochondrial DNA Sequencing, Single Nucleotide Polymorphism, Whole Genome Sequencing Application: Criminal Investigations, Paternity Testing, Disaster Victim Identification, Genetic Research End User: Law Enforcement Agencies, Forensic Laboratories, Academic Institutions, Private Investigators Product Type: Reagents, Kits, Instruments, Software |
| Companies Covered | Illumina, Agilent Technologies, Thermo Fisher Scientific, Bode Technology, Eurofins Scientific, QIAGEN, LGC Limited, Othram, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Forensics Market Emerging Trajectories
Workflow automation and artificial intelligence interpretation tools are compressing analytical timelines while elevating the technical threshold for laboratory entry. These shifts are redrawing competitive boundaries between instrument manufacturers, reagent suppliers, and software specialists.
Rapid DNA instrumentation is fragmenting the traditional laboratory model by enabling analysis at point-of-collection sites. Booking stations and border checkpoints are adopting suitcase-sized systems that return STR profiles within two hours. This capability is compressing the market for centralized batch processing while creating demand for ruggedized hardware and simplified chemistries.
The European Union's AI Act is imposing risk-classification requirements on algorithmic interpretation tools used for evidentiary reporting. Automated mixture deconvolution software now faces conformity assessment obligations that delay product launches. Forensic laboratories in Germany and France are responding by demanding vendor documentation of training data provenance and bias auditing protocols.
Service unbundling is separating instrument ownership from analytical execution. Smaller police departments are abandoning in-house DNA units in favor of regional hub-and-spoke arrangements with private contractors. This pattern concentrates procurement authority among contract laboratory networks in Texas and Florida while fragmenting demand across equipment vendors.
DNA Forensics Market Segmentation
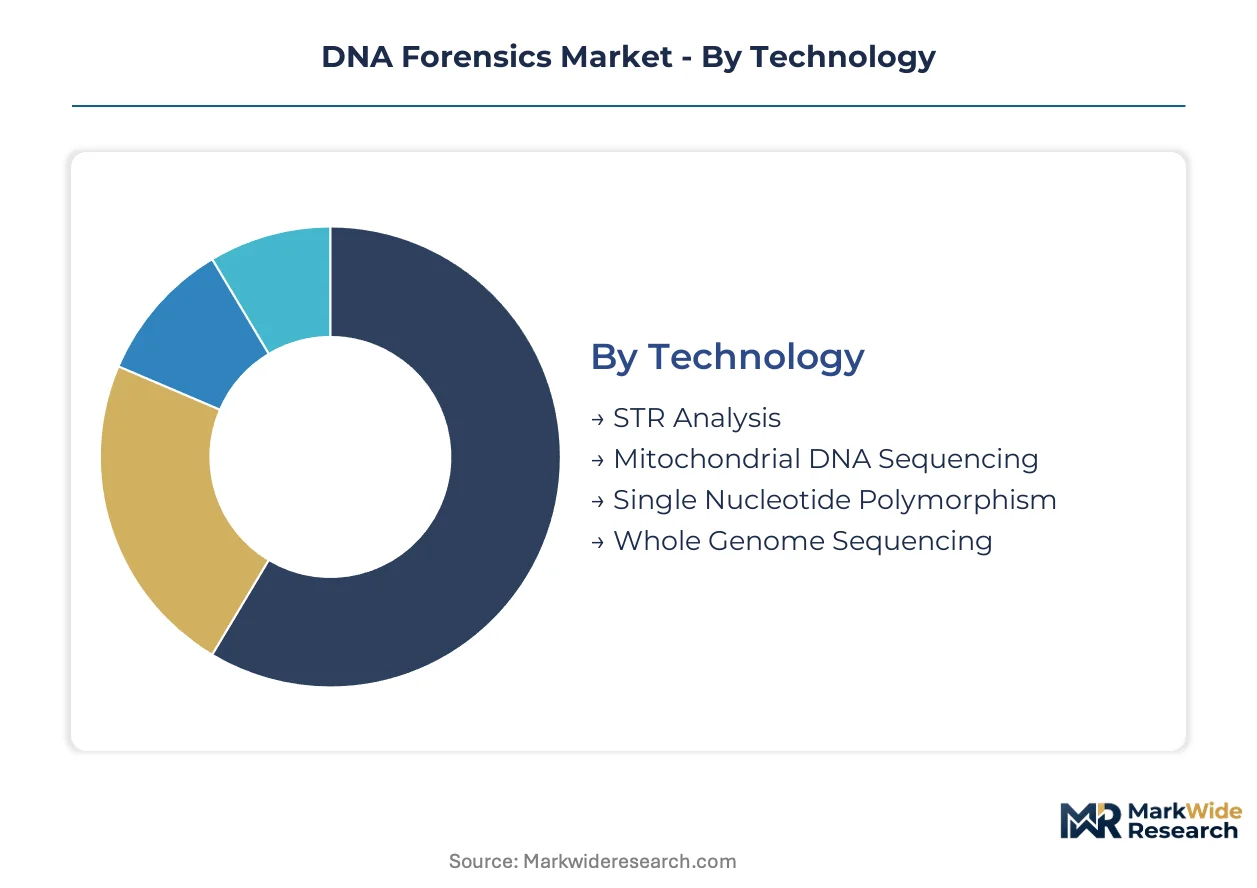
Segmentation in DNA forensics reveals how procurement authority concentrates among contract laboratory networks while technology choices fragment across use cases. Channel dynamics differ sharply between centralized crime laboratories and emerging point-of-collection deployments.
Technology:
Channel mix varies by technical complexity: STR analysis flows through established distributor relationships with state crime labs, while whole genome sequencing concentrates in specialized service providers and academic medical centers.
- STR Analysis:Polymerase chain reaction amplification of 13-20 core short tandem repeat loci generates probability-of-match statistics for criminal DNA databasing. State laboratories in Texas and Florida concentrate procurement for CODIS-compliant workflows, driven by FBI-mandated upload requirements.
- Whole Genome Sequencing:Massively parallel sequencing platforms deliver complete genetic profiles for complex kinship analysis and disaster victim identification where fragmented remains challenge conventional approaches. Academic medical centers and federal mass casualty response teams anchor demand.
- Mitochondrial DNA Sequencing:Maternal lineage tracing for historical or highly degraded specimens.
- Single Nucleotide Polymorphism:Point mutation detection for ancestry inference and phenotypic prediction.
By volume, STR Analysis leads. By growth pace, Whole Genome Sequencing is ahead.
Application:
Cost tier segmentation separates premium-priced disaster victim identification from standardized criminal casework, with paternity testing occupying a commoditized middle layer.
- Criminal Investigations:DNA profiling for suspect identification, exclusion, and database matching under chain-of-custody protocols. Cold case backlogs across US state laboratories sustain replacement cycles for capillary electrophoresis infrastructure.
- Disaster Victim Identification:Fragmented remains analysis requiring whole genome sequencing and specialized bioinformatics when conventional STR methods fail. Federal emergency response frameworks trigger episodic but high-value procurement.
- Paternity Testing:Kinship establishment for legal and immigration proceedings.
- Genetic Research:Population studies and ancestry inference for academic institutions.
Criminal Investigations commands the largest revenue pool. Disaster Victim Identification shows the steepest expansion trajectory.
End User:
Customer type determines purchasing modality: law enforcement agencies favor rapid DNA statutes and field-deployable systems, while forensic laboratories prioritize batch throughput and LIMS integration.
- Law Enforcement Agencies:Police departments and sheriff's offices adopting booking-station DNA analysis under rapid DNA legislative frameworks. Procurement concentrates in jurisdictions with statutory authorization for point-of-collection testing.
- Forensic Laboratories:Centralized state and regional facilities performing high-volume casework under FBI Quality Assurance Standards. CODIS database expansion mandates drive instrument replacement cycles.
- Academic Institutions:Research universities conducting population genetics and method validation studies.
- Private Investigators:Independent practitioners accessing consumer genealogy databases for familial search.
Forensic Laboratories dominate current installed base. Law Enforcement Agencies are gaining share fastest.
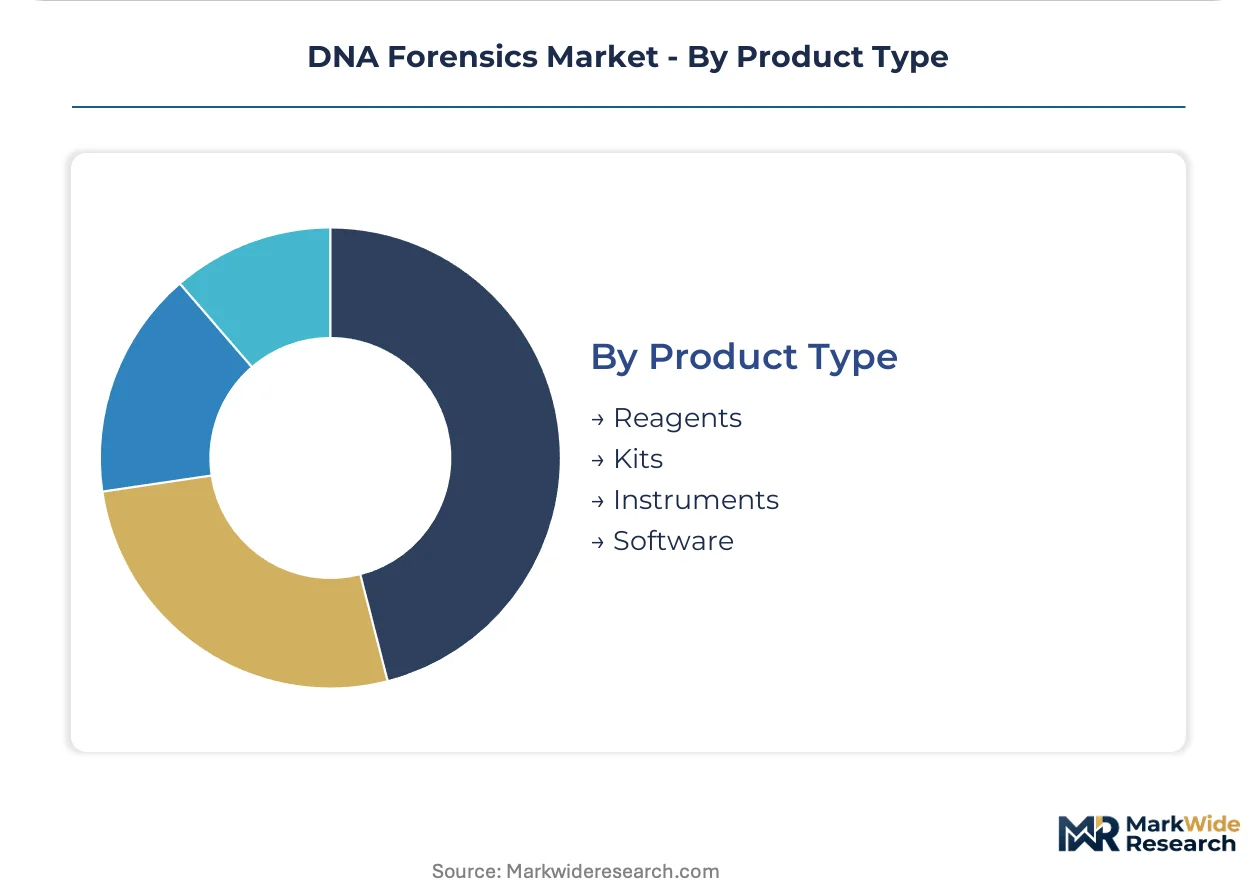
Product Type:
Margin structure inverts across the value chain: reagents and kits generate recurring revenue streams, while instruments command upfront capital expenditure and software emerges as a contested margin pool.
- Reagents:Proprietary chemistries for DNA extraction, amplification, and purification that reduce contamination risk in degraded samples. Specialized formulations for STR amplification remain concentrated among limited suppliers.
- Software:Automated interpretation pipelines for complex mixture deconvolution and LIMS integration. The EU AI Act imposes conformity assessment obligations that delay product launches in European markets.
- Instruments:Capillary electrophoresis and sequencing platforms for analytical execution.
- Kits:Bundled consumable sets for standardized workflow execution.
Reagents capture the highest recurring revenue share. Software is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as federal grants sustain premium procurement, while European laboratories face sharper budget constraints under fragmented national funding regimes. Emerging markets in Asia-Pacific exhibit intermediate sensitivity, prioritizing rapid DNA capabilities over comprehensive sequencing infrastructure.
United States
The FBI's CODIS database expansion and rapid DNA statutory frameworks drive sustained instrument replacement cycles across state crime laboratories. Federal grants through the Department of Justice's forensic infrastructure programs reduce procurement price sensitivity. Texas and Florida host the densest concentrations of contract forensic laboratories, where hub-and-spoke service models concentrate purchasing authority among private operators.
Germany
ENFSI guidelines impose divergent validation protocols that fragment product development roadmaps for manufacturers serving European markets. The Federal Criminal Police Office enforces quality assurance standards that exceed baseline EU requirements, elevating technical barriers to entry. Berlin-Brandenburg and Bavaria anchor the country's forensic laboratory network, where regional hubs coordinate casework for smaller police departments.
United Kingdom
Privatization of forensic services has concentrated procurement among a handful of contract providers, compressing margins for equipment vendors. The Forensic Science Regulator mandates accreditation standards that shape technology adoption timelines. London and the Southeast dominate service capacity, though regional hubs in Manchester and Birmingham retain specialized capabilities for complex kinship analysis.
China
Public security bureaus are expanding DNA databasing infrastructure under national surveillance modernization programs, creating demand for high-throughput sequencing platforms. The Ministry of Public Security sets technical standards that favor domestic equipment suppliers for sensitive applications. Beijing-Tianjin-Hebei and the Yangtze River Delta concentrate laboratory construction, with Shenzhen emerging as a manufacturing center for rapid DNA instrumentation.
Canada
The Royal Canadian Mounted Police coordinates national DNA databasing through the National DNA Data Bank, with provincial laboratories varying in technical capabilities. Health Canada regulates forensic testing standards that align closely with FBI Quality Assurance Standards for cross-border compatibility. Ontario and Quebec maintain the most comprehensive in-house forensic capacity, while Prairie provinces rely increasingly on regional service arrangements.
DNA Forensics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-spectrum providers commanding premium positioning in centralized laboratory procurement while niche operators capture point-solution opportunities. The market structure reflects technology lock-in effects, particularly around proprietary reagent chemistries and validated workflow protocols. Two archetypes dominate: diversified life science conglomerates leveraging cross-portfolio synergies, and focused forensic specialists building reputation through high-profile case resolution. Competitive dynamics center on M&A activity to secure reagent supply chains and strategic partnerships to penetrate emerging rapid DNA deployment sites.
Among integrated life science conglomerates, Thermo Fisher Scientific and Illumina occupy positions reflecting distinct technology bets—Thermo Fisher through its reagent-to-instrument integration and Illumina through sequencing platform leadership. QIAGEN represents the specialized chemistry archetype, with its extraction and purification portfolios reducing contamination risk in degraded sample workflows. These three companies exemplify how competitive positioning in DNA forensics increasingly depends on controlling critical workflow steps rather than point-product dominance.
| Leading Market Players |
|---|
| Illumina |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Bode Technology |
| Eurofins Scientific |
| QIAGEN |
| LGC Limited |
| Othram |
| Promega Corporation |
| Others |
Supply Flow & Price Mechanics
The displacement of capillary electrophoresis by massively parallel sequencing platforms simultaneously redistributes manufacturing gravity toward sequencing instrument hubs and compresses reagent pricing power as standardized chemistries displace proprietary STR kits. This substitution dynamic concentrates margin capture among integrated workflow providers while fragmenting procurement across point-solution vendors.
Pricing Analysis
After-sales revenue from reagent consumables and extended service contracts drives lifetime value in DNA forensics instrumentation. The dominant pricing structure separates premium whole genome sequencing systems from standard STR analysis platforms and economy-grade rapid DNA field units. Price differentiation rests on FBI Quality Assurance Standards certification tier and after-sales service bundling. Pricing pressure stems from federal grant compression in state laboratory budgets. Contract forensic laboratories in Texas and Florida demonstrate lowest price sensitivity, while smaller police departments adopting rapid DNA statutes exhibit highest sensitivity.
Supply Chain Analysis
Proprietary polymerase enzyme production in the United States and Germany creates a chokepoint for STR amplification chemistries. Geographic supply concentration centers on the United States, Germany, and China for sequencing platforms, reagent formulations, and rapid DNA instrumentation respectively. Raw material dependencies include fluorescent dyes, modified nucleotides, and specialized polymerases. Single-source vulnerability in certified reagent supply creates structural risk. Distribution runs through direct sales forces for large centralized laboratories and distributor networks for point-of-collection deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
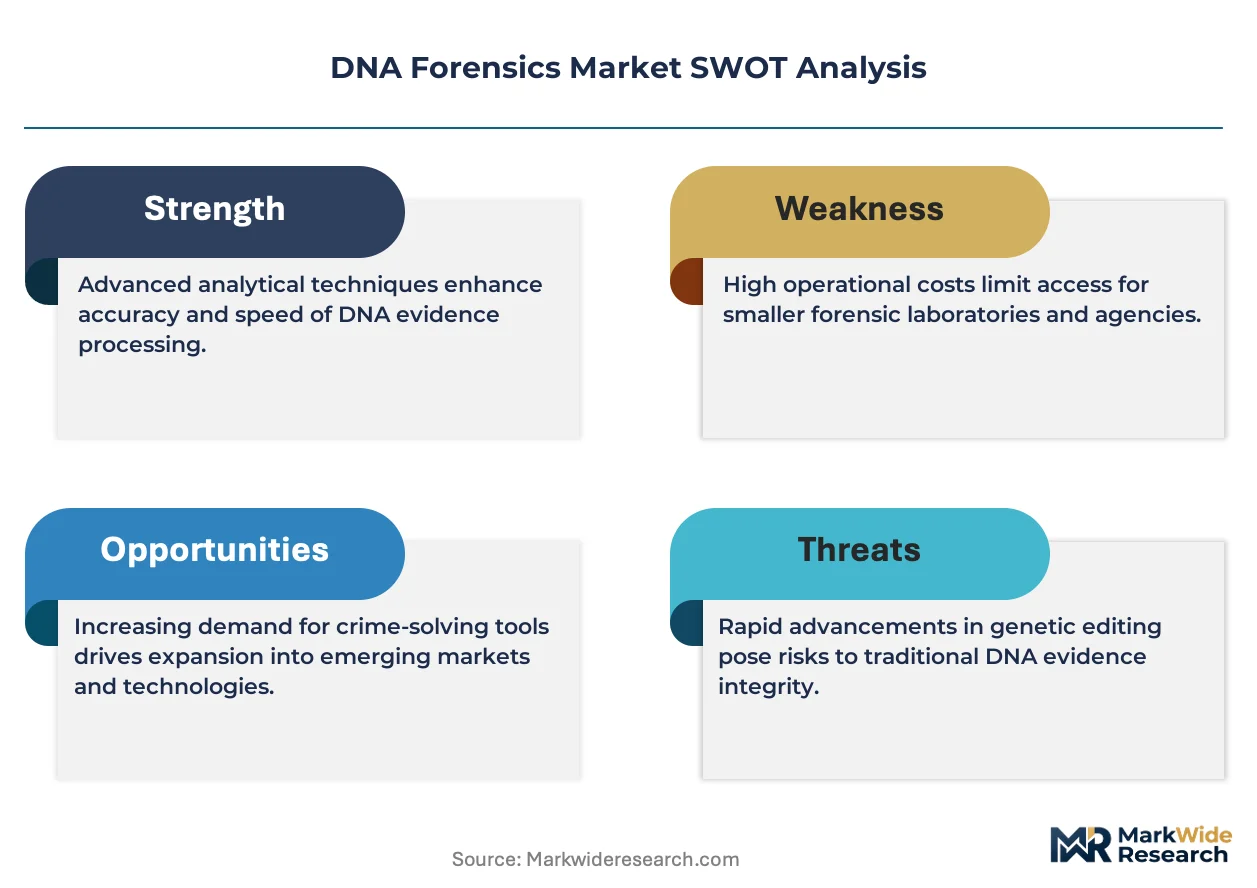
Analyst Recommendations
The acute shortage of bioinformatics specialists capable of complex mixture interpretation outpaces laboratory workforce expansion, constraining technology adoption regardless of instrument availability. This capability gap defines competitive advantage.
For Market Incumbents: Shield proprietary reagent chemistries through backward integration into polymerase manufacturing and lock in contract forensic laboratories with multi-year service agreements. The threat of open-source sequencing platforms commoditizing analytical execution demands exclusive FBI CODIS validation status as the priority defensive lever. For New Entrants and Emerging Players: Anchor in environmental DNA forensics for wildlife trafficking enforcement, the most penetrable application segment with minimal incumbent saturation. Target biosecurity monitoring contracts with simplified species-level identification kits. Pursue go-to-market partnerships with federal mass casualty response teams for disaster victim identification service provision. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract forensic laboratory networks in Florida and Texas. Long-term viability hinges on consolidation economies in regional hub-and-spoke service models. The acquisition target archetype combines validated LIMS integration with rapid DNA statutory compliance. Watch legislative momentum on familial search restrictions as the inflection signal determining next procurement wave timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Chemistry Backward Integration | Captive polymerase production insulates margins from supply disruption in FBI-certified workflows. |
| Rapid DNA Statutory Compliance Investment | Booking-station validation opens field-deployable revenue streams beyond centralized laboratories. |
| AI Mixture Interpretation Platform Launch | Automated deconvolution software addresses workforce scarcity while navigating EU AI Act conformity obligations. |
| Contract Laboratory Network Acquisition | Hub-and-spoke service concentration in Texas and Florida consolidates procurement authority. |
| Environmental DNA Application Expansion | Wildlife trafficking enforcement creates uncontested positioning in underpenetrated biosecurity verticals. |
Methodological Framework
Desk research of FBI CODIS technical standards, ENFSI guideline documents, and federal forensic infrastructure grant disclosures preceded structured interviews with state crime laboratory directors, rapid DNA program managers at police departments, forensic bioinformatics specialists, and reagent procurement officers at contract laboratories. Secondary validation drew from Department of Justice funding announcements, EU AI Act implementation guidance, and instrument vendor SEC filings. Bottom-up segment sizing triangulated against top-down federal budget allocation analysis.
Variance decomposition across technology substitution rates, statutory adoption timelines, and reagent price elasticity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include technology platform, application use case, end-user procurement modality, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis and consumable attach rate projections. Industry-specific inputs encompassed CODIS upload mandate compliance deadlines and rapid DNA legislative passage trajectories.
Underlying assumptions cover continued federal grant flow for forensic infrastructure, FBI Quality Assurance Standards stability, and EU AI Act enforcement intensity, with deviation risk concentrated in familial search prohibition legislation and biometric surveillance substitution. Practitioners should keep alternative scenarios live as statutory frameworks and funding appropriations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Cell Cryopreservation Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Proteomics Market
Biomedical Technology
Fluoro Enzymatic Assays Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
BOD Incubator Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Global Cell Harvesting Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Cell Penetrating Peptide Market
Biomedical Technology
Global Glycobiology Market