
 Nucleic Acid Electrophoresis and Blotting Market | 2026-2036
Nucleic Acid Electrophoresis and Blotting Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleic Acid Electrophoresis and Blotting Market Analytics
China is reconfiguring its domestic life-sciences supply chain through expanded electrophoresis reagent manufacturing zones in Suzhou and Shanghai. Thermo Fisher Scientific leverages its vertically integrated consumables portfolio to sustain pricing power across gel matrices and transfer membranes. Bio-Rad Laboratories anchors its position through proprietary western blotting automation systems that reduce manual protocol variability. Agilent Technologies differentiates via capillary electrophoresis platforms optimized for nucleic acid fragment analysis in pharmaceutical quality control.
Nucleic acid electrophoresis and blotting encompasses the separation, visualization, and transfer of DNA or RNA molecules through porous gel matrices under electric fields, typically resolving fragments from 50 base pairs to 20 kilobases with ethidium bromide or fluorescent dye detection. Blotting extends this by immobilizing separated nucleic acids onto nitrocellulose or nylon membranes for subsequent probe hybridization, enabling quantitative and qualitative analysis in research and diagnostic settings. Capillary electrophoresis systems command premium positioning due to superior resolution and throughput in genetic analysis workflows, while blotting kits generate recurring revenue through antibody and reagent replenishment cycles. Automated platforms are displacing manual techniques in high-volume diagnostic laboratories, though academic settings retain manual methods for teaching flexibility and cost containment.
The FDA regulates nucleic acid-based diagnostic devices under 21 CFR Part 820 quality system requirements, while the EPA oversees hazardous waste disposal from ethidium bromide and acrylamide gel processing. ISO 13485 certification shapes supplier eligibility for OEM partnerships with instrument manufacturers. Stakeholders must monitor evolving EPA state authorization variations for gel waste classification, as California and Massachusetts impose stricter handling protocols that ripple through national distribution economics.
Market Dynamics
Automated electrophoresis platforms are compressing manual protocol margins while tightening FDA quality benchmarks force consumables suppliers to recertify transfer membranes and gel matrices against 21 CFR Part 820 standards.
Growth Catalysts
- NIH Funding Priorities:Precision medicine infrastructure grants in the United States are channeling capital toward high-throughput genomic workflows. Academic institutes are expanding automated platform procurement.
- Capillary Electrophoresis Resolution:Pharmaceutical quality control laboratories are adopting fragment analysis systems for superior nucleic acid resolution. This displaces slab gel methods in regulated environments.
- China Manufacturing Zones:Suzhou and Shanghai electrophoresis reagent production clusters are reducing import dependency. Domestic supply chain reconfiguration accelerates regional self-sufficiency.
Market Restraints
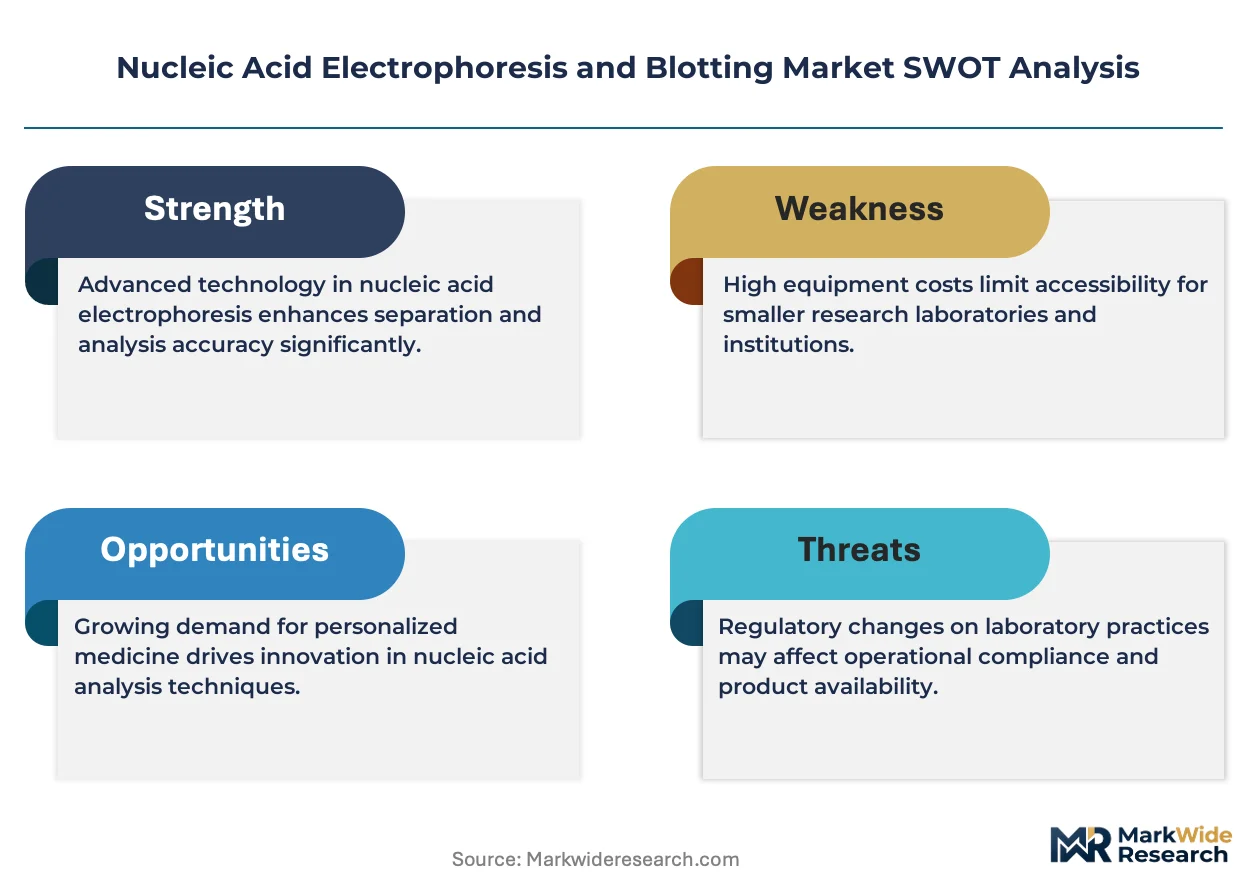
- Acrylamide Price Volatility:Petrochemical feedstock fluctuations destabilize gel matrix input costs. Suppliers face margin compression without pass-through pricing power.
- Ethidium Bromide Disposal:EPA hazardous waste protocols impose handling surcharges that ripple through California and Massachusetts distribution economics. Smaller laboratories defer volume expansion.
- Manual Technique Persistence:Academic teaching requirements retain low-automation methods. This fragments demand between premium systems and economy consumables.
Strategic Opportunities
- Point-of-Care Diagnostics:Miniaturized electrophoresis devices for decentralized nucleic acid testing remain underdeveloped. Portable platforms could penetrate rural clinic networks.
- ISO 13485 OEM Partnerships:Certification eligibility opens captive supply relationships with instrument manufacturers. Membrane and reagent suppliers can lock in recurring revenue streams.
- CRISPR Quality Control:Gene editing workflows require fragment validation at unprecedented scale. Custom capillary electrophoresis protocols serve this emerging application.
Industry Challenges
- Multiplex Assay Integration:Laboratories struggle to synchronize electrophoresis outputs with next-generation sequencing pipelines. Data format standardization remains unresolved.
- Technical Specialist Scarcity:Capillary system operation and troubleshooting require specialized training. Workforce gaps delay platform deployment in mid-sized diagnostic facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleic Acid Electrophoresis and Blotting Market |
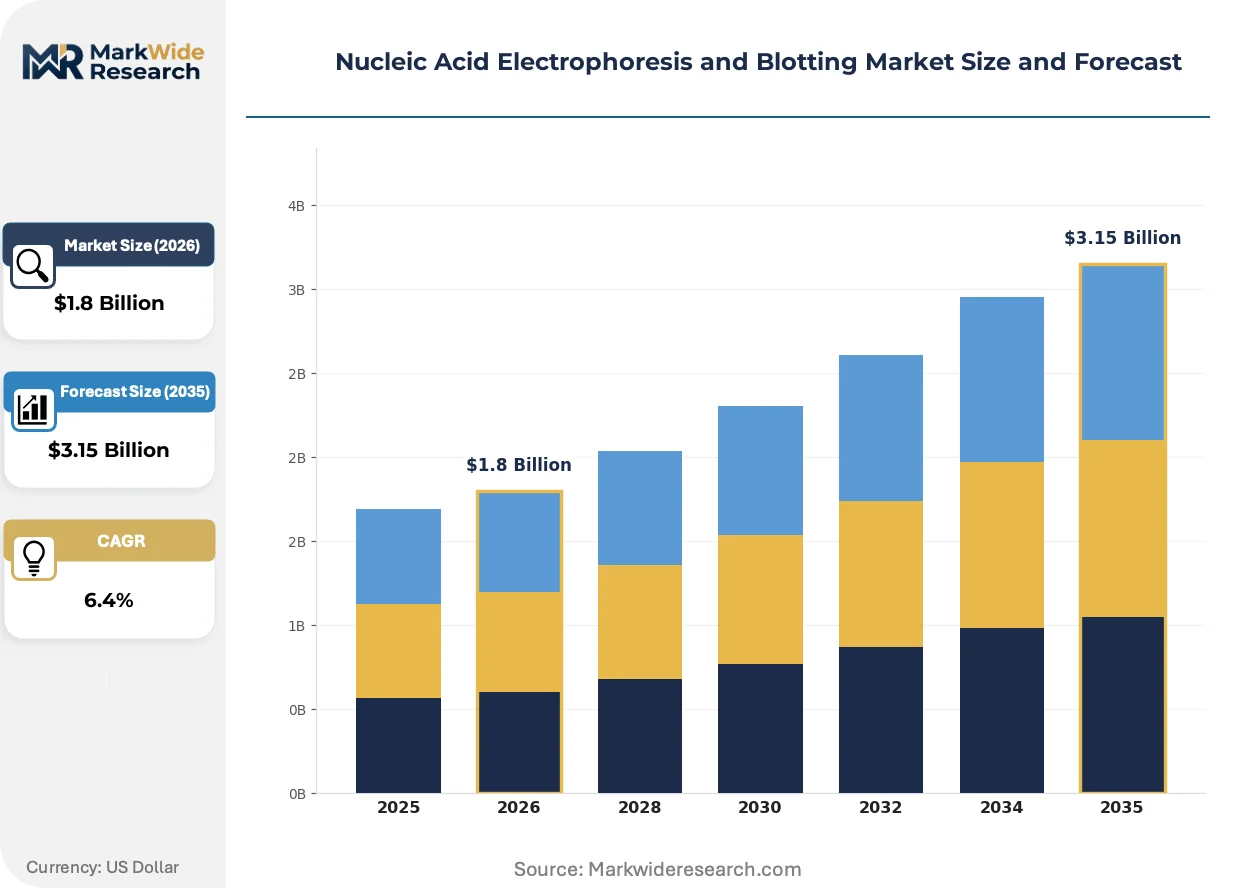
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Gel Electrophoresis, Horizontal Gel Electrophoresis, Capillary Electrophoresis, Blotting Kits Application: Molecular Biology, Genetic Research, Clinical Diagnostics, Forensic Analysis End User: Academic Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Research Organizations Technology: Manual Techniques, Automated Platforms, Microfluidics, Real-Time Analysis |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, Merck KGaA, Qiagen, Takara Bio, Promega Corporation, Cytiva, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleic Acid Electrophoresis and Blotting Market Evolving Landscape
Workflow automation and regulatory digitization are compressing validation timelines while fragment analysis precision becomes a competitive differentiator in pharmaceutical quality assurance.
Microfluidic electrophoresis cartridges are hybridizing sample preparation with separation functions in single-use formats. Contract research organizations are adopting these platforms for accelerated nucleic acid screening. The convergence is compressing turnaround times from hours to minutes while reducing cross-contamination risk in high-throughput environments.
EMA's In Vitro Diagnostic Regulation is tightening performance documentation requirements for nucleic acid-based devices. Manufacturers must submit expanded clinical evidence for blotting consumables used in diagnostic workflows. European pharmaceutical laboratories are prioritizing CE-marked reagent kits to preempt regulatory friction during technology transfers.
Consolidated purchasing through group procurement organizations is displacing direct manufacturer relationships in hospital laboratory networks. Diagnostic chains are negotiating enterprise-wide electrophoresis platform contracts with bundled service provisions. This concentration is most visible in United States health system affiliates seeking volume discounts on automated systems.
Nucleic Acid Electrophoresis and Blotting Market Segmentation
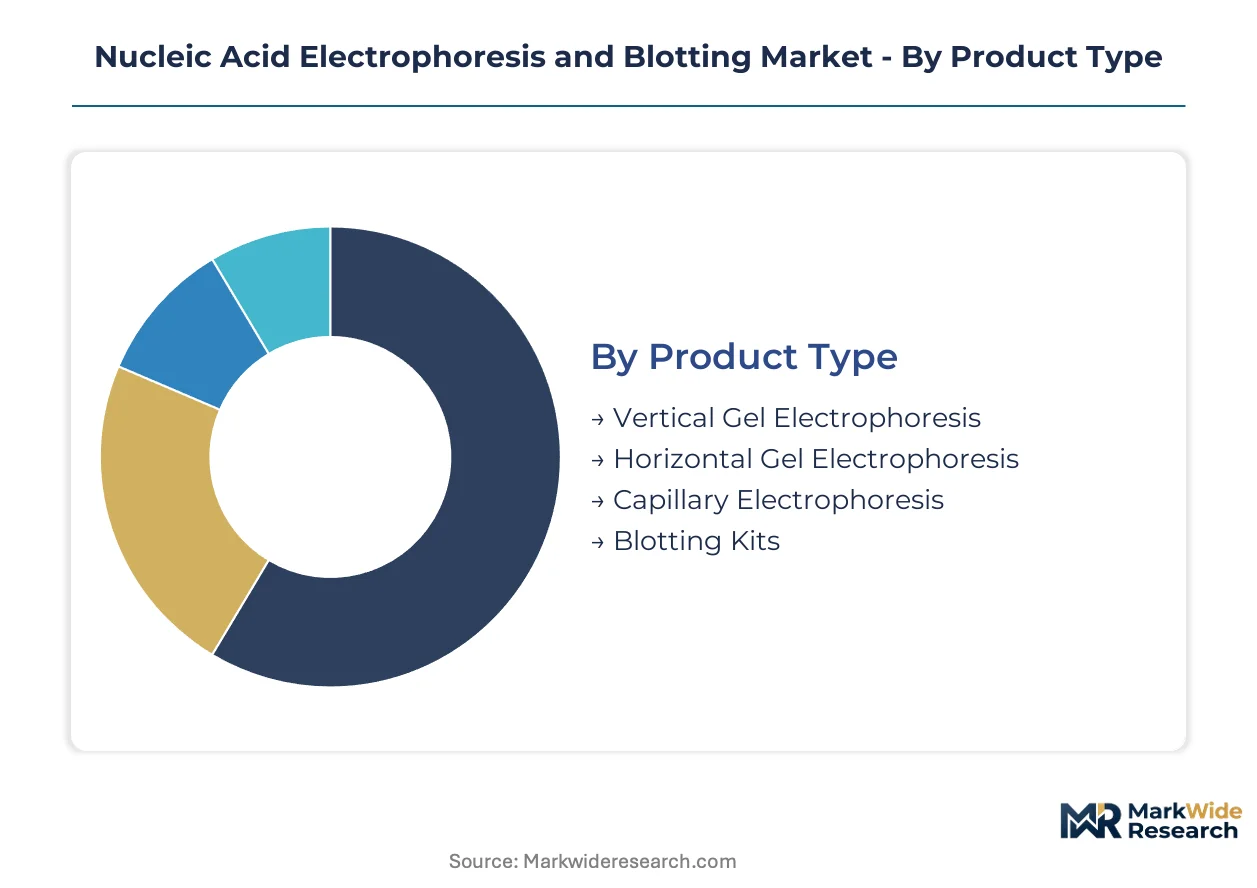
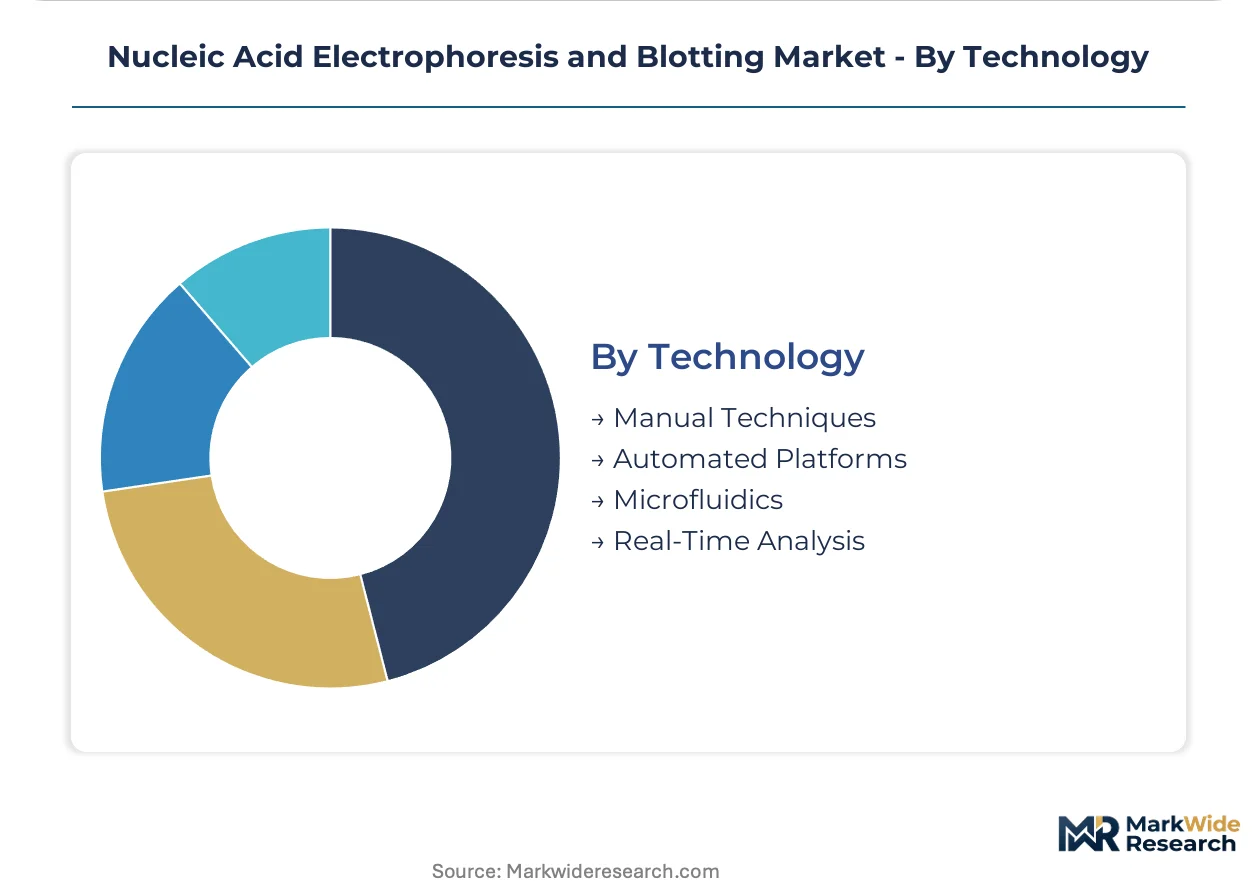
Segmentation in nucleic acid electrophoresis and blotting reveals divergent service intensity across product tiers. Automated platforms demand intensive calibration contracts and consumable replenishment cycles, while manual techniques minimize recurring vendor engagement.
Product Type:
After-sales-service intensity varies sharply across electrophoresis hardware tiers, with automated systems locking customers into multi-year service agreements and reagent subscriptions.
- Vertical Gel Electrophoresis:Slab gel systems with perpendicular current flow resolve protein and nucleic acid complexes in polyacrylamide matrices. Pharmaceutical quality control laboratories in the United States favor these systems for batch consistency validation, though acrylamide price volatility compresses operational budgets.
- Capillary Electrophoresis:Fused-silica capillaries achieve single-base resolution for fragment analysis through automated injection and laser-induced fluorescence detection. Diagnostic laboratories in Germany and Switzerland are displacing slab gel methods for regulatory submissions, driven by EMA's tightened performance documentation requirements.
- Horizontal Gel Electrophoresis:Submarine-style chambers with agarose matrices dominate educational settings and routine DNA sizing workflows in academic institutes.
- Blotting Kits:Pre-cast membrane and buffer systems generate recurring revenue through antibody replenishment cycles in research organizations.
By volume, Horizontal Gel Electrophoresis leads. By growth pace, Capillary Electrophoresis is expanding most quickly.
Application:
Cost tier stratification separates premium-priced clinical diagnostic workflows from economy-positioned academic research applications.
- Molecular Biology:Fundamental nucleic acid manipulation workflows including cloning, sequencing preparation, and gene expression analysis. Academic institutes in the United States and United Kingdom concentrate procurement here, constrained by NIH funding cycle timing and teaching budget limitations.
- Clinical Diagnostics:FDA-regulated nucleic acid testing for infectious disease and genetic disorder identification. Diagnostic laboratory chains in the United States negotiate enterprise-wide platform contracts, consolidating purchasing through group procurement organizations.
- Genetic Research:Population-scale genomics and functional gene studies utilizing electrophoresis for quality control checkpoints.
- Forensic Analysis:DNA profiling for criminal casework and paternity testing requiring chain-of-custody documentation.
Clinical Diagnostics commands premium pricing per test. Genetic Research shows the steepest expansion trajectory as CRISPR validation workflows proliferate.
End User:
Customer type determines procurement sophistication, with pharmaceutical companies demanding ISO 13485-certified supply chains that academic institutes bypass.
- Pharmaceutical Companies:Integrated drug developers requiring GMP-compliant electrophoresis for biologics characterization and release testing. Facilities in Switzerland and Germany prioritize CE-marked reagent kits to preempt EMA regulatory friction during technology transfers.
- Diagnostic Laboratories:High-volume testing facilities processing thousands of nucleic acid samples daily. United States health system affiliates are consolidating purchasing through group procurement organizations for automated platform volume discounts.
- Academic Institutes:University and research foundation laboratories balancing teaching flexibility against throughput requirements.
- Research Organizations:Contract research and government laboratories with project-based funding cycles.
Pharmaceutical Companies lead in per-unit spending. Diagnostic Laboratories are gaining share fastest through consolidation.
Technology:
Maturity gradients separate established manual techniques from emerging microfluidic platforms still seeking manufacturing scale.
- Automated Platforms:Robotic sample handling with integrated imaging and data analysis reducing protocol variability. Pharmaceutical quality control laboratories in Japan and South Korea are deploying these systems to compress validation timelines under PMDA and MFDS guidance.
- Microfluidics:Lab-on-chip cartridges combining sample preparation, separation, and detection in single-use formats. Contract research organizations in the United States and Netherlands are adopting these for accelerated nucleic acid screening, though technical specialist scarcity delays deployment in mid-sized facilities.
- Manual Techniques:Hand-poured gels and passive transfer methods retained for educational flexibility.
- Real-Time Analysis:Continuous monitoring systems with immediate digital output for time-sensitive workflows.
Manual Techniques dominate installed base. Microfluidics is climbing the fastest as miniaturization converges with point-of-care diagnostic development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophoresis reagent manufacturing clusters in Suzhou and Shanghai are redirecting trade flows across Asia-Pacific, while precision medicine infrastructure investments in the United States and Germany concentrate demand for high-resolution analytical platforms.
United States
NIH precision medicine grants and private biotech capital are converging on automated genomic workflows. FDA's updated 21 CFR Part 820 guidance tightens quality benchmarks for blotting consumables used in diagnostic validation. The Greater Boston and San Francisco Bay Area clusters anchor demand for capillary systems in pharmaceutical quality control.
China
Domestic life-sciences supply chain reconfiguration is accelerating through expanded electrophoresis reagent production zones. NMPA regulatory harmonization with international standards is elevating certification requirements for imported diagnostic platforms. Suzhou and Shanghai manufacturing clusters are reducing import dependency for gel matrices and transfer membranes.
Germany
Pharmaceutical quality control laboratories are displacing slab gel methods with capillary systems for EMA regulatory submissions. The country's national pharmaceutical regulator enforces tightened performance documentation under IVDR implementation. The Rhine-Main and Upper Bavaria regions concentrate biologics characterization facilities requiring GMP-compliant electrophoresis.
Japan
PMDA guidance on nucleic acid-based device validation is compressing timelines for automated platform deployment. Pharmaceutical quality control laboratories are adopting robotic sample handling systems to meet biologics release testing standards. The Kanto region around Tokyo anchors demand for integrated imaging and data analysis systems.
Switzerland
Integrated drug developers prioritize CE-marked reagent kits to preempt regulatory friction during technology transfers. Swissmedic oversight of in vitro diagnostic performance documentation shapes supplier selection for nucleic acid testing workflows. The Basel and Zurich clusters concentrate biologics characterization facilities requiring fragment analysis precision.
Nucleic Acid Electrophoresis and Blotting Market Competitive Landscape
Vertically integrated conglomerates and specialized automation developers split the market into distinct capability tiers. The vendor landscape exhibits moderate concentration, with scale advantages accruing to players controlling captive consumables production. Two archetypes dominate: diversified life-science conglomerates leveraging portfolio breadth, and focused electrophoresis specialists commanding premium positioning in fragment analysis. Competitive dynamics center on backward integration into gel matrix manufacturing and strategic partnerships with diagnostic platform OEMs.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the integrated archetype through captive supply of consumables portfolios. Bio-Rad Laboratories occupies a specialist position, representing the focused automation tier with proprietary western blotting systems. These three anchors illustrate the market's bifurcation between scale-driven platform bundling and precision-oriented technical differentiation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Merck KGaA |
| Qiagen |
| Takara Bio |
| Promega Corporation |
| Cytiva |
| Lonza Group |
| Others |
Value Network & Pricing Analysis
Suzhou and Shanghai electrophoresis reagent manufacturing clusters concentrate gel matrix and transfer membrane production capacity, granting domestic Chinese suppliers pricing leverage over import-dependent distributors in North America and Europe. This geographic concentration compresses margins for international consumables vendors while enabling tiered pricing stratification across certification grades.
Pricing Analysis
21 CFR Part 820 dictates the pricing tier structure for blotting consumables used in FDA-regulated diagnostic workflows, separating ISO 13485-certified premium tiers from uncertified economy alternatives. Price differentiation rests on certification level and after-sales service bundling, with pharmaceutical quality control laboratories showing lowest price sensitivity due to GMP compliance requirements. Cost compression in manual gel matrices is intensifying because acrylamide feedstock volatility erodes supplier margins without full pass-through pricing power.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electrophoresis hardware and consumables procurement. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning petrochemical-derived acrylamide, high-purity agarose, and nitrocellulose membrane substrates. Distribution runs through consolidated group procurement organizations in United States hospital networks and direct OEM partnerships in European pharmaceutical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nucleic acid electrophoresis and blotting sits in early-cycle expansion as CRISPR quality control workflows and precision medicine infrastructure investments accelerate platform adoption beyond traditional research boundaries.
For Market Incumbents: Pre-empt margin erosion in manual consumables by accelerating backward integration into gel matrix manufacturing and locking multi-year service contracts with diagnostic laboratory chains. Microfluidic platform entrants threaten traditional capillary system positioning; defend through proprietary protocol libraries and ISO 13485 certification investments that create switching costs. For New Entrants and Emerging Players: Pursue point-of-care diagnostic white space where miniaturized electrophoresis devices remain underdeveloped, particularly rural clinic networks in Asia-Pacific and Latin America. Academic teaching laboratories retain manual technique persistence and represent the most penetrable segment for economy-positioned consumables; enter through distributor partnerships targeting NIH-funded institutes with constrained capital budgets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated platform specialists with captive consumables revenue streams over pure-play reagent suppliers. Long-term viability hinges on regulatory compliance infrastructure and OEM partnership density; watch FDA guidance evolution on nucleic acid-based diagnostic validation as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Opens captive supply relationships with Agilent and Bio-Rad instrument platforms. |
| Microfluidic Cartridge Manufacturing Scale-Up | Addresses CRO demand for accelerated nucleic acid screening turnaround times. |
| Backward Integration into Acrylamide Production | Insulates gel matrix margins from petrochemical feedstock volatility exposure. |
| Point-of-Care Platform Development | Penetrates underdeveloped rural clinic networks with portable diagnostic devices. |
| CRISPR Validation Protocol Partnerships | Captures emerging gene editing quality control workflow demand from pharmaceutical developers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors, diagnostic platform engineers, GPO contracts managers, and regulatory affairs specialists at FDA and EMA. Secondary validation drew from FDA 510(k) filings, EMA IVDR submission databases, NIH grant award records, and SEC 10-K disclosures from diversified life-science conglomerates. Bottom-up and top-down triangulation reconciled instrument shipment data with consumables replenishment cycle analysis.
Calibration against historical platform deployment rates and consumables attach ratios anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology maturity tier, with CAGRs derived from regression analysis of NIH funding trajectories and pharmaceutical R&D intensity indices. Forecast inputs incorporated PMDA and MFDS regulatory timeline compression effects in Asia-Pacific markets.
Macroeconomic conditions sit as an overlay; deviation in biotech venture capital availability and acrylamide commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and CRISPR therapeutic pipeline advancement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Biochips Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global RNA Analysis Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Cell Disrupters Market